
 Reciprocating Air Compressor Market | 2026-2036
Reciprocating Air Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Reciprocating Air Compressor Market Analysis
Small and medium machine shops is unwinding from large integrated manufacturing complexes as the primary growth buyer archetype for reciprocating units. Atlas Copco AB leverages its aftermarket service density to capture replacement cycles in this fragmented base. Ingersoll Rand Inc. anchors North American distribution through contractor-focused dealer networks. Kaeser Compressors, Inc. specializes in energy-efficient two-stage designs that appeal to electricity-conscious operators.
A reciprocating air compressor employs a piston-driven mechanism within a cylinder to compress air through successive intake and compression strokes, typically achieving discharge pressures from 100 to 6,000 psi depending on staging configuration. The technology serves as foundational pneumatic power for tooling, process control, and material handling across industrial and commercial settings. Two-stage products command the premium margin pool where continuous-duty cycles justify higher capital outlay. Portable electric units are gaining fastest in construction and mobile service applications. Food and beverage end users increasingly specify oil-free reciprocating designs to comply with product contact air purity requirements.
The EPA regulates stationary reciprocating engine emissions under New Source Performance Standards, while OSHA mandates compressed air safety protocols for workplace pneumatic systems. ISO 8573 air quality classes shape product specifications for food, pharmaceutical, and electronics manufacturing. In Europe, the Ecodesign Directive and F-Gas Regulation indirectly steer compressor efficiency benchmarks and refrigerant-based dryer pairings. Stakeholders must weigh electric grid reliability against gas and diesel alternatives as carbon pricing mechanisms expand across industrial power choices.
Market Dynamics
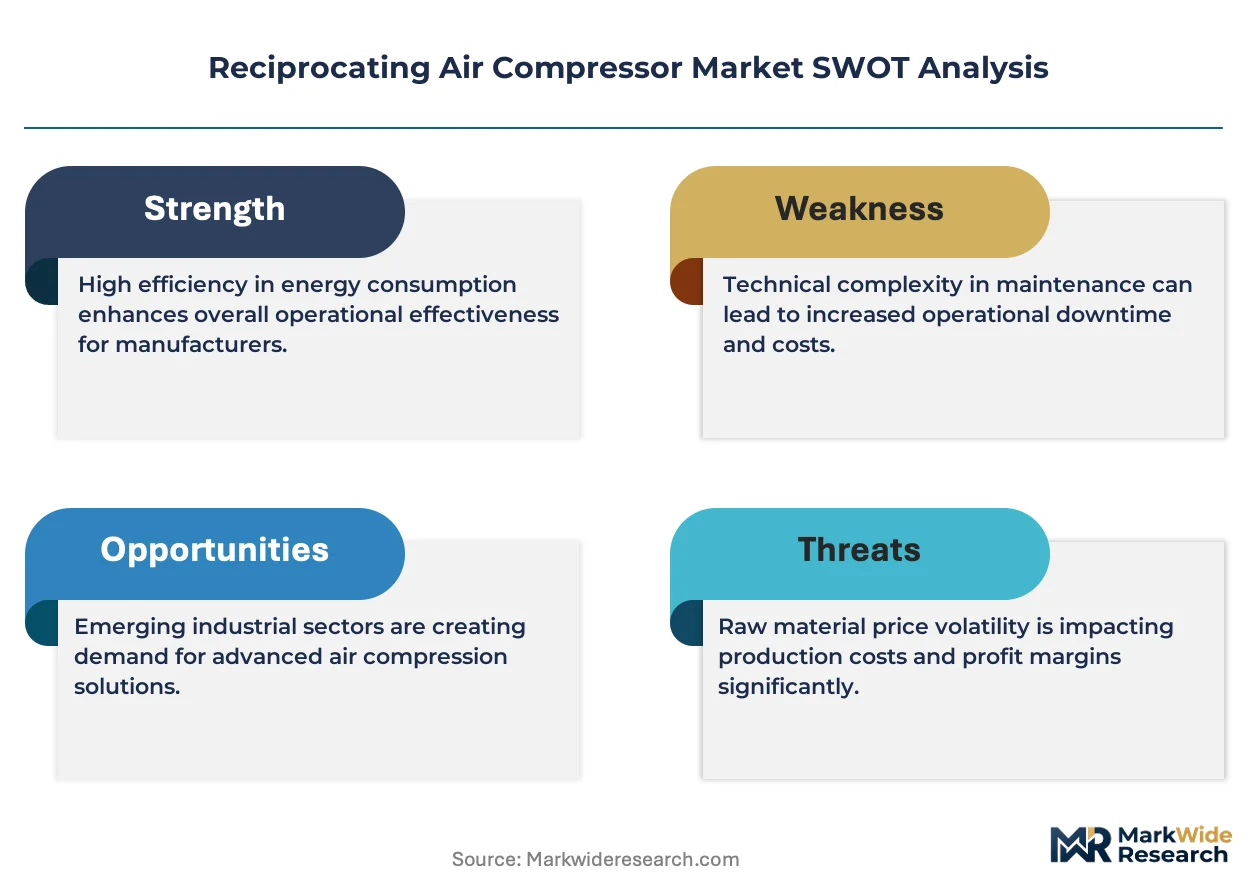
The reciprocating air compressor market is restructuring around the tension between stationary electric systems and portable combustion-engine units as carbon pricing mechanisms reshape industrial power procurement decisions across manufacturing corridors.
Growth Catalysts
- EPA Stationary Engine Standards:Tightening New Source Performance Standards for reciprocating engines are accelerating end-user migration toward electric-drive compressor systems in US manufacturing facilities.
- Food Processing Hygiene Mandates:ISO 8573 air purity classes are compelling food and beverage processors to install oil-free reciprocating designs for product-contact pneumatic applications.
- India's Industrial Corridors:PLI-linked manufacturing investments across Tamil Nadu, Gujarat, and Maharashtra are generating concentrated demand for reliable on-site compressed air infrastructure.
Market Restraints
- Copper and Steel Input Volatility:Cylinder block and pressure vessel fabrication costs fluctuate with base metal commodity pricing, compressing margin predictability for equipment fabricators.
- Two-Stage System Capex Burden:Premium two-stage designs require substantially higher capital outlay than single-stage alternatives, limiting penetration in price-sensitive small machine shop segments.
- Rotary Screw Substitution:Continuous-duty industrial applications increasingly specify rotary screw compressors for their superior energy efficiency and lower maintenance profiles.
Strategic Opportunities
- Construction Electrification:Battery-powered portable electric units are capturing share from gasoline-driven models in urban construction zones facing emissions restrictions.
- Aftermarket Service Density:Fragmented small and medium machine shop bases present whitespace for service networks to capture replacement cycle revenue through preventive maintenance contracts.
- EU F-Gas Regulation Alignment:Refrigerant-based dryer pairings with reciprocating systems are adapting to F-Gas phasedown schedules, creating upgrade demand for compliant integrated packages.
Industry Challenges
- Pneumatic Systems Integration:Legacy compressed air distribution infrastructure in aging industrial facilities comples retrofit installations and performance optimization.
- OSHA Compliance Documentation:Workplace pneumatic safety protocol verification requires specialized technician certification that strains field service workforce availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reciprocating Air Compressor Market |
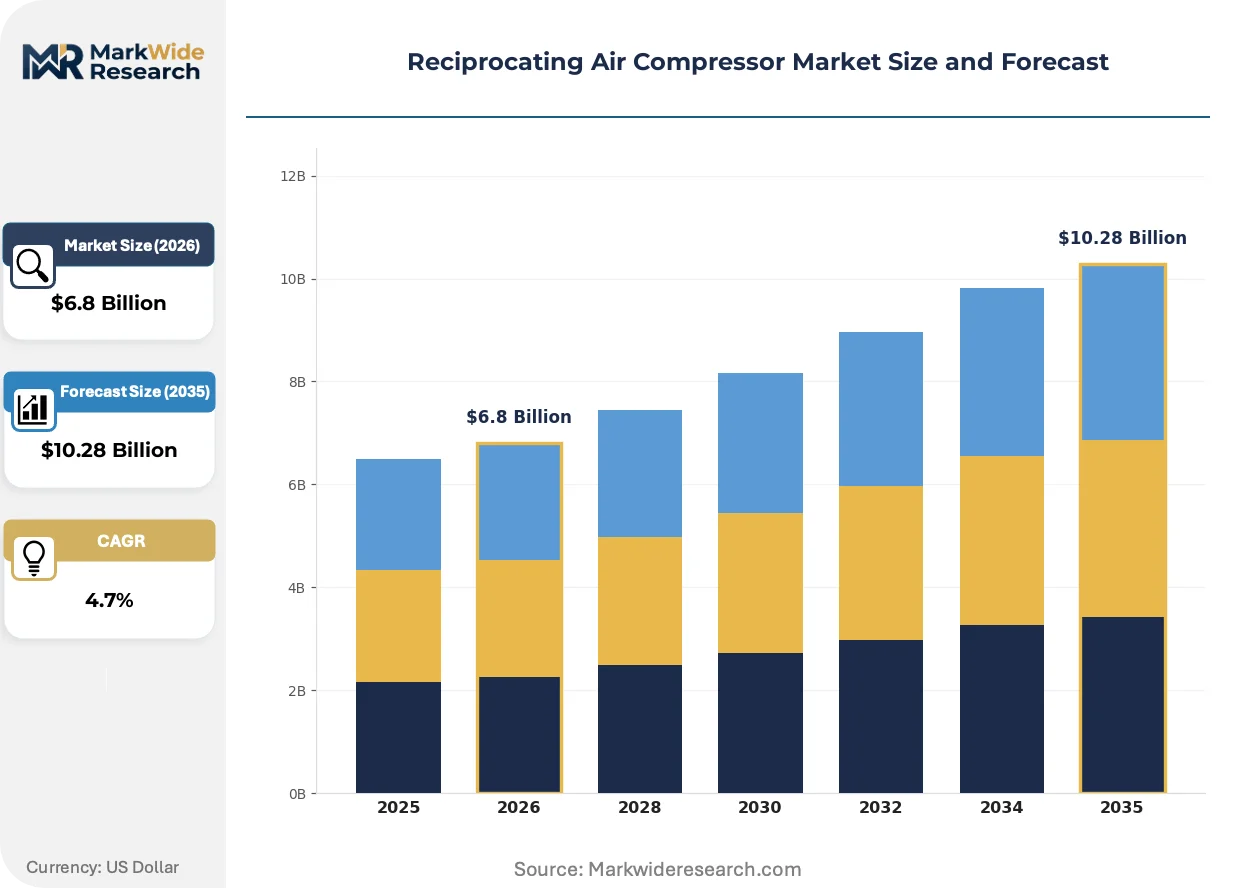
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Stage, Two Stage, Portable, Stationary End User: Manufacturing, Construction, Automotive, Food & Beverage Power Source: Electric, Gas, Diesel, Hybrid Deployment: On-site, Off-site, Mobile, Fixed |
| Companies Covered | Atlas Copco AB, Ingersoll Rand Inc., Burckhardt Compression AG, Gardner Denver Holdings, Inc., Kaeser Compressors, Inc., Ariel Corporation, Siemens Energy AG, General Electric Company, ELGi Equipments Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reciprocating Air Compressor Market Emerging Trajectories
Product architecture is diverging between premium two-stage stationary systems and lightweight portable electrics as regulatory pressure and application specificity reshape R&D priorities across the supplier base.
Two-stage compression technology is bifurcating the market into premium continuous-duty installations and intermittent-use single-stage alternatives. Automotive tier suppliers and metal fabrication shops with 24-hour production schedules are specifying these systems despite higher capital requirements. The technology is compressing replacement cycles in high-utilization environments while marginalizing single-stage units to occasional-use applications.
The EPA's New Source Performance Standards for stationary reciprocating engines are forcing manufacturing facilities to evaluate electric-drive alternatives for compressor installations. Industrial end users in emissions-nonattainment zones face compliance deadlines that accelerate capital replacement timelines. Food processing and electronics manufacturing verticals are responding fastest due to concurrent air purity certification requirements.
Service contract structures are unbundling from equipment sales as fragmented small machine shop buyers prioritize uptime guarantees over ownership. Distributor networks are replacing direct sales relationships in North American contractor markets. India's industrial corridors exhibit the most pronounced shift, where PLI beneficiaries demand integrated service packages spanning installation, monitoring, and predictive maintenance.
Reciprocating Air Compressor Market Segmentation
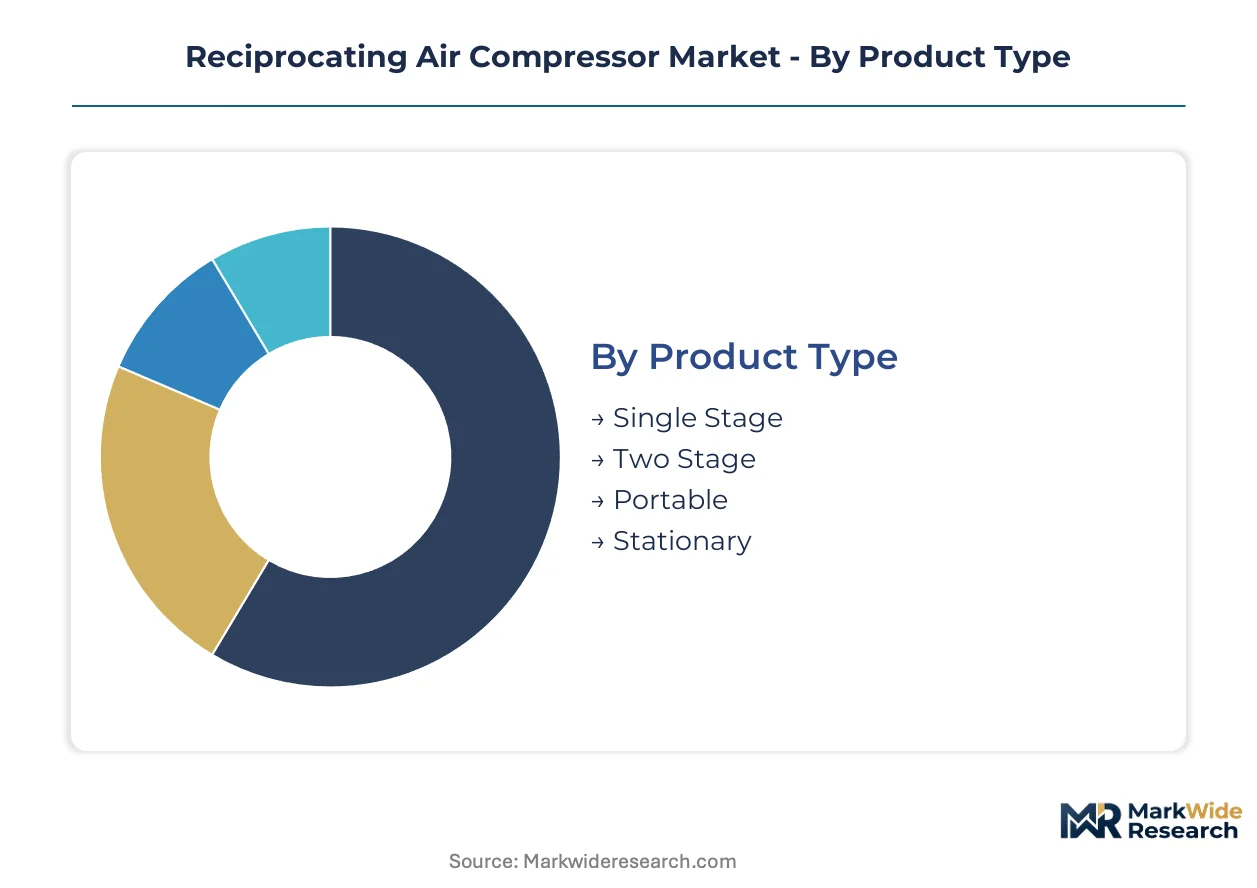
Reciprocating air compressor procurement splits sharply across duty cycles, emissions compliance zones, and air purity mandates. Specification divergence between food-grade oil-free systems and general industrial units creates parallel demand tracks with minimal buyer overlap.
Product Type:
EPA New Source Performance Standards and ISO 8573 air purity classes reshape capital allocation across compression architectures.
- Single Stage:Piston compresses air in one stroke to discharge pressures typically below 150 psi. Intermittent-use machine shops in India's Gujarat industrial corridor favor these units for capital-constrained tool powering despite higher energy intensity per cubic foot.
- Two Stage:Successive compression across low and high pressure cylinders achieves 175-200 psi with superior thermodynamic efficiency. Continuous-duty automotive tier suppliers in Tamil Nadu specify these for 24-hour production schedules where lifecycle cost trumps first cost.
- Portable:Lightweight chassis-mounted units serve construction sites and mobile service fleets. Battery-electric variants gain share in urban emissions-restricted zones.
- Stationary:Permanent installations anchor manufacturing facility pneumatic infrastructure. Electric-drive models displace gas-engine units under tightening stationary engine regulations.
Established volume favors Single Stage; emerging adoption favors Two Stage.
End User:
Air purity certification requirements and duty cycle intensity segment buyer specifications across vertical applications.
- Manufacturing:Metal fabrication and general assembly operations constitute the installed base volume. OSHA pneumatic safety compliance documentation shapes procurement alongside energy efficiency benchmarks.
- Construction:Mobile pneumatic powering for breaking, drilling, and fastening drives portable unit demand. Electrification pressure from municipal emissions ordinances accelerates battery-powered adoption.
- Automotive:Tier supplier paint shops and assembly lines require continuous-duty two-stage systems with integrated drying. PLI-linked investments across Maharashtra industrial corridors concentrate new specification activity.
- Food & Beverage:Oil-free reciprocating designs eliminate hydrocarbon contamination risk in product-contact pneumatic conveying. FSSAI hygiene mandates and ISO 8573 Class 0/1 requirements compel premium specification.
Manufacturing commands current installed value; Food & Beverage climbs the fastest on regulatory compulsion.
Power Source:
Carbon pricing mechanisms and grid reliability calculus reweight procurement decisions across industrial power alternatives.
- Electric:Grid-connected motors dominate stationary installations in EPA nonattainment zones. Ecodesign Directive efficiency benchmarks steer European specification toward premium motor classes.
- Gas:Natural gas engines serve facilities with unreliable grid access or favorable fuel economics. Stationary engine emissions standards compress viable deployment geography.
- Diesel:Compression-ignition engines power remote construction and mining pneumatics. Urban emissions restrictions marginalize these units to ex-urban project sites.
- Hybrid:Dual-fuel or battery-buffered architectures bridge grid dependency gaps. Early adoption concentrates in distributed manufacturing clusters with intermittent power supply.
Electric holds dominant share; Hybrid gains share fastest where grid instability meets emissions pressure.
Deployment:
Asset mobility requirements and infrastructure permanence define procurement packaging and service contract structures.
- On-site:Dedicated compressor installations serve single-facility pneumatic demand. Predictive maintenance contracts increasingly bundle with equipment procurement.
- Off-site:Centralized compression facilities distribute air through pipeline networks to multiple users. Industrial park models in Gujarat and Maharashtra explore this structure.
- Mobile:Trailer or skid-mounted units relocate between project phases. Construction electrification trends favor battery-electric portability over combustion alternatives.
- Fixed:Permanent foundation-mounted systems anchor facility infrastructure. Replacement cycles correlate with depreciation schedules and efficiency upgrade economics.
Fixed deployment anchors revenue stability; Mobile deployment expands most quickly on construction electrification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German compressor fabricators supply precision-engineered two-stage systems to automotive tier suppliers across Tamil Nadu and Maharashtra, while Chinese manufacturers dominate portable electric unit exports to Southeast Asian construction markets.
United States
EPA New Source Performance Standards accelerate electric-drive adoption in manufacturing facilities across Ohio and Michigan industrial corridors. OSHA pneumatic safety documentation requirements strain field service workforce availability in legacy Rust Belt facilities. Atlas Copco AB leverages aftermarket service density to capture replacement cycles in fragmented Midwest machine shop bases.
Germany
Ecodesign Directive efficiency benchmarks steer specification toward premium motor classes in Baden-Württemberg automotive clusters. The F-Gas Regulation drives refrigerant-based dryer upgrade demand for compliant integrated packages. Siemens Energy AG anchors industrial compressor supply relationships across Bavaria's precision manufacturing belt.
China
Dual carbon goals compress viable deployment geography for diesel-powered portable units in Yangtze River Delta construction zones. MIIT efficiency mandates reshape procurement toward grid-connected electric systems in Pearl River Delta export manufacturing. Zhengzhou-based fabricators concentrate single-stage production for capital-constrained domestic tool powering.
India
PLI-linked manufacturing investments across Tamil Nadu, Gujarat, and Maharashtra generate concentrated demand for reliable on-site compressed air infrastructure. FSSAI hygiene mandates compel food processors in Maharashtra to specify oil-free reciprocating designs. ELGi Equipments Ltd. occupies a position serving fragmented small and medium machine shop replacement cycles through preventive maintenance contracts.
Japan
METI industrial efficiency programs accelerate two-stage system specification in Kansai automotive paint shops. JIS standards shape product certification requirements for electronics manufacturing pneumatic applications in Chubu precision component clusters. Kaeser Compressors, Inc. exemplifies energy-efficient design specialization appealing to electricity-conscious operators in Tokyo Bay industrial zones.
Reciprocating Air Compressor Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and service network reach, producing a tiered structure where scale-driven aftermarket density battles localized fabrication agility. Publicly traded entities anchor premium two-stage and oil-free portfolios through direct sales relationships. Private specialists capture intermittent-use single-stage demand via distributor networks. Dominant competitive moves include preventive maintenance contract unbundling from equipment sales and battery-electric portable product line expansion.
Within the premium-tier vector, Atlas Copco AB and Ingersoll Rand Inc. represent listed multinational archetypes with dense service infrastructure, while Burckhardt Compression AG occupies a position among specialized Swiss fabricators. Kaeser Compressors, Inc. exemplifies the efficiency-focused private specialist tier. These three entities collectively illustrate the market's structural divergence between scale-driven aftermarket capture and technology-differentiated specification.
| Leading Market Players |
|---|
| Atlas Copco AB |
| Ingersoll Rand Inc. |
| Burckhardt Compression AG |
| Gardner Denver Holdings, Inc. |
| Kaeser Compressors, Inc. |
| Ariel Corporation |
| Siemens Energy AG |
| General Electric Company |
| ELGi Equipments Ltd. |
| Others |
Supply Flow & Price Mechanics
Steel-to-aluminum substitution in pressure vessel fabrication redraws procurement geography toward Chinese and Indian rolling mills while compressing margin structures for European fabricators locked into legacy supply contracts. This materials transition simultaneously erodes pricing power for incumbent premium-tier producers and opens cost-advantaged positioning for Asia-Pacific manufacturers serving price-sensitive single-stage demand.
Pricing Analysis
Two-stage-to-single-stage pricing gaps stratify procurement decisions across duty-cycle intensity, with continuous-duty automotive tier suppliers absorbing premium capital outlays while intermittent-use machine shops gravitate toward economy-tier alternatives. Certification-grade differentiation separates ISO 8573 Class 0 oil-free systems from general industrial units through hygienic design premiums. Cost compression in single-stage categories intensifies as Chinese manufacturers scale aluminum-cylinder production for India's Gujarat industrial corridor. Small and medium machine shops exhibit acute price sensitivity, whereas food and beverage processors prioritize lifecycle compliance costs over first-cost minimization.
Supply Chain Analysis
China and India anchor cast-iron cylinder block and aluminum pressure vessel fabrication, while Germany and Switzerland concentrate precision-machined valve train and control component production. Copper winding stock and specialty steel forgings feed motor and crankshaft assembly lines across these manufacturing nodes. Single-source vulnerability concentrates in rare-earth magnet supply for high-efficiency permanent magnet motors, with Chinese export license volatility threatening European Ecodesign Directive compliance timelines. Distribution runs through authorized dealer networks for stationary systems and equipment rental channels for portable construction units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Preventive maintenance contract unbundling from equipment sales generates recurring revenue expansion exceeding hardware shipment growth, particularly across India's fragmented small machine shop base where uptime guarantees command premium positioning.
For Market Incumbents: Shield installed base relationships through predictive maintenance platform deployment that captures replacement cycle revenue before rotary screw substitution accelerates in continuous-duty applications. Deepen aftermarket service density in India's PLI-linked manufacturing corridors where ELGi Equipments Ltd. has established preventive maintenance contract penetration. Anchor channel control through exclusive distributor agreements in North American contractor markets facing OSHA pneumatic safety documentation requirements. For New Entrants and Emerging Players: Differentiate on battery-electric portable architecture to capture construction electrification demand in urban emissions-restricted zones across China's Yangtze River Delta. Target India's Maharashtra and Tamil Nadu industrial corridors for two-stage system specification where automotive tier suppliers prioritize lifecycle cost over first-cost minimization. Pursue integrated service packaging bundling installation, monitoring, and predictive maintenance as the primary go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed mid-cap specialists holding dense regional service networks but lacking oil-free certification portfolios for food and beverage vertical penetration. Long-term viability hinges on electrification transition execution and aftermarket revenue mix expansion toward recurring service contracts. Monitor EPA stationary engine compliance deadline acceleration as the critical inflection signal for electric-drive replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Aftermarket Service Platform Expansion | Predictive maintenance contracts capture replacement cycles in India's fragmented machine shop base. |
| Battery-Electric Portable Product Line | Urban emissions restrictions in China's construction zones accelerate gasoline-to-electric substitution. |
| Oil-Free Certification Investment | FSSAI hygiene mandates and ISO 8573 Class 0 requirements compel food processor specification premiums. |
| Backward Integration into Aluminum Casting | Chinese and Indian rolling mill partnerships reduce pressure vessel fabrication cost volatility exposure. |
| Regional Manufacturing Footprint Expansion | Tamil Nadu and Gujarat proximity shortens lead times for PLI-linked automotive tier supplier demand. |
Methodological Framework
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base for this reciprocating air compressor market assessment. Primary field engagement across India's industrial corridors, Germany's Baden-Württemberg automotive clusters, and the US Rust Belt manufacturing belt combined with secondary validation from SEC 10-K filings, customs and trade data, and EPA regulatory dockets. Bottom-up equipment shipment analysis triangulated against top-down industrial pneumatic demand modeling to establish volume and value estimates.
Sensitivity analysis around copper and steel input price trajectories, PLI scheme implementation pace, and stationary engine emissions compliance deadlines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include compression stage configuration, end-use vertical duty cycle intensity, power source architecture, and regional regulatory cluster. CAGRs derived from installed base replacement dynamics, capacity expansion announcements, and efficiency upgrade economics across food processing and automotive manufacturing verticals.
Material uncertainties — commodity price volatility, grid reliability fluctuations in India's manufacturing corridors, and rotary screw substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions regarding EPA enforcement consistency, F-Gas Regulation phasedown schedules, and PLI beneficiary capital commitment timelines. Recalibration cycles align with material shifts in base metal pricing, emissions regulation stringency, and industrial electrification policy announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Booster Compressor Market
Compressors
PAG Compressor Oil Market
Compressors
Compressed Air Lubricators Market
Compressors
Gas Compressors Market
Compressors
Reciprocating Hydrogen Compressor Market
Compressors
Regenerative Blowers Market
Compressors
Centrifugal Compressors Market
Compressors
Hydrogen Compressor Market
Compressors
North America Centrifugal Compressor Market
Compressors
Oil Filled Air Compressor Market
Compressors
Russia Reciprocating Compressor Market
Compressors
USA Scroll Compressor Market
Compressors
Asia-Pacific Booster Compressor Market
Compressors
North America Air Compressor Market
Compressors
High Speed Blowers Market
Compressors
Axial Compressor Market