
 Global Floating LNG Terminal Market | 2026-2036
Global Floating LNG Terminal Market Size, Share, and Industry Trends Forecast 2026-2036
Global Floating LNG Terminal Market Analysis
Qatari liquefaction expansions is realigning global floating terminal deployment schedules. Shell plc leverages its integrated LNG trading arm to secure long-term FSRU offtake agreements across emerging demand centers. Höegh LNG Holdings Ltd. dominates the specialized FSRU ownership segment with one of the largest purpose-built fleets in commercial operation.
A floating LNG terminal is a marine-based facility—typically a converted vessel or newbuild hull—equipped with cryogenic storage tanks, regasification trains, and offloading systems that process, store, and transfer liquefied natural gas at temperatures near minus 162 degrees Celsius. These terminals serve coastal markets lacking onshore infrastructure by receiving LNG carrier deliveries and injecting regasified product directly into national grids or industrial offtakers. FSRU vessels anchor the installed base owing to lower capital requirements and faster deployment timelines versus greenfield onshore terminals. FLNG units command concentrated engineering margins due to their integrated liquefaction complexity and limited supplier pool. LNG bunkering infrastructure represents the fastest-growing service layer as port authorities mandate cleaner marine fuels under emission control area rules.
The International Maritime Organization enforces sulfur caps that redirect vessel operators toward LNG propulsion, directly expanding bunkering terminal demand. ISO 28460 and SIGTTO guidelines govern cargo transfer safety standards, shaping equipment certification requirements for terminal operators and vessel constructors. Stakeholders must monitor liquefaction project final investment decisions in Qatar and Mozambique, as these supply pulses determine FSRU charter rate trajectories and fleet utilization patterns.
Market Dynamics
Qatar's liquefaction capacity expansions are compressing global FSRU deployment timelines as charterers front-load terminal commitments to capture 2026-2027 supply waves. This supply pulse concentration is redistributing vessel availability across Southeast Asian import markets.
Growth Catalysts
- IMO 2020 Sulfur Caps:The International Maritime Organization's sulfur emission limits are redirecting vessel operators toward LNG propulsion, directly expanding bunkering terminal demand at major transshipment hubs.
- Indonesia Power Demand:PLN's electrification targets anchor multiple FSRU contracts as the state utility seeks rapid baseload capacity without onshore construction delays.
- FLNG Technology Maturation:Integrated liquefaction systems are unlocking stranded gas fields previously uneconomical for development, expanding the addressable resource base for floating production.
Market Restraints
- Specialized Hull Supply Concentration:Purpose-built FSRU construction relies on a limited pool of South Korean and Chinese shipyards, creating orderbook bottlenecks during demand surges.
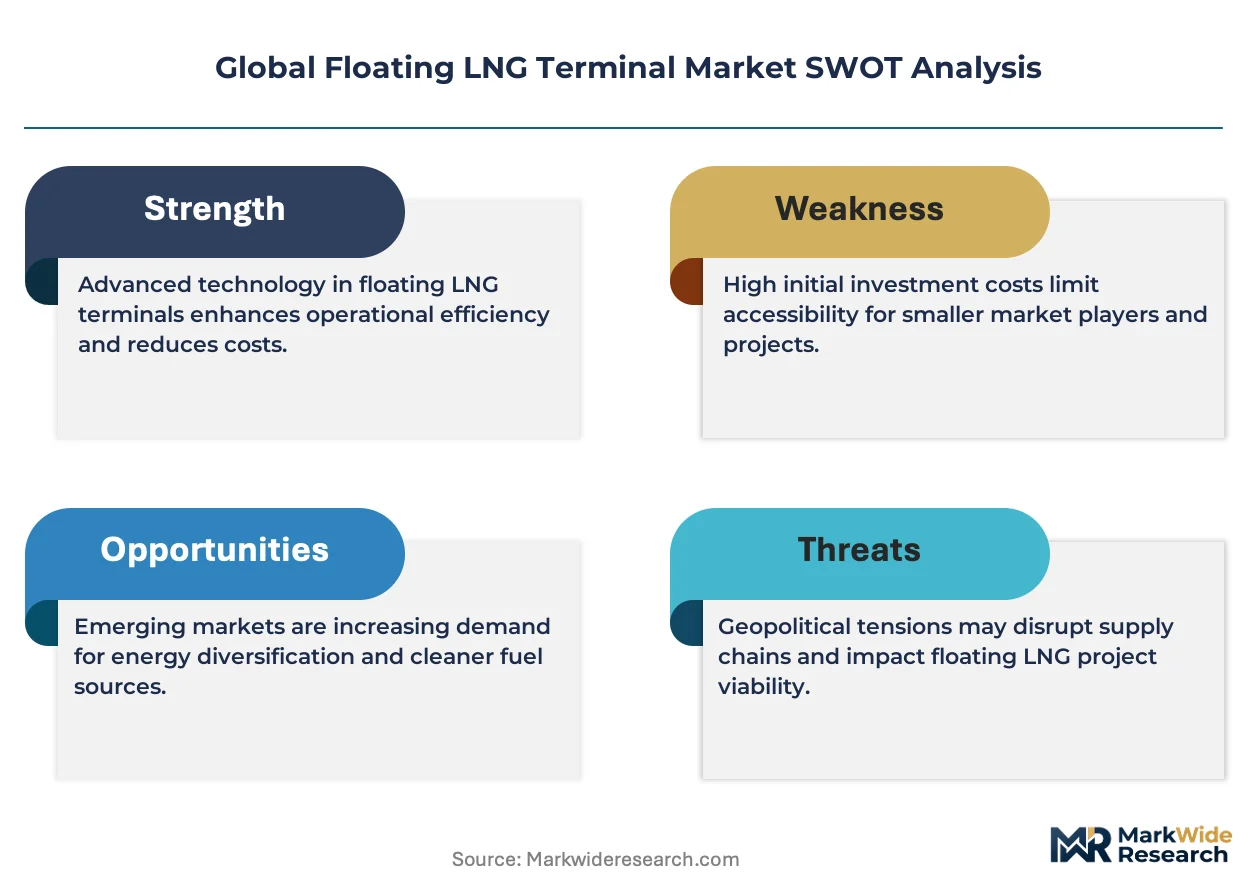
- Cryogenic Equipment Cost Volatility:Nickel alloy prices for containment systems and regasification heat exchangers inject margin uncertainty into newbuild quotations.
- Long-Term Charter Rigidity:Twenty-year take-or-pay structures limit offtaker flexibility when spot LNG prices diverge from contracted slopes, deterring smaller market entrants.
Strategic Opportunities
- Vietnam Power Deficit:The country's southern industrial zones lack pipeline connectivity, creating immediate demand for offshore regasification serving combined-cycle gas turbines.
- ISO 28460 Certification Alignment:Standardized cargo transfer safety protocols are reducing insurance premiums for compliant operators, improving project returns.
- LNG-to-Power Integration:Floating storage units paired with mobile power barges are converging to serve island grids in the Philippines and Papua New Guinea.
Industry Challenges
- Cryogenic Welding Certification Delays:Qualified technicians for nine-percent nickel steel fabrication remain scarce, extending construction timelines at specialized yards.
- Legacy Grid Interconnection:FSRU projects in Myanmar and Bangladesh face complex negotiations with state utilities over offtake metering and pressure regulation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Floating LNG Terminal Market |
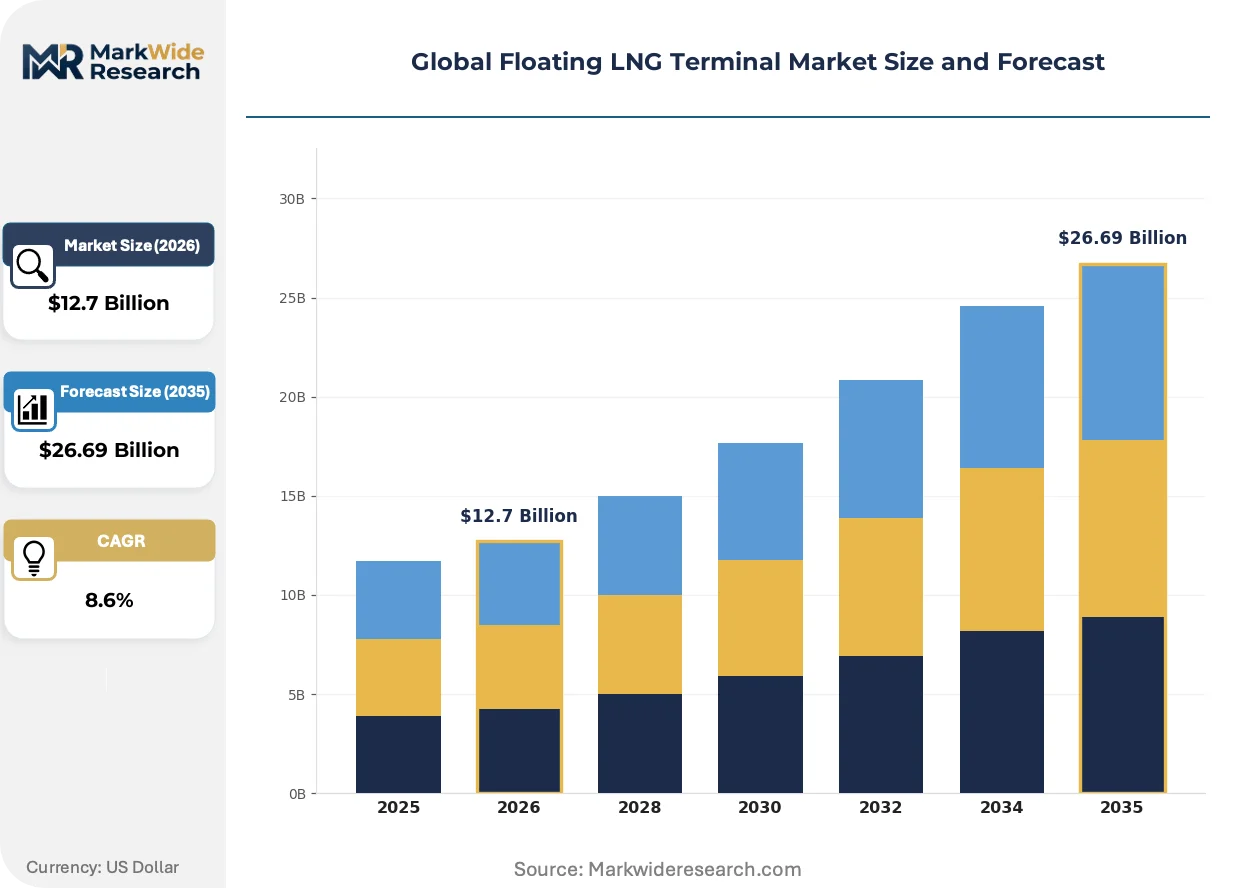
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $26.69 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FSRU, FLNG, LNG Bunkering, LNG Carrier End User: Utilities, Industrial Players, Shipping Companies, Exporters Technology: Regasification, Liquefaction, Loading Systems, Storage Solutions Service Type: Operation & Maintenance, Transportation, Engineering, Consulting |
| Companies Covered | Petroliam Nasional Berhad (PETRONAS), Mitsui O.S.K. Lines, Shell plc, Golar LNG Limited, Höegh LNG Holdings Ltd., ExxonMobil Corporation, Chevron Corporation, Woodside Energy Group Ltd, TotalEnergies SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Floating LNG Terminal Market Emerging Trajectories
Regulatory emission mandates and supply chain compression are accelerating technology adoption across floating terminal operations. Equipment standardization and digital integration are reshaping how charterers evaluate vessel performance.
Regasification train designs are modularizing as engineering firms package liquefaction and vaporization skids into standardized forty-foot container formats. Independent power producers in Southeast Asia are adopting these configurations for rapid redeployment between seasonal demand peaks. This standardization is modularizing project development cycles, compressing feasibility-to-operation timelines from thirty-six months to under eighteen.
Europe's F-Gas Regulation is phasing down fluorinated greenhouse gas use in onboard refrigeration systems, forcing terminal operators to evaluate ammonia or CO2 cascade alternatives for cargo boil-off management. Equipment suppliers are recertifying compressor packages under ECHA guidelines ahead of mandatory conversion deadlines. The retrofit obligation concentrates most acutely on FSRU vessels chartered under EU-flagged registries or operating in North Sea emission control areas.
Utility procurement departments are unbundling long-term charter commitments into separate vessel, regasification, and maintenance contracts to improve cost transparency. This disaggregation allows PLN and comparable state buyers to benchmark operational performance against spot-market alternatives. The practice is most visible in Indonesia, where 2024 tender documents explicitly separate capital recovery from operating expenditure components.
Global Floating LNG Terminal Market Segmentation
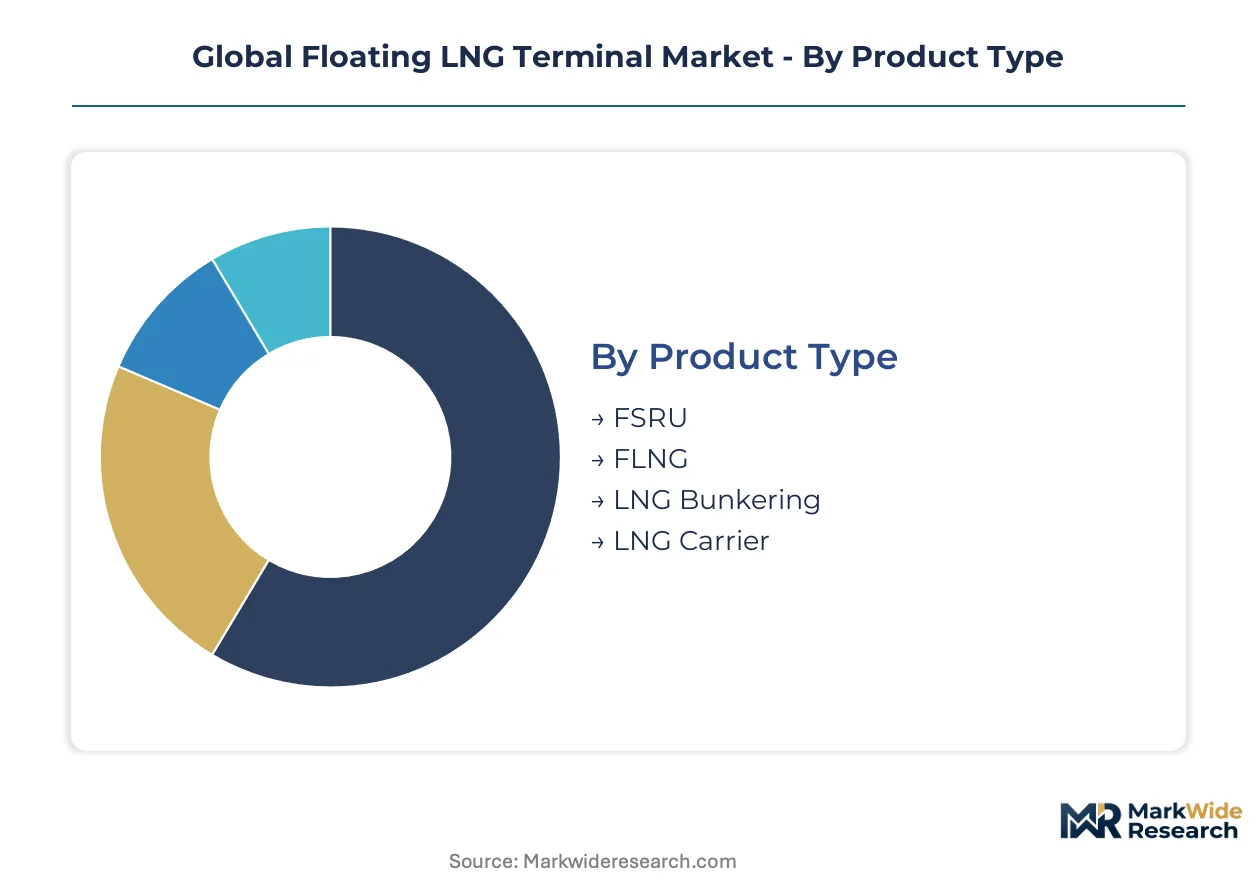
Floating LNG terminal procurement decisions hinge on vessel configuration, end-use application, and technology integration. Segment boundaries blur as charterers demand bundled solutions combining storage, regasification, and bunkering capabilities on single hulls.
Product Type:
Replacement cycles accelerate as early FSRU conversions reach structural survey deadlines, forcing charterers to evaluate newbuilds against life-extension refits.
- FSRU:Purpose-built hulls with membrane or spherical containment systems process LNG carrier deliveries through submerged turrets or side-by-side offloading arms. Indonesia's PLN anchors the largest procurement pipeline, with multiple twenty-year charters displacing aging onshore terminals in Java and Sumatra.
- FLNG:Integrated liquefaction trains mounted on barge or ship-shaped hulls unlock stranded gas fields without pipeline infrastructure. Mozambique's offshore developments and Qatar's North Field expansions concentrate engineering demand for these high-complexity units.
- LNG Bunkering:Specialized feeder vessels and shore-based systems supply LNG fuel to IMO 2020-compliant tankers and container ships at Singapore, Rotterdam, and Busan.
- LNG Carrier:Conventional transport vessels increasingly double as floating storage during demand troughs, with slow-steaming ballast voyages extending effective terminal availability.
FSRU sits at the top of the volume ranking, with LNG Bunkering climbing the fastest.
End User:
Customer procurement maturity varies sharply across utility, industrial, and maritime segments, dictating contract structure preferences.
- Utilities:State-owned power generators in Southeast Asia dominate long-term FSRU charters, seeking baseload gas supply without onshore construction risk. Bangladesh's Petrobangla and Pakistan's Sui Southern Gas Company anchor regional demand through sovereign-backed offtake agreements.
- Industrial Players:Fertilizer manufacturers, petrochemical complexes, and steel mills procure spot regasification capacity where pipeline interconnects remain incomplete. Vietnam's southern industrial zones lack grid connectivity, driving direct FSRU-to-factory arrangements.
- Shipping Companies:Container lines and tanker operators contract bunkering services at emission control area ports, with Mediterranean and Baltic Sea routes mandating LNG fuel compliance.
- Exporters:Portfolio traders and national oil companies charter FLNG units for stranded field monetization, with QatarEnergy and Shell plc anchoring liquefaction-focused deployment.
Utilities command the dominant contract value share, while Industrial Players are expanding most quickly.
Technology:
Technology selection follows feed gas characteristics and product specifications, with modular designs compressing deployment timelines.
- Regasification:Open-rack vaporizers and submerged combustion units convert cryogenic LNG to pipeline-pressure gas. Coastal terminals in Turkey and Brazil favor open-rack systems for ambient heat utilization.
- Liquefaction:Mixed-refrigerant and nitrogen-expansion cycles cool feed gas to minus 162 degrees Celsius. Pre-salt developments offshore Brazil and East African fields drive demand for compact liquefaction trains.
- Loading Systems:Cryogenic transfer arms and tandem offloading configurations connect carrier vessels to terminal hulls. ISO 28460 certification requirements shape equipment procurement specifications.
- Storage Solutions:Membrane tanks from GTT and SPB independent tanks from IHI offer alternative containment architectures, with membrane systems dominating newbuild FSRU orders.
Regasification holds the installed base lead, with Liquefaction posting the steepest expansion trajectory.
Service Type:
Service unbundling allows charterers to benchmark operational performance and optimize lifecycle costs.
- Operation & Maintenance:Crewing, cargo management, and regulatory compliance services dominate recurring expenditure. Höegh LNG and Excelerate Energy anchor third-party O&M provision.
- Transportation:LNG carrier chartering and feeder logistics connect import terminals to downstream markets. Spot vessel availability tightens during Qatari supply expansion waves.
- Engineering:Front-end design, construction supervision, and commissioning support concentrate among specialized marine engineering firms.
- Consulting:Regulatory navigation, offtake structuring, and risk advisory services support project finance due diligence.
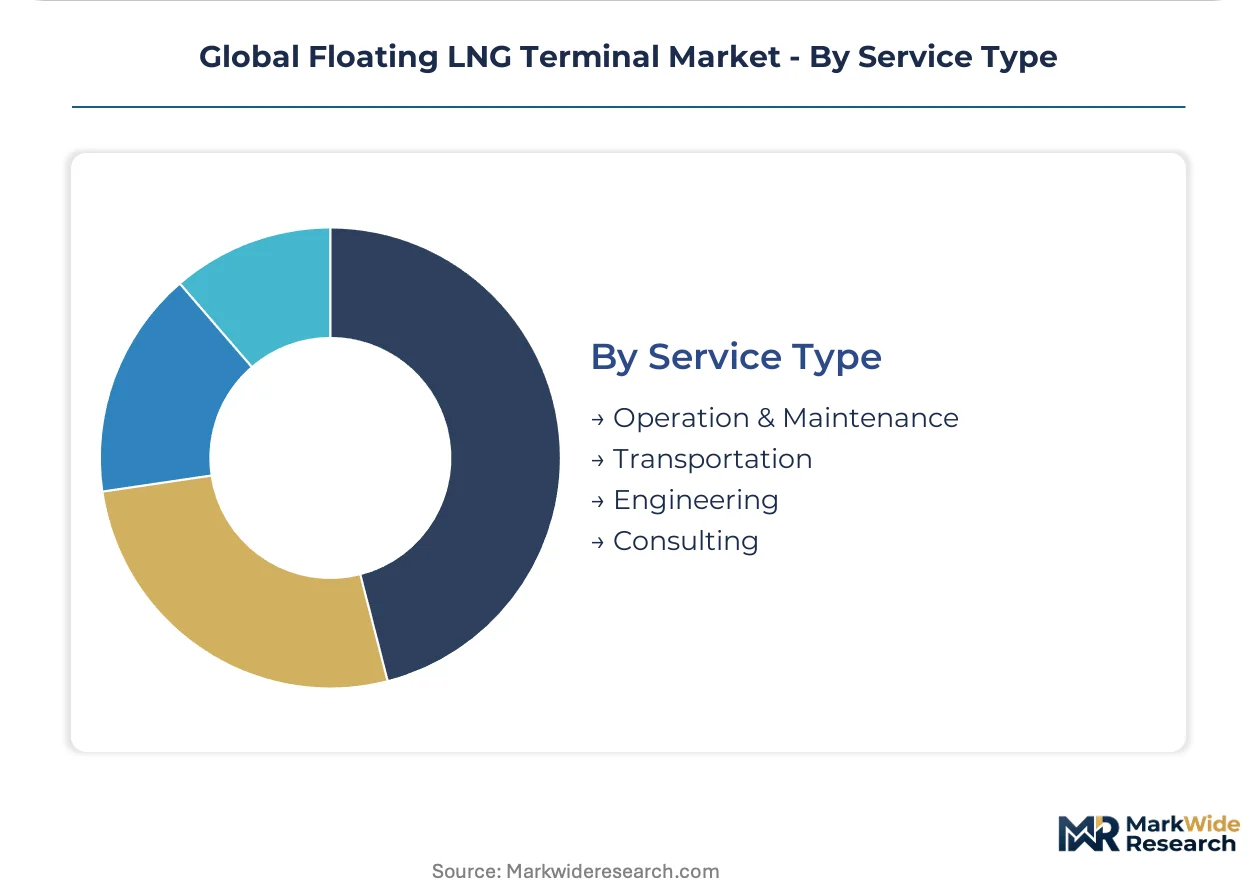
Operation & Maintenance generates the largest revenue pool, with Consulting gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials between Asian shipyards and European engineering centers are redistributing floating terminal construction contracts toward South Korean and Chinese builders, compressing delivery timelines for FSRU hulls while European yards retain liquefaction train integration work.
Indonesia
PLN's electrification program anchors the largest FSRU procurement pipeline in Southeast Asia, with state-backed twenty-year charters displacing aging onshore terminals across Java and Sumatra. The Ministry of Energy and Mineral Resources mandates domestic content requirements for terminal components, shaping local fabrication partnerships. Industrial clusters in Batam and Surabaya host regasification module assembly operations serving PLN's Lampung and Bali projects.
Qatar
North Field liquefaction expansions are compressing global FSRU deployment schedules as charterers front-load terminal commitments to capture 2026-2027 supply waves. QatarEnergy's procurement standards enforce ISO 28460 certification for all cargo transfer equipment, elevating supplier qualification barriers. Ras Laffan Industrial City concentrates engineering oversight for FLNG hull specifications and integrated liquefaction system commissioning.
United States
Gulf Coast export capacity expansions are redirecting FSRU vessel availability toward European and Asian import markets as domestic demand absorbs conventional LNG carrier fleets. FERC permitting timelines for onshore terminals push developers toward floating alternatives in Puerto Rico and Alaska. Industrial corridors along the Houston Ship Channel host engineering design centers for regasification train modularization and cryogenic equipment specification.
Vietnam
Southern industrial zones in Ba Ria-Vung Tau lack pipeline connectivity, creating immediate demand for offshore regasification serving combined-cycle gas turbines. The country's national power development plan prioritizes LNG-to-power projects without grid transmission infrastructure, favoring floating terminal solutions. The Cai Mep-Thi Vai port complex anchors FSRU mooring studies and marine terminal licensing negotiations with provincial authorities.
Brazil
Pre-salt gas field developments offshore Santos Basin are driving FLNG engineering demand for stranded resource monetization without subsea pipeline infrastructure. ANP regulatory frameworks for floating production units are adapting to accommodate integrated liquefaction systems on converted hulls. The Rio de Janeiro technology corridor hosts project management offices for mixed-refrigerant cycle optimization and compact liquefaction train design.
Global Floating LNG Terminal Market Vendor Landscape
South Korean shipyards anchor one tier of hull construction; European engineering specialists hold liquefaction system integration and regasification technology licensing. The vendor base separates into three strategic tiers: integrated oil companies with captive project demand, independent vessel owners chartering to utility offtakers, and specialized engineering firms licensing containment and process technology. Dominant competitive moves include long-term charter contracting to lock in utilization rates and modular equipment standardization to compress construction timelines.
Within the integrated oil company tier, Shell plc and ExxonMobil Corporation exemplify portfolio players combining upstream liquefaction equity with downstream terminal offtake commitments. Among independent vessel operators, Höegh LNG Holdings Ltd. and Golar LNG Limited occupy positions as specialized FSRU owners with purpose-built fleets in commercial operation. Mitsui O.S.K. Lines represents the Japanese trading house archetype, bridging ship finance, LNG carrier operations, and terminal chartering through diversified maritime platforms.
| Leading Market Players |
|---|
| Petroliam Nasional Berhad (PETRONAS) |
| Mitsui O.S.K. Lines |
| Shell plc |
| Golar LNG Limited |
| Höegh LNG Holdings Ltd. |
| ExxonMobil Corporation |
| Chevron Corporation |
| Woodside Energy Group Ltd |
| TotalEnergies SE |
| Others |
Supply Flow & Price Mechanics
Qualified cryogenic welding technicians concentrated in South Korean shipyards widen pricing-tier spreads between premium newbuild FSRU hulls and economy-tier converted LNG carriers, as labor-cost differentials compound with nickel-alloy containment system premiums.
Pricing Analysis
Direct-to-utility charter rates dominate terminal economics, compressing distributor margins that intermediaries once captured in spot vessel brokering. Price differentiation hinges on ISO 28460 certification tier and hull membrane containment grade, with GTT-licensed membrane systems commanding premiums over SPB independent tank configurations. Pricing pressure stems from South Korean yard orderbook congestion as QatarEnergy front-loads FLNG commitments. State utilities in Indonesia and Bangladesh exhibit lowest price sensitivity due to sovereign-backed offtake structures, while industrial spot buyers in Vietnam's southern zones negotiate hardest on regasification tariffs.
Supply Chain Analysis
Workforce availability constraints in South Korean and Chinese specialized yards tether hull delivery schedules to nine-percent nickel steel fabrication certification pipelines. Raw material dependencies center on nickel alloys for cryogenic containment, mixed-refrigerant liquefaction packages from European engineering houses, and submerged turret mooring systems from Norwegian suppliers. Single-source vulnerability concentrates in GTT's membrane tank licensing monopoly. Distribution runs through long-term charter contracting direct to state utilities, bypassing spot market intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by twenty-year take-or-pay utility charters that insulate vessel owners from LNG price volatility.
For Market Incumbents: Lock in orderbook slots at Hyundai Heavy Industries and Samsung Heavy Industries before Qatar's liquefaction expansion wave saturates yard capacity. Secure backward integration into cryogenic equipment supply through captive relationships with nickel alloy foundries to defend margins against commodity volatility. ISO 28460 certification investments create switching costs that deter charterer defection to emerging vessel operators.
For New Entrants and Emerging Players: The price-point gap between premium purpose-built FSRUs and economy converted carriers opens white-space in Southeast Asian industrial zones requiring sub-five-year deployment timelines. Target Vietnam's Ba Ria-Vung Tau power corridor where pipeline infrastructure gaps force direct FSRU-to-factory arrangements outside PLN's centralized procurement. Pursue modular regasification skids in standardized container formats as the go-to-market angle for rapid redeployment between seasonal demand peaks.
For Investors and Strategic Acquirers: Valuations sit cheapest among independent vessel operators with aging fleets facing structural survey deadlines, where charter rate recovery potential offsets near-term capital expenditure burdens. Five-to-ten year viability hinges on fleet renewal execution rather than spot market exposure. Watch FID timelines for Mozambique and Qatar liquefaction projects as the inflection signal determining FSRU utilization trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Charter Contracting | Shell plc and Höegh LNG anchor utilization through PLN's twenty-year offtake structures. |
| Backward Integration into Containment Systems | Captive nickel alloy sourcing insulates margins against Korea Zinc and Vale price volatility. |
| Modular Regasification Standardization | Forty-foot container formats compress Indonesia project timelines from thirty-six to eighteen months. |
| ISO 28460 Certification Investment | QatarEnergy's cargo transfer standards elevate barriers for non-compliant equipment suppliers. |
| FLNG Technology Licensing | Mixed-refrigerant cycle patents from Air Products and Linde unlock stranded Mozambique gas monetization. |
Methodological Framework
Multiple input streams — structured interviews with FSRU chartering managers, EPC contractor project directors, and shipyard planning officers; secondary validation through Lloyd's List vessel databases, FERC import terminal filings, and IEA LNG trade statistics; plus customs records for cryogenic equipment trade flows — were reconciled through bottom-up vessel deployment tallies and top-down LNG import demand modeling.
Historical charter rate trajectories were cross-referenced against panel input from utility procurement executives to anchor projections across the analysis window. Segmentation dimensions modeled include vessel configuration tier, end-use application, technology integration type, and regional regulatory framework cluster. CAGRs were derived from fitted growth curves calibrated to liquefaction project FID schedules and national power development plan commitments.
Caveats apply where Qatar North Field expansion delays, nickel alloy price spikes, or IMO 2020 enforcement variability could materially shift the outlook. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Refinery Maintenance Services Market
Oil & Gas
Large Scale LNG Terminal Market
Oil & Gas
Oil & Gas Defoaming Separator Market
Oil & Gas
North America Coiled Tubing Services Market
Oil & Gas
Malaysia Oil and Gas Pipeline Market
Oil & Gas
Middle-East and Africa Liner Hanger System Market
Oil & Gas
LAMEA Oilfield Auxiliary Rental Equipment Market
Oil & Gas
Asia-Pacific Oil and Gas Storage Tank Market
Oil & Gas
Subsea Well Intervention Market
Oil & Gas
Modular Refinery Market
Oil & Gas
Sensors in Oil and Gas Market
Oil & Gas
United States Oil and Gas Midstream Market
Oil & Gas
Oil and Gas Corrosion Protection Market
Oil & Gas
Kuwait Oil and Gas Market
Oil & Gas
HPHT Cubic Press Market
Oil & Gas
Russian Federation Oil and Gas Upstream Market