
 Tidal Power Market | 2026-2036
Tidal Power Market Size, Share, and Industry Trends Forecast 2026-2036
Tidal Power Market Analytics
Marine engineering expertise is collapsing across European tidal energy hubs, creating severe bottlenecks for project developers. Orbital Marine Power leverages its Scottish workforce to sustain turbine deployment in the Pentland Firth. SIMEC Atlantis Energy anchors large-scale barrage development through its MeyGen site operations. Nova Innovation competes in small-scale stream arrays with differentiated subsea connection systems.
Tidal power harnesses kinetic and potential energy from ocean tides through submerged turbines, barrage structures, or dynamic fence configurations, typically operating at water depths of 20-50 meters with rotor diameters spanning 16-20 meters for utility-class units. Its primary purpose is dispatchable baseload generation for coastal grid networks where intermittent wind and solar require firm backup. Tidal stream technology dominates current capital deployment due to lower environmental permitting barriers compared to barrage construction. Offshore installation types capture the fastest-growing project pipeline as floating platform designs reduce seabed foundation costs. Utility-scale capacity segments concentrate margin pools where long-term power purchase agreements from government agencies provide revenue certainty.
The UK's Marine Management Organisation coordinates seabed licensing with Crown Estate lease allocations, while the EU's Renewable Energy Directive sets binding offshore targets that member states transpose into national tidal feed-in tariffs. The International Electrotechnical Commission's IEC 62600 technical specifications govern turbine performance certification and grid connection standards. Stakeholders must monitor evolving consenting timelines as marine spatial planning conflicts with fishing and shipping interests in high-yield tidal channels.
Market Dynamics
Marine engineering talent scarcity is compressing deployment timelines across coastal utilities, forcing developers to compete for a shrinking pool of subsea installation specialists and turbine maintenance crews in high-yield tidal corridors.
Growth Catalysts
- EU Green Deal offshore mandates:Binding renewable targets are accelerating national permitting reforms in member states, reducing consenting timelines for tidal stream arrays in Scottish and French waters.
- Floating platform designs:Reduced seabed foundation costs are unlocking deeper-water sites previously uneconomical for fixed-bottom turbine installation.
- Pentland Firth resource concentration:The United Kingdom's Orkney archipelago corridor hosts the densest cluster of grid-connected tidal stream capacity worldwide.
Market Restraints
- Specialized vessel dependency:Heavy-lift jack-up vessels for turbine installation command day rates that dominate project capex structures.
- Copper and rare-earth magnet volatility:Permanent magnet generators in direct-drive turbines expose manufacturers to dysprosium and neodymium price swings.
- Environmental permitting friction:Marine spatial planning conflicts with fishing and shipping interests delay consenting in high-yield channels.
Strategic Opportunities
- Island grid hybridization:Remote coastal communities in Indonesia and the Philippines seek dispatchable baseload to complement diesel generation.
- Dynamic tidal fence arrays:Modular fence configurations allow phased deployment without full-channel barrage construction.
- UK Contracts for Difference:The allocation round mechanism provides revenue certainty for utility-scale projects through indexed strike prices.
Industry Challenges
- Subsea cable installation expertise:Cross-linked polyethylene cable laying and jointing skills are concentrated among North Sea oil-service veterans nearing retirement.
- IEC 62600 certification timelines:Type certification for novel turbine designs requires multi-year tank testing and sea trials before grid connection approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tidal Power Market |
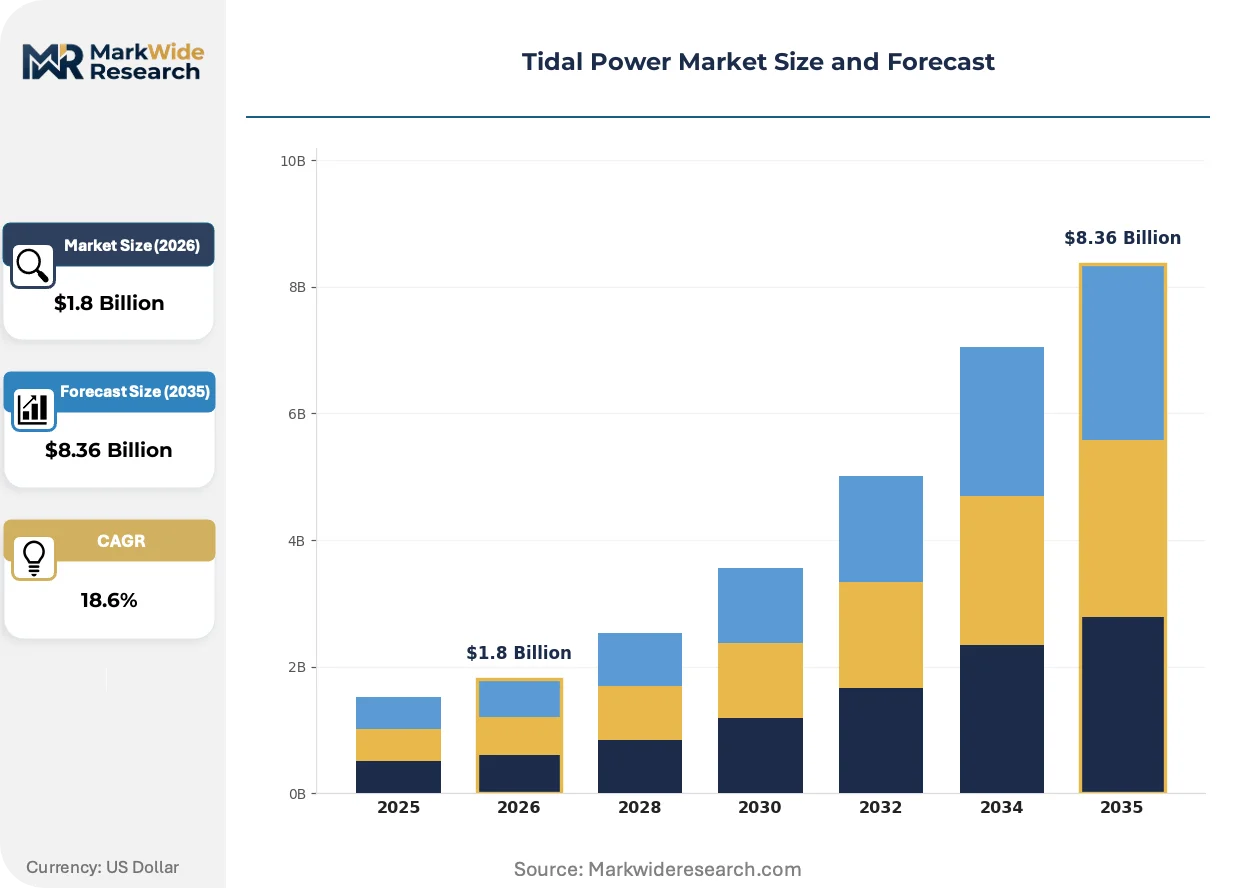
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Tidal Stream, Tidal Barrage, Dynamic Tidal Power, Tidal Kite End User: Utilities, Industrial Plants, Coastal Communities, Government Agencies Installation Type: Onshore, Offshore, Hybrid, Integrated Systems Capacity: Small Scale, Medium Scale, Large Scale, Utility Scale |
| Companies Covered | Orbital Marine Power, SIMEC Atlantis Energy, Minesto AB, Verdant Power, Nova Innovation, Andritz AG, HydroQuest SAS, Sustainable Marine Energy, Magallanes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tidal Power Market Evolving Landscape
Floating platform architectures are unlocking deeper-water sites while regulatory frameworks adapt to accommodate novel consenting pathways for demonstration arrays.
Direct-drive permanent magnet generators are fragmenting the drivetrain supply landscape. These systems eliminate gearbox maintenance burdens that plagued early demonstration units. Offshore wind turbine manufacturers are adapting their nacelle designs for tidal stream duty cycles. The technology is fragmenting traditional marine engineering procurement channels as aerospace and automotive magnet suppliers enter the renewable energy component market.
The EU's Renewable Energy Directive transposition into national feed-in tariffs is reshaping project finance structures. Member states must designate renewable energy acceleration areas for streamlined permitting. French and Scottish developers are prioritizing sites within these zones to compress consenting timelines. Grid operators in both jurisdictions are upgrading coastal substations to accommodate clustered tidal generation.
Power purchase agreement structures are evolving from government-backed tariffs toward corporate offtake arrangements. Large industrial consumers with coastal manufacturing footprints are contracting directly with tidal developers for firm renewable supply. This shift is most visible in the United Kingdom where aluminum smelters and data center operators seek 24/7 carbon-free electricity. Contract tenors are shortening from 20-year government allocations to 10-12 year corporate structures with renegotiation clauses.
Tidal Power Market Segmentation
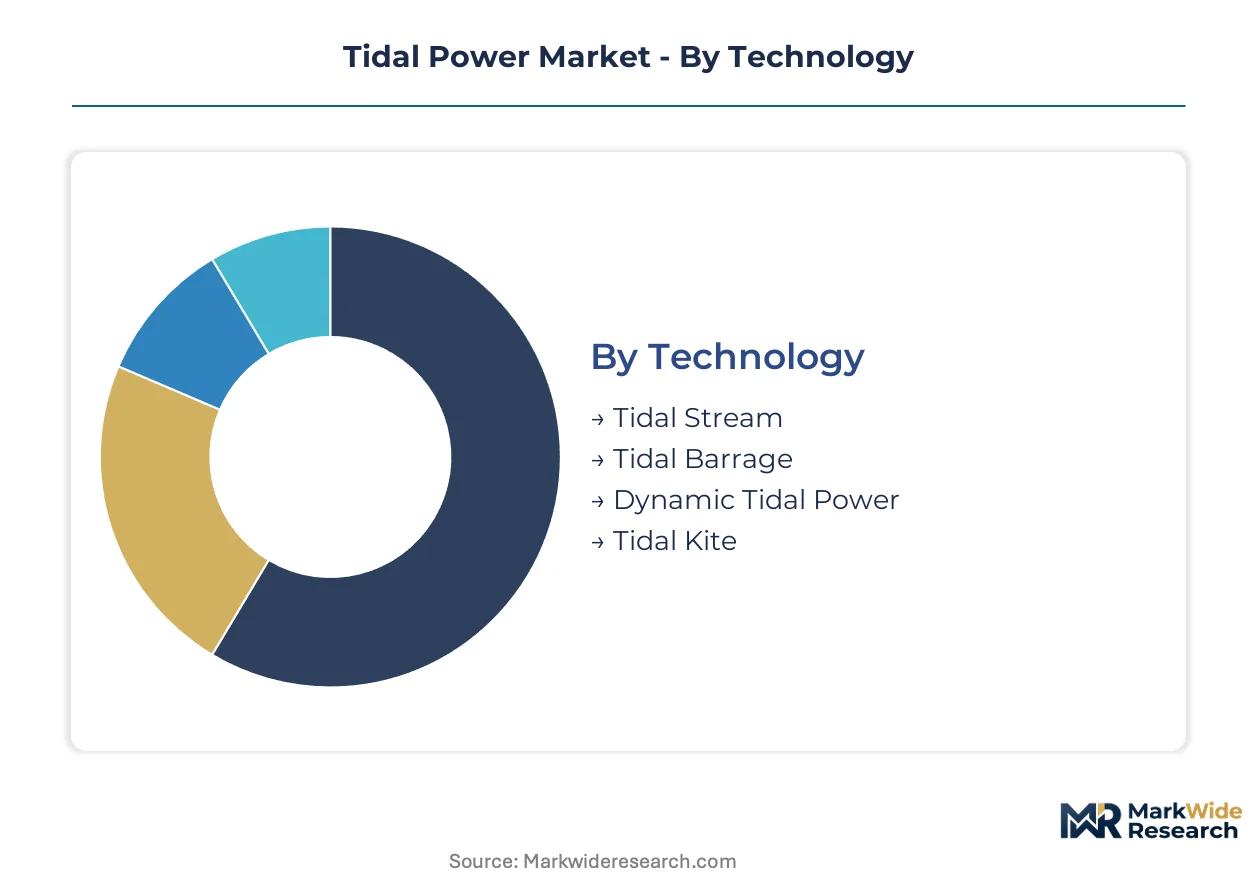
Tidal power segmentation reveals how technology maturity, installation economics, and buyer procurement power concentrate revenue across distinct commercial pockets. Developers must align segment targeting with specific project finance structures and regulatory pathways.
Technology:
Margin pools concentrate in technologies with proven permitting pathways and operational track records that de-risk investor capital.
- Tidal Stream:Submerged horizontal-axis turbines extract kinetic energy from tidal currents at 20-50 meter depths. Pentland Firth developers in Scotland prioritize this technology for its lower environmental review burden compared to barrage construction.
- Tidal Barrage:Dam structures spanning estuaries capture potential energy through sluice gates and bulb turbines. The La Rance facility in France demonstrates multi-decade operational longevity that attracts infrastructure fund capital seeking contracted cash flows.
- Dynamic Tidal Power:Long dam structures perpendicular to coastlines generate head differences without enclosed basins. Dutch and South Korean engineering consortia evaluate this concept for shallow continental shelves with strong coastal currents.
- Tidal Kite:Tethered underwater wings sweep large areas at variable depths to harvest energy from low-velocity currents. Minesto deploys this technology in Welsh waters where traditional fixed turbines face seabed geology constraints.
Tidal Stream holds installed capacity. Dynamic Tidal Power is rotating up the share rankings.
End User:
Procurement power varies sharply across buyer types, with government-backed offtakers commanding strike price negotiations that reshape developer returns.
- Utilities:Vertically integrated coastal grid operators contract for baseload generation to firm intermittent renewable portfolios. Orkney Islands Council and ScottishPower seek dispatchable tidal output to balance North Sea wind variability.
- Industrial Plants:Aluminum smelters and data center operators pursue 24/7 carbon-free power through corporate PPAs. These buyers accept shorter tenors than government allocations but demand renegotiation clauses for technology cost declines.
- Coastal Communities:Island grids in Indonesia and the Philippines hybridize tidal with diesel to reduce fuel import exposure.
- Government Agencies:Defense installations and research stations procure dedicated generation for energy security and demonstration purposes.
Utilities anchor current procurement volume. Industrial Plants are climbing the fastest as corporate renewable targets harden.
Installation Type:
Foundation economics and vessel access dictate where project returns materialize across deployment configurations.
- Offshore:Floating platform designs reduce seabed preparation costs and unlock deeper-water sites. French developers prioritize this approach in the Raz Blanchard channel where fixed foundations face technical limits.
- Onshore:Land-based powerhouses with submerged intake structures serve estuarine barrage projects. The MeyGen phased development in Scotland incorporates onshore substation infrastructure to minimize subsea cable runs.
- Hybrid:Combined fixed-floating systems adapt to variable bathymetry across project sites.
- Integrated Systems:Tidal co-located with wave or offshore wind shares grid connection and maintenance logistics.
Offshore dominates committed capital. Hybrid configurations are gaining share fastest as site-specific engineering optimizes levelized costs.
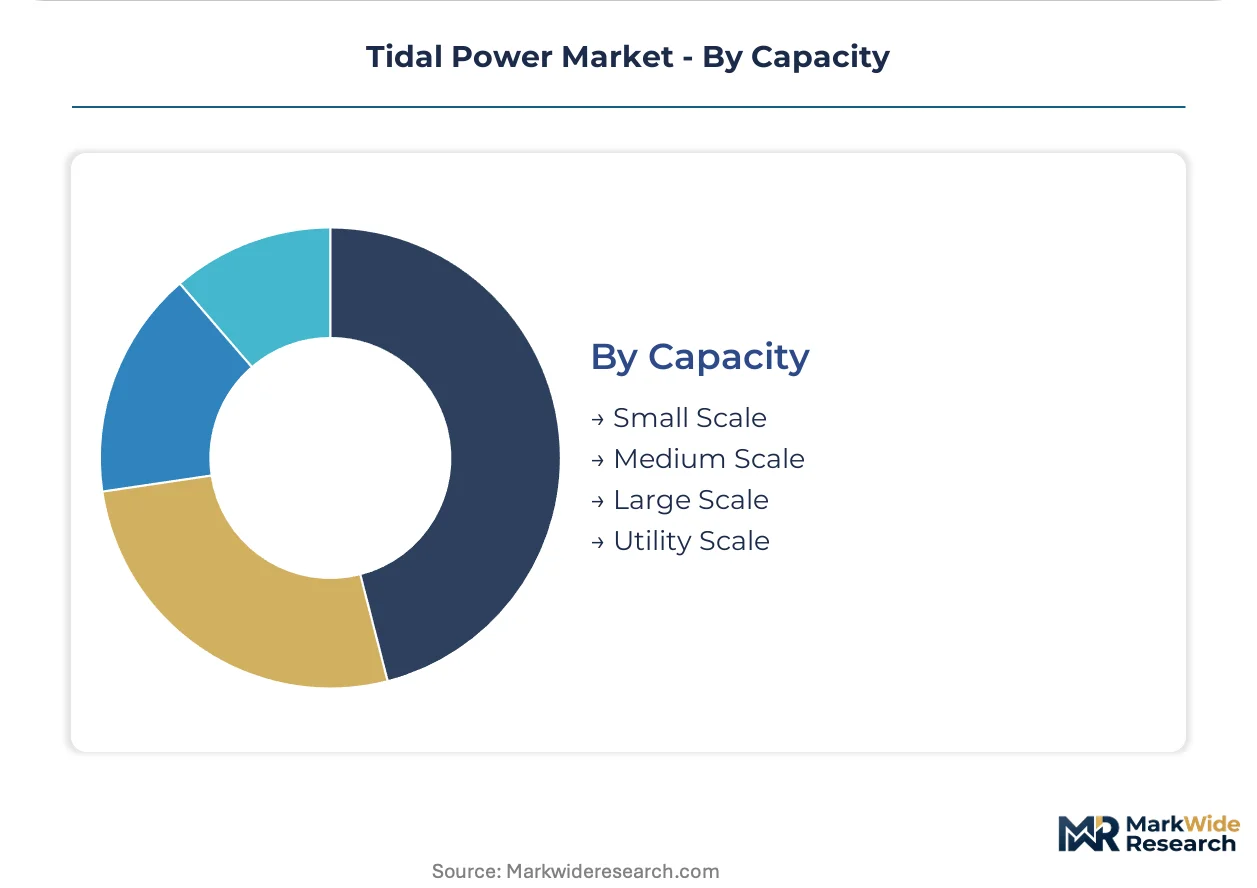
Capacity:
Scale tiers separate demonstration projects from bankable utility assets with access to institutional capital pools.
- Utility Scale:Projects exceeding 50MW capacity access UK Contracts for Difference allocation rounds with indexed strike prices. These developments concentrate in the Pentland Firth where resource density supports clustered turbine arrays.
- Large Scale:10-50MW arrays serve regional grid reinforcement needs with shorter development timelines than utility-class sites.
- Medium Scale:1-10MW installations target island grids and industrial microgrids requiring firm renewable supply.
- Small Scale:Sub-1MW demonstration and community projects validate novel turbine designs before scale-up.
Utility Scale captures institutional capital commitment. Medium Scale is expanding most quickly as remote market applications multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's binding offshore mandates are accelerating national permitting reforms across member states, while the UK's Marine Management Organisation coordinates seabed licensing with Crown Estate lease allocations. Crown Estate lease allocations in Scottish waters command particular attention from developers seeking long-term site security.
United Kingdom
The Pentland Firth and Orkney archipelago corridor hosts the densest cluster of grid-connected tidal stream capacity worldwide. UK Contracts for Difference allocation rounds provide revenue certainty through indexed strike prices for utility-scale projects. MeyGen site operations in Scottish waters anchor large-scale barrage development through phased deployment strategies.
France
The Raz Blanchard channel attracts French developers prioritizing floating platform approaches where fixed foundations face technical limits. ANSM and national maritime authorities coordinate environmental review processes for tidal stream arrays. La Rance facility demonstrates multi-decade operational longevity that attracts infrastructure fund capital seeking contracted cash flows.
Scotland
Marine engineering expertise concentrates around Orbital Marine Power's Scottish workforce sustaining turbine deployment. Crown Estate Scotland manages seabed leasing separate from UK-wide allocations. The Pentland Firth resource density supports clustered turbine arrays with shared grid connection infrastructure.
South Korea
Dynamic tidal power concepts attract Dutch and South Korean engineering consortia evaluating long dam structures for shallow continental shelves. The country's national renewable energy regulator oversees feed-in tariff structures for demonstration projects. Coastal provinces with strong currents are prioritizing marine spatial planning zones for streamlined consenting.
Canada
The Bay of Fundy's extreme tidal range draws developers seeking baseload generation for Atlantic Canada grid networks. Environment and Climate Change Canada coordinates federal environmental assessment processes with provincial regulators. Nova Scotia's FORCE test facility provides grid-connected demonstration infrastructure for technology validation.
Tidal Power Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the tidal power equipment landscape. The upper tier commands project development pipelines through captive installation capabilities and long-term site leases. Specialist players occupy technology niches in turbine design, subsea connection systems, or floating platform architectures. Competitive moves center on strategic partnerships for vessel access and technology licensing agreements for drivetrain components.
Within the integrated developer tier, Orbital Marine Power and SIMEC Atlantis Energy exemplify vertically-structured operators combining turbine manufacturing with site development. Nova Innovation occupies a specialist position in small-scale stream arrays. Minesto AB represents the tidal kite archetype with tethered underwater wing systems. These companies anchor distinct competitive positions without overlapping technology approaches.
| Leading Market Players |
|---|
| Orbital Marine Power |
| SIMEC Atlantis Energy |
| Minesto AB |
| Verdant Power |
| Nova Innovation |
| Andritz AG |
| HydroQuest SAS |
| Sustainable Marine Energy |
| Magallanes |
| Others |
Value Network & Pricing Analysis
Long-term Contracts for Difference lock in both seabed lease access and strike price visibility for UK and French developers, anchoring project finance around indexed revenue streams that compress supplier pricing power while extending component procurement timelines across multi-year buildouts.
Pricing Analysis
UK strike prices diverge from French feed-in tariffs by margins reflecting divergent consenting risk profiles and grid connection cost allocations. The dominant pricing structure is contract-based long-term offtake through government allocation rounds, with price differentiation driven by project scale tier and IEC 62600 certification status. Cost compression in medium-scale arrays is intensifying because floating platform designs reduce foundation expenditures. Coastal utilities exhibit lowest price sensitivity given baseload procurement mandates, while island grid operators in Southeast Asia face acute budget constraints.
Supply Chain Analysis
Strategic stockpiling of rare-earth magnets and copper busbars dominates procurement strategy over just-in-time approaches, given dysprosium and neodymium price volatility exposure. Supply concentrates in China for permanent magnet processing, Scotland for subsea cable jointing expertise, and France for specialized heavy-lift vessel operators. Raw material dependencies span rare-earth elements, high-grade copper, and cross-linked polyethylene insulation. Single-source vulnerability in magnet supply chains threatens turbine manufacturing schedules. Distribution runs through integrated developers with captive installation fleets rather than independent component vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, where Crown Estate lease allocations and marine spatial planning consents create multi-year barriers to site replication that protect incumbent project pipelines.
For Market Incumbents: Secure long-term vessel charter agreements before day-rate inflation erodes project returns, and deepen backward integration into permanent magnet supply chains to hedge against rare-earth price volatility from Chinese export restrictions. For New Entrants and Emerging Players: Anchor in medium-scale island grid deployments across Indonesia and the Philippines where diesel displacement economics justify premium equipment costs, pursuing hybrid system integration as the primary go-to-market angle. For Investors and Strategic Acquirers: Subsea cable installation specialists with North Sea oil-service lineage represent the most defensible acquisition targets, given concentrated expertise and approaching retirement-driven supply contraction. Watch for UK allocation round strike price adjustments as the inflection signal for sector-wide repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Marine Engineering Workforce Development | Scottish technical institutes and French maritime academies must expand subsea certification programs to address talent scarcity constraining deployment timelines. |
| Floating Platform Technology Licensing | Raz Blanchard developers license French floating foundation designs to unlock deeper-water sites in Canadian and South Korean waters. |
| Rare-Earth Magnet Supply Agreements | Direct offtake contracts with Chinese processors reduce exposure to spot market volatility in dysprosium and neodymium pricing. |
| Corporate PPA Structuring | Aluminum smelters and data center operators in coastal UK manufacturing zones contract directly for 24/7 carbon-free baseload supply. |
| Marine Spatial Planning Zone Designation | EU member states must accelerate renewable energy acceleration area declarations to compress consenting timelines under Green Deal mandates. |
Research Methodology
Cross-validation between primary interviews with tidal project developers, marine engineering contractors, and Crown Estate leasing officers anchors the qualitative findings, while secondary validation draws from UK Marine Management Organisation consenting databases, French ANSM environmental review filings, and IEC 62600 certification records. Bottom-up project pipeline aggregation triangulates against top-down regulatory target analysis.
Sensitivity analysis across capacity deployment schedules, strike price indexation assumptions, and rare-earth cost trajectories shapes the analytical framework over the projection horizon. Segmentation dimensions span technology type, installation configuration, capacity tier, end-user procurement archetype, and national regulatory framework. CAGRs derive from installed capacity buildout curves mapped against revenue-per-MW benchmarks. Industry-specific inputs include vessel day-rate forecasts and marine engineering wage inflation assumptions.
Material uncertainties — consenting timeline extensions, magnet supply disruptions, and floating platform performance validation — sit outside the modeled envelope. Forecasts reflect documented assumptions around EU Green Deal transposition schedules and UK Contracts for Difference allocation round frequency. Revision becomes warranted when marine spatial planning conflict resolution timelines exceed baseline thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydropower Systems
Africa Small Hydropower Market
Hydropower Systems
Offshore Hydropower Market
Hydropower Systems
Asia-Pacific Hydropower Market
Hydropower Systems
Europe Small Hydropower Market
Hydropower Systems
Hydro Turbines Market
Hydropower Systems
South America Hydropower Market
Hydropower Systems
Asia-Pacific Pumped Hydro Storage Market
Hydropower Systems
Hydropower Generation Market
Hydropower Systems
Japan Hydropower Market
Hydropower Systems
Europe Hydropower Market
Hydropower Systems
Hydropower Turbine Market
Hydropower Systems
South America Pumped Hydro Storage Market
Hydropower Systems
North America Pumped Hydro Storage Market
Hydropower Systems
Global Hydro Turbine Generator Unit Market
Hydropower Systems
Hydroelectricity Market
Hydropower Systems
Hydropower Market