
 Singapore Bunker Fuel Market | 2026-2036
Singapore Bunker Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Bunker Fuel Market Outlook
Marine fuel procurement channels are reshaping as direct supplier-to-carrier relationships displace traditional broker intermediaries. Shell plc leverages its integrated supply chain to sustain volume leadership in low-sulfur blends. Vitol Bunkers competes through flexible floating storage and barge delivery networks. Exxon Mobil Corporation anchors its position with dedicated terminal infrastructure at Jurong Island.
Singapore bunker fuel comprises residual and distillate marine fuels refined to ISO 8217 specifications, with sulfur content capped at 0.50% mass fraction for conventional grades and 0.10% for emission control areas; its primary purpose is propulsion and auxiliary power generation for commercial vessels. Low Sulfur Fuel Oil dominates volume throughput as the compliant default for post-IMO 2020 operations, while LNG bunkering posts the fastest growth trajectory among fuel types driven by dual-fuel engine retrofits. Container Ships represent the largest vessel-type demand pool, though Offshore Support Vessels generate premium pricing through specialized delivery logistics.
The Maritime and Port Authority of Singapore enforces bunker licensing and mass flow meter mandates, while the IMO's MARPOL Annex VI sulfur regulations determine fuel specification requirements for vessels calling at the port. Singapore's National Environment Agency monitors air quality impacts from bunkering operations, creating compliance costs that filter into supplier pricing structures. Stakeholders must monitor ammonia and methanol pilot projects to anticipate which alternative fuel infrastructure warrants early capital commitment.
Market Dynamics
The IMO's sulfur cap enforcement and the Maritime and Port Authority of Singapore's mass flow meter mandate are compressing supplier margins while accelerating infrastructure investment in alternative fuel terminals.
Growth Catalysts
- Dual-fuel engine retrofits:Container shipping lines are retrofitting vessels to accept LNG bunkering, expanding addressable demand for cryogenic storage infrastructure at Jurong Island.
- MPA licensing consolidation:Stricter bunker supplier licensing by Singapore's port authority is eliminating marginal operators and concentrating volume among certified terminals.
- Malaysian anchorage spillover:Vessel queuing patterns are shifting bunkering demand to Port Klang and Tanjung Pelepas, creating cross-border supply chain extensions.
Market Restraints
- Crude-linked price volatility:Residual fuel oil pricing tracks Dubai crude benchmarks, exposing Singapore bunker suppliers to margin compression during contango periods.
- Terminal concentration risk:Jurong Island handles over 80 percent of physical storage, creating single-point vulnerability for VLSFO blending operations.
- Ammonia infrastructure gap:Zero-carbon ammonia bunkering requires cryogenic storage and toxic gas handling protocols that exceed current terminal specifications.
Strategic Opportunities
- Methanol pilot corridors:The Port of Singapore's methanol bunkering trials with Maersk Line are establishing first-mover protocols for container vessel refueling.
- Digital bunker delivery platforms:Blockchain-based mass flow meter data verification is enabling real-time sulfur compliance documentation for vessel operators.
- Offshore Support Vessel specialization:Premium pricing for dynamic positioning fueling operations at Malaysian oilfield clusters rewards dedicated barge fleets.
Industry Challenges
- Cryogenic engineering shortage:LNG and ammonia bunkering infrastructure requires specialized welding and pressure vessel certification that outpaces Singapore's technical training pipeline.
- Multi-fuel terminal retrofit costs:Converting existing VLSFO storage for methanol or ammonia compatibility demands eight-figure capital commitments with uncertain demand timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Bunker Fuel Market |
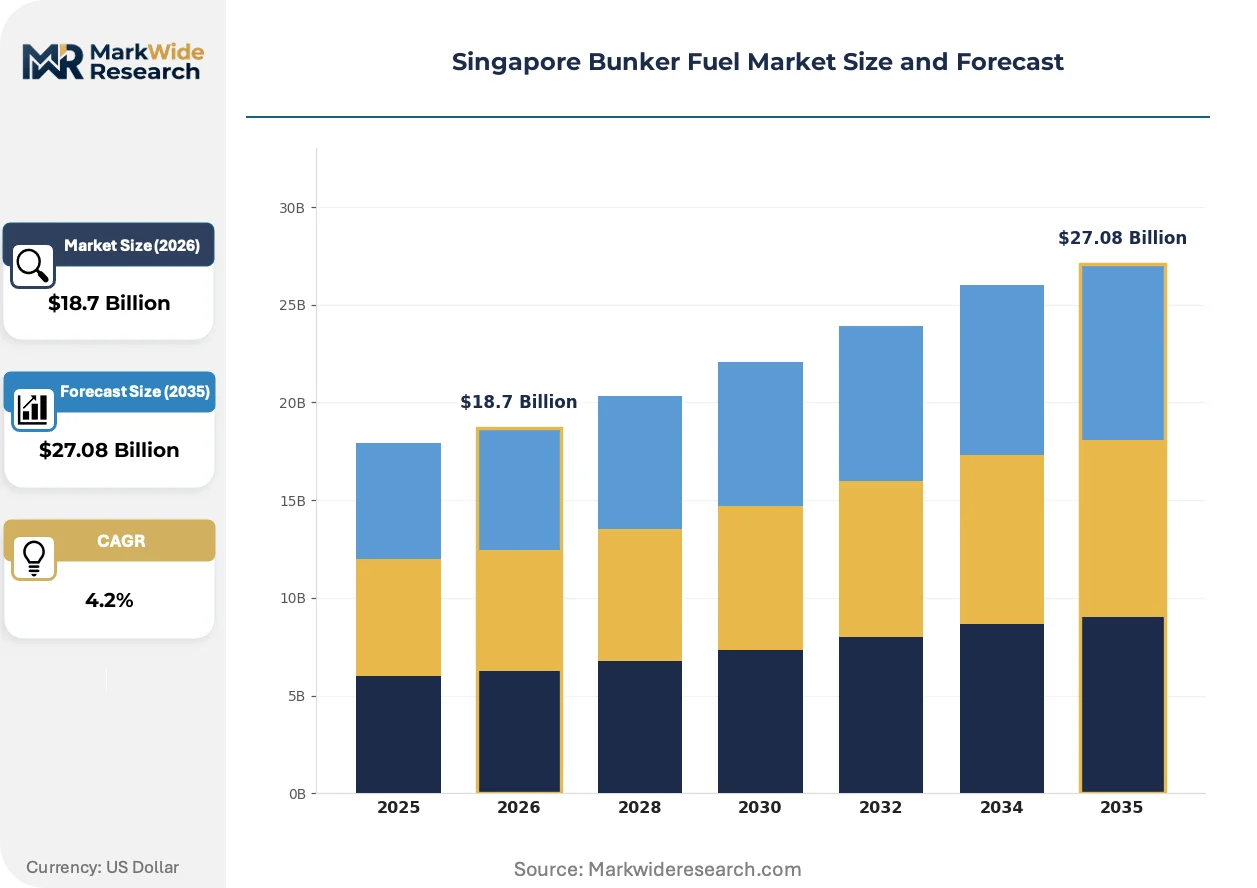
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
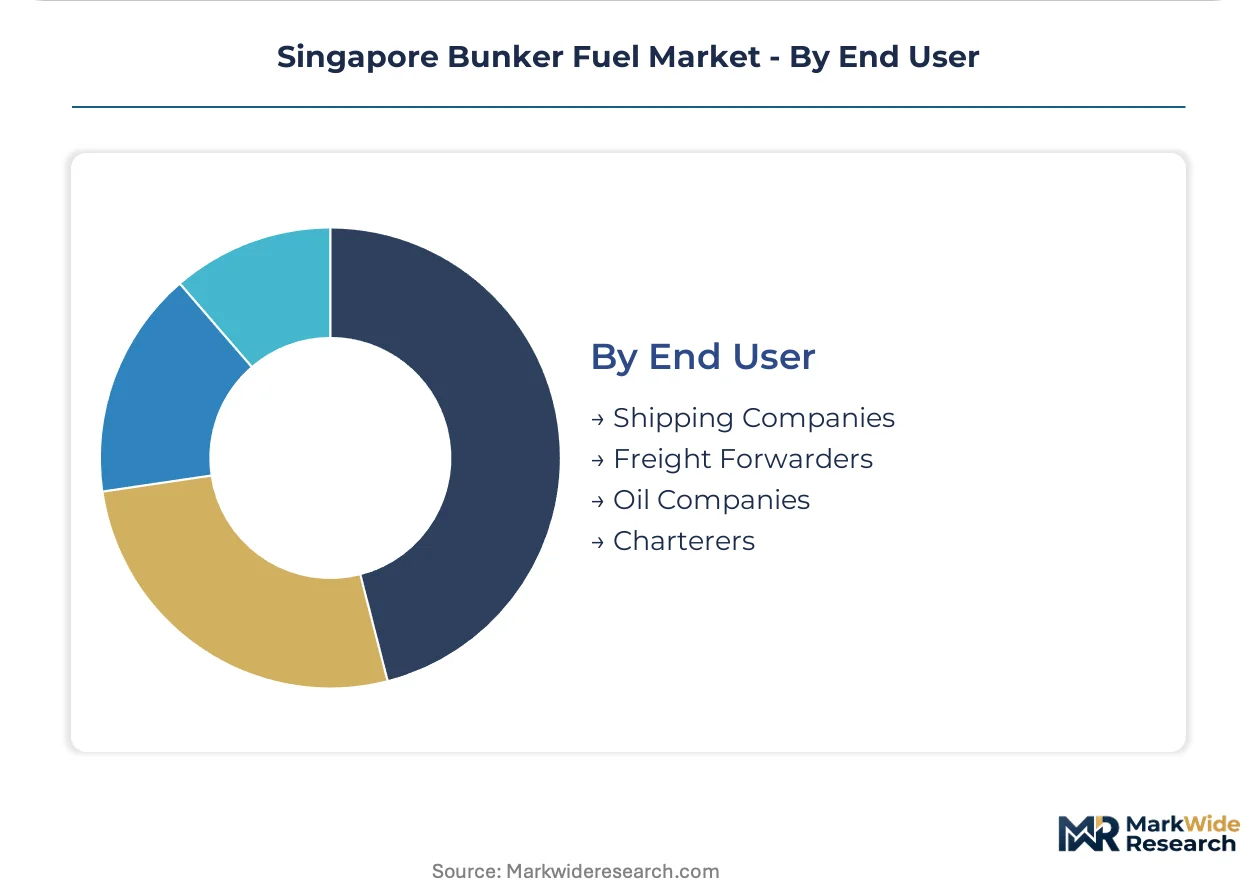
| Segmentation | Fuel Type: Low Sulfur Fuel Oil, Marine Gas Oil, High Sulfur Fuel Oil, LNG Distribution Channel: Direct Sales, Brokers, Online Platforms, Distributors Vessel Type: Container Ships, Bulk Carriers, Tankers, Offshore Support Vessels End User: Shipping Companies, Freight Forwarders, Oil Companies, Charterers |
| Companies Covered | Exxon Mobil Corporation, Vitol Bunkers, Shell plc, Sinopec Fuel Oil (Singapore), Chevron Singapore, BP p.l.c., PetroChina Company Limited, Equatorial Marine Fuel, TotalEnergies SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Bunker Fuel Market Strategic Shifts
Marine fuel supply chains are embedding sensor networks and automated compliance verification to reduce sulfur testing delays and arbitration costs at the point of delivery.
Mass flow meter systems integrated with blockchain verification protocols are digitizing bunker delivery documentation. Container shipping lines now mandate MPA-certified meter data for every Singapore lift, compressing dispute resolution cycles from weeks to hours. The technology is digitizing trust mechanisms between suppliers and buyers, reducing the role of independent surveyors in quantity verification.
Singapore's National Environment Agency is tightening particulate matter monitoring around Jurong Island bunkering zones. The regulator's enhanced air quality surveillance is forcing terminal operators to install vapor recovery units and shore power connections for hotelling vessels. Container terminals at Pasir Panjang are absorbing the highest compliance retrofit costs, passing sulfur emission surcharges to vessel operators.
Direct supplier-to-carrier contracting is displacing traditional bunker broker intermediaries. Major container lines now maintain dedicated procurement desks in Singapore, negotiating annual offtake agreements with Shell and Vitol that lock in volume commitments and sulfur specification guarantees. This pattern is most visible among Asia-Europe trade lane operators with Singapore as their primary Asian hub port.
Singapore Bunker Fuel Market Segmentation

Singapore's bunker fuel segmentation reflects the port's dual role as a compliance checkpoint and a technology transition laboratory. Fuel specifications, vessel categories, and procurement channels each carry distinct margin profiles and infrastructure requirements that shape supplier strategy.
Fuel Type:
Mature refining infrastructure anchors residual fuel grades while cryogenic alternatives emerge from pilot status.
- Low Sulfur Fuel Oil:Blended residual fuel meeting ISO 8217:2017 specifications with 0.50% sulfur mass fraction. Container shipping lines at Pasir Panjang Terminal drive the bulk of demand as the default post-IMO 2020 compliance fuel.
- Marine Gas Oil:Distillate marine fuel with maximum 0.10% sulfur content for emission control area operations. Tankers and cruise vessels calling at Singapore prioritize MGO for auxiliary engines during port stays.
- LNG:Liquefied natural gas bunkering via cryogenic storage at Jurong Island terminals. Dual-fuel retrofits by Asia-Europe container lines are accelerating infrastructure deployment.
- High Sulfur Fuel Oil:Residual fuel above 0.50% sulfur for vessels equipped with exhaust gas cleaning systems. Scrubber-fitted bulk carriers constitute the remaining addressable demand pool.
Low Sulfur Fuel Oil handles the majority of throughput; LNG is the fastest mover on share.
Distribution Channel:
Channel selection tracks procurement sophistication and volume scale across buyer segments.
- Direct Sales:Annual offtake agreements between integrated suppliers and container line procurement desks. Shell and Vitol negotiate direct contracts with Asia-Europe operators that bypass intermediary margins.
- Brokers:Intermediary matching of spot demand with available barge capacity. Spot charterers and smaller freight forwarders rely on broker networks for flexible lift scheduling.
- Online Platforms:Digital matching engines with real-time MPA mass flow meter data verification. Blockchain-enabled platforms are compressing price discovery cycles from days to hours.
- Distributors:Regional fuel oil traders with floating storage and barge fleets. Malaysian anchorage operators extend Singapore supply chains into Port Klang and Tanjung Pelepas.
Direct Sales commands the largest contract value; Online Platforms are expanding most quickly as container lines digitize procurement.
Vessel Type:
Vessel category determines delivery logistics complexity and sulfur specification stringency.
- Container Ships:Scheduled liner services with predictable bunkering windows at Pasir Panjang. Maersk Line and MSC anchor demand through hub-and-spoke Asia-Europe rotations.
- Bulk Carriers:Tramp shipping with irregular port calls and opportunistic lifting patterns. Scrubber-equipped Capesize vessels generate residual HSFO demand at anchorage.
- Tankers:Product and crude carriers with segregated cargo and fuel oil systems. Chemical tankers impose the strictest sulfur verification protocols at point of delivery.
- Offshore Support Vessels:Dynamic positioning vessels serving Malaysian oilfield clusters. Premium pricing rewards specialized barge fleets with DP-2 certification.
Container Ships generate the highest absolute volume; Offshore Support Vessels capture the steepest pricing premium per metric ton.
End User:
End-user category shapes contract structure from spot spot purchases to multi-year offtake commitments.
- Shipping Companies:Liner operators and tramp owners with owned or chartered fleets. COSCO and Evergreen Marine maintain Singapore procurement desks for regional fleet coordination.
- Freight Forwarders:Non-vessel operating common carriers arranging cargo space and fuel as bundled services. Forwarders aggregate smaller shipper demand into bunker procurement pools.
- Oil Companies:Integrated majors with captive refining and trading operations. Exxon Mobil leverages Jurong Island terminal equity for supply security.
- Charterers:Cargo owners responsible for voyage costs under time charter arrangements. Charterers negotiate bunker escalation clauses tied to Singapore 380 CST benchmarks.
Shipping Companies control the dominant procurement volume; Freight Forwarders are gaining share fastest as NVOCCs consolidate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Maritime and Port Authority of Singapore anchors regulatory oversight for Southeast Asian bunkering corridors. Its mass flow meter mandate and licensing protocols cascade across neighboring jurisdictions. Singapore's infrastructure investments at Jurong Island establish the regional benchmark for alternative fuel terminal specifications.
Malaysia
Port Klang and Tanjung Pelepas capture spillover demand from Singapore anchorage congestion. The Malaysian Marine Department enforces port state control aligned with IMO MARPOL Annex VI standards. Barge operators at Tanjung Langsat cluster near Johor Strait terminals, extending Singapore supply chains across the maritime boundary.
Indonesia
Batam and Bintan free trade zones position for transshipment bunkering along the Malacca Strait. Indonesia's Directorate General of Sea Transportation regulates foreign-flagged bunker barges under cabotage restrictions. The Batu Ampar terminal cluster attracts Singapore-based suppliers seeking lower operational cost bases.
China
Zhoushan and Shanghai ports compete for Asia-Europe liner rotations with Singapore hub status. China's Ministry of Transport implements domestic emission control areas requiring 0.10% sulfur fuels at Yangtze River Delta ports. Zhoushan's bonded oil storage capacity expansion challenges Singapore's volume leadership through tax-advantaged pricing.
South Korea
Busan and Ulsan target Northeast Asian container traffic with dedicated LNG bunkering infrastructure. South Korea's Ministry of Oceans and Fisheries subsidizes dual-fuel vessel construction under its Green Ship-K program. The Busan New Port zone aggregates cryogenic storage investments for ammonia pilot projects.
Singapore Bunker Fuel Market Competitive Environment
Integrated oil majors and independent trading houses split the market between terminal infrastructure control and floating storage flexibility. Supplier concentration intensifies as MPA licensing eliminates marginal operators. Three archetypes dominate: integrated majors with captive refining, trading specialists with barge fleet scale, and state-linked entities with upstream supply security. Capacity expansion at Jurong Island terminals and strategic partnerships for methanol bunkering trials represent the dominant competitive vectors.
Within the integrated major tier, Shell plc and Exxon Mobil Corporation exemplify terminal-anchored supply security. Vitol Bunkers occupies a position representing trading-house flexibility through floating storage optimization. These three entities anchor the competitive structure, with Sinopec Fuel Oil (Singapore) representing state-linked upstream integration into the regional supply base.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Vitol Bunkers |
| Shell plc |
| Sinopec Fuel Oil (Singapore) |
| Chevron Singapore |
| BP p.l.c. |
| PetroChina Company Limited |
| Equatorial Marine Fuel |
| TotalEnergies SE |
| Others |
Value Chain & Pricing Dynamics
Jurong Island's 80 percent storage concentration hands integrated majors pricing power over VLSFO blending margins while forcing smaller distributors toward Malaysian anchorage arbitrage. The MPA's mass flow meter mandate adds compliance costs that Shell and Exxon Mobil absorb through scale while independents pass through as sulfur verification surcharges.
Pricing Analysis
Singapore-Malaysia price spreads of 3-5 dollars per metric ton reward barge operators with cross-border floating storage. Contract-based long-term offtake dominates container line procurement, with sulfur specification guarantees and volume commitments replacing spot market exposure. Price differentiation rests on MPA certification status and barge fleet DP-2 capability for offshore deliveries. Cost compression in the broker-mediated spot tier is intensifying because direct supplier-carrier contracting eliminates intermediary margins; freight forwarders show highest price sensitivity while integrated oil companies demonstrate least.
Supply Chain Analysis
Tariff exposure between Singapore and Malaysia dominates supply chain risk as vessel queuing shifts demand across the maritime boundary. Physical supply concentrates in Singapore, Malaysia, and Indonesia, with Batam free trade zones offering cost-advantaged transshipment alternatives. Raw material feeds draw from Middle Eastern sour crude, Australian condensate, and regional VGO for low-sulfur blending. Single-source vulnerability at Jurong Island terminals threatens VLSFO availability during maintenance turnarounds. Distribution runs through integrated terminal-barge networks for direct sales, with spot broker pools handling residual tramp shipping demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's bunker fuel market sits in early-cycle expansion as LNG bunkering infrastructure builds ahead of dual-fuel engine penetration, with methanol and ammonia pilot projects extending the technology transition runway.
For Market Incumbents: Harden terminal infrastructure against multi-fuel retrofit requirements by securing Jurong Island expansion permits before ammonia storage specifications crystallize. Deepen backward integration into cryogenic engineering partnerships to address welding certification shortages that threaten LNG and ammonia project timelines. Lock in container line procurement desks through sulfur specification guarantees that independent traders cannot match. For New Entrants and Emerging Players: Establish a beachhead in Malaysian anchorage services where Port Klang congestion creates barge capacity shortages. Target offshore support vessel fueling at Tanjung Pelepas with DP-2 certified fleets; this segment shows lowest incumbent saturation and steepest pricing premiums. Lead with digital bunker delivery platforms offering real-time MPA mass flow meter verification to capture container lines mandating blockchain documentation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed trading houses lacking terminal equity and exposed to MPA licensing consolidation. Five-to-ten year viability favors suppliers with captive Jurong Island storage or cross-border Malaysian operational platforms. Watch methanol bunkering trial outcomes with Maersk Line as the inflection signal for alternative fuel infrastructure capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Storage Expansion | Jurong Island terminal upgrades enable LNG and ammonia handling for dual-fuel vessel retrofits. |
| Mass Flow Meter Certification | MPA-mandated digital verification reduces sulfur dispute arbitration from weeks to hours. |
| Cross-Border Barge Fleet Deployment | Malaysian anchorage operations capture Singapore queuing spillover at premium pricing. |
| Methanol Bunkering Pilot Partnership | Maersk Line trials establish first-mover protocols for container vessel alternative fueling. |
| Direct Supplier-Carrier Contracting | Annual offtake agreements with Asia-Europe lines displace traditional broker intermediaries. |
Study Parameters
Desk research of customs trade flows, MPA licensing registers, and IMO MARPOL Annex VI compliance filings preceded structured interviews with bunker procurement managers at container lines, terminal operations directors at Jurong Island facilities, marine fuel traders at independent houses, and MPA regulatory affairs officers. Secondary validation drew from Maritime and Port Authority circulars, Singapore National Environment Agency air quality monitoring reports, and Lloyd's List vessel movement databases. Bottom-up volume estimates from barge lift data and top-down demand models from container shipping fleet rotations were triangulated against Singapore Customs bunker sales statistics.
Assumptions held IMO sulfur cap enforcement and MPA mass flow meter mandates as fixed regulatory conditions, while LNG dual-fuel retrofit penetration rates and methanol pilot project scaling were varied across sensitivity bands. Segmentation modeling spanned fuel type, vessel category, distribution channel, and end-user procurement sophistication. CAGRs were derived from historical volume trajectories projected against fleet composition shifts and alternative fuel infrastructure buildout schedules. Forecast inputs included Asia-Europe trade lane container throughput and scrubber-equipped bulk carrier fleet percentages.
Stress conditions across crude price volatility, MPA licensing rejection rates, and Malaysian anchorage regulatory alignment were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding dual-fuel engine adoption curves and cryogenic storage commissioning timelines. Specific risks that could revise projections include ammonia infrastructure specification delays, Indonesia cabotage enforcement tightening, and Zhoushan bonded storage tax advantage expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Diesel Fuel Market
Fuels
Emulsified Fuel Market
Fuels
City Gas Distribution Market
Fuels
Europe Firewood Market
Fuels
Wood Charcoal Market
Fuels
Global Gas Treatment Market
Fuels
Turbine Drip Oil Market
Fuels
Collapsible Fuel Tank Market
Fuels
Canada Bunker Fuel Market
Fuels
Middle-East and Africa Defense Aircraft Aviation Fuel Market
Fuels
Renewable Fuel Quality and Regulatory Compliance Test Instruments Market
Fuels
Global Charcoal Market
Fuels
North America LNG Bunkering Market
Fuels
Global Chemical Logistics Market
Fuels
Gasoline Market
Fuels
China Coal Market