
 Hydropower Market | 2026-2036
Hydropower Market Size, Share, and Industry Trends Forecast 2026-2036
Hydropower Market Analysis
Brazil's Belo Monte complex expansion is narrowing the cost gap between hydropower and combined-cycle gas plants. GE Vernova leverages its turbine manufacturing scale to dominate large-scale impoundment projects across the Americas. Siemens Energy AG anchors European pumped storage modernization through its grid stabilization technology portfolio. Andritz AG specializes in small-to-medium run-of-river installations, competing on modular design flexibility in alpine and Southeast Asian terrain.
Hydropower harnesses gravitational energy from flowing or stored water to rotate turbines connected to electric generators, with modern installations achieving conversion efficiencies exceeding 90 percent through advanced Francis and Kaplan turbine designs. Its primary purpose is dispatchable baseload and peak-shaving electricity supply that stabilizes grids against renewable intermittency. Pumped storage technology leads capital deployment globally as utilities seek multi-gigawatt-hour energy arbitrage capacity. Run-of-river installations represent the fastest-expanding segment where environmental permitting constraints restrict reservoir construction. The utility end-user channel commands the deepest margin pools through long-term power purchase agreements indexed to carbon pricing mechanisms.
The EU Green Deal and F-Gas Regulation shape European project economics by restricting greenhouse gas-intensive grid alternatives and mandating storage-backed renewable portfolios. China's dual carbon goals and MEE river basin ecological redlines are redirecting domestic development toward pumped storage and retrofit markets rather than greenfield dam construction. India's CEA hydropower purchase obligations and PLI scheme for pumped storage components are creating localized manufacturing demand. Stakeholders must monitor sediment management innovations and fish-passage retrofit requirements as regulatory baselines tighten across jurisdictions without grandfathering existing assets.
Market Dynamics
Pumped storage technology is concentrating capital deployment as utilities across Southeast Asia and Europe prioritize grid stabilization over new reservoir construction. The shift reflects tightening environmental permitting and the need for multi-gigawatt-hour energy arbitrage capacity.
Growth Catalysts
- Pumped Storage Procurement:Utilities in Vietnam and the Philippines are expanding procurement of pumped storage systems to balance intermittent solar and wind generation on their grids.
- EU Green Deal Mandates:The EU Green Deal's renewable energy targets are accelerating refurbishment of aging European dam infrastructure with modernized turbine systems.
- Run-of-River Expansion:Run-of-river projects in Brazil's Amazon basin are avoiding the social and environmental costs of large reservoirs while delivering baseload capacity.
Market Restraints
- Environmental Permitting Friction:China's MEE river basin ecological redlines are redirecting domestic development away from greenfield dam construction toward retrofit markets.
- Sediment Management Costs:Aging reservoirs face rising maintenance expenditures as sediment accumulation reduces storage capacity and turbine efficiency.
- Gas Plant Competition:Combined-cycle gas plants in Brazil are narrowing the cost gap with hydropower through improved thermal efficiency and faster deployment timelines.
Strategic Opportunities
- India's PLI Localization:India's CEA hydropower purchase obligations and PLI scheme for pumped storage components are creating localized manufacturing demand and import substitution opportunities.
- Fish-Passage Retrofit Services:Regulatory baselines tightening across jurisdictions without grandfathering existing assets are opening specialized engineering services for environmental compliance upgrades.
- Alpine Modular Deployment:Small-to-medium run-of-river installations in alpine terrain offer modular design flexibility for decentralized grid applications.
Industry Challenges
- Turbine Engineering Talent Scarcity:Advanced Francis and Kaplan turbine design expertise is concentrating among a shrinking pool of specialized engineering firms.
- Legacy Control System Integration:Digital modernization of aging dam infrastructure requires complex integration with mechanical governor systems installed decades prior.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydropower Market |
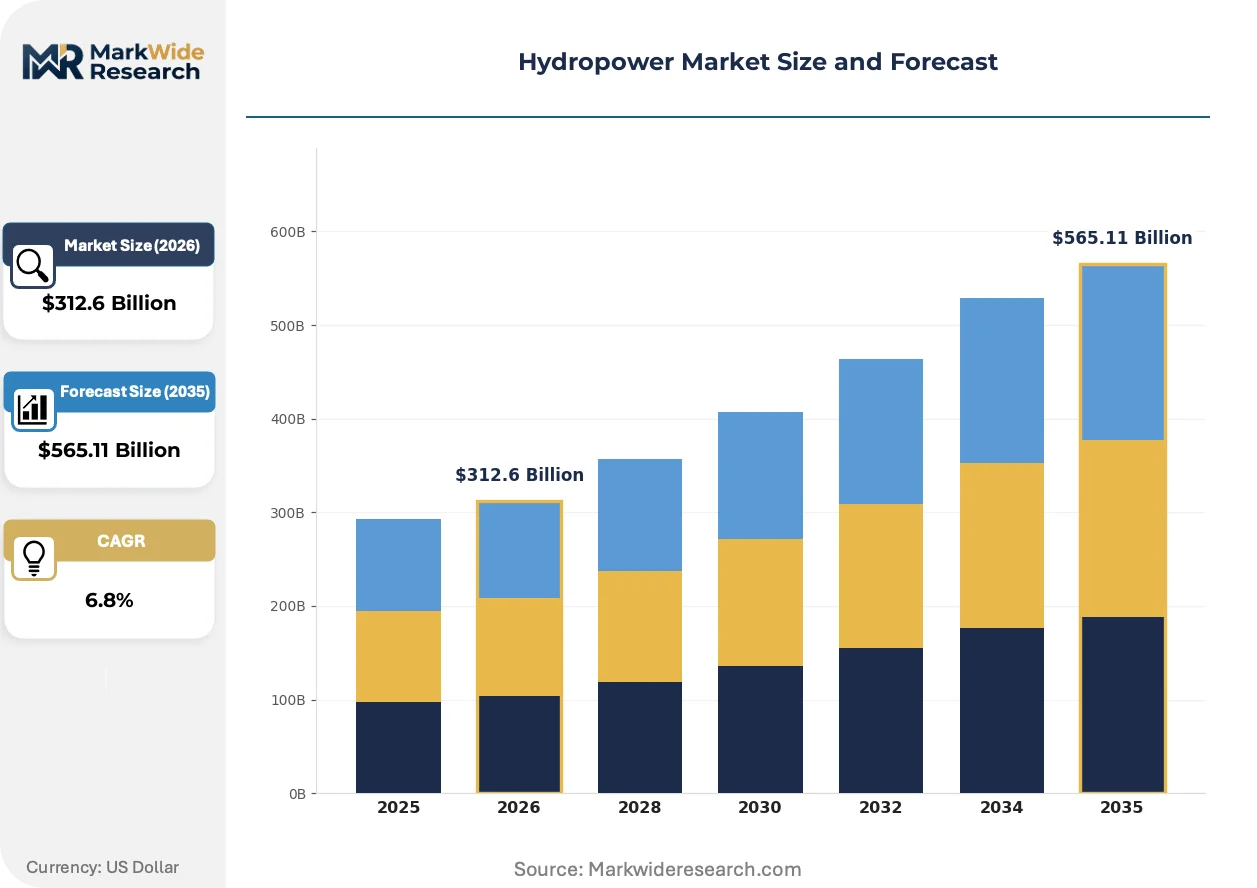
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
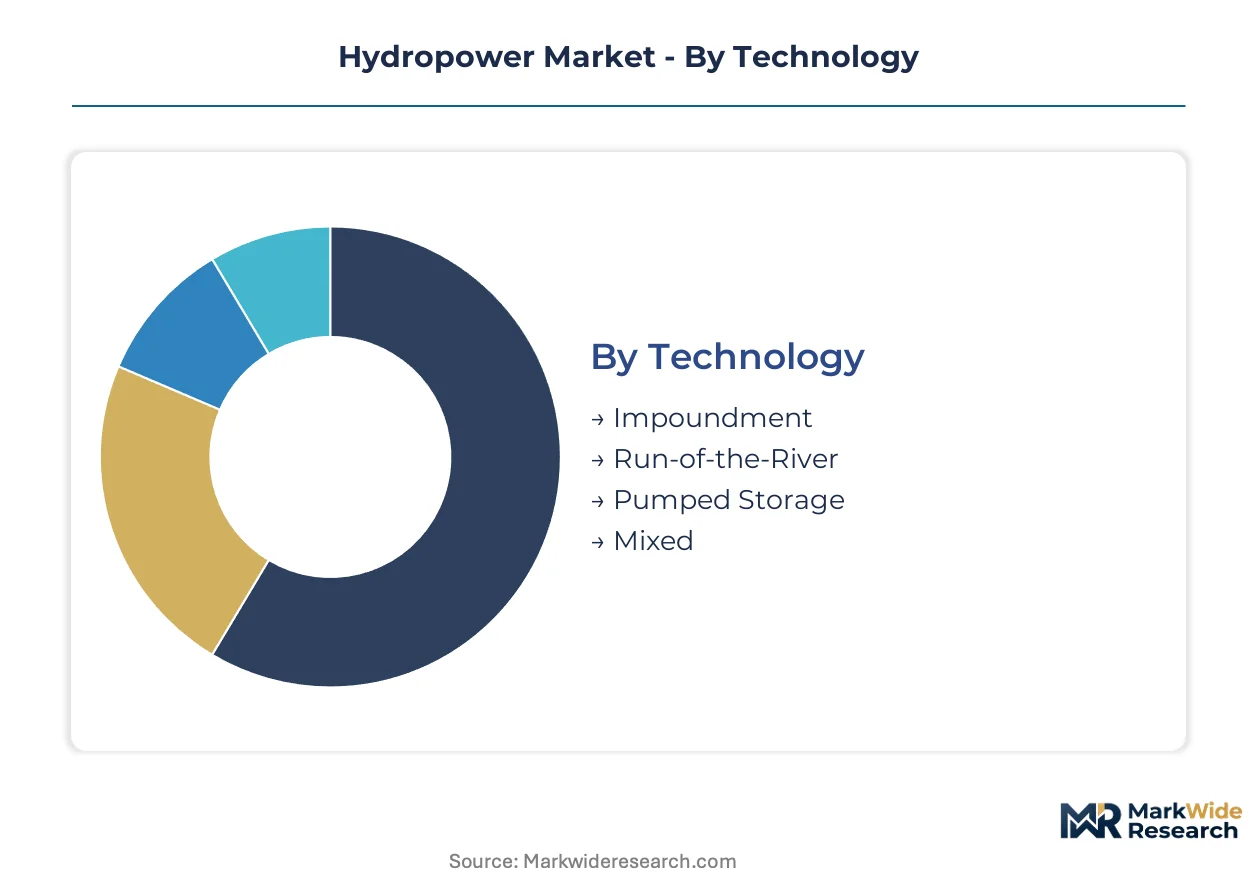
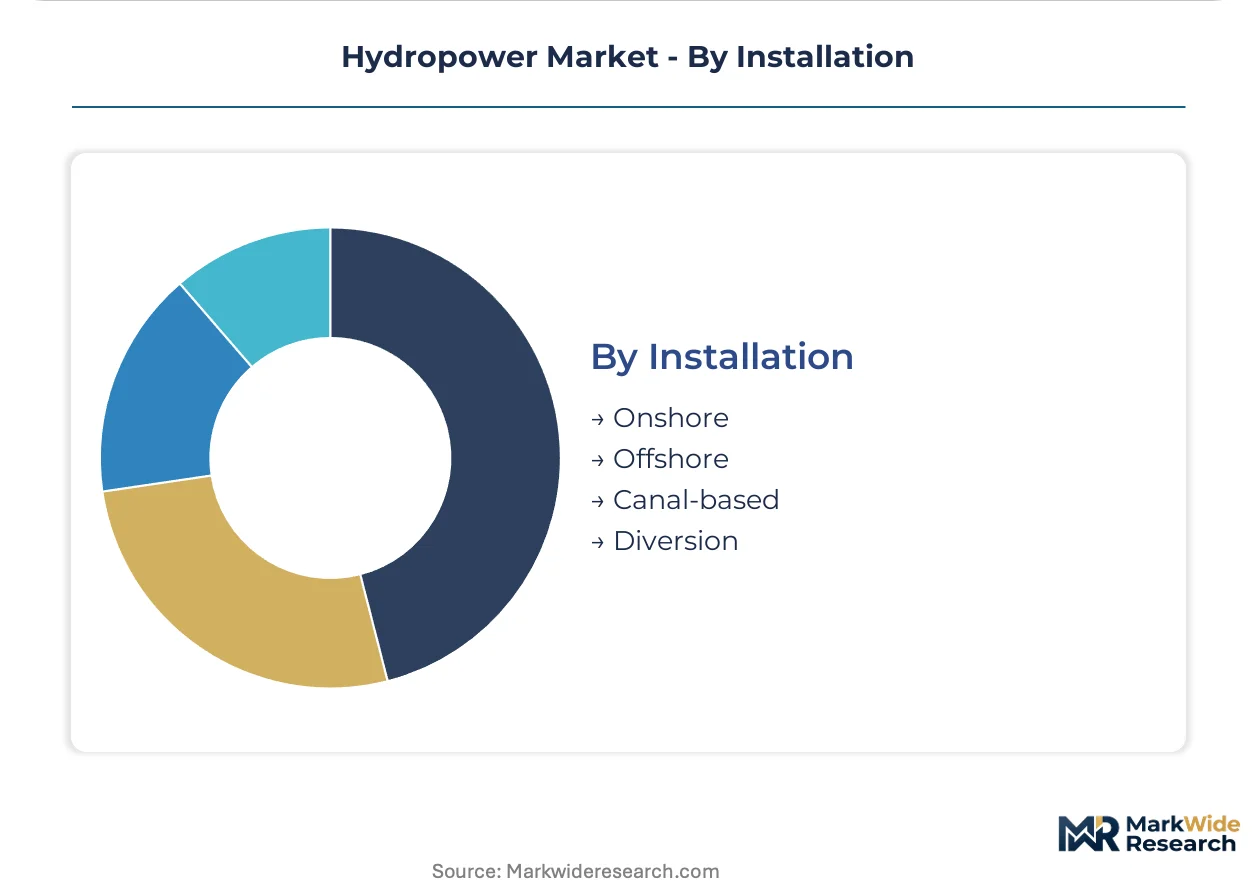
| Segmentation | Technology: Impoundment, Run-of-the-River, Pumped Storage, Mixed Application: Electricity Generation, Irrigation, Flood Control, Recreational End User: Utilities, Industrial, Commercial, Residential Installation: Onshore, Offshore, Canal-based, Diversion |
| Companies Covered | GE Vernova, Siemens Energy AG, Andritz AG, Voith GmbH & Co. KGaA, China Three Gorges Corporation, Statkraft, Toshiba Energy Systems, ABB, Duke Energy Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydropower Market Emerging Trajectories
Digital turbine control systems and environmental retrofit technologies are reshaping how hydropower assets deliver grid services. Equipment suppliers are repositioning around software-defined optimization and ecological compliance rather than pure hardware scale.
Variable-speed pumped storage technology is migrating from fixed-speed synchronous machines to doubly-fed induction machines with full-power converters. European utilities adopting this technology are capturing wider frequency regulation revenue streams. The technology is migrating from large alpine installations toward mid-scale coastal projects in Southeast Asia.
China's dual carbon goals and MEE river basin ecological redlines are prohibiting new reservoir construction in sensitive watersheds. Domestic developers are pivoting toward pumped storage and turbine retrofit markets rather than greenfield impoundment. Equipment procurement is concentrating with suppliers offering fish-passage integration and sediment management systems.
Power purchase agreement structures are unbundling capacity payments from energy arbitrage revenues. Utility offtakers in Brazil and Southeast Asia are negotiating shorter contract tenors with indexation to carbon pricing mechanisms. This restructuring is most visible in markets where F-Gas Regulation and EU Green Deal frameworks are creating compliance-linked pricing premiums.
Hydropower Market Segmentation
Hydropower assets differ fundamentally in capital intensity, permitting timelines, and revenue stability. Understanding segment-level turnover cycles reveals where equipment suppliers can capture recurring upgrade revenue versus one-time installation contracts.
Technology:
Impoundment projects stretch across multi-decade depreciation schedules while pumped storage retrofits turn over every 12-15 years as grid services evolve.
- Impoundment:Large-scale reservoir systems store water behind dams for controlled release through Francis or Kaplan turbines. Demand concentrates in Brazil's Amazon basin where run-of-river alternatives face lower social license barriers than mega-dam construction.
- Run-of-the-River:Diversion channels direct river flow through turbines without significant water storage, achieving faster permitting than impoundment. Alpine utilities in Switzerland and Austria are expanding procurement for decentralized grid balancing.
- Pumped Storage:Reversible turbine-pump systems arbitrage electricity prices by storing energy in upper reservoirs. Vietnam's EVN and the Philippines' NGCP are prioritizing this technology for solar and wind integration.
- Mixed:Hybrid configurations combine run-of-river generation with limited seasonal storage. China's State Grid deploys these systems under MEE ecological redlines that restrict new reservoir construction.
Impoundment dominates installed base. Pumped storage is where expansion concentrates.
Application:
Electricity generation commands the deepest capital pools while recreational and flood control applications depend on municipal budget cycles with slower procurement velocity.
- Electricity Generation:Baseload and peaking power supply through turbine-driven generators achieving conversion efficiencies exceeding 90 percent. EU Green Deal mandates are accelerating refurbishment contracts across Germany, Austria, and Italy.
- Irrigation:Multi-purpose reservoirs store water for agricultural distribution during dry seasons. India's CEA hydropower purchase obligations are linking irrigation infrastructure to renewable energy certificates.
- Flood Control:Seasonal storage capacity buffers downstream communities against river overflow. China's MEE river basin ecological redlines are mandating sediment management upgrades in aging flood control dams.
- Recreational:Reservoir surface area supports boating, fishing, and tourism revenue streams. Alpine operators in Switzerland monetize recreational leases to offset seasonal generation volatility.
Electricity generation commands margin concentration. Irrigation is climbing the fastest as water-energy nexus policies mature.
End User:
Utility procurement cycles align with regulated rate-base approvals while industrial offtakers negotiate shorter-term contracts indexed to carbon pricing.
- Utilities:Vertically integrated grid operators under long-term power purchase agreements. Brazil's Eletrobras and Vietnam's EVN are expanding pumped storage procurement to balance renewable intermittency.
- Industrial:Aluminum smelters, data centers, and chemical plants seeking firm renewable supply. European industrial clusters near alpine hydropower assets are negotiating direct wire agreements.
- Commercial:Corporate renewable energy buyers with 24/7 clean power commitments. India's commercial offtakers are leveraging CEA hydropower purchase obligations for compliance.
- Residential:Micro-hydro installations for off-grid or net-metered applications. Alpine and Southeast Asian terrain supports distributed run-of-river systems for remote communities.
Utilities dominate contract volume. Industrial is gaining share fastest as 24/7 renewable procurement standards spread.
Installation:
Onshore projects amortize over 50-100 year asset lives while canal-based and diversion systems deploy faster with modular equipment packages.
- Onshore:Conventional dam and reservoir construction on river systems with established hydrology. China's domestic developers are pivoting toward retrofit markets rather than greenfield onshore construction.
- Offshore:Tidal barrage and marine current turbine systems in coastal waters. Limited deployment to date due to high capital costs and environmental permitting complexity.
- Canal-based:Run-of-river installations integrated into existing irrigation or navigation infrastructure. India's PLI scheme for pumped storage components is supporting localized canal-based manufacturing.
- Diversion:Channel systems that redirect water flow around natural obstacles without large reservoirs. Brazil's Amazon basin developers favor diversion designs to minimize reservoir social and environmental costs.
Onshore dominates cumulative capacity. Canal-based is expanding most quickly as irrigation-modernization budgets align with renewable targets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turbine manufacturing capacity clusters in Germany, Austria, and China, while project deployment concentrates in Brazil, Vietnam, and Switzerland. Equipment suppliers route shipments through regional hubs to serve localized refurbishment cycles.
China
State Grid Corporation deploys mixed hydropower configurations under MEE river basin ecological redlines that prohibit new reservoir construction. The dual carbon goals redirect capital toward pumped storage retrofits rather than greenfield dams. Sichuan-Chongqing hosts the densest concentration of turbine refurbishment contracts.
Brazil
Eletrobras expands run-of-river procurement in the Amazon basin to avoid social license barriers facing mega-dam projects. ANEEL regulatory frameworks index power purchase agreements to carbon pricing mechanisms. The Belo Monte complex anchors baseload expansion in Pará state.
Germany
RWE and Uniper accelerate pumped storage modernization under EU Green Deal renewable storage mandates. The F-Gas Regulation restricts gas turbine alternatives, tightening the competitive set for grid stabilization assets. Bavarian alpine terrain supports modular run-of-river deployments for decentralized balancing.
Vietnam
EVN prioritizes pumped storage procurement to integrate gigawatt-scale solar additions in the Mekong Delta. The CEA-style purchase obligation structure creates long-term offtake certainty for foreign equipment suppliers. Northern highland provinces concentrate diversion-based run-of-river development.
Switzerland
Alpiq and Axpo monetize recreational reservoir leases to offset seasonal generation volatility while expanding pumped storage capacity. The Swiss Federal Office of Energy mandates fish-passage retrofits without grandfathering existing assets. The Alps region supports the highest density of small-to-medium modular installations in Europe.
Hydropower Market Vendor Landscape
Full-line turbine OEMs and specialized environmental retrofit providers split the market along project scale and permitting complexity. The vendor base concentrates among European and Chinese conglomerates with captive grid stabilization technology portfolios. Two archetypes dominate: integrated energy majors with multi-technology platforms, and modular equipment specialists competing on alpine and run-of-river flexibility. Competitive moves center on sediment management system partnerships and fish-passage engineering acquisitions.
Within the integrated OEM tier, GE Vernova and Siemens Energy AG exemplify scale-driven positioning across large impoundment and pumped storage markets. Andritz AG occupies a specialist position in small-to-medium run-of-river installations, competing on modular design flexibility. These three anchors reflect the market's structural division between mega-project execution and decentralized deployment.
| Leading Market Players |
|---|
| GE Vernova |
| Siemens Energy AG |
| Andritz AG |
| Voith GmbH & Co. KGaA |
| China Three Gorges Corporation |
| Statkraft |
| Toshiba Energy Systems |
| ABB |
| Duke Energy Corporation |
| Others |
Supply Flow & Price Mechanics
Tariff exposure on precision-forged turbine forgings determines both the premium-to-economy equipment spread and the geographic distribution of final assembly capacity. Equipment suppliers route shipments through regional fabrication hubs to minimize duty incidence while maintaining proximity to Brazil's Amazon basin and Vietnam's Mekong Delta project clusters.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across European refurbishment contracts, compressing margins on gas-turbine alternatives and elevating hydropower grid stabilization premiums. Three-tier pricing structure across premium, standard, and economy levels separates OEM turbine packages with full digital integration from modular run-of-river kits and basic retrofit components. Cost compression in the economy tier is intensifying because India's PLI localization scheme is incubating domestic component manufacturers. Utility offtakers under long-term power purchase agreements exhibit the lowest price sensitivity, while commercial renewable energy buyers negotiate aggressively on shorter contract tenors.
Supply Chain Analysis
Voith GmbH & Co. KGaA and Andritz AG hold concentrated contract-manufacturing capacity for Francis and Kaplan turbine runners in Germany and Austria. Manufacturing gravity centers on China for generator stators and excitation systems, with Brazil and Vietnam hosting rising final-assembly investment. The supply chain draws from specialty steel mills in Japan and South Korea for corrosion-resistant blade alloys. Single-source vulnerability concentrates in precision-cast wicket gate suppliers serving the pumped storage retrofit pipeline. Distribution runs through EPC contractor networks anchored by regional utility procurement offices in São Paulo, Hanoi, and Zurich.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent equipment suppliers face substitution pressure from battery energy storage systems capturing frequency regulation revenue streams once exclusive to pumped storage assets.
For Market Incumbents: Insulate turbine refurbishment revenue by acquiring fish-passage engineering specialists before regulatory baselines tighten without grandfathering. Deepen backward integration into precision forging capacity to offset tariff exposure on imported runner components. Lock in multi-decade service contracts with Brazil's Eletrobras and Vietnam's EVN to anchor recurring revenue against lithium-ion storage cost curves. For New Entrants and Emerging Players: Pursue modular run-of-river deployment in alpine terrain where Andritz AG's design flexibility commands premium positioning but capacity constraints create white space. Target India's canal-based installation segment where PLI localization incentives are incubating domestic manufacturing ecosystems. Lead with sediment management system integration as a differentiated entry wedge against established OEMs. For Investors and Strategic Acquirers: The market sits at a retrofit-dominant phase that favors specialized environmental compliance engineering firms over full-line turbine OEMs. Long-term viability hinges on regulatory ratcheting for ecological redlines across China's MEE jurisdictions and Switzerland's Federal Office of Energy mandates. Acquisition candidates with captive fish-passage design expertise and sediment flushing technology portfolios offer defensive positioning. Watch for lithium-ion storage cost parity announcements in Southeast Asian frequency regulation markets as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Pumped Storage Capacity Buildout | Vietnam's EVN and Philippines' NGCP anchor gigawatt-scale procurement for solar-wind balancing. |
| Backward Integration into Forging | German and Austrian OEMs secure runner component supply against Asia-Pacific tariff exposure. |
| Fish-Passage Engineering Acquisition | Swiss Federal Office of Energy mandates retrofit compliance without grandfathering existing assets. |
| Power Purchase Agreement Restructuring | Brazil's ANEEL frameworks index contracts to carbon pricing mechanisms, elevating hydropower premiums. |
| Green Certification Program | EU Green Deal storage mandates tighten competitive set for gas-turbine alternatives in Germany. |
Methodological Framework
Cross-validation between utility planning officer interviews and EIA/IEA secondary data anchors the qualitative findings. Primary fieldwork engaged hydropower project developers, EPC contractors, grid operators, and turbine procurement specialists across Brazil, Vietnam, Germany, and Switzerland. Secondary validation drew from FERC filings, IEA renewable deployment trackers, ANEEL regulatory bulletins, and customs trade records for turbine component flows. Bottom-up project pipeline aggregation and top-down national capacity targets were reconciled through iterative triangulation.
Calibration against historical capacity addition patterns and regulatory announcement timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include technology type, project scale tier, application, and regulatory framework cluster. CAGRs were derived from slope analysis of announced procurement pipelines and depreciation-driven replacement cycles. Forecast inputs incorporated sediment accumulation rates for aging reservoir economics and variable-speed pumped storage adoption curves in European frequency regulation markets.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments and steel commodity indices would shift the trajectory of capital-intensive impoundment projects. Forecasts reflect documented assumptions on regulatory enforcement timelines and carbon pricing mechanism adoption. Quarterly review of MEE ecological redline announcements, EU Green Deal implementation bulletins, and lithium-ion storage cost curves is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydropower Systems
Small Hydropower Market
Hydropower Systems
Tidal Power Market
Hydropower Systems
Wave and Tidal Energy Market
Hydropower Systems
Europe Hydropower Market
Hydropower Systems
North America Hydropower Market
Hydropower Systems
Standard Modular Hydropower Market
Hydropower Systems
Hydro Turbines Market
Hydropower Systems
Global Hydro Turbine Generator Unit Market
Hydropower Systems
North America Pumped Hydro Storage Market
Hydropower Systems
Africa Small Hydropower Market
Hydropower Systems
United States Hydro Turbine Market
Hydropower Systems
Asia-Pacific Small Hydropower Market
Hydropower Systems
Run of River Power Market
Hydropower Systems
Underground Hydro Power Plant Market
Hydropower Systems
Europe Small Hydropower Market
Hydropower Systems
Hydroelectricity Market