
 Nuclear Power Plant Equipment Market | 2026-2036
Nuclear Power Plant Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Nuclear Power Plant Equipment Market Intelligence
Buyer concentration among utility operators is broadening as state-owned nuclear fleets fragment procurement across engineering-procurement-construction consortia and specialized reactor vendors. GE Hitachi Nuclear Energy leverages its BWRX-300 small modular reactor platform to anchor North American utility relationships. Framatome sustains European market presence through specialized fuel assembly and reactor services. Doosan Enerbility dominates heavy component forging for AP1000 and APR1400 reactor supply chains across Northeast Asia.
Nuclear power plant equipment encompasses pressure-retaining components, reactor internals, steam supply systems, and auxiliary plant machinery engineered to ASME Section III standards for radiation tolerance and thermal cycling endurance, serving the controlled fission heat-to-electricity conversion process. Pressurized Water Reactor technology occupies the largest installed base and commands the deepest supplier qualification pools, while Molten Salt Reactor systems attract the fastest-growing engineering investment as developers pursue passive safety and high-temperature process heat applications. Turbine Generator sets concentrate margin pools due to precision manufacturing barriers and long replacement cycles.
The US Nuclear Regulatory Commission enforces 10 CFR Part 50 and Part 52 licensing frameworks that dictate equipment qualification protocols, while China's National Nuclear Safety Administration implements HAF regulations governing indigenous reactor component certification. The International Atomic Energy Agency's safety standards coordinate cross-border supplier audits and quality assurance expectations. Stakeholders must monitor regulatory divergence between established PWR/BWR codes and emerging SMR-specific standards to align certification investments with deployable reactor platforms.
Market Dynamics
Small modular reactor certification pathways from the US Nuclear Regulatory Commission and China's National Nuclear Safety Administration are compressing equipment qualification timelines while fragmenting procurement across specialized vendor consortia rather than integrated OEMs.
Growth Catalysts
- 10 CFR Part 52 licensing:The US Nuclear Regulatory Commission's framework accelerates SMR deployment by streamlining design certification, pulling demand for factory-fabricated pressure vessels and modular steam generators.
- India's indigenous reactor program:The Department of Atomic Energy's construction targets under the three-stage nuclear program concentrate procurement of heavy water reactors and associated fuel handling systems.
- Molten Salt Reactor development:Passive safety architectures and high-temperature process heat capabilities are attracting engineering investment from chemical and hydrogen production end-users seeking co-generation partnerships.
Market Restraints
- Forging capacity concentration:Ultra-heavy reactor pressure vessel forgings depend on a handful of facilities in Japan and South Korea, creating single-source vulnerability for AP1000 and APR1400 supply chains.
- ASME Section III certification timelines:Material qualification and weld procedure development for radiation-tolerant alloys extend lead times, freezing capital in work-in-progress inventory.
- Natural gas competition:Combined-cycle turbine plants offer lower overnight capital costs and faster construction schedules, diverting utility capital allocation in markets without carbon pricing.
Strategic Opportunities
- Poland's nuclear newcomer program:The country's first commercial reactor procurement under the Polish Nuclear Power Program creates greenfield demand for full-scope engineering-procurement-construction consortia without incumbent vendor lock-in.
- EU Taxonomy green classification:The complementary delegated act recognizing nuclear power as sustainable finance-eligible unlocks institutional capital for fleet lifetime extension and replacement projects.
- Additive manufacturing qualification:Directed energy deposition and powder bed fusion techniques for nickel alloy components are converging with digital twin-based quality assurance to enable distributed production of legacy spare parts.
Industry Challenges
- Welding inspector certification scarcity:ASME Section IX-qualified specialists for nuclear-grade pressure boundary work command premium wages and extended lead times, constraining fabrication throughput.
- Legacy analog system integration:Digital instrumentation and control retrofits for operating pressurized water reactors require complex hardware-in-the-loop validation against original safety case assumptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nuclear Power Plant Equipment Market |
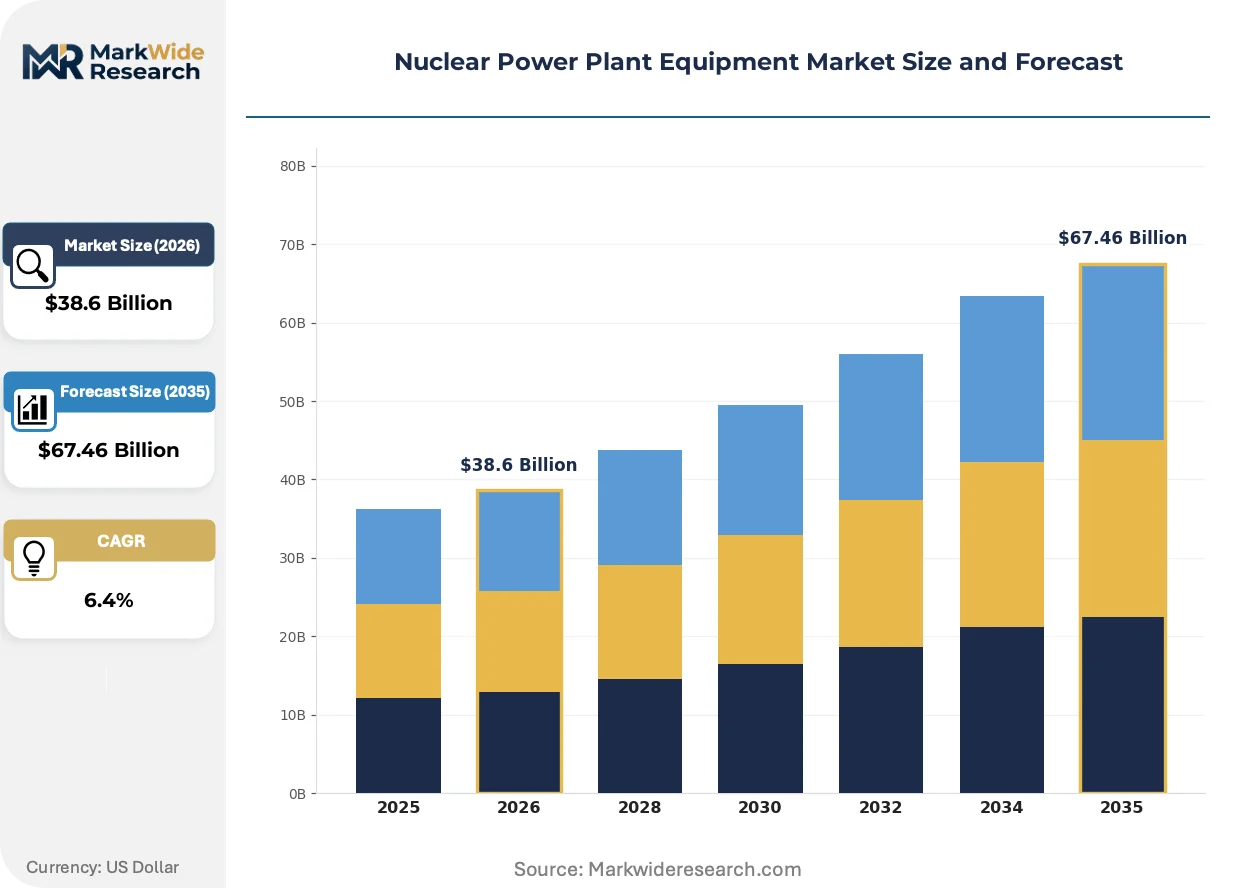
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $67.46 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reactor Pressure Vessel, Steam Generator, Control Rod Drive, Heat Exchanger, Cooling Tower, Turbine Generator Technology: Pressurized Water Reactor, Boiling Water Reactor, Heavy Water Reactor, Gas Cooled Reactor, Fast Breeder Reactor, Molten Salt Reactor Application: Electricity Generation, Desalination, Research Reactors, Medical Isotope Production, Industrial Heat Supply, Space Power End User: Utility Operators, Nuclear Engineering Firms, Government Agencies, Research Institutes, Equipment Suppliers, Reactor Manufacturers |
| Companies Covered | Toshiba Energy Systems & Solutions Corporation, Shanghai Electric, GE Hitachi Nuclear Energy, Framatome, BWX Technologies, Westinghouse Electric Company, Doosan Enerbility, Alstom, Mitsubishi Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nuclear Power Plant Equipment Market Strategic Shifts & Innovations
Equipment vendors are reconfiguring product architectures around factory fabrication and modular transport rather than field assembly, compressing construction schedules while raising precision manufacturing requirements.
Advanced manufacturing techniques for reactor pressure vessel nozzles and core support structures are converging with robotic non-destructive examination protocols. Westinghouse and Framatome are qualifying electron beam welding for thick-section ferritic steels. The structural consequence is collapsing the traditional forge-then-machine-then-inspect sequence into integrated production cells, reducing cycle time and dimensional variability.
The EU's F-Gas Regulation is phasing down sulfur hexafluoride use in switchgear and circuit breakers serving nuclear island electrical distribution. Equipment suppliers are accelerating development of vacuum interrupter and dry air insulation alternatives. European utilities with 1980s-vintage gas-insulated switchgear face accelerated replacement timelines, redirecting capital toward modernized medium-voltage architectures.
Utility engineering departments are unbundling long-term service agreements into discrete scope packages for steam generator tube inspection, reactor vessel head replacement, and turbine overhaul. Buyers are awarding these separately to capture competitive tension and specialized expertise. This pattern is most pronounced in the US merchant nuclear fleet, where Exelon and Constellation procurement teams segment work across multiple qualified vendors rather than defaulting to original equipment manufacturer packages.
Nuclear Power Plant Equipment Market Segmentation
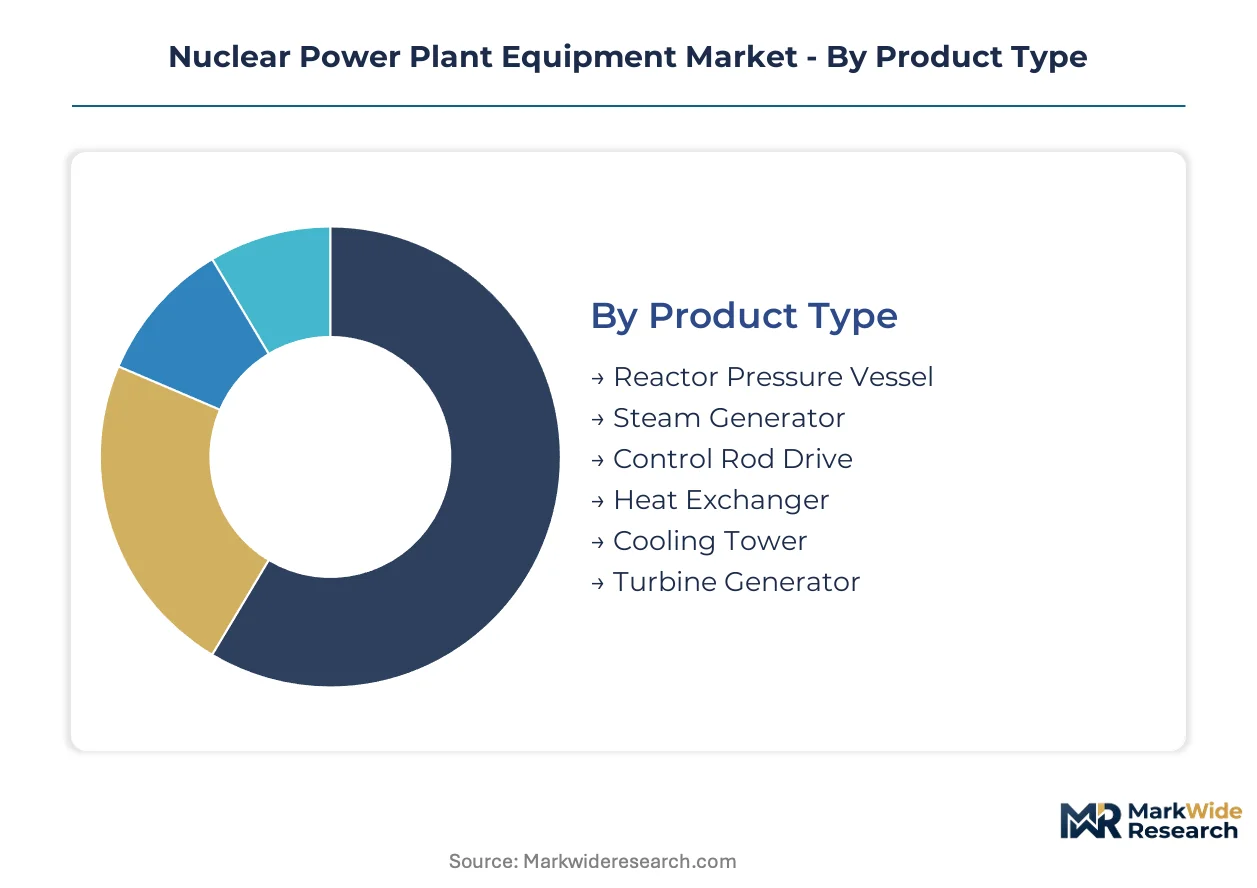
Equipment procurement patterns diverge sharply across reactor technologies and end-use applications. Standardization pressures from regulator certification pathways collide with site-specific engineering requirements for pressure boundaries and safety systems. Understanding these fault lines reveals where vendor consolidation and fragmentation concentrate.
Product Type:
Customization intensity spans from fully bespoke forged components to modular auxiliary systems, with precision tolerances and radiation tolerance dictating supplier qualification depth.
- Reactor Pressure Vessel:Ultra-heavy forged steel containment shells with stainless steel cladding resist neutron embrittlement across sixty-year design lives. India's Department of Atomic Energy and China's National Nuclear Safety Administration drive indigenous forging investments to reduce dependence on Japan Steel Works and Doosan Enerbility capacity.
- Turbine Generator:Precision-machined low-pressure rotors and moisture separator reheaters convert saturated steam to electricity with thermal efficiencies exceeding 33%. Long replacement cycles and proprietary blade geometries concentrate margin pools with GE Hitachi, Siemens Energy, and Alstom Power.
- Steam Generator:Alloy 800 tubing bundles transfer primary loop heat to secondary steam circuits. Tube plugging and replacement schedules dominate plant outage planning.
- Control Rod Drive:Electromechanical and hydraulic mechanisms modulate reactor reactivity. Magnetic jack designs prevail in pressurized water reactor fleets.
- Heat Exchanger:Plate-and-frame and shell-and-tube configurations handle decay heat removal and auxiliary cooling. Compact designs serve small modular reactor footprints.
- Cooling Tower:Natural draft hyperboloid structures and mechanical draft cells dissipate waste heat. Hybrid designs address water-scarce siting in India and the Middle East.
Most installed capacity flows through Reactor Pressure Vessel procurement. Expansion is steepest in Turbine Generator retrofits for lifetime extension programs.
Technology:
Maturity gradients separate decades-qualified light water designs from pre-commercial advanced reactors, with certification status determining equipment supplier pool depth.
- Pressurized Water Reactor:Mature steam supply architecture with three-loop and four-loop variants dominates operating fleets. Westinghouse, Framatome, and Rosatom supply standardized component families qualified to ASME Section III and RCC-M codes. Utility procurement teams leverage deep supplier competition for steam generator and reactor coolant pump replacements.
- Molten Salt Reactor:Liquid fuel systems operate at atmospheric pressure with passive safety and 700°C outlet temperatures for hydrogen and process heat co-generation. TerraPower, ThorCon, and China's TMSR program are qualifying nickel alloy vessels and freeze plug safety systems outside traditional pressure vessel forging constraints.
- Boiling Water Reactor:Direct-cycle steam generation eliminates steam generators, concentrating procurement on reactor internals and recirculation pumps. GE Hitachi's BWRX-300 small modular reactor adapts this architecture for factory fabrication.
- Heavy Water Reactor:Natural uranium fuel and pressurized heavy water moderator enable indigenous fuel cycles. India's PHWR construction program sustains dedicated supply chains.
- Gas Cooled Reactor:Helium coolant and graphite moderation support very high temperature process heat. China's HTR-PM and X-energy's Xe-100 are qualifying ceramic fuel and steam generator components.
- Fast Breeder Reactor:Sodium coolant and plutonium breeding close fuel cycles. Russia's BN-800 and India's PF-500 remain the sole commercial-scale installations.
Pressurized Water Reactor technology anchors current procurement volumes. Molten Salt Reactor engineering investment is climbing the fastest as developers pursue non-electric revenue streams.
Application:
Revenue stability varies across baseload electricity, intermittent industrial demand, and speculative frontier markets with divergent equipment specification requirements.
- Electricity Generation:Grid-connected baseload plants drive procurement of full-scope reactor islands and turbine halls. Capacity markets and carbon pricing in the European Union and United Kingdom sustain fleet investment against natural gas competition.
- Desalination:Multi-stage flash and reverse osmosis integration with nuclear heat requires customized steam extraction configurations. Saudi Arabia's King Abdullah City for Atomic and Renewable Energy and the UAE's Barakah plant are evaluating co-generation architectures.
- Research Reactors:Materials testing and neutron science facilities demand compact cores and specialized beam line equipment. Argentina's RA-10 and Australia's OPAL sustain niche supplier relationships.
- Medical Isotope Production:Molybdenum-99 and iodine-131 irradiation targets require high-flux thermal reactors. Canada's NRU decommissioning shifted supply to Belgium's BR-2 and the Netherlands' HFR.
- Industrial Heat Supply:District heating and process steam for refineries and chemical plants exploit high-temperature reactor outlet temperatures. China's Sinopec and Dow Chemical are assessing molten salt reactor partnerships.
- Space Power:Kilopower and fission surface power systems for lunar and Martian bases drive miniaturization of heat pipe reactors and thermoelectric converters. NASA and DARPA programs are qualifying components for launch vibration and vacuum environments.
Electricity Generation commands the deepest supplier qualification pools. Desalination co-generation is gaining share fastest in water-stressed Middle Eastern markets.
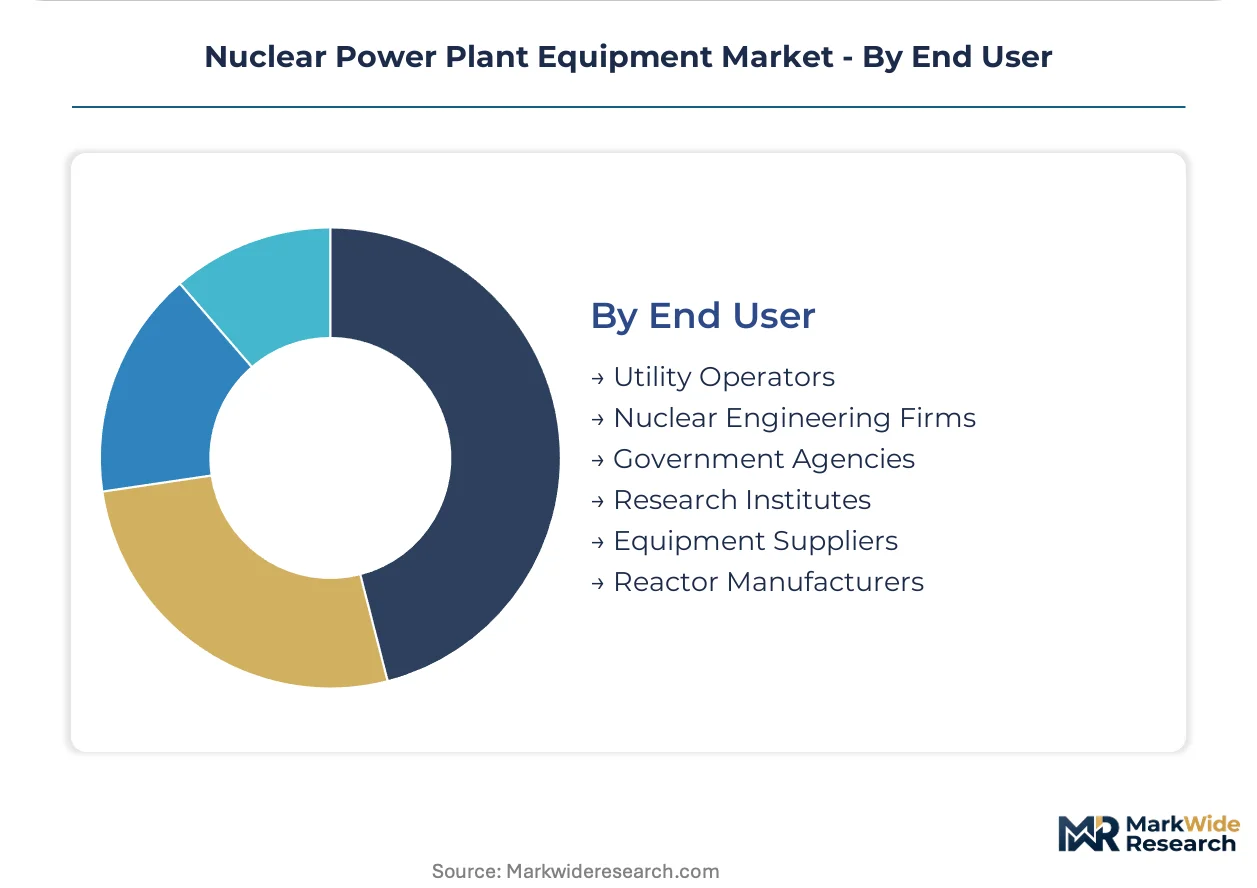
End User:
Procurement sophistication ranges from integrated utility engineering departments to fragmented government research establishments with divergent technical evaluation capacity.
- Utility Operators:Exelon, EDF, and KHNP maintain dedicated nuclear procurement organizations with ASME Section III audit capabilities. Long-term service agreement unbundling is accelerating competitive bidding for steam generator tube inspection and turbine overhaul scope.
- Nuclear Engineering Firms:Bechtel, Fluor, and SNC-Lavalin aggregate equipment procurement for engineering-procurement-construction contracts. Poland's nuclear newcomer program is soliciting full-scope consortium bids without incumbent vendor relationships.
- Government Agencies:National laboratories and defense programs drive specialized procurement for naval propulsion and weapons material production. The US Department of Energy's National Reactor Innovation Center qualifies components for demonstration reactors outside commercial regulatory frameworks.
- Research Institutes:University and national laboratory reactors require low-volume, high-mix procurement with extended technical support. IAEA technical cooperation programs coordinate supplier audits for developing country installations.
- Equipment Suppliers:Tier-2 and Tier-3 component vendors source forgings, castings, and instrumentation from qualified sub-suppliers. ASME N-stamp and ISO 19443 certification requirements constrain vendor base entry.
- Reactor Manufacturers:Westinghouse, Framatome, and Rosatom integrate vertically into core component production while outsourcing auxiliary systems. Small modular reactor developers are qualifying new supplier relationships for factory-fabricated module production.
Utility Operators concentrate procurement decision authority. Nuclear Engineering Firms are expanding fastest as newcomer markets seek full-scope project delivery capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's indigenous forging investments contrast with India's reliance on imported heavy components as both nations scale nuclear construction programs.
United States
Merchant utility procurement teams at Exelon and Constellation segment maintenance scope across multiple vendors to capture competitive tension. The US Nuclear Regulatory Commission's 10 CFR Part 52 framework accelerates small modular reactor deployment. Factory fabrication clusters in Pennsylvania and South Carolina are reconfiguring around modular pressure vessel production.
China
State-owned nuclear fleets fragment procurement across engineering-procurement-construction consortia for Hualong One and CAP1400 reactor builds. The National Nuclear Safety Administration implements HAF regulations governing indigenous component certification. Doosan Enerbility and domestic suppliers concentrate heavy forging capacity in Shandong and Liaoning provinces.
France
EDF maintains dedicated nuclear procurement organizations with RCC-M code audit capabilities for fleet lifetime extension. The EU Taxonomy complementary delegated act unlocks institutional capital for replacement projects. Framatome anchors specialized fuel assembly and reactor services supply from its Grenoble and Le Creusot industrial bases.
India
The Department of Atomic Energy pursues aggressive indigenous pressurized heavy water reactor construction targets under the three-stage nuclear program. BIS certification requirements constrain foreign equipment qualification timelines. Heavy water reactor component supply chains concentrate around Mumbai and Kalpakkam engineering clusters.
Poland
The Polish Nuclear Power Program creates greenfield demand for full-scope engineering-procurement-construction consortia without incumbent vendor lock-in. The country's national energy regulator evaluates vendor bids against EU safety standards. Warsaw-based procurement teams are qualifying new supplier relationships for first-of-a-kind commercial reactor deployment.
Nuclear Power Plant Equipment Market Key Industry Players
Japanese and South Korean producers anchor one tier; European and North American specialists hold differentiated positions in fuel services and digital instrumentation. The vendor base concentrates around heavy component forging, precision turbine manufacturing, and reactor system integration. Three archetypes dominate: integrated reactor vendors, specialized component fabricators, and engineering-procurement-construction aggregators. Capacity expansion and strategic partnerships represent the dominant competitive moves as SMR certification compresses equipment qualification timelines.
Among Asia-Pacific-based industrial conglomerates, Toshiba Energy Systems & Solutions Corporation and Mitsubishi Heavy Industries occupy positions spanning reactor internals and turbine generator supply. GE Hitachi Nuclear Energy anchors North American utility relationships through its BWRX-300 small modular reactor platform. These three exemplify the integrated reactor vendor archetype that is reconfiguring product architectures around factory fabrication rather than field assembly.
| Leading Market Players |
|---|
| Toshiba Energy Systems & Solutions Corporation |
| Shanghai Electric |
| GE Hitachi Nuclear Energy |
| Framatome |
| BWX Technologies |
| Westinghouse Electric Company |
| Doosan Enerbility |
| Alstom |
| Mitsubishi Heavy Industries |
| Others |
Cost & Logistics Intelligence
Factory fabrication and modular transport methods are collapsing traditional field-assembly economics while redistributing pricing power toward precision-manufacturing clusters. This shift simultaneously compresses construction timelines and concentrates supplier qualification burdens in regions with ASME N-stamp and RCC-M certification infrastructure.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for reactor pressure vessel forgings as indigenous heavy forging investments reduce dependence on Japanese and South Korean suppliers. Three-tier pricing structure across ASME Section III-certified, RCC-M-qualified, and non-nuclear industrial grades separates premium nuclear-grade components from standard pressure equipment. Cost compression in auxiliary systems intensifies because engineering-procurement-construction consortia unbundle procurement packages to capture competitive tension. Merchant utility operators in the United States exhibit highest price sensitivity for steam generator tube replacement scope, while state-owned fleets in China prioritize certification compliance over unit cost.
Supply Chain Analysis
Refurbishment and remanufacturing flows for steam generator tube bundles and reactor coolant pumps are extending component service lives and creating secondary supply channels outside original equipment manufacturer networks. Geographic supply concentration centers on Japan, South Korea, and China for ultra-heavy forgings, with India building indigenous capacity under BIS certification requirements. Raw material dependencies draw from specialized nickel alloys, zirconium tubing, and radiation-tolerant ferritic steels. Single-source vulnerability persists for Japan Steel Works and Doosan Enerbility forging capacity serving AP1000 and APR1400 programs. Distribution runs through engineering-procurement-construction aggregators for greenfield projects and direct utility procurement for maintenance and replacement scope.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where certification pathway acceleration by the US Nuclear Regulatory Commission and China's National Nuclear Safety Administration generates sustained equipment demand through standardized design approvals.
For Market Incumbents: Anchor factory fabrication capabilities in Pennsylvania and South Carolina clusters to capture 10 CFR Part 52 licensing pull-through for small modular reactor pressure vessels. Defend against specialized vendor consortium fragmentation by deepening ASME Section III audit capabilities and freezing out Tier-2 competitors through exclusive long-term service agreements with Exelon and Constellation procurement teams.
For New Entrants and Emerging Players: Engineering-procurement-construction consortia represent the most penetrable channel for Poland's nuclear newcomer program, where absence of incumbent vendor lock-in creates greenfield bidding opportunities. Target additive manufacturing qualification for nickel alloy legacy spare parts as distributed production methods converge with digital twin quality assurance. Pursue co-generation partnerships with chemical and hydrogen producers seeking molten salt reactor process heat integration.
For Investors and Strategic Acquirers: Roll-up economics work for specialized component fabricators because ASME N-stamp certification requirements create artificial scarcity and constrain vendor base entry. Five-to-ten-year viability hinges on positioning within SMR-specific supply chains rather than traditional large reactor replacement cycles. Monitor small modular reactor design certification milestones by the US Nuclear Regulatory Commission as inflection indicators for factory-fabrication capacity utilization.
| Strategic Initiative | Industry Significance |
|---|---|
| SMR Design Certification Investment | US Nuclear Regulatory Commission 10 CFR Part 52 approvals unlock factory-fabrication demand for modular pressure vessels. |
| Indigenous Forging Capacity Buildout | India's BIS-certified heavy component investments reduce import dependence for pressurized heavy water reactor construction. |
| Additive Manufacturing Qualification | Directed energy deposition for nickel alloy components enables distributed production of legacy spare parts outside traditional forge constraints. |
| Long-term Service Agreement Unbundling | Exelon and Constellation procurement segmentation creates competitive bidding opportunities for specialized inspection and overhaul vendors. |
| Co-generation Partnership Development | Sinopec and Dow Chemical assessments of molten salt reactor process heat open non-electric revenue streams for advanced reactor developers. |
Research Approach
Multiple input streams — primary interviews with utility procurement officers, nuclear engineering firm project directors, and reactor vendor supply chain managers; secondary validation through US Nuclear Regulatory Commission filings, International Atomic Energy Agency safety standards documentation, and national nuclear safety administration certification records; plus customs and trade data for heavy component imports — were reconciled through bottom-up and top-down triangulation.
Historical deployment patterns were cross-referenced against panel input from EPC contractors and equipment suppliers to construct analytical frameworks across reactor technology type, component specification tier, and regional regulatory cluster. CAGRs were derived from segmented demand modeling incorporating certification timeline acceleration, fleet modernization program announcements, and indigenous construction target commitments. Industry-specific forecast inputs included ASME Section III certification queue lengths and small modular reactor design review milestones.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory divergence between established PWR/BWR codes and emerging SMR-specific standards, plus forging capacity expansion timing in India and China. Practitioners should monitor National Nuclear Safety Administration HAF regulation updates and EU Taxonomy complementary delegated act implementation for early signals of capital allocation shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
Nuclear Power Market
Nuclear Energy
United States Nuclear Power Plant Equipment Market
Nuclear Energy
Global Nuclear Reactor Construction Market
Nuclear Energy
United States Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Thorium Market
Nuclear Energy
Japan Nuclear Power Reactor Decommissioning Market
Nuclear Energy
China Nuclear Power Plant Equipment Market
Nuclear Energy
Nuclear Decommissioning Services Market
Nuclear Energy
Nuclear Powered Merchant Vessel Market
Nuclear Energy
Fusion Power Market
Nuclear Energy
North America Nuclear Power Plant and Equipment Market
Nuclear Energy
North America Nuclear Reactor Construction Market
Nuclear Energy
Europe Nuclear Power Plant and Equipment Market
Nuclear Energy
Helium-3 Market
Nuclear Energy
Uranium Enrichment Market
Nuclear Energy
Europe Nuclear Reactor Construction Market