
 Turbine Drip Oil Market | 2026-2036
Turbine Drip Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Turbine Drip Oil Market Analysis
North American refinery capacity adjustments for Group II+ base oils is rebalancing supply availability for turbine lubricant blenders. Shell plc leverages its integrated base oil production network to sustain formulation consistency across power generation accounts. Castrol Ltd. differentiates through application engineering services tied to large-frame steam turbine operators. Chevron Corporation anchors its position via direct supply agreements with independent power producers in Texas and the Midwest.
Turbine drip oil denotes a low-viscosity lubricant formulated specifically for gravity-fed or wick-based delivery systems that maintain bearing surfaces in steam and gas turbine auxiliary equipment. Typical formulations incorporate refined mineral or synthetic base stocks with oxidation inhibitors and rust preventives, delivering ISO VG 32 to 68 viscosity grades for continuous film strength at temperatures reaching 95°C. Mineral oil formulations still occupy the largest volume share among utilities with mature steam fleets, while synthetic oil commands margin premiums in combined-cycle plants requiring extended drain intervals. Additive-enhanced oil is gaining traction among service providers seeking to consolidate inventory across mixed turbine vintages.
The EPA regulates used oil handling under 40 CFR Part 279, while ASTM D4304 governs turbine lubricant performance benchmarks for oxidation stability and rust prevention. OSHA's workplace exposure limits for mineral oil mist influence product selection in enclosed turbine halls, particularly for maintenance contractors. Power generation utilities and their lubricant suppliers must monitor evolving state-level carbon intensity rules that could accelerate displacement of conventional mineral chemistries.
Market Dynamics
EPA's evolving used oil management standards under 40 CFR Part 279 are forcing blenders to reformulate toward additive-enhanced and biodegradable chemistries, compressing margins for conventional mineral oil suppliers while opening premium positioning for synthetic alternatives.
Growth Catalysts
- Aging steam turbine fleets:Power generation utilities in the United States face mounting pressure to extend equipment life cycles without capital replacement, driving more frequent lubrication maintenance schedules.
- 40 CFR Part 279 standards:The EPA's tightening used oil handling requirements are accelerating displacement of conventional mineral chemistries toward compliant formulations.
- Combined-cycle plant expansion:Gas turbine auxiliary systems requiring extended drain intervals are pulling synthetic ISO VG 32-68 formulations into new installation projects.
Market Restraints
- Group II+ base oil supply concentration:North American refinery capacity adjustments create intermittent availability constraints for turbine lubricant blenders dependent on consistent base stock quality.
- Mineral oil mist exposure limits:OSHA workplace standards in enclosed turbine halls restrict product selection flexibility for maintenance contractors serving legacy steam facilities.
- Biodegradable formulation cost premiums:Additive packages required for EPA-compliant chemistries carry 15-25% raw material cost penalties versus conventional mineral oils.
Strategic Opportunities
- State-level carbon intensity rules:Emerging regulations in California and New York create regulatory tailwinds for low-carbon synthetic formulations displacing mineral oil in utility procurement.
- Independent power producer channel:Direct supply agreements with Texas and Midwest IPPs bypass traditional distributor markups and capture higher margin retention.
- Mixed-vintage fleet consolidation:Service providers seek unified additive-enhanced oils compatible across 1960s steam turbines and modern combined-cycle units, reducing inventory complexity.
Industry Challenges
- Tribology specialization gap:Qualified lubrication engineers capable of diagnosing gravity-fed wick system failures in aging steam auxiliary equipment are retiring faster than replacement training programs produce.
- ASTM D4304 certification timelines:Oxidation stability and rust prevention testing protocols require 12-18 months for formulation validation, delaying product launches behind competitor windows.
- Legacy system integration:Synthetic formulations with different additive chemistries risk incompatibility with residual mineral oil in 40-year-old bearing housings, requiring costly flush protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turbine Drip Oil Market |
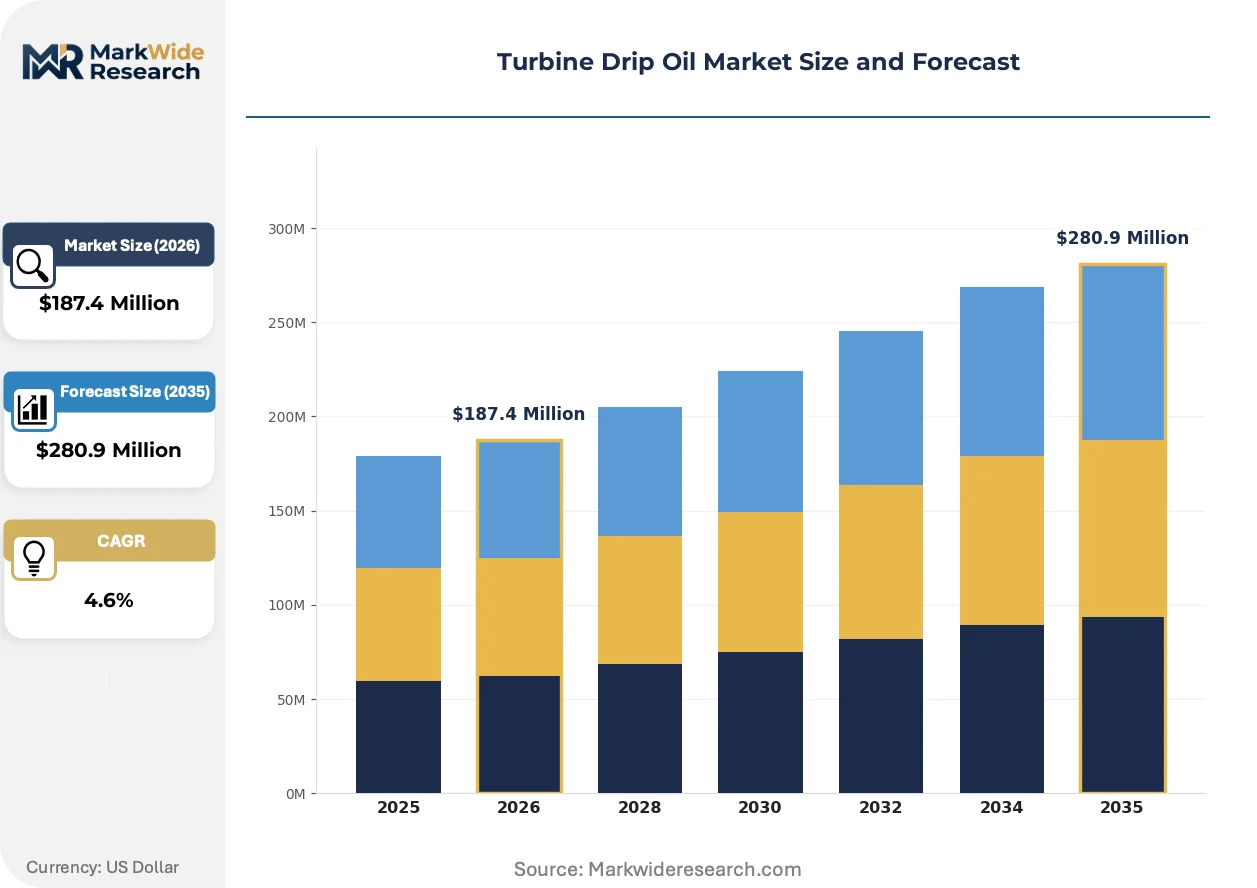
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Oil, Synthetic Oil, Biodegradable Oil, Additive-Enhanced Oil Application: Power Generation, Industrial Machinery, Marine Engines, Aerospace Systems Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers End User: Manufacturers, Utilities, Service Providers, Contractors |
| Companies Covered | Shell plc, Castrol Ltd., Chevron Corporation, Valvoline Inc., Apar Industries Ltd, Exxon Mobil Corporation, CITGO Petroleum Corp, FUCHS PETROLUB SE, BP Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turbine Drip Oil Market Emerging Trajectories
Formulation chemistry and delivery mechanisms for turbine auxiliary lubrication are undergoing material transformation as regulatory pressure intersects with equipment life-extension imperatives.
Synthetic base stock technology is consolidating market position among combined-cycle operators seeking drain interval extension. Gas turbine fleet managers in Texas and the Midwest are specifying polyalphaolefin and ester-based ISO VG 46 formulations for auxiliary bearing systems. This consolidation is compressing demand for conventional mineral oils in new-build installations while creating aftermarket conversion opportunities in existing plants.
EPA enforcement patterns under 40 CFR Part 279 are tightening used oil generator liability for utilities with on-site blending operations. Industrial consequences include mandatory third-party manifesting and reduced on-site storage allowances. Combined-cycle plants in carbon-regulated states are responding fastest, accelerating contracts with registered used oil marketers and reformulating toward biodegradable base stocks.
Buyer concentration among independent power producers is altering channel economics for formulated lubricants. Large Texas and Midwest IPPs are consolidating annual volume commitments into single-source agreements with direct blender relationships, displacing regional distributor networks. This pattern is most visible in the ERCOT and MISO footprints, where plant operators prioritize technical service bundled with supply security over traditional multi-vendor sourcing.
Turbine Drip Oil Market Segmentation
Turbine drip oil procurement patterns diverge sharply across formulation chemistry and delivery channels, with utility operators prioritizing specification compliance while industrial buyers optimize for inventory consolidation. Segment boundaries are blurring as additive-enhanced formulations bridge mineral and synthetic performance tiers.
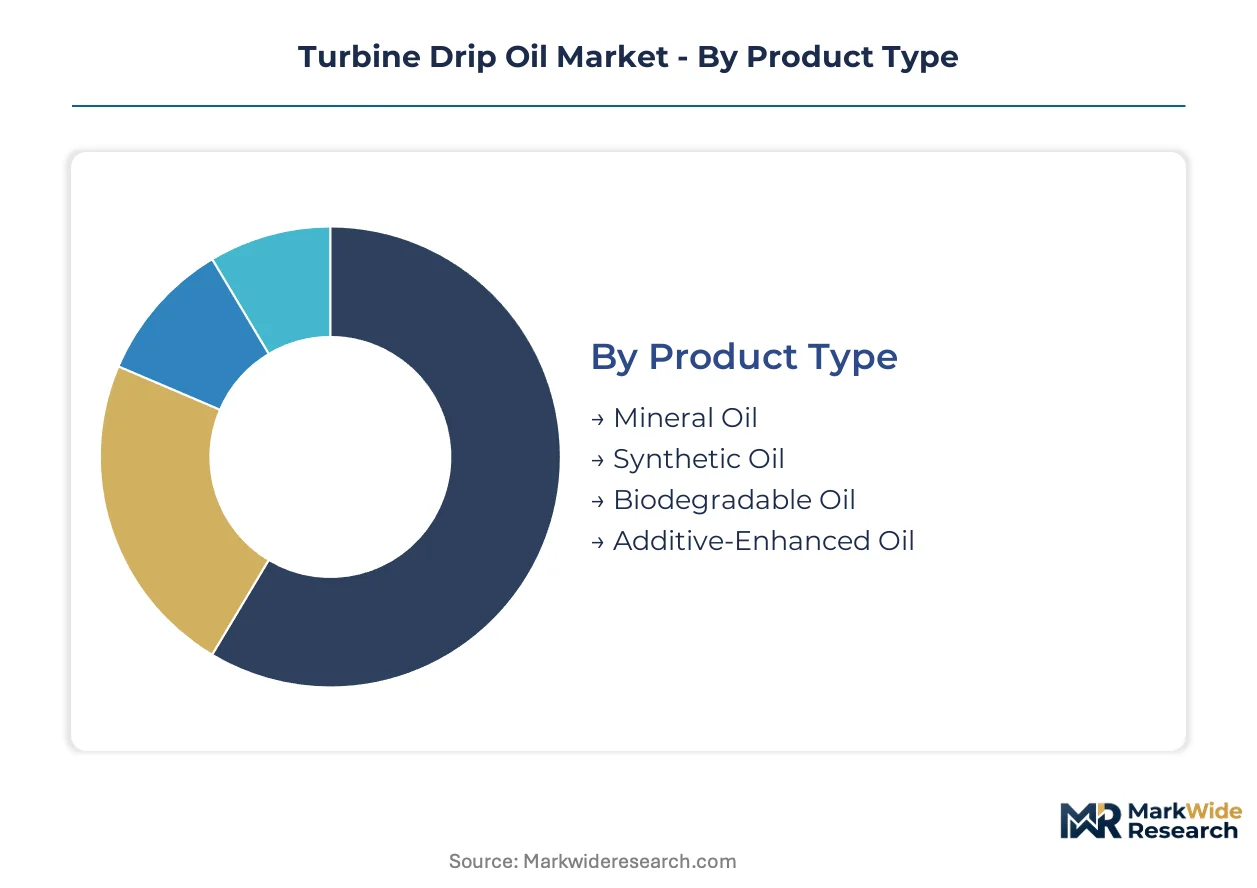
Product Type:
Base stock supply concentrates among Group II+ refiners in the US Gulf Coast, constraining blender formulation flexibility and compressing margins for commodity mineral oils while elevating synthetic positioning.
- Mineral Oil:Refined paraffinic base stocks dominate mature steam turbine fleets requiring ISO VG 32-68 viscosity grades for gravity-fed wick systems. US utilities with 1960s-1980s vintage equipment in the Midwest and Southeast specify mineral formulations for cost-controlled maintenance cycles, though EPA 40 CFR Part 279 compliance costs are eroding this advantage.
- Synthetic Oil:Polyalphaolefin and ester-based chemistries deliver oxidation stability for combined-cycle gas turbines operating at 95°C bearing temperatures. Texas and California IPPs specify synthetic ISO VG 46 for extended drain intervals, capturing lifecycle cost savings that offset 40-60% formulation premiums versus mineral alternatives.
- Biodegradable Oil:Vegetable-derived base stocks with synthetic ester additives serve California and New York utilities facing state-level carbon intensity regulations.
- Additive-Enhanced Oil:Rust inhibitors and oxidation stabilizers blended into Group II+ bases bridge mineral and synthetic performance for mixed-vintage fleets.
Today's leader: Mineral Oil. Tomorrow's challenger: Synthetic Oil.
Application:
Equipment duty cycles and regulatory exposure create four distinct demand profiles with diverging specification requirements and procurement authority structures.
- Power Generation:Steam and gas turbine auxiliary bearing systems in utility and independent power producer facilities represent the dominant volume concentration. ERCOT and MISO grid operators specify drip oils for governor bearings, turning gear systems, and auxiliary pumps, with procurement centralized through direct blender agreements bypassing distributor markups.
- Industrial Machinery:Pulp and paper mills, petrochemical complexes, and steel rolling operations deploy drip-fed lubrication for large-frame motor bearings and gearbox auxiliaries. Ohio and Pennsylvania manufacturing clusters specify ISO VG 68 mineral formulations for continuous-duty equipment where synthetic upgrade economics fail to justify capital conversion costs.
- Marine Engines:Coastal and inland waterway vessels utilize drip oil for auxiliary generator bearings and steering gear systems.
- Aerospace Systems:Ground support equipment and test stand turbines require specialized low-flash-point formulations.
Power Generation commands current volume. Industrial Machinery offers the steepest expansion trajectory as manufacturing reshoring accelerates.
Distribution Channel:
Channel economics are restructuring as buyer scale concentrates procurement authority and technical service bundling displaces transactional supply relationships.
- Direct Sales:Blender-to-utility agreements capture annual volume commitments from Texas and Midwest IPPs seeking supply security and application engineering support. Shell and Castrol field technical service teams co-located with major accounts, displacing regional distributor networks in the ERCOT footprint.
- Distributors:Regional lubricant distributors serve maintenance contractors and smaller industrial accounts requiring just-in-time delivery and credit terms.
- Online Retail:E-procurement platforms capture spot purchases from small contractors and remote facility managers.
- Wholesalers:Bulk break-bulk operations supply jobbers serving marine and aerospace segments with fragmented demand.
Direct Sales is consolidating share fastest. Distributors retain relevance in contractor-served legacy steam facilities.
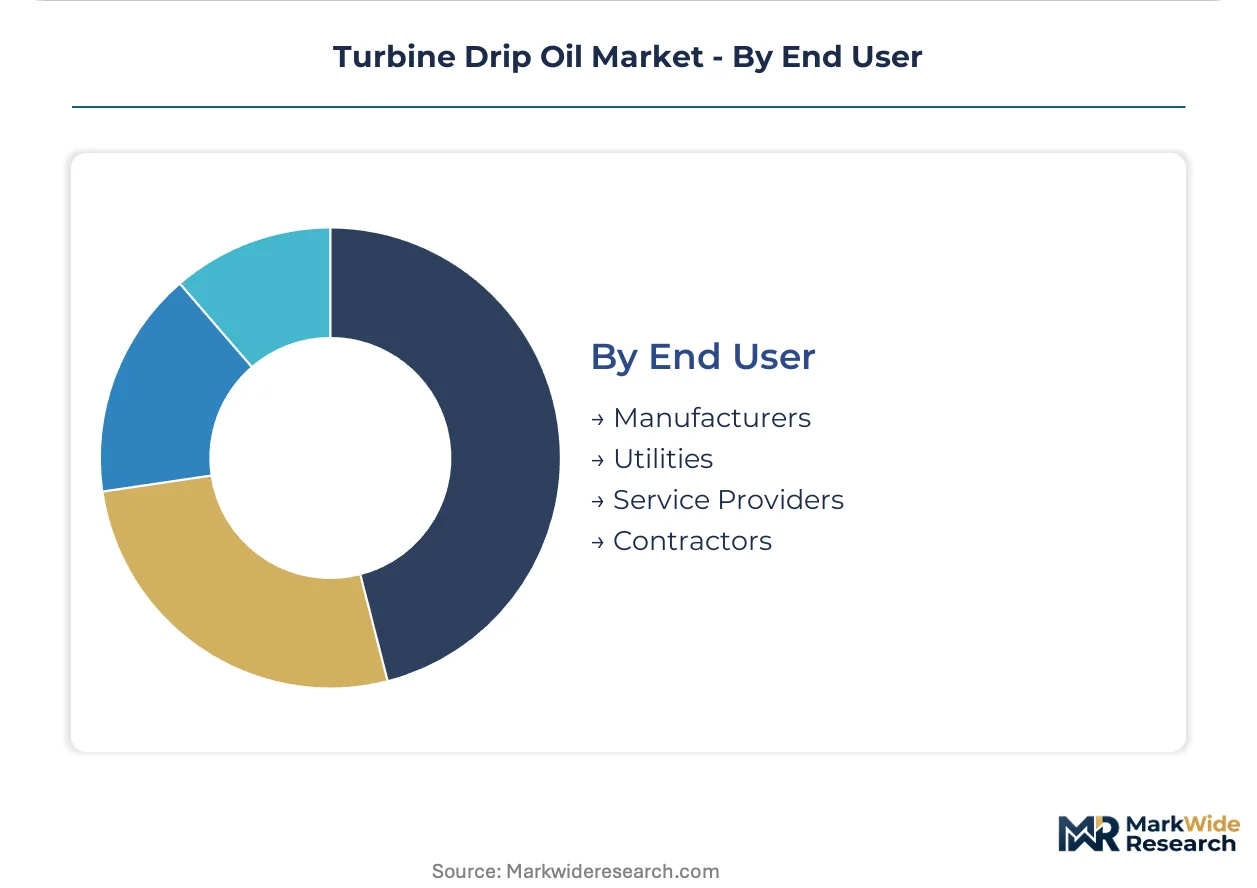
End User:
Procurement sophistication and technical specification authority separate four user categories with diverging price sensitivity and formulation requirements.
- Utilities:Investor-owned and municipal power generation operators specify turbine drip oils through centralized engineering procurement with ASTM D4304 compliance mandates. Duke Energy and Southern California Edison maintain qualified products lists restricting vendor participation to certified blenders with documented oxidation stability testing.
- Service Providers:Turbine maintenance contractors serving mixed-vintage fleets seek unified additive-enhanced oils reducing inventory SKUs across 1960s steam and modern combined-cycle units. Fluor and WorleyParsons specify compatible formulations enabling single-truck mobilization to diverse plant sites.
- Manufacturers:OEM turbine builders specify break-in and warranty lubricants for new equipment shipments.
- Contractors:Independent maintenance firms purchase through distributor channels for spot repair work.
Utilities dominate specification authority. Service Providers are gaining procurement influence through fleet-wide maintenance contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as blenders migrate formulation capacity toward jurisdictions with lower cost-of-compliance for EPA 40 CFR Part 279 standards. This migration pattern concentrates supply investment in states with streamlined environmental permitting while demand remains anchored in legacy industrial clusters.
United States
Power generation utilities in Texas and the Midwest drive procurement volume for ISO VG 32-68 formulations serving aging steam turbine fleets. EPA enforcement under 40 CFR Part 279 tightens used oil handling liability for on-site blending operations at combined-cycle plants. The ERCOT grid footprint around Houston anchors direct supply agreements with lubricant blenders bypassing traditional distributor networks.
Germany
Industrial machinery operators in the Ruhr Valley specify drip-fed lubrication for large-frame motor bearings in steel and chemical processing equipment. REACH compliance requirements under ECHA guidance push formulation chemistries toward biodegradable base stocks with documented oxidation stability testing. Bavaria's manufacturing corridor around Munich concentrates demand from precision equipment builders seeking extended drain interval specifications.
China
State-owned power generators in the Yangtze River Delta expand procurement of synthetic formulations for gas turbine auxiliary systems in combined-cycle installations. MIIT industrial standards for turbine lubricant performance create certification barriers for imported formulations. The Pearl River Delta manufacturing cluster around Shenzhen drives spot demand from electronics fabrication facilities with precision bearing maintenance requirements.
India
NTPC and state electricity boards in Maharashtra and Gujarat specify mineral-based drip oils for 1970s-vintage steam turbine fleets requiring frequent lubrication cycles. BIS certification mandates for industrial lubricants delay product registration timelines for foreign blenders seeking utility procurement approval. The Tamil Nadu industrial corridor around Chennai concentrates demand from textile and petrochemical operations with continuous-duty auxiliary equipment.
Japan
Electric utilities in the Kanto region around Tokyo maintain qualified products lists restricting turbine lubricant procurement to JIS-certified formulations with documented rust prevention performance. METI energy efficiency guidelines incentivize synthetic conversion for combined-cycle plants seeking operational cost reduction. The Chubu industrial zone near Nagoya anchors demand from automotive and machinery builders with precision turbine testing equipment.
Turbine Drip Oil Market Vendor Landscape
United States producers anchor the premium synthetic tier; European specialists hold formulation chemistry advantages in biodegradable segments. Market structure consolidates around integrated base oil producers with captive supply networks, while independent blenders compete on service bundling for mixed-vintage fleet operators. Three archetypes dominate: vertically integrated majors with refinery-to-blender control, application engineering specialists with co-located technical service, and regional distributors with credit-term flexibility for contractor accounts. Capacity expansion and direct supply agreement capture represent the dominant competitive moves, displacing traditional distributor relationships in utility procurement.
Within the integrated-major archetype, Shell plc and Chevron Corporation occupy positions defined by upstream base oil production control and direct utility account relationships. Castrol Ltd. exemplifies the application-engineering specialist model with technical service teams positioned alongside power generation accounts. These three companies represent the competitive core around which procurement consolidation in Texas and Midwest IPPs is organizing, with their positioning reflecting the shift from multi-vendor sourcing toward single-source annual volume commitments.
| Leading Market Players |
|---|
| Shell plc |
| Castrol Ltd. |
| Chevron Corporation |
| Valvoline Inc. |
| Apar Industries Ltd |
| Exxon Mobil Corporation |
| CITGO Petroleum Corp |
| FUCHS PETROLUB SE |
| BP Plc |
| Others |
Supply Flow & Price Mechanics
Qualified lubrication engineers concentrated in the US Gulf Coast and Midwest command premium compensation that widens spreads between economy mineral formulations and synthetic tiers. This labor-cost differential compresses margins for commodity blenders while rewarding integrated majors with captive technical service capabilities.
Pricing Analysis
Distributor markups of 15-22 percent on conventional mineral oils are collapsing under direct blender-to-utility agreements in Texas and the Midwest. Three-tier pricing structure across premium synthetic, mid-grade additive-enhanced, and economy mineral levels separates procurement by drain-interval requirements and regulatory exposure. Cost compression in the mineral tier intensifies because EPA 40 CFR Part 279 compliance burdens erode cost advantages. Independent power producers exhibit lowest price sensitivity due to lifecycle-cost optimization, while maintenance contractors serving legacy steam facilities remain most price-constrained.
Supply Chain Analysis
Freight costs for Group II+ base oils from US Gulf Coast refiners to Midwest blenders add 8-12 percent to landed formulation costs, disadvantaging non-integrated suppliers. Supply concentrates in the United States, South Korea, and Germany for high-performance base stocks. Formulation chemistry draws from polyalphaolefin feedstocks, ester additives, and vegetable-derived base oils. Single-source vulnerability persists for specialized oxidation inhibitors produced by a limited supplier set. Distribution runs through direct sales agreements with large utilities, supplemented by regional distributors for contractor accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The turbine drip oil market compounds steadily as aging steam turbine fleets require sustained maintenance investment without capital replacement cycles. Equipment life-extension imperatives create predictable demand visibility for formulation suppliers.
For Market Incumbents: Deploy technical service co-location as the primary lever. Shell and Castrol field engineers embedded at ERCOT and MISO power plants preempt specification changes before they reach procurement channels. Backward integration into Group II+ base oil production secures formulation consistency against refinery capacity volatility. Incumbents should deepen direct supply agreements to capture independent power producer volume consolidation.
For New Entrants and Emerging Players: Begin with biodegradable formulation certification for California and New York utilities facing state-level carbon intensity regulations. These jurisdictions present the most penetrable regulatory-driven demand segment. A go-to-market angle bundling used oil management compliance services with lubricant supply addresses EPA 40 CFR Part 279 liability concerns.
For Investors and Strategic Acquirers: Integrated base oil producers are the most active acquirer in this space, seeking formulation blending capabilities to complete downstream capture. The five-to-ten-year viability window favors suppliers with ASTM D4304 certification infrastructure and utility-qualified products list placement. Acquisition target archetype: regional blenders with established direct sales relationships in Texas or Midwest IPP clusters. The signal to watch is state-level carbon intensity rule adoption accelerating synthetic displacement timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Production | Captive Group II+ supply secures formulation consistency for utility accounts against refinery volatility. |
| Direct Supply Agreement Capture | Bypassing distributor networks improves margin retention with Texas and Midwest independent power producers. |
| Biodegradable Formulation Development | California and New York carbon regulations create compliant product differentiation for premium positioning. |
| Technical Service Co-location | Shell and Castrol field engineers embedded at power plants preempt competitive specification changes. |
| ASTM D4304 Certification Investment | Oxidation stability testing documentation qualifies products for Duke Energy and Southern California Edison procurement lists. |
Methodological Framework
Multiple input streams — executive interviews with lubricant procurement officers at major utilities, technical discussions with formulation chemists at integrated oil companies, and operational assessments from turbine maintenance contractors — were reconciled against secondary validation. Primary engagement covered plant engineering directors at ERCOT and MISO grid operators, aftermarket service heads at Fluor and WorleyParsons, and procurement leads at independent power producers. Secondary sources included EPA 40 CFR Part 279 enforcement records, ASTM D4304 certification databases, EIA power generation statistics, and SEC filings from listed lubricant manufacturers. Bottom-up volume estimates from individual plant specifications and top-down market sizing from base oil production data were cross-referenced for triangulation.
Data-stream reconciliation across the projection horizon applied segmentation modeling by formulation chemistry, application equipment type, and distribution channel structure. The analytical framework incorporated power generation capacity forecasts, combined-cycle installation pipelines, and regulatory adoption curves for state-level carbon intensity rules. CAGRs were derived from equipment life-extension investment patterns and synthetic conversion timelines. Industry-specific forecast inputs included steam turbine fleet age profiles and EPA enforcement intensity projections for used oil management compliance.
Caveats apply where refinery capacity adjustments, accelerated biodegradable mandate adoption, or breakthrough synthetic formulation economics could materially shift the outlook. Forecasts reflect assumptions about maintenance cycle frequency and regulatory enforcement continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Coal Intelligent Dry Separators Market
Fuels
Global Liquid Gas Cylinder (LGC) Market
Fuels
Gasoline Octane Improvers Market
Fuels
China Coal Market
Fuels
Mobile Fuel Storage Tank Market
Fuels
Hydrogen Cylinder Market
Fuels
Electric Fuel Heater Market
Fuels
Europe Firewood Market
Fuels
India Retail Fuel Market
Fuels
Carbonizers Market
Fuels
Global Methane Hydrate Market
Fuels
LNG Filling Station Market
Fuels
North America Bunker Fuel Market
Fuels
Coal Trading Market
Fuels
LPG Cylinder Manufacturing Market
Fuels
India Coal Market