
 France Tidal Power Market | 2026-2036
France Tidal Power Market Size, Share, and Industry Trends Forecast 2026-2036
France Tidal Power Market Foresight
Modular turbine packaging is repositioning buyer choice in the France Tidal Power Market, as developers shift from monolithic barrage contracts toward smaller, redeployable units that reduce capital commitment. Sabella SAS anchors this transition with its D10 tidal turbine designed for Brittany waters. Hydroquest SAS leverages its vertical-axis architecture to compete in estuarine environments where directional flow varies. Électricité de France sustains long-term market presence through its grid integration expertise and utility-scale project pipeline.
France Tidal Power encompasses electricity generation systems that harness kinetic energy from tidal currents or differential water heights, typically employing axial or cross-flow turbines rated between 100 kW and 2 MW, anchored to seabed frames or suspended from floating platforms, with capacity factors of 35-50% exceeding those of wind or solar. The technology serves baseload renewable supply for coastal grids and industrial offtakers requiring predictable output. Tidal Stream Generators dominate current deployment due to lower environmental impact and faster permitting compared to Barrage Systems. Lagoon Systems represent an emerging margin pool as pilot projects in Normandy test semi-enclosed basin configurations. Dynamic Tidal Power remains pre-commercial but attracts R&D funding for its theoretical capacity to extract energy without coastal geography constraints.
France's Commission de Régulation de l'Énergie oversees grid connection tariffs and renewable energy certificates that determine project finance viability, while the country's environmental authority enforces marine habitat assessments under EU Marine Strategy Framework Directive obligations. Bureau Veritas and DNV classification standards for tidal turbine structural integrity shape equipment procurement specifications and insurer requirements. Stakeholders must monitor how France's next offshore renewable energy auction design allocates seabed leases between tidal and floating wind technologies.
Market Dynamics
Modular turbine architectures are compressing capital deployment cycles in the France Tidal Power Market, enabling developers to phase investments across multiple smaller installations rather than committing to single large-scale barrage projects upfront.
Growth Catalysts
- CRE tariff framework:France's Commission de Régulation de l'Énergie maintains guaranteed purchase prices for marine renewable electricity, de-risking revenue streams for tidal stream projects in Brittany and Normandy.
- EU Marine Strategy Framework Directive:Marine habitat assessment protocols under this directive provide predictable environmental compliance pathways, accelerating permitting timelines for nearshore installations.
- Brittany tidal velocity corridor:The Roscoff-Fromveur strait concentrates France's highest commercially viable current speeds, anchoring developer site selection and grid infrastructure planning.
Market Restraints
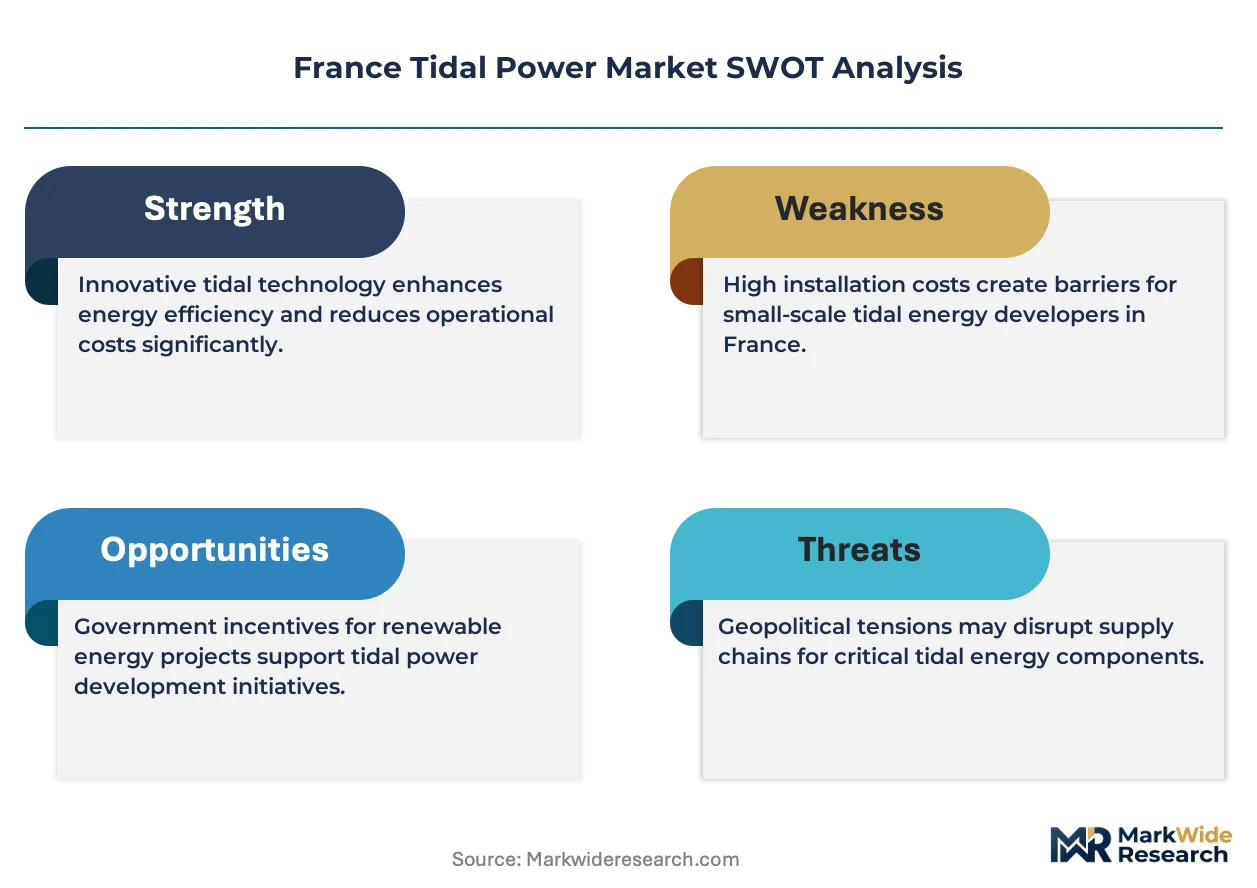
- Steel and rare earth magnet costs:Permanent magnet synchronous generators depend on neodymium supply chains concentrated in China, exposing turbine manufacturers to input price volatility and export restriction risks.
- Seabed lease competition:France's offshore renewable energy auctions allocate finite maritime zones between tidal stream and floating wind technologies, constraining site availability for tidal developers.
- Intermittency compensation requirements:Tidal generation's predictable but non-dispatchable output necessitates backup capacity or storage co-location, raising levelized cost thresholds against gas peakers.
Strategic Opportunities
- Lagoon system pilots:Semi-enclosed basin configurations in Normandy offer reduced environmental impact compared to barrage systems, opening new development zones with lower marine habitat disruption.
- Dynamic tidal power R&D:Pre-commercial coastal engineering concepts without strict geography constraints attract public research funding, potentially expanding addressable site inventory beyond current strait-dependent models.
- Industrial offtaker direct contracts:Coastal manufacturing facilities with baseload power requirements represent underserved demand segments bypassing utility intermediaries.
Industry Challenges
- Marine operations specialist scarcity:Subsea cable installation and turbine maintenance require certified diving technicians and remotely operated vehicle operators, with training pipelines lagging deployment schedules.
- Bureau Veritas certification timelines:Structural integrity classification for novel turbine designs involves extended prototype testing protocols, delaying commercialization of next-generation vertical-axis architectures.
- Grid synchronization complexity:Variable frequency tidal generators require power electronics and converter stations matching RTE transmission standards, adding integration engineering overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Tidal Power Market |
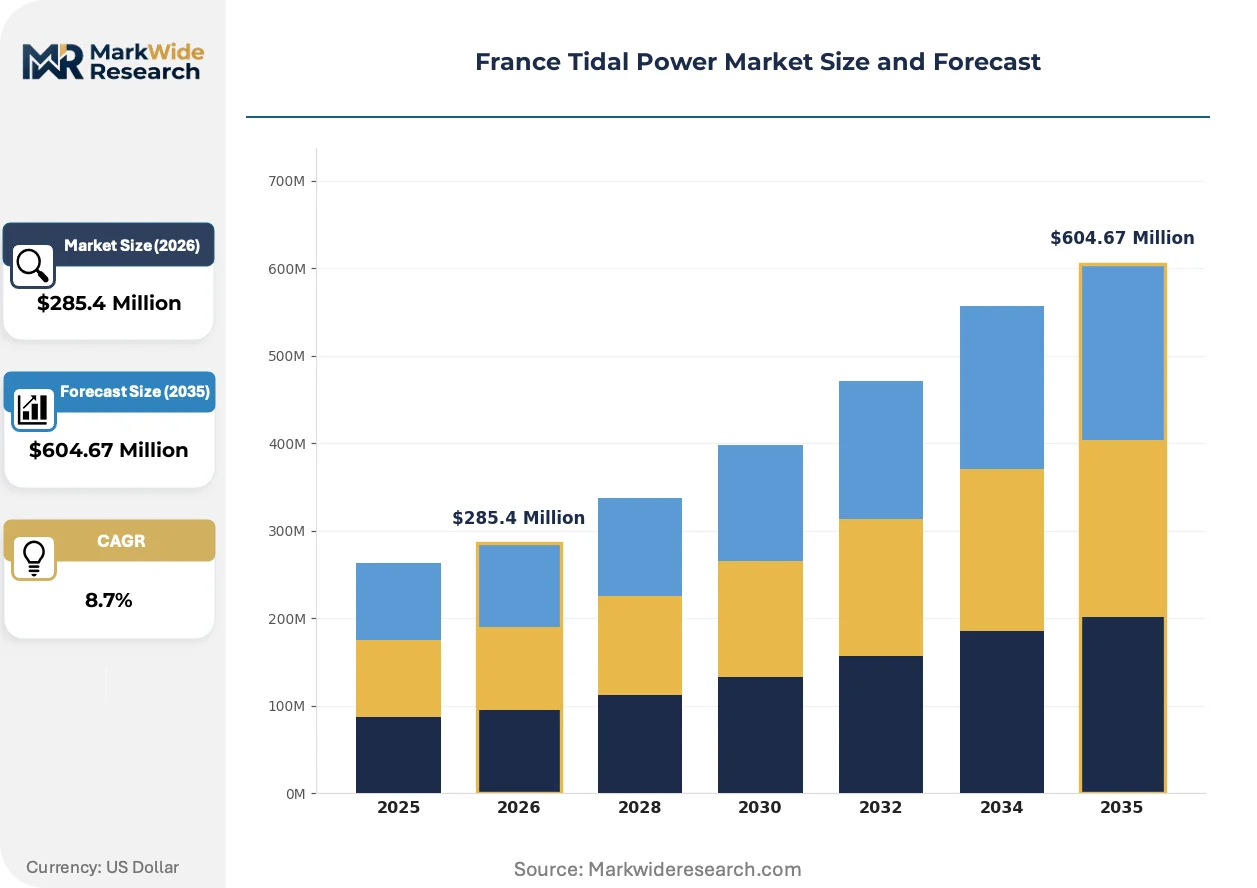
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Lagoon Systems, Dynamic Tidal Power, Tidal Stream Generators, Barrage Systems, Tidal Kite Technology Application: Electricity Generation, Grid Stabilization, Water Desalination, Remote Power Supply, Marine Research Stations End User Industry: Renewable Energy Producers, Utility Providers, Maritime Research Institutes, Coastal Infrastructure Authorities, Independent Power Companies Deployment Type: Nearshore Installations, Offshore Farms, Estuarine Setups, Marine Platforms, Floating Turbines |
| Companies Covered | Sabella SAS, Hydroquest SAS, SIMEC Atlantis Energy Ltd, EEL Energy, Guinard Energies Nouvelles, Morbihan Hydro Energies SAS, Nova Innovation Ltd, Électricité de France, Naval Energies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Tidal Power Market Shifts & Advancements
Technology convergence between tidal stream hardware and floating platform engineering is expanding deployable water depth ranges, while regulatory pressure on marine environmental compliance is filtering equipment procurement specifications.
Modular axial-flow turbine arrays are decentralizing project finance structures in the France Tidal Power Market. Smaller 100-500 kW units permit phased capital commitment from regional energy cooperatives and municipal utilities. This unit scale compression is enabling aggregator business models that pool multiple site revenues into investable portfolios.
France's environmental authority is tightening marine habitat assessment requirements under EU Marine Strategy Framework Directive obligations. Developers must now submit multi-year ecological monitoring plans before construction permits issue. The tidal stream segment bears disproportionate compliance burden as lagoon and barrage alternatives face stricter enclosure impact scrutiny.
Long-term power purchase agreements are displacing merchant exposure for new tidal installations. Institutional investors and pension funds now dominate project equity, demanding contracted revenue streams exceeding fifteen years. This preference shift concentrates development activity around sites with confirmed grid connection agreements and CRE tariff eligibility.
France Tidal Power Market Segmentation
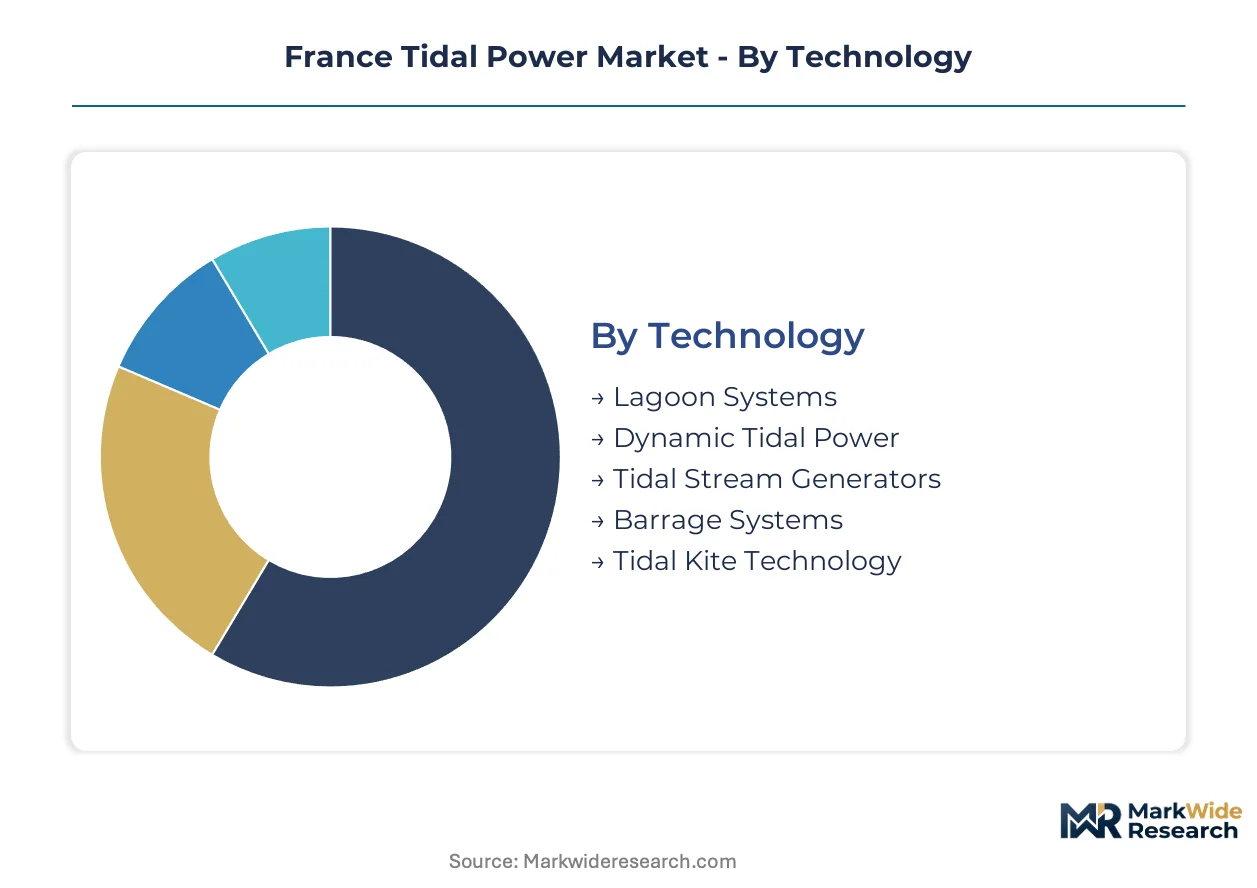
Technology and deployment configurations determine capital requirements and permitting complexity for tidal power developers in France. Segment selection shapes project finance structures, environmental assessment scope, and grid integration pathways across Brittany and Normandy development zones.
Technology:
Capital intensity varies sharply across tidal technologies, with enclosed systems demanding extensive civil engineering while free-flow designs minimize seabed modification.
- Tidal Stream Generators:Axial or cross-flow turbines rated 100 kW to 2 MW extract kinetic energy from unidirectional or bidirectional currents without dam construction. Brittany's Roscoff-Fromveur corridor concentrates commercial deployment due to velocity thresholds exceeding 2.5 m/s.
- Barrage Systems:Coastal dam structures impound tidal basins to generate electricity through low-head hydroelectric turbines. These installations face extended environmental review under EU Marine Strategy Framework Directive habitat assessments.
- Lagoon Systems:Semi-enclosed basin configurations with perimeter embankments reduce marine ecosystem disruption compared to full barrage enclosures. Normandy pilot projects test this architecture for lower-impact development.
- Dynamic Tidal Power:Pre-commercial coastal engineering concepts employ long dams perpendicular to shorelines to harness tidal phase differences without geographic constraints. Public R&D funding supports theoretical modeling and scaled testing.
- Tidal Kite Technology:Subsurface tethered wings sweep large swept areas through figure-eight trajectories, multiplying effective flow velocity. Sabella SAS and other developers evaluate kite systems for deep-water sites beyond fixed turbine reach.
Tidal Stream Generators absorb the bulk of installed capacity; Tidal Kite Technology is expanding most quickly through pilot deployments in deeper water zones.
Application:
Application segmentation reveals divergent revenue stability profiles, with contracted grid supply offering predictable returns versus merchant exposure in niche industrial markets.
- Electricity Generation:Baseload renewable supply fed into RTE transmission networks under CRE guaranteed purchase tariffs. Grid-connected projects dominate financing activity due to fifteen-year revenue visibility.
- Grid Stabilization:Predictable tidal output patterns enable frequency regulation services and renewable integration support. This application gains traction as intermittent wind and solar penetration rises in coastal grids.
- Water Desalination:Direct mechanical or electrical power for reverse osmosis plants in water-stressed coastal regions. Limited deployment due to competing solar-powered desalination economics.
- Remote Power Supply:Off-grid electricity for island communities or isolated industrial facilities bypassing transmission infrastructure. Brittany's archipelago installations test commercial viability.
- Marine Research Stations:Dedicated power for oceanographic monitoring equipment and autonomous underwater vehicle charging. Small-scale demand concentrated around Ifremer and CNRS facilities.
Electricity Generation commands dominant project finance flows; Grid Stabilization is climbing the fastest as ancillary service markets mature.
End User Industry:
Customer type determines procurement sophistication, with utility-scale buyers demanding extensive certification and smaller independents accepting higher technology risk.
- Utility Providers:Électricité de France and regional operators prioritize grid integration expertise and multi-decade asset management capabilities. Long-term power purchase agreements with these buyers dominate institutional investor mandates.
- Renewable Energy Producers:Specialized developers like Sabella SAS and Hydroquest SAS focus on technology demonstration and pipeline expansion. These firms aggregate site portfolios for subsequent utility or infrastructure fund acquisition.
- Independent Power Companies:Merchant developers seeking direct industrial offtaker contracts outside utility intermediaries. Higher return thresholds compensate for uncontracted revenue exposure.
- Coastal Infrastructure Authorities:Public entities procuring tidal installations for harbor protection, breakwater integration, or coastal defense dual-use applications. Procurement cycles align with maritime infrastructure planning horizons.
- Maritime Research Institutes:Ifremer and university consortia operating demonstration platforms for technology validation. Limited budget scale constrains commercial revenue contribution.
Utility Providers anchor current deployment pipelines; Independent Power Companies are gaining share fastest through direct industrial contracting models.
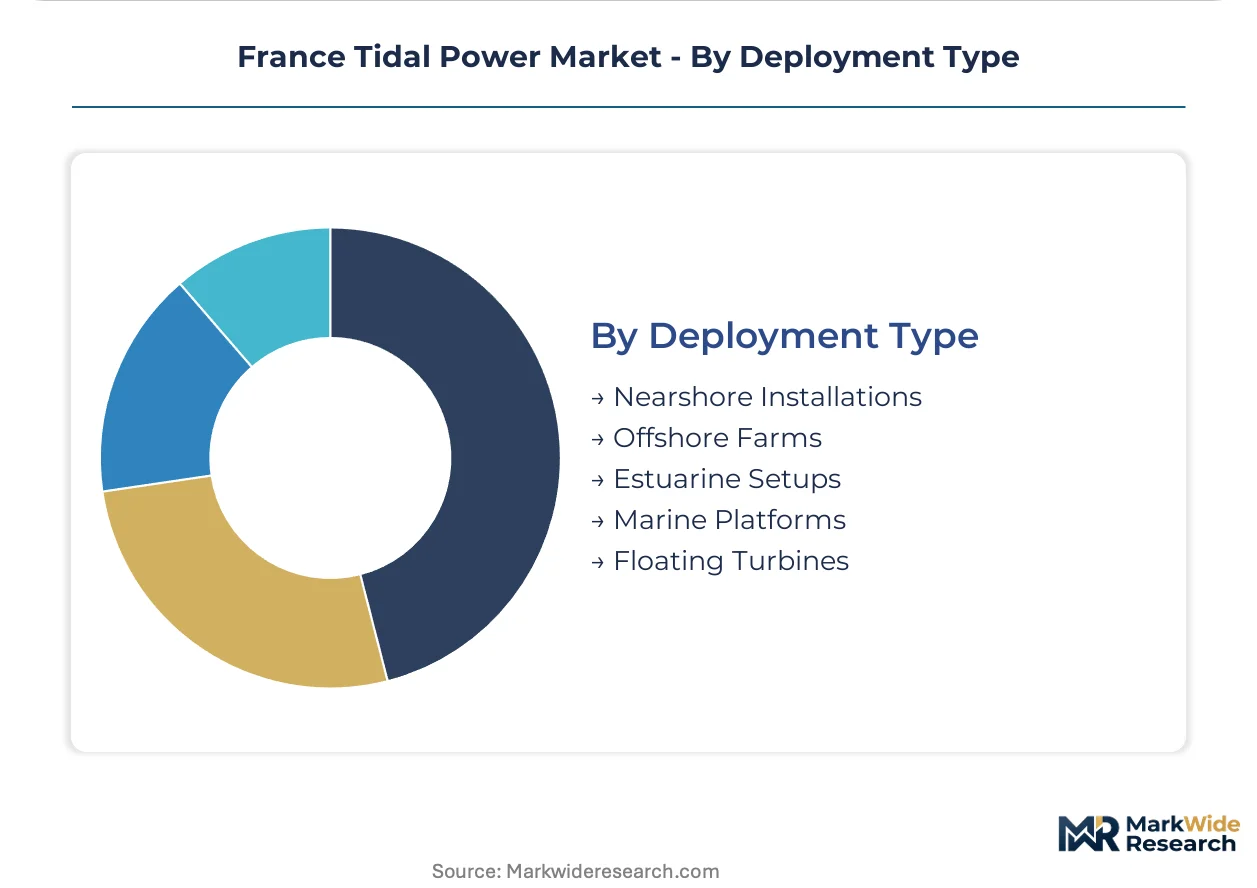
Deployment Type:
Physical configuration dictates installation cost structures, with floating platforms reducing seabed preparation but adding mooring complexity and dynamic cable challenges.
- Nearshore Installations:Bottom-mounted turbines in 20-50 meter depths with diver-accessible maintenance protocols. The Roscoff-Fromveur strait concentrates this deployment type due to favorable bathymetry and grid proximity.
- Offshore Farms:Array configurations in deeper waters requiring remotely operated vehicle maintenance and dynamic subsea cable systems. Higher capital intensity per megawatt limits current developer participation.
- Floating Turbines:Platform-mounted generators moored in water depths exceeding fixed-foundation economic thresholds. Bureau Veritas classification standards for floating marine energy converters shape equipment specifications.
- Estuarine Setups:Installations in river-sea transition zones with variable salinity and sediment loads. Hydroquest SAS targets these environments with vertical-axis architectures tolerant of directional flow variation.
- Marine Platforms:Multi-use structures combining generation with aquaculture, observation, or defense functions. Complex permitting across energy and maritime authorities constrains development velocity.
Nearshore Installations retain dominant deployment share; Floating Turbines are advancing most rapidly as water depth constraints push development offshore.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's tidal power generation concentrates along its western seaboard where Atlantic currents deliver exploitable kinetic energy, while consumption patterns align with coastal industrial demand clusters and grid integration nodes in Brittany and Normandy.
Brittany
The Roscoff-Fromveur strait corridor anchors France's highest commercially viable tidal velocities, exceeding thresholds required for axial turbine operation. Brittany's regional planning authority coordinates marine spatial allocation under the country's offshore renewable energy framework. Saint-Malo and Brest harbor zones concentrate turbine assembly and subsea cable fabrication activity.
Normandy
Estuarine environments in the Seine and Cotentin peninsulas attract vertical-axis turbine developers targeting variable directional flow conditions. The country's environmental authority enforces marine habitat assessments for lagoon system pilots testing semi-enclosed basin configurations. Le Havre port infrastructure supports heavy component logistics for nearshore installation fleets.
Pays de la Loire
The Loire estuary presents transitional water chemistry challenges for equipment corrosion resistance testing. Regional energy agencies coordinate grid connection pre-studies with RTE transmission network planners. Nantes-Saint-Nazaire industrial corridor hosts marine engineering subcontractors serving tidal platform fabrication.
Nouvelle-Aquitaine
Gironde and Adour estuaries offer lower-velocity deployment environments suitable for scaled turbine demonstration programs. The country's energy regulator extends CRE tariff eligibility to southwestern test sites meeting velocity verification protocols. Bordeaux maritime cluster contributes composite material expertise for floating platform construction.
France Tidal Power Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across France's tidal power equipment landscape. The market structure exhibits moderate concentration with utility-backed developers holding grid integration advantages while technology-origin startups retain design innovation primacy. Three strategic archetypes dominate: integrated energy majors with balance-sheet capacity, specialized marine turbine engineering firms with proprietary architectures, and regional project developers aggregating site portfolios. Competitive dynamics center on seabed lease acquisition speed and certification timeline compression.
Among France-based technology developers, Sabella SAS exemplifies the specialized turbine engineering archetype with Brittany-focused deployment expertise, while Hydroquest SAS occupies a position within the vertical-axis specialization tier targeting estuarine flexibility. Électricité de France anchors the integrated utility tier through grid integration capabilities and long-term power purchase agreement structures. Naval Energies represents the diversified industrial group archetype with marine engineering heritage applicable to platform fabrication and subsea systems.
| Leading Market Players |
|---|
| Sabella SAS |
| Hydroquest SAS |
| SIMEC Atlantis Energy Ltd |
| EEL Energy |
| Guinard Energies Nouvelles |
| Morbihan Hydro Energies SAS |
| Nova Innovation Ltd |
| Électricité de France |
| Naval Energies |
| Others |
Supply & Pricing Matrix
Neodymium price benchmarks on the Shanghai Metal Market cascade through permanent magnet synchronous generator costs, compressing margins for turbine manufacturers and forcing three-tier pricing stratification across premium-certified, standard-grade, and economy-tier equipment procurement.
Pricing Analysis
Margin tightening in standard-grade turbine tiers reflects rare earth magnet cost pass-through from concentrated Chinese supply chains. Project-based contract structures dominate, with price differentiation hinging on Bureau Veritas certification tier and after-sales service bundling. Cost-down pressure accelerates as utility buyers extend power purchase agreement duration requirements. Independent power companies exhibit highest price sensitivity due to uncontracted merchant exposure.
Supply Chain Analysis
Single-source vulnerability sits with Chinese neodymium processing facilities that feed permanent magnet production. Component sourcing draws from France for composite platform fabrication, Norway for subsea cable systems, and Germany for power electronics. Tariff exposure on rare earth exports constitutes the primary structural risk. Distribution runs through EPC contractors and marine installation specialists serving Brittany development zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's tidal power sector occupies a technology-transition phase where modular axial-flow turbines displace legacy barrage system architectures. This shift reconfigures competitive positioning across equipment procurement and project finance structures.
For Market Incumbents: Anchor grid integration capabilities through CRE tariff eligibility expansion and seabed lease consolidation in the Roscoff-Fromveur corridor. Sabella SAS and Électricité de France should deepen backward integration into permanent magnet supply chains to offset Chinese export restriction risks. Certification investment in floating platform architectures defends against emerging vertical-axis competitors.
For New Entrants and Emerging Players: Direct-to-utility digital procurement portals offer white-space entry around industrial offtaker direct contracting. Normandy lagoon system pilots represent the most penetrable deployment configuration. Target estuarine vertical-axis specialization where Hydroquest SAS has established technical credibility but market share remains contestable.
For Investors and Strategic Acquirers: Distressed-cycle entries favor technology-origin specialists with demonstrated seabed lease positions in Brittany. Long-term viability over a multi-year window hinges on CRE tariff framework continuity. Watch France's offshore renewable energy auction design as the critical inflection signal for tidal versus floating wind allocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Seabed Lease Consolidation | CRE tariff eligibility accelerates project finance viability for Brittany corridor developers. |
| Vertical-Axis Architecture R&D | Hydroquest SAS validates estuarine flexibility for variable directional flow conditions. |
| Power Purchase Agreement Extension | Fifteen-year contracted revenue streams attract institutional investor equity participation. |
| Floating Platform Certification | Bureau Veritas standards unlock deeper water deployment beyond fixed-foundation limits. |
| Lagoon System Pilot Expansion | Normandy semi-enclosed basins reduce marine habitat disruption versus barrage alternatives. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with tidal project developers, marine EPC contractors, utility planning officers, and CRE regulatory staff combined with secondary validation from France's energy regulator documentation, EU Marine Strategy Framework Directive compliance databases, and seabed lease auction records. Bottom-up project pipeline aggregation and top-down macroeconomic triangulation calibrated market sizing across the analysis window.
Segment-level modeling addressed technology type, deployment configuration, and end-user industry across the projection horizon. CAGRs derived from capacity deployment trajectories, tariff framework evolution, and supply chain cost curve assumptions. Forecast inputs incorporated neodymium price volatility indices, Bureau Veritas certification timeline data, and RTE grid connection queue status.
The model holds under stable CRE tariff continuation and EU marine habitat assessment protocol consistency; deviation in rare earth export restrictions or offshore auction design would shift deployment velocity. Forecasts reflect documented assumptions on seabed lease availability and technology cost reduction curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydropower Systems
Underground Hydro Power Plant Market
Hydropower Systems
South America Pumped Hydro Storage Market
Hydropower Systems
Hydropower Market
Hydropower Systems
Tidal Power Market
Hydropower Systems
Wave and Tidal Energy Market
Hydropower Systems
Standard Modular Hydropower Market
Hydropower Systems
North America Pumped Hydro Storage Market
Hydropower Systems
Europe Small Hydropower Market
Hydropower Systems
Hydro Turbines Market
Hydropower Systems
Africa Small Hydropower Market
Hydropower Systems
Pumped Hydro Storage Market
Hydropower Systems
Hydroelectricity Market
Hydropower Systems
Whirlpool Turbine Market
Hydropower Systems
Europe Hydropower Market
Hydropower Systems
Southeast Asia Hydropower Market
Hydropower Systems
Asia-Pacific Pumped Hydro Storage Market