
 Flight Management Systems Market | 2026-2036
Flight Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Flight Management Systems Market Intelligence
Low-cost carriers and cargo operators is redrawing procurement priorities for flight management systems, shifting volume toward modular upgrade paths and away from full green-field installations. Honeywell International Inc. leverages its integrated avionics portfolio to dominate the retrofit channel for narrow-body fleets. Thales Group anchors European supply through its cockpit electronics specialization, while Collins Aerospace competes via its breadth across commercial and military platforms.
A flight management system computes optimal flight path, fuel consumption, and navigation sequencing through integrated inertial reference units, GPS receivers, and performance databases operating under ARINC 702A standards. The system governs autopilot coupling, thrust management, and vertical profile optimization from pre-flight through final approach. Integrated Systems command the largest revenue pool by bundling navigation, guidance, and performance functions into single line-replaceable units, while Software Solutions represent the fastest-expanding margin layer as airlines pursue over-the-air updates and predictive maintenance analytics. Satellite-Based Systems are displacing legacy ground-based infrastructure for oceanic and remote-area routing, though Ground-Based Systems retain criticality for terminal approach precision.
FAA NextGen mandates and EASA CS-AWF certification requirements are forcing OEMs to embed required navigation performance and automatic dependent surveillance-broadcast compatibility into new deliveries. The EU AI Act and emerging machine-learning guidance from the FAA's AIR-600 division are beginning to shape algorithm validation protocols for autonomous flight path optimization. Stakeholders must decide whether to build in-house AI verification capabilities or partner with specialized aerospace software houses before regulatory deadlines harden.
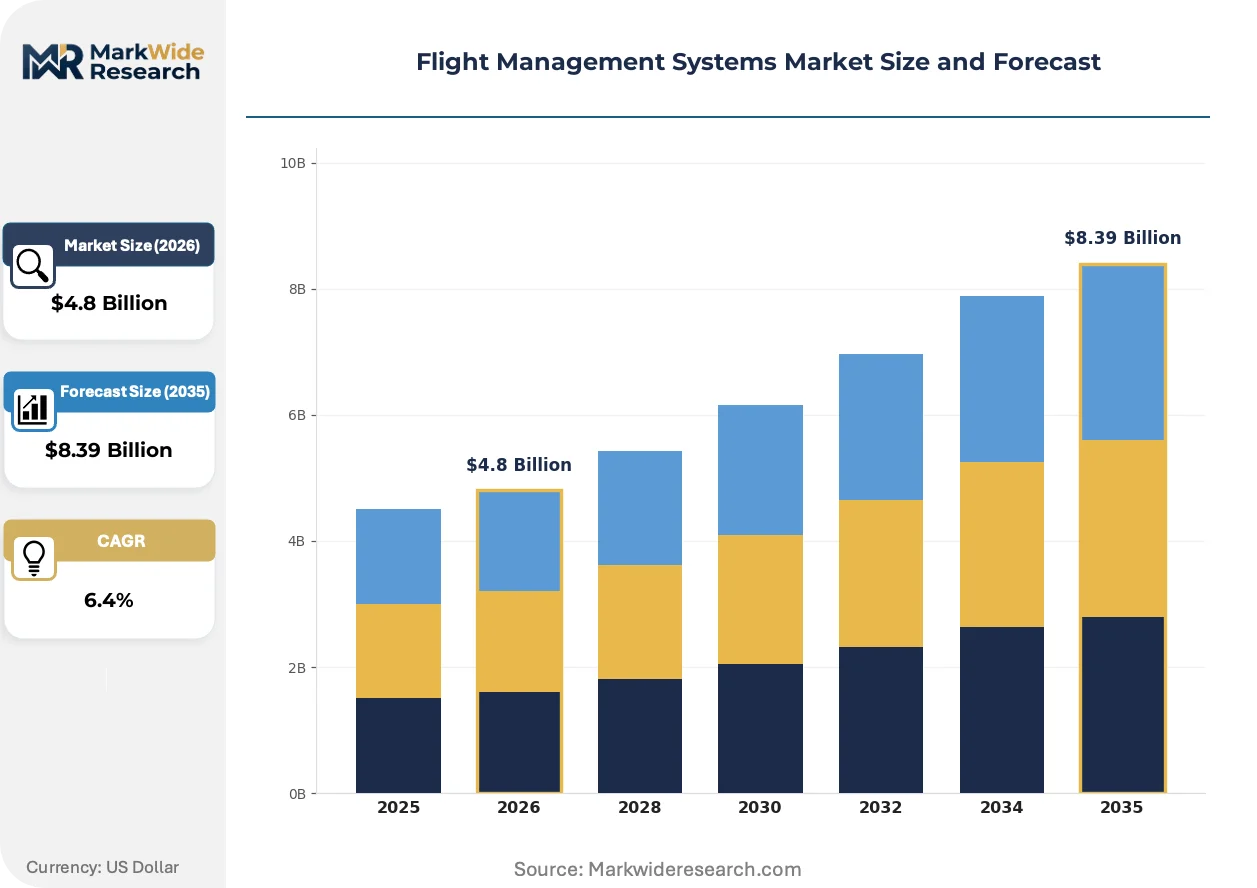
Market Dynamics
FAA NextGen mandates and EASA certification standards are compressing development cycles for flight management systems, forcing OEMs to embed required navigation performance and automatic dependent surveillance-broadcast compatibility into every new cockpit delivery.
Growth Catalysts
- Required Navigation Performance Mandates:FAA NextGen specifications and EASA CS-AWF standards compel fleet-wide avionics upgrades, retrofitting thousands of narrow-body aircraft with precision approach capabilities.
- Low-Cost Carrier Fleet Expansion:Budget airlines in Southeast Asia and Latin America are driving volume for modular FMS upgrades rather than full green-field installations, prioritizing cost-efficient line-replaceable units.
- Satellite-Based Augmentation:GPS-III and Galileo high-accuracy service signals enable oceanic and remote-area routing without ground infrastructure, opening new operational corridors over the North Atlantic and Pacific.
Market Restraints
- Semiconductor Supply Concentration:Advanced avionics-grade processors and radiation-hardened memory components concentrate fabrication in Taiwan and South Korea, exposing lead times to geopolitical friction.
- Certification Cost Escalation:ARINC 702A validation and DO-178C software assurance processes demand 18-24 month approval timelines, freezing development budgets for mid-tier suppliers.
- Legacy System Interoperability:Analog autopilot interfaces and proprietary data bus architectures in aging Boeing 737 NG and Airbus A320ceo fleets resist seamless FMS integration without expensive airframe modifications.
Strategic Opportunities
- Over-the-Air Update Infrastructure:Airlines seek predictive maintenance analytics and real-time navigation database refreshes delivered via satellite datalink, creating recurring revenue streams for software-centric providers.
- Urban Air Mobility Integration:eVTOL manufacturers in the United States and Germany require lightweight, certifiable flight management computers for autonomous urban operations, opening a green-field segment outside traditional commercial aviation.
- Indian Defense Modernization:The country's Ministry of Defence procurement programs for transport and combat aircraft specify indigenous FMS content, incentivizing joint ventures with domestic electronics manufacturers.
Industry Challenges
- DO-178C Software Engineering Talent:The pool of engineers qualified in formal methods, model-based design, and aerospace-specific safety cases remains critically shallow relative to program demand.
- Multi-Standard Harmonization:Divergent FAA, EASA, and CAAC validation protocols for machine-learning flight path algorithms force redundant testing campaigns, inflating development overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flight Management Systems Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Systems, Integrated Systems, Software Solutions, Avionics Systems End User: Commercial Airlines, Cargo Carriers, Private Operators, Military Aviation Technology: GPS Navigation, Inertial Navigation, Satellite-Based Systems, Ground-Based Systems Installation: Onboard Aircraft, Ground Control Centers, Maintenance Facilities, Portable Systems |
| Companies Covered | Honeywell International Inc., Thales Group, Collins Aerospace, Garmin Ltd., GE Aerospace, Leonardo S.p.A., Universal Avionics Systems Corporation, Lufthansa Systems, NAVBLUE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flight Management Systems Market Strategic Shifts & Innovations
Flight management systems are transitioning from hardware-defined boxes to software-defined platforms, with artificial intelligence and satellite-based augmentation rewriting performance benchmarks and procurement criteria across commercial and defense aviation.
Multi-constellation GNSS receivers integrating GPS, Galileo, BeiDou, and GLONASS signals are displacing legacy ground-based navigation aids for en-route and terminal operations. Regional carriers in Australia and Brazil are adopting these units to eliminate VOR/DME infrastructure dependency. The technology is displacing traditional radio-navigation maintenance contracts and enabling continuous descent approaches that cut fuel burn.
The EU AI Act's risk classification framework for safety-critical algorithms is mandating formal verification protocols for autonomous flight path optimization modules. European OEMs must document training data provenance and model drift detection before EASA type certification. Narrow-body retrofit programs face the steepest compliance burden, as legacy architectures lack the computational headroom for explainable AI implementations.
Airlines are unbundling FMS software licenses from hardware procurement, purchasing navigation databases and performance modules as subscription services. Low-cost carriers in the United States and Indonesia lead this transition, trading capital expenditure for operational flexibility. The shift compresses vendor switching costs and rewards providers with robust cloud infrastructure over those with legacy distribution networks.
Flight Management Systems Market Segmentation
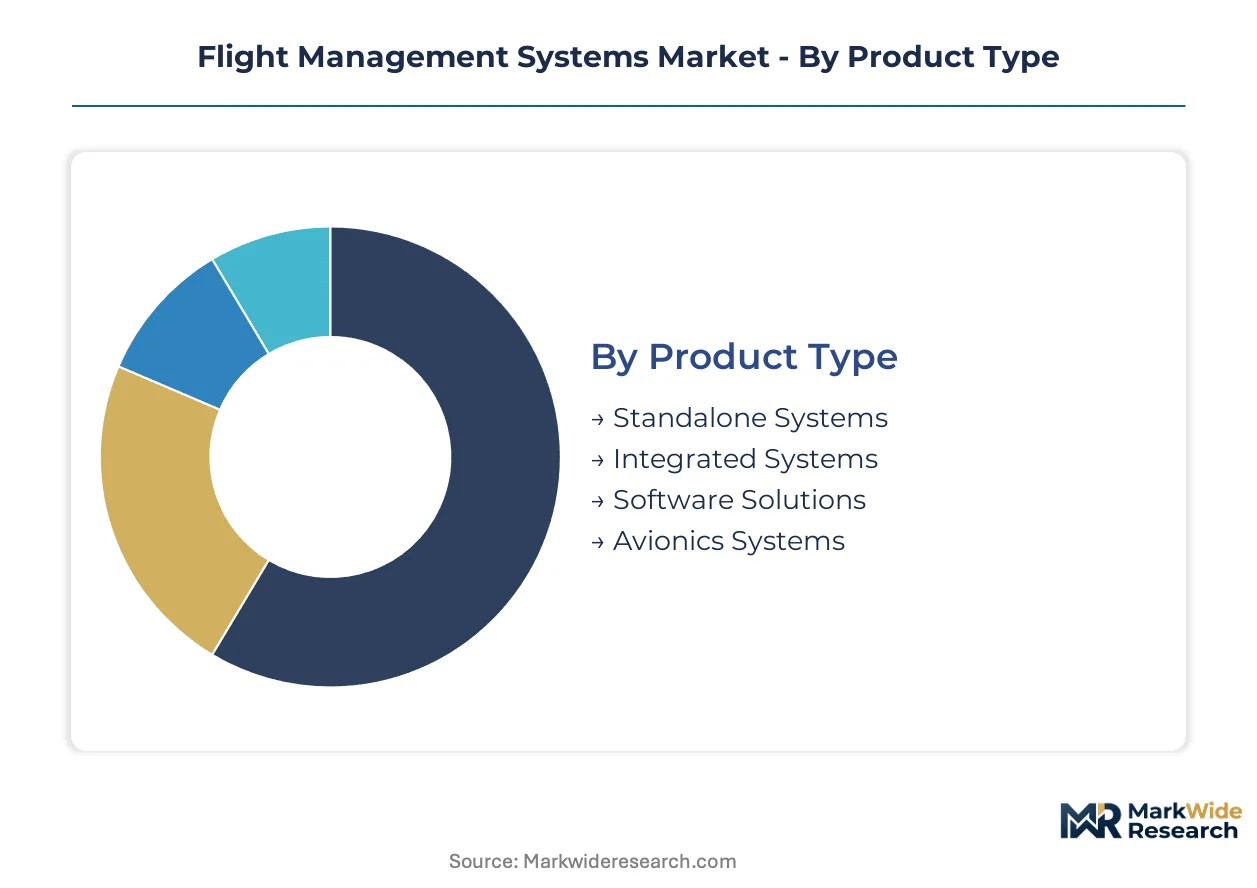
Flight management systems fragment across four distinct dimensions, each commanding different procurement rhythms and margin profiles. Product architecture determines upgrade pathways, while installation location shapes regulatory jurisdiction and service contract structures.
Product Type:
Standalone hardware faces acute substitution pressure from software-defined platforms that bypass dedicated line-replaceable units entirely. Hardware-centric segments must defend through certification moats and airframe integration depth.
- Integrated Systems:Bundled navigation, guidance, and performance functions consolidate into single line-replaceable units certified under ARINC 702A standards. Commercial airlines in the United States prioritize these for narrow-body fleet modernization, trading modularity for reduced cockpit complexity and unified vendor accountability.
- Software Solutions:Navigation databases, performance optimization modules, and predictive analytics deploy via over-the-air satellite datalink without hardware swap. Low-cost carriers in Indonesia and the United States favor subscription licensing here, converting capital expenditure into operational flexibility while enabling real-time route adjustments.
- Standalone Systems:Discrete flight management computers serving single-function roles persist in legacy aircraft where full cockpit retrofit proves uneconomical.
- Avionics Systems:Broader cockpit electronics suites incorporate FMS as one subsystem among integrated displays and communication radios.
Integrated Systems retain volume leadership; Software Solutions hold the steepest expansion curve.
End User:
Procurement scale concentrates sharply in commercial aviation, though military specifications impose divergent security and redundancy requirements that fragment supplier economics.
- Commercial Airlines:Scheduled passenger carriers drive procurement volume through fleet-wide avionics mandates, with FAA NextGen and EASA CS-AWF compliance deadlines forcing narrow-body retrofits across thousands of airframes.
- Cargo Carriers:Express freight operators prioritize fuel optimization algorithms for long-haul routes, adopting satellite-based augmentation for oceanic corridors where ground infrastructure cannot follow network expansion.
- Private Operators:Business aviation and fractional ownership fleets demand portable or lightly certified solutions that balance functionality against acquisition cost.
- Military Aviation:Defense procurement specifies jam-resistant navigation, encrypted datalinks, and nuclear event survivability that civilian platforms cannot satisfy.
Commercial Airlines dominate absolute spend; Cargo Carriers are expanding most quickly as e-commerce logistics reshape route networks.
Technology:
Ground-based infrastructure confronts existential displacement as multi-constellation satellite signals achieve equivalent precision without maintenance-intensive terrestrial stations.
- Satellite-Based Systems:GPS-III, Galileo high-accuracy service, and BeiDou-3 signals enable Required Navigation Performance approaches without VOR/DME dependency. Regional carriers in Australia and Brazil have eliminated ground infrastructure maintenance contracts entirely, rerouting savings into continuous descent approach fuel savings.
- GPS Navigation:Single-constellation receivers persist in cost-constrained retrofit programs where multi-frequency antenna upgrades exceed budget tolerance.
- Inertial Navigation:Ring laser gyro and fiber-optic gyro units provide position data during GPS signal denial, critical for military platforms and oceanic routes where satellite geometry degrades.
- Ground-Based Systems:VOR, DME, and ILS installations retain terminal approach precision where terrain masking or interference requires localized augmentation, though maintenance contracts are contracting as airlines migrate to satellite alternatives.
Satellite-Based Systems command the technology transition; GPS Navigation holds residual retrofit demand.
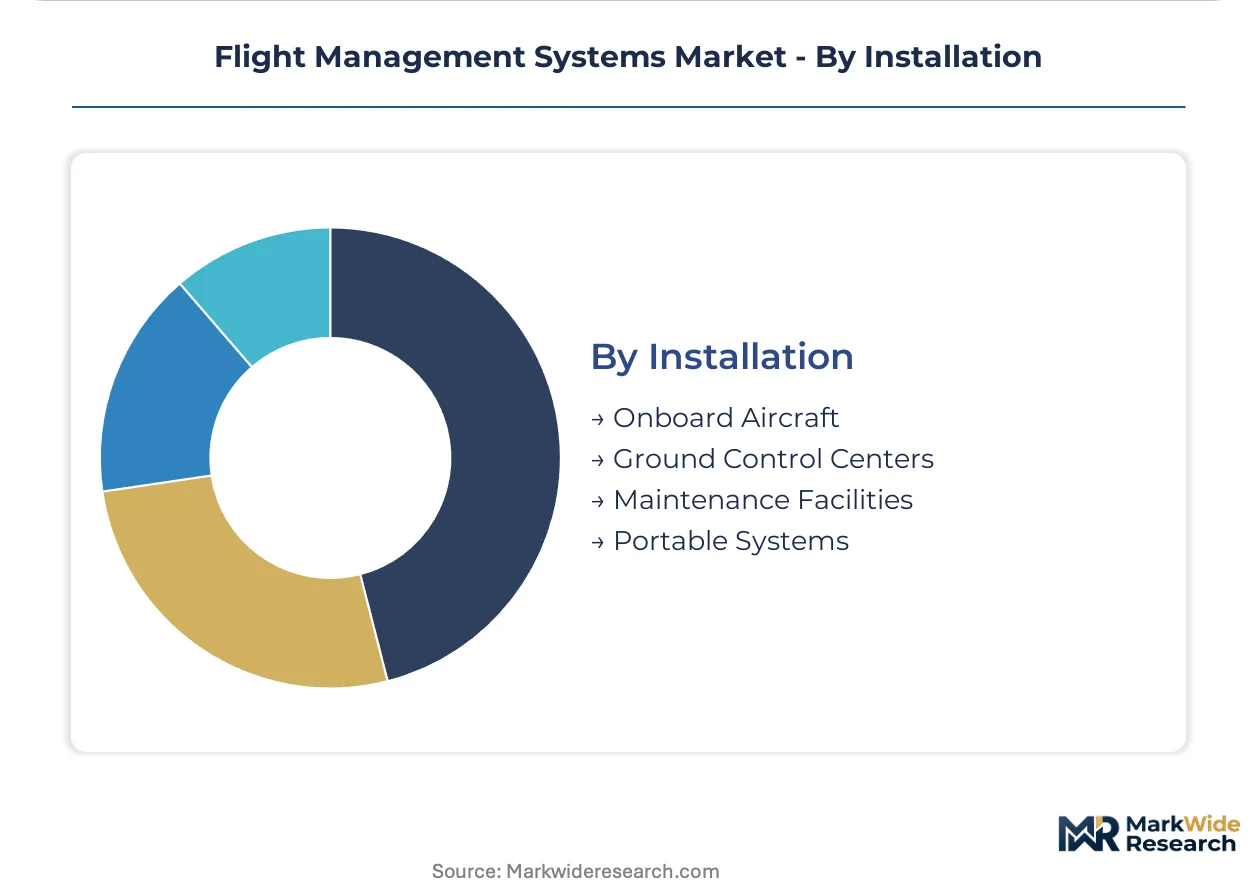
Installation:
Physical location determines certification pathway, with airborne hardware facing airworthiness authority jurisdiction and ground systems falling under telecommunications and facility regulations.
- Onboard Aircraft:Flight management computers, control display units, and sensor suites installed in the cockpit undergo FAA, EASA, or CAAC type certification tied to specific airframe approvals. Hardware refresh cycles here stretch 15-20 years, locking vendors into long-term database subscription relationships.
- Ground Control Centers:Flight planning workstations and fleet monitoring systems aggregate FMS data for dispatch optimization, with airlines in Germany and the United States consolidating these into centralized operations centers.
- Maintenance Facilities:Test benches and diagnostic equipment verify FMS performance during heavy maintenance checks, with MRO providers in Singapore and the United Arab Emirates investing in automated test sets that compress turnaround times.
- Portable Systems:Tablet-based electronic flight bags and handheld navigation aids supplement certified avionics without formal installation, popular among general aviation pilots and flight training organizations.
Onboard Aircraft absorbs the majority of certification expenditure; Portable Systems are gaining share fastest as electronic flight bag penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Major carriers and defense contractors in the United States drive procurement volumes for integrated cockpit systems, while regulatory mandates in Europe and fleet expansion in Asia reshape upgrade priorities.
United States
American Airlines, Delta Air Lines, and United Airlines are retrofitting narrow-body fleets under FAA NextGen deadlines, with required navigation performance mandates forcing avionics refreshes across thousands of Boeing 737 and Airbus A320 airframes. The FAA's AIR-600 division is drafting machine-learning guidance for autonomous flight path optimization. Seattle and Wichita host concentrated engineering clusters where Honeywell and Collins Aerospace operate major development centers.
Germany
Lufthansa Group and cargo operators are adopting satellite-based augmentation for North Atlantic routes, eliminating ground infrastructure dependency. The EU AI Act's risk classification framework is mandating formal verification protocols for safety-critical algorithms before EASA type certification. Hamburg and Munich anchor European cockpit electronics development, with Thales Group and Lufthansa Systems maintaining significant presences.
China
COMAC's C919 production ramp and airline fleet modernization are creating procurement volume for indigenous flight management computers. The Civil Aviation Administration of China is harmonizing certification protocols with FAA and EASA standards for required navigation performance. Shanghai and Xi'an concentrate avionics manufacturing, with state-owned enterprises and joint ventures competing for domestic content mandates.
India
IndiGo and SpiceJet are expanding narrow-body fleets, driving demand for modular FMS upgrades rather than full green-field installations. The Ministry of Defence's procurement programs for transport and combat aircraft specify indigenous FMS content requirements. Bengaluru and Hyderabad host growing aerospace electronics clusters where joint ventures with domestic manufacturers are forming.
Brazil
Azul and Gol Linhas Aéreas are retrofitting regional fleets with multi-constellation GNSS receivers to eliminate VOR/DME infrastructure maintenance. ANAC is aligning certification timelines with FAA NextGen and EASA CS-AWF standards for precision approach capabilities. São José dos Campos anchors Embraer's engineering base, with supply chain spillover into adjacent avionics component production.
Flight Management Systems Market Key Industry Players
Player mix skews toward integrated avionics conglomerates with certification depth and software-defined specialists with recurring revenue models. Three to five diversified aerospace electronics groups control the retrofit channel for narrow-body fleets. Strategic archetypes include full-stack cockpit integrators, modular upgrade specialists, and defense-anchored dual-use suppliers. Competitive moves center on over-the-air update infrastructure deployment and urban air mobility platform partnerships.
Within the integrated avionics tier, Honeywell International Inc. and Thales Group exemplify full-stack cockpit dominance, while Collins Aerospace occupies a position spanning commercial and military platforms. Garmin Ltd. represents the modular specialist archetype with portable and retrofit solutions. Leonardo S.p.A. anchors European defense-anchored supply. These entities collectively illustrate how certification moats and airframe integration depth defend position against software-centric challengers.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Thales Group |
| Collins Aerospace |
| Garmin Ltd. |
| GE Aerospace |
| Leonardo S.p.A. |
| Universal Avionics Systems Corporation |
| Lufthansa Systems |
| NAVBLUE |
| Others |
Cost & Logistics Intelligence
Avionics-grade semiconductor fabrication at 300mm wafer scale in Taiwan and South Korea creates steep fixed-cost barriers that concentrate supply among radiation-hardened memory foundries and simultaneously establish price floors for flight management computers that smaller competitors cannot undercut without sacrificing DO-178C certification depth.
Pricing Analysis
Cost-plus contracts with labor and materials indexation dominate military procurement, while commercial airlines negotiate fixed-price multi-year service agreements bundling hardware refresh cycles with navigation database subscriptions. Price differentiation rests on ARINC 702A certification tier and after-sales support integration, with full-stack cockpit integrators commanding premiums over modular upgrade specialists. Pricing pressure stems from low-cost carrier procurement teams in Southeast Asia demanding SaaS-tiered software licenses that convert capital expenditure to operational flexibility. Cargo operators prove least price-sensitive, prioritizing fuel optimization algorithm accuracy over acquisition cost.
Supply Chain Analysis
Just-in-time inventory strategies prevail for standard commercial avionics, while defense contractors maintain strategic stockpiles of radiation-hardened processors given 18-24 month certification lead times. Supply concentrates in Taiwan for advanced semiconductors, South Korea for memory components, and the United States for integrated cockpit assembly. Raw material dependencies include gallium arsenide substrates, ceramic packaging for thermal management, and specialized aluminum-lithium alloys for chassis fabrication. Single-source vulnerability around Taiwan Strait geopolitical friction threatens fabrication continuity. Distribution runs through OEM direct sales for new aircraft installations and authorized MRO channels for retrofit programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among three major US network carriers and two European airline groups that now account for the majority of narrow-body fleet retrofit decisions, fragmenting procurement leverage across smaller regional operators and forcing tier-two suppliers into unfavorable payment terms.
For Market Incumbents: Consolidate certification moats by deepening in-house production of safety-critical software verification tools before EU AI Act deadlines harden formal validation requirements. Acquire specialized aerospace software houses in Germany or the United States to capture AI flight path optimization talent pools that DO-178C engineering scarcity threatens to exhaust. Prioritize channel control over MRO networks in Singapore and Dubai to lock retrofit access points against modular specialists. For New Entrants and Emerging Players: Anchor in urban air mobility platform development, where eVTOL manufacturers in Germany and the United States require lightweight certifiable flight management computers absent incumbent supply lock-in. Target Indian defense procurement programs specifying indigenous FMS content requirements as the most penetrable geography given joint venture incentives with domestic electronics manufacturers. Pursue subscription-first go-to-market positioning that unbundles software licenses from hardware to bypass entrenched cockpit integration relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-defined platform specialists with recurring revenue models over hardware-centric legacy suppliers facing retrofit saturation. Long-term viability in this market hinges on over-the-air update infrastructure ownership and predictive maintenance analytics capabilities that airlines increasingly demand. Acquisition targets should demonstrate cloud-native navigation database delivery and machine-learning algorithm validation pipelines. Watch FAA AIR-600 machine-learning guidance publication as the signal indicating when AI verification capabilities become table stakes versus differentiators.| Strategic Initiative | Industry Significance |
|---|---|
| Over-the-Air Update Infrastructure Deployment | Enables real-time navigation database refreshes and predictive maintenance analytics for satellite datalink-connected fleets. |
| Urban Air Mobility Platform Partnership | Secures green-field design wins with eVTOL manufacturers requiring certifiable lightweight flight management computers. |
| AI Verification Capability Buildout | Addresses EU AI Act formal validation requirements before EASA type certification deadlines harden algorithm documentation standards. |
| Indian Joint Venture Formation | Satisfies Ministry of Defence indigenous content mandates for transport and combat aircraft FMS procurement programs. |
| Multi-Constellation GNSS Integration | Eliminates VOR/DME infrastructure dependency for regional carriers in Australia and Brazil seeking fuel-saving continuous descent approaches. |
Research Approach
A standing panel of avionics program managers at major airlines, FAA certification engineers, EASA type certification leads, and MRO procurement directors provided ongoing calibration against fleet modernization timelines and regulatory interpretation shifts. Primary fieldwork combined structured interviews with Honeywell and Thales engineering executives, Collins Aerospace platform integration specialists, and Garmin retrofit channel managers. Secondary validation drew from FAA NextGen implementation reports, EASA CS-AWF certification databases, ARINC standards documentation, and airline fleet planning disclosures. Bottom-up segmentation modeling triangulated against top-down OEM revenue attribution by product line.
Consistency checks validated volume and value outputs against external benchmarks including disclosed avionics procurement contracts, airframe delivery schedules, and regulatory mandate compliance deadlines. The analytical framework modeled product architecture, end-user category, navigation technology type, and installation location across the projection horizon. CAGRs derived from segment-level unit economics and pricing trajectory assumptions. Industry-specific forecast inputs included narrow-body fleet age profiles, NextGen equipage mandates, and satellite constellation deployment schedules for GPS-III and Galileo high-accuracy service.
Material uncertainties — semiconductor supply disruptions, FAA-EASA-CAAC regulatory harmonization failures, and AI algorithm validation protocol changes — sit outside the modeled envelope. Forecasts reflect assumptions regarding certification timeline stability and airline capital expenditure continuity. Revision becomes warranted when geopolitical friction in Taiwan Strait fabrication centers triggers supply rationing thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Aerostructures Market
Aircraft
South Korea Aviation Market
Aircraft
Asia-Pacific General Aviation Market
Aircraft
America Freighter Aircraft Market
Aircraft
Airplane and Helicopter Hangar Doors Market
Aircraft
Single-Seat Gyrocopter Market
Aircraft
Asia-Pacific Aircraft Manufacturing Market
Aircraft
Europe Aircraft Manufacturing Market
Aircraft
Water Bomber Market
Aircraft
Aircraft Fairings Market
Aircraft
Military Helicopters Market
Aircraft
Middle-East and Africa Freighter Aircraft Market
Aircraft
Asia-Pacific Attack Helicopter Market
Aircraft
Fighter Aircraft Market
Aircraft
Aircraft Mounts Market
Aircraft
Supersonic Jet Market