
 Autonomous Aircraft Flight Management Computers Market | 2026-2036
Autonomous Aircraft Flight Management Computers Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Aircraft Flight Management Computers Market Analysis
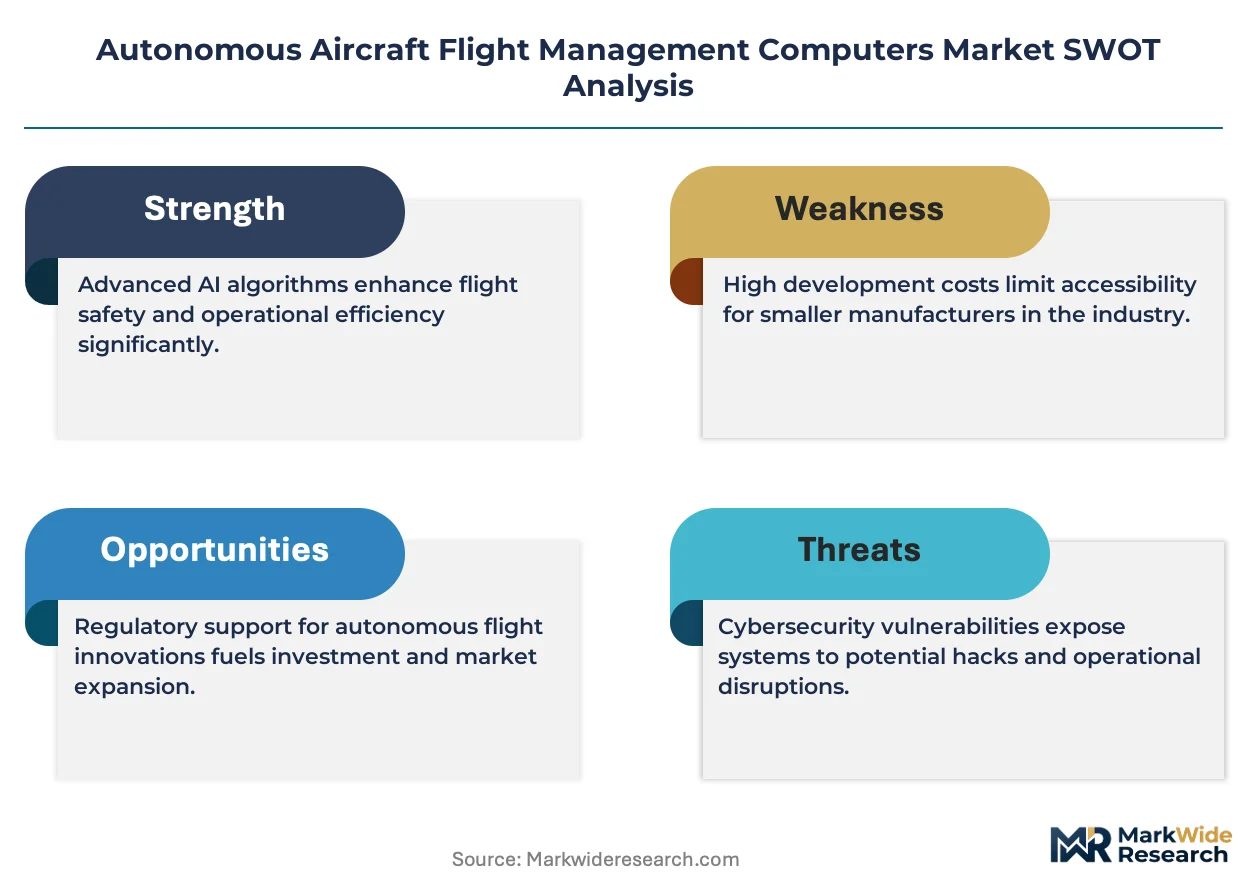
Edge-native computing architectures is reconfiguring how flight management systems process real-time sensor streams without ground station dependency. Boeing sustains extensive vertical integration across its autonomous flight programs, from hardware design to airworthiness certification. Lockheed Martin Corporation dominates classified defense applications through captive R&D facilities in Palmdale, California. Elbit Systems Ltd. positions its autonomous computing suites for export markets across Eastern Europe and the Asia-Pacific.
An autonomous aircraft flight management computer is a hardened avionics processor executing trajectory optimization, fault-tolerant navigation, and vehicle health monitoring at sub-50 millisecond loop rates under DO-178C software assurance standards. Its primary purpose is to replace human pilot decision-making in controlled airspace with certifiable machine autonomy. Military applications generate the deepest margin pools due to classified performance requirements and sole-source contracting structures. AI-Based technology segments attract disproportionate R&D allocation as defense agencies fund neural network verification for safety-critical flight control. Cargo applications remain nascent but hold structural expansion potential as logistics providers evaluate beyond-visual-line-of-sight autonomous freight corridors.
The FAA's Part 89 remote identification rule and EASA's special condition for light unmanned aircraft systems impose divergent certification burdens on hardware architectures targeting transatlantic markets. China's NMPA and MIIT coordinate GB standards for civil unmanned aviation, creating a separate compliance track for suppliers accessing Chinese airspace. ISO 21384-3 unmanned aircraft systems operational standards and RTCA DO-254 hardware design assurance guidelines further fragment the regulatory landscape. Stakeholders must decide whether to architect modular certification stacks or accept geographic market exclusions based on single-authority compliance investments.
Market Dynamics
Edge-native computing architectures are compressing latency requirements for autonomous flight systems, forcing hardware suppliers to rearchitect processing stacks around real-time sensor fusion rather than ground-reliant decision loops.
Growth Catalysts
- Detect-and-avoid mandates:FAA integration requirements for unmanned aircraft systems are accelerating certification demand for onboard computing platforms that execute collision avoidance without human intervention.
- Neural network verification funding:Defense agencies are directing R&D resources toward safety-critical flight control AI, expanding addressable hardware requirements for certifiable machine autonomy.
- California-Texas defense clusters:Geographic concentration of prime contractors and specialized testing infrastructure is concentrating procurement volume and technical talent acquisition.
Market Restraints
- DO-178C compliance costs:Software assurance certification for Level A criticality functions imposes multi-year development timelines and specialized verification labor pools.
- Custom silicon dependency:Radiation-hardened and temperature-extreme processor supply concentrates among a limited set of qualified foundries, creating single-source vulnerability.
- Transatlantic regulatory divergence:FAA Part 89 remote identification and EASA special conditions impose incompatible hardware architecture requirements, fragmenting addressable market scope.
Strategic Opportunities
- Beyond-visual-line-of-sight freight corridors:Logistics providers are evaluating autonomous cargo routes for structural expansion into unmanned aerial freight networks.
- Eastern European export markets:NATO member states are expanding procurement of autonomous flight systems for unmanned surveillance missions, creating demand outside traditional defense prime relationships.
- Modular certification stacks:Hardware architectures that separate compute, I/O, and power domains enable geographic market flexibility without complete redesign for single-authority compliance.
Industry Challenges
- DO-254 hardware verification talent:Design assurance guideline expertise for complex electronic hardware remains scarce relative to software certification specialization.
- Multi-authority parallel certification:Simultaneous FAA, EASA, and NMPA compliance tracks require redundant testing protocols and documentation sets, compressing program margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Aircraft Flight Management Computers Market |
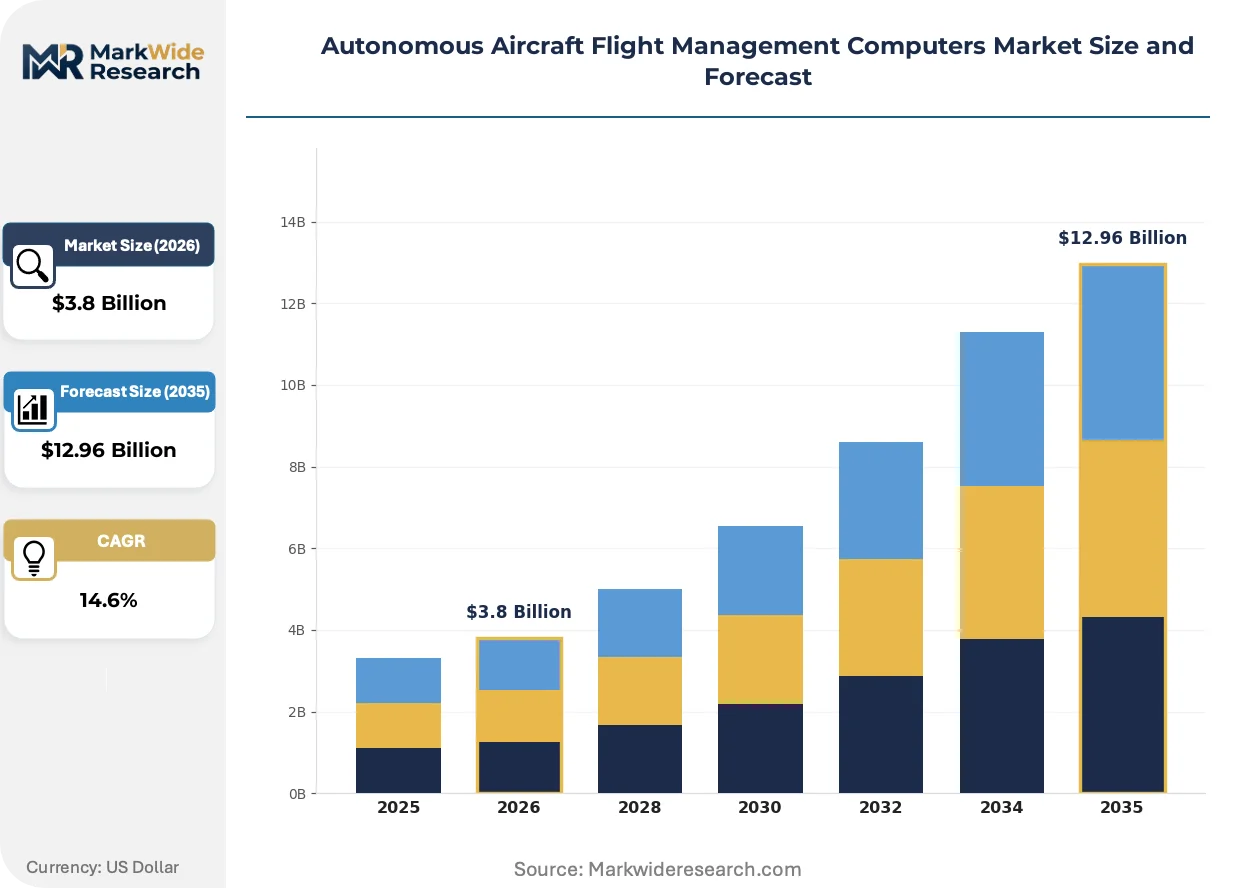
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial, Military, Cargo, Drones Technology: AI-Based, Sensor Fusion, GPS Navigation, Data Links End User: Aerospace OEMs, Airlines, Defense Contractors, Logistics Providers Application: Passenger Transportation, Surveillance, Cargo Delivery, Emergency Services |
| Companies Covered | Textron Inc., Northrop Grumman Corporation, Saab AB, Boeing, Aeronautics Ltd., Elbit Systems Ltd., Airbus S.A.S, BAE Systems Plc, Lockheed Martin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Aircraft Flight Management Computers Market Emerging Trajectories
Real-time processing architectures are displacing ground-station-dependent control models, compressing decision latency from seconds to milliseconds and enabling operations in contested or denied communication environments.
Neuromorphic computing substrates are digitizing sensor preprocessing workloads that previously required discrete analog front-ends. Defense primes operating classified programs in Palmdale, California are piloting these architectures for sub-50 millisecond navigation loop closure. The shift is digitizing fault-tolerant trajectory optimization into standard silicon rather than custom FPGA implementations.
EASA's special condition for light unmanned aircraft systems is mandating equivalent safety demonstrations that diverge from FAA Part 89 remote identification technical standards. Hardware suppliers targeting transatlantic markets must maintain dual certification stacks or accept geographic exclusions. The regulatory friction most affects mid-tier suppliers lacking captive airworthiness certification resources.
Service unbundling is separating hardware procurement from ongoing airworthiness support, with defense agencies negotiating performance-based logistics contracts that transfer operational risk to original equipment manufacturers. Traditional bundled pricing models are yielding to availability-guarantee structures where payment ties to mission-capable rates rather than unit delivery. The shift is most visible in United States unmanned surveillance program contracting.
Autonomous Aircraft Flight Management Computers Market Segmentation
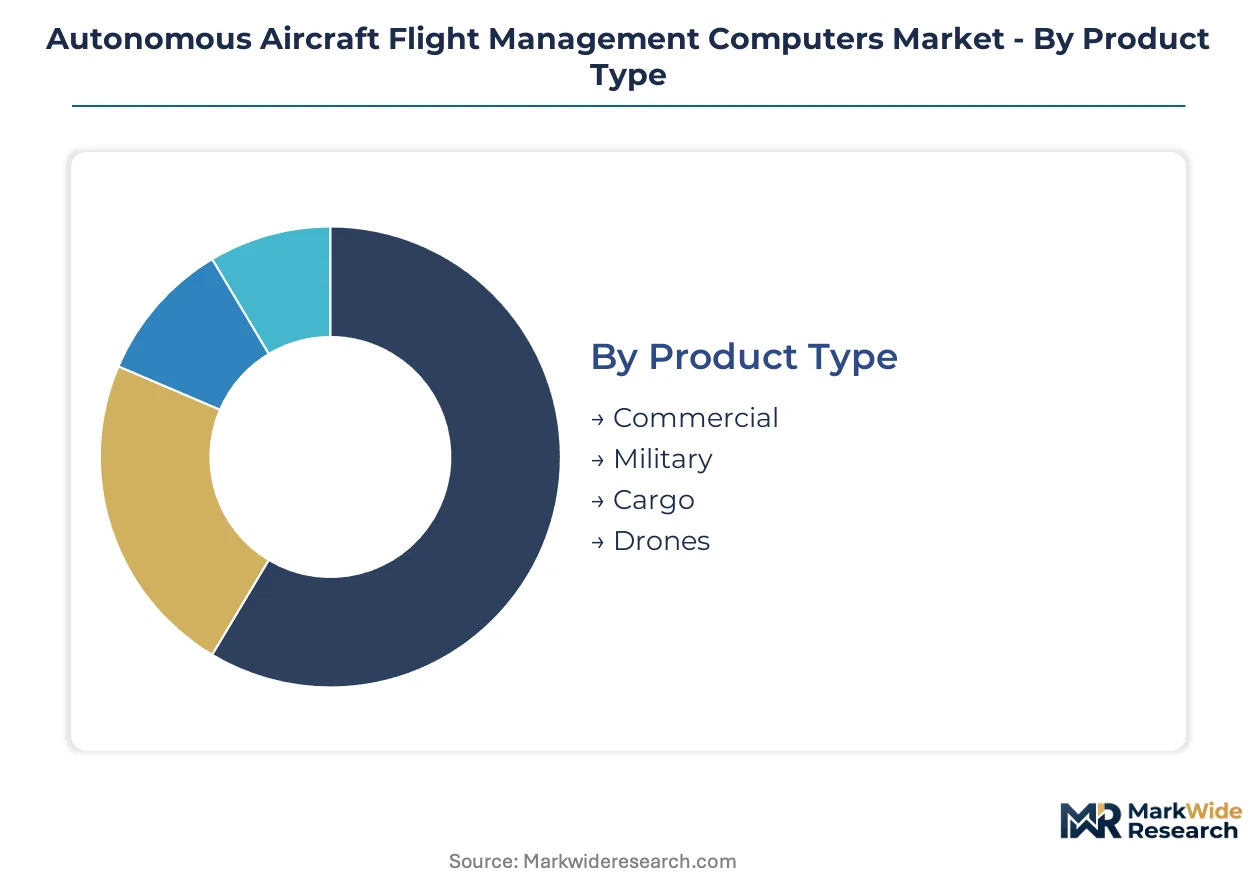
Flight management computer architectures diverge sharply across operational domains, with certification requirements and processing specifications varying by mission criticality. Segmentation reveals how defense procurement patterns, commercial airworthiness standards, and emerging logistics applications create distinct hardware demand profiles with incompatible development timelines.
Product Type:
Cost tiers separate hardened military-grade systems from commercial aviation processors and emerging cargo platforms, with certification burden and unit economics diverging across each bracket.
- Military:Radiation-hardened processors execute fault-tolerant navigation under DO-178C Level A assurance for contested airspace operations. Demand concentrates in classified programs around Palmdale, California and Texas defense clusters, driven by sole-source contracting structures and neural network verification mandates from defense agencies.
- Commercial:Avionics processors for passenger aircraft prioritize transatlantic certification flexibility under FAA and EASA parallel tracks. Airlines in the United States and European Union dominate procurement, constrained by multi-year compliance timelines for equivalent safety demonstrations.
- Cargo:Emerging platforms target beyond-visual-line-of-sight freight corridors with reduced criticality classifications. Logistics providers in the United States evaluate unmanned aerial networks for structural expansion into autonomous delivery routes.
- Drones:Light unmanned systems operate under Part 89 remote identification and EASA special conditions with compressed hardware requirements. Recreational and commercial operators in the United States and European Union drive volume procurement for detect-and-avoid capable compute modules.
Military systems command the established base. The steepest expansion runs through Cargo applications as logistics providers validate autonomous freight economics.
Technology:
Processing architectures differentiate by sensor integration depth, with real-time loop closure requirements forcing hardware specialization across autonomy levels.
- AI-Based:Neural network inference engines execute trajectory optimization and anomaly detection at sub-50 millisecond latencies. Defense agencies in the United States fund safety-critical flight control verification, expanding addressable hardware requirements for certifiable machine autonomy implementations.
- Sensor Fusion:Multi-modal preprocessing integrates LiDAR, radar, and electro-optical streams without ground station dependency. NATO member states in Eastern Europe procure these architectures for unmanned surveillance missions in denied communication environments.
- GPS Navigation:Positioning processors with anti-spoofing countermeasures support navigation integrity in contested electromagnetic environments. Military end-users specify these modules for jamming-resistant operations.
- Data Links:Communication processors manage command-and-control telemetry with encryption and frequency-agility features. Beyond-visual-line-of-sight cargo platforms require these for extended-range operations.
Sensor Fusion anchors current procurement volume. AI-Based architectures are climbing the fastest as neural network verification funding redirects hardware development priorities.
End User:
Customer type determines procurement modality, with defense agencies negotiating performance-based logistics while commercial operators seek bundled airworthiness support.
- Defense Contractors:Prime contractors in California and Texas sustain captive R&D facilities for classified program execution. These stakeholders dominate high-margin procurement through availability-guarantee contracts transferring operational risk to manufacturers.
- Aerospace OEMs:Integrated airframe manufacturers specify flight management computers during platform development, requiring early certification commitment. Boeing maintains extensive backward integration from hardware design through airworthiness certification.
- Airlines:Commercial operators prioritize modular certification stacks enabling geographic market flexibility without complete redesign. United States and European Union carriers evaluate fleet retrofit economics against new platform acquisition.
- Logistics Providers:Freight operators pilot autonomous cargo networks with reduced regulatory burden compared to passenger applications. These end-users drive demand for cost-optimized processors with deferred airworthiness support structures.
Defense Contractors retain the deepest margin pools. Logistics Providers represent the most rapid customer expansion as freight autonomy economics mature.
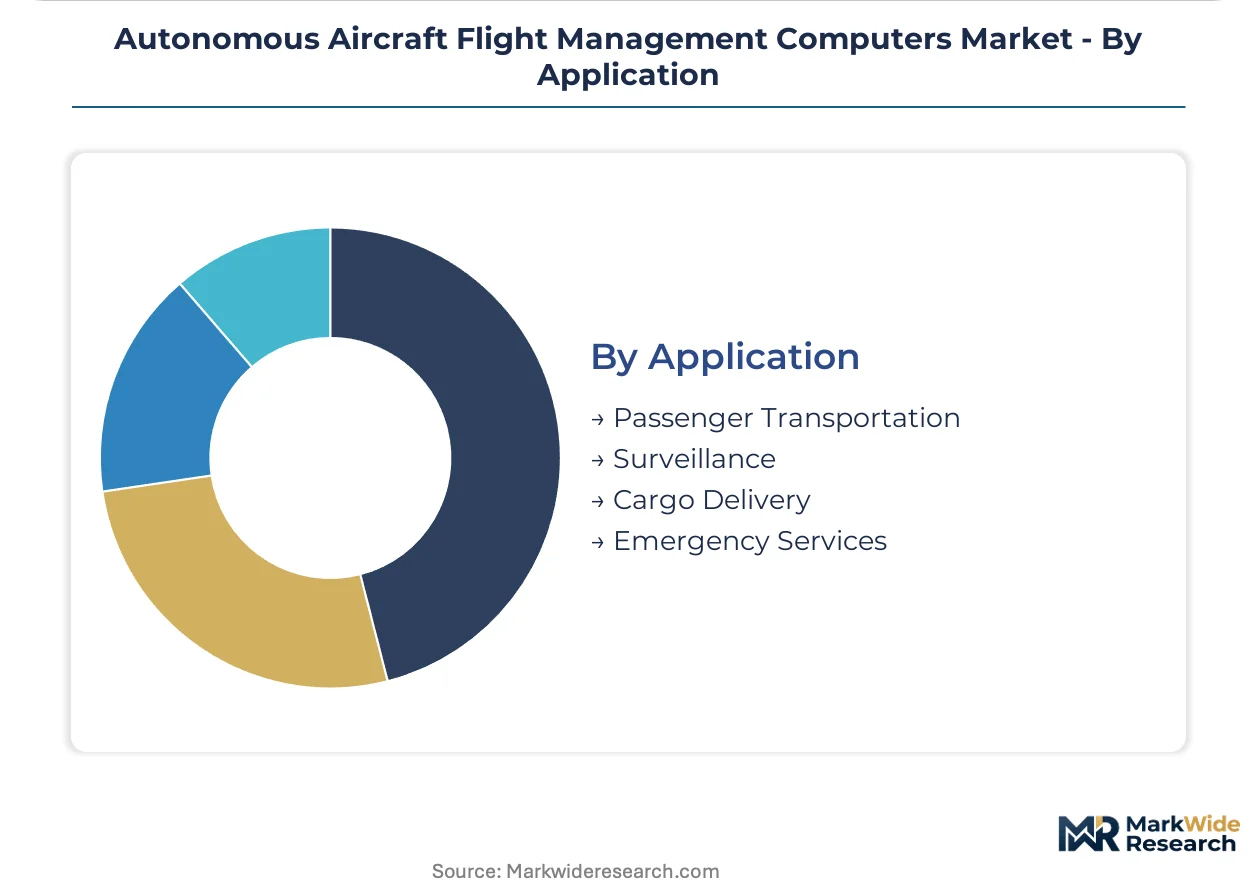
Application:
Mission profiles dictate processing redundancy and certification rigor, with passenger safety requirements imposing stricter assurance standards than unmanned operations.
- Surveillance:Persistent observation platforms require fault-tolerant navigation with degraded-mode operation in GPS-denied environments. NATO procurement across member states concentrates demand in this application for border monitoring and intelligence collection.
- Cargo Delivery:Autonomous freight corridors operate under reduced criticality with remote pilot oversight fallback. United States logistics networks evaluate these routes for structural expansion into unmanned aerial distribution.
- Passenger Transportation:Urban air mobility and autonomous commercial flight demand DO-178C Level A certification with triple-modular redundancy. FAA and EASA equivalent safety demonstrations impose the longest development timelines.
- Emergency Services:Search-and-rescue and medical evacuation platforms balance autonomy with human override capability. These applications attract procurement from public safety agencies with specialized mission requirements.
Surveillance applications hold the established revenue base. Cargo Delivery is gaining share fastest as beyond-visual-line-of-sight regulatory frameworks stabilize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows concentrate among defense-technology clusters in California and Texas, while Eastern European NATO members and Asia-Pacific logistics hubs drive import demand for certifiable autonomous flight systems.
United States
Defense agencies fund neural network verification for safety-critical flight control, expanding procurement of hardened avionics processors. The FAA's Part 89 remote identification rule and detect-and-avoid mandates accelerate certification requirements for onboard computing platforms. Palmdale, California and Austin-San Antonio corridor in Texas concentrate classified program execution and specialized testing infrastructure.
Germany
EASA's special condition for light unmanned aircraft systems shapes hardware architecture requirements for transatlantic market access. The country's national aerospace regulator enforces equivalent safety demonstrations that diverge from FAA technical standards. Bavaria and Baden-Württemberg host integrated airframe manufacturers specifying early certification commitment during platform development.
United Kingdom
BAE Systems Plc anchors domestic defense procurement for autonomous surveillance missions, generating demand for fault-tolerant navigation systems. The national aviation authority implements parallel certification tracks with EASA-aligned standards. Greater London and South West England concentrate airworthiness certification resources and systems integration expertise.
Israel
Elbit Systems Ltd. positions autonomous computing suites for export markets across Eastern Europe and Asia-Pacific, leveraging captive R&D capabilities. The country's defense procurement agency negotiates performance-based logistics contracts transferring operational risk to manufacturers. Tel Aviv and Haifa metropolitan areas concentrate neural network verification research for contested electromagnetic environments.
China
NMPA and MIIT coordinate GB standards for civil unmanned aviation, creating a separate compliance track for suppliers accessing Chinese airspace. The national medical products administration and ministry of industry and information technology impose distinct hardware assurance requirements. Yangtze River Delta and Pearl River Delta clusters develop domestic alternatives to radiation-hardened processor supply chains.
Autonomous Aircraft Flight Management Computers Market Vendor Landscape
On the supply side, the industry is consolidating around defense primes with captive airworthiness certification resources and tiered specialist suppliers serving export markets. Prime contractors sustain extensive backward integration from hardware design through certification, while mid-tier players concentrate on modular architectures enabling geographic market flexibility. Three archetypes dominate: vertically integrated defense primes, regional export specialists, and emerging cargo-platform suppliers. Competitive moves center on strategic partnerships for multi-authority certification and technology licensing for neural network verification.
Among defense-integrated primes, Boeing and Lockheed Martin Corporation exemplify the captive R&D model with facilities in California defense clusters, while Elbit Systems Ltd. represents the export-specialist archetype targeting Eastern European and Asia-Pacific procurement. These three companies occupy distinct competitive positions based on customer relationship structures—availability-guarantee contracting for domestic defense programs versus volume hardware sales for allied nation surveillance missions.
| Leading Market Players |
|---|
| Textron Inc. |
| Northrop Grumman Corporation |
| Saab AB |
| Boeing |
| Aeronautics Ltd. |
| Elbit Systems Ltd. |
| Airbus S.A.S |
| BAE Systems Plc |
| Lockheed Martin Corporation |
| Others |
Supply Flow & Price Mechanics
Undercapacity in radiation-hardened processor foundries is compressing lead times and amplifying pricing power for qualified suppliers serving defense-grade flight management systems. This supply tightness cascades into tiered procurement postures where sole-source contractors absorb cost premiums while commercial cargo platforms face extended delivery schedules.
Pricing Analysis
Technology-generation pricing gaps separate field-proven DO-178C Level A systems from emerging AI-native architectures and legacy GPS-only processors. Three-tier pricing structure across hardened military, certified commercial, and developmental cargo levels reflects certification burden and volume scale. Cost compression in developmental cargo tiers is intensifying because logistics providers prioritize unit economics over fault-tolerance redundancy. Defense contractors exhibit the lowest price sensitivity due to availability-guarantee contracting structures.
Supply Chain Analysis
Export-control regimes under ITAR and EAR restrictions limit radiation-hardened processor flows to qualified defense programs, constraining supplier pools. Manufacturing concentrates in the United States, Israel, and select European Union member states with captive foundry capabilities. Supply chains draw from custom silicon, temperature-extreme packaging substrates, and specialized verification labor pools. Single-source vulnerability in qualified foundry capacity represents the dominant structural risk. Distribution runs through prime contractor procurement offices and defense agency logistics channels with multi-year offtake structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense procurement cycles are recovering from pandemic-era program delays, with neural network verification funding restoring R&D velocity across autonomous flight programs.
For Market Incumbents: Build certification moats through captive airworthiness resources that parallel-track FAA and EASA compliance without redundant redesign. Deepen backward integration into radiation-hardened processor supply by securing long-term foundry allocation agreements. Defend against modular-architecture entrants by embedding proprietary sensor fusion IP into integrated compute stacks. For New Entrants and Emerging Players: Build out white-space positions in cargo-platform processors with deferred certification support structures that undercut prime contractor pricing. Eastern European NATO procurement for unmanned surveillance missions offers the most penetrable geographic entry point. Partner with logistics providers on pilot programs that demonstrate beyond-visual-line-of-sight freight economics without full DO-178C commitment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among suppliers with performance-based logistics contracts tied to mission-capable rates rather than unit delivery. Long-term viability favors acquisition targets with modular certification stacks enabling geographic optionality. Watch neural network verification milestones as the inflection signal for AI-native architecture adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Authority Certification Investment | Parallel FAA and EASA tracks unlock transatlantic procurement without hardware redesign. |
| Neural Network Verification Partnership | Defense agency funding for safety-critical AI expands addressable hardware requirements. |
| Captive Foundry Allocation Agreement | Long-term supply commitments mitigate single-source vulnerability in radiation-hardened silicon. |
| Performance-Based Logistics Contracting | Availability-guarantee structures transfer operational risk and deepen customer retention. |
| Cargo Platform Pilot Program | Beyond-visual-line-of-sight freight validation accelerates regulatory acceptance for reduced-criticality systems. |
Methodological Framework
A spread of perspectives from flight management computer engineering leads, defense procurement officers, airworthiness certification specialists, and logistics technology directors converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FAA certification databases, EASA special condition filings, defense agency budget justifications, and customs records for radiation-hardened processor trade flows. Bottom-up segment sizing triangulated against top-down defense procurement budget analysis.
Demand-supply balance dynamics across military, commercial, and cargo applications anchored the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, technology architecture, end-user procurement modality, and mission application profile. CAGRs derived from installed base evolution and replacement cycle analysis, with neural network verification funding trajectories and detect-and-avoid mandate implementation timelines as key industry-specific inputs.
Stress conditions across defense budget allocation shifts, foundry capacity constraints, and transatlantic regulatory divergence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding procurement cycle recovery and certification timeline compression. Material shifts in FAA-EASA harmonization progress or export-control regime expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Avionics
Aircraft Computers Market
Avionics
Europe Commercial Aircraft in-Flight Entertainment System Market
Avionics
Display for Avionics Application Market
Avionics
Commercial Electronic Flight Bag Market
Avionics
Global Avionics Market
Avionics
Customized Avionic Systems Market
Avionics
Asia-Pacific Aircraft Health Monitoring System Market
Avionics
Commercial Aircraft Avionics Systems Market
Avionics
Temperature Sensor in the Aerospace & Defense Market
Avionics
Asia-Pacific Semiconductor in Military and Aerospace Market
Avionics
Global Helicopter Avionics Market
Avionics
Electronic Flight Instrument System Market
Avionics
Europe Aircraft Avionics Market
Avionics
Military Aircraft Avionics Market
Avionics
Military Avionic Systems Market
Avionics
Europe Military Aircraft Communication Avionics Market