
 Aircraft Aerostructures Market | 2026-2036
Aircraft Aerostructures Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Aerostructures Market Insights
Aerospace composite technician shortages across North America and Western Europe is reorganizing supplier geography, pushing tier-one manufacturers to retrain metallurgy workforces for carbon fiber layup and autoclave curing. Spirit AeroSystems sustains the largest independent aerostructures footprint in Wichita, Kansas, dominating fuselage production for narrowbody programs. Safran specializes in nacelle and thrust reverser systems, leveraging its vertically integrated composite manufacturing in Morocco and Mexico to control cost structures on next-generation engine programs.
Aircraft aerostructures encompass the primary load-bearing airframe components—fuselage barrels, wing boxes, empennage assemblies, and engine nacelles—fabricated from aluminum-lithium alloys, titanium forgings, or carbon fiber reinforced polymer laminates cured under temperature and pressure cycles exceeding 350°F and 100 psi. These structures must withstand limit loads of 3.75g for transport category aircraft per FAA Part 25 certification criteria. Composite materials now lead technology investment as Boeing and Airbus push 50%+ CFRP content on new programs, while aluminum alloys retain cost advantages in regional aircraft where production volumes cannot amortize autoclave capital. Honeycomb structures concentrate in empennage and control surfaces where stiffness-to-weight ratios determine fuel burn performance.
FAA Part 25 airworthiness standards and EASA CS-25 certification requirements govern damage tolerance and fatigue life for all transport category aerostructures, forcing manufacturers to maintain extensive test article fleets for full-scale structural validation. The EU Green Deal's aviation decarbonization targets are pressuring OEMs to source thermoplastic composites with shorter cycle times and full recyclability pathways. Stakeholders must monitor how emerging thermoplastic welding techniques displace traditional fastening methods in wing assembly, as this technology shift threatens established fastener supply chains while promising 30% production cycle reductions.
Market Dynamics
Composite material transition is restructuring capital allocation across the aerostructures supply base, forcing aluminum-dependent suppliers to retool for autoclave-based CFRP curing while OEMs consolidate qualified supplier lists around thermoplastic welding capabilities.
Growth Catalysts
- FAA Part 25 damage tolerance mandates:Certification requirements for fatigue-resistant airframe designs are accelerating adoption of carbon fiber laminates in wing box and empennage assemblies.
- Commercial fleet renewal cycles:Narrowbody replacement demand from North American and European carriers is sustaining production rates for composite-intensive fuselage programs.
- Aluminum-lithium alloy advances:Third-generation Al-Li extrusions are preserving metal's relevance in regional aircraft where production volumes cannot justify autoclave capital deployment.
Market Restraints
- Titanium forging supply concentration:Russian and Chinese dominance in sponge and mill product supply creates input cost volatility for landing gear and engine pylon manufacturers.
- Autoclave capital intensity:Pressure vessel investments exceeding $50 million per unit limit supplier entry and lock in geographic production clusters.
- Adhesive bonding qualification timelines:FAA and EASA certification protocols for primary structural joints extend development cycles by 18-24 months versus mechanical fastening.
Strategic Opportunities
- Thermoplastic composite welding:Induction and ultrasonic joining techniques are eliminating fastener counts in wing assembly, compressing production cycles and enabling in-situ repair protocols.
- Morocco-Mexico manufacturing corridors:Labor cost arbitrage and free trade access are attracting nacelle and thrust reverser production for next-generation engine programs.
- EU Green Deal aviation decarbonization targets:Recyclability mandates for end-of-life airframes are favoring thermoplastic matrices over thermoset epoxies in new program sourcing decisions.
Industry Challenges
- Aerospace composite technician scarcity:North American and Western European workforce gaps in carbon fiber layup and automated fiber placement are constraining output expansion at tier-one suppliers.
- Full-scale structural test article requirements:FAA Part 25 and EASA CS-25 certification protocols demand multiple airframe specimens for static and fatigue validation, consuming 8-12% of program engineering budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Aerostructures Market |
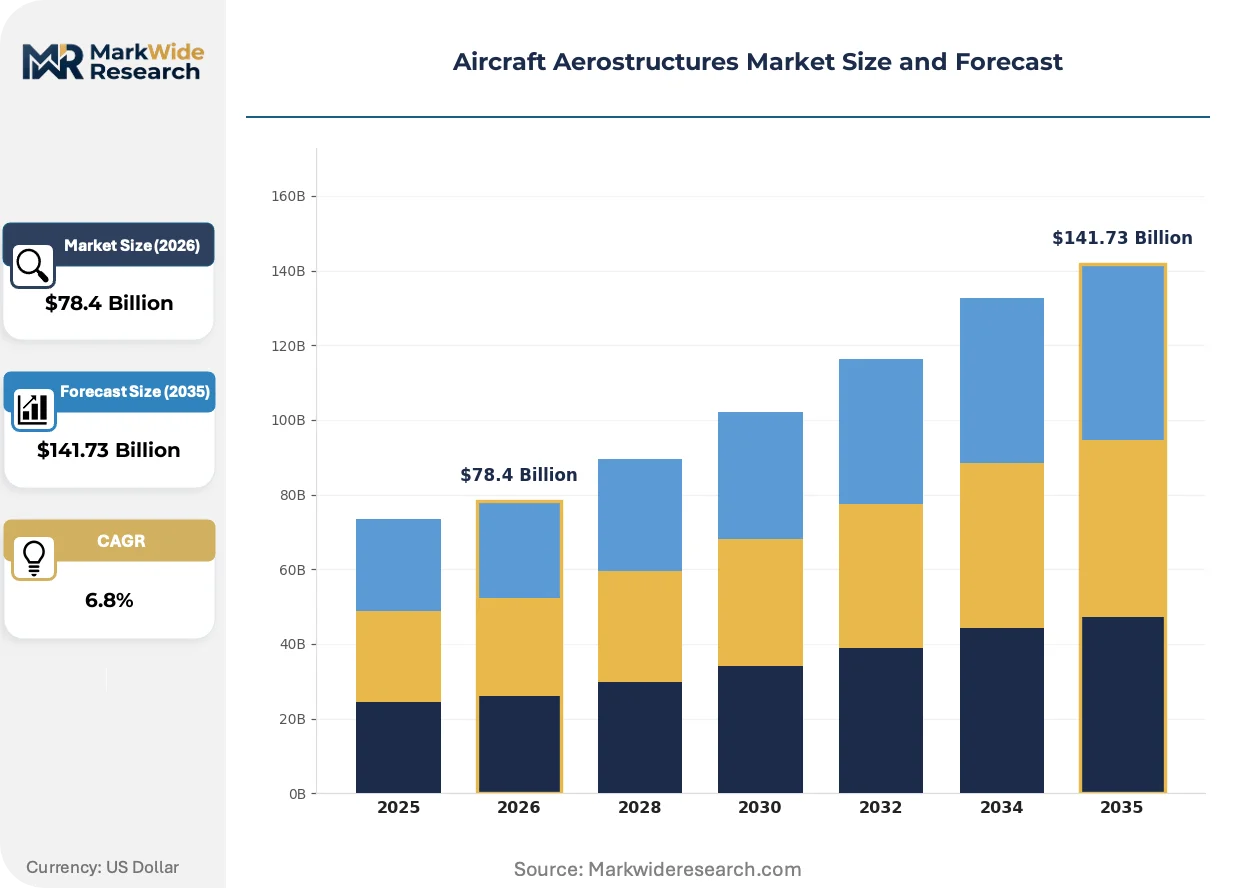
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuselage, Wings, Empennage, Landing Gear, Engine Nacelle Technology: Composite Materials, Aluminum Alloys, Titanium Alloys, Carbon Fiber Reinforced Polymer, Honeycomb Structures Application: Commercial Aviation, Business Jets, Military Aircraft, Regional Aircraft, Unmanned Aerial Vehicles End User: Aircraft Manufacturers, Maintenance Repair Organizations, Aerospace Tier-1 Suppliers, Defense Contractors, OEMs |
| Companies Covered | Lockheed Martin, RTX Corporation, Spirit AeroSystems, Safran, BAE Systems, Boeing, Northrop Grumman, Triumph Group, Airbus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Aerostructures Market Trends and Innovations
Material science breakthroughs and regulatory pressure for lifecycle emissions reduction are converging to transform aerostructures fabrication, compressing traditional process timelines while elevating performance thresholds for damage tolerance and repairability.
Thermoplastic composite welding is supplanting mechanical fastening in wing box assembly, with Boeing and Airbus suppliers adopting induction bonding for stringer-to-skin joints. This shift eliminates 40,000+ fasteners per wing on new programs while enabling automated in-line production. The technology is compressing wing assembly cycle times and threatening established titanium and stainless steel fastener supply chains.
EASA CS-25 damage tolerance amendments and FAA airworthiness directives are tightening fatigue life demonstration requirements for transport category aircraft, forcing manufacturers to expand non-destructive inspection protocols and digital twin monitoring capabilities. European OEMs face additional pressure from EU Green Deal recyclability mandates that favor thermoplastic matrices. Suppliers are responding by qualifying PEEK and PPS-based laminates for primary structure applications previously reserved for thermosets.
Airline procurement teams are consolidating aerostructures sourcing through long-term exclusive supplier agreements tied to fleet renewal commitments, displacing spot purchasing and multi-source strategies. This concentration shifts negotiation leverage toward OEMs and tier-one integrators. The pattern is most visible in North American narrowbody programs where single-source fuselage contracts now span 15-20 year horizons.
Aircraft Aerostructures Market Segmentation
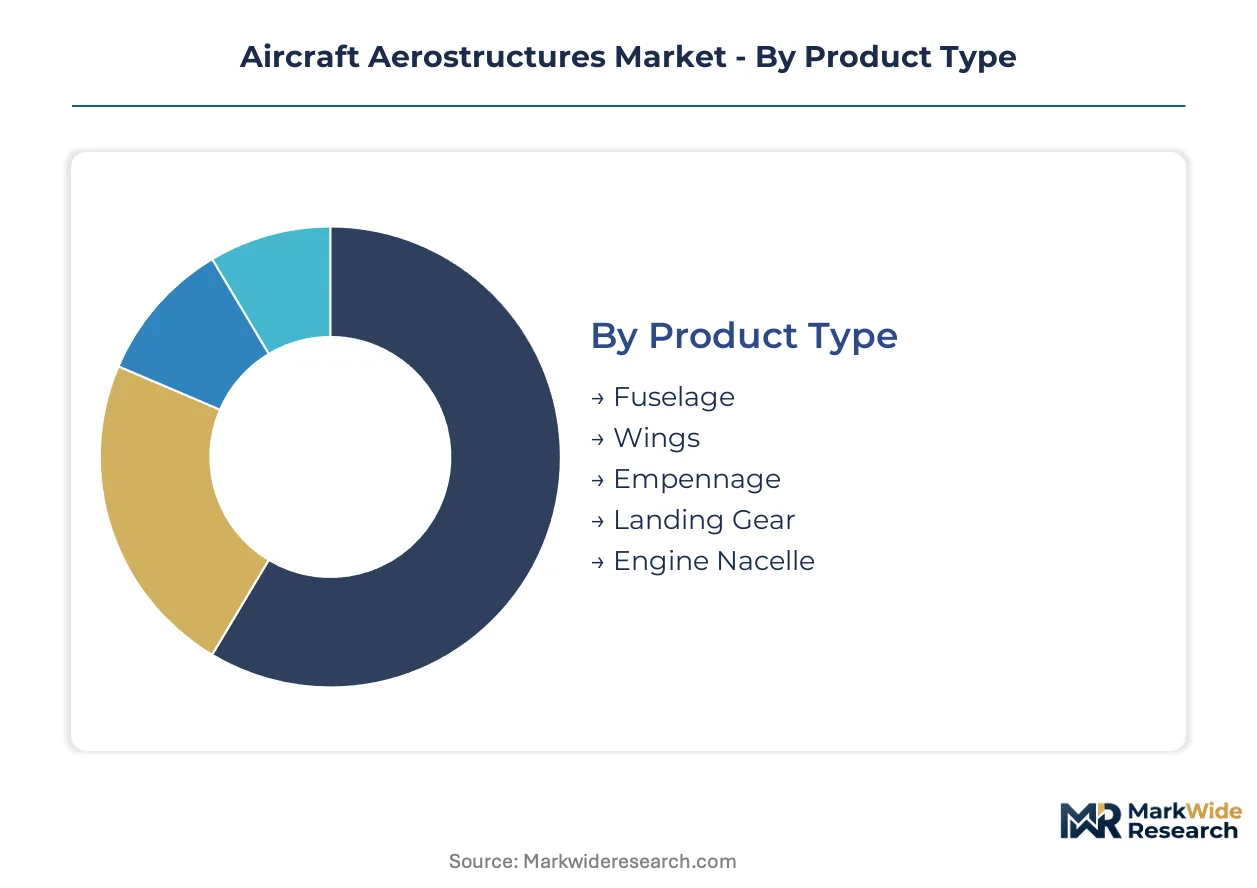
Aerostructures procurement channels vary sharply by segment—fuselage and wing assemblies flow through long-term OEM contracts, while landing gear and nacelle components split between original equipment and aftermarket MRO channels. Understanding these channel dynamics illuminates where pricing power concentrates and where supplier margins face compression.
Product Type:
Fuselage and wing assemblies move through exclusive multi-year supply agreements with Boeing and Airbus, while empennage and nacelle components sustain more fragmented procurement patterns across engine OEMs and tier-one integrators.
- Fuselage:Cylindrical pressure-bearing barrels fabricated from aluminum-lithium alloys or CFRP laminates, integrating floor beams, frames, and skin panels. Demand clusters at Spirit AeroSystems' Wichita facilities for narrowbody programs, where Boeing 737 and Airbus A320 family rates dictate capacity allocation.
- Wings:Multi-spar box structures with stringer-stiffened skins, increasingly adopting thermoplastic composite welding to eliminate mechanical fasteners. Airbus wing production at Broughton, UK and Boeing's composite wing center in Everett, Washington anchor geographic supply concentration for widebody platforms.
- Empennage:Horizontal and vertical stabilizer assemblies where stiffness-to-weight ratios drive honeycomb sandwich construction. Regional aircraft programs in Brazil and Canada sustain aluminum-intensive tailcone production.
- Landing Gear:High-strength titanium and steel forgings for shock absorption and load transfer, subject to Russian and Chinese sponge supply volatility. Safran and Collins Aerospace dominate integrated strut and brake system sourcing.
- Engine Nacelle:Thrust reverser and inlet lip assemblies requiring fire-resistant composite matrices and acoustic lining integration. Morocco-Mexico manufacturing corridors capture cost-sensitive production for next-generation engine programs.
Fuselage dominates installed base by structural mass and program value. Engine nacelle is where expansion concentrates as propulsion efficiency upgrades drive replacement demand.
Technology:
Cost tier segmentation separates autoclave-dependent CFRP curing—capital intensive and qualification-heavy—from aluminum alloy stamping accessible to lower-volume regional aircraft suppliers.
- Composite Materials:Glass and carbon fiber systems with thermoset epoxy or thermoplastic matrices, requiring temperature-pressure curing cycles exceeding 350°F. Boeing 787 and Airbus A350 programs push CFRP content above 50% of airframe mass, concentrating demand at tier-one suppliers with qualified autoclave capacity.
- Aluminum Alloys:Third-generation aluminum-lithium extrusions and sheets preserving metal's cost position in single-aisle and regional platforms. Embraer E-Jet and ATR programs sustain demand where production volumes cannot amortize composite capital deployment.
- Titanium Alloys:High-temperature forgings for engine pylons, landing gear, and fastener applications, vulnerable to sponge supply concentration in Russia and China. Mill product lead times now extend 18-24 months for aerospace-grade stock.
- Carbon Fiber Reinforced Polymer:Unidirectional tape and fabric laminates with automated fiber placement or hand layup processing. Toray, Hexcel, and Solvay control precursor and prepreg supply chains for primary structure qualification.
- Honeycomb Structures:Nomex or aluminum core sandwich panels for control surfaces, fairings, and interior monuments where specific stiffness requirements dominate. Empennage and flap production lines at GKN and FACC anchor European supply.
Aluminum alloys dominate installed base across in-service narrowbody fleets. Thermoplastic composites are climbing the fastest as EU Green Deal recyclability mandates reshape new program sourcing.
Application:
Volume concentration separates high-rate commercial aviation production—where learning curves and scale economies determine supplier viability—from low-rate military and business jet programs prioritizing performance over unit cost.
- Commercial Aviation:Narrowbody and widebody transport aircraft with FAA Part 25 and EASA CS-25 certification requirements, driving 60-70 unit monthly production rates at final assembly. Fleet renewal cycles in the United States and France sustain composite fuselage and wing demand.
- Business Jets:Part 25-certified corporate aircraft with customized interiors and shorter production runs, favoring aluminum structures for cost flexibility. Gulfstream and Dassault programs at Savannah and Bordeaux-Mérignac anchor geographic demand.
- Military Aircraft:Fighter, transport, and tanker platforms with damage tolerance specifications exceeding civil requirements. Lockheed Martin F-35 production at Fort Worth, Texas concentrates titanium and composite demand for stealth-optimized structures.
- Regional Aircraft:Turboprop and regional jet platforms below 100 seats, where aluminum-lithium alloys retain economic advantage. ATR and Embraer procurement patterns favor metal-centric supply chains with lower capital barriers.
- Unmanned Aerial Vehicles:Military and commercial drone platforms with relaxed certification requirements enabling rapid composite prototyping. Northrop Grumman Global Hawk and emerging urban air mobility programs drive specialized demand for lightweight sandwich structures.
Commercial aviation dominates installed base by airframe count and structural mass. Unmanned aerial vehicles are gaining share fastest as defense procurement and logistics applications expand platform diversity.
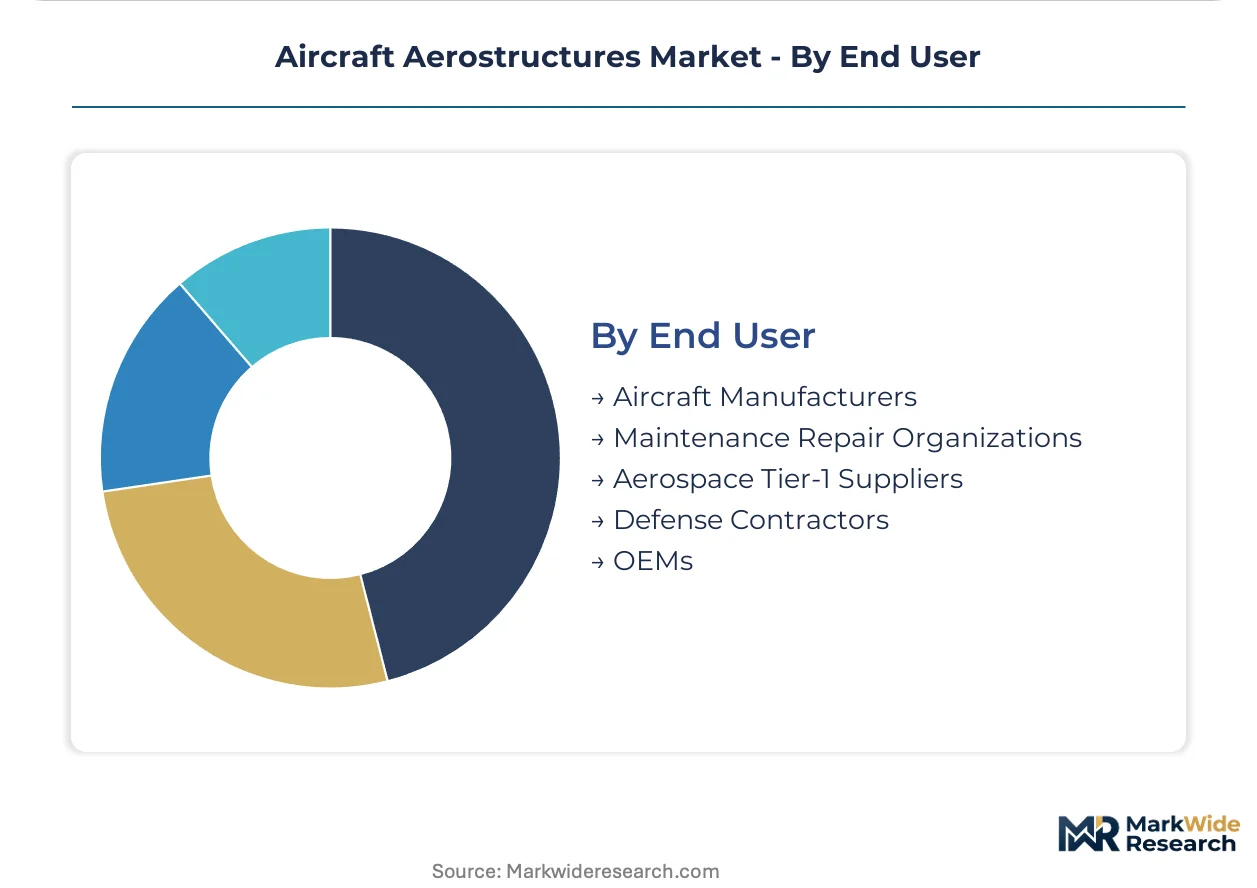
End User:
Customer type determines contract structure—aircraft OEMs impose long-term exclusive agreements, while MRO channels sustain spot purchasing and competitive bidding for replacement components.
- Aircraft Manufacturers:Boeing, Airbus, Embraer, and Bombardier final assembly operations with integrated supply chain management and supplier qualification authority. These OEMs consolidate qualified supplier lists around thermoplastic welding and damage tolerance demonstration capabilities.
- Maintenance Repair Organizations:Lufthansa Technik, ST Engineering, and AAR Corp operations performing heavy checks, structural repairs, and component overhauls on in-service fleets. MRO demand concentrates on fastener-intensive repairs and bonded patch applications.
- Aerospace Tier-1 Suppliers:Spirit AeroSystems, GKN Aerospace, and Leonardo integrated structures divisions supplying major assemblies to OEM final assembly lines. These suppliers face workforce scarcity in carbon fiber layup and automated fiber placement across Wichita, Bristol, and Turin.
- Defense Contractors:Lockheed Martin, Northrop Grumman, and BAE Systems platforms with military-specific survivability and signature requirements. Classified programs sustain specialized titanium and composite forging demand outside commercial pricing benchmarks.
- OEMs:Engine manufacturers and system integrators with captive aerostructures production for nacelles, thrust reversers, and pylons. GE Aviation and Rolls-Royce vertical integration into composite nacelle manufacturing threatens independent supplier margins.
Aircraft manufacturers dominate installed base through design authority and qualification control. Maintenance repair organizations are where expansion concentrates as global fleet age drives heavy check volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. The United States deploys aerostructures primarily for narrowbody fleet renewal, while France concentrates on widebody composite platforms and Morocco-Mexico corridors capture cost-sensitive nacelle assembly.
United States
Boeing 737 MAX production rates and F-35 military demand anchor structural consumption. FAA Part 25 damage tolerance mandates accelerate carbon fiber adoption in wing boxes. Wichita, Kansas hosts Spirit AeroSystems' fuselage operations, where narrowbody barrel production dominates North American capacity allocation.
France
Airbus A350 and A320 family programs sustain composite-intensive demand across the Toulouse-Bordeaux corridor. EASA CS-25 certification standards and EU Green Deal recyclability targets favor thermoplastic matrix development. Nantes and Saint-Nazaire concentrate Safran's nacelle and thrust reverser manufacturing for next-generation engine programs.
United Kingdom
Airbus wing production at Broughton and GKN Aerospace's empennage facilities sustain composite demand despite Brexit-related supply chain adjustments. UK Export Finance guarantees and EASA alignment protocols preserve qualification continuity. Bristol and Portsmouth anchor specialized aerostructures testing and digital twin development capabilities.
Morocco
Safran's vertically integrated composite manufacturing exploits labor cost arbitrage and EU association agreement tariff access. Moroccan Investment Development Agency incentives attract nacelle assembly for LEAP and PW1000G engine programs. Casablanca and Nouaceur free zones concentrate thrust reverser production serving European final assembly lines.
Germany
Airbus Hamburg fuselage sections and Premium AEROTEC composite components sustain structural demand amid energy cost pressures. German KfW export credit facilities and Luftfahrt-Bundesamt certification protocols preserve supplier competitiveness. Augsburg and Nordenham anchor aluminum-lithium machining and titanium forging supply for regional aircraft programs.
Aircraft Aerostructures Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with OEM captive production competing against independent fabricators. Boeing and Airbus maintain design authority and qualification control over tier-one suppliers, while Spirit AeroSystems and Safran occupy intermediate positions as system integrators. Two strategic archetypes dominate: vertically integrated OEMs with captive aerostructures divisions, and independent specialists competing on cost and manufacturing scale. Consolidation through long-term exclusive supply agreements and geographic expansion into Morocco-Mexico corridors represent the dominant competitive vectors reshaping supplier positioning.
Among defense-anchored conglomerates, Lockheed Martin and Northrop Grumman exemplify the captive-production archetype, with classified military programs sustaining specialized titanium and composite demand outside commercial pricing benchmarks. Spirit AeroSystems occupies a distinctive position as the largest independent aerostructures fabricator, while Safran represents the European integrated model with nacelle specialization and North African manufacturing footprint.
| Leading Market Players |
|---|
| Lockheed Martin |
| RTX Corporation |
| Spirit AeroSystems |
| Safran |
| BAE Systems |
| Boeing |
| Northrop Grumman |
| Triumph Group |
| Airbus |
| Others |
Pricing and Supply Chain Analysis
Thermoplastic composite welding displacing mechanical fastening in wing assembly is redrawing supplier geography while compressing pricing premiums for titanium fastener manufacturers. Boeing and Airbus suppliers adopting induction bonding eliminate forty thousand fasteners per wing, forcing legacy fastener producers to absorb volume declines or pivot toward in-situ repair service contracts.
Pricing Analysis
Long-term exclusive supply agreements dominate commercial aviation procurement, with Boeing and Airbus locking tier-one suppliers into fifteen-to-twenty-year fuselage contracts tied to fleet renewal commitments. Price differentiation hinges on damage tolerance certification tier and autoclave capacity scale, with FAA Part 25-qualified suppliers commanding premiums over regional aircraft metal fabricators. Cost compression in narrowbody programs is intensifying because OEMs consolidate qualified supplier lists around thermoplastic welding capabilities. Aftermarket MRO channels exhibit highest price sensitivity, while defense contractors with classified programs show lowest sensitivity due to performance specifications exceeding commercial benchmarks.
Supply Chain Analysis
Inventory lead times for aerospace-grade titanium mill products now extend eighteen-to-twenty-four months, constraining landing gear and engine pylon manufacturers. Supply concentrates in the United States, France, and Morocco, with Wichita fuselage operations, Toulouse composite centers, and Safran's Casablanca facilities anchoring geographic production clusters. Raw material dependencies draw from Russian and Chinese sponge suppliers, Toray-Hexcel-Solvay prepreg oligopolies, and aluminum-lithium alloy producers. Single-source vulnerability in titanium forging feedstock creates input cost volatility. Distribution runs through OEM-integrated tier-one suppliers with direct line-feed to final assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoplastic welding interoperability standards are creating platform-economics inflection points, with Boeing and Airbus supplier qualification protocols acting as ecosystem gatekeepers that determine which fabrication technologies achieve production scale.
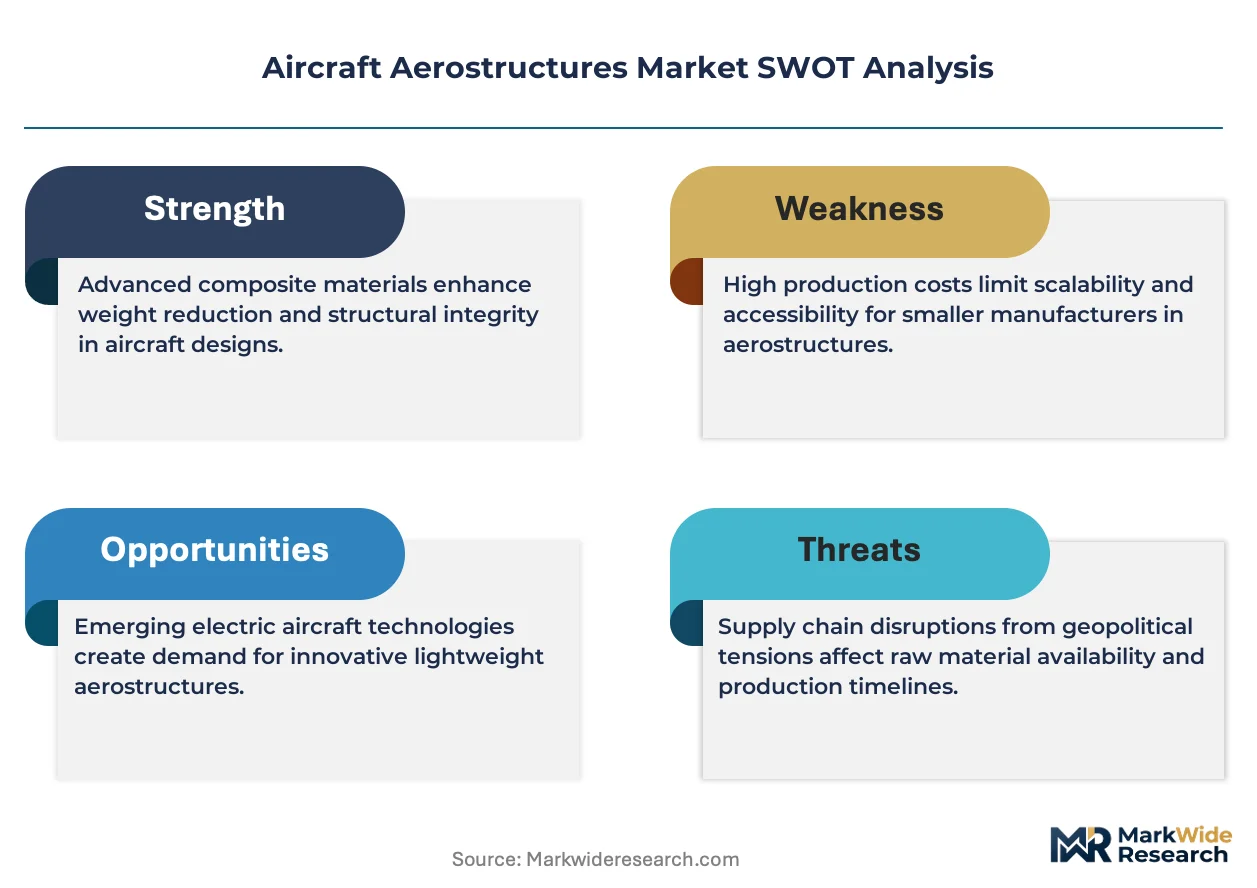
For Market Incumbents: Compound damage tolerance certification advantages by qualifying PEEK and PPS-based laminates for primary structure applications before thermoset epoxy lock-in hardens. Expand autoclave capacity in Morocco-Mexico corridors to capture labor cost arbitrage on nacelle programs. Threat: emerging thermoplastic welding specialists with induction bonding IP threaten established fastener supply chain positions. Lever: vertical integration into automated fiber placement equipment to offset aerospace composite technician scarcity. For New Entrants and Emerging Players: Anchor in unmanned aerial vehicle structural prototyping, where relaxed certification requirements enable rapid composite sandwich development without FAA Part 25 qualification timelines. White-space targets include urban air mobility platforms and defense drone programs requiring lightweight honeycomb structures. Most penetrable segment: UAV empennage and control surface fabrication. Go-to-market angle: direct OEM partnerships bypassing tier-one integrator margin extraction. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with qualified thermoplastic welding capabilities and existing Boeing or Airbus supplier status, as these assets command scarcity premiums during fleet renewal cycles. Long-term viability favors suppliers with backward integration into prepreg manufacturing or captive North African production footprints. Signal to watch: EASA CS-25 amendments mandating recyclability demonstration for new program certification.| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Welding Qualification | Induction bonding certification with Boeing or Airbus unlocks wing assembly exclusivity and fastener displacement. |
| Morocco-Mexico Manufacturing Footprint | Safran's Casablanca-Nouaceur operations demonstrate labor arbitrage capture for nacelle cost structures. |
| Automated Fiber Placement Investment | Spirit AeroSystems' Wichita deployment addresses carbon fiber layup technician gaps constraining output expansion. |
| Titanium Sponge Supply Diversification | Reducing Russian and Chinese feedstock dependence stabilizes landing gear forging input costs. |
| EU Green Deal Recyclability Compliance | Thermoplastic matrix qualification preserves European supplier access under end-of-life airframe mandates. |
Research Methodology
Cross-validation between primary interviews with aerostructures procurement executives, composite manufacturing engineers, and FAA certification specialists and secondary validation through EASA CS-25 amendment filings, FAA airworthiness directives, and OEM supplier qualification databases anchors the qualitative findings. Bottom-up triangulation aggregates program-level production rates and content-per-aircraft assumptions, while top-down verification cross-checks against customs trade data and aerospace trade association capacity surveys.
Sensitivity analysis across composite adoption scenarios, titanium price volatility bands, and fleet renewal timing variations shapes the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, material technology, application platform, and end-user channel. CAGRs derive from structural mass evolution per aircraft generation and replacement cycle phasing. Industry-specific forecast inputs incorporate Boeing and Airbus announced production rate adjustments and LEAP engine delivery schedules.
Material uncertainties — FAA Part 25 rulemaking on adhesive bonding, EU Green Deal implementation timelines for recyclability mandates, and titanium sponge supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions about thermoplastic welding adoption curves and qualified supplier list consolidation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Supersonic Jet Market
Aircraft
Aeronautical Wind Tunnel Market
Aircraft
Middle-East Aviation Market
Aircraft
Europe Business Jet Market
Aircraft
Asia-Pacific Turboprop Aircraft Market
Aircraft
Middle-East and Africa Business Jet Market
Aircraft
Asia-Pacific Heavy-Lift Helicopter Market
Aircraft
Military Helicopters Market
Aircraft
North America Helicopters Market
Aircraft
Japan Aviation Market
Aircraft
Aircraft Nacelle Systems Market
Aircraft
Global Ultralight and Light Aircraft Market
Aircraft
Medium and Heavy-Lift Helicopters Market
Aircraft
Europe Freighter Aircraft Market
Aircraft
Asia-Pacific Business Jet Market
Aircraft
Asia-Pacific Attack Helicopter Market