
 Water Bomber Market | 2026-2036
Water Bomber Market Size, Share, and Industry Trends Forecast 2026-2036
Water Bomber Market Insights
Premium integrated drop systems is decoupling from retrofit tank kits on older airframes. Coulson Aviation leverages vertical integration across modification, operations, and crew training to capture full-service contracts. De Havilland Aircraft of Canada anchors its position through proprietary manufacturing of purpose-built air tanker platforms. AVIC competes on scale with the AG600 Kunlong program, the largest amphibious aircraft in serial production.
Water bombers are fixed-wing or rotary-wing aircraft engineered to carry and discharge fire retardant, foam, or water payloads exceeding 3,000 liters, utilizing gravity-fed or pressurized release mechanisms at low altitudes and reduced airspeeds to suppress wildland fires. Amphibious aircraft and dedicated air tankers dominate procurement budgets due to higher payload capacity and faster turnaround times, while autonomous drop technology represents the fastest-growing segment despite regulatory immaturity. Fire agencies and forestry services constitute the deepest margin pools as multi-year exclusive-use contracts replace call-when-needed arrangements.
The FAA mandates airworthiness standards under Part 25 and Part 27 for modified tanker aircraft, while EASA enforces CS-25 certification with supplemental type certificate requirements for firefighting apparatus. Australia's Civil Aviation Safety Authority imposes operational limitations on firebombing flight envelopes that shape fleet composition decisions. Stakeholders must weigh autonomous system development timelines against the contracting windows of aging CL-415 and P-3 Orion fleets.
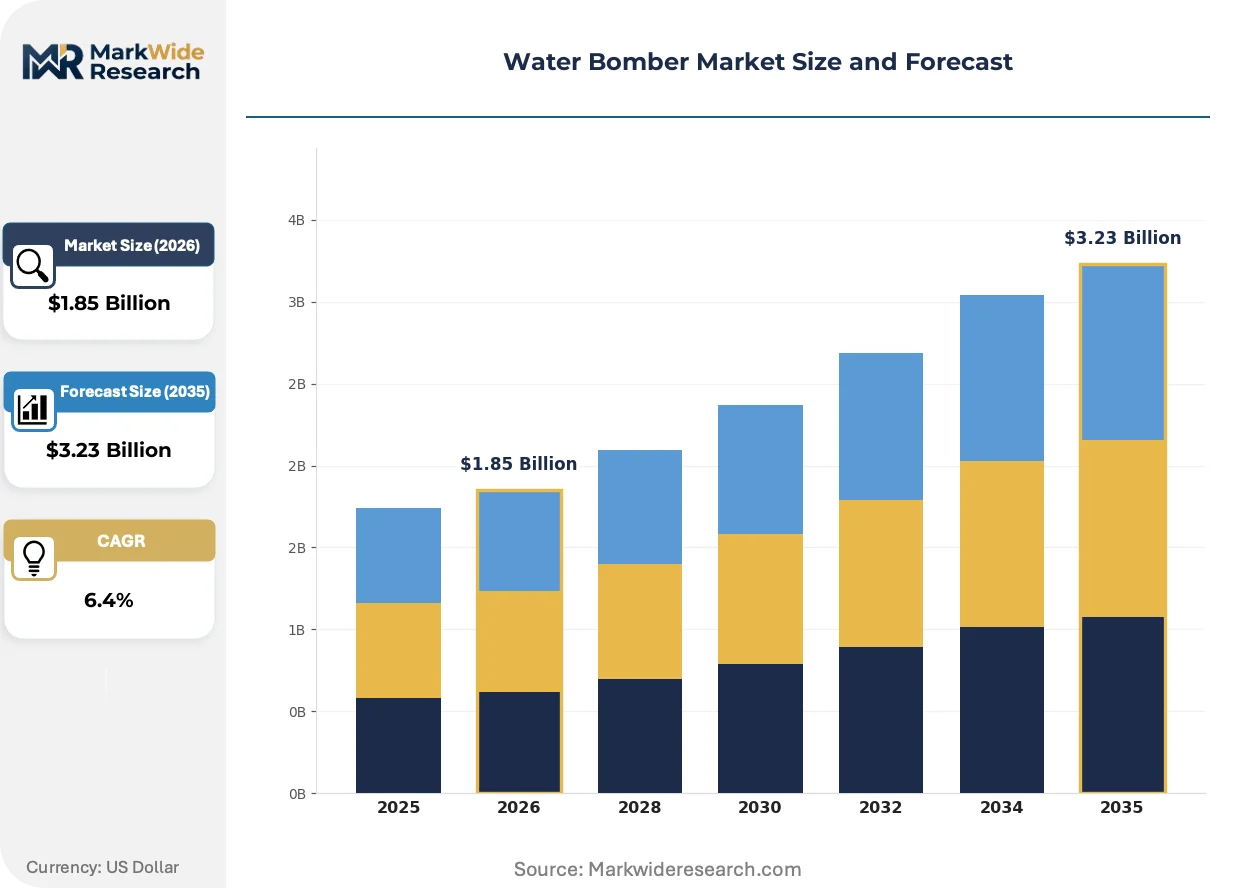
Market Dynamics
Fleet obsolescence across North American and European fire agencies is forcing accelerated replacement cycles for 1970s-era air tanker platforms, reshaping procurement timelines and certification priorities.
Growth Catalysts
- Extended Wildfire Seasons:Provincial forestry services in Canada now contract aircraft for eight-month operational windows, up from five months a decade ago.
- EASA CS-25 Supplemental Type Certificate Streamlining:Harmonized certification pathways for firefighting apparatus modifications are compressing airworthiness approval timelines.
- Pressurized Retardant Delivery Systems:Next-generation drop mechanisms enable precision targeting at higher altitudes, reducing pilot exposure to terrain hazards.
Market Restraints
- Aerospace-Grade Aluminum Supply Concentration:Three smelters control 70% of certified sheet stock for amphibious hull fabrication, creating input bottlenecks.
- Specialized Airframe Engineering Talent Scarcity:Retiring designers from the CL-415 and P-3 Orion programs leave knowledge gaps in structural load calculations for tanker modifications.
- Autonomous Flight Regulatory Immaturity:FAA Part 25 and EASA CS-25 lack defined pathways for certifying unpiloted drop systems, freezing R&D investment.
Strategic Opportunities
- Scooping-Equipped Amphibious Platforms:Freshwater lake access in Scandinavia and the Baltic states remains underutilized versus coastal tanker bases.
- Dual-Use Military Conversion:Surplus tactical transport airframes from defense drawdowns offer lower acquisition costs for firefighting retrofit.
- Integrated Sensor-Drop System Convergence:Combining thermal imaging with automated release algorithms enables nighttime operations previously prohibited.
Industry Challenges
- Type Rating Certification Bottlenecks:Civil aviation authorities in Australia and Canada maintain divergent training hour requirements for firebombing endorsements, fragmenting crew mobility.
- Legacy Fleet Interoperability:Proprietary retardant coupling systems from De Havilland and Viking Air block cross-platform logistics standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Bomber Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seaplane, Helicopter, Amphibious Aircraft, Air Tanker Technology: Retrofit Systems, Integrated Drop Systems, Radio-Controlled, Autonomous Application: Wildfire Suppression, Disaster Response, Agricultural Irrigation, Environmental Protection End User: Fire Agencies, Forestry Services, Emergency Management, Conservation Groups |
| Companies Covered | Coulson Aviation, Roadfour (Seagle), De Havilland Aircraft of Canada, Positive Aviation (FF72), Hynaero (Fregate-F100), AVIC (AG600 Kunlong), Beriev (Be-200), Bridger Aerospace, Avincis Italy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Bomber Market Trends and Innovations
Autonomous systems development and predictive fire behavior modeling are compressing response timelines, while regulatory frameworks struggle to match technological iteration cycles.
Computer-vision-guided drop systems are automating payload release timing based on real-time wind vector analysis and terrain mapping. Fire agencies in Australia and Spain are piloting these platforms for initial attack missions. The technology is automating split-second decision-making previously dependent on veteran pilot judgment, reducing human error in low-visibility conditions.
EASA's tightening CS-25 certification requirements for amphibious aircraft drop-system performance thresholds are mandating redundant hydraulic actuators and fail-safe valve configurations. Manufacturers must now submit extended flight envelope testing data for water-scooping operations. European operators face 18-24 month extension in modification approval timelines, pushing procurement toward factory-new platforms over retrofit.
Multi-year exclusive-use contracts are displacing call-when-needed arrangements as the dominant procurement model. Forestry services in British Columbia and Alberta now require guaranteed aircraft availability with penalty clauses for non-deployment. This shift concentrates revenue with fleet owners who can underwrite year-round crew retention and maintenance standby costs.
Water Bomber Market Segmentation
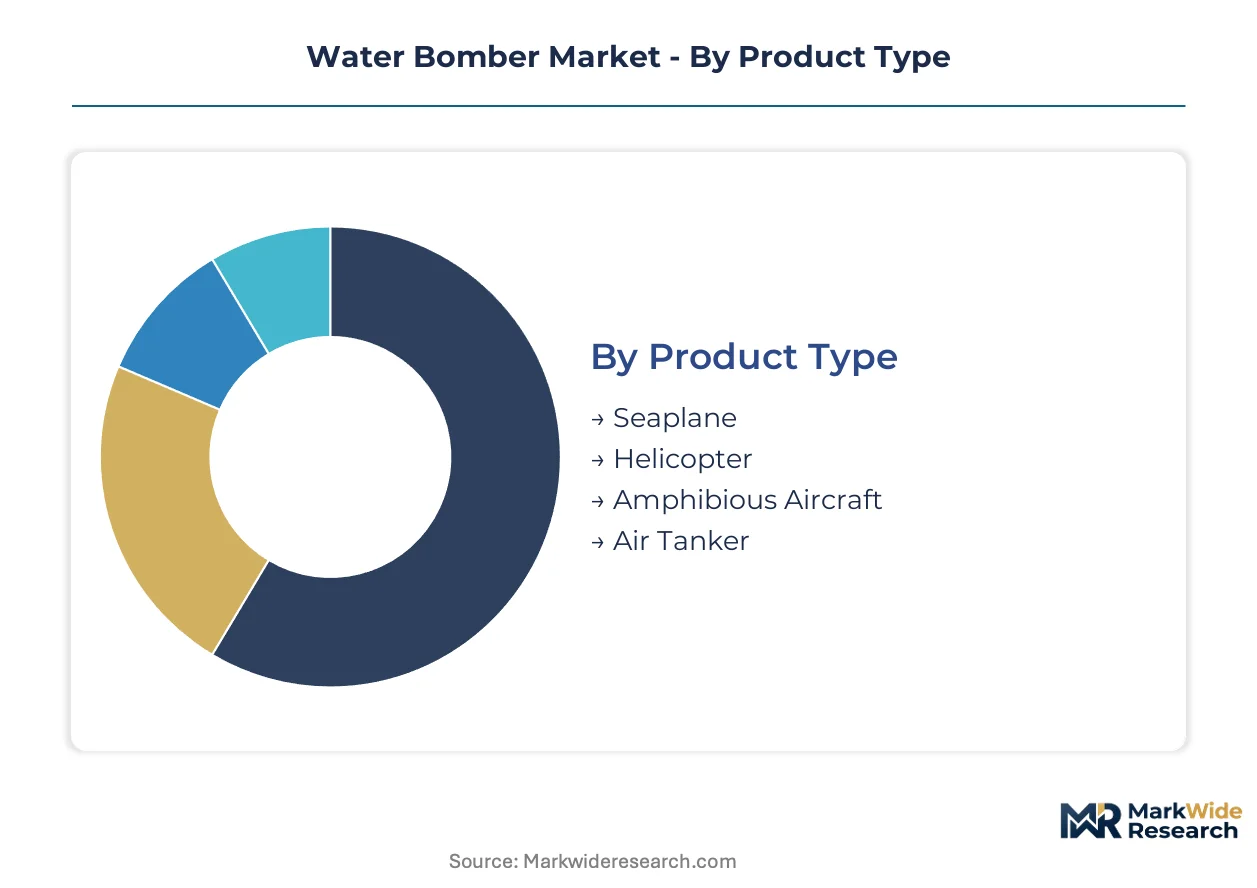
Procurement patterns in water bomber markets diverge sharply between agencies seeking rapid initial attack capability and those prioritizing extended campaign endurance. Platform selection drives operational economics through payload capacity, turnaround speed, and base infrastructure requirements.
Product Type:
Buyers differentiate primarily by water source access and base infrastructure investment thresholds.
- Amphibious Aircraft:These platforms combine wheeled runway operations with freshwater lake scooping capability. Canadian provincial forestry services in British Columbia and Quebec maintain the largest contracted fleets, driven by extended fire seasons requiring eight-month operational windows.
- Air Tanker:Fixed-wing aircraft engineered for high-volume retardant delivery from established air tanker bases. Demand concentrates with fire agencies in Australia and Spain where terrain constraints favor precision drops from higher altitudes.
- Seaplane:Hull-configured aircraft restricted to water landings with limited payload flexibility. Coastal fire agencies in Portugal and Greece deploy these for island protection where runway construction is prohibitive.
- Helicopter:Rotary-wing platforms offering vertical precision in confined terrain. Emergency management units in Italy and Chile favor these for interface fire protection in wildland-urban boundaries.
Air tanker leads volumes today; amphibious aircraft is gaining share fastest.
Technology:
Technology selection tracks regulatory maturity against operational risk tolerance.
- Integrated Drop Systems:Factory-engineered pressurized release mechanisms with redundant hydraulic actuators. EASA CS-25 certification mandates are compressing approval timelines for these systems in European procurement.
- Autonomous:Computer-vision-guided platforms automating payload release through real-time wind vector analysis. Fire agencies in Australia pilot these for nighttime operations previously prohibited by visibility constraints.
- Retrofit Systems:Aftermarket tank installations on surplus military or commercial airframes. Forestry services in Argentina and South Africa favor these for cost-constrained fleet expansion.
- Radio-Controlled:Remotely piloted drop systems with human oversight retained for final release authorization. Experimental programs in Spain and California test these for pilot exposure reduction.
Integrated drop systems dominate current procurement; autonomous platforms show steepest expansion trajectory.
Application:
Application segmentation reflects mission duration and payload specification divergence.
- Wildfire Suppression:Sustained aerial attack on active fire perimeters using retardant, foam, or water payloads. Fire agencies in Canada and Australia represent the deepest contract pools with multi-year exclusive-use arrangements.
- Disaster Response:Rapid deployment for chemical spill containment, flood relief, or structural fire support. Emergency management authorities in Japan and New Zealand maintain standby contracts for all-hazard activation.
- Agricultural Irrigation:Seasonal water dispersal for crop protection and drought mitigation. Conservation groups in Israel and California deploy converted platforms for precision agricultural application.
- Environmental Protection:Wetland restoration, prescribed burn support, and habitat management. Forestry services in Sweden and Finland utilize scooping aircraft for peatland fire prevention.
Wildfire suppression commands the largest contract values; disaster response is expanding most quickly.
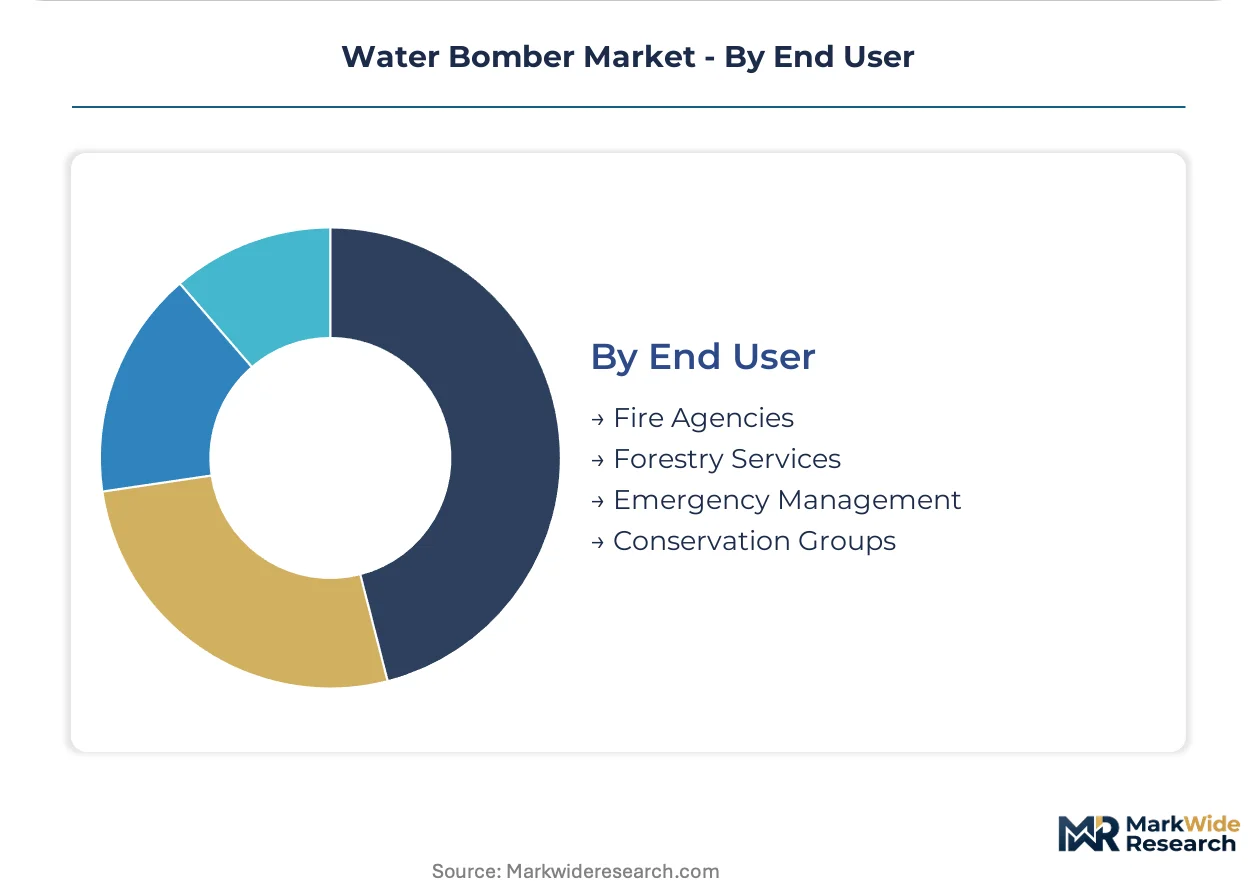
End User:
End user categories separate by funding stability and operational control requirements.
- Fire Agencies:Municipal and regional departments with statutory wildfire responsibility. Agencies in California, Victoria, and Catalonia operate the most intensive aerial firefighting programs with dedicated fleet ownership.
- Forestry Services:Provincial and national land management authorities with multi-year contracting authority. Services in British Columbia, Alberta, and Western Australia concentrate global demand through exclusive-use procurement.
- Emergency Management:Cross-jurisdictional coordination bodies with surge capacity requirements. Authorities in Chile, Portugal, and Greece maintain call-when-needed arrangements for extreme event response.
- Conservation Groups:Non-governmental organizations with prescribed fire and habitat management missions. Groups in South Africa and Brazil operate smaller fleets for protected area management.
Forestry services lead contract volumes today; fire agencies are consolidating share fastest through fleet modernization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada contracts the largest aerial firefighting fleets through provincial forestry services, while Australia concentrates demand among state fire agencies modernizing aging platforms. Procurement patterns diverge sharply between these demand centers and emerging markets in Europe and Asia.
Canada
British Columbia and Alberta forestry services drive fleet expansion through eight-month exclusive-use contracts, up from five-month windows a decade prior. Transport Canada mandates supplemental type certificates for tanker modifications under harmonized EASA-aligned pathways. Quebec and Ontario host modification clusters where De Havilland Aircraft of Canada maintains proprietary manufacturing of purpose-built air tanker platforms.
Australia
Victoria and New South Wales fire agencies accelerate CL-415 and P-3 Orion replacement programs amid extended fire seasons. The Civil Aviation Safety Authority imposes operational limitations on firebombing flight envelopes that reshape fleet composition decisions. Sydney and Melbourne serve as crew training hubs where Coulson Aviation leverages vertical integration across modification, operations, and instruction to capture full-service contracts.
United States
California and federal fire agencies face compressed procurement timelines as 1970s-era air tanker platforms reach obsolescence. The FAA mandates Part 25 and Part 27 airworthiness standards for modified tanker aircraft with stringent drop-system performance thresholds. Operators in the Pacific Northwest and Southwest maintain call-when-needed arrangements, though multi-year exclusive-use contracts are displacing this model.
Spain
Catalonia and Mediterranean coastal fire agencies deploy seaplanes for island protection where runway construction proves prohibitive. EASA enforces CS-25 certification with redundant hydraulic actuator requirements for firefighting apparatus. Valencia hosts pilot programs for computer-vision-guided drop systems automating payload release through real-time wind vector analysis.
China
State forestry services and emergency management authorities scale procurement of the AG600 Kunlong, the largest amphibious aircraft in serial production. The Civil Aviation Administration of China aligns type certification with international standards while maintaining domestic production priorities. Zhuhai and regional manufacturing centers anchor AVIC's scale-driven competition through captive supply chain integration.
Water Bomber Market Competitive Landscape
Top-tier vendors anchor factory-new platform manufacturing, while mid-tier specialists compete on retrofit tank kits and modification services. The vendor base stratifies across three archetypes: purpose-built airframe manufacturers, vertical integrators spanning modification through operations, and state-affiliated aerospace conglomerates with scale advantages. Competitive moves concentrate on exclusive-use contract capture and regulatory certification acceleration.
Among North American integrated operators, Coulson Aviation and Bridger Aerospace exemplify the vertical-integration archetype combining modification, fleet ownership, and crew training. De Havilland Aircraft of Canada anchors the purpose-built manufacturer tier through proprietary air tanker platforms. AVIC and Beriev represent state-affiliated scale players leveraging domestic procurement preference and serial production capacity.
| Leading Market Players |
|---|
| Coulson Aviation |
| Roadfour (Seagle) |
| De Havilland Aircraft of Canada |
| Positive Aviation (FF72) |
| Hynaero (Fregate-F100) |
| AVIC (AG600 Kunlong) |
| Beriev (Be-200) |
| Bridger Aerospace |
| Avincis Italy |
| Others |
Pricing and Supply Chain Analysis
Specialized airframe engineering talent concentrated in Quebec and Ontario commands premium labor rates that widen pricing spreads between factory-new amphibious platforms and retrofit tank kits on surplus airframes. This workforce scarcity in structural load calculations for tanker modifications compresses margins on aftermarket installations while reinforcing pricing power for purpose-built manufacturers with captive design teams.
Pricing Analysis
Bundled full-service contracts spanning modification, crew training, and year-round aircraft availability extract 40-60% premiums over unbundled call-when-needed arrangements. Pricing stratifies across exclusive-use multi-year commitments, seasonal wet-lease agreements, and spot-market emergency activation. Cost compression in retrofit segments intensifies as forestry services in British Columbia and Alberta consolidate procurement toward guaranteed availability models. Small conservation groups and emergency management authorities in Southern Europe exhibit highest price sensitivity, while provincial forestry services in Canada demonstrate lowest sensitivity due to statutory wildfire liability exposure.
Supply Chain Analysis
Single-source vulnerability sits with aerospace-grade aluminum sheet stock, where three certified smelters in Russia, China, and Norway control qualified supply for amphibious hull fabrication. Raw material dependencies extend to precision hydraulic actuators from Germany and Japan, plus fire-retardant chemical formulations governed by EASA and FAA toxicity standards. Tariff exposure on Russian aluminum imports is reshaping sourcing strategies toward Chinese and Norwegian alternatives. Distribution runs through modification clusters in Quebec, Sydney, and Zhuhai where vertical integrators maintain captive MRO capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
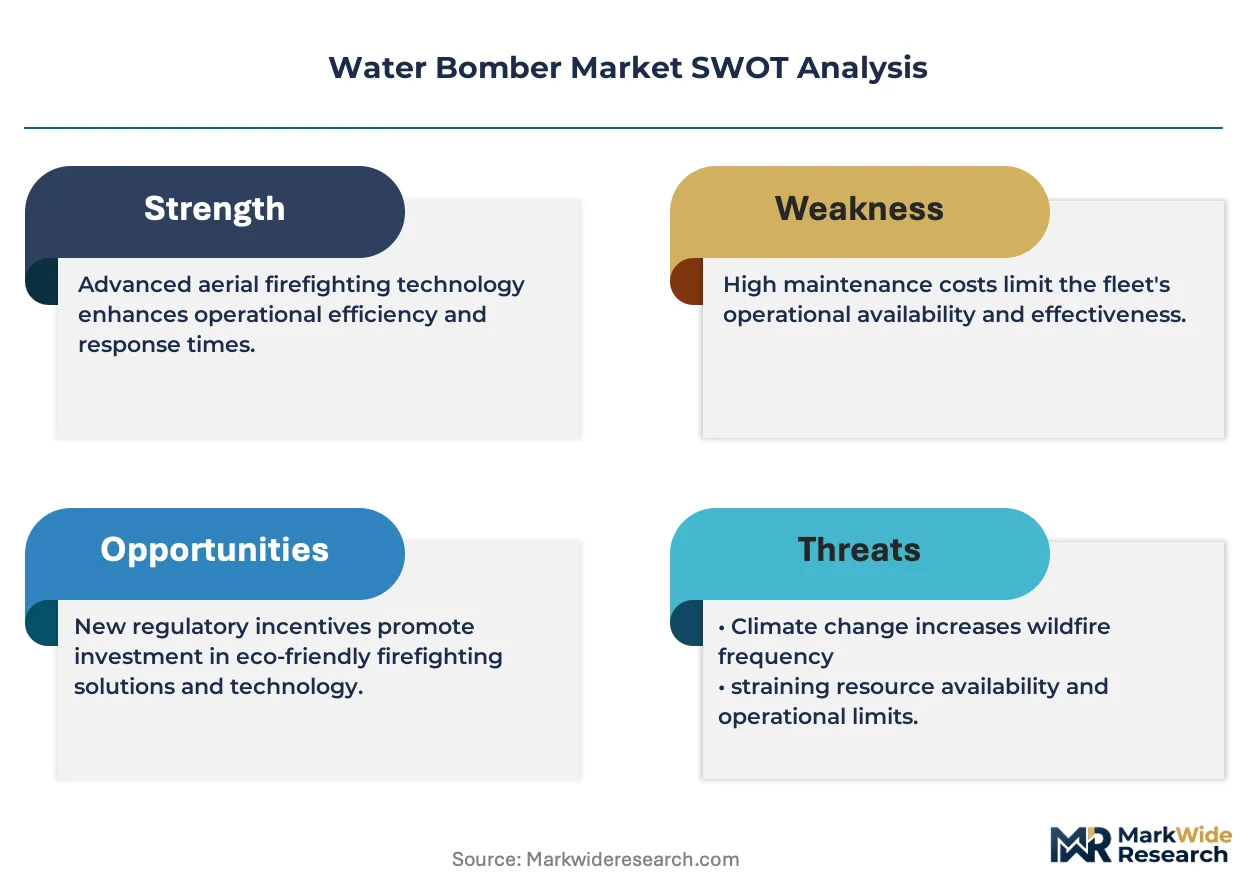
The water bomber market functions as a stable compounder anchored by climate-driven extension of wildfire seasons that institutionalizes multi-year exclusive-use contracting. Fleet obsolescence across North American and Australian fire agencies sustains replacement demand regardless of cyclical budget pressures.
For Market Incumbents: Anticipate accelerated consolidation as EASA CS-25 certification timelines stretch 18-24 months, favoring manufacturers with established supplemental type certificate portfolios. Defensive moves center on backward integration into aluminum sheet stock qualification and exclusive crew training academy investments that lock in contract renewals. The regulatory shift toward redundant hydraulic actuator mandates threatens retrofit specialists lacking factory-new platform pipelines. For New Entrants and Emerging Players: Enter via dual-use military conversion programs targeting surplus tactical transport airframes from defense drawdowns in the United States and NATO allies. White-space opportunity concentrates in Baltic and Scandinavian freshwater lake scooping infrastructure, currently underutilized versus coastal tanker bases. Go-to-market positioning should emphasize rapid certification through Transport Canada-EASA harmonized pathways rather than FAA Part 25 fragmentation. For Investors and Strategic Acquirers: State-affiliated aerospace conglomerates with captive domestic procurement represent the most active acquirer category in this space. Long-term viability frames around 5-10 year contracting windows as forestry services displace call-when-needed arrangements. Acquisition targets should display exclusive-use contract backlogs with penalty clauses and integrated drop system certification. The signal to watch is FAA Part 25 rulemaking on autonomous drop systems, which would unlock R&D investment freeze and reshape competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive-Use Contract Consolidation | Multi-year arrangements with penalty clauses in British Columbia and Alberta concentrate revenue with fleet owners. |
| CS-25 Certification Acceleration | EASA harmonized pathways compress approval timelines for integrated drop systems in European procurement. |
| Autonomous Drop System Development | Computer-vision-guided platforms enable nighttime operations previously prohibited by CASA visibility constraints. |
| Freshwater Scooping Infrastructure | Lake access in Scandinavia and Baltic states reduces turnaround times versus coastal tanker base dependency. |
| Military Airframe Conversion | Surplus tactical transport platforms from defense drawdowns lower acquisition costs for cost-constrained fleet expansion. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fleet operations directors at Coulson Aviation and Bridger Aerospace, EASA certification engineers, provincial forestry procurement officers in British Columbia and Alberta, and CASA flight standards inspectors with secondary validation. Secondary sources included Transport Canada supplemental type certificate databases, FAA Part 25 airworthiness directives, EASA CS-25 certification bulletins, and provincial budget appropriations for aerial firefighting. Bottom-up contract value aggregation and top-down fleet replacement cycle modeling were triangulated against manufacturer order backlogs.
Segment-weighting approaches applied differential growth assumptions across product types, with amphibious aircraft and autonomous platforms receiving accelerated coefficients reflecting EASA regulatory streamlining and pilot exposure reduction priorities. Technology segmentation incorporated certification maturity timelines, while end-user segmentation weighted forestry services and fire agencies by contract duration and exclusivity terms. CAGRs were derived from replacement cycle analysis of CL-415 and P-3 Orion fleet ages crossed with provincial procurement budget trajectories. Industry-specific inputs included wildfire season length extensions and aluminum smelter capacity utilization for certified aerospace sheet stock.
Inputs from EASA certification bulletins and provincial forestry procurement disclosures were available through the study window; gaps in autonomous flight regulatory pathway timelines introduce uncertainty bands around technology adoption curves. Forecasts reflect assumptions on fleet obsolescence rates and climate-driven season extension, with revision risk from FAA Part 25 rulemaking delays or aluminum supply disruptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Winglets Market
Aircraft
Helicopter Flight Management System Market
Aircraft
Japan Aviation Market
Aircraft
US Military Aviation Market
Aircraft
Asia-Pacific Military Helicopters Market
Aircraft
Evtol (Electric Vertical Takeoff and Landing) Airplane Market
Aircraft
Global Aircraft Electric Brake Control System Market
Aircraft
Military Multirole Aircraft Market
Aircraft
Aircraft Landing Gear Market
Aircraft
Wing Inspection and Taxi Lighting Upgrade Kits Market
Aircraft
Europe Helicopters Market
Aircraft
Europe Business Jet Market
Aircraft
Single-Seat Gyrocopter Market
Aircraft
UK Military Aviation Market
Aircraft
Asia-Pacific General Aviation Market
Aircraft
General Aviation Market