
 Commercial Aircraft Electronic Flight Bag (EFB) Systems Market | 2026-2036
Commercial Aircraft Electronic Flight Bag (EFB) Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Electronic Flight Bag (EFB) Systems Market Insights
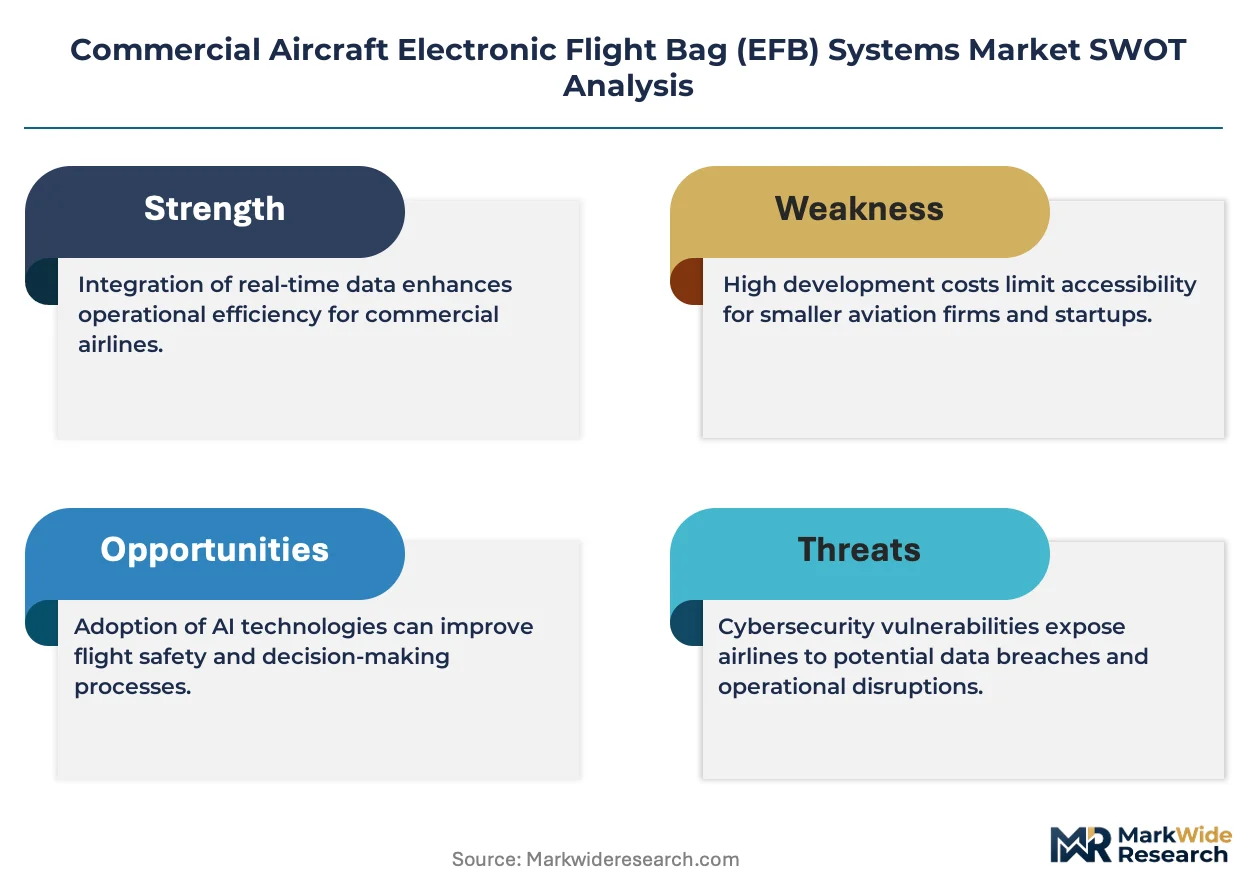
FAA AC 120-76D is broadening the cost-of-entry calculus for EFB system vendors by mandating rigorous software validation and hardware certification pathways. Collins Aerospace leverages its avionics heritage to sustain integrated cockpit display architectures. Thales Group anchors European airline upgrade programs with certified combined hardware-software platforms. Honeywell International competes through specialized performance computation modules that interface with existing flight management systems.
Commercial Aircraft Electronic Flight Bag Systems comprise portable or installed computing devices, typically featuring sunlight-readable displays, solid-state storage, and wireless connectivity interfaces, that digitize flight manuals, charts, and operational data for cockpit crews. These systems eliminate paper documentation, reduce pilot workload, and enable real-time data link communications with ground operations. Software Applications currently command the strongest margin pools due to recurring update cycles and airworthiness certification requirements, while Cloud-Enabled Systems represent the fastest-expanding deployment mode as airlines pursue fleet-wide data synchronization. Airlines dominate the Customer Type landscape, though Cargo Operators are emerging as a concentrated growth vector driven by long-haul route optimization needs.
The FAA, EASA, and ICAO frameworks collectively govern EFB airworthiness approval, operational authorization, and interoperability standards across jurisdictions. These bodies shape demand by specifying minimum display performance, data integrity requirements, and connectivity protocols that vendors must satisfy before fleet deployment. Stakeholders must monitor evolving cybersecurity directives from these regulators, as connected EFB architectures introduce new attack surfaces requiring continuous certification updates.
Market Dynamics
Fleet-wide digitization mandates from aviation regulators are compressing hardware refresh cycles and forcing vendors to recertify platforms under stricter cybersecurity protocols.
Growth Catalysts
- FAA AC 120-76D:This advisory circular mandates rigorous software validation pathways, compelling airlines to replace legacy portable EFB units with certified installed systems.
- Full-service carriers:These operators are completing fleet-wide retrofits to eliminate paper-based cockpit documentation and enable real-time data link communications with ground operations.
- Cloud synchronization:Airlines are deploying cloud-enabled architectures to synchronize flight manuals, performance calculations, and operational updates across dispersed aircraft fleets instantly.
Market Restraints
- Avionics-grade display panels:Sunlight-readable, high-brightness LCD and OLED panels face supply concentration among Asian display manufacturers, creating procurement bottlenecks.
- EASA certification timelines:Hardware-software combined approval processes extend 18-24 months, delaying revenue recognition for vendors and freezing airline deployment schedules.
- Tablet-based substitutes:Consumer-grade tablets with ruggedized enclosures threaten dedicated EFB hardware in Class 1 portable applications, pressuring margins at the entry tier.
Strategic Opportunities
- Cargo operators:Long-haul freight carriers present concentrated demand for performance computation modules that optimize fuel burn across extended routes with variable payload profiles.
- 5G ATG connectivity:Convergence of air-to-ground cellular networks with EFB platforms enables streaming weather, NOTAM updates, and collaborative decision-making tools previously limited to satellite links.
- ICAO cybersecurity framework:Emerging standards for connected cockpit systems create compliance service revenue streams for vendors offering continuous monitoring and threat response capabilities.
Industry Challenges
- DO-178C software engineering:Aviation-grade software development requires specialized talent pools that remain shallow relative to commercial software markets, inflating labor costs.
- Legacy FMS integration:Interfacing modern EFB architectures with proprietary flight management systems from incumbent avionics suppliers demands costly bilateral engineering agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Electronic Flight Bag (EFB) Systems Market |
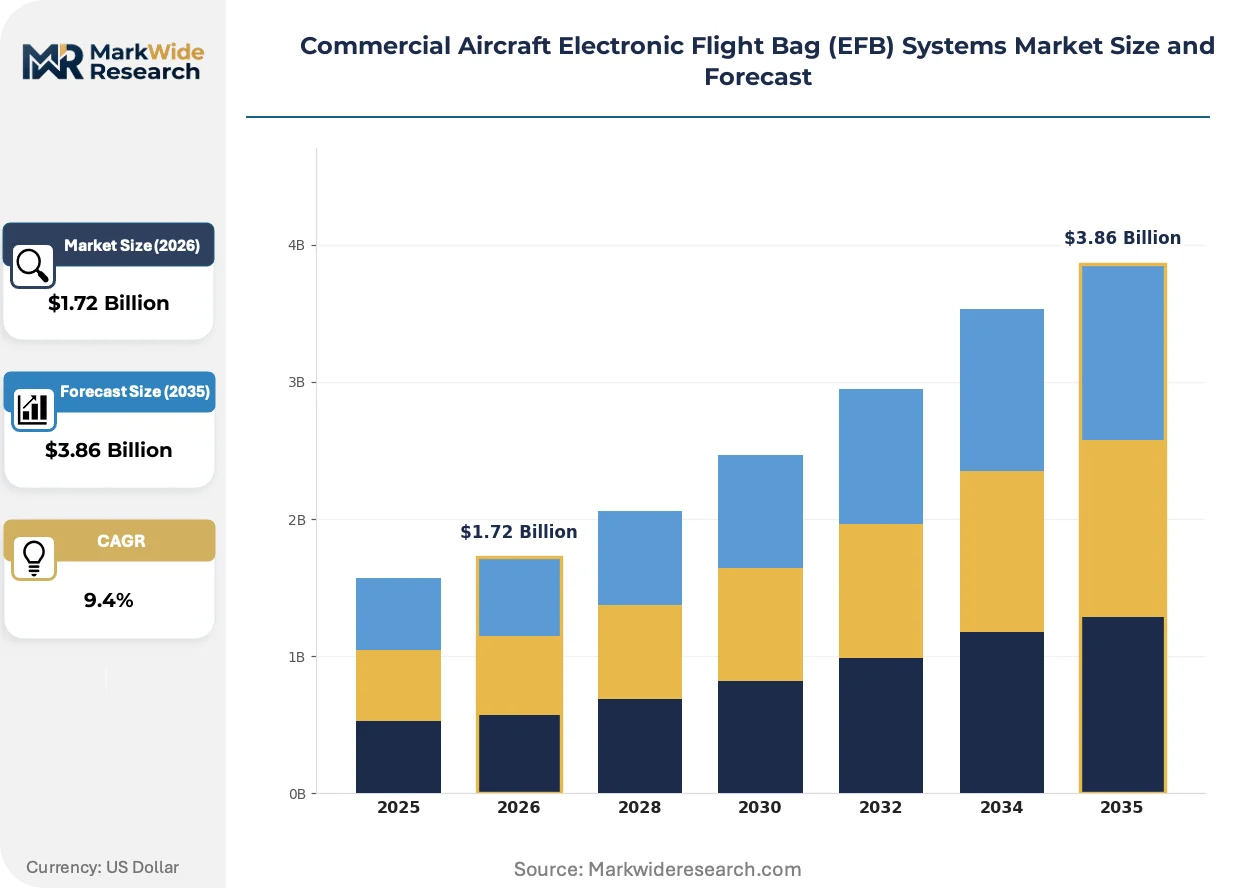
| Market Size in 2026 | $1.72 Billion |
| Market Size in 2035 | $3.86 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware Devices, Software Applications, Combined Solutions, Network Components Deployment Mode: Onboard Installation, Portable Devices, Cloud-Enabled Systems, Standalone Units Use Case: Flight Planning, Performance Monitoring, Weather Tracking, Documentation Management Customer Type: Airlines, Charter Services, Cargo Operators, Flight Training Institutions |
| Companies Covered | Thales Group, Astronautics Corporation of America, Collins Aerospace, Garmin, Lufthansa Systems, Honeywell International, Rockwell Collins, Teledyne Technologies, Boeing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Electronic Flight Bag (EFB) Systems Market Trends and Innovations
Aviation connectivity architectures are undergoing fundamental restructuring as airlines prioritize real-time data exchange over periodic manual updates.
Artificial intelligence-driven predictive maintenance modules are converging with EFB platforms to surface engine and system anomalies during pre-flight and in-flight phases. Regional carriers with mixed fleets are piloting these integrations most aggressively. This convergence is compressing the traditional separation between flight operations and maintenance control centers.
EASA's regulatory guidance on connected EFB cybersecurity introduces mandatory penetration testing and continuous monitoring obligations for fleet operators. Hardware vendors must now embed hardware security modules and encrypted boot processes into certified devices. European low-cost carriers are responding fastest, embedding these requirements into next-generation procurement specifications.
Airlines are unbundling EFB software subscriptions from hardware purchase contracts, creating standalone recurring revenue relationships with application developers. This shift displaces the traditional bundled sale model dominated by integrated avionics suppliers. Cargo operators in North America are leading this transition, negotiating direct agreements with performance computation specialists.
Commercial Aircraft Electronic Flight Bag (EFB) Systems Market Segmentation
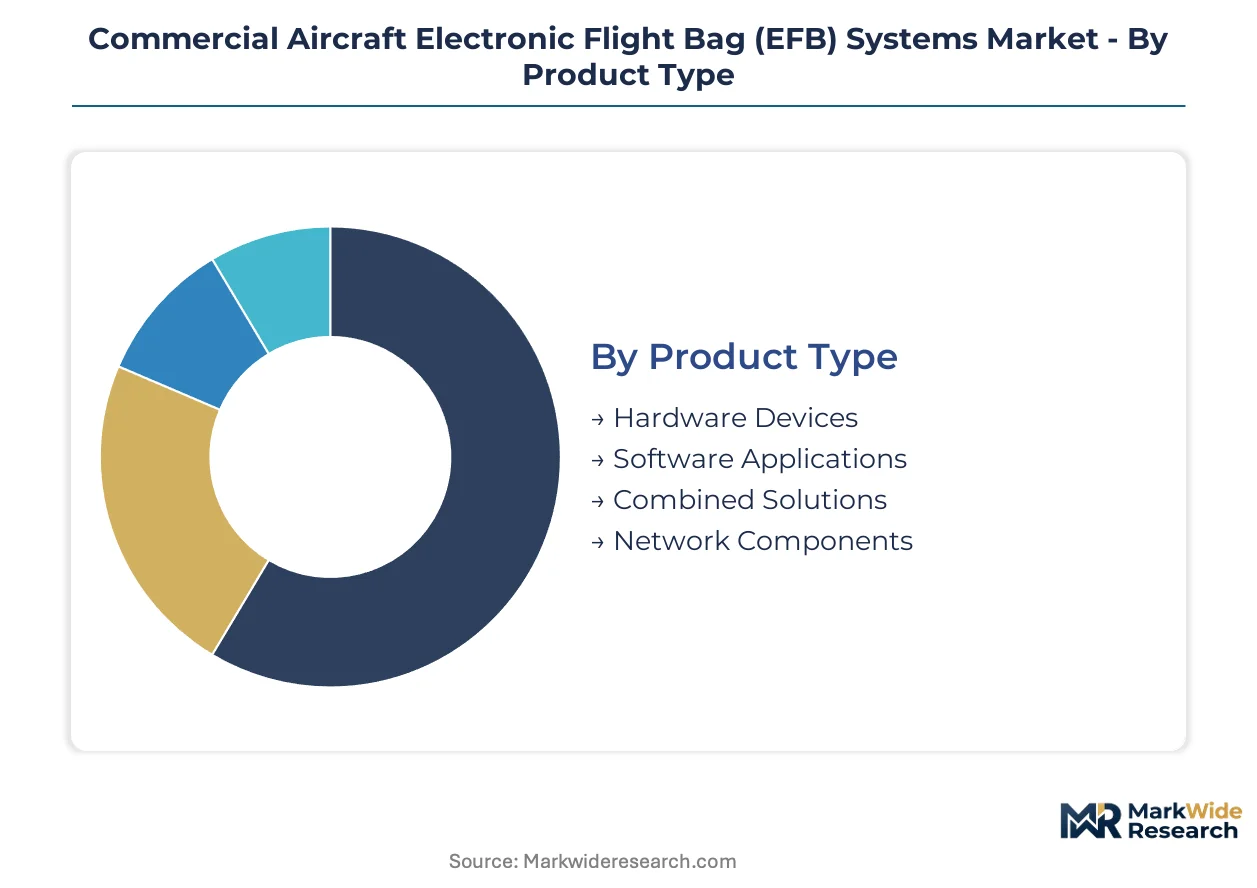
EFB procurement patterns diverge sharply across operator types, with full-service carriers prioritizing integrated cockpit architectures while cargo operators and training institutions favor modular, cost-optimized configurations. Segmentation reveals how regulatory mandates and fleet modernization cycles reshape demand concentration across hardware, software, and service layers.
Product Type:
Hardware buyers prioritize certification pedigree and sunlight-readable display performance, while software purchasers weight recurring update reliability and airworthiness validation pathways.
- Hardware Devices:Sunlight-readable LCD and OLED panels with solid-state storage form the physical computing layer. Demand concentrates among United States-based full-service carriers completing fleet-wide retrofits under FAA AC 120-76D mandates. Procurement bottlenecks in avionics-grade display panels from Asian manufacturers extend lead times.
- Software Applications:Flight manual digitization, performance computation, and data link modules command recurring revenue through subscription-based update cycles. Airlines dominate procurement, driven by operational authorization requirements for real-time ground-to-air synchronization.
- Combined Solutions:Integrated hardware-software platforms reduce certification complexity for operators seeking single-vendor accountability.
- Network Components:Wireless connectivity interfaces enable fleet-wide data distribution and cloud synchronization capabilities.
Hardware Devices lead volumes today; Software Applications is gaining share fastest.
Deployment Mode:
Certification burden and cybersecurity exposure separate installed architectures from portable alternatives, with cloud architectures emerging as a distinct cost tier for synchronized fleet operations.
- Onboard Installation:Permanently mounted EFB units with dedicated aircraft power and data bus integration satisfy FAA and EASA installed system requirements. Full-service airlines in the United States favor this mode for reduced pre-flight setup and enhanced regulatory compliance.
- Cloud-Enabled Systems:Fleet-wide synchronization architectures distribute flight manual updates, performance data, and operational notices instantly across dispersed aircraft. Cargo operators with long-haul networks pilot these deployments aggressively for route optimization.
- Portable Devices:Detachable computing units carried by flight crews offer lower capital commitment but require manual synchronization.
- Standalone Units:Self-contained EFB systems without aircraft integration reduce certification scope for smaller operators.
Onboard Installation anchors current deployments; Cloud-Enabled Systems shows the steepest expansion trajectory.
Use Case:
Operational criticality and pilot interaction frequency determine software module prioritization, with performance computation commanding premium pricing due to fuel optimization impact.
- Flight Planning:Route optimization, weight-and-balance calculation, and fuel load determination modules integrate with flight management systems. Airlines prioritize these tools for direct operating cost reduction across high-frequency short-haul networks.
- Performance Monitoring:Real-time engine parameter tracking and predictive maintenance alerting converge EFB platforms with maintenance control systems. Regional carriers with mixed fleets deploy these capabilities most aggressively.
- Weather Tracking:Streaming meteorological data and NOTAM integration enhance situational awareness for extended operations.
- Documentation Management:Digitized flight manuals, checklists, and regulatory publications eliminate paper-based cockpit workloads.
Flight Planning dominates current module deployment; Performance Monitoring is climbing the fastest.
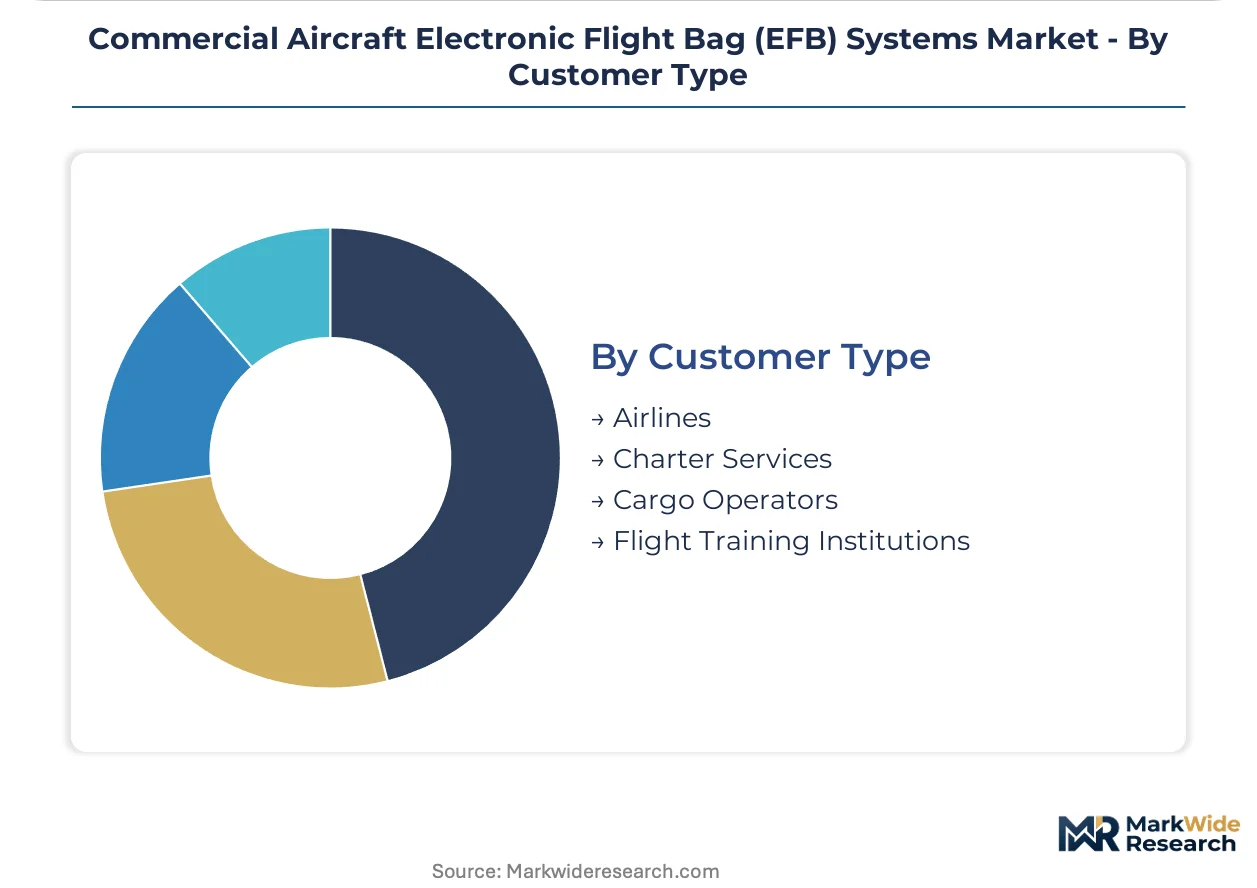
Customer Type:
Fleet scale and regulatory exposure shape procurement sophistication, with large airlines demanding integrated platforms while specialized operators seek targeted performance tools.
- Airlines:Full-service and low-cost carriers with substantial fleets drive volume demand for certified installed systems and fleet-wide software subscriptions. FAA mandates for real-time flight data accessibility accelerate hardware refresh cycles among United States operators.
- Cargo Operators:Long-haul freight carriers with variable payload profiles present concentrated demand for performance computation modules optimizing fuel burn across extended routes. North American cargo operators lead unbundled software procurement, negotiating direct agreements with application specialists.
- Charter Services:On-demand operators with irregular route structures favor portable EFB configurations for operational flexibility.
- Flight Training Institutions:Simulator-integrated EFB platforms prepare cadets for paperless cockpit environments.
Airlines command current procurement volumes; Cargo Operators is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The commercial aircraft EFB industry traces its operational origins to United States aviation modernization programs, where early digitization mandates established certification frameworks later adopted internationally. Regulatory harmonization now shapes deployment patterns across major aviation markets.
United States
FAA AC 120-76D mandates rigorous software validation and hardware certification pathways, compelling fleet-wide retrofits among full-service carriers. The advisory circular eliminates legacy portable EFB units in favor of installed systems with dedicated aircraft power integration. Major carriers headquartered in Dallas-Fort Worth and Atlanta are completing synchronized hardware refresh cycles across narrow-body and wide-body fleets.
Germany
EASA certification timelines extending 18-24 months delay revenue recognition for vendors serving German operators. The country's national aviation regulator enforces hardware-software combined approval processes that freeze airline deployment schedules. Lufthansa Systems anchors European upgrade programs from its Hamburg and Frankfurt operational centers, supplying certified platforms to Lufthansa Group carriers and third-party airlines.
France
Thales Group leverages its avionics heritage to sustain integrated cockpit display architectures for French and European flag carriers. EASA regulatory guidance on connected EFB cybersecurity introduces mandatory penetration testing obligations that hardware vendors must embed into certified devices. The Paris-Saclay aerospace cluster concentrates engineering talent for DO-178C software development and hardware security module integration.
United Kingdom
British Airways and low-cost carriers pilot cloud-enabled fleet synchronization architectures that distribute flight manual updates instantly across dispersed aircraft. The country's civil aviation authority aligns with ICAO interoperability standards while specifying minimum display performance requirements. London Gatwick and Manchester serve as deployment hubs for performance monitoring modules that converge EFB platforms with maintenance control systems.
Japan
ANA and JAL expand EFB deployments across their combined fleets to reduce paper-based cockpit workloads and enable real-time data link communications. METI industrial policy supports aviation digitization through procurement incentives for domestic carriers. The Nagoya aerospace corridor hosts subsystem suppliers specializing in sunlight-readable LCD and OLED panel integration for avionics-grade applications.
Commercial Aircraft Electronic Flight Bag (EFB) Systems Market Competitive Landscape
The competitive structure tilts toward integrated avionics specialists with established certification pedigrees and recurring software revenue streams. Vendor concentration remains moderate, with tier-one suppliers commanding installed system deployments while modular specialists capture portable and retrofit opportunities. Three archetypes dominate: full-stack platform integrators, performance computation specialists, and connectivity hardware fabricators. Consolidation pressure manifests through strategic partnerships for FMS integration and portfolio diversification into predictive maintenance modules.
Within the full-stack integrator tier, Thales Group and Collins Aerospace exemplify European and North American certification-heavy positioning. Honeywell International occupies a specialist position in performance computation modules that interface with incumbent flight management systems. Garmin represents the portable-device segment, leveraging consumer electronics scale for Class 1 EFB applications where ruggedized enclosures substitute for dedicated avionics hardware.
| Leading Market Players |
|---|
| Thales Group |
| Astronautics Corporation of America |
| Collins Aerospace |
| Garmin |
| Lufthansa Systems |
| Honeywell International |
| Rockwell Collins |
| Teledyne Technologies |
| Boeing |
| Others |
Pricing and Supply Chain Analysis
Cloud-enabled fleet synchronization architectures are compressing hardware margins while elevating software subscription economics, concentrating pricing power among vendors with certified airworthiness validation pathways. This structural shift simultaneously redraws supplier qualification criteria and procurement timelines across avionics-grade component markets.
Pricing Analysis
The bundled-versus-unbundled service split separates integrated avionics suppliers from modular software specialists. Subscription-based software applications command recurring revenue through airworthiness-certified update cycles, while hardware devices face cost compression from consumer-grade tablet substitutes in portable Class 1 applications. Price differentiation rests on certification pedigree and DO-178C software validation depth, with full-service airlines showing lowest price sensitivity due to regulatory compliance mandates and cargo operators driving hardest bargains on performance computation modules.
Supply Chain Analysis
Dual-sourcing requirements for avionics-grade display panels mandate multi-supplier qualification across Asian manufacturing hubs. Sunlight-readable LCD and OLED components draw from concentrated production in Japan, South Korea, and Taiwan, while solid-state storage and wireless connectivity modules feed from Chinese and Malaysian facilities. Single-source vulnerability in avionics-grade panel manufacturing creates procurement bottlenecks, with distribution running through tier-one avionics integrators and airline direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FAA AC 120-76D mandates for installed EFB systems generate sustained replacement demand across fleet retrofit cycles.
For Market Incumbents: Deploy certification leverage as the primary defensive mechanism. Deepen hardware-software integration to lock out modular competitors seeking FMS interface agreements, while accelerating cybersecurity certification investments to capture EASA continuous monitoring compliance revenue. Tablet-based substitutes and unbundled software procurement by cargo operators represent the most acute margin threats. For New Entrants and Emerging Players: The price-point gap between premium installed systems and economy portable configurations offers entry terrain. Target cargo operator segments with specialized performance computation tools for long-haul route optimization, leveraging direct software licensing agreements that bypass incumbent avionics bundles. Cloud-native architectures provide the fastest go-to-market angle for fleet synchronization capabilities. For Investors and Strategic Acquirers: Valuations sit cheapest among modular software specialists with narrow certification moats but expanding recurring revenue bases. Long-term viability favors vendors with installed system pedigree and 5G ATG connectivity integration capabilities. Watch for ICAO cybersecurity framework adoption velocity as the inflection signal for compliance service revenue scaling.| Strategic Initiative | Industry Significance |
|---|---|
| DO-178C Software Certification Investment | Deepens regulatory moats against consumer-grade tablet encroachment in portable applications. |
| 5G ATG Connectivity Partnership | Enables streaming weather and NOTAM updates previously limited to satellite data links. |
| Hardware Security Module Integration | Satisfies EASA mandatory penetration testing obligations for connected cockpit architectures. |
| Performance Computation Specialist Acquisition | Captures cargo operator demand for fuel optimization across variable payload long-haul routes. |
| Cloud-Native Fleet Synchronization Platform | Supports unbundled software procurement trends among North American freight carriers. |
Research Methodology
Direct dialogue with avionics procurement directors, airline flight operations executives, EASA certification engineers, and cargo carrier dispatch managers grounded qualitative findings. Secondary validation drew from FAA AC 120-76D guidance documents, EASA certification bulletins, ICAO cybersecurity framework drafts, and airline fleet modernization disclosures. Bottom-up triangulation across hardware shipment data and software subscription records converged with top-down expenditure estimates from carrier annual reports.
Segment-level outputs across hardware devices, software applications, combined solutions, and network components were modeled against deployment modes including onboard installation, cloud-enabled systems, portable devices, and standalone units. CAGRs were derived from fleet retrofit cycle analysis, regulatory mandate compliance timelines, and cargo operator expansion patterns. Forecast inputs incorporated 5G ATG network rollout schedules and EASA cybersecurity directive implementation trajectories.
The model assumes a particular technology adoption path; alternative pathways for satellite-to-cellular connectivity convergence would alter the outlook. Forecasts reflect assumptions regarding FAA and EASA harmonization timelines, avionics-grade panel supply expansion, and cargo operator digitalization rates. Deviation in ICAO cybersecurity framework adoption velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Avionics
Customized Avionic Systems Market
Avionics
Global Avionics Market
Avionics
Display for Avionics Application Market
Avionics
Europe Commercial Aircraft in-Flight Entertainment System Market
Avionics
Europe Aircraft Avionics Market
Avionics
Global Helicopter Avionics Market
Avionics
Asia-Pacific Aircraft Health Monitoring System Market
Avionics
Commercial Aircraft Avionics Systems Market
Avionics
Military Aircraft Avionics Market
Avionics
Avionics LRU Repair and Test Services Market
Avionics
Asia-Pacific Semiconductor in Military and Aerospace Market
Avionics
Asia-Pacific Aircraft Avionics Market
Avionics
Electronic Flight Instrument System Market
Avionics
Global Commercial Avionics Systems Market
Avionics
Commercial Electronic Flight Bag Market
Avionics
Aircraft EMI Shielding Market