
 Europe Aircraft Manufacturing Market | 2026-2036
Europe Aircraft Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Aircraft Manufacturing Market Analytics
Multi-source to dual-source supplier strategies is rebalancing how European airframers manage aerostructures and propulsion risk. Airbus leverages its transnational supply footprint to sustain A320 family output rates. Dassault Aviation anchors French defense-industrial sovereignty through Rafale production and naval aviation programs. Leonardo competes on rotorcraft specialization while extending its electronics and aerostructures supply role across European platforms.
Europe Aircraft Manufacturing encompasses the design, assembly, and certification of fixed-wing and rotary-wing vehicles with maximum takeoff weights from under six hundred kilograms for light sport aircraft to over five hundred sixty tonnes for wide-body commercial transports, employing aluminum-lithium alloys, carbon fiber reinforced polymers, and additive-manufactured titanium components to achieve specific strength targets and fuel burn reductions. The primary purpose spans commercial passenger and cargo carriage, military power projection, and sovereign airspace patrol. Commercial aircraft generates the largest revenue pool given narrow-body replacement cycles, while electric propulsion represents the fastest-expanding technology segment as battery energy density improvements and hydrogen fuel cell integration advance toward regional aircraft certification. Military aircraft retains margin concentration through long-term government contracts and classified subsystem content.
EASA type certification standards, EU Green Deal emission benchmarks, and REACH chemical compliance frameworks collectively shape airframe material selection, propulsion system approval pathways, and aftermarket chemical handling protocols across European production sites. The EU AI Act introduces additional conformity requirements for autonomous flight control and predictive maintenance algorithms. Stakeholders must monitor how CSRD sustainability disclosure rules will reshape supplier qualification criteria and capital allocation toward low-carbon manufacturing processes.
Market Dynamics
The EU Green Deal emission benchmarks are compressing certification timelines for sustainable aviation fuels while forcing concurrent retooling across aluminum-lithium and composite fabrication lines.
Growth Catalysts
- ReFuelEU Aviation Mandate:Binding SAF blending quotas create guaranteed offtake volumes for European fuel producers and airframe OEMs with certified propulsion integration.
- France-Germany FCAS Investment:Bilateral defense procurement frameworks channel sovereign R&D funding toward next-generation combat air systems and unmanned wingman platforms.
- Carbon Fiber Reinforced Polymers:Automated fiber placement advances cut wingbox assembly hours while reducing structural weight ratios below metallic alternatives.
Market Restraints
- Titanium Sponge Concentration:European additive manufacturing feedstock relies on Russian and Chinese sponge supply subject to export license volatility.
- REACH Chemical Compliance:Chromate conversion coating restrictions complicate corrosion protection for legacy aluminum airframe joints.
- Battery Energy Density Ceiling:Current lithium-ion cell performance caps electric regional aircraft range below commercially viable sector lengths.
Strategic Opportunities
- Hydrogen Fuel Cell Convergence:Cryogenic tank integration with turbofan architectures opens zero-emission narrow-body development pathways.
- EASA CS-23 Simplified Certification:Revised light aircraft standards reduce validation costs for electric propulsion startups targeting sub-19 seat commuter routes.
- Poland-Czech Aerostructure Clusters:Central European machining and composite layup capacity offers cost-competitive sourcing for Western European tier-one suppliers.
Industry Challenges
- Airworthiness Software Verification:EU AI Act conformity requirements for autonomous flight control algorithms extend DO-178C validation cycles.
- Specialized Welding Labor Scarcity:Titanium and nickel superalloy joining expertise concentrates in aging workforce pools across Midlands and Rhône-Alpes manufacturing belts.
- Legacy Avionics Integration:Retrofitting predictive maintenance sensors onto certified analog systems triggers expensive hardware-in-the-loop recertification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Aircraft Manufacturing Market |
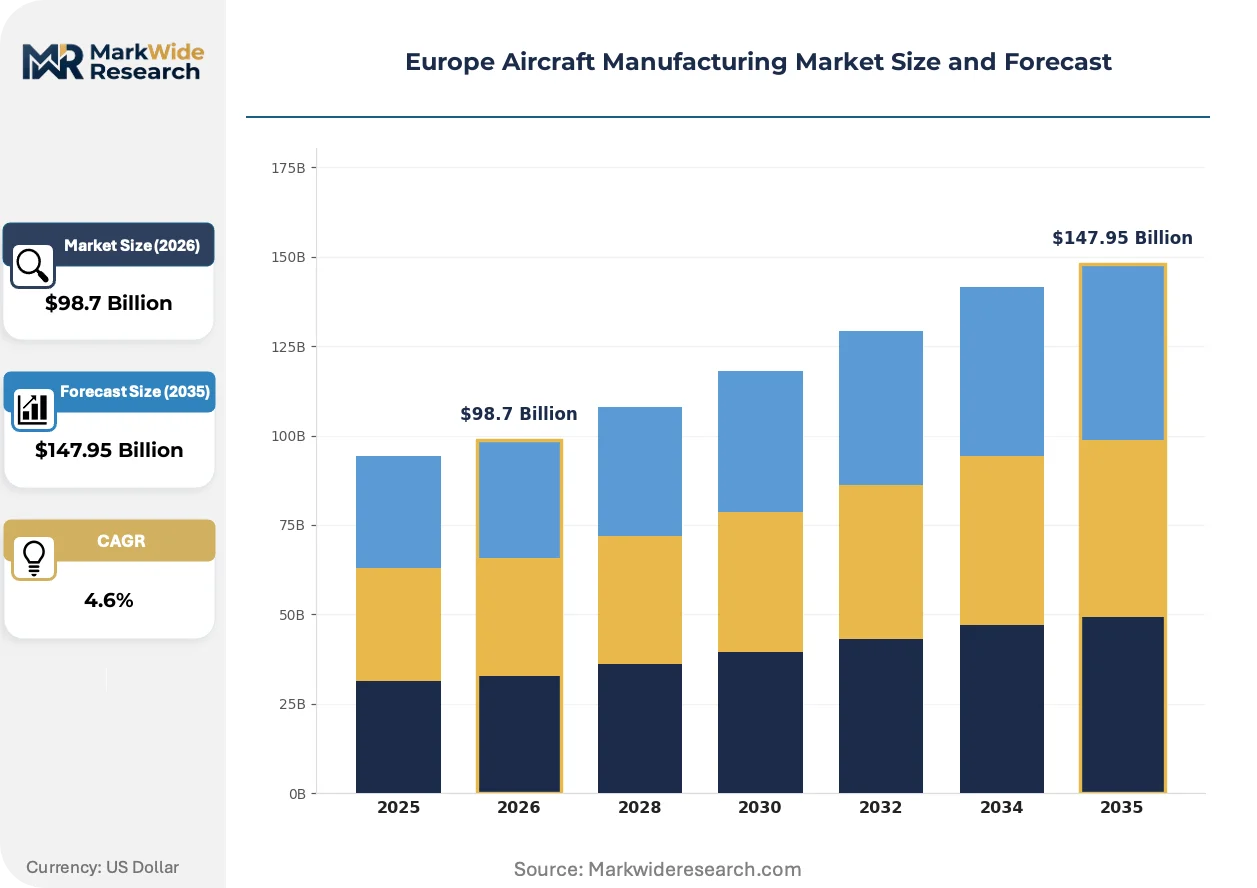
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $147.95 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial Aircraft, Military Aircraft, Helicopters, Drones Technology: Electric Propulsion, Avionics, Composite Materials, Turbofan Engines End User: Airlines, Defense Agencies, Freight Carriers, Government Application: Cargo Transport, Passenger Transport, Surveillance, Training |
| Companies Covered | Airbus, Dassault Aviation, Leonardo, BAE Systems, Saab Group, Bombardier, ATR Aircraft, Turkish Aerospace Industries, Embraer, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Aircraft Manufacturing Market Evolving Landscape
Digital thread architectures and additive manufacturing are collapsing traditional handoff points between design, tooling, and quality assurance functions across European production networks.
Additive manufacturing of titanium structural brackets is decentralizing final part production from centralized forging facilities to cell-level printer farms adjacent to assembly lines. Tier-two aerostructure suppliers in Toulouse and Hamburg are qualifying laser powder bed fusion for flight-critical brackets. This topology optimization capability is compressing buy-to-fly ratios from historical 15:1 forging waste to near-net-shape deposition.
CSRD sustainability disclosure rules are mandating granular Scope 3 emissions reporting from European airframers and their supply bases. Material suppliers must now certify cradle-to-gate carbon intensity for aluminum-lithium sheet and carbon fiber prepreg. The commercial aircraft segment faces the steepest compliance burden as airlines pressure OEMs for lifecycle footprint transparency.
Airline technical procurement teams are unbundling power-by-the-hour contracts into discrete component-level service agreements. Lessors and low-cost carriers now negotiate separate predictive maintenance subscriptions, rotable pool access, and engineering support. This decomposition is most advanced among Irish and UK-based leasing platforms managing mixed OEM fleets.
Europe Aircraft Manufacturing Market Segmentation
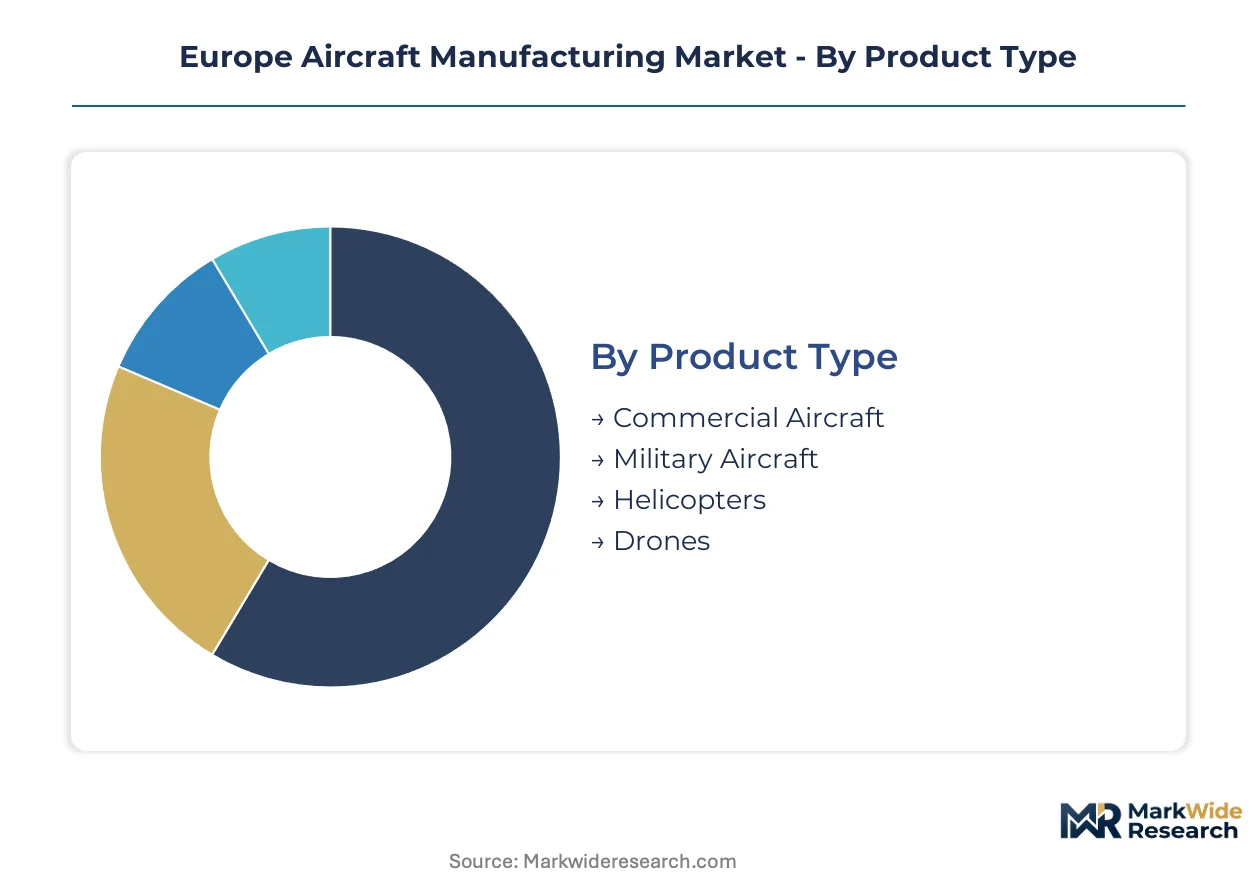
Segmentation in European aircraft manufacturing reveals how replacement cycles and fleet modernization reshape procurement patterns across distinct product categories. Upgrade timelines for narrow-body commercial fleets diverge sharply from defense procurement rhythms and emerging electric platforms.
Product Type:
Replacement cycles and fleet age profiles drive divergent investment patterns across fixed-wing and rotary-wing categories, with commercial narrow-bodies commanding the largest capital deployment.
- Commercial Aircraft:Narrow-body and wide-body platforms built from aluminum-lithium alloys and carbon fiber reinforced polymers dominate European assembly output. Airlines in France, Germany, and the UK anchor demand through A320 family re-engining programs and long-haul fleet renewal. EASA type certification timelines and ReFuelEU Aviation blending mandates compress delivery schedules for SAF-compatible propulsion.
- Military Aircraft:Combat air systems, transport platforms, and maritime patrol aircraft integrate classified subsystems and sovereign manufacturing content. France-Germany FCAS investment channels R&D toward sixth-generation fighters and unmanned wingman architectures. Government offset requirements and security-cleared supply chains sustain margin concentration absent in commercial segments.
- Helicopters:Twin-engine rotorcraft for offshore energy and emergency medical services leverage Leonardo's production footprint in Italy and Poland.
- Drones:Uncrewed aerial systems span military ISR platforms, cargo delivery prototypes, and civil surveillance applications regulated under EU AI Act conformity frameworks.
Volume placements concentrate in Commercial Aircraft; the faster expansion belongs to Drones.
Technology:
Cost tiers separate mature propulsion architectures from emerging electric and hydrogen systems, with certification expense acting as the primary segmentation boundary.
- Electric Propulsion:Battery-electric and hydrogen fuel cell systems target sub-19 seat regional routes through revised EASA CS-23 certification pathways. Energy density limitations constrain range viability, though Hamburg and Toulouse startups advance toward type validation. Clean aviation partnerships in France and Germany provide grant funding for powertrain integration.
- Composite Materials:Automated fiber placement of carbon fiber prepreg reduces wingbox structural weight below metallic alternatives. Airbus and tier-one suppliers in Spain and Germany qualify out-of-autoclave curing processes to cut fabrication cycle time.
- Avionics:Integrated flight control and predictive maintenance algorithms face EU AI Act conformity requirements extending software verification timelines.
- Turbofan Engines:Geared turbofan architectures from Franco-German propulsion ventures dominate narrow-body powerplant selections, with SAF compatibility now mandatory for new European deliveries.
Cost concentration sits with Turbofan Engines; steepest expansion trajectory belongs to Electric Propulsion.
End User:
Customer type determines contract structure, with airlines demanding lifecycle transparency and defense agencies prioritizing sovereign content and security classification.
- Airlines:Full-service and low-cost carriers negotiate power-by-the-hour contracts decomposed into discrete predictive maintenance subscriptions. Irish and UK-based lessors drive standardization across mixed OEM fleets.
- Defense Agencies:National procurement offices in France, Germany, Italy, and Spain mandate domestic workshare and technology transfer as contract conditions.
- Freight Carriers:Express parcel operators and integrators convert passenger aircraft to dedicated cargo configuration or acquire factory-built freighters.
- Government:State aviation services, coast guards, and border patrol agencies acquire surveillance-configured platforms through framework agreements.
Contract value concentrates with Defense Agencies; fastest share gain belongs to Freight Carriers.
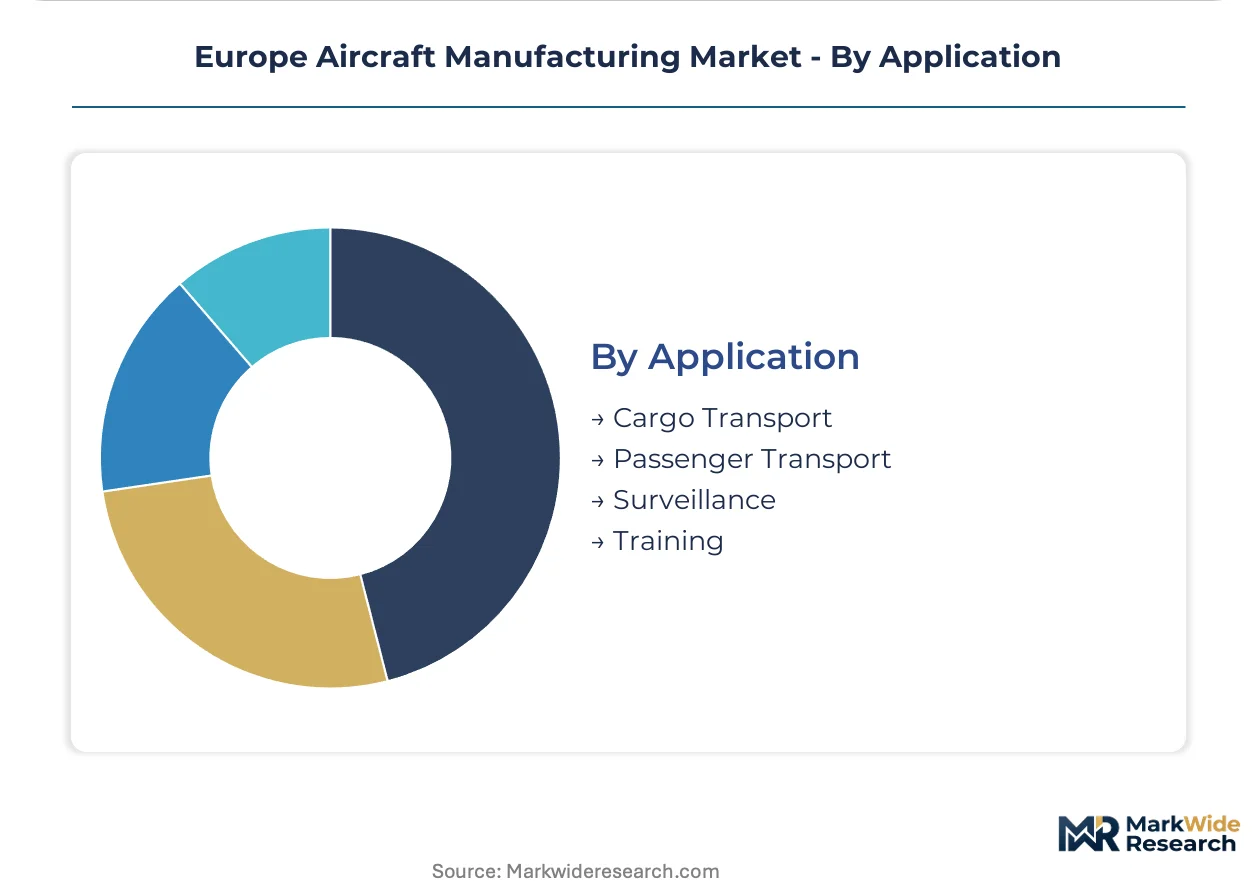
Application:
Application segmentation tracks how mission profiles dictate airframe configuration, sensor payload, and certification basis across transport and non-transport roles.
- Passenger Transport:Scheduled airline service and business aviation generate the largest European production volume, with cabin reconfiguration cycles driving aftermarket revenue. Single-aisle aircraft configured for 150-200 seats dominate Toulouse and Hamburg final assembly lines.
- Surveillance:Maritime patrol, airborne early warning, and border monitoring missions require sensor-integrated platforms with extended loiter endurance. Leonardo and Airbus Defence and Space compete on radar and electro-optical payload integration.
- Cargo Transport:Dedicated freighter production and passenger-to-cargo conversion programs serve e-commerce fulfillment networks.
- Training:Jet and turboprop trainer aircraft sustain pilot pipeline capacity for military and civilian aviation authorities.
Production volume concentrates in Passenger Transport; the climbing trajectory belongs to Surveillance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France and Germany concentrate the largest share of European aircraft manufacturing demand through defense procurement frameworks and commercial assembly dominance. Sovereign investment programs and EU regulatory mandates reshape production footprints across the continent.
France
Dassault Aviation sustains Rafale fighter production for export markets while anchoring the Future Combat Air System program with Germany. The EU Green Deal drives Safran and Airbus toward hydrogen propulsion research in Toulouse. The Occitanie aerospace cluster hosts automated fiber placement facilities supplying wing components across European final assembly lines.
Germany
Airbus Hamburg final assembly lines set narrow-body delivery rates for global airline customers. The ReFuelEU Aviation mandate accelerates SAF-compatible engine certification at MTU Aero Engines. Bavaria's Munich-Upper Bavaria region concentrates additive manufacturing qualification labs for titanium structural brackets.
United Kingdom
BAE Systems manages Eurofighter Typhoon workshare and F-35 subassembly contracts for Royal Air Force requirements. The UK AI Act extends software verification protocols for autonomous flight systems. The Midlands aerospace belt around Birmingham and Derby retains specialized welding capacity for nickel superalloy engine components.
Italy
Leonardo sustains AW139 helicopter output for offshore energy and emergency medical services across European markets. The EU AI Act conformity requirements extend to predictive maintenance algorithms developed in Rome. The Campania region around Naples hosts aerostructures fabrication for A320 family wingboxes.
Spain
Airbus Getafe and Illescas facilities produce A350 carbon fiber wing components and rear fuselage sections. EASA type certification timelines compress delivery schedules for SAF-integrated propulsion systems. The Madrid-Castile region concentrates composite out-of-autoclave curing qualification for lower fabrication cycle times.
Europe Aircraft Manufacturing Market Competitive Landscape
Multi-source to dual-source supplier rebalancing dominates the current landscape as airframers manage aerostructures and propulsion risk across transnational footprints. The vendor base concentrates around three strategic tiers: transnational integrators with final assembly authority, national champions anchoring sovereign defense content, and specialized tier-one suppliers controlling critical subsystems. Consolidation through government-backed defense procurement and clean aviation partnerships shapes competitive positioning. Geographic expansion into Central European machining clusters and technology licensing for electric propulsion startups represent parallel competitive vectors.
Within the transnational integrator tier, Airbus exemplifies multi-country production coordination across Toulouse, Hamburg, and Getafe final assembly lines. Dassault Aviation occupies a position anchoring French defense-industrial sovereignty through combat aircraft and naval aviation programs. Leonardo sits within the rotorcraft specialization archetype while extending electronics and aerostructures supply roles across European platforms. These three entities represent distinct competitive positioning strategies: transnational commercial scale, national defense champion, and dual-use specialization.
| Leading Market Players |
|---|
| Airbus |
| Dassault Aviation |
| Leonardo |
| BAE Systems |
| Saab Group |
| Bombardier |
| ATR Aircraft |
| Turkish Aerospace Industries |
| Embraer |
| Others |
Value Network & Pricing Analysis
Specialized titanium and nickel superalloy welding expertise concentrates in the Midlands and Rhône-Alpes manufacturing belts, where labor-cost differentials between these aging workforce pools and Central European machining clusters widen pricing-tier spreads for aerostructure and propulsion components.
Pricing Analysis
Warranty and service-bundling unbundling reshapes contract structures across European aircraft manufacturing. Power-by-the-hour agreements now decompose into discrete predictive maintenance subscriptions, rotable pool access, and engineering support tiers. Three-tier pricing structure across premium, standard, and economy levels separates full-service airlines with lifecycle transparency demands from low-cost carriers and freight operators. Pricing pressure stems from airline procurement teams extracting granular cost visibility for lifecycle footprint compliance. Low-cost carriers exhibit highest price sensitivity; defense agencies with sovereign content mandates show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale airline demand while tier-one aerostructure suppliers feed final assembly lines across Toulouse, Hamburg, and Getafe. Geographic supply concentration centers on France, Germany, and Spain for carbon fiber wing components and aluminum-lithium fuselage sections. Raw material dependencies rest on titanium sponge from Russian and Chinese sources, carbon fiber prepreg from specialized European suppliers, and lithium-ion cells for electric propulsion prototypes. Single-source vulnerability in titanium sponge feedstock exposes additive manufacturing operations to export license volatility. Distribution runs through long-term framework agreements with national procurement offices and airline technical teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
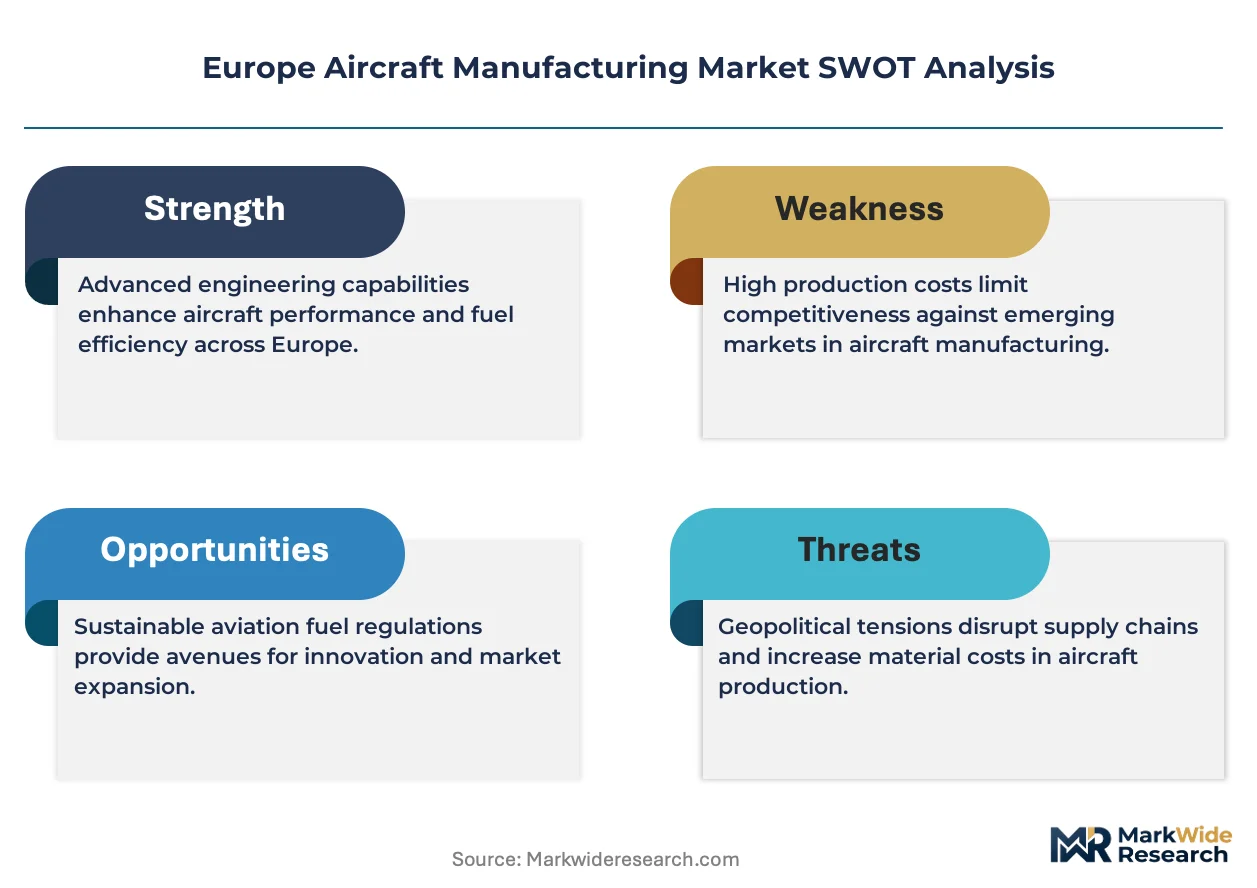
European aircraft manufacturing operates as a supply-constrained market where specialized welding labor scarcity and titanium sponge concentration prop pricing power toward incumbent tier-one suppliers with captive metallurgical expertise.
For Market Incumbents: Hedge against titanium sponge supply disruption by qualifying Central European additive manufacturing feedstock alternatives and securing long-term offtake agreements with non-Russian sponge producers. Backward integration into automated fiber placement capabilities in Poland-Czech machining clusters reduces exposure to Rhône-Alpes labor-cost inflation. EASA CS-23 simplified certification pathways for electric propulsion represent a defensive R&D lever against hydrogen fuel cell startups. For New Entrants and Emerging Players: Tier-two aerostructure suppliers in Central Europe offer the most penetrable channel partner type for sub-assembly contracts feeding Airbus and Leonardo final assembly lines. White-space targets include cryogenic tank integration for hydrogen narrow-body architectures and predictive maintenance algorithm development under EU AI Act conformity frameworks. A go-to-market angle through clean aviation partnership grant funding in France and Germany accelerates powertrain validation timelines. For Investors and Strategic Acquirers: Re-rating potential sits with specialized tier-two composite suppliers given ReFuelEU Aviation SAF blending mandates and CSRD Scope 3 disclosure requirements forcing airline procurement toward certified low-carbon aerostructures. Long-term viability favors entities with out-of-autoclave curing qualifications and EASA type certification relationships. Monitor EASA validation timelines for electric regional aircraft as inflection indicator for battery energy density breakthrough commercialization.| Strategic Initiative | Industry Significance |
|---|---|
| SAF-Compatible Propulsion Certification | ReFuelEU Aviation mandates now require SAF blending quotas for all new European deliveries. |
| Central European Aerostructure Expansion | Poland-Czech machining clusters offer cost-competitive sourcing for Western European tier-one suppliers. |
| Hydrogen Fuel Cell Integration | Cryogenic tank architecture development opens zero-emission narrow-body pathways for Franco-German partnerships. |
| Predictive Maintenance Algorithm Development | EU AI Act conformity requirements extend software verification cycles for autonomous flight systems. |
| Titanium Sponge Supply Diversification | Export license volatility from Russian and Chinese sources forces qualification of alternative feedstock channels. |
Research Methodology
EASA type certification databases, EU Green Deal regulatory filings, and REACH chemical compliance frameworks formed the secondary backbone for this analysis. Primary interviews with airframe OEM procurement directors, tier-one aerostructure supplier plant managers, and defense agency acquisition officers combined with secondary validation across customs records and SEC filings from listed aerospace entities. Bottom-up segment sizing across commercial, military, and helicopter categories triangulated against top-down European production value estimates.
Historical trendline analysis of narrow-body delivery rates, defense procurement cycles, and electric propulsion certification timelines informed projection modeling across the analysis window. Segmentation dimensions included product type, propulsion technology, end-user contract structure, and application mission profile. CAGRs were derived from replacement cycle dynamics and fleet age profiles rather than extrapolated growth assumptions. Industry-specific forecast inputs incorporated ReFuelEU Aviation mandate compliance costs and FCAS program funding trajectories.
Several conditions sit outside the modeled scope, including geopolitical disruptions to titanium sponge supply, battery energy density breakthroughs beyond current lithium-ion ceilings, and unilateral national defense procurement cancellations. Forecasts reflect documented assumptions about EASA certification timeline stability and EU regulatory framework continuity. Practitioners should monitor EASA validation progress for electric regional aircraft and FCAS bilateral funding commitments for early signals of trajectory revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Active Air Deflector Market
Aircraft
Commercial Aerospace Market
Aircraft
Water Bomber Market
Aircraft
Single-Seat Gyrocopter Market
Aircraft
Asia-Pacific Business Jet Market
Aircraft
Asia-Pacific Heavy-Lift Helicopter Market
Aircraft
Europe Commercial Aircraft Market
Aircraft
Aircraft Leasing Market
Aircraft
Wind Tunnel Market
Aircraft
Asia-Pacific Light and Very Light Jets Market
Aircraft
UK Military Aviation Market
Aircraft
Global Business Aircraft Market
Aircraft
North America Business Jet Market
Aircraft
Turboprop Aircraft Market
Aircraft
Commercial Aircraft Landing Gear Market
Aircraft
Global LW Sport Aircraft Market