
 Asia-Pacific Attack Helicopter Market | 2026-2036
Asia-Pacific Attack Helicopter Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Attack Helicopter Market Outlook
Defense procurement channels across Southeast Asia are being redrawn as bilateral offset agreements replace traditional direct foreign military sales, a shift that is reshaping how original equipment manufacturers establish local assembly partnerships. Hindustan Aeronautics Limited leverages its integrated production complexes in Bangalore and Lucknow to anchor India's attack helicopter self-sufficiency drive. Aviation Industry Corporation of China dominates indigenous development through its Harbin and Changhe aircraft subsidiaries, controlling vertical supply chains for rotor systems and fire-control architectures.
An attack helicopter constitutes a rotary-wing military aircraft engineered for close air support, anti-armor engagement, and armed reconnaissance missions, typically integrating tandem cockpit configurations, stub-wing weapon pylons, and composite rotor blades rated for sustained 150-knot dash speeds. The platform serves ground commanders with organic precision fires without fixed-wing runway dependency. Multi-role configurations now lead procurement budgets across the region as operators demand interoperable platforms spanning anti-tank, close support, and maritime strike profiles, while fly-by-wire technology segments attract the fastest upgrade cycles as legacy mechanical flight controls reach obsolescence thresholds. Heavy attack variants concentrate margin pools where composite armor integration and integrated electronic warfare suites command premium pricing.
India's Ministry of Defence enforces indigenization mandates through the Defence Acquisition Procedure, while China's MIIT coordinates military-civil fusion standards for dual-use aerospace components; both frameworks restrict import dependency and redirect demand toward qualified domestic suppliers. METI in Japan governs defense equipment transfers through its Three Principles on Arms Exports, constraining Kawasaki Heavy Industries' regional partnership scope. Stakeholders must monitor how evolving offset requirements and technology transfer conditions determine which manufacturers secure long-term fleet modernization contracts across divergent national procurement regimes.
Market Dynamics
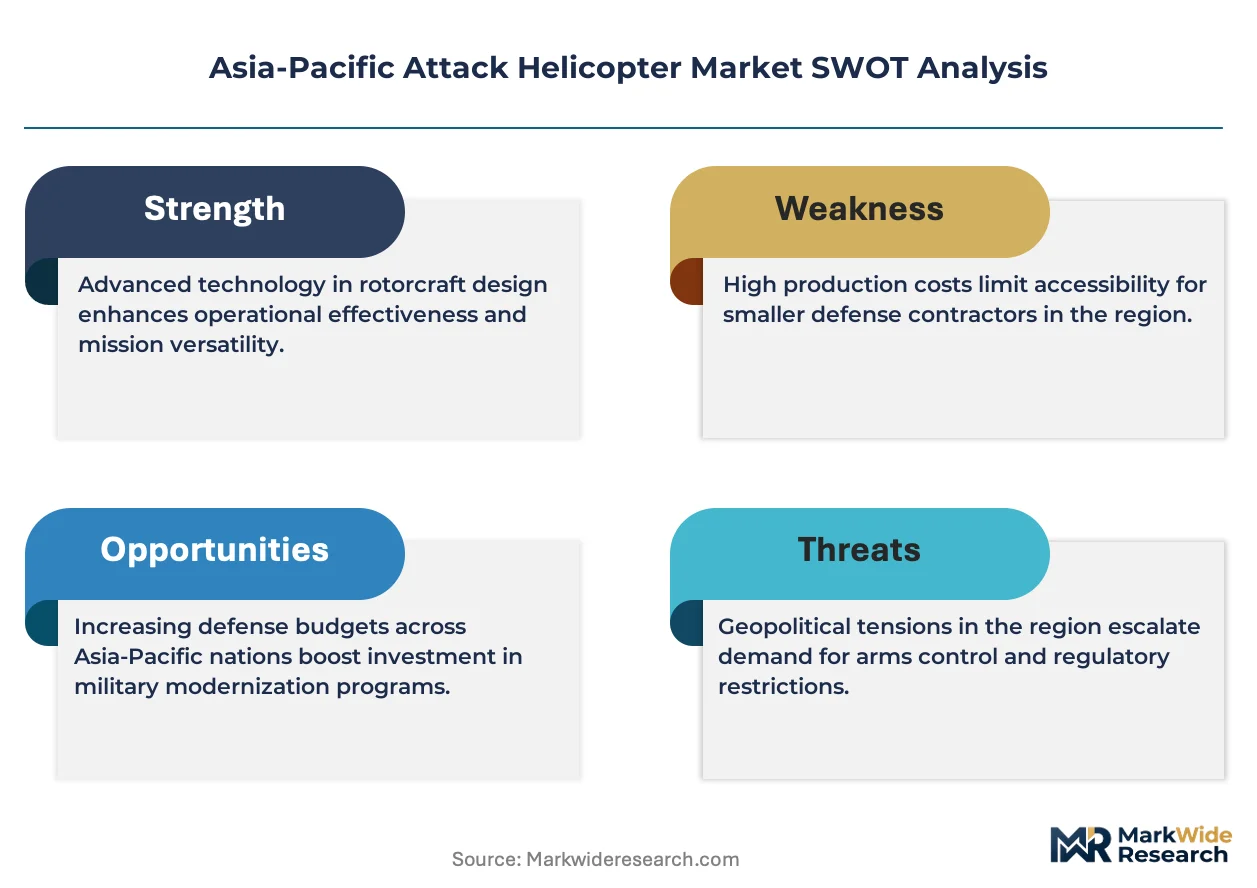
India's Defence Acquisition Procedure indigenization mandates are forcing original equipment manufacturers to restructure supply chains around domestic assembly partnerships, compressing traditional direct foreign military sales channels across the region.
Growth Catalysts
- Maritime Border Tensions:Southeast Asian naval forces require rotary-wing strike platforms for littoral zone patrol and anti-ship interdiction, driving fleet expansion programs in Indonesia, Vietnam, and the Philippines.
- MIIT Military-Civil Fusion:China's coordination of dual-use aerospace standards accelerates domestic rotor system and fire-control component production, reducing import dependency for next-generation attack helicopter programs.
- Counter-Insurgency Mandates:Persistent internal security operations in India's northeastern states and Myanmar's border regions sustain demand for armed reconnaissance platforms with precision strike and thermal imaging capabilities.
Market Restraints
- Composite Armor Input Costs:Carbon-ceramic armor plating and radar-absorbent materials face price volatility tied to aerospace-grade carbon fiber supply concentration in Japan and South Korea.
- Technology Transfer Friction:METI's Three Principles on Arms Exports constrains Japanese manufacturers from establishing regional co-production partnerships, limiting Kawasaki Heavy Industries' market access.
- Manned Platform Substitution:Armed unmanned aerial systems with loitering munition payloads encroach on traditional attack helicopter mission profiles in reconnaissance and light strike roles.
Strategic Opportunities
- Vietnam Fleet Modernization:Replacement of aging Mi-24 Hind airframes creates white space for Western and Asian manufacturers willing to establish maintenance partnerships under offset agreements.
- Fly-by-Wire Retrofit Cycles:Mechanical flight control obsolescence across legacy fleets in Australia and South Korea opens upgrade markets for digital avionics integration.
- PLI Scheme Alignment:India's Production Linked Incentive scheme for aerospace components rewards local manufacturing of transmission systems and engine sub-assemblies, attracting tier-one suppliers to Bangalore and Hyderabad clusters.
Industry Challenges
- Integrated Avionics Integration:Merging third-party mission computers with indigenous rotorcraft platforms creates software architecture conflicts that extend certification timelines by 18-24 months.
- Turboshaft Engine Supply:Qualified powerplant manufacturers concentrate in France, the United States, and Ukraine, forcing Asia-Pacific assemblers to navigate export control complexity and spare parts lead time volatility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Attack Helicopter Market |
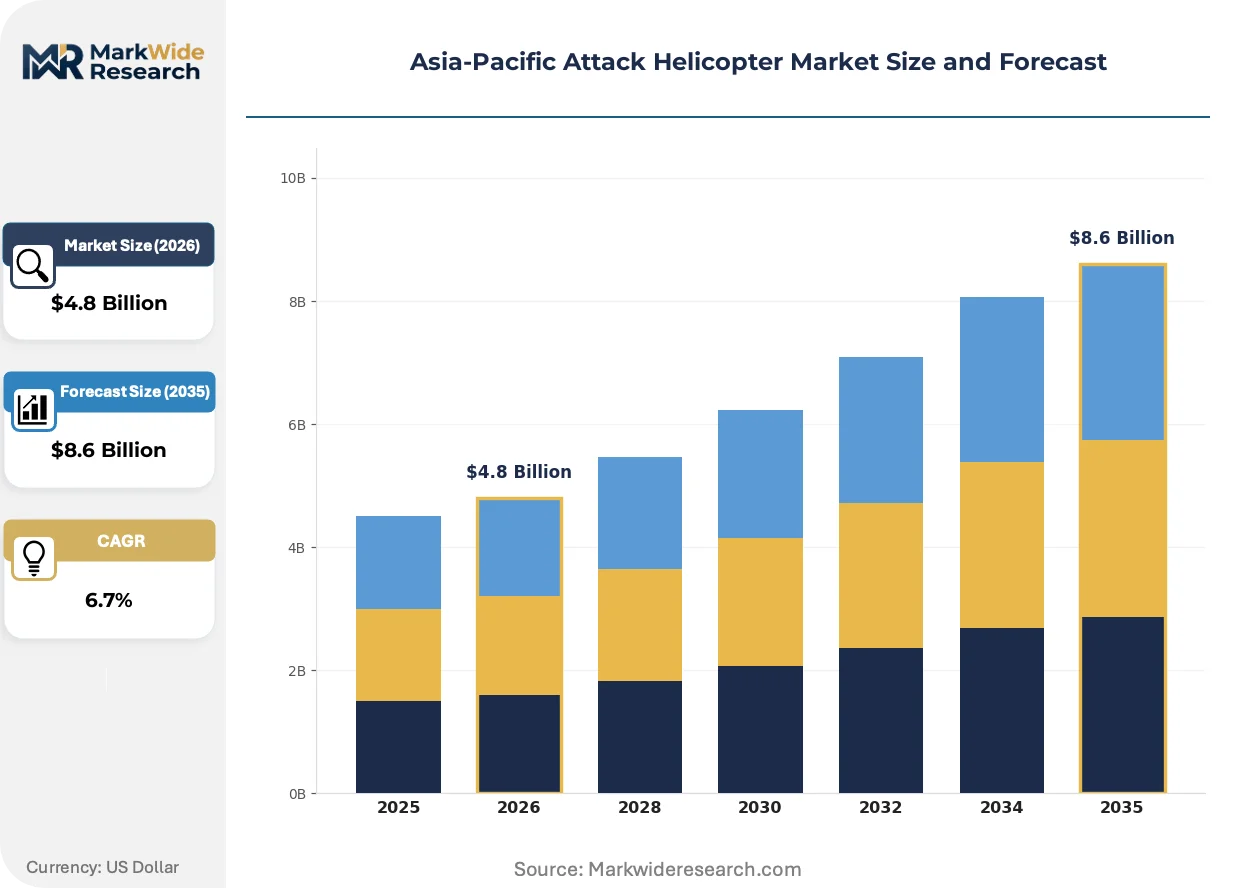
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Attack, Multi-Role, Heavy Attack, Advanced Armed Technology: Fly-by-Wire, Rotorcraft, Avionics, Weapon Systems End User: Military Forces, Law Enforcement, Private Contractors, Government Agencies Deployment: Onshore, Offshore, Urban Operations, Rural Operations |
| Companies Covered | Hindustan Aeronautics Limited, Aviation Industry Corporation of China, The Boeing Company, Textron Inc., Kawasaki Heavy Industries Ltd., Rostec State Corporation, Leonardo S.p.A., Lockheed Martin Corporation, Airbus SE, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Attack Helicopter Market Strategic Shifts
Active electronically scanned array radar and helmet-mounted cueing systems are compressing sensor-to-shooter timelines, redefining how attack helicopters integrate into joint force command structures across the region.
Fly-by-wire flight control architecture is collapsing mechanical linkage maintenance burdens while enabling automatic terrain-following modes. Indian and Australian operators now mandate digital flight controls for all new attack helicopter acquisitions. This compression eliminates hydromechanical system suppliers from future procurement competitions.
India's Defence Acquisition Procedure 2020 mandates minimum 50 percent indigenous content for capital acquisitions, forcing foreign manufacturers to license production to Hindustan Aeronautics Limited or private sector partners. The policy most heavily affects engine and transmission sourcing, with European and American suppliers establishing Bangalore-based component factories to maintain fleet access.
Performance-based logistics contracts are displacing traditional spares-and-maintenance purchasing across Australian and Japanese attack helicopter fleets. Operators now contract for availability hours rather than individual part orders, transferring inventory risk to original equipment manufacturers and their regional service partners.
Asia-Pacific Attack Helicopter Market Segmentation
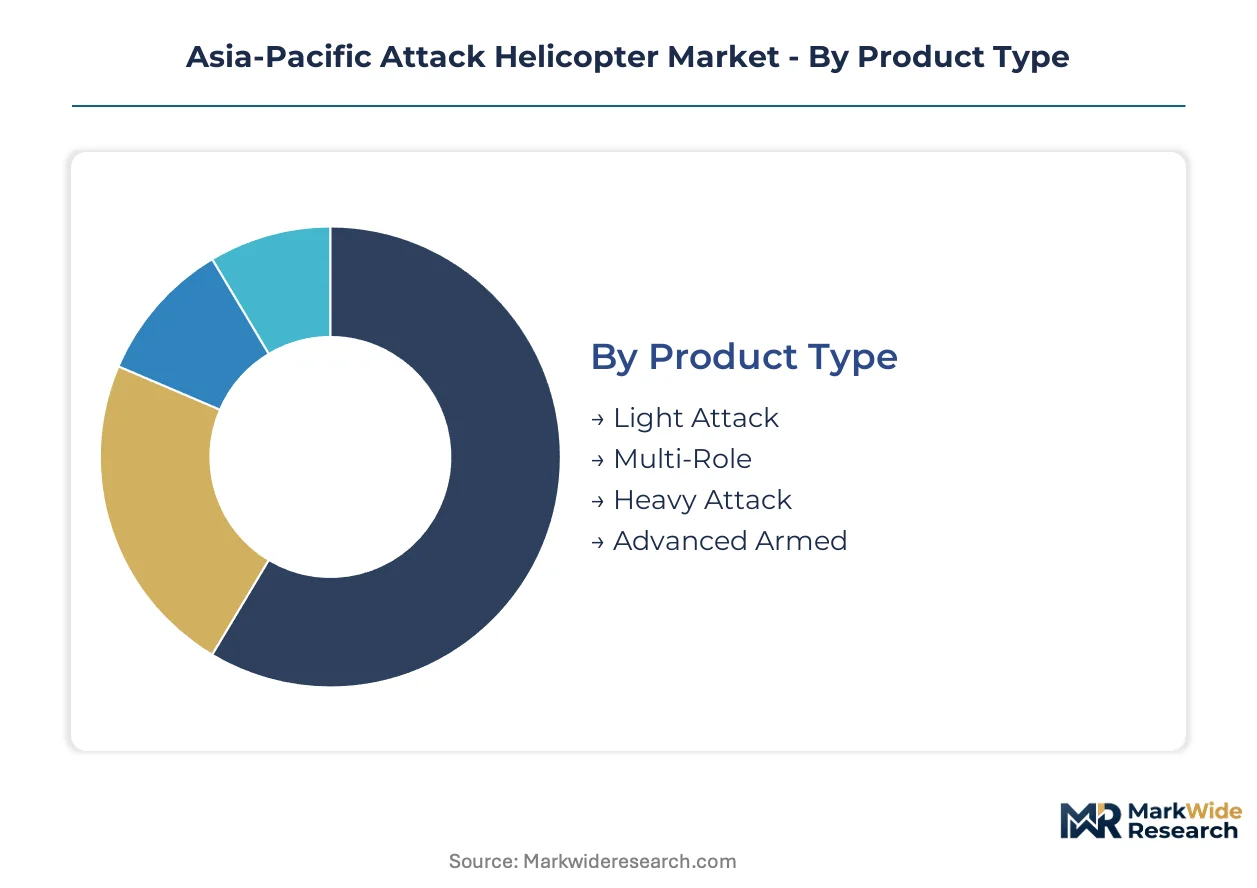
Attack helicopter procurement patterns diverge sharply across product weight classes and mission configurations. Technology refresh cycles and operational doctrine shifts in India and China are reshaping which segments absorb capital allocation versus sustainment spending.
Product Type:
Multi-role platforms turn over every 8-12 years as avionics obsolescence outpaces airframe fatigue, while heavy attack variants operate 20-25 year lifecycles with incremental armor and sensor upgrades.
- Multi-Role:Configurable stub-wing pylons support anti-tank missiles, rocket pods, and gun pods on the same airframe. Indian Army Aviation Corps and People's Liberation Army Ground Force concentrate new procurement here, driven by fiscal pressure to collapse multiple mission types into single fleet types.
- Heavy Attack:Tandem cockpit designs with integrated electronic warfare suites and composite armor withstand 23mm anti-aircraft fire. Margin pools concentrate in this segment where survivability specifications command premium pricing from operators in Australia and South Korea.
- Light Attack:Scout-attack hybrids optimized for high-hot performance in Himalayan and Southeast Asian terrain.
- Advanced Armed:Next-generation platforms with unmanned teaming capability and directed energy weapon provisions.
Multi-role configurations dominate installed base. Heavy attack is where expansion concentrates as threat environments harden.
Technology:
Cost tiers separate legacy mechanical systems from digitally integrated architectures, with mid-tier hybrid upgrades capturing sustainment budgets in aging fleets.
- Fly-by-Wire:Digital flight control computers replace mechanical linkages, enabling automatic terrain-following and reducing pilot workload in nap-of-earth profiles. Australia's ARH Tiger replacement and India's LCH Prachand production lines mandate this architecture, eliminating hydromechanical suppliers from competitions.
- Weapon Systems:Helmet-mounted cueing systems and millimeter-wave fire control radars compress sensor-to-shooter timelines. China's military-civil fusion standards accelerate domestic production of these components, reducing reliance on French and Israeli imports for PLA attack helicopter fleets.
- Avionics:Integrated mission computers managing sensor fusion and datalink interoperability.
- Rotorcraft:Composite main rotor blades and bearingless hub designs rated for sustained dash speeds.
Weapon systems dominate installed base. Fly-by-wire is where expansion concentrates as legacy mechanical controls reach obsolescence thresholds.
End User:
Customer type determines procurement channel structure, with military forces operating through defense acquisition procedures while non-state actors navigate export control complexity.
- Military Forces:Nation-state armed services with fleet modernization mandates and indigenization requirements. India's Ministry of Defence and China's Central Military Commission direct attack helicopter procurement through state-owned production complexes, constraining foreign OEM access without local partnership structures.
- Law Enforcement:Paramilitary and border security agencies requiring armed reconnaissance for counter-insurgency. Myanmar's military and Philippine security forces sustain demand for light attack variants with thermal imaging and precision strike in jungle and maritime border environments.
- Government Agencies:Non-military state operators with disaster response and infrastructure protection mandates.
- Private Contractors:Security firms operating under government contract with restricted weapons certifications.
Military forces dominate installed base. Law enforcement is where expansion concentrates as internal security missions proliferate.
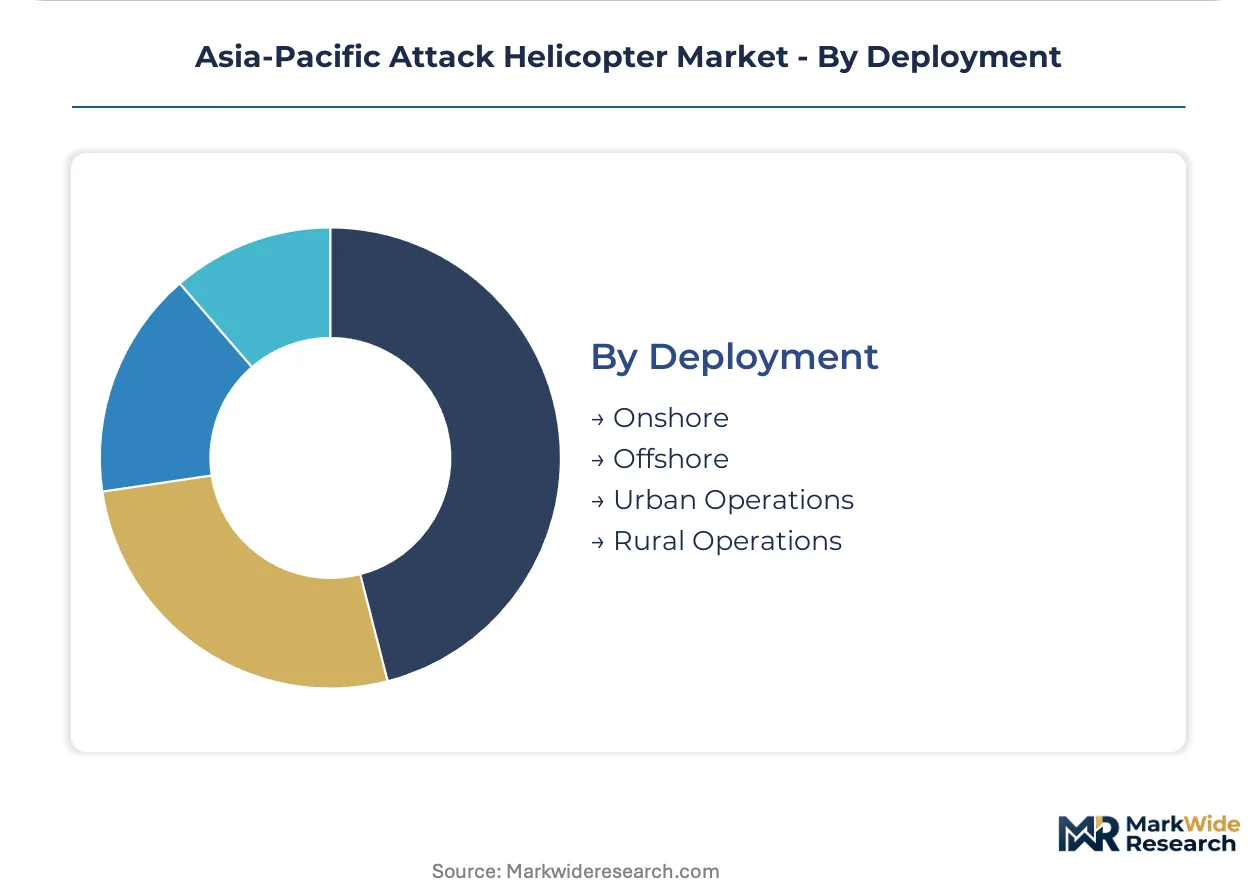
Deployment:
Geography of operation dictates platform specifications, with littoral and urban environments imposing distinct survivability and maneuverability requirements.
- Offshore:Maritime strike configurations with corrosion-resistant coatings, folding rotor blades, and anti-ship missile integration. Vietnam People's Navy and Indonesian Naval Aviation drive demand for deck-compatible attack helicopters addressing South China Sea patrol requirements.
- Urban Operations:Low-altitude maneuvering in dense electromagnetic environments with degraded visual reference. Rooftop landing limitations and wire strike hazards in megacities like Manila and Jakarta shape sensor and flight control specifications for Southeast Asian operators.
- Onshore:Conventional land-based deployment from fixed airfields with full logistics support.
- Rural Operations:Dispersed forward operating bases with austere maintenance infrastructure.
Onshore deployments dominate installed base. Offshore is where expansion concentrates as maritime territorial disputes intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in China's vertically integrated production complexes while Indian offset requirements compress foreign OEM margins. Southeast Asian procurement channels fragment across bilateral agreements rather than regional frameworks. National indigenization mandates reshape where assembly partnerships anchor.
India
The Ministry of Defence enforces 50 percent indigenous content floors through Defence Acquisition Procedure 2020, redirecting engine and transmission sourcing toward domestic factories. Hindustan Aeronautics Limited anchors production at Bangalore and Lucknow complexes. The Production Linked Incentive scheme rewards local manufacturing of transmission systems, attracting tier-one suppliers to Hyderabad clusters.
China
MIIT coordinates military-civil fusion standards for dual-use aerospace components, accelerating domestic rotor system and fire-control production. Aviation Industry Corporation of China controls vertical supply chains through Harbin and Changhe subsidiaries. Central Military Commission procurement directives prioritize self-sufficiency in next-generation attack helicopter programs.
Japan
METI's Three Principles on Arms Exports constrain Kawasaki Heavy Industries from establishing regional co-production partnerships. Domestic demand centers on maritime strike configurations for littoral patrol requirements. Tokyo-based defense contractors face limited market access without technology transfer waivers from the national regulator.
South Korea
Legacy fleet mechanical flight control obsolescence opens upgrade markets for digital avionics integration. The national defense acquisition program emphasizes multi-role platforms collapsing anti-tank and maritime strike into single fleet types. Seoul-area aerospace clusters concentrate fly-by-wire retrofit capabilities for regional operators.
Vietnam
Aging Mi-24 Hind airframe replacement creates procurement white space for manufacturers willing to establish maintenance partnerships under offset agreements. Maritime territorial disputes in the South China Sea drive deck-compatible attack helicopter demand. Hanoi negotiates fleet modernization through bilateral frameworks rather than multilateral procurement channels.
Asia-Pacific Attack Helicopter Market Competitive Environment
State-owned production complexes and Western defense primes split the market along indigenization fault lines. Chinese and Indian state entities control domestic procurement through captive supply chains, while American and European manufacturers navigate offset requirements to secure fleet access. Two strategic archetypes dominate: vertically integrated national champions and foreign OEMs licensing production to local partners. Competitive moves concentrate on technology transfer negotiations and in-country assembly partnerships rather than direct foreign military sales.
Among state-owned fabricators, Hindustan Aeronautics Limited and Aviation Industry Corporation of China occupy positions as national production anchors, each controlling domestic attack helicopter supply chains through integrated manufacturing complexes. Western primes including The Boeing Company and Lockheed Martin Corporation represent the foreign OEM archetype, restructuring operations around Indian and Southeast Asian offset mandates to maintain fleet participation. Kawasaki Heavy Industries Ltd. exemplifies the constrained regional specialist, limited by METI export principles from expanding partnership scope beyond domestic demand.
| Leading Market Players |
|---|
| Hindustan Aeronautics Limited |
| Aviation Industry Corporation of China |
| The Boeing Company |
| Textron Inc. |
| Kawasaki Heavy Industries Ltd. |
| Rostec State Corporation |
| Leonardo S.p.A. |
| Lockheed Martin Corporation |
| Airbus SE |
| Others |
Value Chain & Pricing Dynamics
Carbon-ceramic armor plating and radar-absorbent materials concentrate production in Japanese and South Korean specialty composites facilities, anchoring premium pricing in heavy attack helicopter configurations where survivability specifications command margin pools unavailable to standard multi-role platforms.
Pricing Analysis
Configured-to-order pricing for heavy attack variants with integrated electronic warfare suites and composite armor runs 40-60 percent above standard multi-role configurations. Price differentiation rests on certification grade for military airworthiness and customization level for mission-specific sensor packages. Cost compression in fly-by-wire retrofit markets is intensifying because mechanical flight control obsolescence has collapsed supplier alternatives. Law enforcement operators in Southeast Asia exhibit highest price sensitivity, while Australian and South Korean military forces absorb premiums for survivability-tier specifications.
Supply Chain Analysis
Extended payment terms from tier-one assemblers to turboshaft engine suppliers have become standard practice, with supply-chain finance facilities bridging cash-flow gaps for transmission system manufacturers. Geographic supply concentration centers on France, the United States, and Ukraine for qualified powerplants, while India and China build captive rotor system capabilities. Raw material dependencies include aerospace-grade carbon fiber, rare-earth magnet alloys, and high-temperature turbine coatings. Single-source vulnerability in Ukrainian engine supply channels creates structural risk. Distribution runs through state-owned production complexes in India and China, with offset-mandated partnerships governing Western OEM access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Attack helicopter procurement is shifting toward platform-ecosystem economics where sensor-to-shooter interoperability and unmanned teaming architectures determine fleet value, compressing standalone airframe margins and rewarding integrated system providers.
For Market Incumbents: Entrench through backward integration into transmission system production at Bangalore and Hyderabad clusters, securing PLI scheme benefits while locking out emerging tier-one suppliers. Deepen captive supply of fire-control radars to offset substitution pressure from armed unmanned aerial systems encroaching on reconnaissance missions. Control maintenance, repair and overhaul networks to capture performance-based logistics contract value as Australian and Japanese operators shift from spares purchasing to availability contracting.
For New Entrants and Emerging Players: Build out maintenance partnerships in Vietnam around aging Mi-24 Hind replacement cycles, exploiting Hanoi's preference for bilateral offset frameworks over multilateral procurement channels. Target deck-compatible configurations for Indonesian and Vietnamese naval aviation as South China Sea patrol requirements intensify. Pursue fly-by-wire retrofit opportunities in South Korea's legacy fleet as mechanical flight control obsolescence eliminates incumbent suppliers from upgrade competitions.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed aerospace component specialists holding Bangalore-based transmission system factories established to satisfy Indian indigenization mandates. Long-term viability hinges on positioning within platform-ecosystem value chains rather than standalone component supply, with unmanned teaming capability integration serving as the critical inflection indicator for next-generation program participation.
| Strategic Initiative | Industry Significance |
|---|---|
| Local Assembly Partnership | HAL's Bangalore complex anchors Indian indigenization compliance for foreign OEM fleet access. |
| Fly-by-Wire Retrofit Program | Australia's ARH Tiger replacement eliminates hydromechanical suppliers from digital avionics competitions. |
| Composite Armor Integration | Japanese carbon-ceramic facilities command premium pricing in heavy attack survivability tiers. |
| Maritime Strike Configuration | Vietnam's deck-compatible requirements open procurement white space for offset-willing manufacturers. |
| Unmanned Teaming Development | PLA next-generation programs prioritize self-sufficient military-civil fusion standards for sensor architecture. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with attack helicopter program managers at India's Ministry of Defence, procurement officers within China's Central Military Commission, platform engineers at Hindustan Aeronautics Limited and Aviation Industry Corporation of China subsidiaries, and aftermarket service heads at Australian and Japanese fleet operators. Secondary validation drew from Defence Acquisition Procedure filings, MIIT military-civil fusion standard disclosures, METI equipment transfer documentation, customs records for aerospace component trade flows, and SEC filings from Western defense primes. Bottom-up fleet inventory analysis was triangulated against top-down defense budget allocation data.
Calibration against historical procurement cycles and announced fleet modernization timelines shaped analytical framework construction across the analysis window. Segmentation dimensions modeled include product weight class, flight control architecture generation, end-user military versus law enforcement classification, and littoral versus land-based deployment profile. CAGRs were derived from regression analysis of defense expenditure trajectories and platform replacement schedules, with turboshaft engine supply availability and indigenization mandate enforcement timelines serving as critical forecast inputs.
Sensitivities concentrate around regulatory enforcement variance in Indian indigenous content floors, Ukrainian engine supply continuity, and armed unmanned aerial system substitution rates in light strike roles. Forecasts reflect documented assumptions regarding bilateral offset agreement proliferation and military-civil fusion standard adoption. Macroeconomic defense budget contraction, regulatory technology transfer restriction tightening, or autonomous platform capability breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Wireless in-Flight Entertainment Market
Aircraft
America Attack Helicopter Market
Aircraft
South Korea Aerospace and Defense Market
Aircraft
Military Aircraft Market
Aircraft
Fighter Aircraft Market
Aircraft
Middle-East and Africa Turboprop Aircraft Market
Aircraft
Europe Aircraft Manufacturing Market
Aircraft
GCC Business Jet Market
Aircraft
North America Light and Very Light Jets Market
Aircraft
Commercial Aircraft in-Seat Power System Market
Aircraft
Airplane and Helicopter Hangar Doors Market
Aircraft
Civil Helicopter Market
Aircraft
Middle East and Africa Military Helicopters Market
Aircraft
Flight Management Systems Market
Aircraft
High-Bypass Engine Nacelle External Aerodynamic Optimization Kits Market
Aircraft
Hybrid Aircraft Market