
 Asia-Pacific General Aviation Market | 2026-2036
Asia-Pacific General Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific General Aviation Market Outlook
Business jet premium cabin specifications is unwinding legacy single-aisle configurations across the Asia-Pacific. Gulfstream Aerospace leverages ultra-long-range platforms to sustain trans-Pacific nonstop positioning for high-net-worth buyers in Singapore and Sydney. Bombardier Inc. anchors the super-midsize segment with manufacturing scale that competes directly on delivery timelines against European rivals. Textron Aviation specializes in turboprop utility aircraft, dominating remote island and archipelago operations where jet runway infrastructure remains limited.
General aviation encompasses all civil aircraft operations excluding scheduled commercial airline services, typically involving fixed-wing aircraft below 19 passenger seats, rotorcraft, and unmanned aerial vehicles operating under visual or instrument flight rules with maximum takeoff weights generally under 12,500 pounds for light aircraft categories. These platforms serve commercial transport, emergency medical evacuation, flight training, and aerial survey functions where point-to-point flexibility outweighs hub-and-spoke efficiency. Fixed-wing aircraft occupy the largest revenue share across the Asia-Pacific, though rotary-wing platforms represent the fastest-growing category driven by offshore oil support and emergency services expansion in Indonesia and Vietnam. Charter Services within the End User dimension command premium yield pools, while FBO Services under Service Type face margin compression from airport concession fragmentation across secondary Chinese and Indian cities.
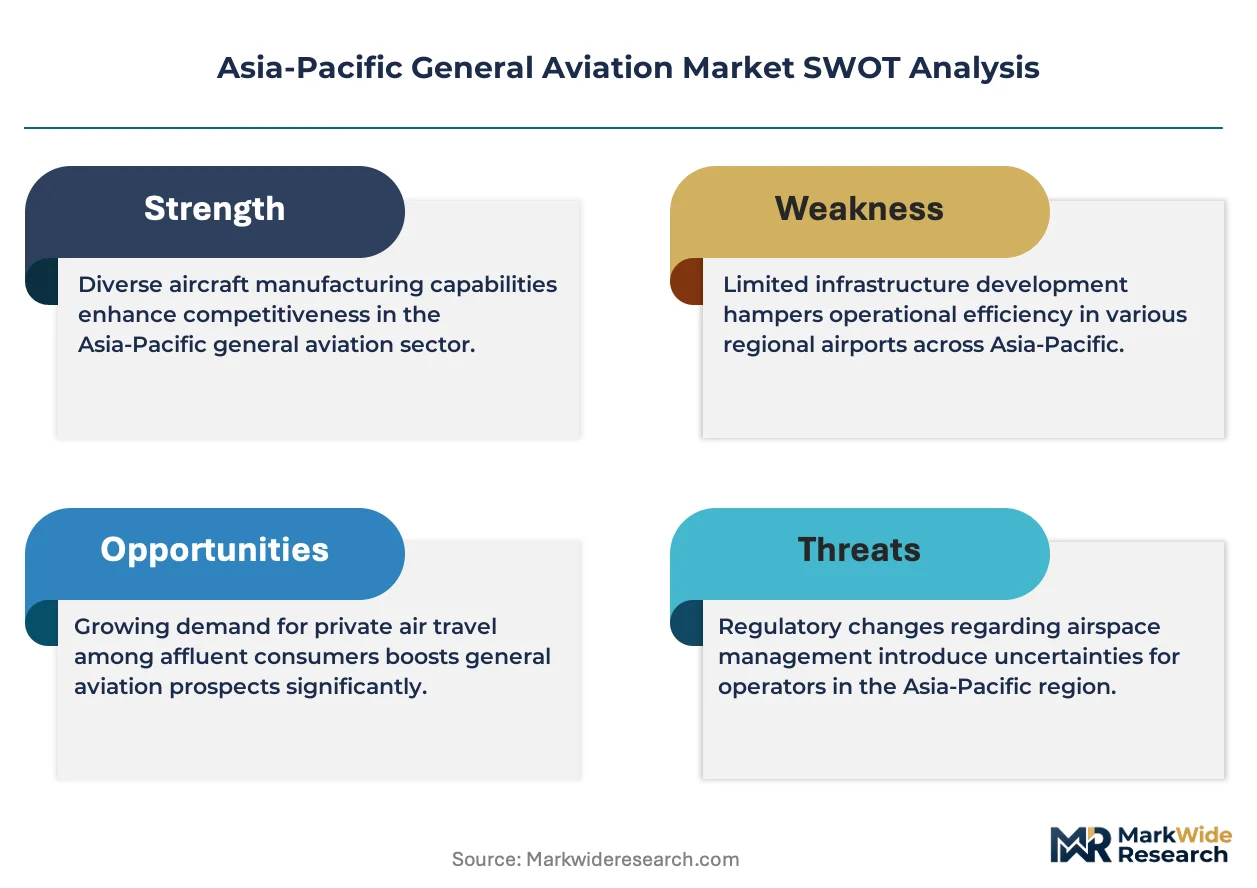
CAAC airworthiness directives and Australia's CASA Part 135 operational standards shape fleet renewal timelines and pilot certification requirements throughout the region. India's DGCA implements bilateral validation agreements with FAA and EASA that determine import eligibility for pre-owned business aircraft entering the domestic registry. Japan's MLIT maintains noise abatement corridors around Tokyo and Osaka that restrict general aviation slot access and influence aircraft selection toward quieter Stage IV powerplants. Stakeholders must weigh regulatory divergence against platform commonality when configuring multi-country fleet deployments.
Market Dynamics
CAAC certification reforms are dismantling airframe import barriers that previously constrained fleet modernization across China's general aviation sector, forcing regional operators to recalibrate procurement timelines against newly accessible manufacturer options.
Growth Catalysts
- Offshore energy expansion:Indonesia's Pertamina and Vietnam's Petrovietnam are expanding rotary-wing contracts for platform supply runs, pulling turbine helicopter demand across the Java Sea and Mekong Delta basins.
- MIIT airworthiness streamlining:China's Ministry of Industry and Information Technology compressed type certification timelines for light sport aircraft, enabling domestic assembly joint ventures to reach market faster than import-dependent competitors.
- Medical evacuation network gaps:Australia's Royal Flying Doctor Service and similar programs in Papua New Guinea are extending fixed-wing coverage into remote mining camps and island communities where road infrastructure remains absent.
Market Restraints
- Aviation turbine fuel volatility:Jet A-1 price spikes across Singapore and Hong Kong bunkering hubs compress operating margins for charter operators running high-cycle schedules.
- Pilot certification bottlenecks:Australia's CASA and India's DGCA maintain divergent multi-engine instrument rating requirements that fragment training pipeline efficiency across transnational fleet deployments.
- Heliport infrastructure scarcity:Vertical landing infrastructure in Philippine archipelago routes and Indonesian island chains remains concentrated around Manila and Jakarta, limiting point-to-point rotary flexibility.
Strategic Opportunities
- Unmanned cargo corridors:Civil Aviation Authority of Singapore's beyond-visual-line-of-sight permits for drone logistics are opening last-mile delivery routes across the Strait of Malacca shipping lanes.
- Electric propulsion convergence:Battery-electric and hydrogen fuel cell powertrains are converging with composite airframe manufacturing, enabling new entrant OEMs to bypass incumbent engine supplier relationships.
- Myanmar and Cambodia penetration:These underdeveloped general aviation markets present first-mover positioning for turboprop operators establishing tourism and resource exploration routes ahead of regulatory maturation.
Industry Challenges
- Maintenance technician scarcity:Airframe and powerplant certificated mechanics are concentrated in Sydney, Singapore, and Shanghai, leaving secondary hubs in Perth, Kuala Lumpur, and Ho Chi Minh City dependent on fly-in contract labor.
- Multi-registry compliance complexity:Operators running aircraft across Australian CASA, Chinese CAAC, and Japanese MLIT jurisdictions face fragmented continuing airworthiness management organization standards that duplicate documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific General Aviation Market |
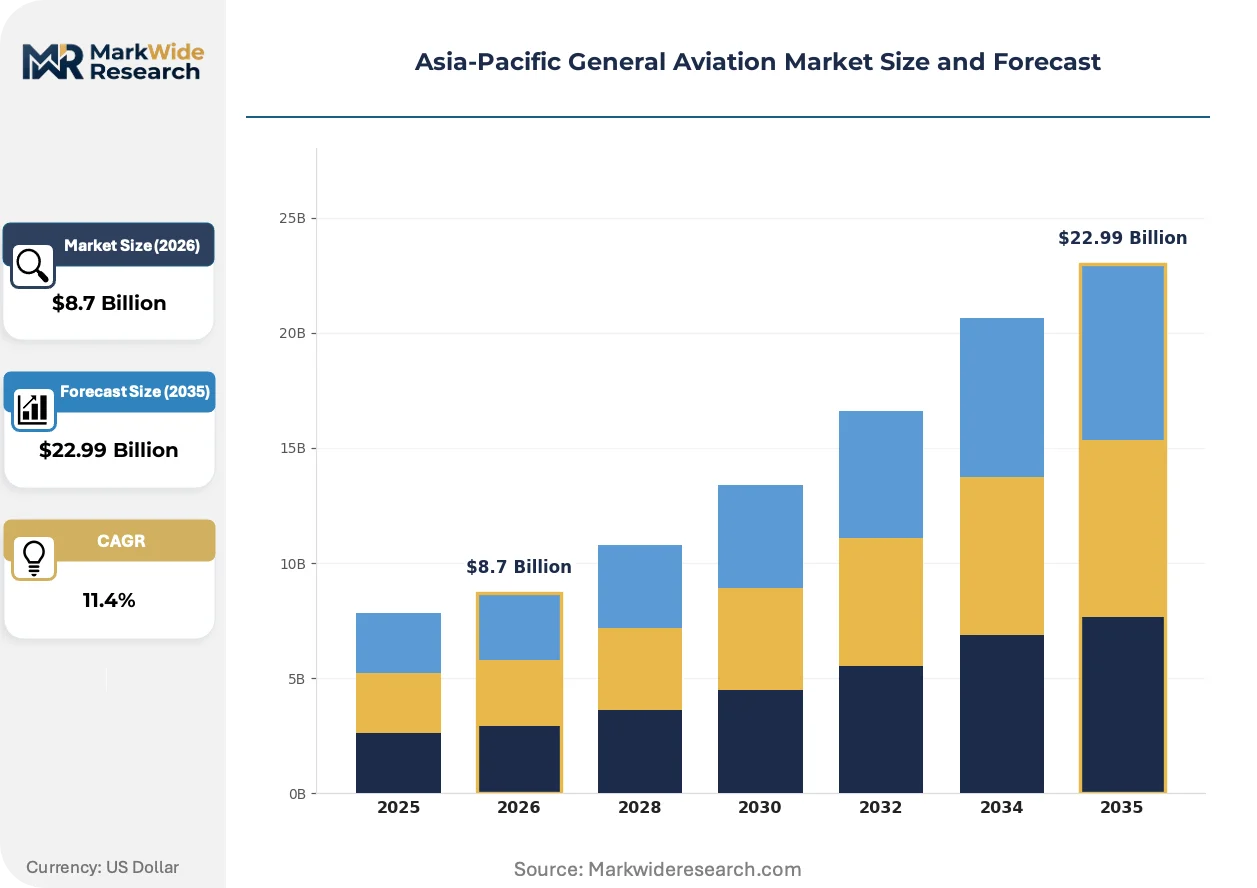
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
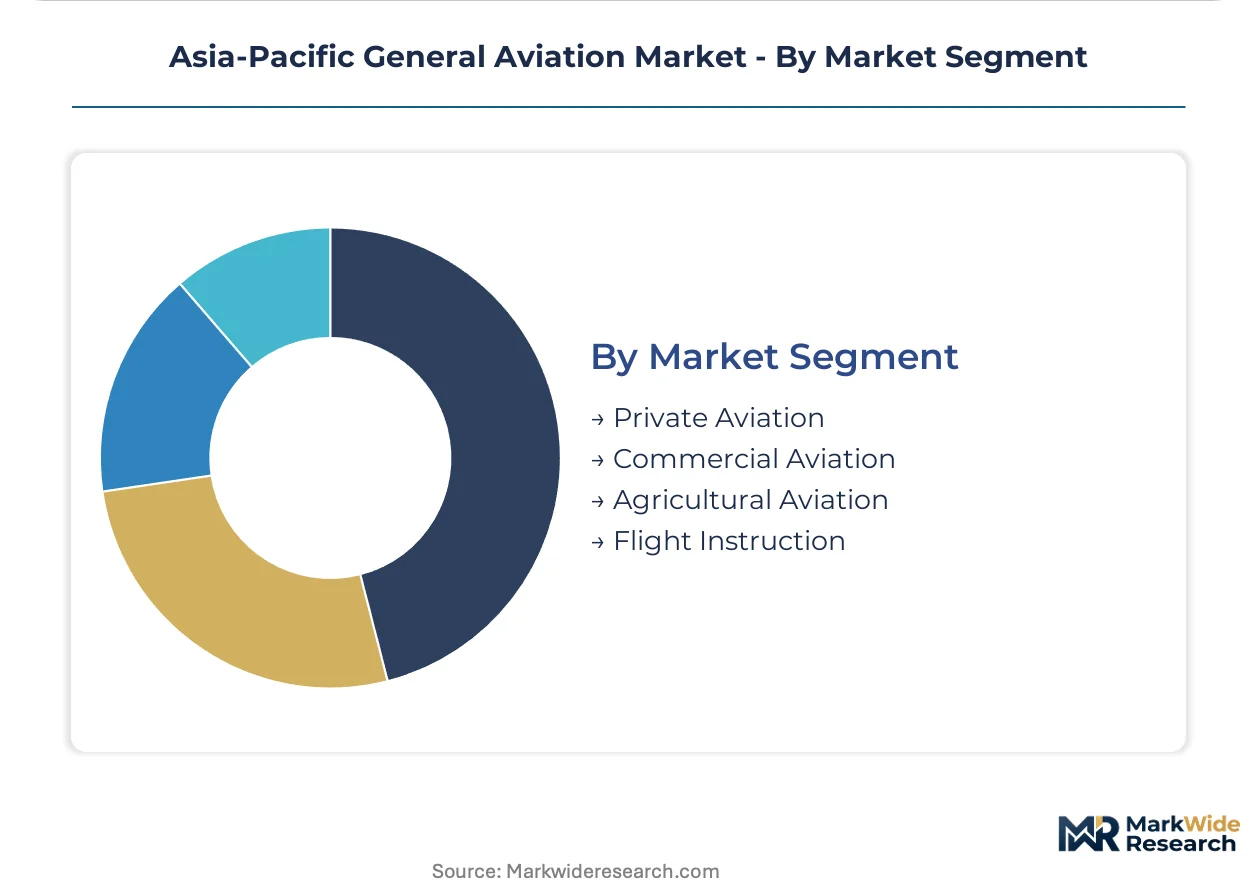
| Segmentation | Aircraft Type: Fixed-Wing, Rotary-Wing, UAV, Amphibious End User: Business Travel, Emergency Services, Tourism, Charter Services Service Type: Maintenance, Pilot Training, Charter Operations, FBO Services Market Segment: Private Aviation, Commercial Aviation, Agricultural Aviation, Flight Instruction |
| Companies Covered | Gulfstream Aerospace, Bombardier Inc., Textron Aviation, Dassault Aviation, Embraer, Airbus SE, General Dynamics Corporation, Leonardo S.p.A., Pilatus Aircraft, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific General Aviation Market Strategic Shifts
Digital avionics suites and sustainable propulsion architectures are compressing equipment replacement cycles across Asia-Pacific flight schools and corporate fleets, while regulatory harmonization efforts attempt to keep pace with cross-border operational complexity.
Advanced synthetic vision systems are bifurcating cockpit equipment specifications across the Asia-Pacific. These systems integrate terrain databases with real-time sensor fusion to eliminate visual meteorological condition limitations. High-net-worth owners in Singapore and Sydney are specifying them as standard on new deliveries, while flight training organizations in Melbourne and Bangkok adopt them for instrument rating curriculum compression. The technology is bifurcating premium cabin configurations from utility-focused platforms, creating distinct equipment tiers that manufacturers must maintain in parallel production lines.
Japan's MLIT noise abatement corridors around Tokyo Haneda and Osaka Itami are tightening Stage III aircraft operational windows, accelerating fleet transitions toward Stage IV powerplants. The industrial consequence is a secondary market displacement of older turbofan aircraft toward Southeast Asian registries with less stringent acoustic standards. Indonesian and Philippine charter operators are absorbing these displaced platforms for inter-island routes where noise exposure contours are less restrictive, creating a two-tier equipment flow across the region.
Fractional ownership models are displacing traditional whole-aircraft acquisition among mid-cap corporate flight departments across Australia and New Zealand. These programs unbundle capital commitment from utilization, appealing to mining services firms and agricultural conglomerates with seasonal demand spikes. The disruption is most visible in Queensland and Western Australia, where fly-in-fly-out workforce logistics previously required dedicated fleet capacity now satisfied through hourly access programs managed from Brisbane and Perth.
Asia-Pacific General Aviation Market Segmentation
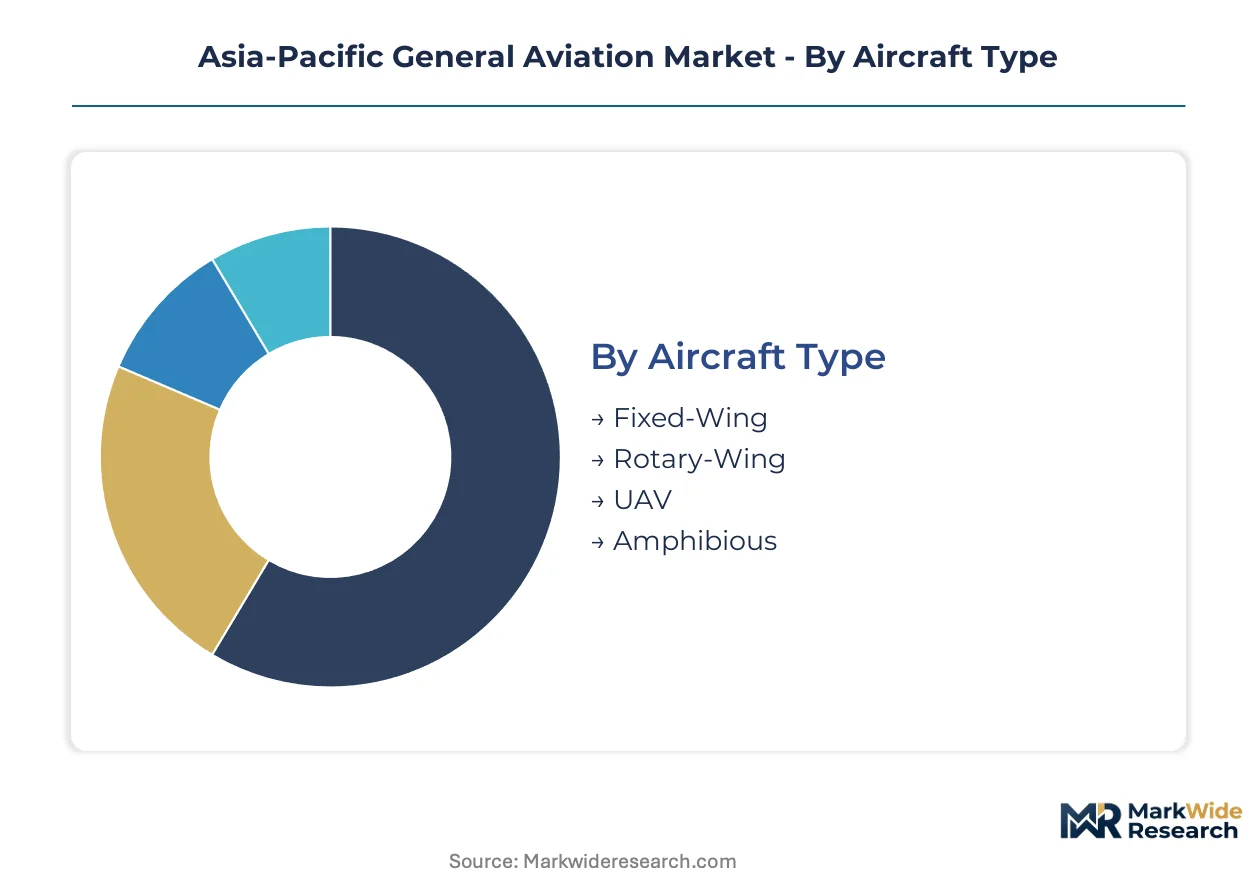
Segmentation reveals how regulatory divergence and infrastructure asymmetry fragment procurement patterns across Asia-Pacific general aviation. Platform selection, service bundling, and operational scope each respond to distinct geographic constraints and customer risk profiles.
Aircraft Type:
Rotary-wing platforms face the most acute substitution pressure from UAVs in surveillance and light cargo roles, while fixed-wing categories defend position through payload and range advantages.
- Fixed-Wing:Conventional piston and turboprop airframes dominate Australia's outback mining corridors and Papua New Guinea's island-hopping medical evacuation routes. Demand concentrates in Queensland's fly-in-fly-out workforce logistics, where CAOC Part 135 operators require rugged short-field performance.
- Rotary-Wing:Turbine helicopters serve Indonesia's offshore oil platforms and Vietnam's Mekong Delta energy infrastructure with vertical landing capability. Demand clusters around Pertamina and Petrovietnam contract awards, though heliport scarcity in secondary archipelago markets limits point-to-point flexibility.
- UAV:Beyond-visual-line-of-sight permits from Singapore's CAAS are opening last-mile cargo corridors across the Strait of Malacca.
- Amphibious:Seaplane configurations access coastal tourism routes in the Philippines and Maldives where runway construction faces environmental barriers.
Fixed-wing retains volume leadership; UAV holds the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive fleet acquisitions from hourly access models across the region's corporate and institutional buyers.
- Business Travel:Fractional ownership programs are displacing whole-aircraft acquisition among Australian mining services firms and New Zealand agricultural conglomerates with seasonal demand spikes. Queensland and Western Australia operations increasingly source hourly access from Brisbane and Perth management hubs.
- Emergency Services:Australia's Royal Flying Doctor Service extends fixed-wing coverage into remote mining camps where road infrastructure remains absent. Papua New Guinea's similar programs rely on turboprop reliability for island community access.
- Tourism:Coastal resort chains in Thailand and Indonesia charter amphibious and light fixed-wing platforms for inter-island guest transfers.
- Charter Services:Premium yield pools attract high-net-worth buyers in Singapore and Sydney seeking trans-Pacific nonstop positioning.
Emergency services anchor volume stability; business travel displays the most rapid model disruption.
Service Type:
Supply concentration in certified labor markets creates geographic chokepoints that fragment service delivery economics.
- Maintenance:Airframe and powerplant certificated mechanics concentrate in Sydney, Singapore, and Shanghai, leaving Perth, Kuala Lumpur, and Ho Chi Minh City dependent on fly-in contract labor. Indonesia's archipelago operations face particular downtime risk from technician mobilization delays.
- Pilot Training:Australia's CASA and India's DGCA maintain divergent multi-engine instrument rating requirements that fragment training pipeline efficiency across transnational fleet deployments. Melbourne and Bangkok flight schools adopt synthetic vision systems for curriculum compression.
- Charter Operations:High-cycle schedules face margin compression from Jet A-1 price volatility across Singapore and Hong Kong bunkering hubs.
- FBO Services:Airport concession fragmentation across secondary Chinese and Indian cities squeezes ground handling margins.
Maintenance claims the largest revenue share; pilot training exhibits the most pronounced regulatory fragmentation effects.
Market Segment:
Maturity gradients separate established regulatory frameworks from emerging compliance environments that shape first-mover positioning.
- Private Aviation:High-net-worth owners in Singapore and Sydney specify Stage IV powerplants and synthetic vision systems as standard on new deliveries. Japan's MLIT noise abatement corridors around Tokyo and Osaka accelerate this equipment transition.
- Commercial Aviation:Charter and air taxi operators absorb displaced Stage III turbofan aircraft from Japanese registries for Southeast Asian inter-island routes with less stringent acoustic standards.
- Agricultural Aviation:Queensland and Western Australia seasonal spraying operations source rotary-wing capacity through fractional programs rather than dedicated fleet investment.
- Flight Instruction:China's MIIT compressed type certification timelines for light sport aircraft enable domestic assembly joint ventures to reach training fleet markets faster than import-dependent competitors.
Commercial aviation maintains the broadest geographic footprint; private aviation generates the highest equipment specification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified airframe mechanics cluster in Sydney, Singapore, and Shanghai, leaving secondary hubs dependent on fly-in contract labor. This concentration shapes fleet deployment economics across the region's archipelago and outback corridors.
China
MIIT certification reforms are dismantling airframe import barriers and compressing type certification timelines for light sport aircraft. Domestic assembly joint ventures now reach training fleet markets faster than import-dependent competitors. Manufacturing activity concentrates in the Yangtze River Delta where composite airframe facilities serve both domestic and export demand.
Australia
Queensland's fly-in-fly-out mining corridors and Western Australia's coastal tourism routes drive fixed-wing turboprop demand. CASA Part 135 operational standards shape fleet renewal timelines and pilot certification requirements. The Royal Flying Doctor Service extends coverage into remote mining camps where road infrastructure remains absent.
Indonesia
Pertamina's offshore platform supply contracts pull turbine helicopter demand across the Java Sea basin. Heliport infrastructure scarcity outside Jakarta limits point-to-point rotary flexibility for archipelago operations. Secondary island chains remain underserved despite energy sector procurement scale.
Japan
MLIT noise abatement corridors around Tokyo Haneda and Osaka Itami tighten Stage III aircraft operational windows. High-net-worth owners specify Stage IV powerplants and synthetic vision systems as standard on new deliveries. This accelerates displacement of older turbofan aircraft toward Southeast Asian registries with less stringent acoustic standards.
Singapore
CAAS beyond-visual-line-of-sight permits for drone logistics open last-mile delivery routes across the Strait of Malacca shipping lanes. The city-state's bunkering hub status exposes charter operators to Jet A-1 price volatility that compresses high-cycle schedule margins. Premium yield pools attract trans-Pacific nonstop positioning demand from high-net-worth buyers.
Asia-Pacific General Aviation Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific general aviation sector. The market structure tiers around ultra-long-range platform specialists, super-midsize scale manufacturers, and utility-focused turboprop providers. Gulfstream Aerospace, Bombardier Inc., and Textron Aviation anchor distinct competitive positions. Dominant moves include portfolio diversification into sustainable propulsion architectures and geographic expansion through regional service center networks.
Among North American-based platform specialists, Gulfstream Aerospace and Bombardier Inc. occupy positions at the premium and super-midsize tiers respectively, while Textron Aviation exemplifies the utility-focused archetype. These manufacturers represent contrasting strategic postures: ultra-long-range positioning for trans-Pacific routes, manufacturing scale competing on delivery timelines, and specialized turboprop dominance where runway infrastructure remains limited. Each anchors a distinct equipment tier that shapes procurement patterns across Singapore, Sydney, and Southeast Asian corporate fleets.
| Leading Market Players |
|---|
| Gulfstream Aerospace |
| Bombardier Inc. |
| Textron Aviation |
| Dassault Aviation |
| Embraer |
| Airbus SE |
| General Dynamics Corporation |
| Leonardo S.p.A. |
| Pilatus Aircraft |
| Others |
Value Chain & Pricing Dynamics
Long-term rotary-wing service contracts between Pertamina and turbine helicopter operators lock in both airframe access and fuel cost visibility across Indonesia's offshore corridors. These take-or-pay structures insulate charter rates from Singapore bunkering hub volatility while committing operators to minimum utilization thresholds that shape fleet sizing decisions.
Pricing Analysis
Japan's MLIT noise abatement directives dictate the pricing tier structure for Stage IV powerplant upgrades across Tokyo and Osaka operational corridors. Three-tier pricing structure across premium, standard, and economy levels separates synthetic vision-equipped deliveries from basic avionics configurations and secondary-market Stage III acquisitions. Cost compression in the utility turboprop segment is intensifying because CAAC certification reforms enable domestic Chinese assembly joint ventures to undercut import-dependent competitors on delivery timelines. Mining services firms in Queensland and Western Australia display the highest price sensitivity, sourcing hourly access through fractional programs rather than whole-aircraft capital commitment.
Supply Chain Analysis
Strategic stockpiling of airframe components dominates maintenance economics where A&P certificated mechanic concentration in Sydney, Singapore, and Shanghai creates geographic chokepoints. Manufacturing feeds from composite airframe facilities in China's Yangtze River Delta, turbine engine production in the United States, and avionics suites from European suppliers. Single-source vulnerability runs through Indonesian archipelago operations dependent on fly-in contract labor from Perth and Kuala Lumpur. Distribution runs through regional service center networks anchored by manufacturer-authorized facilities in Brisbane, Singapore, and Shanghai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific general aviation sector is recovering from pandemic-induced fleet groundings and pilot certification backlogs. Offshore energy expansion across Indonesia and Vietnam provides the cyclical lift driving rotary-wing utilization rates.
For Market Incumbents: Consolidate maintenance technician training pipelines in secondary hubs like Perth and Ho Chi Minh City to reduce fly-in contract labor dependency. Acquire Stage III turbofan airframes displaced from Japanese registries for Southeast Asian inter-island charter deployment before regulatory maturation closes this arbitrage window. For New Entrants and Emerging Players: Lead with electric propulsion platforms targeting Singapore's CAAS beyond-visual-line-of-sight cargo corridors across the Strait of Malacca. Myanmar and Cambodia present the most penetrable geographies for turboprop tourism route establishment ahead of airworthiness framework formalization. For Investors and Strategic Acquirers: Fractional ownership program operators with established Brisbane and Perth management hubs offer the strongest acquisition profile for exposure to Australian mining services demand cyclicality. Monitor CAAC bilateral validation agreement expansion with FAA and EASA as the inflection signal for pre-owned business aircraft import eligibility liberalization across China.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Service Center Expansion | Manufacturer-authorized facilities in Perth and Kuala Lumpur reduce downtime risk from technician mobilization delays across archipelago operations. |
| Sustainable Propulsion Certification | Battery-electric and hydrogen fuel cell powertrain investments enable new entrant OEMs to bypass incumbent engine supplier relationships. |
| Synthetic Vision System Integration | Advanced avionics adoption by Melbourne and Bangkok flight schools compresses instrument rating curriculum timelines. |
| Fractional Ownership Platform Launch | Hourly access programs unbundle capital commitment from utilization for Queensland mining services firms with seasonal demand spikes. |
| Multi-Registry Compliance Harmonization | Unified continuing airworthiness management organization standards across CASA, CAAC, and MLIT jurisdictions reduce documentation duplication burdens. |
Study Parameters
Desk research of CAAC airworthiness directives, CASA Part 135 operational standards, and MIIT certification reform documentation preceded structured interviews with fleet operations directors, FBO services managers, and A&P certificated maintenance technicians. Primary fieldwork with charter operators in Singapore, Sydney, and Jakarta was cross-referenced against customs import records for pre-owned business aircraft registrations and offshore energy contract award databases. Bottom-up segment sizing across fixed-wing, rotary-wing, and UAV categories was triangulated against top-down manufacturer delivery disclosures.
Variance decomposition across aircraft type, end user, service type, and market segment dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from equipment replacement cycle analysis and regulatory reform implementation timelines. Forecast inputs incorporated heliport infrastructure development pipelines in the Philippine archipelago and noise abatement corridor expansion plans around Tokyo Haneda and Osaka Itami.
Forecasts assume regulatory continuity in CAAC, CASA, and MLIT jurisdictions; material policy shifts in bilateral validation agreements or Stage IV powerplant mandates would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Airplane Ailerons Market
Aircraft
Aeronautical Wind Tunnel Market
Aircraft
Multi-Band SATCOM and 6G-Ready Aircraft Radome Systems Market
Aircraft
Wireless in-Flight Entertainment Market
Aircraft
Flight Management Systems Market
Aircraft
Drone Turbojet Engine Market
Aircraft
Crashworthy Aircraft Seats Market
Aircraft
Active Air Deflector Market
Aircraft
North America Light and Very Light Jets Market
Aircraft
Southeast Asia Business Jet Market
Aircraft
Global Aircraft De-Icing Market
Aircraft
France Aviation Market
Aircraft
Winglets Market
Aircraft
Small Evtol Aircraft Market
Aircraft
Attack Helicopter Market
Aircraft
Europe Attack Helicopter Market