
 Military Helicopters Market | 2026-2036
Military Helicopters Market Size, Share, and Industry Trends Forecast 2026-2036
Military Helicopters Market Foresight
India's defense industrial base is tilting toward indigenous helicopter manufacturing under its Make-in-India framework. Lockheed Martin Corporation leverages its Sikorsky lineage to sustain dominance in heavy-lift naval platforms. Airbus Helicopters competes aggressively in European NATO markets with its NH90 and Tiger programs. Leonardo S.p.A. specializes in naval-optimized rotorcraft, anchoring Mediterranean fleet modernization efforts.
Military helicopters are powered rotary-wing aircraft designed for armed forces operations, typically featuring twin-turboshaft engines, articulated or hingeless rotor systems, and maximum takeoff weights ranging from light-class models below six metric tons to heavy-lift platforms exceeding twenty metric tons. Their primary purpose spans tactical transport, close air support, anti-submarine warfare, search and rescue, and medical evacuation in contested or denied environments. Attack Helicopters command premium pricing due to integrated targeting suites and armor-penetrating munitions, while Transport Helicopters generate volume through multi-role fleet standardization. Reconnaissance Helicopters are gaining technology investment as unmanned teaming architectures mature, though Utility Helicopters remain the largest installed base for sustainment and upgrade contracts.
The FAA and EASA enforce stringent rotorcraft airworthiness standards that govern structural integrity, vibration tolerance, and system redundancy for military type certifications. India's DGCA and CEMILAC align indigenous platforms like the HAL Dhruv and Light Combat Helicopter with MIL-STD-810 environmental testing and DEF-STAN crashworthiness benchmarks. The EU AI Act and emerging autonomous flight regulations will reshape avionics development priorities as manufacturers integrate sensor fusion and decision-support algorithms. Stakeholders must weigh sovereign production requirements against interoperability standards when positioning for next-generation vertical lift procurements.
Market Dynamics
Defense procurement agencies are consolidating fleet architectures around modular open systems, compressing supplier ecosystems while demanding faster upgrade cycles for electronic warfare and survivability packages.
Growth Catalysts
- FAA and EASA airworthiness mandates:Stricter certification requirements for crash-resistant fuel systems and fly-by-wire architectures are accelerating platform replacement cycles among NATO operators.
- Counter-insurgency mission profiles:Special Operations Units across member states are expanding rotary-wing fleets for rapid response and urban warfare scenarios.
- Heavy-lift naval modernization:Carrier-based anti-submarine and vertical replenishment missions are driving demand for twin-turboshaft platforms with integrated targeting suites.
Market Restraints
- Titanium and composite input volatility:Articulated rotor hub assemblies and armor-penetrating munitions casings depend on aerospace-grade alloys subject to supply concentration in limited smelting jurisdictions.
- Dual-use export control friction:ITAR and EAR classifications restrict technology transfer for sensor fusion and decision-support algorithms, lengthening sales cycles for multinational programs.
- Interoperability standard gaps:Divergent national requirements for communications suites and datalink protocols fragment production runs and dilute economies of scale.
Strategic Opportunities
- Unmanned teaming architectures:Manned-unmanned teaming protocols for reconnaissance and electronic attack missions are opening white space in avionics and autonomous flight software.
- India's Make-in-India framework:Indigenous production incentives for the HAL Dhruv and Light Combat Helicopter are creating offset partnership opportunities for foreign subsystem suppliers.
- EU AI Act compliance pathways:Emerging autonomous flight regulations are reshaping development priorities for sensor fusion and decision-support algorithms in next-generation vertical lift programs.
Industry Challenges
- Flight control software certification timelines:MIL-STD-810 environmental testing and DEF-STAN crashworthiness benchmarks for fly-by-wire systems extend development schedules by 18-36 months.
- Legacy platform sustainment complexity:Aging Black Hawk and Seahawk fleets require reverse engineering of obsolete avionics components while parallel next-generation development strains engineering bandwidth.
- Skilled rotorcraft engineer scarcity:Hingeless rotor dynamics and vibration tolerance specialization pools are concentrated among retiring workforce cohorts with limited pipeline replenishment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Helicopters Market |
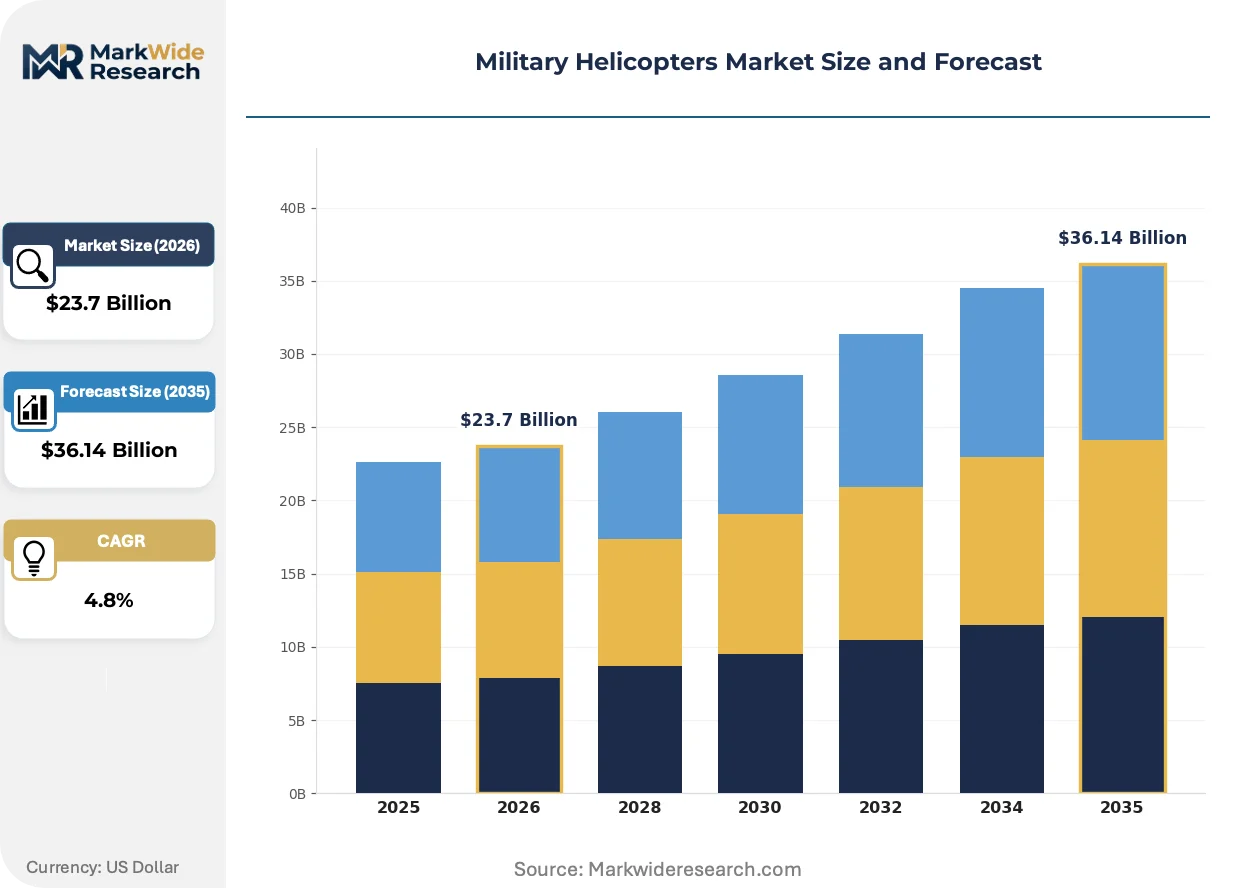
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $36.14 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Attack Helicopters, Transport Helicopters, Reconnaissance Helicopters, Utility Helicopters Technology: Avionics Systems, Rotorcraft Technologies, Weapon Systems, Navigation Systems End User: Military Forces, Defense Contractors, Government Agencies, Special Operations Units Deployment: Onshore, Offshore, Land-Based, Ship-Based |
| Companies Covered | Lockheed Martin Corporation, Sikorsky Aircraft Corporation, The Boeing Company, Airbus Helicopters, Leonardo S.p.A., Bell Textron Inc., Russian Helicopters, Hindustan Aeronautics Limited, NHIndustries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Helicopters Market Shifts & Advancements
Rotorcraft engineering is pivoting toward survivability-centric architectures, with electronic warfare integration and autonomous flight capabilities displacing incremental performance upgrades as the primary competitive differentiators.
Fly-by-wire flight control systems are migrating from mechanical linkages to digital architectures with triple-redundant processing. Attack Helicopter programs across NATO members are adopting these platforms for terrain-following and target-handoff precision. The shift is compressing supplier tiers as mechanical actuator specialists lose position to integrated avionics houses.
EU AI Act provisions on autonomous decision-making are forcing avionics manufacturers to document algorithmic transparency for sensor fusion systems. The regulation mandates human-on-the-loop protocols for armed rotorcraft, adding software validation layers. Reconnaissance Helicopter segments are responding with modular architectures that partition autonomous functions from weapons release authority.
Defense agencies are unbundling platform acquisition from through-life support contracts. Fleet operators now procure airframes and sustainment separately, with performance-based logistics replacing fixed-price spares agreements. This pattern is most visible in United States Army and Navy modernization programs, where contractors compete for availability guarantees rather than parts delivery.
Military Helicopters Market Segmentation
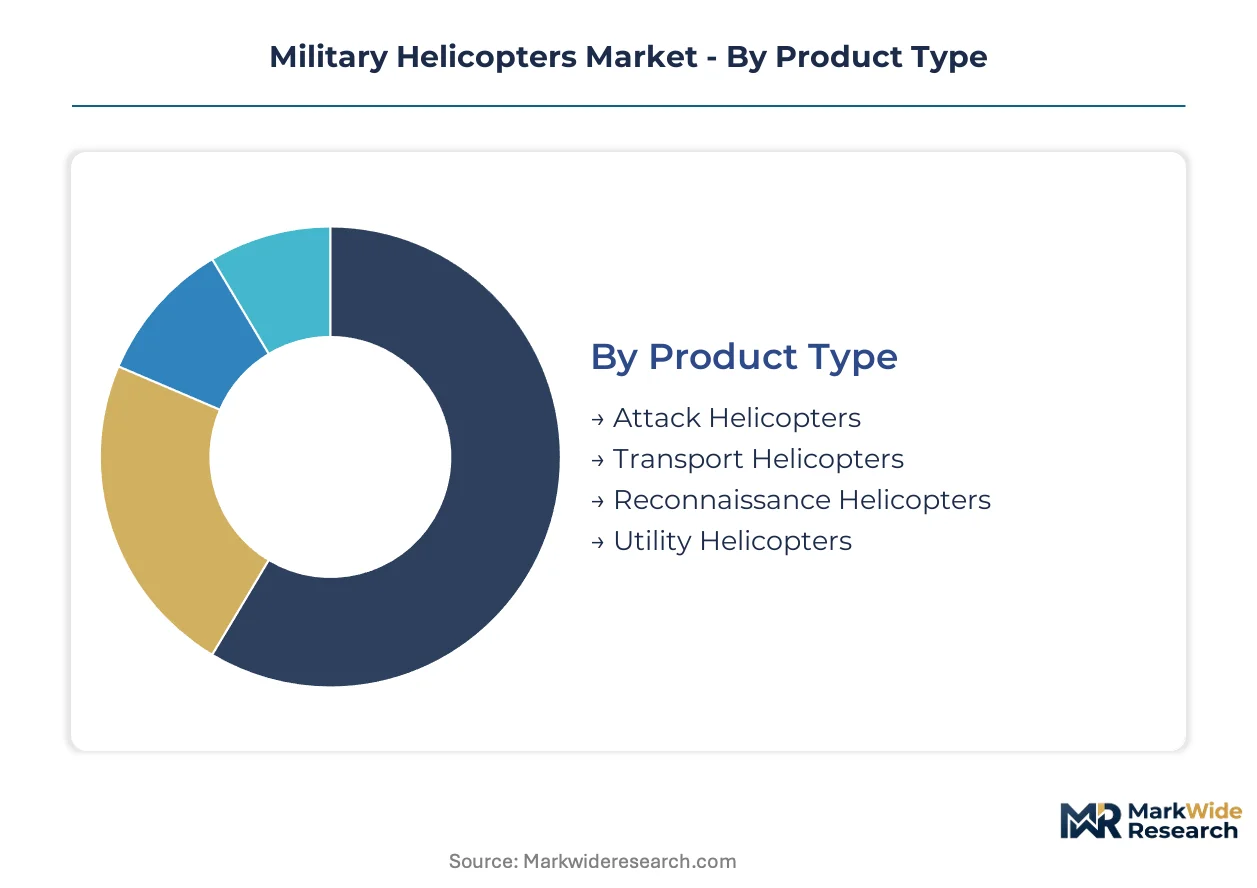
Rotorcraft procurement cycles vary dramatically by mission profile, with attack platforms turning over every 25-30 years while utility fleets stretch to 40 years through incremental avionics upgrades. Understanding these divergent replacement rhythms helps suppliers align development pipelines with actual contract windows.
Product Type:
Attack Helicopters compress replacement cycles through combat attrition and technology obsolescence, while Utility Helicopters sustain decades of service life through modular subsystem refreshes.
- Attack Helicopters:Twin-turboshaft platforms integrate armor-penetrating munitions and targeting suites for close air support missions. Demand concentrates in United States Army modernization programs replacing aging fleets with fly-by-wire architectures under stricter FAA and EASA crashworthiness mandates.
- Transport Helicopters:Heavy-lift configurations with maximum takeoff weights exceeding twenty metric tons enable tactical troop movement and vertical replenishment. NATO members in Europe are expanding fleets for rapid response scenarios, though titanium supply volatility constrains articulated rotor hub production.
- Reconnaissance Helicopters:Sensor-fusion platforms for manned-unmanned teaming protocols.
- Utility Helicopters:Multi-role workhorses dominating installed base volumes for sustainment contracts.
Utility Helicopters dominate installed base. Attack Helicopters is where expansion concentrates.
Technology:
Cost tiers separate integrated avionics houses from mechanical subsystem suppliers, with digital architectures commanding premium positioning against legacy actuator specialists.
- Avionics Systems:Triple-redundant fly-by-wire processing architectures displace mechanical linkages. United States Navy carrier-based programs are driving demand for terrain-following and target-handoff precision, compressing supplier tiers as mechanical specialists lose position.
- Rotorcraft Technologies:Articulated and hingeless rotor systems with vibration tolerance specifications. India's HAL Dhruv and Light Combat Helicopter programs under Make-in-India framework are creating offset partnerships for foreign subsystem suppliers in this category.
- Weapon Systems:Integrated targeting suites and munitions release authority systems.
- Navigation Systems:Datalink protocols and communications suites facing interoperability fragmentation.
Avionics Systems captures the steepest expansion trajectory. Rotorcraft Technologies anchors long-term sustainment revenue.
End User:
Customer type determines procurement authority and contract structure, with military forces owning platform acquisition while special operations units drive niche capability requirements.
- Military Forces:Army and Navy services with consolidated fleet architectures and modular open systems mandates. United States modernization programs are unbundling platform acquisition from through-life support, with contractors competing for availability guarantees rather than parts delivery.
- Special Operations Units:Rapid response and counter-insurgency mission profiles across NATO members. These units are expanding rotary-wing fleets for urban warfare scenarios, though ITAR and EAR classifications restrict technology transfer for sensor fusion systems.
- Defense Contractors:Prime integrators managing subsystem supplier ecosystems.
- Government Agencies:Border patrol and coast guard operators with multi-role requirements.
Military Forces dominate procurement volume. Special Operations Units is where capability differentiation concentrates.
Deployment:
Application environment shapes engineering specifications, with ship-based platforms requiring corrosion resistance and deck-handling features absent from land-based configurations.
- Ship-Based:Naval-optimized rotorcraft with anti-submarine warfare and vertical replenishment capabilities. Mediterranean fleet modernization efforts led by Italy and France are driving demand for twin-turboshaft platforms with integrated targeting suites.
- Land-Based:Tactical transport and medical evacuation platforms for contested environments. United States Army programs are replacing aging Black Hawk fleets with next-generation rotorcraft featuring crash-resistant fuel systems.
- Onshore:Coastal patrol and search and rescue configurations.
- Offshore:Extended-range platforms for blue-water operations.
Land-Based deployments dominate installed base. Ship-Based configurations is where modernization investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aerospace-grade titanium smelting and composite fabrication clusters concentrate in five national jurisdictions, each anchoring distinct supply chain tiers for rotorcraft manufacturing.
United States
Army and Navy modernization programs are replacing aging Black Hawk and Seahawk platforms with next-generation rotorcraft featuring fly-by-wire architectures. FAA airworthiness mandates for crash-resistant fuel systems are accelerating platform replacement cycles among Pentagon operators. Connecticut's Sikorsky lineage and Texas-based Bell operations anchor heavy-lift and attack helicopter production corridors.
India
Defense procurement is tilting toward indigenous manufacturing under the Make-in-India framework for HAL Dhruv and Light Combat Helicopter programs. CEMILAC and DGCA align domestic platforms with MIL-STD-810 environmental testing and DEF-STAN crashworthiness benchmarks. Bangalore's aerospace cluster is generating offset partnership opportunities for foreign subsystem suppliers in rotorcraft technologies.
France
Airbus Helicopters competes aggressively in European NATO markets with NH90 and Tiger program deliveries. EU AI Act provisions on autonomous decision-making are forcing avionics manufacturers to document algorithmic transparency for sensor fusion systems. Marignane's engineering base drives naval-optimized rotorcraft development for Mediterranean fleet modernization.
Italy
Leonardo S.p.A. specializes in naval-optimized rotorcraft, anchoring Mediterranean fleet modernization efforts with twin-turboshaft platforms. EASA certification requirements for fly-by-wire systems are compressing supplier tiers as mechanical actuator specialists lose position. Cascina Costa's manufacturing complex concentrates on ship-based anti-submarine and vertical replenishment configurations.
United Kingdom
Special Operations Units are expanding rotary-wing fleets for counter-insurgency and rapid response missions in urban warfare scenarios. DEF-STAN crashworthiness benchmarks govern structural integrity and vibration tolerance for military type certifications. Yeovil's Westland heritage site sustains engineering specialization in hingeless rotor dynamics and vibration tolerance.
Military Helicopters Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in rotor hub assemblies, avionics processing architectures, and targeting suite subsystems. The vendor base stratifies around three tiers: primes managing end-to-end program delivery, mid-tier subsystem houses controlling fly-by-wire and sensor fusion technologies, and specialized fabricators supplying titanium alloy components. Consolidation pressure is intensifying as defense agencies unbundle platform acquisition from through-life support contracts. Two dominant competitive moves are reshaping positioning: strategic partnerships for indigenous production offsets under India's Make-in-India framework, and technology licensing arrangements to navigate ITAR and EAR export control restrictions.
Among US-based primes, Lockheed Martin Corporation and The Boeing Company occupy positions as system-tier anchors, while Airbus Helicopters and Leonardo S.p.A. exemplify European state-linked aerospace champions. Bell Textron Inc. represents the specialized attack and utility helicopter archetype. These named entities serve as structural reference points for understanding how geographic origin and corporate lineage shape competitive access to NATO procurement channels and sovereign production requirements.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Sikorsky Aircraft Corporation |
| The Boeing Company |
| Airbus Helicopters |
| Leonardo S.p.A. |
| Bell Textron Inc. |
| Russian Helicopters |
| Hindustan Aeronautics Limited |
| NHIndustries |
| Others |
Supply & Pricing Matrix
The Rotterdam-Texas maritime corridor's freight volatility amplifies cost spreads between titanium alloy suppliers in Russia and aerospace-grade composite fabricators in Japan, compressing margins for European rotorcraft primes while enabling price premiums for crash-resistant fuel system integrators serving FAA-certified platforms.
Pricing Analysis
FAA and EASA airworthiness mandates dictate the pricing tier structure across the Military Helicopters Market, separating fly-by-wire certified platforms from mechanical linkage legacy systems. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and integrated targeting suite complexity. Cost compression in economy-tier utility helicopter segments is intensifying because India's Make-in-India framework subsidizes indigenous assembly. Special Operations Units exhibit lowest price sensitivity due to mission-critical requirements, while government agencies with border patrol mandates drive hardest bargain negotiations.
Supply Chain Analysis
Aerospace-grade titanium sponge feeds from concentrated smelting operations in Russia, Japan, and Kazakhstan, with hingeless rotor hub assemblies drawing from these feedstocks. Articulated rotor systems rest on carbon fiber prepregs sourced from Toray's Japanese plants and Hexcel's US facilities. Single-source vulnerability in titanium alloy supply creates procurement risk for NATO members amid export licensing friction. Distribution runs through prime integrator channels with performance-based logistics contracts displacing fixed-price spares agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Military Helicopters Market fragments around unmanned teaming architectures and sovereign production mandates, with defense agencies unbundling platform acquisition from sustainment creating niche entry points for subsystem specialists.
For Market Incumbents: Pre-empt displacement by mechanical actuator specialists through accelerated certification of triple-redundant fly-by-wire architectures under EU AI Act transparency requirements. Lockheed Martin Corporation and Airbus Helicopters should deepen backward integration into sensor fusion algorithm development to offset ITAR transfer restrictions compressing multinational program margins. Anchor capacity in India's Bangalore aerospace cluster to capture Make-in-India offset partnerships before foreign subsystem suppliers consolidate positions. For New Entrants and Emerging Players: Mid-tier avionics houses in South Korea and Israel represent the most penetrable entry point for fly-by-wire processing architectures displaced from NATO prime supply chains. Unmanned teaming protocol development for reconnaissance helicopter segments offers white-space positioning without direct confrontation with Sikorsky-Bell duopoly in heavy-lift naval platforms. Go-to-market through technology licensing arrangements navigates EAR classification barriers while preserving algorithmic IP control. For Investors and Strategic Acquirers: Specialist firms with CEMILAC certification for HAL Dhruv subsystem integration command scarcity premia as India's indigenous production accelerates. Long-term viability hinges on positioning for through-life support contract unbundling, where availability guarantees generate recurring revenue streams superior to lumpy platform sales. Monitor FAA certification timeline compression for fly-by-wire systems as inflection signal for engineering bandwidth constraints among incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Fly-by-Wire Certification Investment | FAA and EASA mandates accelerate platform replacement cycles among NATO operators. |
| Make-in-India Offset Partnership | CEMILAC alignment creates captive supply positions for foreign rotorcraft technology suppliers. |
| Unmanned Teaming Protocol Development | EU AI Act human-on-the-loop requirements reshape autonomous flight software validation layers. |
| Performance-Based Logistics Contracting | United States Army unbundling separates airframe procurement from availability guarantee competition. |
| Titanium Supply Diversification | Russian smelting concentration drives Japanese and Kazakh alternative qualification programs. |
Research Methodology
Operator-level perspectives from Army aviation program officers, Navy carrier air wing commanders, CEMILAC certification engineers, and defense procurement agency contract specialists anchored the qualitative base for this study. Primary interview intelligence combined with secondary validation from FAA type certification databases, EASA airworthiness directives, Pentagon budget justification documents, and Indian defense ministry offset disclosure filings. Bottom-up fleet replacement modeling and top-down defense expenditure allocation analysis triangulated volume and value estimates across the projection horizon.
Scenario-bracketing framed the analytical approach, with optimistic and constrained trajectories bounding the central case across the analysis window. Segmentation dimensions modeled include mission profile taxonomy, technology architecture tier, end-user procurement authority, and deployment environment specification. CAGRs derived from fitted trend extrapolation adjusted for platform replacement cycle nonlinearity and regulatory mandate acceleration effects. Forecast inputs incorporated titanium alloy price volatility indices and skilled rotorcraft engineer pipeline constraints.
Practitioners should monitor FAA certification timeline extensions and EU AI Act implementation rulings for early signals of forecast revision. Cross-checking against Pentagon program budget execution rates and HAL production schedule disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
US Aircraft Windshield Wiper and Washer System Market
Aircraft
Evtol (Electric Vertical Takeoff and Landing) Airplane Market
Aircraft
Airship Market
Aircraft
Europe Aircraft Engines Market
Aircraft
Aircraft Anchoring System Market
Aircraft
Global Commercial Aircraft Disassembly Market
Aircraft
Southeast Asia Business Jet Market
Aircraft
Aircraft Galley Equipment Market
Aircraft
North America Helicopters Market
Aircraft
Aircraft Control Surface Market
Aircraft
Aerospace Turbojet Market
Aircraft
Light Sport Aircraft (LSA) Market
Aircraft
Wireless in-Flight Entertainment Market
Aircraft
Wing Inspection and Taxi Lighting Upgrade Kits Market
Aircraft
Europe Helicopters Market
Aircraft
Enhanced Flight Vision Systems ( EFVS) Market