
 Middle-East and Africa Freighter Aircraft Market | 2026-2036
Middle-East and Africa Freighter Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Freighter Aircraft Market Foresight
Arab Gulf cargo operators is decoupling from traditional wet-lease dependence by building owned freighter fleets. The Boeing Company anchors wide-body conversion programs across Middle Eastern maintenance hubs. Israel Aerospace Industries Ltd specializes in narrow-body freighter modifications for African short-haul networks. Airbus SE competes through A330P2F offerings targeting high-volume routes between Dubai and Sub-Saharan gateways.
Freighter aircraft denote commercial airframes engineered or converted for dedicated cargo transport, typically featuring reinforced floors, wide cargo doors, and payload capacities spanning below 20 tons to above 60 tons. These platforms serve pharmaceutical cold chains, automotive parts, and express parcel networks where speed outweighs maritime economics. Wide-body conversions command premium lease rates on long-haul trunk routes, while narrow-body freighters penetrate secondary African cities with limited runway infrastructure. The 40 to 60 tons capacity band captures the fastest expansion as e-commerce volumes strain existing belly-hold capacity on passenger services.
The UAE's General Civil Aviation Authority and South Africa's Civil Aviation Authority enforce divergent certification timelines for supplemental type certificates, fragmenting conversion approval workflows. Military end users in the region bypass commercial lease structures through direct procurement, reshaping delivery model mix. Stakeholders must monitor how Saudi Arabia's General Authority of Civil Aviation harmonizes freighter noise regulations with European EASA benchmarks.
Market Dynamics
The Middle-East and Africa freighter aircraft market pivots on the tension between belly-hold capacity constraints on passenger wide-bodies and the operational imperative for dedicated main-deck cargo platforms. This structural squeeze intensifies as Gulf carriers prioritize premium passenger cabins over freight-forwarder contracts.
Growth Catalysts
- E-commerce logistics corridors:Express parcel networks between Dubai and Lagos strain existing belly-hold capacity. Dedicated freighter deployment on this trunk route accelerates fleet renewal cycles.
- GCAA supplemental type certificate streamlining:The UAE's General Civil Aviation Authority has compressed approval timelines for Boeing 737-800BCF conversions. Maintenance hubs in Sharjah report faster turnaround on narrow-body freighter entry-into-service.
- Pharmaceutical cold chain infrastructure:Temperature-controlled cargo demand from Johannesburg's vaccine distribution networks pulls wide-body freighter capacity from European transshipment points.
Market Restraints
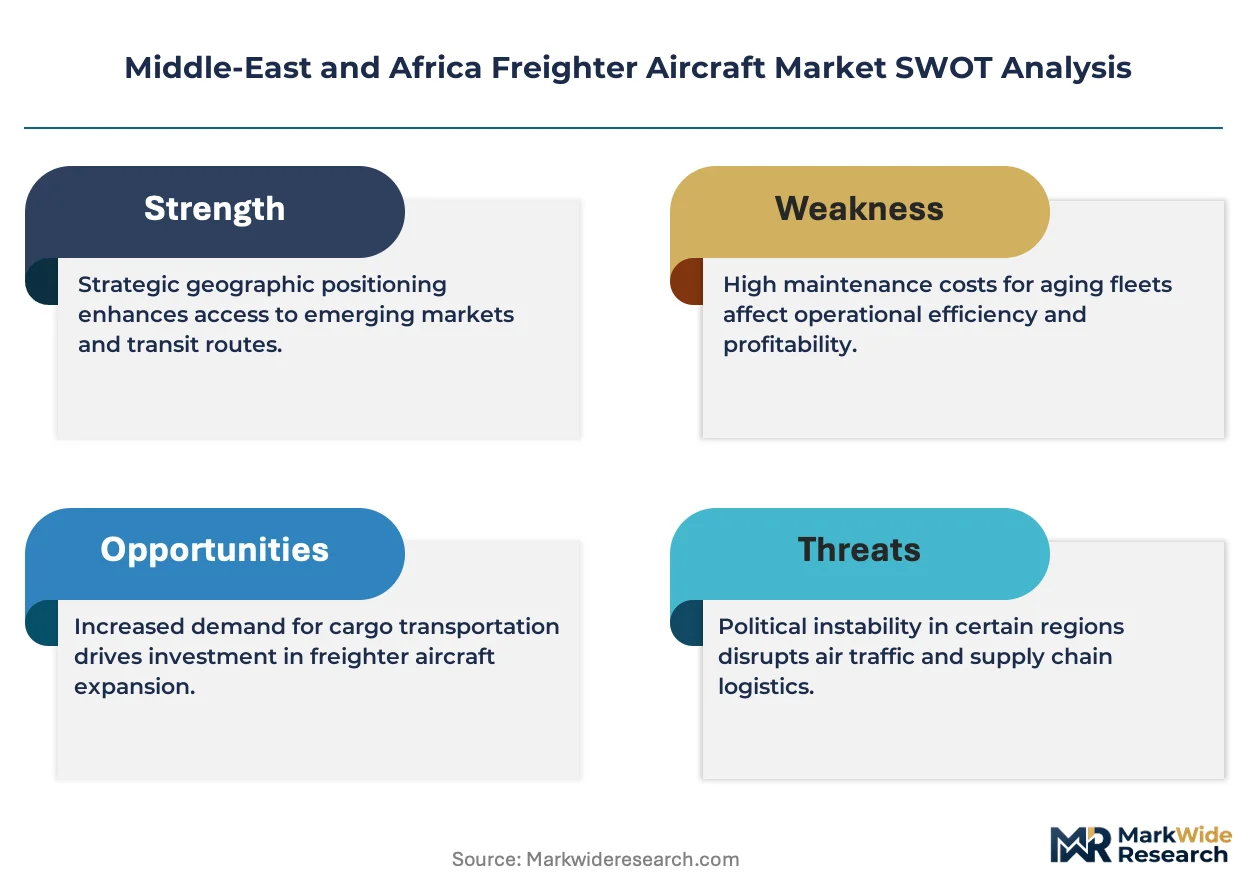
- Feedstock scarcity for conversions:Suitable passenger airframe availability concentrates in lessor portfolios dominated by Dublin and Singapore-based asset managers. Middle Eastern conversion houses face extended sourcing timelines.
- Divergent certification timelines:South Africa's Civil Aviation Authority operates on parallel supplemental type certificate review tracks distinct from UAE GCAA workflows. Dual-registered operators absorb compliance duplication costs.
- Jet fuel price volatility:Kerosene cost spikes compress operating margins on thinly-traded African secondary routes where yield premiums cannot absorb fuel surcharges.
Strategic Opportunities
- Ethiopian cargo hub expansion:Addis Ababa's geographic positioning between Asian manufacturing and African consumption remains underutilized for freighter technical stops. Cold chain infrastructure investment would capture perishable transshipment volumes.
- Saudi GACA-EASA noise harmonization:Anticipated regulatory alignment would enable European-registered converted freighters to operate into Kingdom airports without acoustic retrofit penalties.
- Drone-to-freighter intermodal pilots:Last-mile unmanned aerial vehicle networks in Rwanda and Ghana converge with fixed-wing freighter trunk routes. Hybrid distribution models reduce ground transport leakage in landlocked territories.
Industry Challenges
- Supplemental type certificate engineering talent scarcity:Conversion design organizations in the region compete for finite stress analysis and systems integration specialists. Dubai Aerospace Enterprise and Israel Aerospace Industries poach from overlapping labor pools.
- Legacy avionics integration complexity:Older-generation passenger airframes targeted for conversion require cockpit modernization to meet GCAA minimum navigation performance specifications. Software certification delays push delivery dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Freighter Aircraft Market |
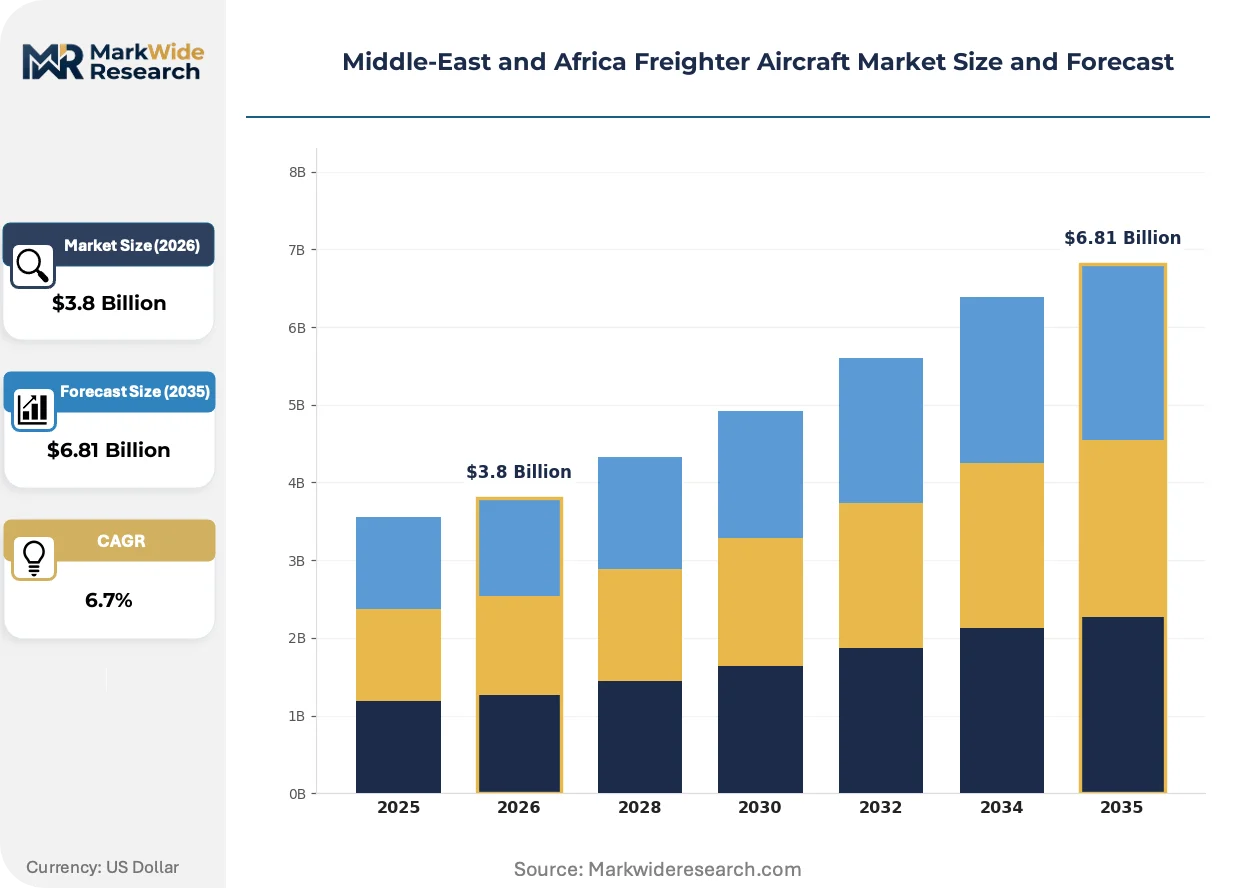
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Wide-body, Narrow-body, Cargo Aircraft, Freighter Conversion End User: Freight Forwarders, Airlines, Logistics Companies, Military Delivery Model: Lease, Purchase, Charter, Time-share Capacity: Below 20 Tons, 20 to 40 Tons, 40 to 60 Tons, Above 60 Tons |
| Companies Covered | Singapore Technologies Engineering Ltd, Textron Inc, The Boeing Company, KF Aerospace, Precision Aircraft Solutions, Airbus SE, ATR, Aeronautical Engineers Inc, Israel Aerospace Industries Ltd, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Freighter Aircraft Market Shifts & Advancements
Conversion technology maturation and regulatory pathway divergence are compressing fleet planning horizons across Middle Eastern and African operators. These forces reshape capital deployment and technical partnership strategies.
Electrified ground support equipment is electrifying apron operations at Dubai World Central and Johannesburg OR Tambo. Cargo handlers deploy battery-powered cargo loaders and pushback tractors to reduce jet fuel auxiliary power unit dependency. This infrastructure shift enables overnight charging cycles that align with freighter turn schedules, compressing ground time and extending airframe utilization rates.
GCAA-EASA bilateral airworthiness recognition negotiations are advancing toward mutual acceptance of supplemental type certificates issued in either jurisdiction. This regulatory convergence would eliminate duplicate technical reviews for freighter conversions operated across UAE and European registers. Narrow-body conversion specialists in the region anticipate streamlined export approval processes for African operator deliveries.
Forwarders now bundle charter commitments into annual block-hour agreements rather than transactional spot-market purchases. This procurement consolidation concentrates negotiating leverage with Emirates SkyCargo and Ethiopian Cargo. The shift is most visible on the Dubai-Lagos-Johannesburg triangle, where pharmaceutical and automotive shippers lock multi-year dedicated freighter access.
Middle-East and Africa Freighter Aircraft Market Segmentation
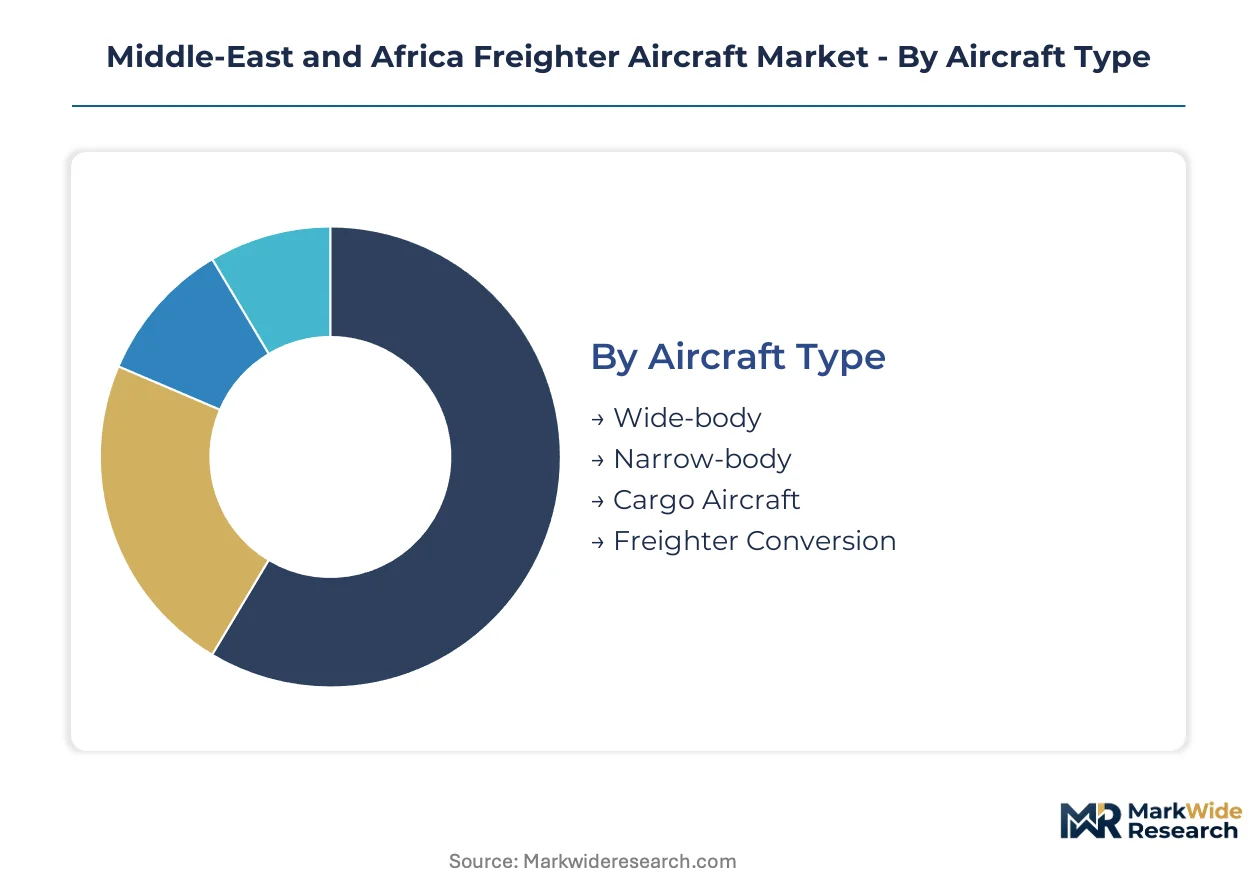
Freighter fleet planning in the Middle-East and Africa hinges on matching airframe specifications to corridor economics and regulatory constraints. Segment boundaries reflect payload engineering, operator business models, and capital deployment preferences across diverse aviation authorities.
Aircraft Type:
Airframe engineering specifications determine route eligibility, fuel burn profiles, and conversion economics across the region's maintenance hubs.
- Wide-body:Factory-built or converted twin-aisle platforms with reinforced main decks accommodate containerized cargo on trunk routes. Demand concentrates on Dubai-Lagos pharmaceutical corridors where temperature-controlled pallets justify premium lease rates.
- Narrow-body:Single-aisle converted freighters penetrate secondary African cities with runway limitations below 2,400 meters. Ethiopian Cargo deploys these platforms on thin routes to landlocked capitals where wide-body economics fail.
- Cargo Aircraft:Purpose-built freighter designs from original equipment manufacturers bypass conversion timelines but command higher capital outlays. Gulf operators favor these for fleet standardization under UAE GCAA oversight.
- Freighter Conversion:Passenger-to-cargo modification programs extend airframe utility through supplemental type certificate pathways. Israel Aerospace Industries and Dubai Aerospace Enterprise compete for feedstock in this segment.
Wide-body leads on scale; freighter conversion leads on momentum.
End User:
Operator business models shape procurement patterns and fleet utilization strategies across the region.
- Freight Forwarders:Logistics integrators like DHL Global Forwarding and Kuehne+Nagel secure dedicated freighter capacity through multi-year block-hour agreements. Their procurement concentrates on Dubai-Johannesburg automotive parts corridors.
- Airlines:Full-service carriers with cargo divisions leverage belly-hold networks while supplementing with main-deck freighters during peak seasons. Emirates SkyCargo anchors this segment with owned and leased wide-body assets.
- Logistics Companies:E-commerce specialists including Aramex and Fetchr build captive freighter fleets to escape wet-lease dependency. Their demand pulls narrow-body conversions for last-mile feeder routes.
- Military:Defense procurement bypasses commercial lease structures through direct acquisition of strategic airlift capacity. Saudi Arabia's military aviation authority and South African National Defence Force represent distinct procurement regimes.
Airlines dominate installed base; logistics companies are expanding most aggressively.
Delivery Model:
Capital structure preferences and operational flexibility requirements segment access pathways.
- Lease:Operating lease structures dominate among African operators seeking to preserve balance sheet capacity. Dublin and Singapore-based lessors control feedstock availability, creating sourcing bottlenecks for Sharjah conversion houses.
- Purchase:Direct acquisition concentrates among Gulf sovereign wealth-backed carriers with long-term fleet planning horizons. Etihad Cargo and Qatar Airways Cargo favor ownership for wide-body assets on core trunk routes.
- Charter:Spot-market procurement serves humanitarian relief and project cargo spikes. ACMI providers position aircraft in Addis Ababa and Nairobi for rapid African deployment.
- Time-share:Fractional ownership models remain nascent but attract mid-sized forwarders seeking dedicated capacity without full asset commitment. Regulatory frameworks for fractional freighter operations vary between UAE GCAA and South African CAA jurisdictions.
Lease structures capture majority volume; purchase models concentrate value.
Capacity:
Payload thresholds align with route density, infrastructure constraints, and cargo commodity mix across the region.
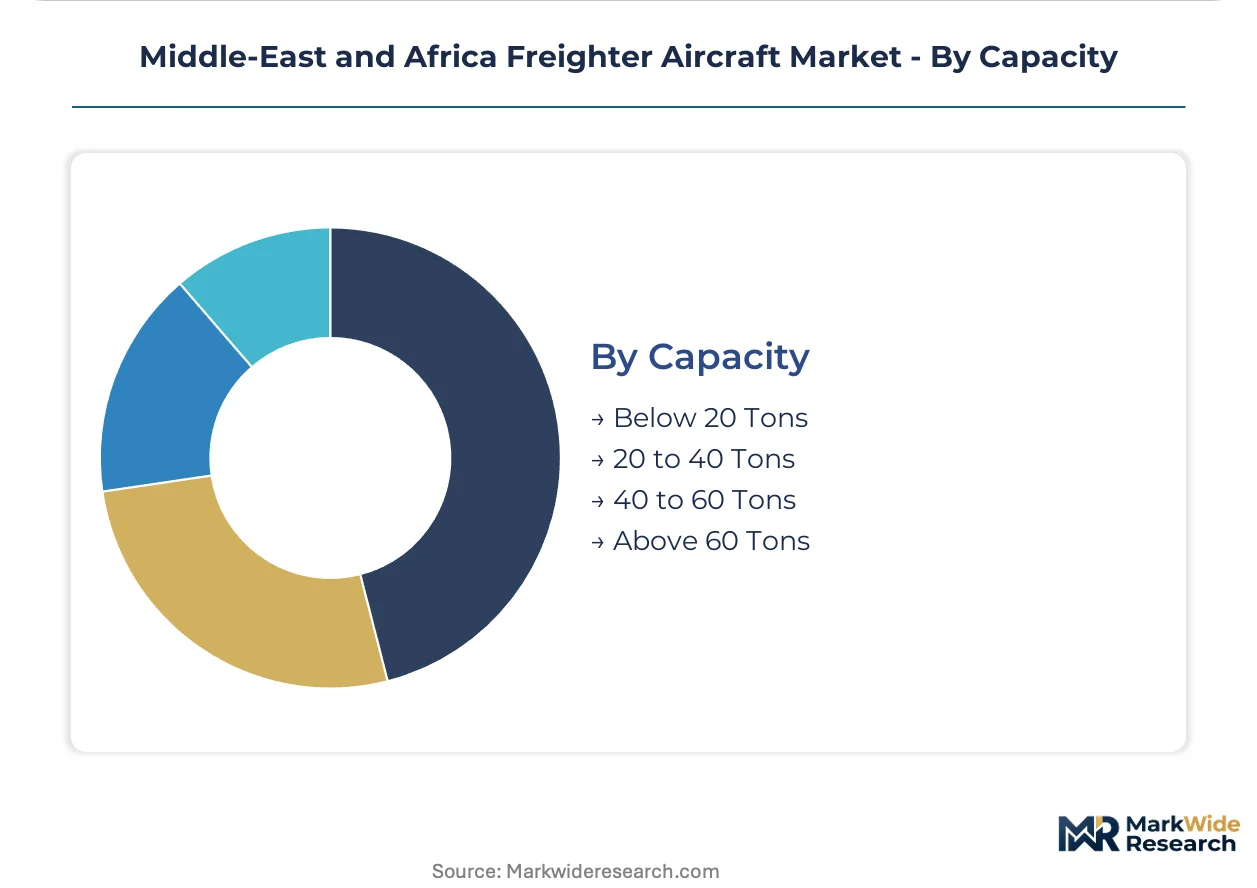
- Below 20 Tons:Small freighter platforms serve remote airstrips and humanitarian access routes. Rwandan drone-to-freighter intermodal pilots converge with these assets for last-mile distribution.
- 20 to 40 Tons:Mid-range narrow-body conversions bridge secondary city pairs with insufficient volume for wide-body deployment. This band captures express parcel growth on East African coastal corridors.
- 40 to 60 Tons:High-volume narrow-body and small wide-body conversions strain existing belly-hold capacity on passenger services. E-commerce volumes between Dubai and Lagos accelerate fleet renewal cycles in this segment.
- Above 60 Tons:Heavy wide-body platforms dominate long-haul trunk routes and specialized project cargo. Johannesburg's vaccine distribution networks pull this capacity from European transshipment points.
40 to 60 tons commands strategic focus; above 60 tons retains premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between UAE GCAA and South African CAA certification timelines drives conversion house location decisions. Sharjah maintenance hubs exploit faster supplemental type certificate approvals, while Johannesburg operators absorb compliance duplication costs for dual-registered fleets.
United Arab Emirates
Dubai World Central anchors Gulf freighter capacity with electrified ground support infrastructure. The General Civil Aviation Authority compressed Boeing 737-800BCF conversion timelines, pulling narrow-body modification demand toward Sharjah clusters. Emirates SkyCargo consolidates wide-body lease negotiations through multi-year block-hour agreements on pharmaceutical corridors.
Saudi Arabia
Riyadh's cargo hub expansion targets European-registered freighter access through anticipated GACA-EASA noise harmonization. The General Authority of Civil Aviation prepares acoustic retrofit exemptions that would eliminate penalties for converted wide-bodies operating into Kingdom airports. Military procurement bypasses commercial lease structures entirely through direct strategic airlift acquisition.
South Africa
Johannesburg OR Tambo pulls wide-body capacity from European transshipment points for vaccine distribution networks. The Civil Aviation Authority operates parallel supplemental type certificate review tracks distinct from UAE workflows, fragmenting conversion approval workflows for dual-registered operators. Cape Town maintenance capacity remains underutilized for cold chain infrastructure investment.
Israel
Tel Aviv conversion specialists compete for finite stress analysis talent with Dubai Aerospace Enterprise. Israel Aerospace Industries anchors narrow-body modification programs for African short-haul networks with limited runway infrastructure. The national aviation regulator enforces minimum navigation performance specifications that accelerate cockpit modernization requirements for older-generation feedstock.
Ethiopia
Addis Ababa's geographic positioning between Asian manufacturing and African consumption remains underutilized for freighter technical stops. Ethiopian Cargo deploys narrow-body platforms on thin routes to landlocked capitals where wide-body economics fail. Cold chain infrastructure investment would capture perishable transshipment volumes currently leaking to European hubs.
Middle-East and Africa Freighter Aircraft Market Competitive Landscape
US-based original equipment manufacturers anchor the factory-built freighter tier; European and Israeli conversion specialists hold the passenger-to-cargo modification segment. The market structure concentrates around wide-body platform providers and narrow-body conversion houses competing for finite feedstock availability. Three archetypes dominate: factory freighter OEMs, supplemental type certificate conversion houses, and integrated maintenance-repair-overhaul operators with captive modification capabilities. Competitive moves center on feedstock sourcing partnerships with Dublin and Singapore-based lessors, and regulatory pathway optimization through bilateral airworthiness recognition negotiations.
Among US-based aerospace manufacturers, The Boeing Company anchors wide-body conversion programs across Middle Eastern maintenance hubs. Airbus SE competes through A330P2F offerings targeting high-volume routes between Dubai and Sub-Saharan gateways. Israel Aerospace Industries Ltd occupies a specialist position in narrow-body freighter modifications for African short-haul networks with infrastructure constraints.
| Leading Market Players |
|---|
| Singapore Technologies Engineering Ltd |
| Textron Inc |
| The Boeing Company |
| KF Aerospace |
| Precision Aircraft Solutions |
| Airbus SE |
| ATR |
| Aeronautical Engineers Inc |
| Israel Aerospace Industries Ltd |
| Others |
Supply & Pricing Matrix
Multi-year block-hour agreements from pharmaceutical and automotive shippers on the Dubai-Lagos-Johannesburg triangle are compressing spot-market premiums and forcing conversion houses to absorb feedstock scarcity costs through tighter supplier negotiations.
Pricing Analysis
Lessors in Dublin and Singapore extract channel margins through feedstock control, while Sharjah conversion houses compete on turnaround speed rather than price. Pricing stratifies across GCAA-certified premium conversions, dual-registered standard assets, and single-jurisdiction economy modifications. Cost compression in narrow-body conversions is intensifying because feedstock competition from Asian cargo operators has tightened passenger airframe availability. African operators exhibit highest price sensitivity due to thin route yields; Gulf sovereign carriers show lowest sensitivity given long-term fleet planning horizons.
Supply Chain Analysis
Feedstock availability rests on Dublin-based and Singapore-based lessor portfolios controlling end-of-lease passenger wide-bodies and narrow-bodies targeted for conversion. Critical inputs include reinforced main-deck flooring systems, wide cargo door assemblies, and supplemental type certificate engineering packages from Israel and the UAE. Single-source vulnerability concentrates in stress analysis and systems integration specialist labor pools shared between Dubai Aerospace Enterprise and Israel Aerospace Industries. Distribution runs through ACMI providers positioning aircraft in Addis Ababa and Nairobi for rapid African deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market stems from GCAA supplemental type certificate streamlining reducing conversion downtime and enabling faster asset turns for premium lease rates.
For Market Incumbents: Acquire conversion engineering talent pools before competitors exhaust regional stress analysis capacity. Lock multi-year feedstock agreements with Dublin and Singapore lessors to defend against emerging Asian cargo operators bidding up passenger airframe prices. Invest in GCAA-EASA bilateral airworthiness recognition to eliminate duplicate certification costs for dual-registered fleets. For New Entrants and Emerging Players: Maintenance-repair-overhaul partnerships with Sharjah clusters offer the fastest path to conversion capability without captive engineering investment. Underpenetrated cold chain infrastructure at Addis Ababa and Cape Town presents white-space capture opportunity for perishable transshipment volumes currently leaking to European hubs. Target Ethiopian Cargo and East African coastal express parcel networks with narrow-body conversion offerings tailored to runway-limited secondary cities. For Investors and Strategic Acquirers: Asymmetric upside sits with narrow-body conversion specialists holding established GCAA approval pathways and African operator relationships. Five-to-ten year viability favors assets positioned on e-commerce corridor growth rather than traditional belly-hold substitution plays. Watch Saudi GACA-EASA noise harmonization implementation as inflection indicator for European-registered freighter access into Kingdom airports.| Strategic Initiative | Industry Significance |
|---|---|
| Feedstock Partnership with Lessor | Secures passenger airframe pipeline for Sharjah conversion houses against Asian competition. |
| GCAA-EASA Bilateral Negotiation | Eliminates duplicate supplemental type certificate reviews for dual-registered operator fleets. |
| Cold Chain Infrastructure Investment | Captures pharmaceutical transshipment volumes at Addis Ababa currently routing through European hubs. |
| Narrow-Body Conversion Specialization | Penetrates African secondary cities with runway limitations below wide-body operational thresholds. |
| Electrified Ground Support Deployment | Compresses freighter turn times at Dubai World Central through battery-powered cargo handling equipment. |
Research Methodology
Bottom-up cargo operator fleet planning modeling reconciled against top-down conversion house capacity tracking forms the analytical core of this study. Primary interviews with UAE GCAA certification officials, Sharjah maintenance hub operations directors, Ethiopian Cargo network planners, and DHL Global Forwarding procurement leads combined with secondary validation from ICAO airworthiness directives, GCAA supplemental type certificate filings, and IATA cargo traffic databases. Dublin and Singapore lessor portfolio disclosures provided feedstock availability triangulation against OEM delivery schedules.
Input-output matrices mapped conversion feedstock flows through maintenance hub clusters to end-user deployment patterns across the projection horizon. Segmentation dimensions modeled include aircraft type, end-user business model, delivery model capital structure, and payload capacity tier alongside corridor-specific route density and regulatory jurisdiction clustering. CAGRs derived from fleet renewal cycle analysis and e-commerce volume elasticity assumptions applied to existing belly-hold capacity constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to jet fuel price volatility, feedstock competition from Asian operators, and regulatory harmonization timing between UAE GCAA and South African CAA. Forecasts reflect documented assumptions on conversion approval timeline compression and pharmaceutical cold chain demand elasticity. A small set of triggers—Saudi GACA-EASA noise regulation alignment, Ethiopian cargo hub infrastructure investment decisions, and drone-to-freighter intermodal pilot scalability—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Evtol Aircraft Market
Aircraft
Latin America General Aviation Market
Aircraft
Aerospace Turbojet Market
Aircraft
Aircraft Wheels Market
Aircraft
Middle-East and Africa Commercial Aircraft Market
Aircraft
Aircraft Flight Control System Market
Aircraft
Aircraft Autopilot System Market
Aircraft
Autonomous Aircraft Propulsion Systems Market
Aircraft
United States Aerospace and Defense Market
Aircraft
Aircraft Fairings Market
Aircraft
Onboard Oxygen Generating System (OBOGS) Market
Aircraft
Asia-Pacific Light and Very Light Jets Market
Aircraft
Aircraft Elevator Market
Aircraft
Aircraft Mounts Market
Aircraft
Regional Jet Market
Aircraft
Global Aircraft Electric Brake Control System Market