
 Supersonic Jet Market | 2026-2036
Supersonic Jet Market Size, Share, and Industry Trends Forecast 2026-2036
Supersonic Jet Market Analysis
Corporate aviation is repositioning toward time-critical executive travel, creating fresh demand for point-to-point supersonic connectivity. Boom Supersonic leverages advanced aerodynamics and sustainable aviation fuel integration to anchor its development program in Colorado. Spike Aerospace competes through low-boom shaping technology that reduces sonic signature over populated corridors. Dassault Aviation SA sustains its heritage in high-speed business aircraft while navigating the shift from subsonic to supersonic platforms.
A supersonic jet is a fixed-wing aircraft engineered to sustain flight speeds exceeding Mach 1, typically incorporating area-ruled fuselages, variable-geometry inlets, and thermally resistant alloys to manage aerodynamic heating and wave drag. These aircraft serve commercial, military, and research missions where transit time reduction justifies fuel burn premiums and specialized infrastructure. Business Jets within the Product Type dimension dominate current order backlogs as ultra-high-net-worth individuals and fractional ownership programs prioritize schedule control over absolute seat cost. Turbofan configurations under the Technology segment attract the deepest engineering investment, balancing thrust efficiency across subsonic climb and supersonic cruise regimes. Government buyers within the End User category supply the most predictable procurement timelines, though Corporate demand offers wider margin pools.
The FAA mandates noise certification under Part 36 Stage 5 standards, while ICAO's Committee on Aviation Environmental Protection enforces CO2 and non-CO2 emissions limits that constrain engine thermodynamic cycles. EASA's CS-25 certification requirements for supersonine transport add parallel compliance burdens for any European route access. Stakeholders must monitor whether bilateral recognition agreements between FAA and EASA streamline dual certification or fragment market entry timelines.
Market Dynamics
FAA Part 36 Stage 5 noise limits and ICAO Chapter 14 emissions caps are compressing engine thermodynamic cycles, forcing airframers to redesign inlets, nozzles, and thermal management systems before first flight certification.
Growth Catalysts
- Time-Critical Executive Travel:Ultra-high-net-worth individuals and fractional ownership programs now prioritize schedule control over seat-mile economics, repositioning business aviation toward point-to-point supersonic connectivity.
- Sustainable Aviation Fuel Mandates:The EU Green Deal and ReFuelEU Aviation regulations are creating certified demand pools for SAF-compatible supersonic platforms, rewarding early powerplant integrators.
- Denver-Reno Development Clusters:Concentrated engineering talent and state-level aerospace incentives in Colorado and Nevada are accelerating prototype assembly timelines and supplier co-location.
Market Restraints
- Titanium-Alloy Supply Concentration:Thermally resistant alloys for airframe skins and engine hot sections face single-source dependency on Russian and Chinese sponge suppliers, exposing programs to input volatility.
- Dual Certification Burden:EASA CS-25 supersonic transport requirements run parallel to FAA Part 25, fragmenting market entry timelines unless bilateral recognition agreements advance.
- Subsonic Business Jet Substitution:Long-range platforms like the Gulfstream G700 and Bombardier Global 7500 compress transatlantic block times without sonic boom restrictions or specialized infrastructure.
Strategic Opportunities
- Overland Low-Boom Corridors:NASA's Quesst mission and FAA overflight rulemaking could unlock transcontinental US routes previously banned under Mach 1.0 limits, expanding addressable city pairs.
- Defense-Adjacent Procurement:Government buyers seeking rapid response and intelligence, surveillance, and reconnaissance capabilities offer predictable multiyear timelines and cost-plus contracting structures.
- Synthetic Fuel-Engine Convergence:Pairing variable-cycle turbofans with 100% SAF certification pathways is integrating propulsion and fuel system development, collapsing certification cycles for clean-sheet designs.
Industry Challenges
- Supersonic Aerodynamics Talent Scarcity:The retirement of Concorde-era engineers and limited university programs in compressible flow analysis are constraining computational fluid dynamics and wind tunnel validation capacity.
- Prolonged Type Certification Timelines:First-of-kind approvals for sustained Mach 1.4+ cruise require novel acoustic, thermal, and structural test regimes that lack precedent in current FAA advisory circulars.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Supersonic Jet Market |
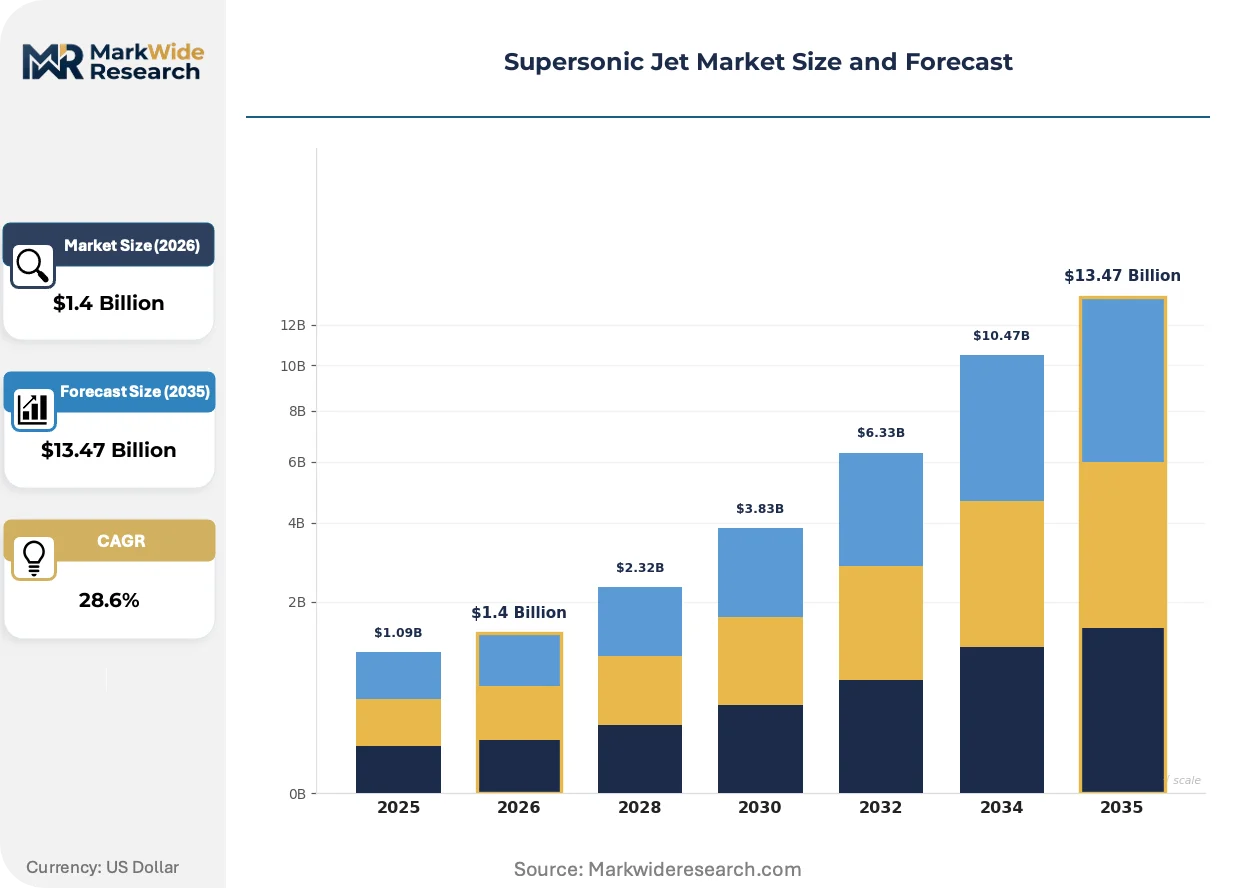
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $13.47 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Business Jets, Commercial Jets, Military Jets, Research Aircraft Technology: Turbojet, Turbofan, Hybrid, Advanced Aerodynamics End User: Government, Corporate, Private Owners, Research Institutions Capability: Speed Range, Altitude Range, Capacity, Range |
| Companies Covered | Boom Supersonic, BAE Systems, Lockheed Martin Corporation, COMAC (Commercial Aircraft Corporation of China), Dassault Aviation SA, The Boeing Company, Spike Aerospace, Aerion Group, Airbus S.A.S., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Supersonic Jet Market Emerging Trajectories
Propulsion-airframe integration and regulatory rulemaking are advancing in parallel, with each technology breakthrough triggering corresponding certification pathway updates and buyer education cycles.
Variable-cycle turbofan architectures are integrating adaptive fan pressure ratios and multi-stage compressors to maintain thrust efficiency across subsonic climb and Mach 1.6 cruise regimes. Corporate operators with existing fractional ownership contracts are requesting early delivery slots contingent on overland boom clearance. This propulsion flexibility is integrating engine OEMs into airframe development programs earlier than historical subsonic business jet precedents.
ICAO's Committee on Aviation Environmental Protection is tightening CO2 and non-CO2 emissions limits through metric value calculations that penalize high-thrust supersonic thermodynamic cycles. Engine manufacturers must now optimize for both cruise efficiency and landing-takeoff cycle NOx constraints. European route access hinges on compliance with these evolving standards, pushing development resources toward hybrid-electric auxiliary power and thermal management innovations.
Buyer preference is rotating from outright ownership toward fractional and jet-card models that amortize supersonic premiums across multiple users. Charter operators and membership programs are displacing traditional brokerage channels for initial market penetration. This behavioral shift concentrates most visibly in the United States, where NetJets and Flexjet are evaluating supersonic platform additions to existing fleet commitments.
Supersonic Jet Market Segmentation
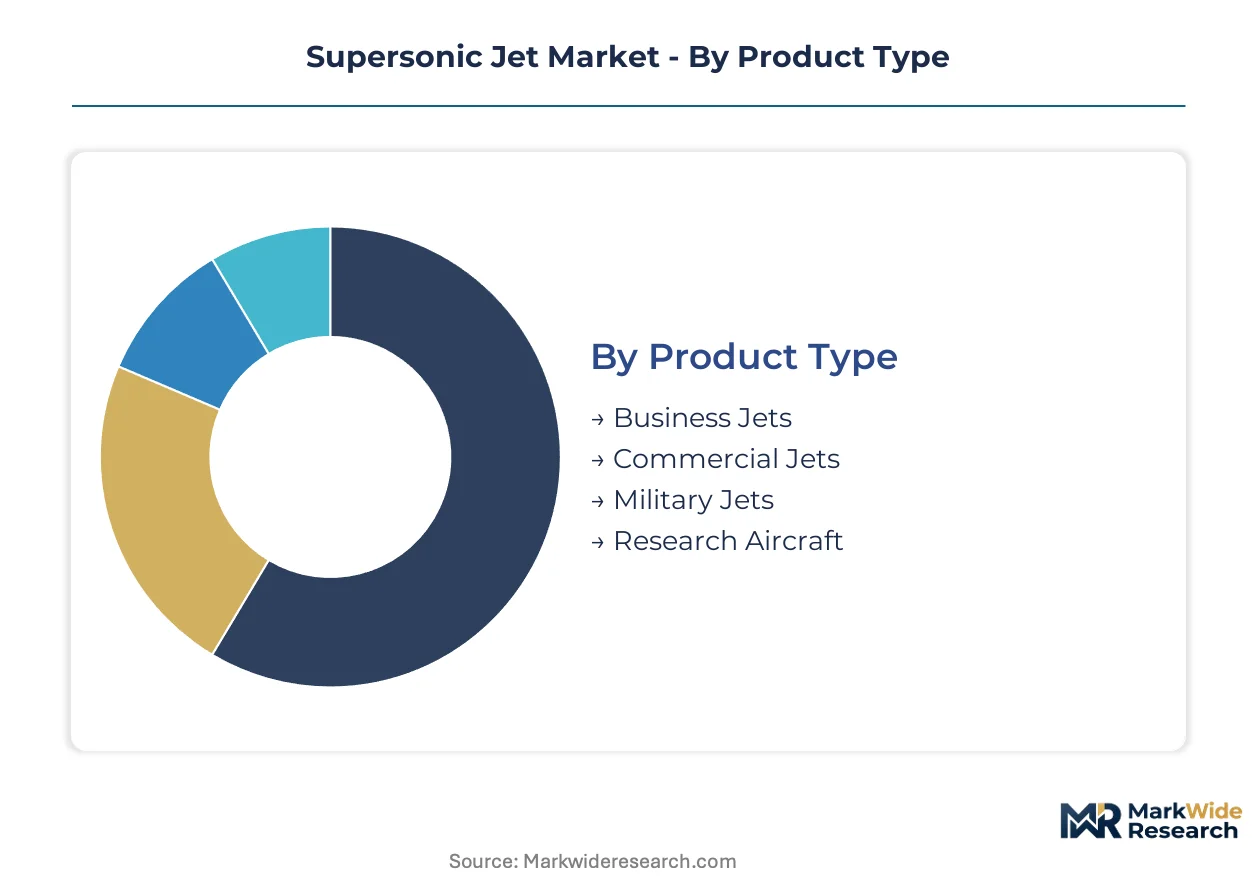
Supersonic jet segmentation reveals divergent development priorities across mission profiles and propulsion architectures. Each dimension carries distinct certification pathways, customer acquisition costs, and margin structures that shape manufacturer resource allocation.
Product Type:
Volume concentrates in subsonic-capable platforms with supersonic dash options, while premium pricing attaches to clean-sheet Mach 1.4+ designs purpose-built for sustained cruise.
- Business Jets:Area-ruled fuselages with low-boom shaping dominate engineering investment for point-to-point executive travel. Demand clusters in the United States where fractional ownership programs evaluate early delivery slots contingent on overland flight clearance.
- Commercial Jets:Higher passenger capacity demands variable-cycle turbofan architectures and thermal management systems that multiply development costs. EASA CS-25 certification requirements and FAA Part 25 noise limits compress design margins for any European or transatlantic route access.
- Military Jets:Intelligence, surveillance, and reconnaissance missions drive procurement with cost-plus contracting structures.
- Research Aircraft:NASA and national aerospace laboratories acquire platforms for sonic boom measurement and atmospheric sampling.
Mature deployment sits with Military Jets. Newer deployment is concentrated in Business Jets.
Technology:
Cost tier separation runs deepest in propulsion architecture, where development timelines and fuel burn penalties stratify platform economics.
- Turbofan:Multi-stage compressors with adaptive fan pressure ratios balance thrust efficiency across subsonic climb and Mach 1.6 cruise regimes. Engineering investment concentrates in the United States and France where engine OEMs integrate into airframe programs earlier than historical subsonic precedents.
- Turbojet:Simpler thermodynamic cycles suit military applications where fuel burn premiums matter less than thrust-to-weight ratios.
- Hybrid:Electric auxiliary power and thermal management innovations address ICAO Chapter 14 emissions constraints.
- Advanced Aerodynamics:Computational fluid dynamics capacity constrains validation timelines for compressible flow optimization.
Established production sits with Turbojet. Emerging deployment is accelerating in Turbofan.
End User:
Customer type determines procurement predictability, with government buyers supplying multiyear timelines and corporate demand offering wider margin pools.
- Government:Rapid response and ISR requirements generate predictable procurement cycles through defense agencies. Cost-plus structures absorb development risk while mandating specific performance thresholds for speed, altitude, and range.
- Corporate:Ultra-high-net-worth individuals and fractional ownership programs prioritize schedule control over absolute seat economics. Charter operators in the United States displace traditional brokerage channels for initial platform penetration.
- Private Owners:Outright acquisition concentrates among single-digit billionaire demographics with existing pilot certifications.
- Research Institutions:National laboratories and university consortiums acquire limited production runs for atmospheric science missions.
Stable procurement sits with Government. Expanding deployment is climbing fastest in Corporate.
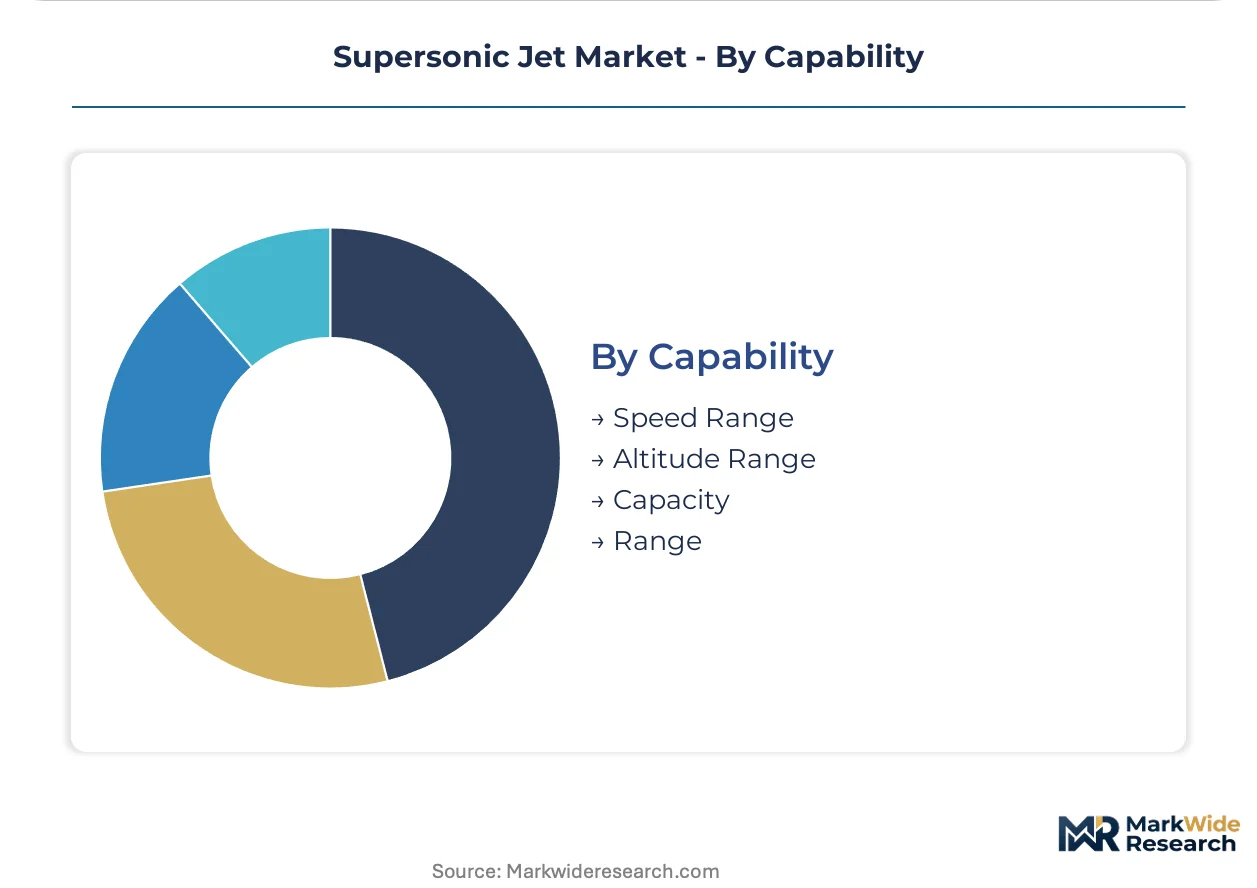
Capability:
Performance tier differentiation maps directly to addressable route networks and regulatory constraints on overland flight.
- Speed Range:Mach 1.0-1.4 cruise unlocks transoceanic corridors; Mach 1.4+ requires specialized acoustic certification for population center overflight.
- Altitude Range:FL500-FL600 operations reduce sonic boom ground signature but impose pressurization and thermal management penalties.
- Capacity:Four-to-eight seat configurations dominate business jet backlogs; commercial platforms target 50-100 passenger economics.
- Range:Transatlantic capability (3,500+ nm) separates premium platforms from regional dash configurations.
Baseline capability sits with Range. Advancing deployment is gaining share fastest in Speed Range.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent concentrates in the United States while certification bodies in Europe and Asia-Pacific shape route access rules. Demand for point-to-point executive travel is fragmenting across regulatory jurisdictions with divergent noise and emissions standards.
United States
Fractional ownership programs in the United States are evaluating supersonic platform additions contingent on overland flight clearance. FAA Part 36 Stage 5 noise limits and ongoing NASA Quesst mission coordination are reshaping low-boom corridor rulemaking. Denver and Reno anchor development clusters where Boom Supersonic and Aerion Group have concentrated prototype assembly and supplier co-location.
France
Dassault Aviation SA sustains heritage in high-speed business aircraft while navigating the shift from subsonic to supersonic platforms. EASA CS-25 certification requirements for supersonic transport impose parallel compliance burdens alongside FAA Part 25 for any transatlantic route access. Toulouse and Bordeaux engineering centers retain compressible flow analysis capacity from military fighter programs.
United Kingdom
BAE Systems leverages defense procurement relationships to advance rapid response and intelligence, surveillance, and reconnaissance capabilities. The UK Civil Aviation Authority coordinates with EASA on supersonic noise certification reciprocity while maintaining national discretion on overflight permissions. Farnborough and Bristol clusters host wind tunnel facilities and computational fluid dynamics expertise from Concorde-era programs.
China
COMAC evaluates supersonic transport concepts as part of broader civil aviation industrial policy objectives. The Civil Aviation Administration of China aligns with ICAO Chapter 14 emissions frameworks while developing domestic certification standards for sustained Mach 1.0+ cruise. Shanghai and Xi'an engineering centers concentrate titanium-alloy fabrication capabilities for thermally resistant airframe structures.
Japan
Research institutions in Japan acquire limited production runs for atmospheric science missions and sonic boom measurement campaigns. METI coordinates national aerospace technology roadmaps with emphasis on low-noise propulsion and thermal management innovations. Nagoya and Tokyo clusters maintain university consortium partnerships in adaptive cycle engine research.
Supersonic Jet Market Vendor Landscape
Top-tier vendors anchor integrated airframe-propulsion development, while specialized engineering boutiques concentrate on aerodynamic shaping and low-boom acoustic signature reduction. The competitive structure stratifies across three archetypes: legacy defense contractors with cost-plus government relationships, clean-sheet startups pursuing FAA Part 25 certification, and established business jet manufacturers extending product portfolios. Dominant competitive moves include strategic partnerships between engine OEMs and airframe developers, plus geographic expansion through state-level aerospace incentive capture.
Among United States-based developers, Boom Supersonic and Spike Aerospace exemplify the clean-sheet startup archetype with concentrated engineering investment in Colorado and Nevada clusters. Dassault Aviation SA occupies a position within the established manufacturer tier, leveraging heritage in high-speed platforms to bridge subsonic and supersonic product generations. These three companies represent divergent strategic postures on certification sequencing, propulsion integration timing, and route network prioritization.
| Leading Market Players |
|---|
| Boom Supersonic |
| BAE Systems |
| Lockheed Martin Corporation |
| COMAC (Commercial Aircraft Corporation of China) |
| Dassault Aviation SA |
| The Boeing Company |
| Spike Aerospace |
| Aerion Group |
| Airbus S.A.S. |
| Others |
Supply Flow & Price Mechanics
Variable-cycle turbofan integration is compressing development timelines while concentrating procurement power among engine OEMs with captive hot-section alloy supplies. This dual shift simultaneously elevates upfront platform pricing and locks airframers into long-term component offtake agreements with Russian and Chinese sponge-dependent foundries.
Pricing Analysis
Lead-time premiums dominate supersonic jet contracting, with contingent delivery slots commanding substantial markups over firm orders. Contract-based long-term offtake structures anchor the market, with price differentiation driven by certification tier (FAA Part 25 versus EASA CS-25 dual compliance) and customization level for cabin avionics. Pricing pressure stems from subsonic business jet substitution, as Gulfstream G700 and Bombardier Global 7500 platforms compress transatlantic block times without sonic boom restrictions. Corporate fractional ownership programs exhibit highest price sensitivity, while government ISR procurement shows lowest sensitivity due to cost-plus structures.
Supply Chain Analysis
Regional distribution centers for titanium-alloy semifinished products concentrate in Colorado, Nevada, and Toulouse, feeding just-in-time assembly at Denver-Reno development clusters. Supply draws from Russian and Chinese sponge producers, with United States and French foundries providing downstream forging and machining. Raw material dependencies center on titanium sponge, nickel-based superalloys, and thermally resistant composites. Single-source vulnerability in Eastern hemisphere sponge supply exposes programs to input volatility. Distribution runs through aerospace-tier supplier networks with airframe OEM captive control over critical hot-section components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supersonic jet manufacturing is becoming a vertical-integration race, with engine-airframe convergence and captive titanium-alloy supply the decisive upstream levers separating viable platforms from stranded development programs.
For Market Incumbents: Hedge against clean-sheet startup disruption by securing long-term offtake agreements with Russian and Chinese sponge suppliers before geopolitical friction hardens. Incumbents should accelerate EASA-FAA bilateral recognition advocacy to compress dual certification timelines, while building in-house variable-cycle turbofan integration capabilities to reduce engine OEM pricing power.
For New Entrants and Emerging Players: Launch via defense-adjacent procurement channels that offer cost-plus structures and predictable multiyear timelines. White-space targets include rapid response ISR platforms for government buyers and fractional ownership programs in the United States contingent on overland boom clearance. The most penetrable segment is corporate point-to-point executive travel, accessed through charter operator partnerships rather than traditional brokerage channels.
For Investors and Strategic Acquirers: Exit pathways concentrate in defense contractor acquisition of clean-sheet startups with FAA Part 25 certification progress. Long-term viability hinges on whether NASA Quesst mission data unlocks transcontinental low-boom corridors. Acquisition target archetypes are engine-airframe integrators with SAF certification pathways. The signal to watch is EASA-FASA bilateral recognition agreement advancement as inflection indicator for European route access economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Engine-Airframe Integration Partnership | Lockheed Martin's variable-cycle turbofan collaboration collapses thermal management development cycles for Mach 1.6 cruise regimes. |
| SAF Certification Pathway Investment | Spike Aerospace's 100% synthetic fuel compatibility unlocks EU Green Deal compliant route access for European corporate buyers. |
| Titanium-Alloy Backward Integration | Boom Supersonic's Colorado foundry investments reduce Russian sponge dependency exposure for Overture airframe skins. |
| Low-Boom Acoustic Certification | NASA Quesst mission data feeds FAA overflight rulemaking that determines transcontinental US corridor viability. |
| Defense-Adjacent Procurement Capture | BAE Systems' rapid response platform contracts provide cost-plus revenue stability absent commercial certification risk. |
Methodological Framework
Multi-period observation of FAA certification timeline progression, engine OEM integration announcements, and fractional ownership program fleet commitments anchored the trend analysis, supplemented by interviews with airframe program directors, engine thermodynamics engineers, fractional ownership fleet planners, and aerospace materials procurement leads. Secondary validation drew from FAA Part 25 docket filings, EASA CS-25 supersonic transport working papers, NASA Quesst mission technical releases, and SEC 10-K aerospace segment disclosures. Bottom-up platform delivery forecasts triangulated against top-down addressable route network analysis.
Input-output matrix modeling connected propulsion architecture choices to certification pathway timelines and buyer willingness-to-pay estimates across the projection horizon. Segmentation dimensions included product type (business jet, commercial, military, research), technology (turbofan, turbojet, hybrid, advanced aerodynamics), end user (government, corporate, private owner, research institution), and capability tier (speed range, altitude, capacity, range). CAGRs derived from S-curve penetration modeling calibrated to Concorde-era adoption benchmarks and adjusted for SAF regulatory mandate acceleration. Industry-specific inputs incorporated titanium-alloy supply elasticity and bilateral certification recognition probability.
Geopolitical friction in titanium sponge supply, EASA-FAA bilateral recognition delays, and subsonic business jet performance advancement are the dominant revision risks that could compress or extend forecast trajectories. Forecasts reflect documented assumptions regarding NASA Quesst mission timeline adherence and ICAO Chapter 14 emissions limit enforcement stringency. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Radome Market
Aircraft
Helicopter Flight Management System Market
Aircraft
Commercial Aircraft Lighting Market
Aircraft
Europe Commercial Aircraft Market
Aircraft
Latin America Commercial Aircraft Market
Aircraft
Aircraft Autopilot System Market
Aircraft
Aerospace Turbojet Market
Aircraft
GCC Business Jet Market
Aircraft
Asia-Pacific Freighter Aircraft Market
Aircraft
Tilt Rotor Aircraft Market
Aircraft
Aircraft Strut Market
Aircraft
Aircraft Leasing Market
Aircraft
Aeronautic Propeller Market
Aircraft
US Aircraft Windshield Wiper and Washer System Market
Aircraft
Aviation Crew Management System Market
Aircraft
Air Starter Market