
 Europe Satellite IoT Market | 2026-2036
Europe Satellite IoT Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Satellite IoT Market Insights
CE marking under the EU Radio Equipment Directive is bifurcating the vendor landscape between certified module suppliers and uncertified hardware importers. Iridium Communications leverages its L-band spectrum rights to sustain coverage across Arctic shipping lanes where terrestrial networks fail. ORBCOMM anchors its European position through specialized dual-mode satellite-cellular terminals for refrigerated logistics fleets.
Europe Satellite IoT denotes networked sensor-to-satellite data links operating in L-band, S-band, or Ku-band frequencies, typically transmitting sub-1 kB payloads from remote assets to ground stations for cloud ingestion. These systems serve industrial and commercial purposes by enabling telemetry from beyond cellular range for fleet coordination, pipeline integrity, and environmental compliance. Maritime applications lead current revenue pools across the End User dimension due to SOLAS-mandated safety telemetry and fuel-consumption optimization programs. Cloud-Based deployment architectures are capturing the fastest expansion within the Deployment category as vessel operators and utility grids abandon on-premise gateway maintenance for managed satellite backhaul services.
EMA and ECHA frameworks govern radiation-hardened component standards and restricted substance thresholds in satellite IoT hardware sold across EU member states. REACH compliance raises material substitution costs for terminal manufacturers sourcing legacy solder and battery chemistries. The EU AI Act introduces algorithmic transparency requirements for autonomous edge analytics running on satellite-connected remote sensors. Stakeholders must weigh spectrum licensing timelines against constellation deployment schedules when committing to multi-year connectivity contracts.
Market Dynamics
The EU Green Deal's emissions reporting mandates are compressing procurement cycles for hybrid satellite-cellular terminals as maritime operators face compliance deadlines.
Growth Catalysts
- CE marking requirements:The EU Radio Equipment Directive is forcing terminal standardization, reducing integration costs for fleet operators deploying certified modules.
- Decarbonized shipping corridors:The EU Green Deal's corridor designations mandate real-time fuel monitoring, pulling satellite IoT into vessel retrofit programs.
- Arctic route expansion:L-band spectrum coverage gaps above 70°N latitude are driving demand for polar-orbiting constellation access among ice-class vessel operators.
Market Restraints
- REACH compliance costs:Terminal manufacturers face material substitution expenses for restricted solder and battery chemistries, raising unit production costs.
- Spectrum licensing timelines:National regulatory authorities in EU member states issue terrestrial coordination rulings that delay satellite terminal activation by 12-18 months.
- Cellular-LPWAN substitution:NB-IoT coverage expansion along coastal corridors is displacing satellite backhaul for near-shore vessel tracking applications.
Strategic Opportunities
- Refrigerated logistics convergence:Dual-mode satellite-cellular terminals enable cold-chain integrity monitoring across Germany's port-to-inland distribution networks.
- EU AI Act edge analytics:Algorithmic transparency requirements for autonomous sensors create certification service revenue streams for terminal vendors.
- Baltic Sea corridor penetration:Polish and Estonian port authorities lack dedicated satellite IoT procurement frameworks, opening first-mover positioning for managed service providers.
Industry Challenges
- RF engineering talent scarcity:L-band antenna design expertise concentrates among legacy aerospace suppliers, constraining terminal vendor R&D expansion.
- Legacy fleet integration:Vessel operators running 15-20 year asset replacement cycles face gateway hardware incompatibility with cloud-native satellite backhaul architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Satellite IoT Market |
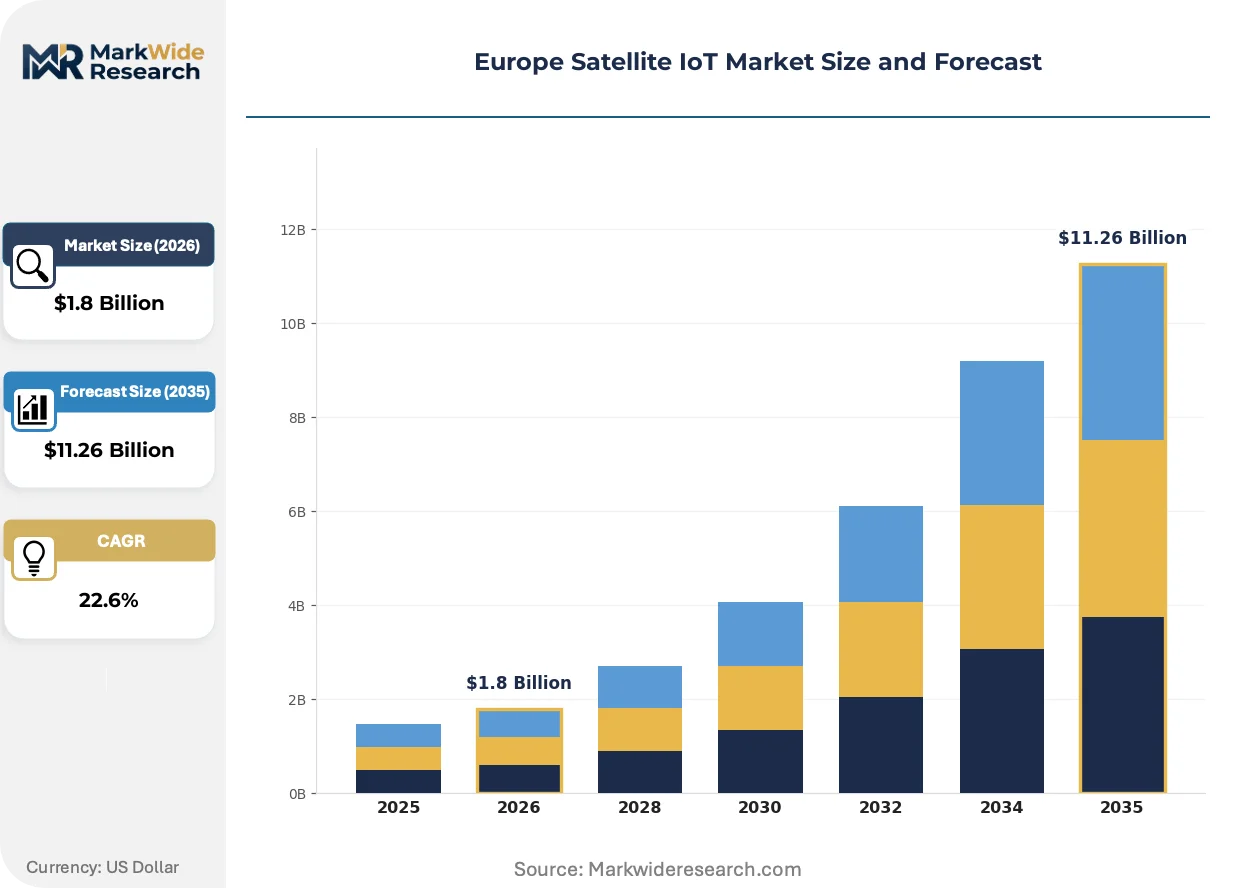
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.26 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Agriculture, Logistics, Asset Tracking, Remote Monitoring Technology: LPWAN, Satellite Communication, Sigfox, NB-IoT End User: Utilities, Transport, Maritime, Oil & Gas Deployment: Managed Services, On-Premise, Cloud-Based, Hybrid |
| Companies Covered | Iridium Communications, ORBCOMM, Inmarsat, Globalstar, Eutelsat, SES Networks, Thuraya Telecommunications, Kongsberg Satellite Services, Sateliot, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Satellite IoT Market Trends and Innovations
Satellite IoT architecture is pivoting from proprietary gateway stacks toward managed cloud ingestion, compressing operator technical staffing requirements.
Low-earth orbit constellations deploying S-band transceivers are bifurcating the module supplier landscape. German automotive logistics fleets are adopting these terminals for continental asset tracking. The technology is bifurcating procurement patterns between certified module vendors and uncertified hardware importers.
REACH substance restrictions are tightening restricted material thresholds for satellite IoT batteries and solder compounds. Terminal manufacturers must reformulate supply chains to maintain EU market access. German industrial IoT clusters are absorbing these compliance costs faster than peripheral EU markets.
Fleet operators are unbundling satellite connectivity from terminal hardware procurement. Vessel management companies now source managed backhaul services separately from antenna modules, compressing vendor margin pools. This pattern concentrates in North Sea routes where operator consolidation has reduced buyer fragmentation.
Europe Satellite IoT Market Segmentation
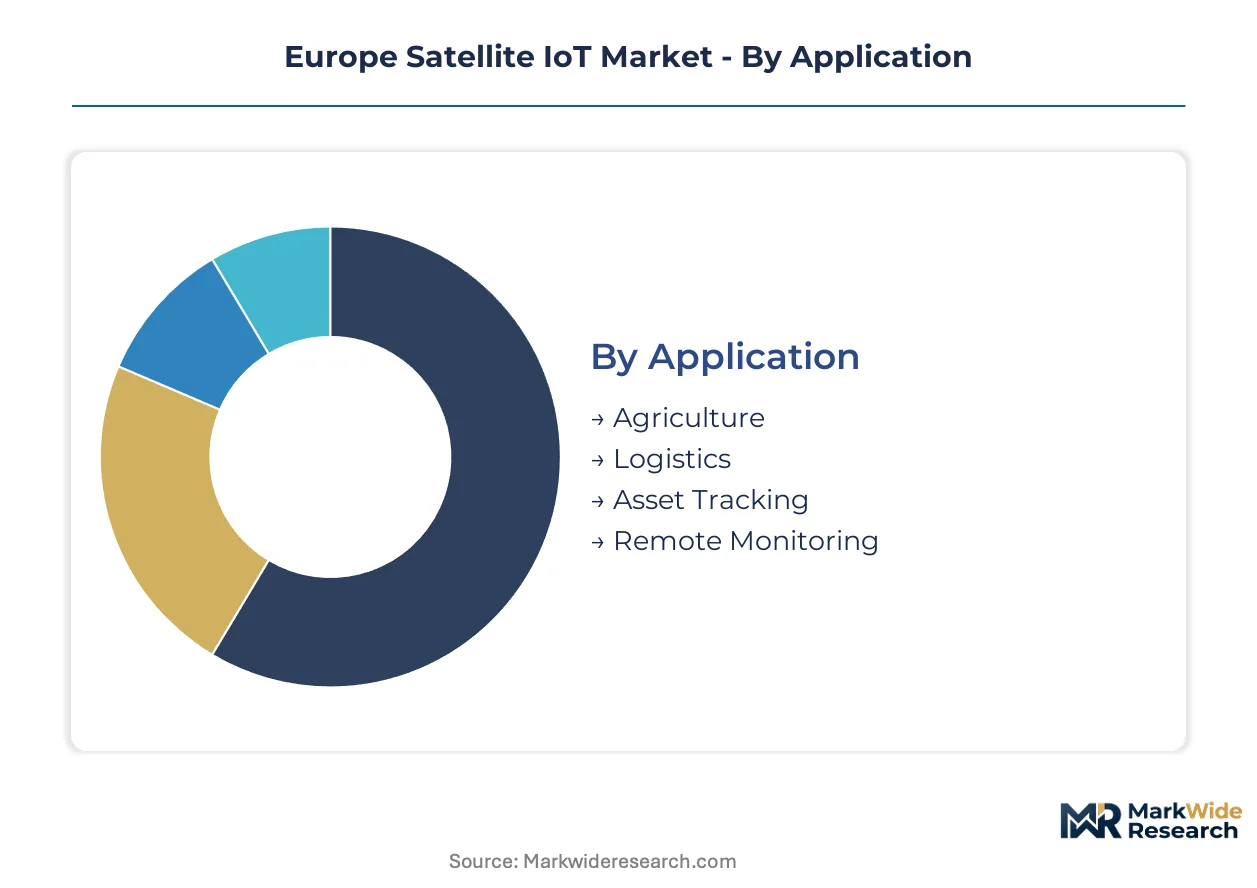
Segmentation reveals how procurement patterns diverge across the EU regulatory landscape. CE marking requirements and REACH compliance create distinct cost tiers that reshape vendor selection criteria for fleet operators and utility managers.
Application:
German industrial IoT clusters drive domestic demand concentration, while Baltic and North Sea corridors pull export-oriented deployment toward maritime-heavy segments.
- Maritime:SOLAS-mandated safety telemetry and fuel-consumption optimization programs anchor procurement across Dutch and Danish port authorities. Ice-class vessel operators above 70°N latitude require L-band connectivity that terrestrial networks cannot provision.
- Logistics:Refrigerated fleet operators across Germany's port-to-inland distribution networks deploy dual-mode satellite-cellular terminals for cold-chain integrity. EU Green Deal emissions reporting deadlines compress retrofit procurement cycles.
- Agriculture:Polish and Romanian agritech deployments favor low-data-rate crop moisture monitoring.
- Asset Tracking:German automotive logistics fleets adopt S-band transceivers for continental visibility.
- Remote Monitoring:Pipeline integrity sensors across Norwegian North Sea infrastructure transmit sub-1 kB payloads.
Maritime commands the established base. The steepest expansion runs through logistics.
Technology:
Cost tiers separate certified module vendors from uncertified hardware importers under EU Radio Equipment Directive enforcement.
- Satellite Communication:L-band spectrum rights sustain coverage across Arctic shipping lanes where terrestrial infrastructure fails. EMA radiation-hardened component standards govern terminal hardware sold across member states.
- NB-IoT:Coastal corridor expansion in France and Spain displaces satellite backhaul for near-shore vessel tracking. Cellular-LPWAN substitution pressures pricing for maritime applications within 50km of shore.
- LPWAN:German industrial clusters absorb REACH compliance costs faster than peripheral EU markets.
- Sigfox:Narrowband deployments concentrate in French utility metering applications.
Satellite communication anchors installed terminal volume. NB-IoT climbs the fastest as coastal coverage densifies.
End User:
Customer type determines contract structure, with vessel management companies unbundling connectivity from hardware procurement.
- Transport:Fleet operators running 15-20 year asset replacement cycles face gateway hardware incompatibility with cloud-native architectures. German automotive logistics absorb these integration costs through volume procurement.
- Utilities:Grid operators abandon on-premise gateway maintenance for managed satellite backhaul services. ECHA restricted substance thresholds raise material substitution costs for battery and solder chemistries.
- Maritime:Polish and Estonian port authorities lack dedicated procurement frameworks, opening first-mover positioning.
- Oil & Gas:Norwegian North Sea infrastructure requires radiation-hardened telemetry for platform integrity monitoring.
Transport commands terminal deployment scale. Utilities gain share fastest through cloud migration.
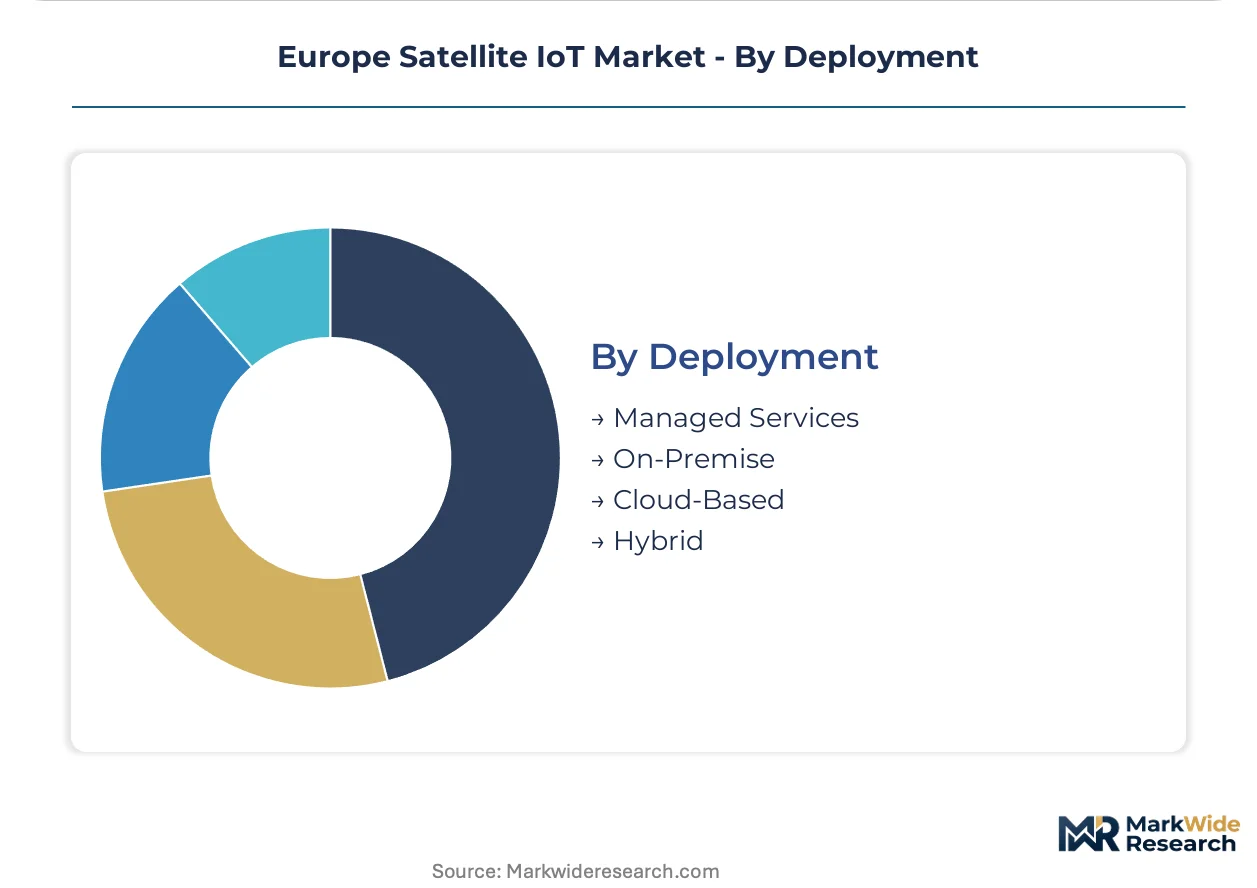
Deployment:
Margin concentration favors managed service providers as operators shed technical staffing requirements.
- Cloud-Based:Vessel operators and utility grids compress operator technical staffing through managed ingestion. National regulatory authorities issue terrestrial coordination rulings that delay activation 12-18 months.
- Hybrid:Dual-mode satellite-cellular architectures dominate German refrigerated logistics. EU AI Act algorithmic transparency requirements create certification service revenue for edge analytics vendors.
- Managed Services:North Sea route consolidation reduces buyer fragmentation, concentrating vendor margin pools.
- On-Premise:Legacy fleet integration constraints persist among operators with extended replacement cycles.
Hybrid architectures command current procurement volume. Cloud-Based deployment expands most quickly as technical staffing costs rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's automated container handling systems anchor Dutch demand for hybrid satellite-cellular terminals, while Norway's North Sea pipeline infrastructure underwrites Nordic procurement of radiation-hardened telemetry modules.
Germany
Port logistics hubs in Hamburg and Bremerhaven drive concentrated procurement of dual-mode connectivity terminals for refrigerated fleet tracking. REACH compliance costs for restricted solder and battery chemistries concentrate among Baden-Württemberg industrial IoT clusters. Bavaria's automotive logistics corridors absorb these material substitution expenses through volume-scale deployment of S-band transceivers.
Netherlands
Dutch maritime operators across Rotterdam-Amsterdam port complexes accelerate retrofit programs for SOLAS-mandated safety telemetry systems. CE marking under the EU Radio Equipment Directive compresses vendor selection to certified module suppliers. The Randstad logistics belt concentrates cold-chain integrity monitoring deployments for pharmaceutical distribution networks.
Norway
North Sea oil and gas platforms require EMA-governed radiation-hardened components for subsea pipeline integrity sensors. Ice-class vessel operators above 70°N latitude depend on L-band spectrum coverage for Arctic route expansion. Stavanger-based offshore service companies unbundle satellite connectivity from hardware procurement to reduce technical staffing.
Poland
Gdansk and Gdynia port authorities lack dedicated satellite IoT procurement frameworks, creating first-mover positioning for managed service providers. Polish agritech deployments in Mazovia favor low-data-rate crop moisture monitoring over cellular-LPWAN alternatives. The country's national telecommunications regulator issues terrestrial coordination rulings that delay terminal activation timelines.
United Kingdom
Scottish North Sea fishing fleets and Shetland logistics operators require polar-orbiting constellation access for safety telemetry beyond cellular range. Maritime and Coastguard Agency enforcement of emissions reporting deadlines compresses procurement cycles for vessel retrofit programs. Aberdeen's offshore energy corridor anchors demand for cloud-based satellite backhaul services.
Europe Satellite IoT Market Competitive Landscape
Listed leaders compete with private specialists across spectrum licensing and terminal certification dimensions, producing a bifurcated vendor landscape between certified module suppliers and uncertified hardware importers. The structure concentrates margin pools among managed service providers as fleet operators shed technical staffing requirements. Two archetypes dominate: constellation operators leveraging proprietary spectrum rights, and dual-mode terminal specialists integrating satellite-cellular architectures. Competitive moves center on CE marking compliance investments and cloud-native gateway stack development.
Within the constellation operator tier, Iridium Communications and Inmarsat exemplify spectrum-based competitive positioning through L-band coverage rights. ORBCOMM occupies a specialist position among dual-mode terminal vendors, anchoring the refrigerated logistics segment with hybrid connectivity architectures. These three companies represent distinct strategic archetypes: spectrum ownership, maritime specialization, and logistics-focused hardware integration.
| Leading Market Players |
|---|
| Iridium Communications |
| ORBCOMM |
| Inmarsat |
| Globalstar |
| Eutelsat |
| SES Networks |
| Thuraya Telecommunications |
| Kongsberg Satellite Services |
| Sateliot |
| Others |
Pricing and Supply Chain Analysis
Baden-Württemberg industrial IoT clusters absorb REACH compliance costs through volume procurement of certified L-band modules, compressing price floors for peripheral EU markets that lack comparable scale economies. This concentration of certified manufacturing capacity in Germany's southwest creates tiered procurement dynamics where Hamburg port operators secure preferential unit economics against Polish agritech buyers facing identical regulatory burdens.
Pricing Analysis
Certification level under the EU Radio Equipment Directive creates the primary spread between CE-marked module suppliers and uncertified hardware importers. Three-tier pricing structure across certified premium, compliant standard, and uncertified economy levels segments procurement patterns. Cost compression in the economy tier intensifies because NB-IoT coastal coverage expansion displaces satellite backhaul for near-shore applications. Maritime vessel management companies demonstrate lowest price sensitivity due to SOLAS-mandated safety requirements, while Polish agritech deployments exhibit highest sensitivity to per-unit terminal costs.
Supply Chain Analysis
L-band antenna design expertise concentrates among legacy aerospace suppliers in France and Germany, constraining terminal vendor R&D expansion across the continent. Terminal manufacturing draws from radiation-hardened component foundries in Norway and the Netherlands, plus REACH-compliant battery cell suppliers in South Korea. Single-source vulnerability persists for polar-orbiting constellation access above 70°N latitude. Distribution runs through Hamburg and Rotterdam port logistics hubs before radiating to inland refrigerated fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Satellite IoT Market exhibits cyclical recovery characteristics as EU Green Deal emissions reporting deadlines compress vessel retrofit procurement cycles against a backdrop of constellation deployment delays.
For Market Incumbents: Consolidate spectrum licensing positions through accelerated terrestrial coordination filings with national regulatory authorities in Poland and Estonia, where 12-18 month activation delays create first-mover vulnerability. Deepen backward integration into REACH-compliant battery chemistry supply through captive sourcing agreements with South Korean cell manufacturers, insulating margin pools from material substitution cost spikes.
For New Entrants and Emerging Players: Lead with cloud-native gateway stack development targeting North Sea route vessel operators shedding technical staffing requirements. Polish and Estonian port authorities lack dedicated procurement frameworks, representing the most penetrable geography for managed service positioning. Pursue dual-mode satellite-cellular certification as the primary go-to-market angle, anchoring refrigerated logistics convergence in Germany's port-to-inland distribution networks.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors dual-mode terminal specialists with established CE marking pathways over pure-play constellation operators facing polar coverage commoditization. Long-term viability across the projection horizon rests on algorithmic transparency certification capabilities under the EU AI Act for autonomous edge analytics. Acquisition targets should demonstrate managed service revenue concentration exceeding hardware transactional exposure. The signal to watch is terrestrial coordination ruling velocity from Baltic national regulators as inflection indicator for terminal activation throughput.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU Radio Equipment Directive compliance compresses vendor selection to certified module suppliers. |
| Dual-Mode Terminal Development | Hybrid satellite-cellular architectures dominate German refrigerated logistics procurement. |
| Managed Service Transition | North Sea vessel operators unbundle connectivity from hardware to reduce technical staffing. |
| Polar Constellation Access Agreement | Ice-class vessel operators above 70°N latitude require L-band coverage beyond terrestrial reach. |
| REACH-Compliant Supply Chain Restructuring | Material substitution for restricted solder and battery chemistries raises production cost barriers. |
Research Methodology
Cross-validation between primary interviews with maritime fleet operations directors, terminal procurement managers at German automotive logistics clusters, and EMA regulatory affairs specialists anchors the qualitative findings. Secondary validation draws from EU Green Deal implementation progress reports, ECHA substance restriction updates, national spectrum licensing databases, and port authority procurement disclosures. Bottom-up terminal deployment estimates triangulate against top-down connectivity service revenue analysis.
Sensitivity analysis across constellation deployment schedules, terrestrial coordination ruling timelines, and REACH compliance cost trajectories informs the analytical framework. Segmentation dimensions modeled include application type, technology protocol, end-user industry, and deployment architecture, with additional granularity on certification tier and polar coverage requirements. CAGRs derive from connectivity service contract value projections and terminal hardware replacement cycle analysis, incorporating EU AI Act algorithmic transparency compliance as emerging revenue stream input.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement intensity or accelerated NB-IoT coastal densification would require recalibration. Forecasts reflect documented assumptions regarding spectrum licensing velocity and constellation launch cadence. Revision becomes warranted when cellular-LPWAN substitution rates in near-shore maritime applications cross thresholds that compress satellite backhaul addressable market.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Brazil Satellite Imagery Services Market
Satellite
Germany Satellite-Based Earth Observation Market
Satellite
Russia Satellite Imagery Services Market
Satellite
Asia-Pacific Satellite Manufacturing Market
Satellite
Africa Satellite Connectivity Market
Satellite
China Satellite-Based Earth Observation Market
Satellite
Global Satellite Propulsion System Market
Satellite
United States Satellite Communications Market
Satellite
Middle East Satellite-Based Earth Observation Market
Satellite
Global Dish Antennas Market
Satellite
LEO Satellite System Market
Satellite
Asia-Pacific Military Satellite Market
Satellite
Satellite Data Service Market
Satellite
UK Satellite Imagery Services Market
Satellite
Israel Satellite Imagery Services Market
Satellite
Communication Satellite Launch Services Market