
 Airplane and Helicopter Hangar Doors Market | 2026-2036
Airplane and Helicopter Hangar Doors Market Size, Share, and Industry Trends Forecast 2026-2036
Airplane and Helicopter Hangar Doors Market Outlook
The EU Green Deal is pivoting European aviation infrastructure toward lower-carbon hangar construction, which is tightening thermal performance requirements for door assemblies. Champion Door leverages its Nordic engineering heritage to dominate cold-climate specifications across Northern Europe. Butzbach GmbH sustains manufacturing scale from its German base, while Hydroswing anchors the hydraulic door segment with North American production capacity.
Airplane and helicopter hangar doors are engineered structural closures spanning 20 to 60 meters in width, fabricated from aluminum extrusions, steel trusses, or composite sandwich panels, and designed to withstand wind loads exceeding 150 km/h while sealing against temperature differentials and debris ingress. Their primary function is to protect aircraft during maintenance, storage, and pre-flight preparation while accommodating the vertical tail clearance of commercial jets and rotorcraft. Sliding door systems occupy the mature volume tier across legacy military bases and regional aviation facilities, whereas hydraulic doors command premium positioning in new commercial airport construction where single-panel operation reduces mechanical complexity. Composite material adoption is accelerating fastest among private hangar developers seeking corrosion resistance in coastal environments.
FAA airfield design standards govern door height and emergency egress integration across United States installations, while EASA certifies structural load ratings for European aviation facilities under its continuing airworthiness framework. The EU F-Gas Regulation indirectly shapes demand by pressuring hangar operators to improve building envelopes and reduce HVAC leakage through higher-performance door seals. Stakeholders must weigh aluminum tariff exposure against composite supply chain maturity when specifying materials for upcoming aviation infrastructure commitments.
Market Dynamics
The EU F-Gas Regulation is compressing HVAC leakage tolerances across European aviation infrastructure, forcing hangar operators to specify higher-performance door seals and thermal breaks. This regulatory pressure cascades through material selection, installer certification requirements, and long-term maintenance contracting structures.
Growth Catalysts
- FAA airfield design standards:United States commercial airports are expanding covered maintenance bays to accommodate larger aircraft fleets, mandating wider door clearances and integrated emergency egress systems.
- Composite sandwich panel technology:Private hangar developers in coastal environments are specifying corrosion-resistant door skins that outlast aluminum in salt-air conditions.
- EASA continuing airworthiness framework:European facilities must demonstrate structural load ratings for hangar closures, creating certified demand for engineered door systems.
Market Restraints
- Aluminum tariff exposure:Cross-border material sourcing faces duty volatility that disturbs project budgeting for frame fabrication.
- Hydraulic actuator supply concentration:Precision cylinder manufacturing clusters in German and Japanese industrial corridors, creating single-source vulnerability.
- Wind load engineering complexity:Doors spanning 60 meters require finite element analysis certification that extends bid timelines.
Strategic Opportunities
- EU Green Deal thermal mandates:Building envelope performance requirements are opening specification windows for vacuum-insulated door panels.
- Urban air mobility infrastructure:Vertiport construction in France and Germany requires compact helicopter door systems with rapid cycle times.
- Digital twin integration:Predictive maintenance platforms are creating attach-rate potential for sensor-embedded door operators.
Industry Challenges
- Certified installer scarcity:EASA mandates specialized technician qualifications for structural door modifications that outpace training pipeline capacity.
- Legacy sliding door retrofit complexity:Military base modernization projects must integrate new hydraulic systems with existing structural openings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airplane and Helicopter Hangar Doors Market |
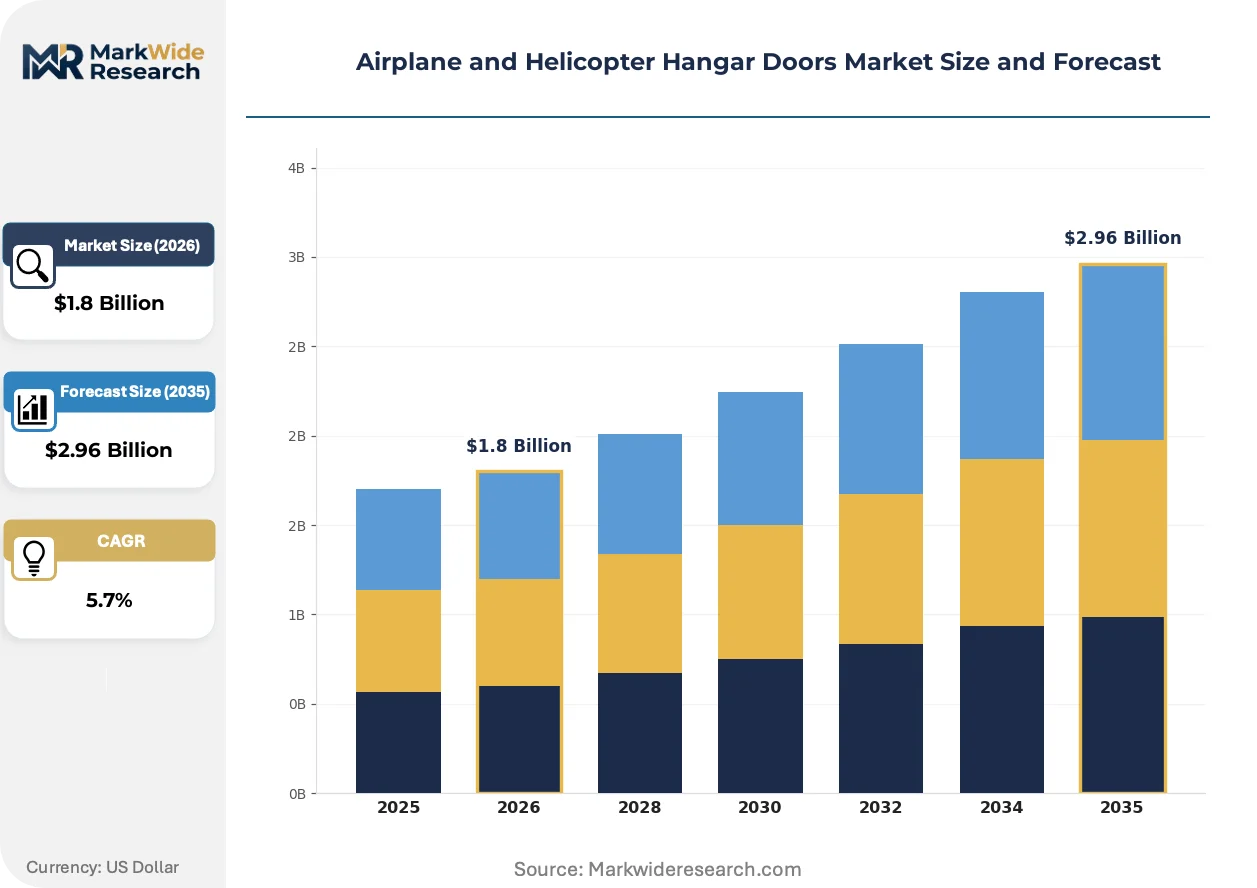
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sliding Doors, Bi-Fold Doors, Manual Doors, Hydraulic Doors End User: Aviation Facilities, Private Hangars, Military Bases, Commercial Airports Material: Aluminum, Steel, Composite, Fiberglass Installation Type: New Construction, Renovation, Retrofit, Custom Installations |
| Companies Covered | Champion Door, Wessex Industrial Doors Ltd., Jewers Doors Ltd., Door Engineering and Manufacturing, LLC, Hydroswing, Butzbach GmbH, Norco Manufacturing Corp., AeroDoor, Spec-Dor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airplane and Helicopter Hangar Doors Market Strategic Shifts
Aviation infrastructure procurement is pivoting toward lifecycle-cost contracting that bundles door installation with predictive maintenance services. This shift compresses upfront capital decisions into multi-year operational agreements.
Aluminum extrusion framing with integrated thermal breaks is modularizing hangar door construction, allowing field assembly of 40-meter spans without crane-dependent single-piece delivery. Regional airport authorities in Spain and Italy are adopting this approach to bypass narrow access roads. The technology is modularizing project logistics and reducing site preparation costs for constrained airfields.
The EU F-Gas Regulation is tightening permissible leakage rates for fluorinated gases used in hangar climate control, compelling operators to improve building envelope integrity. Door seal specifications now carry HVAC system compliance implications. Northern European facilities are responding with triple-gasket designs and automated compression systems.
Buyer procurement committees are consolidating vendor relationships from component-specific contracts to integrated building envelope packages. General contractors are displacing specialized door subcontractors in bid negotiations. This concentration is most visible in German commercial airport expansions where single-source accountability reduces interface risk.
Airplane and Helicopter Hangar Doors Market Segmentation
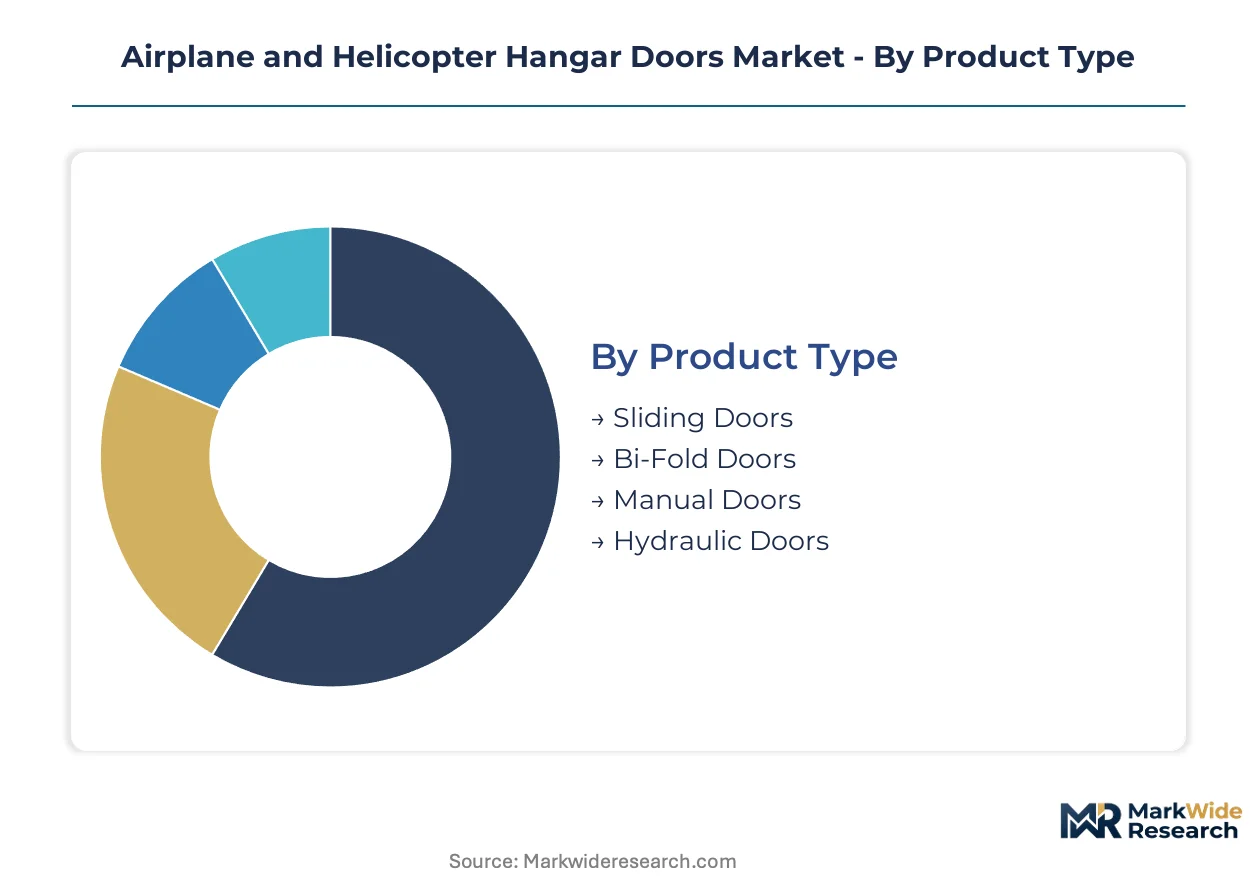
Hangar door procurement decisions cascade through four distinct lenses: operational cycle requirements, facility ownership structures, environmental exposure conditions, and project delivery timelines. Each segmentation axis carries different weight across military, commercial, and private aviation contexts.
Product Type:
Facility operators select door mechanisms based on clear opening speed, structural load tolerance, and lifecycle maintenance burden.
- Hydraulic Doors:Single-panel vertical lift systems employing precision cylinder actuation deliver the widest uninterrupted clearances for commercial jet tail sections. Demand concentrates in new German and French airport expansions where EASA structural certification requirements favor integrated engineered solutions with documented load ratings.
- Sliding Doors:Horizontal track-mounted panels remain the default specification across legacy United States military installations where existing structural frames constrain retrofit options. Procurement volumes here reflect base modernization budgets rather than new construction cycles.
- Bi-Fold Doors:Vertically stacking panels divide wind loads across multiple hinge points, suiting mid-span commercial hangars in coastal Spain and Italy where modular field assembly bypasses narrow access constraints.
- Manual Doors:Hand-crank or push-operated systems serve small private helicopter hangars below 15-meter spans where electrical infrastructure is unavailable or cost-prohibitive.
Volume sits with Sliding Doors; growth tilts toward Hydraulic Doors.
End User:
Capital allocation authority and specification standards diverge sharply across ownership categories.
- Commercial Airports:FAA-mandated covered maintenance bay expansions drive demand for 40-60 meter clearances with integrated emergency egress systems. United States gateway airports in Texas and California anchor procurement volumes through fleet upgauging programs.
- Private Hangars:Individual owners prioritize corrosion-resistant composite skins and rapid-cycle hydraulic operation for personal rotorcraft and business jets. Coastal Florida and Mediterranean France exhibit concentrated development activity.
- Military Bases:United States Air Force and Army Aviation installations specify hardened steel framing with blast-resistant specifications, though legacy sliding door retrofits dominate near-term spending.
- Aviation Facilities:Regional maintenance, repair, and overhaul operators in Germany and the United Kingdom balance door performance against 20-year lifecycle cost models under EU Green Deal thermal mandates.
Procurement scale favors Commercial Airports; specification innovation originates with Private Hangars.
Material:
Environmental exposure and tariff exposure frame material selection tradeoffs.
- Aluminum:Extruded framing with integrated thermal breaks dominates Northern European specifications where Champion Door and Butzbach GmbH manufacturing proximity reduces logistics complexity.
- Composite:Sandwich panel construction with fiberglass-reinforced skins gains share fastest among private developers in salt-air environments from Florida to the French Riviera.
- Steel:Truss-frame assemblies persist in military and heavy commercial applications requiring ballistic or blast-resistant ratings.
- Fiberglass:Pultruded profiles serve niche coastal specifications demanding dielectric properties for radar-adjacent installations.
Installed base rests with Aluminum; composite substitution accelerates most quickly in coastal markets.
Installation Type:
Project delivery modality determines contractor qualification requirements and warranty structures.
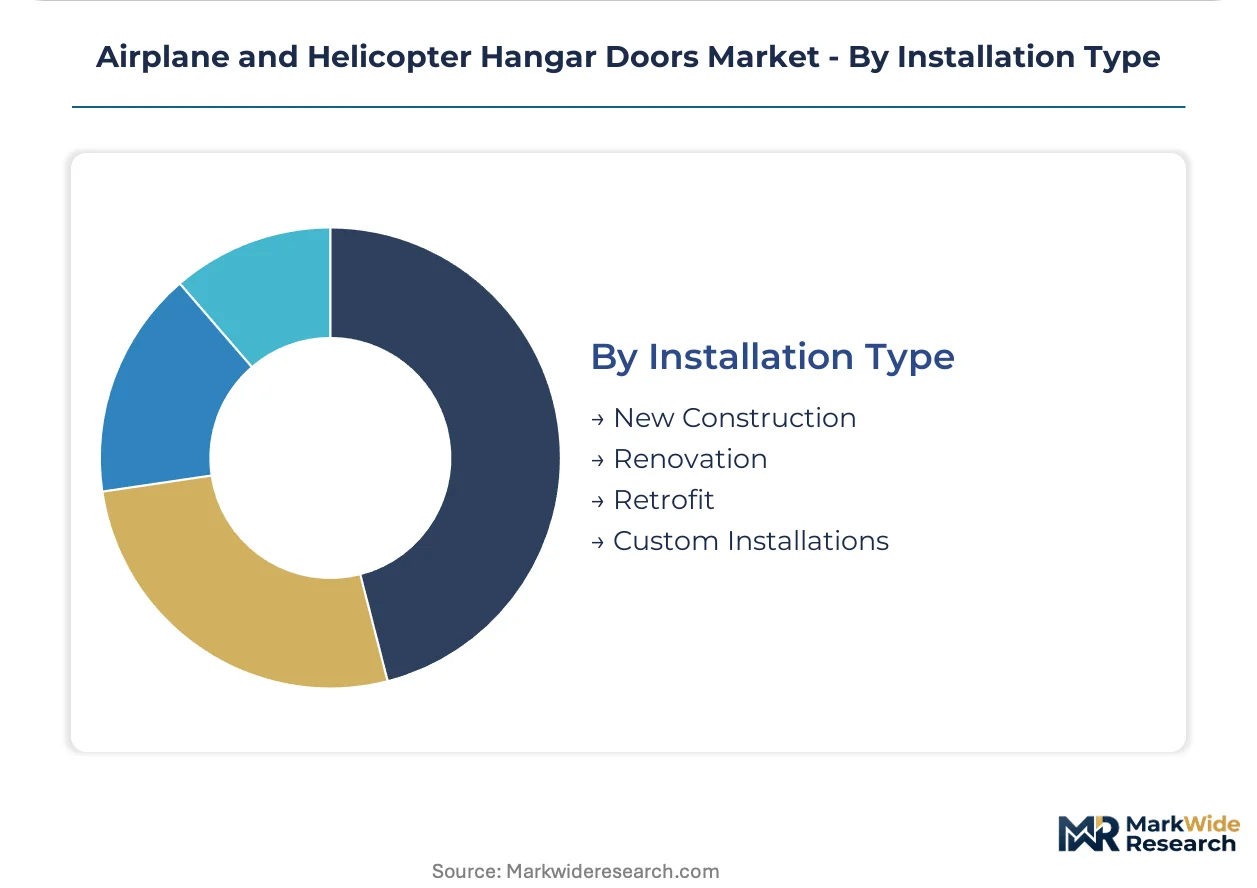
- New Construction:Greenfield airport terminals in France and Germany enable integrated door-frame-foundation engineering with single-source accountability.
- Retrofit:Existing structural opening modifications dominate United States military base contracts where hydraulic systems replace aging sliding mechanisms.
- Renovation:Partial envelope upgrades with seal replacement and operator modernization serve European facilities responding to EU F-Gas Regulation leakage tolerances.
- Custom Installations:Non-standard spans and specialized clearances for unusual rotorcraft or heritage aircraft collections command premium engineering fees.
Contract value aggregates in New Construction; project frequency concentrates in Retrofit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hamburg anchors European aviation infrastructure procurement, with Airbus operations and Lufthansa Technik maintenance facilities driving specification standards for wide-body hangar clearances across Northern Europe.
United States
Dallas-Fort Worth and Los Angeles international airports are expanding covered maintenance bays under FAA airfield design standards requiring 60-meter door clearances for fleet upgauging. The FAA mandates integrated emergency egress systems and wind load certifications that extend engineering timelines. Texas and California anchor procurement volumes through commercial airport capital programs.
Germany
Frankfurt and Munich airport expansions prioritize aluminum-framed hydraulic systems under EASA continuing airworthiness frameworks. The EU F-Gas Regulation compresses HVAC leakage tolerances, forcing thermal break specifications and triple-gasket door seals. Baden-Württemberg and Bavaria concentrate manufacturing capacity for precision actuator components.
France
Toulouse-Blagnac infrastructure supports Airbus final assembly line logistics with engineered door systems certified for A350 tail clearance. EASA structural load ratings govern hangar construction across the Occitanie and Île-de-France regions. The EU Green Deal pivots new vertiport construction toward rapid-cycle helicopter door specifications for urban air mobility.
United Kingdom
London Heathrow and Manchester maintenance facilities balance lifecycle cost models against EU-origin thermal mandates post-Brexit. The Civil Aviation Authority maintains alignment with EASA certification standards for structural door modifications. Southeast England clusters MRO operators specifying composite sandwich panels for corrosion resistance in coastal environments.
Canada
Calgary and Vancouver international airports retrofit legacy sliding systems with hydraulic alternatives under Transport Canada airfield standards. Cold-climate specifications from Champion Door's Nordic engineering heritage penetrate Prairie Provinces and British Columbia. Health Canada building codes intersect with aviation safety requirements for insulated door assemblies.
Airplane and Helicopter Hangar Doors Market Competitive Environment
The competitive structure tilts toward specialized engineering fabricators with demonstrated EASA and FAA certification track records. Market concentration remains moderate, with regional leaders commanding specification influence through proximity to major airport authorities. Three archetypes dominate: Nordic cold-climate specialists, German precision-engineering houses, and North American hydraulic-system integrators. Consolidation pressure manifests through strategic partnerships for actuator supply security and geographic licensing arrangements for thermal break technology.
Among European fabricators, Butzbach GmbH and Champion Door exemplify the engineering-intensive tier, with the former representing German manufacturing scale and the latter anchoring Nordic cold-climate specifications. Hydroswing occupies a distinct position as the North American hydraulic door archetype. These three companies illustrate how regional certification proximity and climate-specific engineering heritage shape competitive positioning across procurement committees.
| Leading Market Players |
|---|
| Champion Door |
| Wessex Industrial Doors Ltd. |
| Jewers Doors Ltd. |
| Door Engineering and Manufacturing, LLC |
| Hydroswing |
| Butzbach GmbH |
| Norco Manufacturing Corp. |
| AeroDoor |
| Spec-Dor |
| Others |
Value Chain & Pricing Dynamics
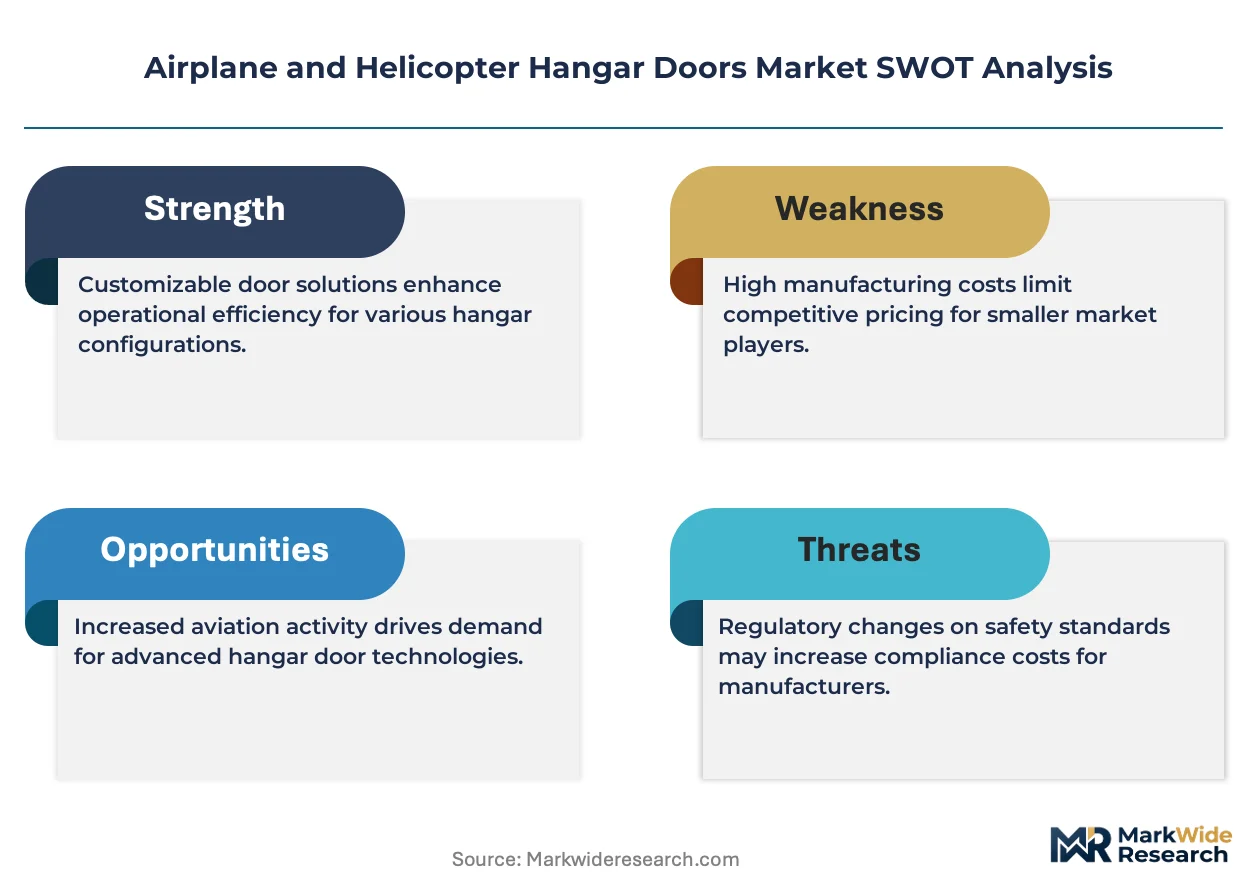
Aluminum LME spot pricing volatility cascades through hangar door manufacturing into three distinct procurement tiers: premium hydraulic systems for EASA-certified commercial airports, mid-grade bi-fold assemblies for regional aviation facilities, and economy sliding retrofits for military base modernization programs. This commodity-driven segmentation concentrates pricing power among fabricators with captive extrusion capacity in Germany and France, while buyers in coastal markets absorb composite material premiums to offset salt-air corrosion risks.
Pricing Analysis
Lifecycle-cost contracting anchors value-based pricing for commercial airport installations, where door specification bundles predictive maintenance services and thermal performance guarantees. Price differentiation separates EASA-certified hydraulic systems with documented load ratings from uncertified alternatives, while volume scale and geographic delivery cost stratify regional procurement. Cost compression in aluminum-framed segments intensifies as tariff exposure disrupts project budgeting, with private hangar developers in Florida and Mediterranean France exhibiting the highest price sensitivity due to discretionary capital allocation.
Supply Chain Analysis
Freight costs for single-panel hydraulic systems exceeding 40-meter spans constrain field assembly logistics, favoring modular bi-fold alternatives in markets with narrow access infrastructure. Precision actuator manufacturing concentrates in Germany and Japan, creating single-source vulnerability for cylinder components. Raw material dependencies span aluminum extrusions from Northern European mills, composite sandwich panels from specialized laminators, and steel truss assemblies from heavy fabrication facilities. Distribution runs through general contractors consolidating building envelope accountability in German commercial airport expansions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates under supply-constrained conditions where certified installer scarcity outpaces training pipeline capacity, propping pricing power for EASA-qualified fabricators across European aviation infrastructure.
For Market Incumbents: To counter hydraulic actuator supply concentration, secure long-term cylinder sourcing agreements with Baden-Württemberg precision manufacturers and expand backward integration into thermal break extrusion technology. Champion Door and Butzbach GmbH should deepen certification investment for EU Green Deal thermal mandates to lock out uncertified competitors. For New Entrants and Emerging Players: Capture specification windows in vertiport urban air mobility infrastructure across France and Germany, where rapid-cycle helicopter door demand outpaces established vendor capacity. Target coastal private hangar segments in Florida and the French Riviera with corrosion-resistant composite offerings, deploying direct-to-developer sales channels that bypass general contractor consolidation. For Investors and Strategic Acquirers: Distressed-cycle entries favor Nordic cold-climate engineering specialists with demonstrated FAA and EASA certification track records in Canadian Prairie Provinces and Northern European markets. Long-term viability hinges on thermal performance technology ownership as building envelope mandates tighten. Monitor EU F-Gas Regulation enforcement intensity as the inflection signal for premium seal specification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment in EASA Thermal Standards | EU F-Gas Regulation compliance creates specification barriers for uncertified competitors in German airport expansions. |
| Backward Integration into Actuator Manufacturing | German and Japanese cylinder supply concentration demands captive production capacity to secure delivery reliability. |
| Vertiport Door System Development | Urban air mobility infrastructure in France and Germany requires rapid-cycle specifications absent from legacy portfolios. |
| Composite Panel Supply Agreement | Coastal corrosion resistance specifications in Florida and Mediterranean France accelerate fiberglass-reinforced substitution. |
| Predictive Maintenance Platform Launch | Lifecycle-cost contracting trends favor sensor-embedded operators with attach-rate service revenue potential. |
Study Parameters
Multi-period observation of aluminum pricing indices, EASA certification timelines, and FAA airfield construction permits anchored the trend analysis, supplemented by interviews with hangar door procurement managers at commercial airports, maintenance directors at military aviation installations, and project engineers at German general contracting firms. Secondary validation drew from FAA airfield design standard filings, EASA continuing airworthiness documentation, EU F-Gas Regulation enforcement records, and customs data on aluminum extrusion trade flows. Bottom-up project pipeline tracking triangulated against top-down aviation infrastructure capital expenditure forecasts.
The input-output matrix framework modeled demand across product type, end user ownership structure, material specification, and installation modality, with CAGRs derived from regression analysis of historical procurement volumes and projected fleet expansion schedules. Door span requirements, wind load certification tiers, and thermal performance thresholds served as industry-specific forecast inputs throughout the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to aluminum tariff volatility, hydraulic actuator supply disruptions, and EU Green Deal enforcement acceleration. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Commercial Aircraft Lavatory System Market
Aircraft
Global Commercial Aircraft Seat Actuation Market
Aircraft
Fixed Wing Turbine Aircraft Market
Aircraft
Small Evtol Aircraft Market
Aircraft
Asia-Pacific General Aviation Market
Aircraft
Aircraft Nacelle Systems Market
Aircraft
Commercial Aircraft Aerostructures Market
Aircraft
Aircraft Cables Market
Aircraft
Europe Fighter Aircraft Market
Aircraft
Aircraft Leasing Market
Aircraft
Aircraft Sequencing System Market
Aircraft
Aerospace Winglet System Market
Aircraft
Aircraft Ailerons Market
Aircraft
Drone Turbojet Engine Market
Aircraft
Tilt Rotor Aircraft Market
Aircraft
Freighter Aircraft Market