
 Single-Seat Gyrocopter Market | 2026-2036
Single-Seat Gyrocopter Market Size, Share, and Industry Trends Forecast 2026-2036
Single-Seat Gyrocopter Market Insights
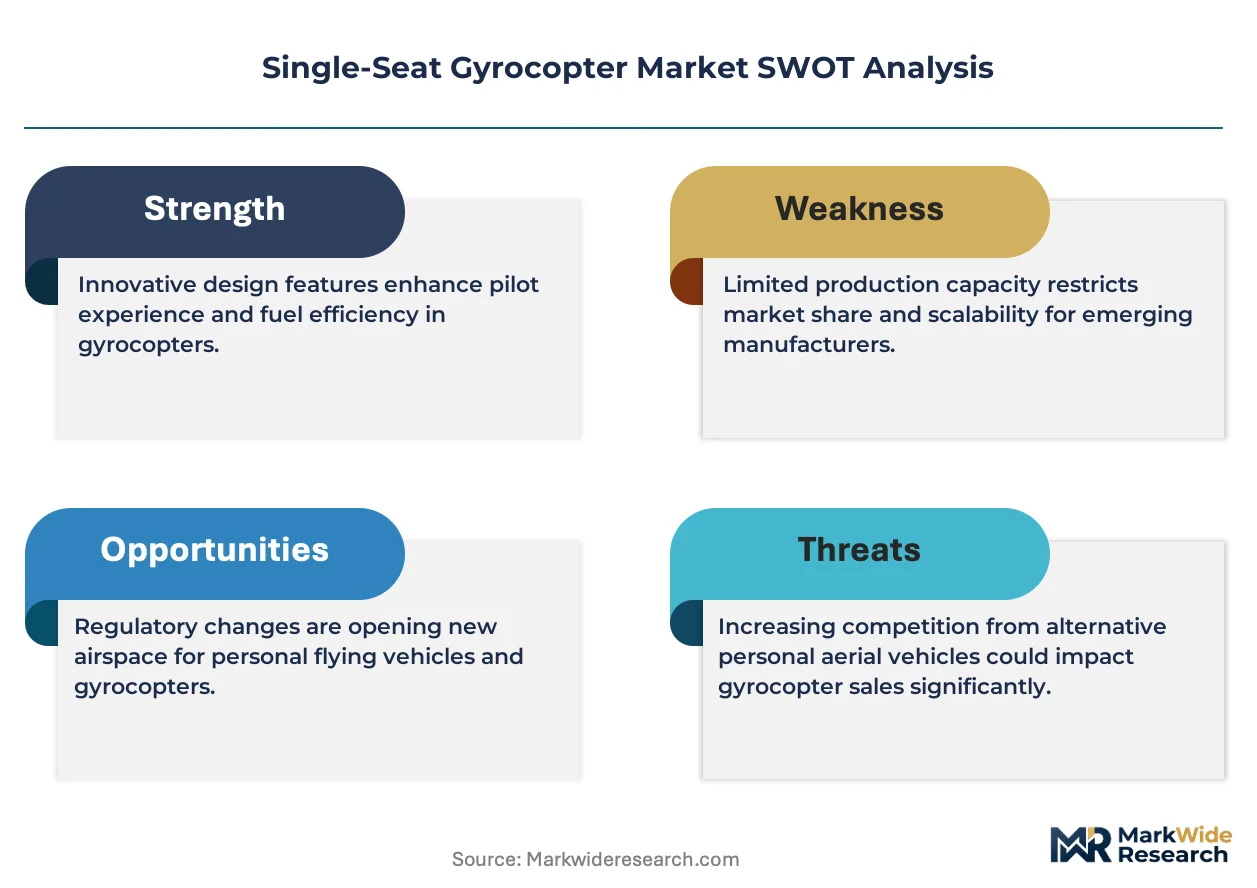
Carbon fiber composites is rebalancing airframe economics as manufacturers replace traditional aluminum rotor mast assemblies to cut weight and extend flight endurance. AutoGyro leverages its German engineering base to sustain premium positioning across European markets. Sport Copter anchors North American distribution through specialized dealer networks focused on experimental and light sport categories. Niki Rotor Aviation competes on manufacturing scale from its Bulgarian facility, supplying components to multiple European assemblers.
A single-seat gyrocopter employs an unpowered rotor in autorotation for lift, with thrust generated by a rear-mounted propeller, typically operating at 60–120 knots with stall-resistant flight characteristics suited to low-altitude maneuvering. The design serves personal recreation, flight training, and surveillance missions where helicopter complexity proves economically prohibitive. Open cockpit configurations dominate unit shipments among private pilots seeking minimal acquisition cost, while enclosed cockpit variants capture stronger margins from law enforcement and surveillance operators requiring sensor payload protection. Electric propulsion technology represents the fastest-growing segment as battery energy density improvements enable shorter training missions with reduced noise signatures near populated areas.
FAA Part 103 ultralight rules and EASA CS-LSA certification frameworks govern airworthiness standards, with FAA inspectors emphasizing pilot training hour minimums that directly expand flight school procurement volumes. The EU AI Act and emerging national drone integration policies are creating overlapping regulatory jurisdictions where gyrocopter operators must clarify altitude separation protocols with unmanned traffic management systems. Stakeholders must monitor how certification reciprocity agreements between FAA and EASA evolve, as harmonized standards would reshape cross-border manufacturing economics and aftermarket parts distribution.
Market Dynamics
Electric propulsion systems are compressing the total cost of ownership equation for flight schools and recreational operators, forcing airframe manufacturers to redesign powertrain mounting architectures and battery thermal management systems around 400-volt electrical buses.
Growth Catalysts
- FAA Part 103 ultralight framework:The United States maintains the most permissive operating rules for unlicensed pilots, sustaining a baseline demand channel for open-cockpit designs that require no type certificate or medical certification.
- Carbon fiber rotor mast fabrication:Automated fiber placement and resin transfer molding are slashing airframe weight by 30-40% versus legacy aluminum assemblies, extending flight endurance for surveillance missions.
- Flight training infrastructure clustering:Established aerodromes in Germany, Australia, and the United States are expanding dedicated gyroplane curricula, creating predictable fleet replacement cycles for training aircraft.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack costs for electric variants remain hostage to cathode material processing capacity concentrated in China, exposing European and North American assemblers to input volatility.
- EASA CS-LSA certification timeline:The European framework demands extensive flight testing and quality system audits that stretch type certificate acquisition to 18-24 months, freezing out smaller airframe developers.
- Autogyro substitution by electric fixed-wing:Pipistrel and similar manufacturers are delivering Part 103-compliant electric fixed-wing aircraft at comparable price points with simpler pilot transition training.
Strategic Opportunities
- Australian outback patrol applications:Cattle station operators and mining security teams are evaluating gyroplanes for fence-line inspection and wildlife monitoring where runway access is limited and helicopter charter costs are prohibitive.
- EU AI Act unmanned traffic integration:The regulatory framework is creating formal altitude separation protocols between manned gyroplanes and drone corridors, potentially unlocking urban periphery routes for commercial operators.
- Direct-to-consumer digital sales channels:Manufacturers are bypassing traditional dealer networks for experimental category kits, capturing margin and reducing delivery lead times for builder-assist programs.
Industry Challenges
- Rotorcraft-rated instructor scarcity:Flight schools in the United States and Germany report 6-12 month waiting lists for gyroplane-specific CFI training, throttling fleet expansion plans.
- Battery thermal runaway containment:Electric airframe developers must engineer crash-resistant battery enclosures and venting systems without mature certification precedents, extending engineering validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single-Seat Gyrocopter Market |
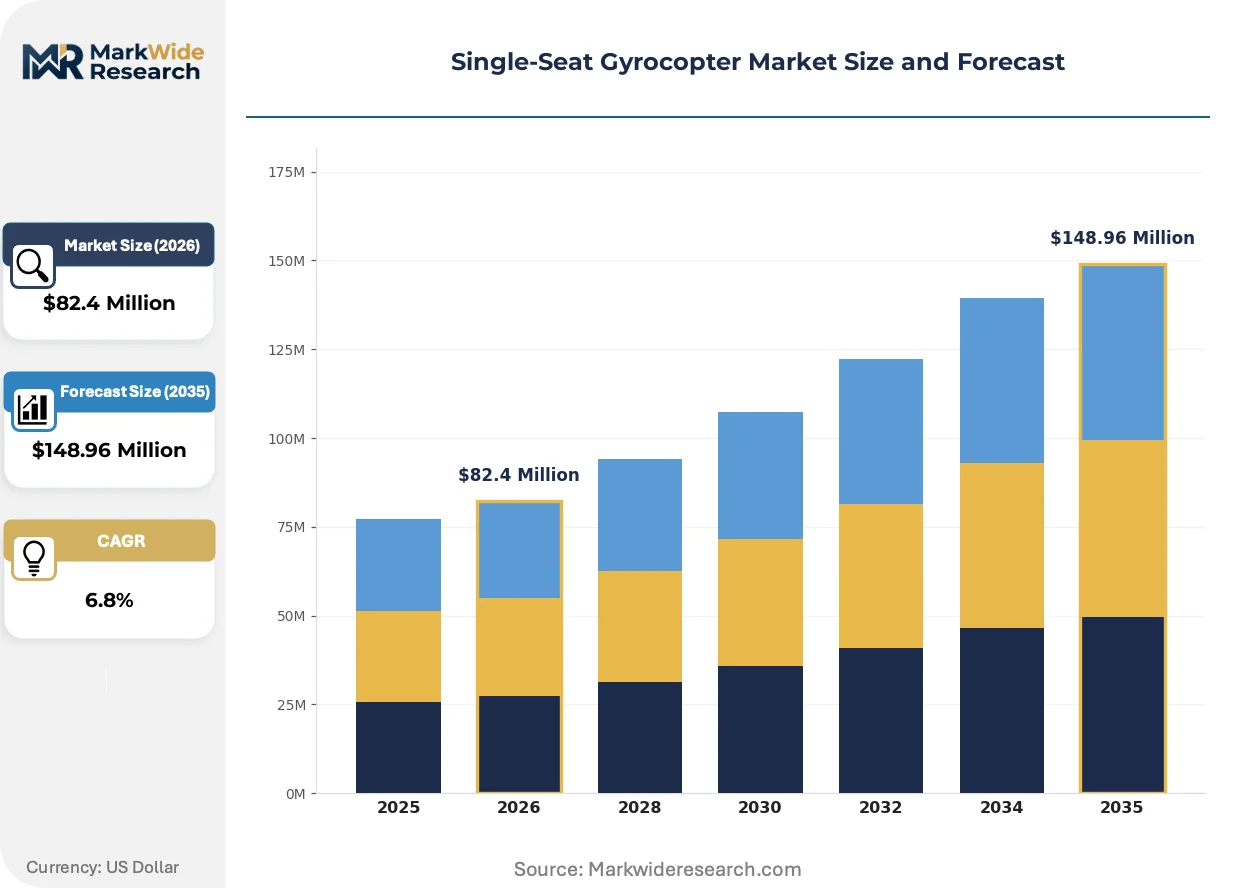
| Market Size in 2026 | $82.4 Million |
| Market Size in 2035 | $148.96 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Cockpit, Enclosed Cockpit, Experimental, Light Sport, Ultralight Technology: Rotary Wing, Fixed Wing, Hybrid, Electric Propulsion, Gasoline Engine Application: Aerial Photography, Personal Recreation, Surveillance, Flight Training, Agriculture Monitoring End User: Private Pilots, Flight Schools, Law Enforcement, Agricultural Operators, Research Institutions |
| Companies Covered | Aviomania Aircraft, Sport Copter, AutoGyro, Niki Rotor Aviation, Rotorvox, Trixy Aviation Products, Aviation Artur Trendak, Carpenterie Pagotto, ELA Aviation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single-Seat Gyrocopter Market Trends and Innovations
Propulsion electrification and air traffic management digitization are converging to redefine operational economics and flight corridor access for single-seat operators.
Silicon carbide power electronics are integrating into motor controller designs, enabling higher switching frequencies that reduce motor weight and improve regenerative braking efficiency during autorotation descent. Flight schools in Germany are piloting these systems for circuit training missions where noise abatement restrictions limit conventional Rotax-powered operations. The technology is integrating battery-electric variants into urban periphery training markets previously closed to piston noise signatures.
EASA's evolving CS-LSA certification memos are tightening rotor system fatigue life demonstration requirements, forcing manufacturers to submit extended flight test data and metallurgical analysis. The industrial consequence is a bifurcation between established type certificate holders and experimental kit builders who operate outside the framework. Light sport category applicants in Bulgaria and the Czech Republic are responding by consolidating quality management systems under EN 9100 aerospace standards to preempt audit findings.
Recreational buyers are compressing their purchasing cycles through fractional ownership cooperatives and club-based maintenance pools, displacing the traditional sole-owner model that dominated the 2010s. Specialized online marketplaces are connecting sellers across national borders, disrupting the territorial exclusivity that protected legacy dealer networks. This pattern is most visible in Australia, where dispersed population centers and high inter-city shipping costs historically entrenched regional distributor monopolies.
Single-Seat Gyrocopter Market Segmentation
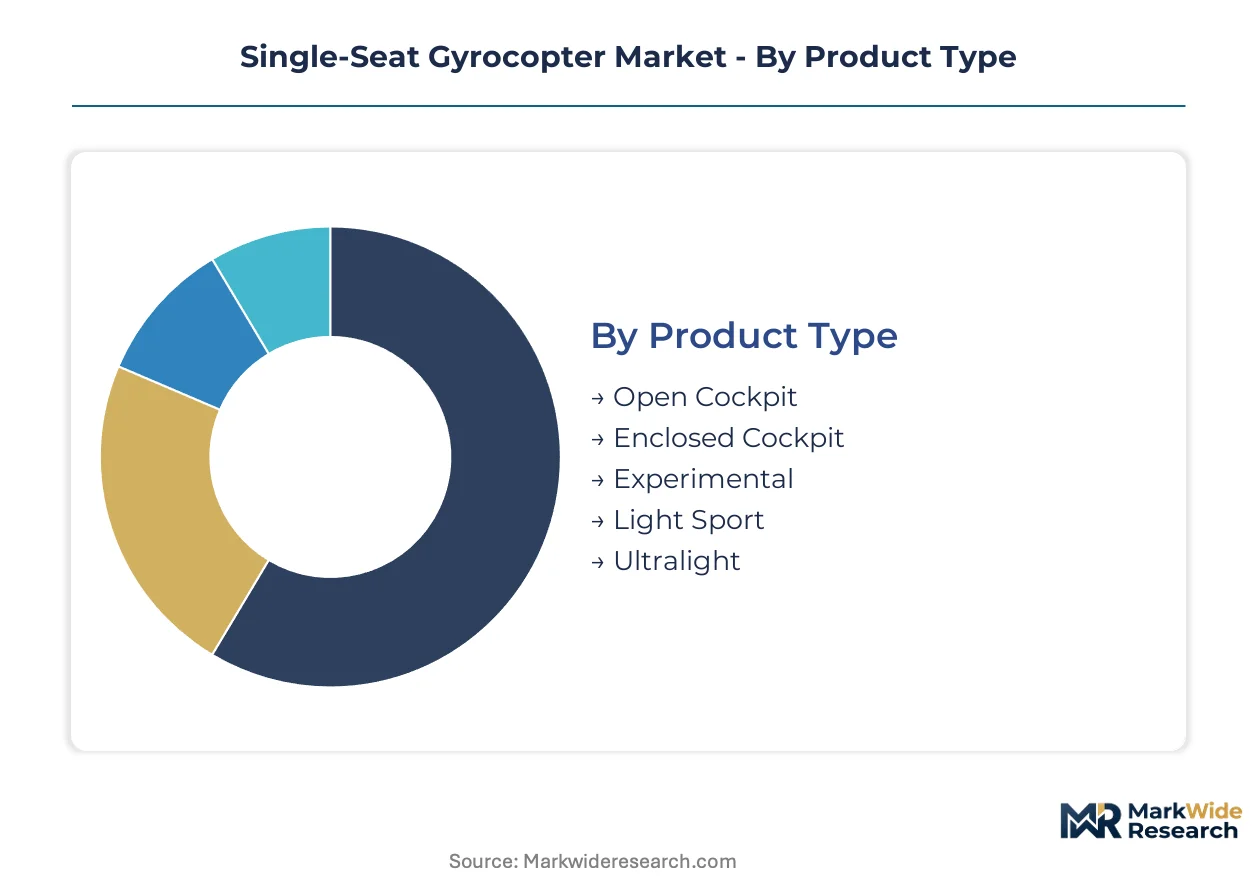
Single-seat gyrocopter procurement patterns diverge sharply across certification tiers, with FAA Part 103 ultralight rules enabling direct consumer sales while EASA CS-LSA compliance demands structured quality audits that reshape manufacturer economics.
Product Type:
FAA Part 103 ultralight and experimental categories operate outside type certificate requirements, whereas light sport and enclosed cockpit variants trigger extensive flight testing protocols under EASA and FAA frameworks.
- Open Cockpit:Minimalist tube-and-fabric construction with exposed pilot stations dominates recreational sales in the United States under Part 103 rules. Private pilots in Florida and Arizona clusters favor these configurations for their sub-$50,000 entry points and simplified owner maintenance.
- Enclosed Cockpit:Composite fuselage shells with integrated instrument panels and weather protection command premium positioning from law enforcement and surveillance operators. German federal police units specify these variants for border patrol missions requiring sensor payload integration.
- Experimental:Kit-built airframes sold as builder-assist programs bypass dealer networks entirely. Australian recreational aviation clubs aggregate component orders to reduce per-unit shipping costs from European suppliers.
- Light Sport:Factory-built designs under ASTM consensus standards require manufacturer quality system audits but permit reduced pilot medical certification. Bulgarian assemblers target this category for European market access.
- Ultralight:Weight-restricted configurations below 254 pounds empty mass operate without pilot licensing in US airspace. Demand concentrates among retirement-age buyers seeking minimal regulatory burden.
Leading the category by volume: Open Cockpit. Growing fastest: Enclosed Cockpit.
Technology:
Powertrain selection determines airworthiness certification pathways, with electric propulsion forcing novel battery thermal management designs absent mature regulatory precedents.
- Rotary Wing:Autorotating rotor systems define gyrocopter flight mechanics, with unpowered main rotors providing stall-resistant lift characteristics. German flight schools specify these for ab initio training where helicopter transition complexity is prohibitive.
- Fixed Wing:Canard and delta configurations from competing ultralight manufacturers threaten gyrocopter substitution in recreational segments. Pipistrel's electric fixed-wing designs capture pilot candidates seeking simpler transition training.
- Hybrid:Series-hybrid architectures combining piston generators with electric motors remain pre-commercial, with battery energy density limitations constraining endurance.
- Electric Propulsion:Silicon carbide power electronics enable 400-volt architectures that reduce motor weight and enable regenerative braking during autorotation. Noise abatement restrictions in German urban peripheries are accelerating adoption for circuit training.
- Gasoline Engine:Rotax two-stroke and four-stroke powerplants dominate current fleet composition, with established maintenance networks and parts availability anchoring residual values.
Volume leadership: Gasoline Engine. Steepest expansion trajectory: Electric Propulsion.
Application:
Mission profiles determine payload and endurance specifications, with surveillance and training applications driving divergent airframe configurations.
- Aerial Photography:Gyro-stabilized gimbal mounts require reinforced rotor mast structures and vibration isolation systems. Australian mining operators deploy these for site documentation where helicopter charter rates exceed operational budgets.
- Personal Recreation:Weekend flying and cross-country touring sustain baseline demand across US Sun Belt states. Fractional ownership cooperatives in California are displacing traditional sole-owner purchasing patterns.
- Surveillance:Law enforcement and private security missions demand enclosed cockpits with integrated radio and sensor suites. German state police specifications require 4-hour endurance with 30-minute fuel reserves.
- Flight Training:Dedicated gyroplane curricula at established aerodromes create predictable fleet replacement cycles. US flight schools report 6-12 month waiting lists for rotorcraft-rated instructors, throttling expansion.
- Agriculture Monitoring:Cattle station operators in Australian outback regions evaluate gyroplanes for fence-line inspection and mustering support. Limited runway access favors short-field performance over fixed-wing alternatives.
Category volume leader: Personal Recreation. Fastest-gaining segment: Surveillance.
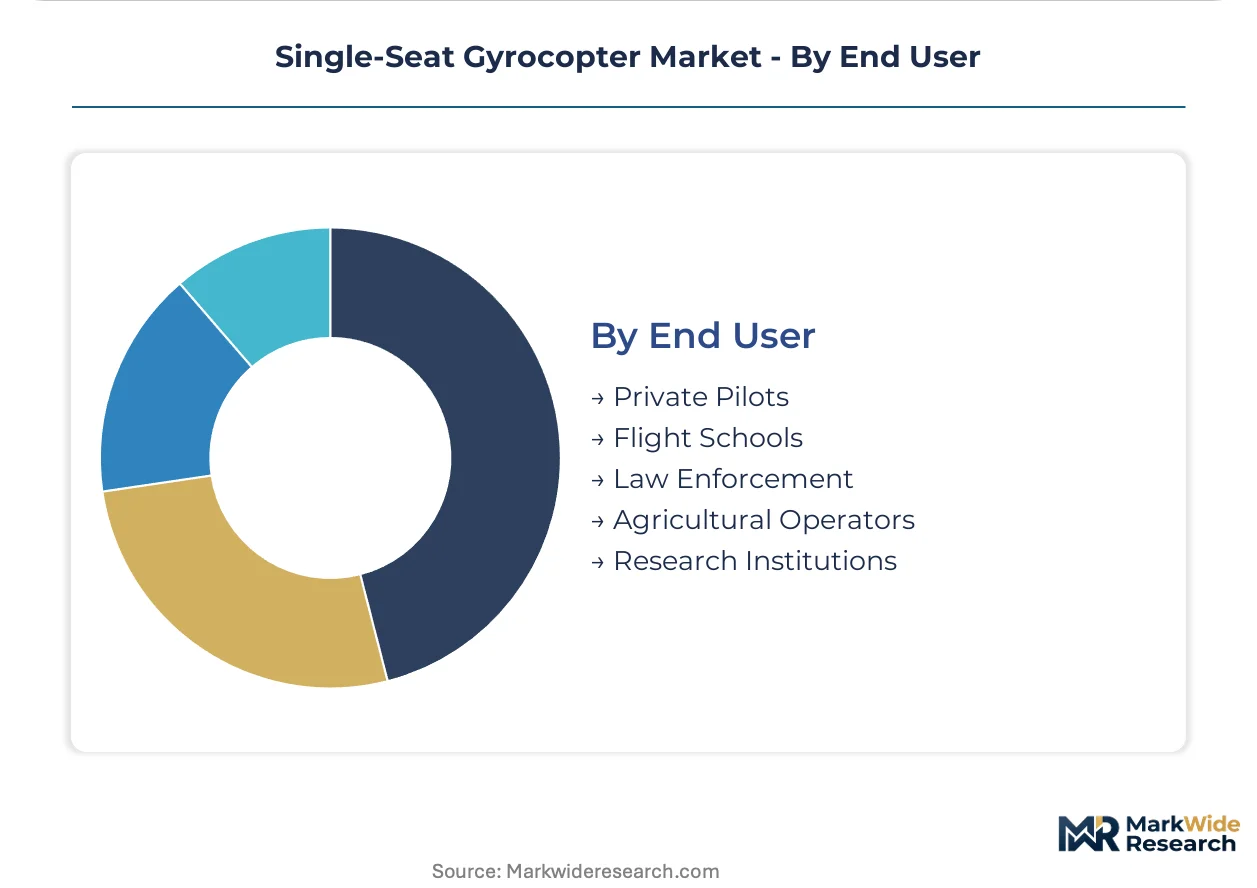
End User:
Customer type dictates pricing tolerance and aftermarket service expectations, with institutional buyers demanding manufacturer-direct support unavailable to recreational purchasers.
- Private Pilots:Individual owner-operators prioritize acquisition cost minimization and owner-maintainability. Digital marketplaces connecting cross-border sellers are eroding territorial dealer exclusivity.
- Flight Schools:Fleet purchasers require predictable maintenance intervals and instructor training program compatibility. German schools are piloting electric variants for noise-restricted training circuits.
- Law Enforcement:Agency procurement specifications mandate enclosed cockpits, integrated avionics, and manufacturer warranty terms. Bulgarian and Czech assemblers compete for European tender contracts.
- Agricultural Operators:Cattle station and vineyard managers seek utility configurations with external cargo attachment points. Australian demand concentrates in Queensland and Western Australia.
- Research Institutions:University aeronautics programs acquire experimental variants for flight dynamics research and student capstone projects. US land-grant universities maintain active gyroplane research programs.
Volume concentration: Private Pilots. Most rapid expansion: Flight Schools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Private pilot communities and flight training infrastructure cluster around established aerodromes in the United States, Germany, and Australia, with regulatory frameworks in each jurisdiction reshaping procurement patterns and manufacturer market access.
United States
Florida and Arizona Sun Belt states sustain recreational demand through year-round flying weather and dense private pilot populations. FAA Part 103 ultralight rules enable unlicensed operation of sub-254-pound open-cockpit designs, eliminating medical certification barriers for retirement-age buyers. California fractional ownership cooperatives are displacing traditional sole-owner purchasing patterns through digital marketplace aggregation.
Germany
Bavarian and Baden-Württemberg aerodromes anchor European flight training infrastructure with dedicated gyroplane curricula expanding fleet replacement cycles. EASA CS-LSA certification demands 18-24 month type certificate timelines with extensive flight testing and quality system audits. German federal police units specify enclosed-cockpit variants for border patrol missions requiring 4-hour endurance and integrated sensor suites.
Australia
Queensland and Western Australia cattle station operators evaluate gyroplanes for fence-line inspection and mustering support where runway access is limited. Civil Aviation Safety Authority regulations govern recreational aviation with medical certification exemptions parallel to FAA frameworks. Perth and Brisbane recreational aviation clubs aggregate component orders to reduce per-unit shipping costs from European suppliers.
Bulgaria
Sofia-based manufacturing facilities supply rotor system components to multiple European assemblers leveraging lower labor costs and EN 9100 aerospace quality certifications. Bulgarian assemblers target EASA light sport category compliance for European market access despite extended certification timelines. The country's emerging role reflects consolidation of quality management systems to preempt audit findings from notified bodies.
Single-Seat Gyrocopter Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with established type certificate holders defending premium positioning against experimental kit builders operating outside certification frameworks. The vendor base organizes into three strategic archetypes: German-engineered premium specialists, North American distribution-focused assemblers, and Eastern European component-scale suppliers. Competitive moves concentrate on carbon fiber rotor mast fabrication automation and direct-to-consumer digital sales channel development for experimental categories.
Among German-engineered premium specialists, AutoGyro GmbH exemplifies sustained market positioning through engineering-intensive product architectures. Sport Copter anchors North American distribution through specialized dealer networks focused on experimental and light sport categories. Niki Rotor Aviation occupies the scale-driven tier from its Bulgarian manufacturing base, supplying components to multiple European assemblers. These three entities represent distinct competitive vectors: premium engineering heritage, regional distribution control, and manufacturing cost optimization.
| Leading Market Players |
|---|
| Aviomania Aircraft |
| Sport Copter |
| AutoGyro |
| Niki Rotor Aviation |
| Rotorvox |
| Trixy Aviation Products |
| Aviation Artur Trendak |
| Carpenterie Pagotto |
| ELA Aviation |
| Others |
Pricing and Supply Chain Analysis
EU AI Act altitude separation mandates for manned-unmanned traffic integration are gating qualified battery thermal management suppliers and enclosed-cockpit certification pathways, compressing premium-tier pricing access to manufacturers with proven EASA CS-LSA audit histories.
Pricing Analysis
Volume leadership in open-cockpit Part 103 ultralights trades at thin margins against scarce margin capture in enclosed-cockpit surveillance variants. Three-tier pricing structure across premium, standard, and economy levels separates EASA-certified factory builds from ASTM light sport assemblies and experimental kit configurations. Cost compression in electric propulsion tiers is intensifying because lithium-ion cathode processing concentrates in China. Flight schools exhibit highest price sensitivity; law enforcement agencies demonstrate lowest.
Supply Chain Analysis
Refurbishment flows for Rotax gasoline powerplants and carbon fiber rotor mast assemblies sustain secondary parts markets in Australia and Germany. Component manufacturing concentrates in Bulgaria, Germany, and the Czech Republic. Raw material dependencies span carbon fiber prepreg from Japan, lithium nickel manganese cobalt oxide cathodes from China, and aluminum forgings from Eastern European mills. Single-source vulnerability in battery cell supply exposes European assemblers to input volatility. Distribution runs through specialized dealer networks for certified categories and direct-to-consumer digital channels for experimental kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where captive control over carbon fiber rotor mast fabrication and silicon carbide power electronics sourcing determines who captures margin in electrified variants.
For Market Incumbents: Anticipate electric fixed-wing substitution from Pipistrel and similar manufacturers by deepening in-house production of battery thermal management systems. Secure EN 9100 aerospace quality certifications to preempt EASA CS-LSA audit findings. Anchor rotorcraft-rated instructor training pipelines to throttle flight school fleet expansion by competitors.
For New Entrants and Emerging Players: Australian cattle station operators seeking fence-line inspection capability represent an underserved buyer archetype with limited runway access and prohibitive helicopter charter costs. Target Queensland and Western Australia agricultural operators with utility configurations featuring external cargo attachment points. Pursue direct-to-consumer digital sales for experimental kit categories to bypass entrenched dealer territorial exclusivity.
For Investors and Strategic Acquirers: EASA type certificate reciprocity agreements with FAA is the leading indicator that cross-border manufacturing economics and aftermarket parts distribution will consolidate around harmonized standards. Five-to-ten year viability favors vertically integrated assemblers with captive carbon fiber fabrication and certified electric propulsion architectures. Monitor Bulgarian and Czech quality management system consolidations under EN 9100 as early signals of acquisition-ready targets.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Fiber Rotor Mast Automation | AutoGyro and German specialists defend premium positioning through automated fiber placement weight reduction. |
| Silicon Carbide Power Electronics Integration | 400-volt architectures enable German flight schools to access noise-restricted urban training circuits. |
| Direct-to-Consumer Digital Channel Launch | Experimental kit builders capture margin and compress delivery lead times for builder-assist programs. |
| EASA CS-LSA Certification Investment | Bulgarian assemblers consolidate EN 9100 quality systems to preempt notified body audit findings. |
| Rotorcraft Instructor Pipeline Development | US and German flight schools address 6-12 month waiting lists throttling fleet expansion plans. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining primary interviews with gyroplane flight school operators, EASA certification consultants, carbon fiber composite suppliers, and recreational aviation club administrators. FAA Part 103 docket archives, EASA CS-LSA type certificate databases, and Australian Civil Aviation Safety Authority recreational aviation statistics provided validation layers. Bottom-up airframe production estimates triangulated against top-down flight training fleet replacement cycles.
Segment-level modeling tracked certification tier, propulsion technology, cockpit configuration, and end-user archetype across the projection horizon. CAGRs derived from airframe shipment trajectories, battery energy density improvement curves, and pilot training hour minimums. Forecast inputs incorporated EASA regulatory memo evolution, FAA-EASA reciprocity negotiation status, and electric propulsion endurance thresholds for circuit training missions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium-ion supply concentration and unmanned traffic management integration timelines. Forecasts reflect documented assumptions regarding battery thermal runaway containment certification precedents and rotorcraft-rated instructor availability. Practitioners should monitor EASA-FAA harmonization announcements and Chinese cathode material export policy shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Latin America General Aviation Market
Aircraft
Aviation Market
Aircraft
Aircraft Pushback Tugs Market
Aircraft
Aircraft Leasing Market
Aircraft
Cargo Compartment Latches Market
Aircraft
Japan Aviation Market
Aircraft
Airship Market
Aircraft
Aircraft Radome Market
Aircraft
Aircraft Wheels Market
Aircraft
Asia-Pacific Aviation Market
Aircraft
Commercial Aircraft Lighting Market
Aircraft
Asia-Pacific Attack Helicopter Market
Aircraft
Military Multirole Aircraft Market
Aircraft
Aircraft Aerostructures Market
Aircraft
Global Aircraft Heat Exchanger Market
Aircraft
Zero-Emission Aircraft Market