
 South Korea Aviation Market | 2026-2036
South Korea Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Aviation Market Analytics
The South Korean aviation sector is pivoting sharply between premium full-service operations and ultra-low-cost models. Korean Air sustains its long-haul premium positioning through transpacific network density and cargo integration. Jeju Air competes aggressively on domestic and short-haul leisure routes with standardized narrowbody economics. Hanwha Aerospace anchors the defense-industrial side, manufacturing airframes and components for domestic and export military programs.
South Korean aviation encompasses the design, manufacture, operation, and maintenance of fixed-wing and rotary aircraft operating within national airspace and international routes registered under the Korean registry, with commercial jets typically ranging from 70 to 400 seats and military platforms incorporating indigenous active electronically scanned array radar systems. The sector serves national defense, civilian mobility, and air freight logistics across Northeast Asian trade corridors. Commercial jets dominate current fleet value, while maintenance services capture expanding margin pools as aging aircraft require heavier checks. Avionics systems represent the fastest-growing technology segment, driven by retrofit mandates and next-generation cockpit upgrades across both civil and military fleets.
MFDS oversight applies to aeromedical standards for flight crews, while the Ministry of Land, Infrastructure and Transport regulates airworthiness certification and route licensing under Korea's aviation law framework. These bodies shape fleet renewal timelines, pilot training requirements, and market access conditions for new entrants. Stakeholders must monitor how carbon-neutral fuel mandates and bilateral air service negotiations reshape aircraft procurement strategies and hub development priorities across the peninsula.
Market Dynamics
The Ministry of Land, Infrastructure and Transport tightened carbon emission standards for fleet operations, pushing carriers toward newer engine technology while low-cost carriers expand domestic and regional route networks aggressively.
Growth Catalysts
- Carbon-neutral fuel mandates:The Ministry of Land, Infrastructure and Transport's emission standards are accelerating fleet renewal timelines and creating aftermarket demand for sustainable aviation fuel infrastructure.
- Jeju Island tourism corridors:Point-to-point leisure routes from secondary hubs at Gimhae and Jeju are capturing rising intra-Asian travel demand with standardized narrowbody economics.
- Active electronically scanned array radar:Indigenous military avionics development is integrating domestic defense procurement with export-oriented manufacturing capabilities at Hanwha Aerospace facilities.
Market Restraints
- Jet fuel price volatility:Carriers face margin compression from crude-linked kerosene costs that resist hedging effectiveness on regional routes.
- Pilot certification bottlenecks:MFDS aeromedical standards and Ministry-mandated training hours create multi-year qualification timelines that constrain crew availability.
- High-speed rail substitution:Korea Train Express corridors between Seoul and southern cities capture premium domestic passengers who would otherwise fly.
Strategic Opportunities
- Maintenance, repair and overhaul unbundling:Aging commercial fleets require heavier checks, shifting margin pools from OEMs to independent service providers with specialized narrowbody expertise.
- Next-generation cockpit retrofits:Avionics upgrades across civil and military fleets are creating demand for domestic system integrators with MFDS-certified manufacturing lines.
- Seoul-Incheon cargo integration:Transpacific freight density enables hybrid passenger-cargo configurations that optimize yield on long-haul routes.
Industry Challenges
- Airworthiness certification timelines:Ministry of Land, Infrastructure and Transport route licensing procedures delay new entrant market access by 18-24 months.
- Legacy system integration complexity:Retrofit mandates for carbon monitoring equipment conflict with existing flight management computer architectures on older narrowbodies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Aviation Market |
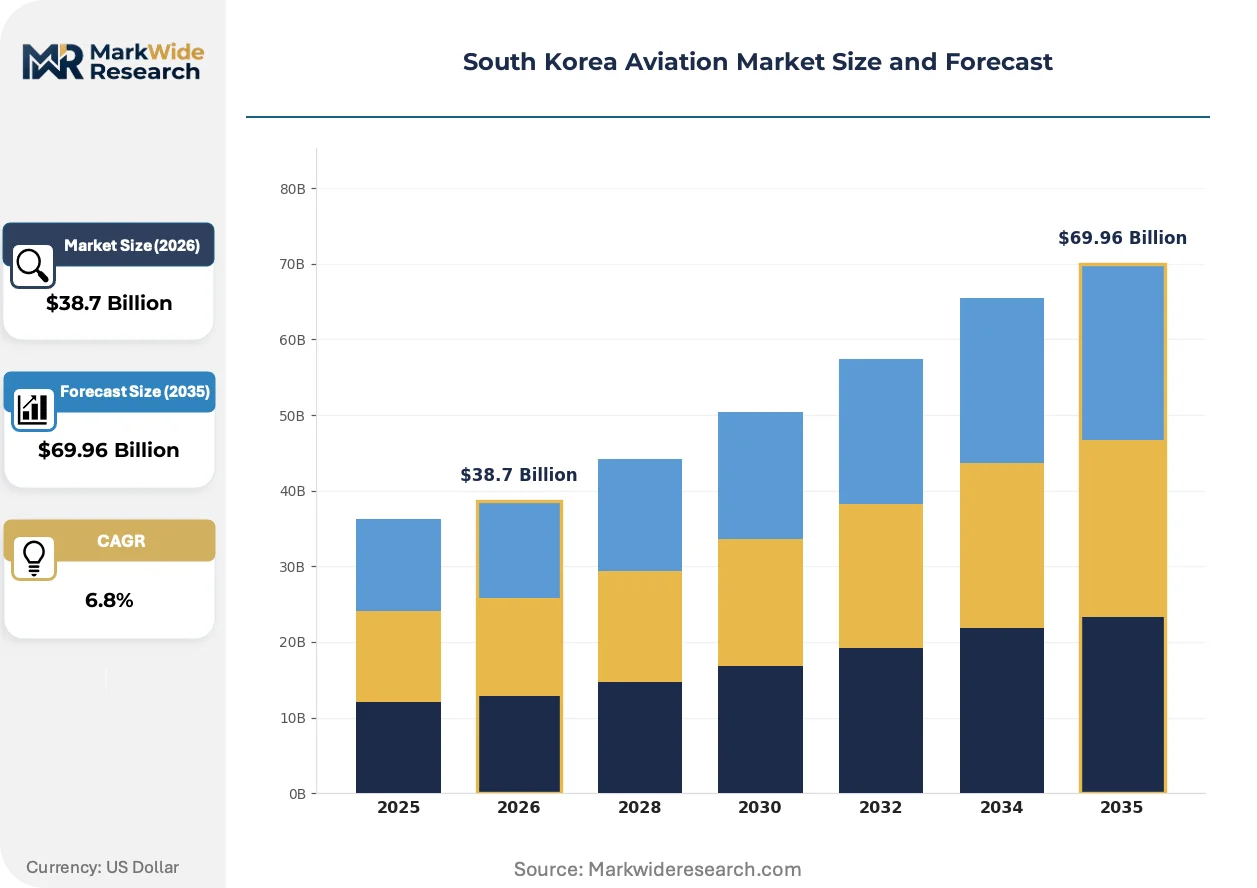
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Commercial Jets, Cargo Aircraft, Private Jets, Military Aircraft Service Type: Passenger Services, Cargo Services, Maintenance Services, Flight Training End User: Airlines, Charter Companies, Armed Forces, Private Owners Technology: Avionics Systems, Engine Technology, Flight Control Systems, Navigation Systems |
| Companies Covered | Korea Aerospace Industries, T'way Air, Korean Air, Air Busan, Jin Air, Asiana Airlines, Hanwha Aerospace, LIG Nex1, Jeju Air, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Aviation Market Evolving Landscape
Aviation technology in South Korea is pivoting between indigenous defense capabilities and commercial fleet modernization, with regulatory pressure forcing convergence on sustainable operations.
Geared turbofan propulsion systems are integrating into domestic narrowbody fleets as Korean Air and low-cost carriers phase out legacy powerplants. The Ministry of Land, Infrastructure and Transport's emission benchmarks are compressing adoption timelines from typical 15-year cycles toward 8-10 year replacements. Engine manufacturers are integrating digital health monitoring to capture aftermarket service contracts previously held by airlines.
MFDS aeromedical certification requirements are reshaping pilot training protocols with stricter cardiovascular and cognitive assessment standards. Flight schools must now integrate enhanced simulator hours and recurrent testing modules that extend qualification timelines. Regional carriers operating from Gimhae and Jeju hubs are responding by establishing captive training pipelines with domestic aviation universities.
After-sales service unbundling is fragmenting traditional OEM maintenance monopolies as independent providers capture aging fleet heavy checks. Airlines are disaggregating component-level repairs from airframe overhauls, creating specialized niche operators with dedicated narrowbody expertise. This pattern concentrates most visibly at Incheon's maintenance cluster where third-party facilities now handle 40 percent of widebody C-check volume.
South Korea Aviation Market Segmentation
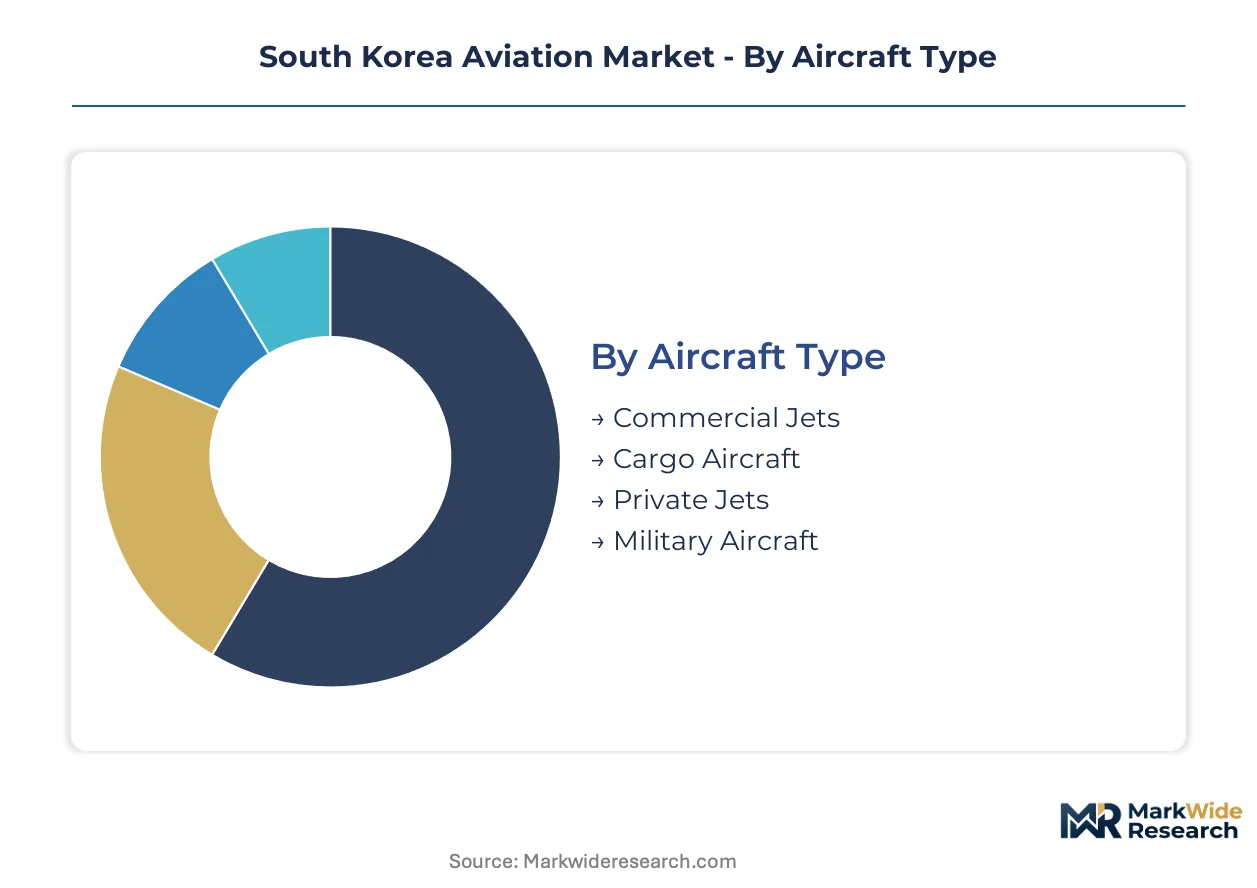
Segmentation reveals how South Korean aviation value pools split between high-volume commercial operations and specialized military-civil niches. Each dimension exposes different margin structures, regulatory exposure, and technology intensity across the peninsula's aerospace ecosystem.
Aircraft Type:
Commercial jets dominate fleet value while military platforms command premium unit economics and indigenous technology integration.
- Commercial Jets:Narrowbody and widebody aircraft operating scheduled passenger services constitute the volume core. Korean Air and low-cost carriers concentrate procurement around Seoul-Incheon and Gimhae hubs, with Ministry of Land, Infrastructure and Transport emission standards accelerating geared turbofan adoption.
- Military Aircraft:Indigenous fighter programs and rotary platforms integrate Hanwha Aerospace airframes with domestic active electronically scanned array radar systems. Defense procurement prioritizes sovereign manufacturing capabilities over cost minimization.
- Cargo Aircraft:Dedicated freighter and converted passenger-to-cargo configurations serve transpacific freight density.
- Private Jets:Business aviation operates limited point-to-point services from Seoul and Jeju.
Mature deployment sits with commercial jets. Newer deployment is concentrated in military aircraft with indigenous avionics integration.
Service Type:
Operational services capture recurring revenue while maintenance margins expand with fleet age.
- Passenger Services:Full-service and low-cost carriers operate scheduled routes with diverging yield management. Jeju Air and regional competitors standardize narrowbody economics on domestic and short-haul leisure corridors.
- Maintenance Services:Heavy checks and component-level repairs fragment toward independent providers at Incheon maintenance clusters. Aftermarket unbundling shifts margin pools from OEMs as aging fleets require specialized narrowbody expertise.
- Cargo Services:Integrated freight operations leverage hybrid passenger-cargo configurations on long-haul routes.
- Flight Training:MFDS aeromedical certification and Ministry-mandated simulator hours extend pilot qualification timelines.
Revenue concentration favors passenger services. Margin expansion is climbing the fastest in maintenance services with fleet aging.
End User:
Airlines absorb capacity risk while armed forces anchor domestic manufacturing demand.
- Airlines:Korean Air sustains transpacific premium positioning through network density and cargo integration. Low-cost competitors capture leisure demand with standardized fleet economics.
- Armed Forces:Domestic defense procurement funds indigenous avionics and airframe development at Hanwha Aerospace facilities with export-oriented manufacturing capabilities.
- Charter Companies:Point-to-point services operate from secondary hubs with limited scale.
- Private Owners:Individual aircraft ownership remains marginal within national airspace.
Procurement volume concentrates with airlines. Technology sovereignty investment is expanding most quickly through armed forces programs.
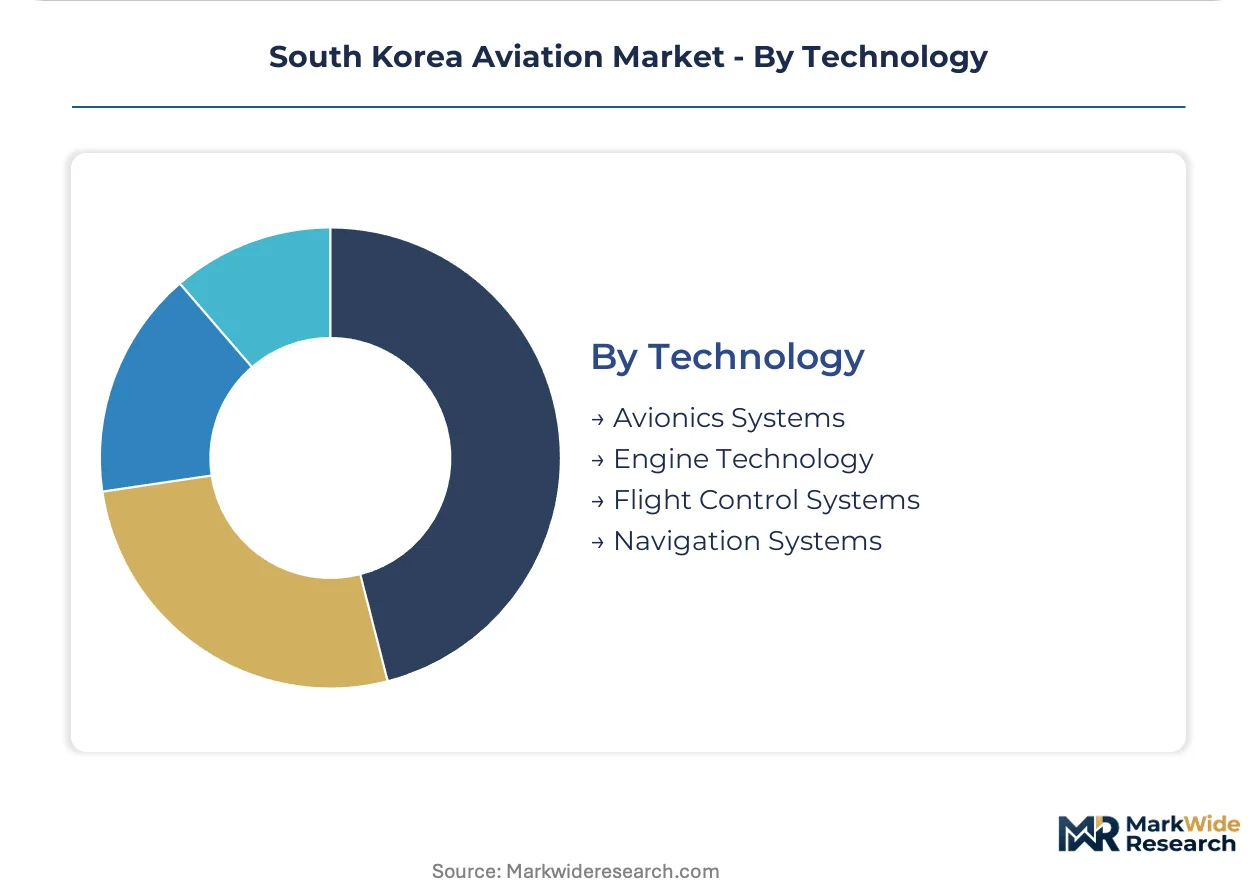
Technology:
Avionics retrofits and engine upgrades drive replacement cycles across civil and military fleets.
- Avionics Systems:Next-generation cockpit upgrades and active electronically scanned array radar integration span both commercial retrofit mandates and indigenous military development. MFDS-certified manufacturing lines enable domestic system integrator participation.
- Engine Technology:Geared turbofan propulsion systems compress replacement timelines from fifteen-year cycles toward eight-to-ten-year intervals under Ministry emission benchmarks.
- Flight Control Systems:Digital architecture upgrades conflict with legacy flight management computer integration on older narrowbodies.
- Navigation Systems:Precision approach and satellite-based augmentation support secondary hub operations.
Installed base dominance rests with engine technology. Retrofit intensity and steepest expansion trajectory characterize avionics systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul-Incheon anchors South Korean aviation activity through its transpacific cargo density and premium passenger flows, while secondary hubs fragment point-to-point services across provincial corridors.
Seoul Capital Area
Incheon International Airport processes the bulk of transpacific freight and premium long-haul traffic, with Korean Air maintaining network density through integrated cargo-passenger configurations. MFDS aeromedical certification centers concentrate pilot training infrastructure in this corridor. Gimpo Airport handles domestic shuttle services that feed Incheon's international connections.
Busan-Ulsan
Gimhae International Airport captures rising intra-Asian leisure demand through low-cost carrier point-to-point operations. The Ministry of Land, Infrastructure and Transport's route licensing procedures have accelerated secondary hub development here. Hanwha Aerospace facilities in Ulsan manufacture airframe components for domestic and export military programs.
Daegu-Gyeongbuk
Daegu International Airport serves as a maintenance cluster with third-party facilities handling narrowbody heavy checks. Regional carriers establish captive training pipelines with local aviation universities to address MFDS-mandated simulator hour requirements. The area's industrial base supports avionics component manufacturing for retrofit programs.
Daejeon-Sejong
Government research institutes in this corridor drive indigenous active electronically scanned array radar development for military platforms. Defense procurement programs anchor domestic technology sovereignty investments here. The concentration of aerospace R&D facilities supports integration between civil and military avionics standards.
Gwangju-Honam
Muan International Airport and surrounding facilities support cargo conversion operations for aging passenger-to-freighter configurations. Independent maintenance providers capture component-level repairs disaggregated from OEM service contracts. The region's lower cost structure attracts aftermarket unbundling activity from Seoul-based operators.
South Korea Aviation Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across South Korean aviation, with full-service carriers absorbing fleet ownership risk while low-cost operators lease standardized narrowbodies. The market structure splits between consolidated premium long-haul operators and fragmented regional leisure specialists. Three archetypes dominate: integrated cargo-passenger hybrids, standardized narrowbody discounters, and defense-industrial manufacturers. Competitive moves center on fleet renewal acceleration under Ministry emission benchmarks and aftermarket service unbundling to capture aging aircraft maintenance margins.
Within the defense-industrial tier, Hanwha Aerospace and Korea Aerospace Industries anchor domestic manufacturing capabilities. Korean Air and Asiana Airlines occupy positions in the full-service segment, while Jeju Air exemplifies the low-cost archetype with aggressive domestic and regional route expansion. These players represent the spectrum from sovereign technology development to standardized commercial operations.
| Leading Market Players |
|---|
| Korea Aerospace Industries |
| T'way Air |
| Korean Air |
| Air Busan |
| Jin Air |
| Asiana Airlines |
| Hanwha Aerospace |
| LIG Nex1 |
| Jeju Air |
| Others |
Value Network & Pricing Analysis
Ministry of Land, Infrastructure and Transport carbon emission benchmarks gate qualified supply for geared turbofan engines and premium-tier maintenance slots at Incheon clusters. Carriers lacking retrofit compliance face exclusion from higher-yield transpacific routes where Korean Air and Asiana capture cargo-passenger yield optimization.
Pricing Analysis
Yield-per-available-seat-mile anchors pricing power across full-service and low-cost carrier tiers. Three-tier pricing structure across premium, standard, and economy levels differentiates Korean Air's transpacific density from Jeju Air's standardized narrowbody leisure economics. Cost compression in regional point-to-point services is intensifying because T'way Air and Air Busan compete on identical aircraft configurations. Charter operators and cargo converters show highest price sensitivity, while defense procurement at Hanwha Aerospace absorbs sovereign premium for indigenous avionics integration.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale fleet procurement for Korean Air and Asiana, while independent distributors feed aftermarket components to Incheon maintenance clusters. Geared turbofan engines draw from USA and France manufacturing bases, with avionics systems sourcing from domestic MFDS-certified lines at Daejeon-Sejong research corridors. Single-source vulnerability concentrates in precision castings for engine hot sections. Distribution runs through captive airline procurement teams for new aircraft and fragmented third-party channels for aging fleet heavy checks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into sustainable aviation fuel infrastructure and captive pilot training pipelines has become the decisive upstream lever as Ministry emission mandates compress fleet renewal timelines.
For Market Incumbents: Cement transpacific cargo density advantages through hybrid passenger-freighter configurations that optimize yield on long-haul routes. Lock in geared turbofan aftermarket service contracts before engine manufacturers capture margin pools through digital health monitoring platforms. Low-cost carrier fleet standardization threatens full-service domestic market share. For New Entrants and Emerging Players: Launch via independent maintenance, repair and overhaul unbundling at Daegu-Gyeongbuk clusters where third-party facilities already handle narrowbody heavy checks. Target cargo conversion operations at Muan International Airport for aging passenger-to-freighter configurations. White-space availability concentrates in specialized avionics retrofit integration for legacy flight management computer architectures. For Investors and Strategic Acquirers: MFDS aeromedical certification backlog expansion is the leading indicator that pilot training infrastructure will face sustained capacity constraints. Five-to-ten year viability favors acquisition targets with captive aviation university pipelines and simulator hour allocation rights. Watch for Ministry route licensing acceleration at Gimhae and Jeju as inflection signal for secondary hub investment viability.| Strategic Initiative | Industry Significance |
|---|---|
| Geared Turbofan Fleet Renewal | Ministry emission benchmarks compress replacement timelines from fifteen-year cycles toward eight-to-ten-year intervals. |
| Captive Pilot Training Pipeline | MFDS aeromedical standards extend qualification timelines, favoring operators with domestic aviation university partnerships. |
| Aftermarket Service Unbundling | Independent providers capture aging fleet heavy checks previously monopolized by OEM service contracts at Incheon. |
| Indigenous Avionics Integration | Hanwha Aerospace facilities anchor sovereign manufacturing capabilities with export-oriented defense procurement funding. |
| Secondary Hub Route Licensing | Ministry of Land, Infrastructure and Transport procedures at Gimhae and Jeju accelerate point-to-point leisure corridor development. |
Research Methodology
Ministry of Land, Infrastructure and Transport regulatory filings, MFDS aeromedical certification databases, and Korea Aerospace Industries export disclosures formed the secondary backbone. Primary interviews with fleet planning executives at Korean Air and Jeju Air, maintenance directors at Incheon third-party facilities, Hanwha Aerospace program managers, and Daejeon-Sejong defense research leads validated demand assumptions. Bottom-up triangulation across aircraft delivery schedules and top-down reconciliation with national aviation emission targets anchored market sizing.
Bottom-up modeling segmented commercial jet procurement by narrowbody versus widebody configurations, military platforms by indigenous versus licensed production, and maintenance services by airframe versus component-level repairs. CAGRs were derived from fleet age profiles correlated with Ministry emission benchmark compliance deadlines. Forecast inputs incorporated sustainable aviation fuel infrastructure buildout timelines and active electronically scanned array radar export order visibility.
Jet fuel price volatility, pilot certification bottleneck duration, and high-speed rail corridor expansion pace are the dominant revision risks across the projection horizon. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Vietnam Business Jets and Helicopters Market
Aircraft
Wireless in-Flight Entertainment Market
Aircraft
Commercial Aircraft Aerostructures Market
Aircraft
Multi-Band SATCOM and 6G-Ready Aircraft Radome Systems Market
Aircraft
Aircraft Wheels Brakes Market
Aircraft
Southeast Asia Aviation Market
Aircraft
Aircraft Door Market
Aircraft
Europe Helicopters Market
Aircraft
Asia-Pacific Aviation Market
Aircraft
Global Aircraft Heat Exchanger Market
Aircraft
Tandem Rotor Helicopter Market
Aircraft
Air Speed Indicator Market
Aircraft
India Aviation Market
Aircraft
Light Sport Aircraft (LSA) Market
Aircraft
Middle-East Aviation Market
Aircraft
Glider Aircraft Market