
 Aircraft Fairings Market | 2026-2036
Aircraft Fairings Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Fairings Market Analysis
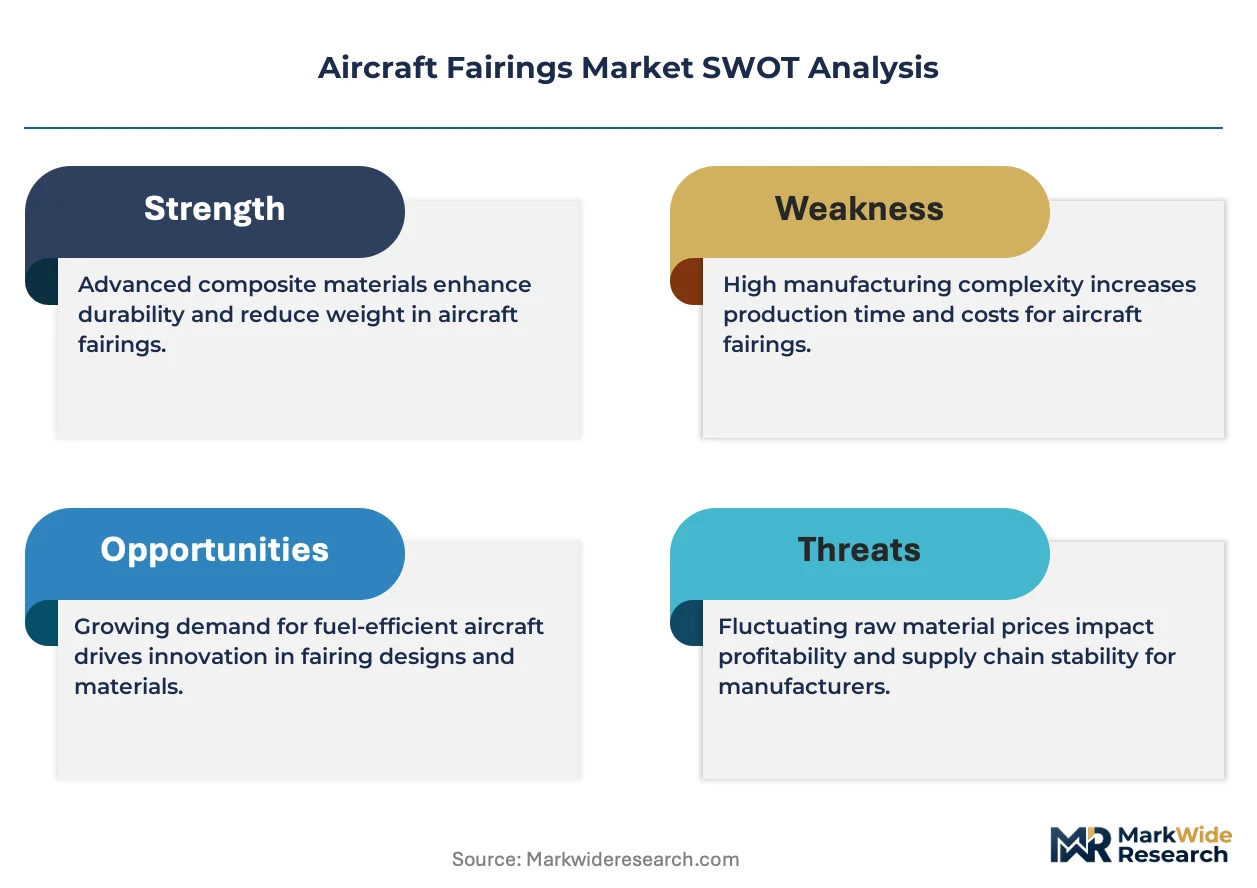
A capital-intensity divergence between integrated aerostructures houses and specialized fairing shops is rotating competitive dynamics across the supply base. NORDAM leverages its vertical integration through Tulsa and Dallas facilities to capture high-value engine nacelle and thrust reverser work. FACC AG anchors European composite aerostructures output from its Austrian headquarters, sustaining long-term contracts with Airbus across wing and fuselage fairing programs.
Aircraft fairings are aerodynamic surfaces attached to primary structure to reduce form drag, typically manufactured from carbon fiber-reinforced polymer composites or aluminum alloys through resin transfer molding or automated fiber placement processes, with operational temperature ratings spanning minus 55 to 85 degrees Celsius. Wing fairings dominate current procurement volumes due to large surface areas on narrowbody and widebody platforms, while composite material adoption outpaces aluminum across new programs as OEMs pursue weight reduction targets. MRO Providers represent a structurally distinct demand pool driven by damage tolerance inspections and life-limited part replacement cycles rather than airframe production rates.
FAA Part 25 airworthiness standards and EASA CS-25 certification requirements govern structural integrity, flammability, and lightning strike protection for fairing installations on transport category aircraft. EPA regulations on volatile organic compound emissions from composite manufacturing processes are reshaping shop-floor chemistry and curing equipment investments at supplier facilities. Stakeholders must monitor evolving OEM qualification timelines and sustainability-linked procurement criteria as Airbus and Boeing embed lifecycle carbon accounting into supplier scorecards.
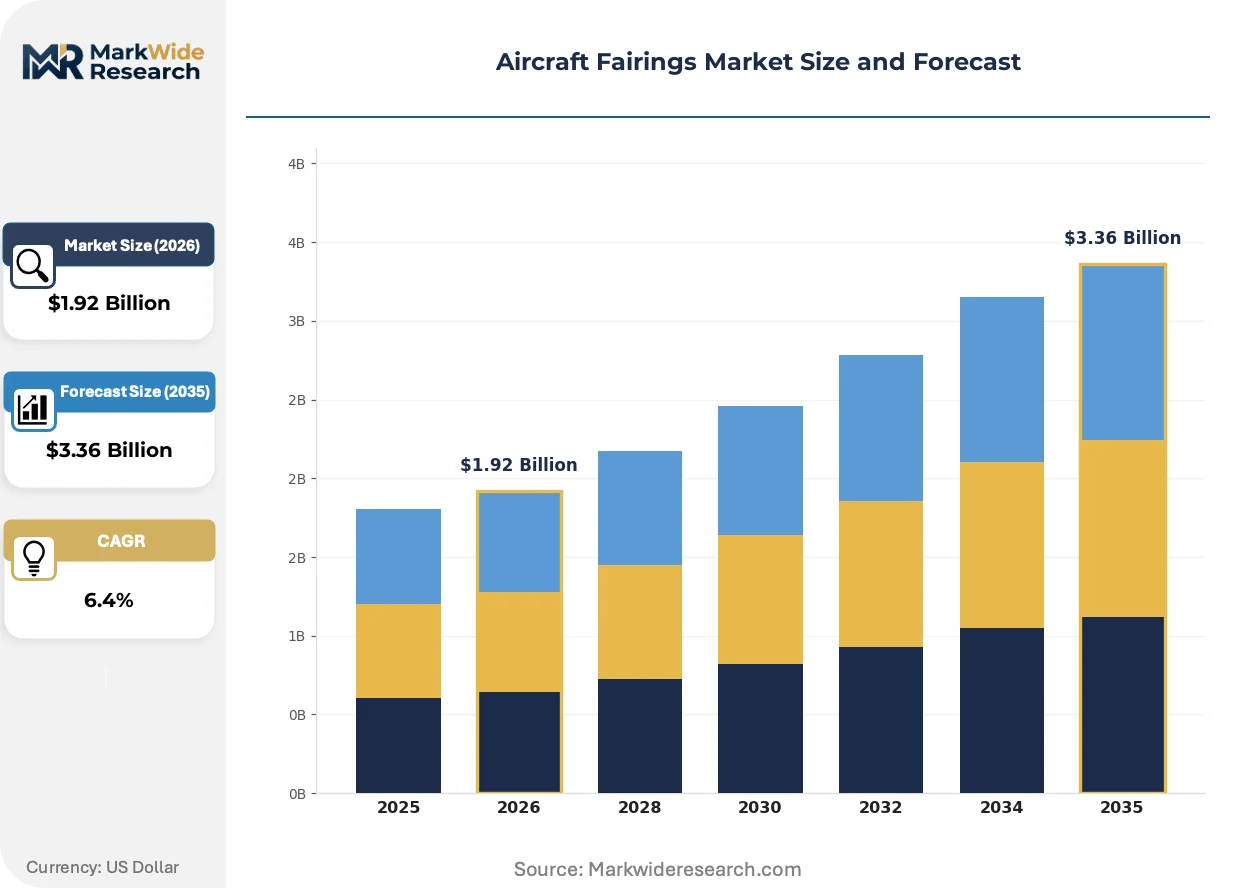
Market Dynamics
Fleet renewal cycles at Boeing and Airbus are compressing supplier qualification timelines while FAA and EASA tighten composite damage tolerance standards, forcing tier-two aerostructures shops to choose between capital-intensive automation or program exit.
Growth Catalysts
- Composite Material Substitution:Carbon fiber-reinforced polymers are displacing aluminum across wing-to-body fairings as OEMs pursue specific weight reduction targets on next-generation narrowbody platforms.
- FAA Part 25 Amendments:Updated airworthiness standards for lightning strike protection are mandating upgraded conductive mesh integration in nacelle fairings, creating replacement demand across in-service fleets.
- Commercial Aviation Production:Airbus A320neo and Boeing 737 MAX output rates are pulling forward procurement of engine cowls, pylon fairings, and flap track canoe fairings from qualified supplier bases.
Market Restraints
- Prepreg Carbon Fiber Supply:Toray Industries and Hexcel Corporation control approximately 70 percent of aerospace-grade precursor supply, concentrating input cost risk for fairing manufacturers dependent on autoclave-capable material streams.
- Autoclave Capacity Bottleneck:Large-diameter autoclaves required for wing fairing cure cycles require 18-24 month lead times and 15-25 million dollar capital commitments, constraining expansion by mid-tier suppliers.
- Aluminum-Lithium Alloys:Third-generation Al-Li sheet products from Constellium and Arconic retain cost advantages on smaller fairing applications, limiting composite penetration in price-sensitive regional jet programs.
Strategic Opportunities
- Urban Air Mobility Fairings:eVTOL airframe developers require specialized nose and tail cone fairings optimized for low-Reynolds-number aerodynamics, opening design contracts outside traditional commercial aviation procurement channels.
- Out-of-Autoclave Curing:Oven-curable resin systems paired with vacuum-assisted resin transfer molding are enabling tier-two suppliers to compete for wing fairing work without autoclave infrastructure investments.
- Sustainability-Linked Procurement:Airbus and Boeing supplier scorecards now embed lifecycle carbon accounting, creating preference premiums for fairing manufacturers with renewable energy-powered production facilities.
Industry Challenges
- Composite Repair Technician Scarcity:FAA-certified structural repair stations face 12-18 month backlogs for damage tolerance inspection and scarf repair qualified personnel, constraining MRO throughput.
- Qualification Timeline Compression:New fairing designs require 18-36 months for full FAA Part 25 certification including flammability, lightning, and hail impact testing, misaligning with OEM production ramp schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Fairings Market |
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $3.36 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wing Fairings, Engine Fairings, Fuselage Fairings, Tail Fairings Material: Composite, Aluminum, Steel, Thermoplastic End User: Commercial Aviation, Military Aviation, General Aviation, MRO Providers Installation Type: Integrated, Retrofit, Replacement, Custom |
| Companies Covered | NORDAM, Strata Manufacturing, Airbus, FACC AG, Royal Engineered Composites, Boeing, Malibu Aerospace, Kaman Aerosystems, ShinMaywa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Fairings Market Emerging Trajectories
Automated fiber placement and thermoplastic welding are displacing hand layup and mechanical fastening across aerostructures fabrication, compressing labor content while enabling geometric complexity previously uneconomical at production scale.
Thermoplastic composite tapes with PEEK and PPS matrices are miniaturizing the feature resolution achievable in automated fiber placement, enabling integrally stiffened fairing designs that eliminate bonded doublers and reduce fastener count by 40 percent. Engine nacelle manufacturers at GKN Aerospace and Spirit AeroSystems are adopting these systems for thrust reverser cascades and fan cowl assemblies. The technology is miniaturizing the minimum gauge thickness producible with structural integrity, opening weight reduction pathways on secondary structure previously locked into thermoset processing.
EPA National Emission Standards for Hazardous Air Pollutants are tightening volatile organic compound limits on resin transfer molding and spray-up operations, forcing supplier facilities to install thermal oxidizers or switch to closed-mold infusion processes. The rule affects approximately 200 U.S. aerostructures shops with composite wet layup capacity. Texas and Kansas manufacturing clusters are responding fastest due to state-level technical assistance programs paired with existing EPA Small Business Compliance Assistance resources.
Airline procurement departments are unbundling fairing replacement from heavy maintenance checks, creating standalone material sourcing agreements with distributors rather than airframe OEMs. This disintermediation is most visible in North American and European MRO networks where independent repair stations now hold direct contracts with FACC AG and NORDAM for rotable spare pools. The shift compresses lead times for AOG events but transfers inventory carrying costs downstream to airline technical operations teams.
Aircraft Fairings Market Segmentation
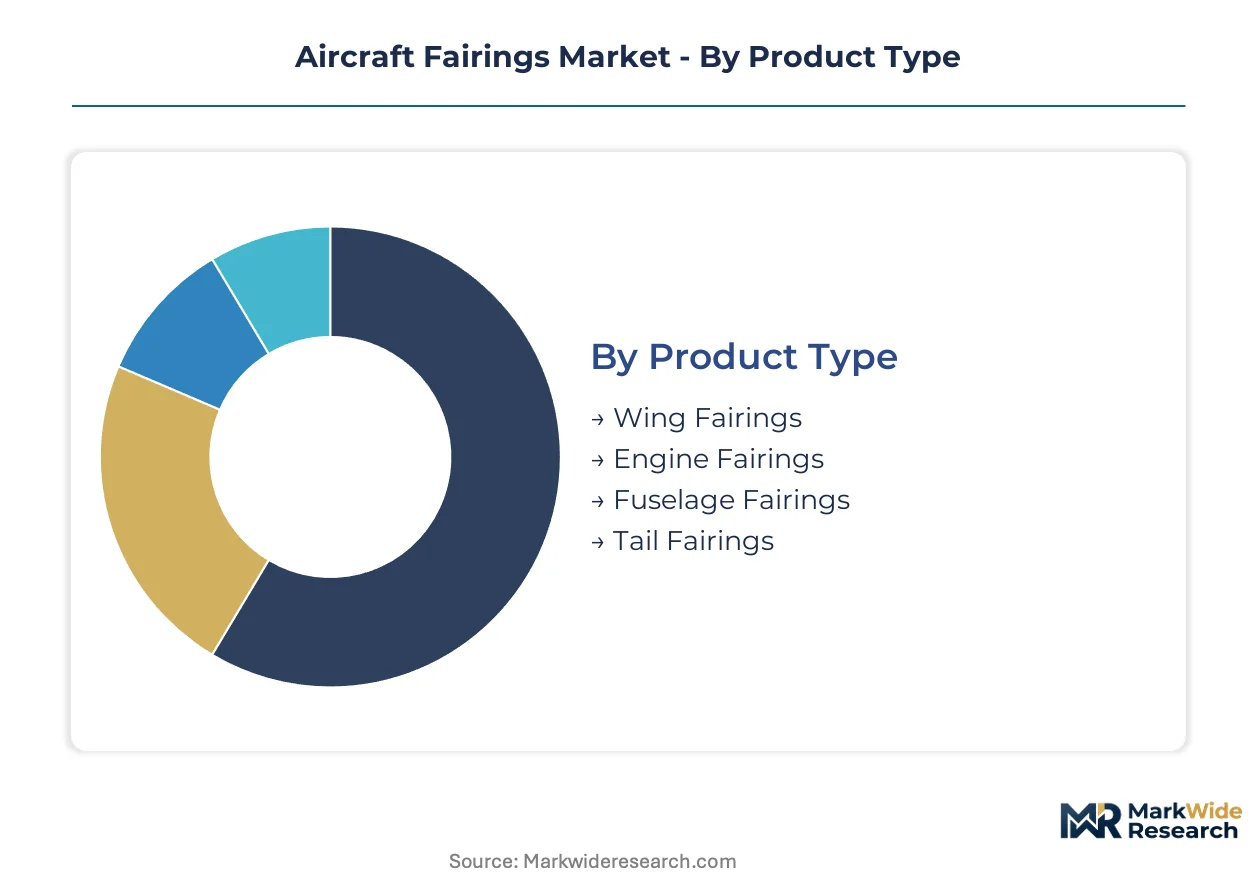
Aircraft fairing procurement channels diverge sharply between OEM production lines and aftermarket distribution networks. Material certification tiers and installation complexity create distinct margin profiles across each segment category, reshaping supplier positioning strategies.
Product Type:
Wing fairings flow through Boeing and Airbus tier-one contracts, while engine fairings concentrate at nacelle specialists with FAA Part 25 repair station credentials.
- Wing Fairings:Large-surface carbon fiber-reinforced polymer structures covering flap tracks and wing-to-body junctions. Demand clusters at Airbus A320neo and Boeing 737 MAX production rates in Toulouse and Renton, constrained by autoclave cure cycle bottlenecks at mid-tier suppliers.
- Engine Fairings:Nacelle cowls and thrust reverser cascades requiring integrated lightning strike mesh and acoustic liner bonding. Procurement concentrates at Spirit AeroSystems and GKN Aerospace facilities in Wichita and Bristol, pulled by next-generation turbofan diameter increases.
- Fuselage Fairings:Smaller-profile aerodynamic closures with lower composite penetration due to curvature complexity.
- Tail Fairings:Empennage surfaces with limited aftermarket demand relative to wing and engine categories.
By volume, wing fairings lead. By growth pace, engine fairings are climbing the fastest.
Material:
Cost tiers separate aerospace-grade carbon fiber from commodity aluminum, with thermoplastics commanding premium positioning for high-temperature nacelle applications.
- Composite:Carbon fiber-reinforced thermosets processed through resin transfer molding or automated fiber placement, achieving specific strength ratios exceeding aluminum by 40 percent. Adoption accelerates at Airbus Hamburg and Boeing Charleston as OEMs pursue fuel burn reduction targets on single-aisle platforms.
- Aluminum:Third-generation aluminum-lithium alloys from Constellium retaining cost advantages on regional jet fairings and legacy fleet retrofits. Procurement persists at Embraer E-Jet programs where composite qualification timelines exceed production windows.
- Steel:Limited to attachment fittings and localized reinforcement zones rather than primary fairing skins.
- Thermoplastic:PEEK and PPS matrix tapes enabling out-of-autoclave processing with weldable joint configurations.
Composite captures the highest absolute spend. Thermoplastic materials are expanding most quickly from a smaller base.
End User:
Customer type determines contract structure — OEMs negotiate multi-year frame agreements while MRO Providers spot-buy through distributor networks.
- Commercial Aviation:Fleet renewal programs at Delta, United, and Lufthansa Technical Operations driving scheduled replacement of life-limited fairing components. Procurement consolidates through Boeing Global Services and Airbus Flight Hour Services long-term agreements.
- MRO Providers:Independent repair stations in Singapore, Frankfurt, and Dallas-Fort Worth holding direct spare pool contracts with FACC AG and NORDAM. Damage tolerance inspection backlogs create 12-18 month technician scarcity constraints.
- Military Aviation:Defense procurement through Lockheed Martin F-35 and Boeing F/A-18 programs with classified performance specifications.
- General Aviation:Fragmented demand across business jet OEMs and aftermarket modifiers with lower certification stringency.
Commercial aviation dominates procurement value. MRO Providers are gaining share fastest as fleet ages and unbundled sourcing spreads.
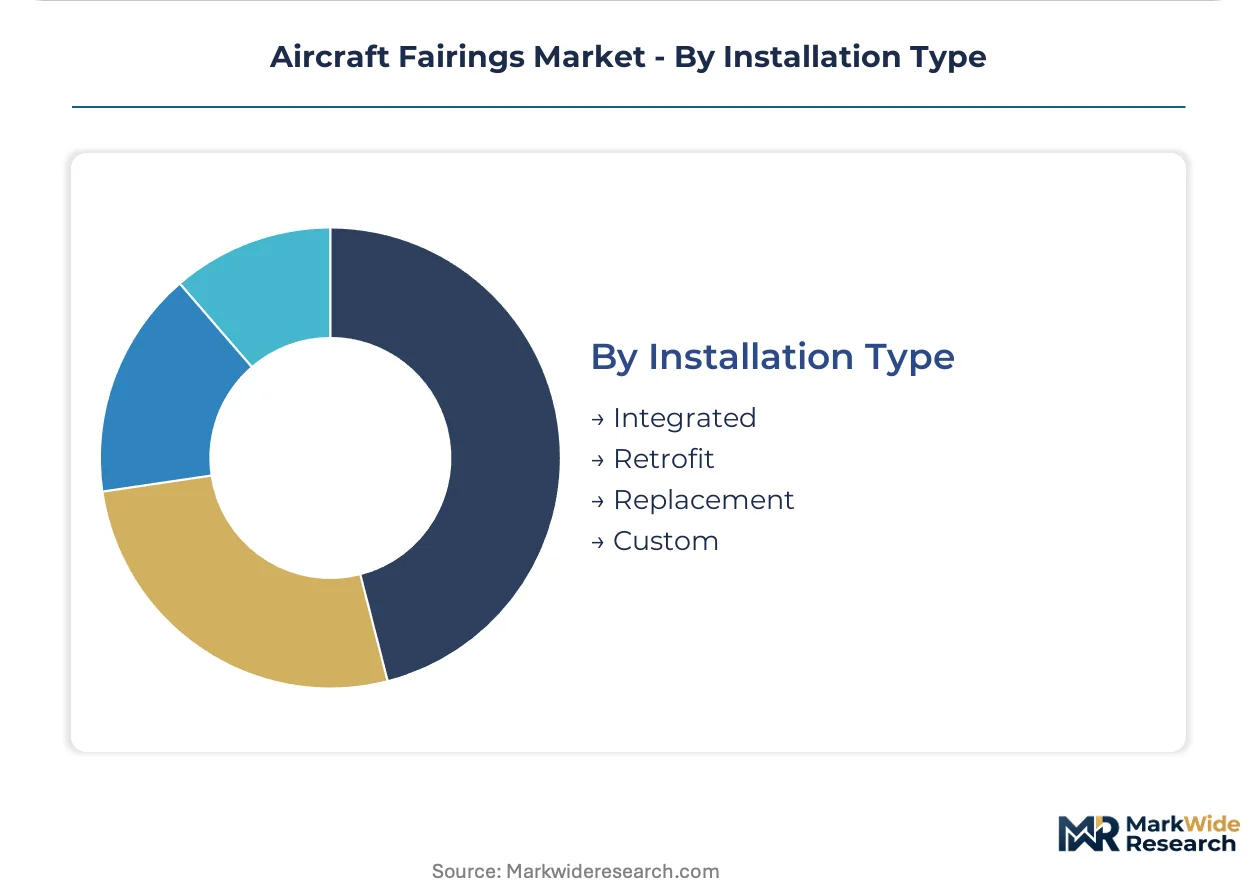
Installation Type:
Application maturity separates integrated production-line installs from aftermarket retrofit complexity, with replacement cycles creating recurring revenue pools.
- Integrated:Fairings installed during final assembly at Airbus Toulouse, Boeing Everett, and Embraer São José dos Campos. Contracts bundle with airframe purchase agreements, locking suppliers into 10-15 year production horizons with penalty clauses for rate misses.
- Replacement:Life-limited part swaps triggered by damage tolerance inspections, hail impact, or lightning strike events. Demand concentrates at Lufthansa Technik, ST Engineering, and AAR Corp heavy maintenance facilities with direct material sourcing agreements bypassing OEM distribution.
- Retrofit:Aerodynamic modification kits for in-service fleet performance upgrades.
- Custom:Specialized fairings for VIP completions and experimental aircraft with non-standard geometries.
Integrated installations lead by unit volume. Replacement demand is expanding most quickly as narrowbody fleets mature through first heavy check cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in aircraft fairing procurement varies sharply by geography. Airlines in mature aviation markets prioritize OEM-certified composite structures with full traceability. Operators in cost-constrained emerging markets favor aluminum alternatives and PMA-approved replacement parts.
United States
Boeing's 737 MAX and 787 production lines at Renton and North Charleston pull the majority of North American fairing demand. FAA Part 25 certification requirements for lightning strike protection govern all transport-category installations. The Tulsa-Dallas aerostructures corridor hosts NORDAM's integrated nacelle facilities and a dense cluster of tier-two composite shops serving engine OEMs.
France
Airbus Toulouse and Saint-Nazaire final assembly lines generate concentrated procurement of wing-to-body fairings for A320neo and A350 programs. EASA CS-25 structural integrity standards align with FAA requirements but add specific flammability testing protocols. The Nouvelle-Aquitaine region around Bordeaux hosts specialized thermoplastic composite development for next-generation nacelle applications.
Germany
Lufthansa Technik's Hamburg heavy maintenance base drives aftermarket replacement demand for life-limited fairing components across European narrowbody fleets. German KBA-type technical standards influence component traceability requirements for EU-registered aircraft. The Bavaria-Baden-Württemberg corridor contains precision machining suppliers for fairing attachment fittings and metallic substructures.
Japan
ShinMaywa's aerostructures division supplies Boeing and Airbus programs from its Kobe and Nagoya facilities, leveraging METI-supported aerospace cluster development. Japan's industrial standards for carbon fiber quality (JIS K 7073) exceed baseline aerospace specifications. The Chubu region around Nagoya hosts Toray Industries' precursor manufacturing, tightening supply chain integration for local fairing fabricators.
United Arab Emirates
Emirates Engineering and Etihad Airways Engineering in Dubai and Abu Dhabi operate the Middle East's largest independent MRO capacity for composite fairing repair. The UAE General Civil Aviation Authority has adopted EASA-aligned certification standards with accelerated approval pathways for established repair station networks. Dubai South's aerospace free zone is attracting European fairing specialists seeking Gulf carrier maintenance contracts.
Aircraft Fairings Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated aerostructures houses with captive autoclave capacity command premium OEM contracts for large wing fairings. Specialized fairing shops compete on qualification speed and MRO responsiveness rather than scale. The dominant competitive moves are backward integration into prepreg supply relationships and geographic expansion to follow OEM final assembly line locations.
Among North American integrated suppliers, NORDAM anchors the engine nacelle tier with vertical control through Tulsa and Dallas facilities. FACC AG represents the European composite aerostructures archetype from its Austrian headquarters, sustaining long-term Airbus wing and fuselage fairing relationships. Strata Manufacturing exemplifies the emerging Gulf-based fabrication model, leveraging Abu Dhabi location for Middle East carrier proximity and state-supported capacity expansion.
| Leading Market Players |
|---|
| NORDAM |
| Strata Manufacturing |
| Airbus |
| FACC AG |
| Royal Engineered Composites |
| Boeing |
| Malibu Aerospace |
| Kaman Aerosystems |
| ShinMaywa |
| Others |
Supply Flow & Price Mechanics
Autoclave scale economies at integrated aerostructures houses create asymmetric pricing power that compresses margins for mid-tier suppliers lacking cure-cycle capacity. Boeing and Airbus tier-one contracts anchor price floors through long-term offtake agreements, while FAA Part 25 qualification timelines extend payback periods for new entrants seeking OEM certification.
Pricing Analysis
Aftermarket parts and rotable spare pools generate lifetime value multiples exceeding original equipment sales for qualified suppliers. Three-tier pricing structure across OEM-certified, PMA-approved, and surplus aftermarket levels separates Airbus-Boeing direct contracts from independent MRO sourcing channels. Cost compression in aluminum-lithium fairing tiers reflects Constellium volume scale and regional jet program price sensitivity. Airlines in emerging markets exhibit highest price sensitivity, favoring PMA alternatives, while North American carriers prioritize traceability and lightning strike certification regardless of premium.
Supply Chain Analysis
Container availability on Asia-North America trade lanes constrains just-in-time delivery of Toray Industries carbon fiber precursor to Tulsa and Dallas fabrication clusters. Supply concentrates in Japan, Austria, and the United States, with Chubu-region precursor manufacturing feeding ShinMaywa and Boeing Charleston facilities. Raw material dependencies on aerospace-grade epoxy systems and conductive lightning strike mesh create single-source vulnerability at tier-two shops. Distribution runs through Boeing Global Services and Airbus Flight Hour Services long-term agreements for OEM channels, with independent repair stations in Singapore and Frankfurt bypassing these structures for direct spare pool contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Standalone MRO material sourcing agreements expand faster than production-line contracts as narrowbody fleets mature through first heavy check cycles, transforming fairing procurement from hardware transaction to service-attach annuity.
For Market Incumbents: Shield installed base relationships by deepening backward integration into prepreg supply partnerships with Toray Industries and Hexcel Corporation, countering emerging out-of-autoclave competitors. Lock in 10-15 year rate agreements with Boeing Renton and Airbus Toulouse before thermoplastic welding adoption accelerates. Prioritize certification investment in FAA Part 25 repair station credentials to capture unbundled airline procurement. For New Entrants and Emerging Players: Lead with out-of-autoclave curing capabilities targeting wing fairing work at tier-two supplier price points, bypassing the 15-25 million dollar autoclave capital barrier. Urban air mobility eVTOL developers present the most penetrable segment, requiring specialized low-Reynolds-number nose and tail cone fairings outside established commercial aviation qualification timelines. Pursue direct design contracts with Joby Aviation and Archer Aviation rather than OEM tier-one qualification pathways. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among MRO-focused fairing specialists with FAA-certified repair station networks and direct airline spare pool agreements. Five-to-ten year viability favors suppliers with thermoplastic composite tape capabilities and renewable energy-powered production facilities aligned to Airbus-Boeing sustainability scorecards. Monitor EPA National Emission Standards enforcement intensity as inflection indicator for shop-floor compliance costs and consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Out-of-Autoclave Capacity Expansion | Enables tier-two suppliers to compete for wing fairing work without capital-intensive cure-cycle infrastructure. |
| Backward Integration into Prepreg Supply | Secures aerospace-grade carbon fiber streams from Toray Industries and Hexcel Corporation against allocation risk. |
| FAA Part 25 Repair Station Certification | Unlocks standalone MRO material sourcing agreements with Delta, United, and Lufthansa Technical Operations. |
| Thermoplastic Welding Technology Adoption | PEEK and PPS matrix tapes enable 40 percent fastener reduction and integrally stiffened fairing designs. |
| Renewable Energy Production Transition | Aligns supplier facilities with Airbus and Boeing lifecycle carbon accounting embedded in procurement scorecards. |
Methodological Framework
A standing panel of aerostructures procurement directors, FAA certification engineers, MRO operations managers, and composite manufacturing technicians provided ongoing calibration across the study period. Primary interviews with tier-one supplier executives at NORDAM and FACC AG were cross-validated against secondary sources including FAA airworthiness directive filings, EASA CS-25 certification databases, and EPA National Emission Standards compliance records. Bottom-up build from individual program production rates and top-down cross-check against OEM disclosed supply chain expenditures ensured triangulation integrity.
Consistency checks against Boeing and Airbus disclosed supplier payment terms validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, material grade, end-user category, and installation type, with composite penetration rates and fleet age distributions as industry-specific forecast inputs. CAGRs were derived from production rate trajectories and life-limited part replacement cycle analysis rather than extrapolation.
Forecasts assume regulatory continuity in FAA Part 25 and EASA CS-25 certification regimes; material policy shifts would require re-modeling of qualification timelines and supplier准入 barriers. Composite precursor supply disruptions, accelerated thermoplastic adoption curves, or airline bankruptcy waves represent specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Airplane and Helicopter Hangar Doors Market
Aircraft
Commercial Aircraft in-Seat Power System Market
Aircraft
Asia-Pacific Light and Very Light Jets Market
Aircraft
Europe Attack Helicopter Market
Aircraft
Middle East and Africa Military Helicopters Market
Aircraft
Europe Fighter Aircraft Market
Aircraft
Multi-Band SATCOM and 6G-Ready Aircraft Radome Systems Market
Aircraft
Fixed Wing Turbine Aircraft Market
Aircraft
US Business Jet Market
Aircraft
Aircraft Pushback Tugs Market
Aircraft
Asia-Pacific Commercial Aircraft Market
Aircraft
Helicopter Flight Management System Market
Aircraft
Drone Turbojet Engine Market
Aircraft
Aircraft Radome Market
Aircraft
Aircraft Strut Market
Aircraft
Civil Helicopter Market