
 Middle East Satellite-Based Earth Observation Market | 2026-2036
Middle East Satellite-Based Earth Observation Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Satellite-Based Earth Observation Market Insights
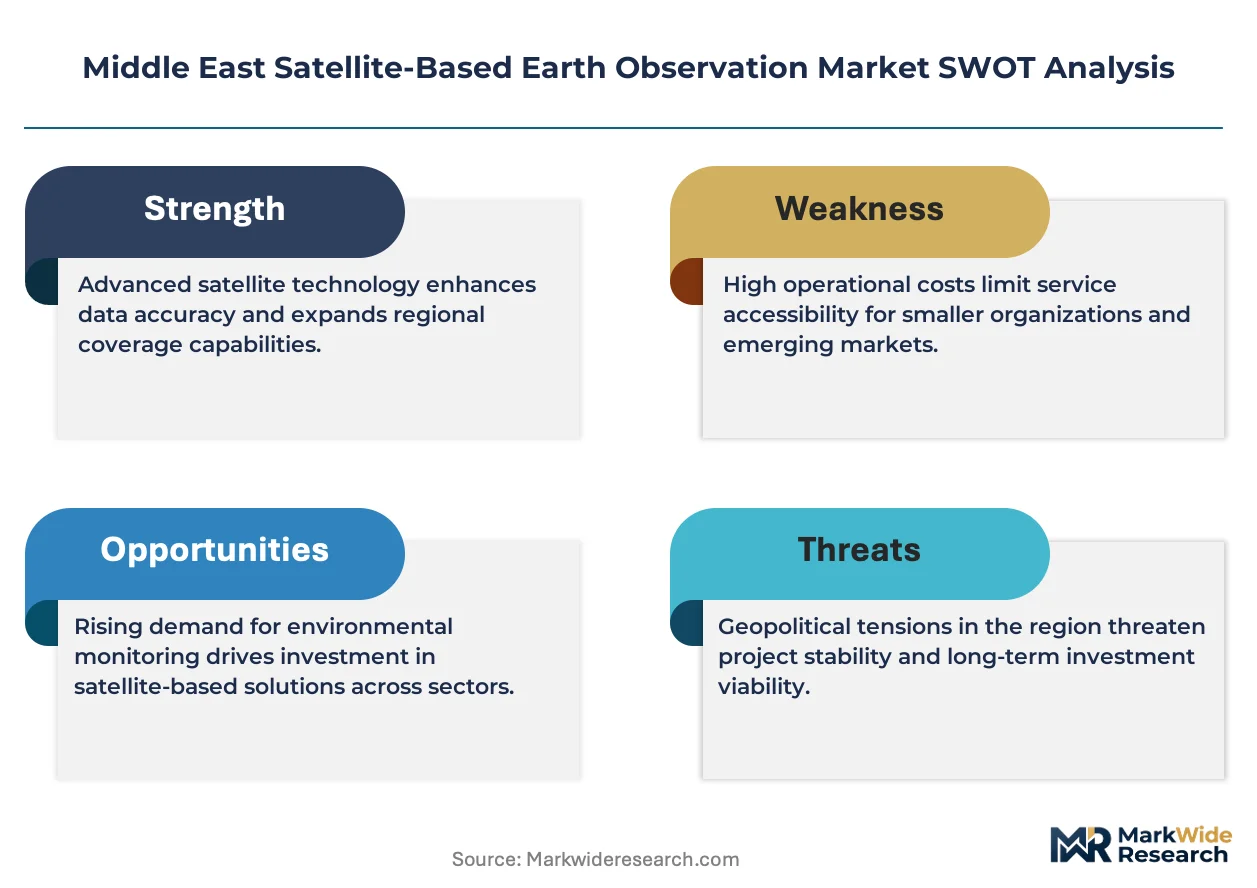
CE marking for satellite component export is collapsing as a gatekeeper qualification, forcing non-European vendors to pursue alternative compliance pathways. Airbus Defense and Space leverages its dual-use heritage to sustain institutional contracts across Gulf defense ministries. ICEYE differentiates through its synthetic aperture radar constellation, offering all-weather imaging that competes with optical alternatives in regional maritime monitoring.
Middle East satellite-based Earth observation encompasses the acquisition, processing, and distribution of geospatial data from low-Earth orbit and geostationary platforms, typically achieving spatial resolutions below one meter for commercial applications and serving defense, agriculture, and infrastructure planning needs. Optical sensors dominate current procurement volumes for agricultural monitoring across the Nile Delta and Fertile Crescent, while radar sensors represent the fastest-expanding technology segment due to persistent cloud cover and dust storm interference that degrades optical performance. Disaster management applications command premium pricing from sovereign buyers, whereas land use monitoring has matured into a volume-driven service category.
The UAE Space Agency and Saudi Communications and Information Technology Commission shape operational licensing requirements for foreign satellite operators seeking to serve domestic end users, effectively mandating local data residency or partnership structures. ISO 17770 geospatial data quality standards influence procurement specifications for defense and environmental monitoring contracts across the region. Stakeholders must weigh sovereign capacity-building objectives against the cost advantages of foreign commercial imagery as Gulf governments expand domestic manufacturing targets.
Market Dynamics
Sovereign capacity-building programs across Gulf Cooperation Council states are compressing procurement timelines while mandating domestic technology transfer, fundamentally restructuring vendor-client relationships in satellite-based Earth observation.
Growth Catalysts
- Saudi Vision 2030 space initiatives:Riyadh's sovereign wealth deployment into domestic satellite manufacturing creates captive demand for optical and radar payload components, pulling foreign suppliers into joint venture structures.
- Maritime domain awareness requirements:Coast guard and naval procurement for Persian Gulf and Red Sea surveillance generates recurring revenue streams for synthetic aperture radar operators capable of all-weather vessel tracking.
- ISO 17770 geospatial data quality standards:Defense and environmental monitoring contracts across the region now embed these specifications, favoring vendors with certified processing pipelines over opportunistic imagery resellers.
Market Restraints
- Optical sensor performance degradation:Persistent dust storms and cloud cover across the Arabian Peninsula and Fertile Crescent limit effective collection windows, forcing redundant satellite passes and inflating operational costs.
- CE marking pathway collapse:Non-European component vendors face exclusion from traditional qualification routes, requiring expensive alternative compliance investments for Gulf market access.
- Data residency mandates:UAE Space Agency and Saudi Communications and Information Technology Commission licensing rules compel foreign operators to establish local ground stations or partnership structures, raising fixed cost thresholds.
Strategic Opportunities
- Nile Delta agricultural monitoring:Egypt's irrigation-intensive farming sector remains underserved by high-revisit commercial offerings, presenting volume potential for crop health analytics providers.
- Disaster response premium services:Flood and seismic event management agencies across the region command above-market rates for rapid-tasking capabilities, creating margin expansion potential distinct from commoditized land use monitoring.
- AI-driven change detection convergence:Machine learning classification algorithms fused with sub-meter optical imagery enable automated infrastructure monitoring, opening subscription-based revenue models for construction and utility clients.
Industry Challenges
- Geospatial analytics talent scarcity:Domestic workforce development in remote sensing interpretation and spectral analysis lags behind satellite launch schedules, forcing reliance on expatriate specialists and inflating personnel costs.
- Dual-use export control complexity:Defense-grade resolution thresholds trigger multilateral regime compliance requirements, elongating sales cycles and creating licensing uncertainty for commercial vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Satellite-Based Earth Observation Market |
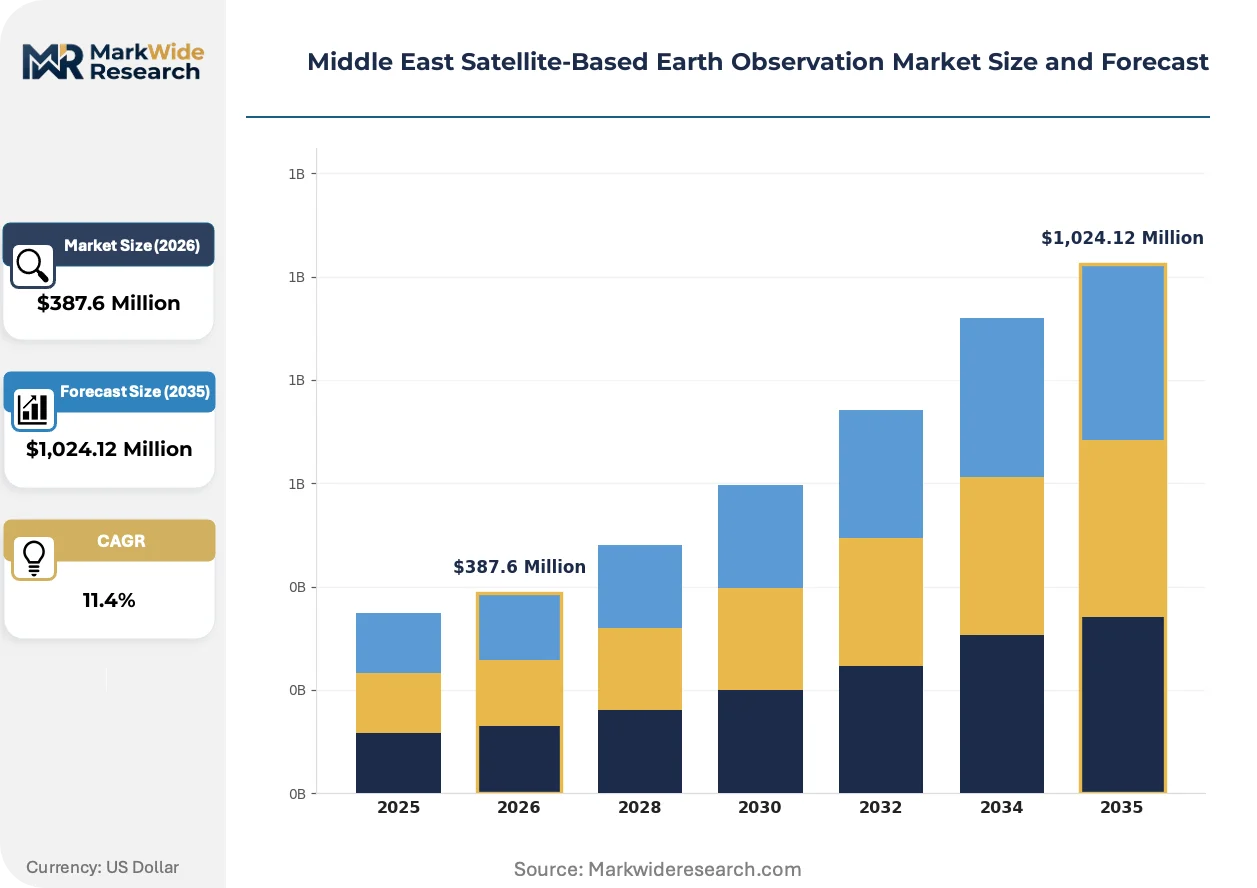
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Satellites, Communication Satellites, Remote Sensing Satellites, Navigation Satellites End User: Agriculture, Defense, Environmental Monitoring, Urban Planning Application: Disaster Management, Land Use Monitoring, Climate Change Analysis, Resource Management Technology: Optical Sensors, Radar Sensors, Multispectral Imaging, Hyperspectral Imaging |
| Companies Covered | Al Yah Satellite Communications Company PJSC (Yahsat), Airbus Defense and Space, SARsat Arabia, Mohammed Bin Rashid Space Centre (MBRSC), Arabsat, Maxar Technologies, Planet Labs PBC, ICEYE, ImageSat International, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Satellite-Based Earth Observation Market Trends and Innovations
Small satellite constellation architectures are compressing revisit intervals while fragmenting traditional prime contractor roles, enabling new entrants to capture value previously concentrated in integrated platform providers.
Synthetic aperture radar technology is fragmenting the optical-dominated procurement landscape across maritime and defense applications. Saudi naval commands and UAE coast guard units now specify radar payloads as primary collection assets for Persian Gulf surveillance. This sensor shift is compressing contract awards to vendors with operational SAR constellations, marginalizing pure-play optical operators in security-sensitive procurements.
SFDA and MOHAP data governance frameworks are extending into environmental monitoring domains, creating compliance overlays for satellite-derived health-relevant datasets. Industrial consequence includes mandatory anonymization protocols for settlement pattern analysis and stricter chain-of-custody documentation. Agricultural analytics providers serving precision farming clients across the region face the most acute adaptation requirements.
Subscription-based imagery access is displacing per-scene licensing across infrastructure and agricultural buyer segments. Engineering firms and commodity traders now expect API-delivered, analytics-ready data streams rather than raw product downloads. This pattern shift is most visible in UAE and Saudi Arabia, where sovereign wealth-backed agtech ventures demand continuous field monitoring rather than seasonal campaign purchases.
Middle East Satellite-Based Earth Observation Market Segmentation
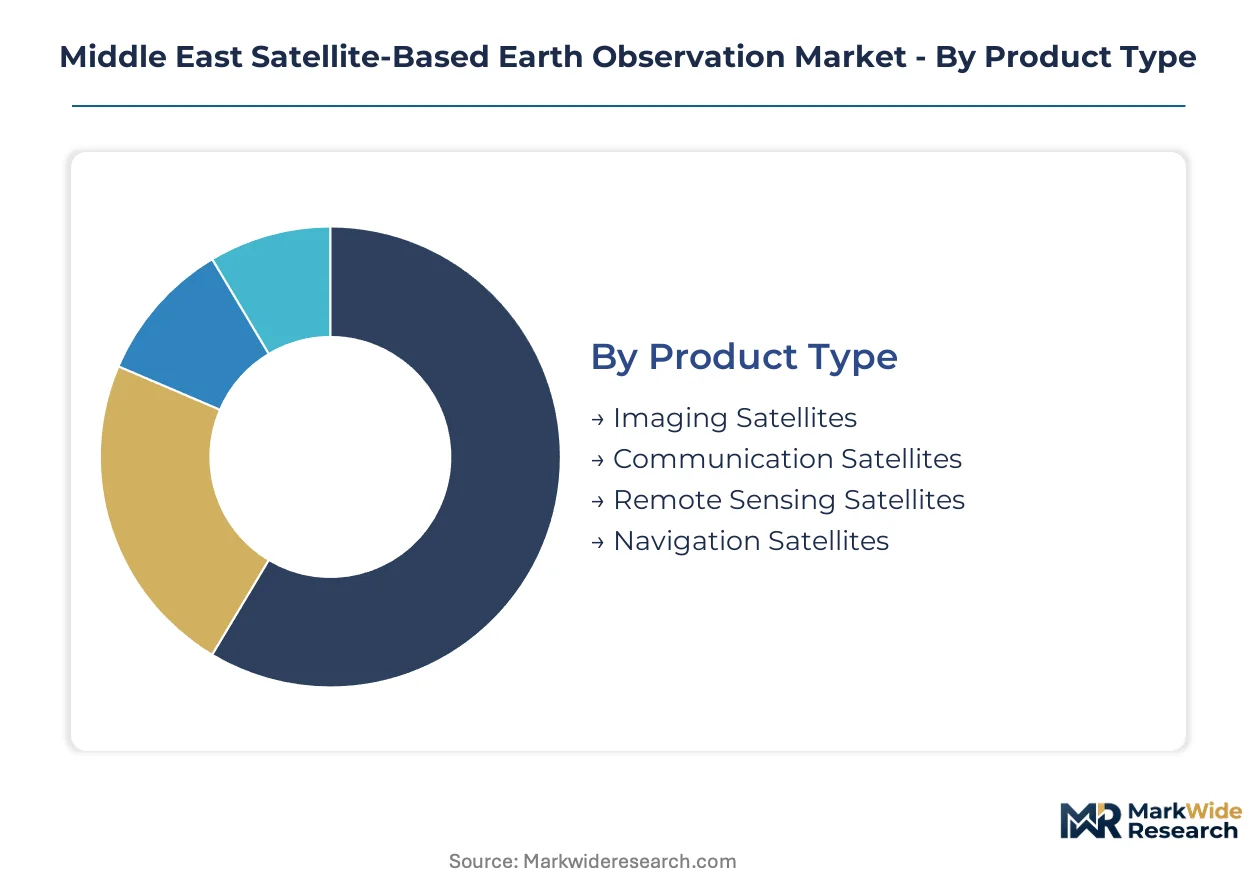
Segmentation in the Middle East satellite-based Earth observation market reveals how procurement specifications diverge across defense, agricultural, and infrastructure applications. Regulatory mandates from the UAE Space Agency and Saudi Communications and Information Technology Commission shape which technology configurations qualify for sovereign contracts.
Product Type:
ISO 17770 geospatial data quality standards and local data residency requirements create divergent qualification pathways for each satellite category across Gulf defense ministries.
- Imaging Satellites:High-resolution optical and synthetic aperture radar platforms deliver sub-meter resolution for border surveillance and maritime domain awareness. Defense ministries across Saudi Arabia and the UAE prioritize these assets for Persian Gulf vessel tracking, with procurement timelines compressing under sovereign capacity-building mandates.
- Remote Sensing Satellites:Multispectral and hyperspectral payloads capture reflected electromagnetic signatures across agricultural zones in the Nile Delta and Fertile Crescent. Egypt's irrigation-intensive farming sector generates recurring demand for crop health analytics, though dust storm interference limits effective collection windows.
- Communication Satellites:Relay infrastructure enabling real-time data downlink for tactical military operations and emergency response coordination.
- Navigation Satellites:Positioning augmentation supporting precision agriculture machinery and autonomous maritime vessel routing.
Imaging satellites handle the majority of throughput; remote sensing satellites are the fastest mover on share.
End User:
Customer procurement sophistication varies sharply, with defense buyers commanding premium pricing for rapid-tasking capabilities while agricultural users migrate toward subscription-based access models.
- Defense:Gulf Cooperation Council naval commands and coast guard units specify all-weather synthetic aperture radar for Red Sea and Persian Gulf surveillance. Contract awards concentrate with vendors offering certified processing pipelines and local ground station partnerships mandated by Saudi and UAE licensing frameworks.
- Agriculture:Precision farming operations across Egypt, Saudi Arabia, and the UAE demand high-revisit crop monitoring. Sovereign wealth-backed agtech ventures in Riyadh and Abu Dhabi now expect API-delivered, analytics-ready data streams rather than seasonal campaign purchases.
- Environmental Monitoring:SFDA and MOHAP data governance frameworks extend compliance requirements to satellite-derived health-relevant datasets, mandating anonymization protocols for settlement pattern analysis.
- Urban Planning:Infrastructure development agencies leverage sub-meter optical imagery for construction progress tracking and utility corridor monitoring.
Defense commands the highest contract values; agriculture is expanding most quickly as subscription models displace per-scene licensing.
Application:
Pricing stratification across premium, standard, and economy tiers reflects urgency thresholds and data freshness requirements rather than resolution alone.
- Disaster Management:Flood and seismic event response agencies pay above-market rates for rapid-tasking capabilities. Saudi civil defense and UAE national emergency authorities specify guaranteed collection windows within hours of activation, creating margin expansion distinct from commoditized offerings.
- Land Use Monitoring:Volume-driven service category serving infrastructure planning and property registration functions across Gulf municipal governments. Mature procurement standards favor vendors with ISO-certified processing pipelines over opportunistic imagery resellers.
- Climate Change Analysis:Long-term environmental trend tracking for desertification monitoring and coastal erosion assessment.
- Resource Management:Water reservoir monitoring and petroleum infrastructure surveillance across Saudi Arabia's Eastern Province and UAE onshore fields.
Land use monitoring handles the majority of throughput; disaster management is gaining share fastest through premium service differentiation.
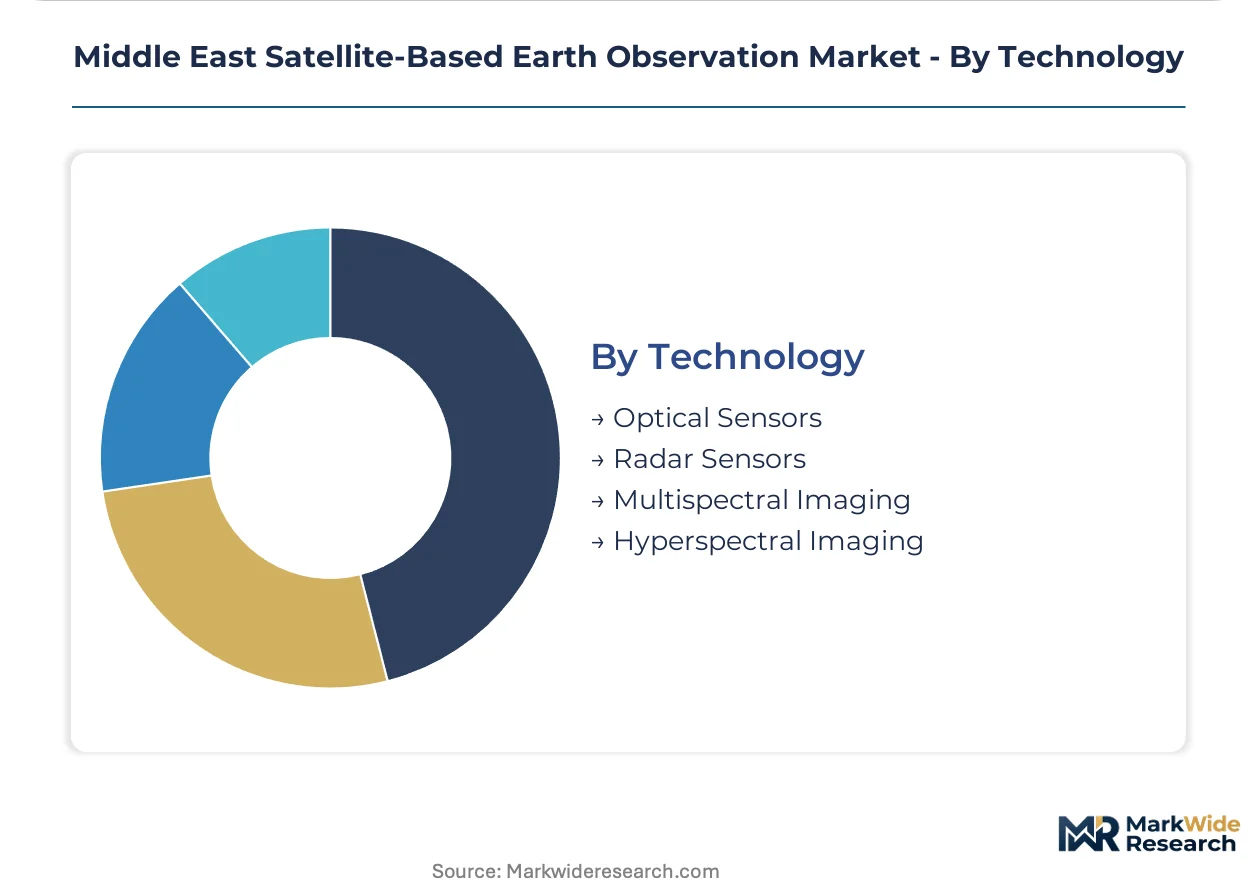
Technology:
Sensor selection increasingly hinges on atmospheric conditions across the Arabian Peninsula rather than resolution specifications alone.
- Radar Sensors:Synthetic aperture radar penetrates dust storms and cloud cover that degrade optical performance across the region. Saudi naval procurement now specifies radar as primary collection assets for maritime domain awareness, marginalizing pure-play optical operators in security-sensitive contracts.
- Optical Sensors:Sub-meter resolution systems dominate agricultural monitoring procurement for the Nile Delta and Fertile Crescent where atmospheric clarity permits. Persistent dust storm interference across the Arabian Peninsula forces redundant satellite passes and inflates operational costs.
- Multispectral Imaging:Narrowband spectral capture for vegetation index calculation and mineral deposit identification.
- Hyperspectral Imaging:Continuous spectrum analysis for advanced material classification and environmental contaminant detection.
Optical sensors retain volume leadership in agricultural applications; radar sensors show the steepest expansion trajectory as defense procurement shifts toward all-weather capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense ministries and sovereign wealth funds concentrate procurement authority in Gulf capitals, with satellite imagery buyers clustering around Riyadh, Abu Dhabi, and Dubai. National space agencies channel contract awards toward vendors meeting domestic technology transfer requirements.
Saudi Arabia
Naval commands and coast guard units drive synthetic aperture radar procurement for Red Sea vessel tracking. Saudi Vision 2030 mandates joint venture structures for foreign satellite manufacturers seeking defense contracts. The Eastern Province hosts petroleum infrastructure surveillance operations requiring sub-meter optical monitoring.
United Arab Emirates
The UAE Space Agency licenses foreign operators through data residency requirements that compel local ground station partnerships. Mohammed Bin Rashid Space Centre anchors domestic Earth observation capacity building in Dubai. Abu Dhabi sovereign wealth vehicles channel capital into agtech ventures demanding API-delivered crop analytics.
Egypt
Irrigation-intensive farming across the Nile Delta generates volume demand for multispectral crop health monitoring. The country's national space regulator shapes procurement specifications for agricultural analytics contracts. Cairo-based engineering firms subscribe to continuous field monitoring services rather than seasonal imagery purchases.
Israel
Defense and intelligence agencies sustain premium pricing for rapid-tasking capabilities with guaranteed collection windows. The national communications regulator oversees satellite operator licensing with stringent security protocols. Tel Aviv metropolitan area clusters geospatial analytics talent serving regional maritime domain awareness contracts.
Qatar
Coast guard modernization programs specify all-weather radar payloads for Persian Gulf surveillance operations. The national space policy framework emphasizes sovereign capacity building through technology transfer agreements. Doha-based infrastructure development agencies leverage sub-meter imagery for construction progress tracking.
Middle East Satellite-Based Earth Observation Market Competitive Landscape
Player mix skews toward dual-use aerospace conglomerates and commercial constellation operators. Market structure concentrates contract awards among vendors with certified processing pipelines and local partnership structures. Two strategic archetypes dominate: integrated platform providers with sovereign manufacturing heritage, and specialized sensor operators with rapid-revisit architectures. Competitive moves center on joint venture formation with Gulf state entities and ground station infrastructure deployment.
Within the integrated platform tier, Airbus Defense and Space represents established defense ministry relationships across the region. Among commercial constellation specialists, ICEYE and Planet Labs PBC occupy positions exemplifying divergent sensor strategies—synthetic aperture radar versus high-revisit optical architectures. Maxar Technologies anchors the premium-resolution segment serving detailed infrastructure monitoring requirements. These three operators illustrate how vendor qualification pathways fragment between sovereign partnership mandates and direct commercial licensing routes.
| Leading Market Players |
|---|
| Al Yah Satellite Communications Company PJSC (Yahsat) |
| Airbus Defense and Space |
| SARsat Arabia |
| Mohammed Bin Rashid Space Centre (MBRSC) |
| Arabsat |
| Maxar Technologies |
| Planet Labs PBC |
| ICEYE |
| ImageSat International |
| Others |
Pricing and Supply Chain Analysis
ISO 17770 geospatial data quality standards gate both vendor qualification and price differentiation simultaneously, favoring certified processing pipelines over opportunistic imagery resellers while compressing margins for uncertified operators across Gulf defense procurement.
Pricing Analysis
Cost-plus contracts with Saudi Vision 2030 joint ventures and UAE Space Agency partnerships typically index to payload component costs and local technology transfer milestones. Pricing stratifies across premium rapid-tasking, standard subscription, and economy per-scene tiers, with defense buyers least sensitive and agricultural users most price-responsive. Cost compression in standard-tier agricultural monitoring intensifies as API-delivered analytics displace raw imagery downloads. Disaster management agencies command premium rates for guaranteed collection windows within hours of activation.
Supply Chain Analysis
Port congestion along Jebel Ali and Dammam corridors elevates inbound logistics costs for optical sensor components and radar payload subsystems sourced from European and East Asian manufacturing hubs. Component supply concentrates in France, Germany, and South Korea for synthetic aperture radar arrays, multispectral detectors, and attitude control systems. Single-source vulnerability persists for radiation-hardened electronics and precision optics. Distribution runs through sovereign joint venture structures mandated by Saudi and UAE licensing frameworks, with local ground station partnerships required for market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from small satellite constellation operators compressing revisit intervals and fragmenting traditional prime contractor roles across Middle East defense and agricultural procurement.
For Market Incumbents: Secure certified processing pipeline investments to maintain ISO 17770 compliance advantages as Gulf defense ministries tighten qualification requirements. Anchor local ground station partnerships in Riyadh and Abu Dhabi to satisfy data residency mandates from the UAE Space Agency and Saudi Communications and Information Technology Commission. Vertical integration into domestic manufacturing joint ventures defends against emerging constellation specialists capturing maritime domain awareness contracts. For New Entrants and Emerging Players: Certification fast-track through ISO 17770 accreditation opens procurement pathways currently blocked to opportunistic imagery resellers. White-space concentration exists in Nile Delta agricultural analytics, where Egypt's irrigation-intensive farming sector remains underserved by high-revisit commercial offerings. Target subscription-based API delivery models for sovereign wealth-backed agtech ventures in Saudi Arabia and the UAE that demand continuous field monitoring rather than seasonal campaign purchases. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across synthetic aperture radar constellation deployment as Saudi naval procurement shifts toward all-weather capabilities. Long-term viability favors vendors with dual-use heritage and established Gulf defense ministry relationships over pure-play commercial operators. Acquisition target archetype: specialized sensor operators with rapid-revisit architectures and existing local partnership structures. Signal to watch: joint venture announcement velocity with Mohammed Bin Rashid Space Centre or Saudi sovereign wealth vehicles as inflection indicator for contract award concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Formation | Local partnership structures satisfy UAE Space Agency and Saudi CITC data residency mandates for market access. |
| Ground Station Deployment | Domestic downlink infrastructure enables real-time tactical support for Gulf coast guard rapid-tasking requirements. |
| ISO 17770 Certification | Certified processing pipelines qualify vendors for defense and environmental monitoring contracts across the region. |
| SAR Constellation Expansion | All-weather imaging capabilities capture Saudi naval procurement shifting from optical-dominated specifications. |
| API Platform Development | Analytics-ready data streams align with subscription migration among UAE and Saudi agtech ventures. |
Research Methodology
A standing panel of satellite payload engineers, defense procurement officers at Gulf Cooperation Council ministries, geospatial analytics directors, and ground station operations managers provided ongoing calibration across primary interview cycles. Secondary validation drew from UAE Space Agency licensing disclosures, Saudi Communications and Information Technology Commission regulatory filings, ISO certification registries, and customs data on optical and radar component trade flows. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including sovereign space agency budget disclosures and defense ministry procurement announcements. The analytical framework modeled technology segments, end-user categories, application types, and regional regulatory clusters throughout the projection horizon. CAGRs derived from segment-level growth trajectory analysis incorporating satellite launch schedules, joint venture formation velocity, and procurement timeline compression under Saudi Vision 2030 mandates.
Decision-makers should treat outputs as directional under assumptions of sustained sovereign wealth deployment into domestic satellite manufacturing and continued dust storm interference degrading optical sensor performance; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Satellite Operation Service Market
Satellite
Israel Satellite-Based Earth Observation Market
Satellite
Global Nanosatellite and Microsatellite Market
Satellite
Mexico Satellite Connectivity Market
Satellite
Asia-Pacific Satellite Manufacturing Market
Satellite
Global Dish Antennas Market
Satellite
Satellite Bus Market
Satellite
Global Commercial Satellite Imaging Market
Satellite
Small Satellite Launch Market
Satellite
Europe Military Satellite Market
Satellite
Satellite Imaging Market
Satellite
Global Maritime Satellite Communication Market
Satellite
Satellite Compass Market
Satellite
India Satellite Connectivity Market
Satellite
Satellite Attitude and Orbit Control System Market
Satellite
Flat Panel Satellite Antenna Market