
 Aircraft Mounts Market | 2026-2036
Aircraft Mounts Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Mounts Market Intelligence
North American specialty elastomer compounders is realigning capacity toward aerospace-grade rubber-metal bonding for next-generation engine mounts. Trelleborg AB leverages its polymer formulation heritage across Swedish and US manufacturing nodes. LORD Corporation anchors the high-damping segment through proprietary constrained-layer architectures. Parker-Hannifin Corporation competes on integrated hydraulic-mechanical mount systems for commercial turbofan programs.
Aircraft mounts are load-bearing structural interfaces engineered to isolate vibration, absorb shock, and maintain alignment between engines, avionics, or auxiliary equipment and the airframe, typically fabricated from elastomeric compounds bonded to metallic substrates with specified stiffness ratings measured in pounds per inch deflection. Their primary function is to protect sensitive components from fatigue-inducing oscillations while transmitting operational loads without resonance amplification. Engine mounts command the largest value pool given their load-critical role and certification burden, while composite material mounts represent the fastest-expanding category as airframers pursue gram-level weight reduction targets. Vibration isolators sustain premium pricing due to proprietary elastomer recipes and extended qualification cycles.
FAA airworthiness standards under Part 25 and Part 29 govern mount fatigue life and fire resistance, while EASA CS-25 imposes equivalent European certification demands that shape transatlantic supplier qualification protocols. China's CAAC harmonizes with FAA baseline but adds domestic material traceability requirements that extend approval timelines for foreign producers. Stakeholders must monitor evolving sustainable aviation fuel compatibility standards, as thermal and chemical exposure profiles from alternative propulsion architectures will redefine elastomer specification thresholds.
Market Dynamics
Lightweight composite mount architectures are displacing traditional elastomer-metal bonded assemblies across narrowbody programs, compressing qualification timelines while elevating material traceability burdens on compounders.
Growth Catalysts
- FAA Part 25 fatigue mandates:Stricter airworthiness directives on vibration isolation lifespan force fleet retrofits, expanding aftermarket demand for certified replacement mounts.
- Asia-Pacific narrowbody assembly:China's COMAC C919 and India's regional aircraft programs require localized mount supply chains with domestic content thresholds.
- Silicone-fluorocarbon elastomer blends:Next-generation compounds withstand sustainable aviation fuel thermal profiles, enabling compatibility with alternative propulsion architectures.
Market Restraints
- Specialty polymer feedstock concentration:Aerospace-grade fluoroelastomer precursors concentrate among three German and Japanese chemical suppliers, exposing mount fabricators to input volatility.
- Extended CAAC material traceability:China's aviation regulator requires batch-level documentation extending approval timelines for foreign producers.
- Metallic substrate substitution ceiling:Titanium and Inconel mounts retain load-critical engine applications where composites lack proven fatigue life.
Strategic Opportunities
- Urban air mobility platforms:Electric vertical takeoff aircraft need compact, high-frequency vibration isolators for distributed propulsion motors.
- Indian military helicopter modernization:Indigenous rotorcraft programs under Hindustan Aeronautics create captive demand for shock-mount qualification partnerships.
- EU Green Deal sustainable aviation incentives:EASA CS-25 amendments favoring lighter airframe components accelerate composite mount adoption on European-registered fleets.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise for high-damping aerospace elastomers concentrates among retiring specialists at legacy rubber compounders.
- Dual certification burden:Simultaneous FAA and EASA qualification for engine mounts extends development cycles without harmonized test protocols.
- Legacy fleet retrofit complexity:Installing modern isolators on aging Boeing 737NG and Airbus A320ceo airframes requires structural modification approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Mounts Market |
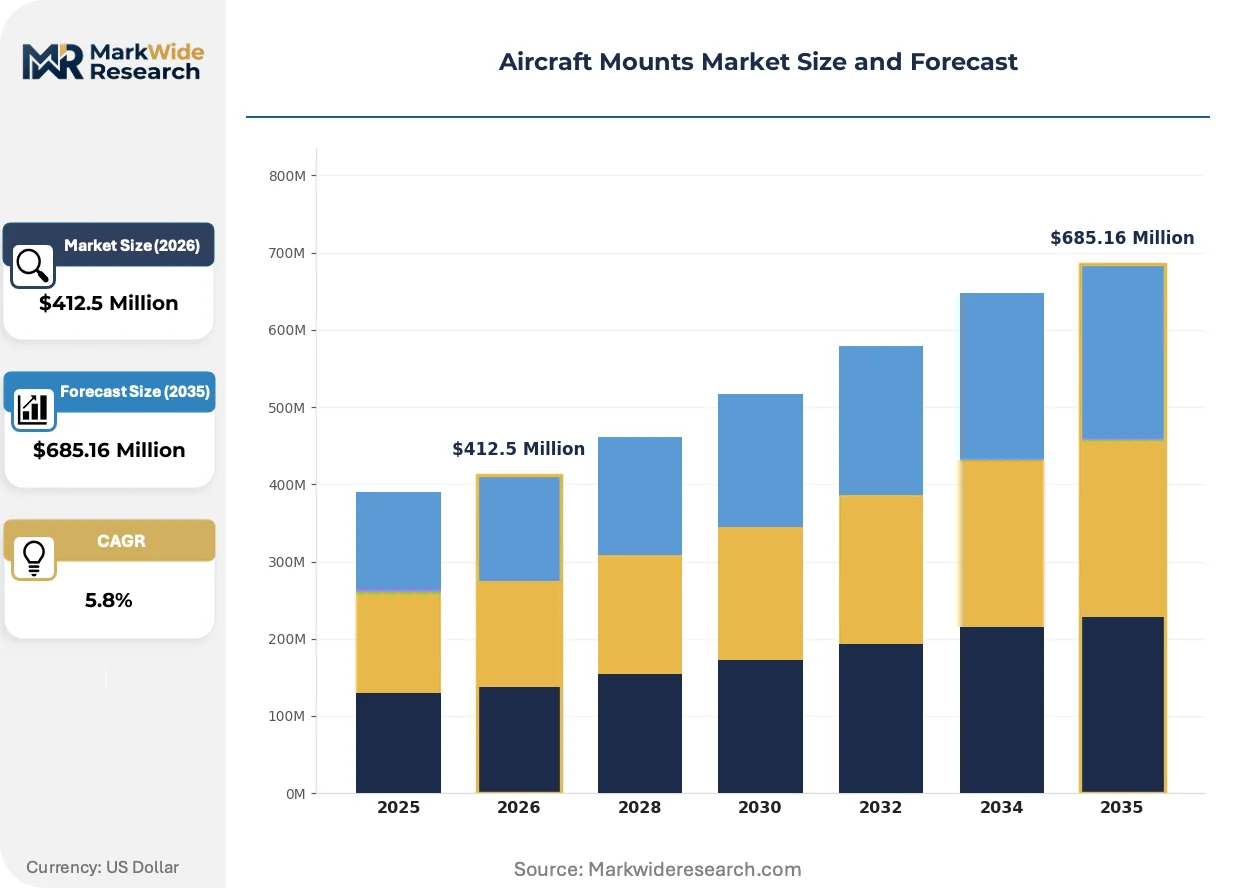
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Aluminum, Steel, Composite, Titanium Type: Vibration Isolators, Engine Mounts, Equipment Mounts, Sensor Mounts Application: Commercial Aviation, Military Aviation, Helicopters, Unmanned Aerial Vehicles Design: Custom-Fabricated, Standardized, Modular, Integrated |
| Companies Covered | Trelleborg AB, GMT Rubber-Metal-Technic Ltd., Cadence Aerospace, ESCO Technologies Inc., Shock Tech, Inc., AirLoc Ltd., Parker-Hannifin Corporation, HUTCHINSON AEROSPACE & INDUSTRY INC., LORD Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Mounts Market Strategic Shifts & Innovations
Additive manufacturing of titanium lattice structures is reshaping mount topology optimization, enabling load-path customization previously unattainable through conventional forging or machining processes.
Topology-optimized metallic lattices fabricated via electron beam melting are decentralizing structural design authority from traditional forging houses to airframer engineering teams. Airbus and Boeing now specify lattice density gradients in mount interfaces rather than purchasing standard elastomer-bonded assemblies. This shift compresses supplier margins on conventional products while elevating software and simulation licensing value.
EASA's proposed CS-25 amendments on fire-resistant elastomer specifications are tightening compound formulation standards across European-registered fleets. The regulation mandates 15-minute flame exposure integrity for engine compartment mounts, disqualifying standard nitrile rubber grades. German and French compounders are accelerating silicone-fluorocarbon blend qualification to capture retrofit demand from operators of aging A320ceo and A330 aircraft.
Airline technical procurement teams now unbundle vibration isolator purchases from airframe OEM service agreements, directly negotiating with Trelleborg and LORD Corporation for aftermarket volume commitments. This disintermediation concentrates in North American and European low-cost carriers with standardized narrowbody fleets. The practice compresses distributor margins while rewarding compounders with established MRO channel relationships and rapid-turn qualification documentation.
Aircraft Mounts Market Segmentation
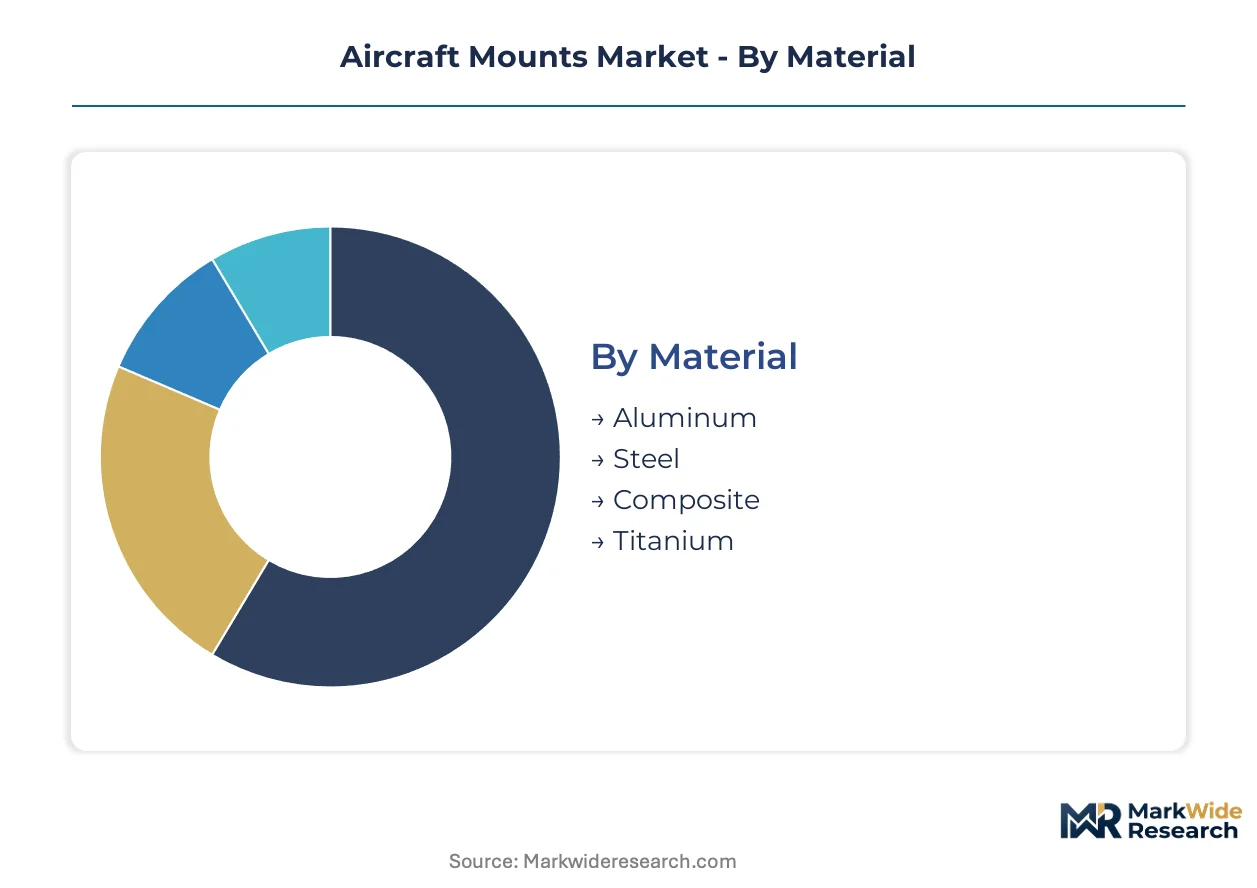
Aircraft mounts demand diverges sharply across material classes and airworthiness tiers, with FAA Part 25 engine mounts commanding distinct qualification protocols from commercial UAV isolators. Segmentation reveals how certification burden concentrates value in metallic substrates for load-critical applications while composite alternatives capture gram-conscious narrowbody programs.
Material:
Aluminum and steel grades require FAA fatigue certification under Part 25 for commercial turbofan engine interfaces, while composite and titanium variants face extended EASA CS-25 fire-resistance validation cycles.
- Aluminum:Cast and forged 7075-T6 alloys dominate narrowbody engine pylons due to strength-to-weight ratios and established MRO repair protocols. China's COMAC C919 assembly lines in Shanghai source aluminum mounts from domestic certified suppliers under CAAC material traceability mandates.
- Steel:High-strength alloy grades anchor military helicopter transmission mounts where fatigue life exceeds 100,000 cycles. India's Hindustan Aeronautics Limited specifies Indian-origin steel substrates for indigenous rotorcraft programs under defense procurement localization rules.
- Composite:Carbon-fiber-reinforced polymers displace metal in avionics racks and auxiliary equipment brackets. EASA Green Deal incentives accelerate adoption on European-registered fleets seeking weight reduction credits.
- Titanium:Ti-6Al-4V forgings retain exclusivity in high-temperature engine zones where thermal expansion coefficients must match turbine housings. Additive manufacturing lattices from electron beam melting now supplement conventional forging for topology-optimized load paths.
Aluminum sits at the top of the volume ranking, with composite climbing the fastest.
Type:
Cost tiering separates million-dollar engine mount assemblies from commoditized equipment brackets, with vibration isolators commanding premium pricing for proprietary elastomer formulations.
- Vibration Isolators:Elastomer-metal bonded assemblies with tuned stiffness ratings protect avionics from harmonic resonance. LORD Corporation's constrained-layer architectures dominate commercial turbofan nacelle applications where FAA mandates 15-minute fire exposure integrity.
- Engine Mounts:Load-critical structural interfaces transmit thrust and weight loads while accommodating thermal expansion. These assemblies carry the heaviest certification burden, requiring simultaneous FAA and EASA qualification that extends development cycles without harmonized test protocols.
- Equipment Mounts:Standardized brackets for galley inserts and cabin systems prioritize interchangeability over custom engineering. Airlines now unbundle these purchases from OEM service agreements, negotiating directly with Trelleborg for aftermarket volume commitments.
- Sensor Mounts:Miniaturized isolators for inertial navigation and weather radar demand micro-deflection precision. Urban air mobility platforms need compact, high-frequency variants for distributed electric propulsion motors.
Engine mounts capture the highest value per unit, with vibration isolators expanding most quickly in the retrofit aftermarket.
Application:
Customer procurement maturity varies from airline technical teams with unbundled sourcing strategies to military programs with captive domestic content thresholds.
- Commercial Aviation:Narrowbody fleets generate volume demand for lightweight isolators as Asia-Pacific carriers expand COMAC and Airbus assembly lines. Low-cost carriers in North America and Europe concentrate purchasing power through standardized fleet configurations.
- Military Aviation:Fighter and transport programs prioritize survivability over weight, specifying titanium and Inconel for battle damage tolerance. Extended CAAC material traceability requirements complicate foreign supplier participation in China's indigenous programs.
- Helicopters:Rotorcraft mounts endure unique multi-axis vibration spectra requiring specialized elastomer recipes. India's military helicopter modernization creates captive demand for shock-mount qualification partnerships with HAL.
- Unmanned Aerial Vehicles:Commercial drone operators prioritize cost over certification depth, accepting standardized aluminum brackets without full Part 25 validation. Regulatory divergence between FAA Part 107 and EASA open categories fragments specification standards.
Commercial aviation dominates unit volume, with unmanned aerial vehicles gaining share fastest in the sub-55-pound regulatory category.
Design:
Supply concentration in polymer formulation expertise shapes which fabricators can deliver integrated versus modular architectures.
- Custom-Fabricated:Airframer-specific designs with proprietary load-path optimization require deep collaboration with compounders. Airbus and Boeing now specify lattice density gradients rather than purchasing standard elastomer-bonded assemblies.
- Standardized:Catalog items for cabin equipment and auxiliary systems enable rapid procurement without engineering review. These products face margin compression as distributors lose volume to direct airline negotiations.
- Modular:Interchangeable subassemblies reduce spare parts inventory for mixed-fleet operators. MRO channels favor modular designs for 737NG and A320ceo retrofit programs where structural modification approvals complicate installation.
- Integrated:Hydraulic-mechanical hybrid systems combine damping and actuation in single assemblies. Parker-Hannifin competes in this segment for commercial turbofan programs requiring active vibration cancellation.
Standardized designs lead in shipment volume, with integrated systems showing the steepest expansion trajectory in next-generation propulsion architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting mount fabrication toward jurisdictions with streamlined certification reciprocity, as compounders seek to minimize dual-qualification burdens while maintaining FAA and EASA equivalence.
United States
Commercial turbofan retrofits and military helicopter upgrades sustain demand for high-damping elastomer assemblies. FAA Part 25 fatigue mandates force fleet-wide vibration isolator replacements, expanding aftermarket volume. Wichita's aviation cluster hosts specialty rubber-metal bonding operations serving Boeing and Gulfstream programs.
Germany
EASA CS-25 fire-resistance amendments accelerate silicone-fluorocarbon blend qualification for European-registered narrowbodies. German compounders dominate aerospace-grade fluoroelastomer precursor supply. Hamburg's MRO corridor concentrates retrofit demand from aging A320ceo and A330 operators seeking 15-minute flame exposure integrity.
China
COMAC C919 assembly lines in Shanghai and Xi'an require localized mount supply chains with domestic content thresholds. CAAC material traceability mandates extend approval timelines for foreign producers. Tianjin's aerospace industrial zone hosts captive fabrication facilities serving narrowbody final assembly.
India
Hindustan Aeronautics Limited's indigenous rotorcraft programs create demand for shock-mount qualification partnerships with domestic fabricators. Defense procurement localization rules specify Indian-origin steel substrates for military helicopter transmission mounts. Bangalore's aerospace engineering corridor attracts joint ventures for vibration isolator technology transfer.
Japan
Specialty elastomer formulation expertise concentrates among legacy compounders facing polymer chemist succession challenges. METI industrial standards govern rubber-metal bonding quality assurance for commercial aviation exports. Nagoya's manufacturing belt supplies mount subassemblies to regional aircraft and helicopter OEMs.
Aircraft Mounts Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue urban air mobility and electric propulsion niches with compact high-frequency isolator designs. The vendor base stratifies across three tiers: integrated system houses with hydraulic-mechanical hybrid capabilities, specialty elastomer compounders with proprietary damping architectures, and regional fabricators serving aftermarket MRO channels. Consolidation pressure concentrates among mid-scale rubber-metal bonding operations lacking qualification documentation depth. Dominant competitive moves include backward integration into polymer formulation and strategic partnerships with airframer engineering teams for topology-optimized lattice specifications.
Among Swedish and US-based compounders, Trelleborg AB and LORD Corporation exemplify the specialty elastomer tier, anchoring proprietary constrained-layer and high-damping product positions. Parker-Hannifin Corporation occupies the integrated systems vector, representing hydraulic-mechanical hybrid architectures for active vibration cancellation applications.
| Leading Market Players |
|---|
| Trelleborg AB |
| GMT Rubber-Metal-Technic Ltd. |
| Cadence Aerospace |
| ESCO Technologies Inc. |
| Shock Tech, Inc. |
| AirLoc Ltd. |
| Parker-Hannifin Corporation |
| HUTCHINSON AEROSPACE & INDUSTRY INC. |
| LORD Corporation |
| Others |
Cost & Logistics Intelligence
Aerospace-grade fluoroelastomer precursors from German and Japanese chemical suppliers cascade through three pricing tiers before reaching mount fabricators, with batch certification costs amplifying spreads between aftermarket retrofits and OEM line-fit assemblies.
Pricing Analysis
Distributor margins on standard equipment brackets compress as low-cost carriers in North America and Europe negotiate direct volume commitments with Trelleborg and LORD Corporation. Pricing stratifies across FAA-certified engine mounts, EASA-validated fire-resistant variants, and non-certified UAV brackets. Cost compression in the standard tier intensifies because airlines now unbundle cabin equipment purchases from OEM service agreements. Military helicopter programs exhibit lowest price sensitivity due to survivability mandates and domestic content rules.
Supply Chain Analysis
Polymer chemist scarcity in Wichita and Hamburg constrains rubber-metal bonding capacity expansion despite narrowbody assembly growth in China and India. Supply concentrates in the United States, Germany, and Japan for aerospace-grade elastomer formulation. Raw material dependencies span fluoroelastomer precursors, titanium forgings, and carbon-fiber prepregs. Single-source vulnerability persists where three chemical suppliers control specialty polymer feedstocks. Distribution runs through airframer-specified tier-1 integrators for engine mounts and direct MRO channels for aftermarket isolators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where CAAC material traceability burdens in China create cost differentials against FAA-streamlined qualification pathways in the United States.
For Market Incumbents: Acquire polymer formulation expertise to secure proprietary damping architectures against emerging lattice-structure competitors. Backward integration into silicone-fluorocarbon blending insulates margin from German and Japanese chemical supplier concentration. Expand Wichita and Hamburg bonding capacity to capture COMAC C919 and A320neo line-fit demand before local Chinese fabricators achieve CAAC certification depth.
For New Entrants and Emerging Players: Direct-to-MRO digital platforms bypass distributor layers on standardized equipment brackets for aging 737NG and A320ceo fleets. Urban air mobility electric propulsion isolators represent the most penetrable white space, with compact high-frequency designs unspecified by incumbent compounders. Target Indian military helicopter modernization through Hindustan Aeronautics qualification partnerships leveraging defense localization mandates.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale rubber-metal bonding operations lack FAA-EASA dual qualification documentation. Long-term viability favors compounders with captive polymer recipes and airframer engineering relationships. Acquisition target archetype: regional fabricators with established MRO channel access but underinvested in fire-resistant elastomer capabilities. Monitor EASA CS-25 amendment implementation timelines for inflection signals on retrofit demand velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Formulation | Captive silicone-fluorocarbon blending reduces exposure to German and Japanese chemical supplier concentration. |
| CAAC Certification Investment | Domestic qualification unlocks COMAC C919 line-fit supply contracts in Shanghai and Xi'an assembly corridors. |
| Urban Air Mobility Product Line Launch | Compact high-frequency isolators address distributed electric propulsion motor vibration in emerging eVTOL platforms. |
| Direct MRO Channel Partnership | Bypassing distributor layers captures aftermarket volume from North American and European low-cost carrier fleet standardization. |
| Additive Manufacturing Lattice Capability | Electron beam melting expertise aligns with Airbus and Boeing topology-optimized mount specifications displacing conventional forgings. |
Research Approach
Coverage spans the United States, Germany, China, India, and Japan, with primary inputs from each region's aerospace manufacturing clusters. The analysis combines structured interviews with airframer procurement directors, compounder R&D leads, MRO channel managers, and regulatory certification specialists with secondary validation from FAA airworthiness directives, EASA CS-25 amendment drafts, CAAC material traceability guidelines, and COMAC supplier qualification documents. Bottom-up segment sizing triangulates against top-down fleet expansion projections from commercial aviation production databases.
Granularity-level modeling disaggregates volume and value across material classes, mount types, application segments, and design architectures throughout the forecast period. CAGRs derive from segment-specific growth trajectories weighted by airframer procurement pipelines and aftermarket retrofit cycles. Industry-specific forecast inputs include narrowbody assembly line ramp schedules, military helicopter modernization program timelines, and urban air mobility platform certification progressions.
The model assumes a particular technology adoption path; alternative pathways for additive manufacturing lattice structures or sustainable aviation fuel thermal compatibility would alter the outlook. Forecasts reflect assumptions on regulatory harmonization progress, polymer chemist workforce availability, and airframer unbundling of vibration isolator procurement. Practitioners should monitor EASA fire-resistance amendment finalization, CAAC traceability rule enforcement intensity, and COMAC C919 production rate milestones for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Manufacturing Market
Aircraft
Aircraft Aerostructures Market
Aircraft
Military Multirole Aircraft Market
Aircraft
Regional Jet Market
Aircraft
North America Helicopters Market
Aircraft
Aircraft Window Frame Market
Aircraft
Europe Commercial Aircraft Market
Aircraft
Air Deflector Market
Aircraft
Amphibious Aircraft Market
Aircraft
Water Bomber Market
Aircraft
Vietnam Business Jets and Helicopters Market
Aircraft
Japan Aerospace and Defense Market
Aircraft
Turboprop Aircraft Market
Aircraft
Supersonic Jet Market
Aircraft
US Business Jet Market
Aircraft
Flight Management Systems Market