
 Flexible Solar Panel Market | 2026-2036
Flexible Solar Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Solar Panel Market Intelligence
Cloud-based performance monitoring and diagnostic services is hardening the value proposition beyond the initial hardware sale. SunPower Corporation leverages its established brand in high-efficiency cells to enter specialized flexible applications. MiaSolé specializes in CIGS thin-film technology for unique architectural integrations. PowerFilm Solar focuses on lightweight, durable solutions for military and portable power markets.
Flexible solar panels are photovoltaic devices built on pliable substrates like plastic or metal foil, enabling them to bend or conform to curved surfaces. These panels often utilize thin-film technologies such as amorphous silicon or CIGS, which offer lower weight compared to traditional crystalline silicon panels. Thin-film product types, including cadmium telluride, are gaining share due to manufacturing scalability. Within applications, building-integrated photovoltaics and portable chargers represent high-growth areas, commanding premium pricing for aesthetics and convenience.
Compliance with the EU's RoHS directive on hazardous substances and IEC standards for photovoltaic performance are critical for market access. In the United States, EPA regulations indirectly influence demand by promoting clean energy solutions for mobile and off-grid applications. Stakeholders must now navigate the trade-off between higher-efficiency but more costly materials and lower-cost, scalable thin-film manufacturing processes.
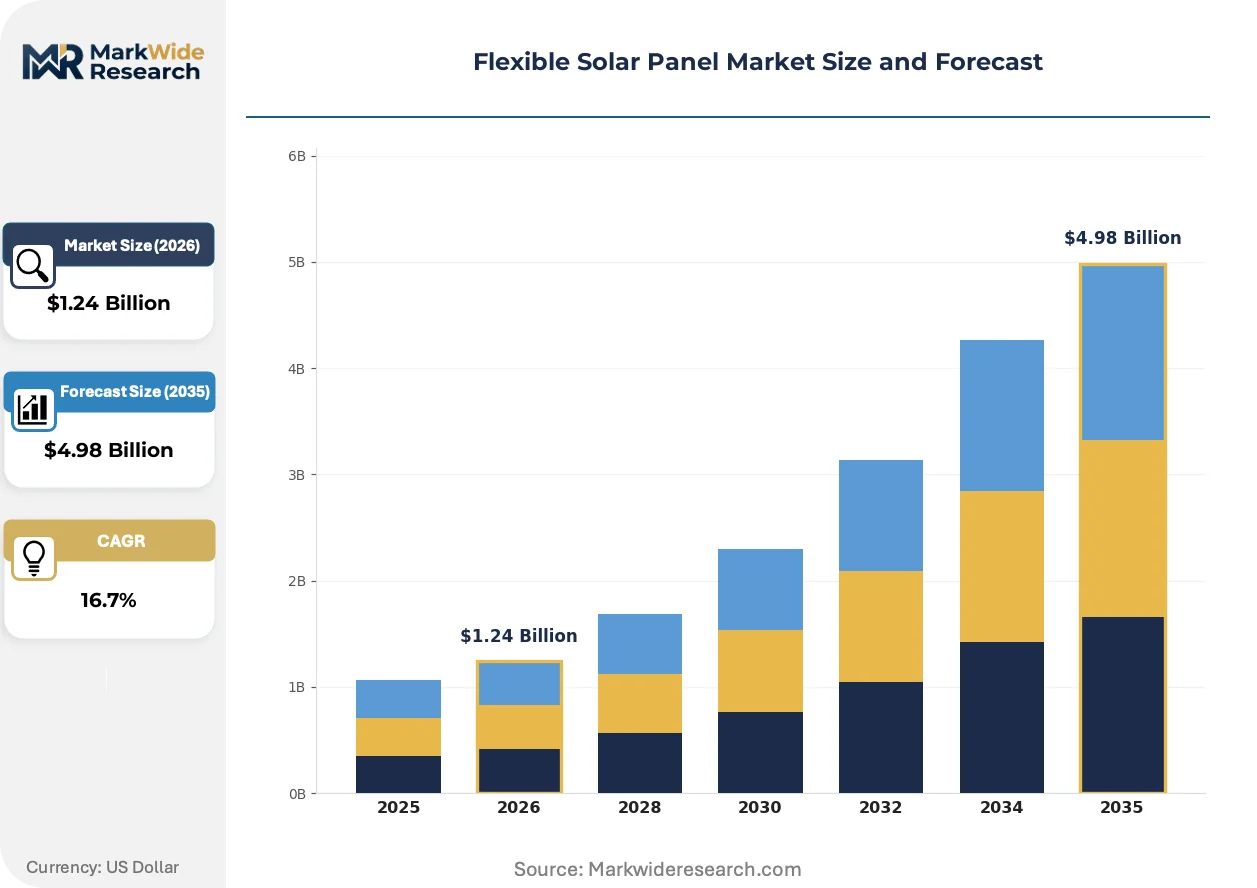
Market Dynamics
A central tension between the pursuit of higher-efficiency, premium-cost materials and the drive for scalable, lower-cost thin-film manufacturing processes defines the flexible solar panel market. This dynamic is shaped by demand for versatile form factors in building-integrated photovoltaics and portable power.
Growth Catalysts
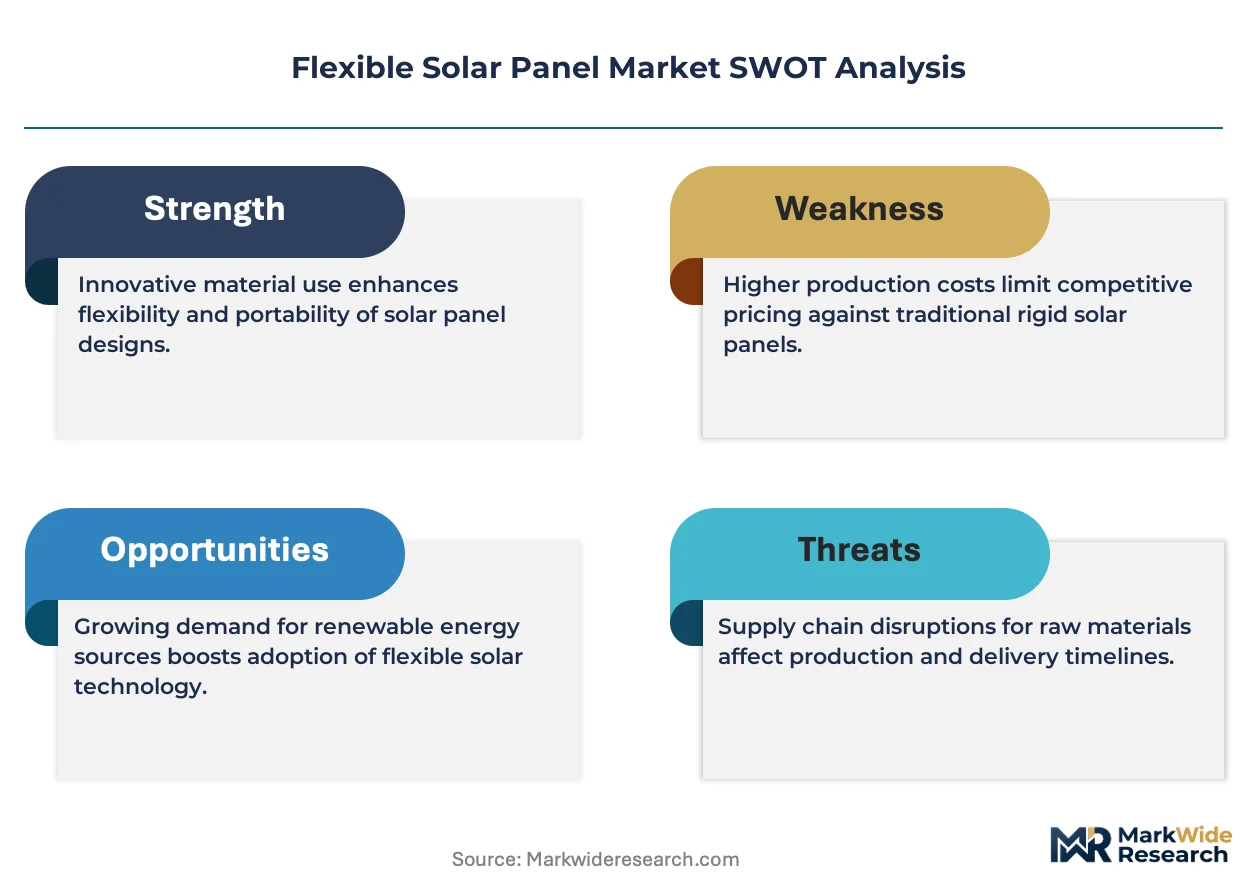
- EU Green Deal Framework:Mandates for nearly zero-energy buildings across the European Union stimulate demand for building-integrated photovoltaics, where flexible panels offer aesthetic and design advantages over rigid counterparts.
- Thin-Film Material Science:Continuous improvements in the conversion efficiency of CIGS and cadmium telluride cells are enabling lighter, more powerful products, expanding viability for aerospace and portable electronics applications.
- Off-Grid Energy Demand:The expansion of recreational vehicle, marine, and remote outdoor activities creates a consistent demand stream for lightweight, durable, and portable power generation solutions independent of grid infrastructure.
Market Restraints
- Material Cost Structure:The use of specialized, high-purity raw materials like indium and tellurium for CIGS and CdTe thin-films, respectively, introduces cost volatility and a higher price point compared to conventional silicon.
- Performance Differentials:Flexible panels generally exhibit lower energy conversion efficiency and a shorter operational lifespan than traditional rigid crystalline silicon panels, limiting their suitability for large-scale, utility-grade power generation projects.
- Substrate Technology Limitations:The polymer and metal foil substrates required for flexibility can be susceptible to degradation from UV radiation and moisture ingress over time, impacting long-term reliability and performance.
Strategic Opportunities
- Automotive Integration:Incorporating flexible photovoltaic cells into the body panels of electric vehicles and commercial trucks presents a significant opportunity to extend range and power auxiliary systems.
- Wearable Electronics:The development of ultra-thin, highly pliable solar cells opens up new product categories in wearable technology and smart fabrics, powering sensors and devices directly from ambient light.
- Disaster Relief and Military Power:Designing rapidly deployable, lightweight solar blankets and chargers for emergency response and forward-operating military bases provides a mission-critical, high-value application segment.
Industry Challenges
- Installation Skill Gap:A shortage of installers trained in integrating flexible BIPV systems into complex roofing and facade structures creates project bottlenecks and increases labor costs for architectural applications.
- End-of-Life Recycling:The lack of a mature, scaled recycling infrastructure for composite thin-film panels poses a long-term environmental and regulatory challenge for manufacturers and asset owners.
- Standardization Deficits:The absence of universal standards for panel dimensions, electrical connectors, and mounting hardware complicates system design and component interoperability, particularly in custom architectural projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Solar Panel Market |
| Market Size in 2026 | $1.24 Billion |
| Market Size in 2035 | $4.98 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin-Film, Amorphous Silicon, Cadmium Telluride Application: Wearable Electronics, Portable Chargers, Building-Integrated Photovoltaics, Outdoor Lighting, Consumer Electronics End User: Satellite Manufacturers, Recreational Vehicle Operators, Marine Equipment Suppliers, Emergency Services, Aviation Deployment: Rooftop Installations, Foldable Devices, Backpack Integration, Tent Attachments, Vehicle Surfaces |
| Companies Covered | SunPower Corporation, Flisom AG, PowerFilm Solar, MiaSolé, Global Solar, Alta Devices, Solbian, Ascent Solar Technologies, Hanergy Thin Film Power Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Solar Panel Market Strategic Shifts & Innovations
Material science advancements and application-specific engineering are transforming the market. The focus is shifting from generic panel production toward integrated systems that embed power generation seamlessly into buildings, vehicles, and portable equipment, with software adding a new layer of value.
Perovskite thin-film technology offers a pathway to high-efficiency, flexible solar cells using low-cost materials. Research institutions and specialized startups are actively developing perovskite layers for use in tandem with existing cell technologies. This emerging material **is absorbing** significant R&D investment away from mature thin-films, promising to elevate the performance ceiling for next-generation flexible and transparent solar applications.
Incentives within the US Inflation Reduction Act (IRA) are reshaping supply chain calculations for photovoltaic manufacturers. The legislation's production tax credits for domestically produced clean energy components encourage onshoring of panel and material manufacturing. This policy particularly affects suppliers targeting US military and government contracts, where secure, domestic supply chains are a procurement priority.
Customers are increasingly seeking bundled hardware and software packages that include cloud-based performance monitoring. This model disrupts the traditional one-time transactional sale of panels by creating opportunities for recurring service revenue and deeper customer engagement. The trend is most visible in the commercial BIPV sector, where building owners use diagnostic data to optimize energy yield and schedule preventative maintenance.
Flexible Solar Panel Market Segmentation
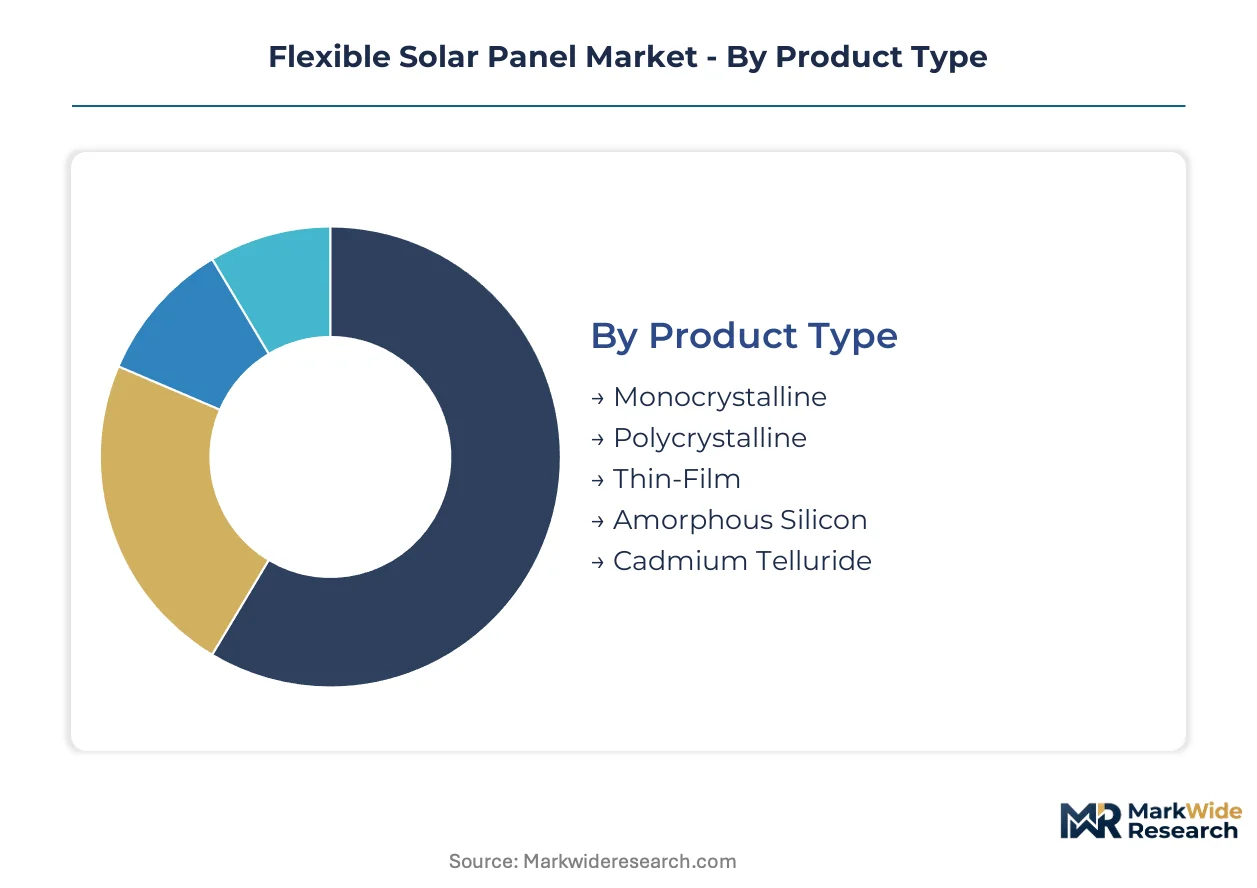
The flexible solar panel market is segmented across diverse product types, applications, end users, and deployment methods. Understanding these distinctions is critical for manufacturers to align product development with specific demand drivers. This granular analysis reveals where value creation concentrates within the market.
Product Type:
Supply concentration for flexible solar panel product types largely dictates manufacturing investment and technological refinement.
- Thin-Film:These panels use pliable substrates like plastic or metal foil and technologies such as amorphous silicon or CIGS. Their low weight and conformability are crucial for building-integrated photovoltaics, offering design advantages on curved surfaces.
- Cadmium Telluride:This thin-film technology offers manufacturing scalability and is gaining share due to efficiency improvements. It is deployed in large-area flexible panels for commercial rooftops and specialized architectural projects, enhancing aesthetic integration.
- Monocrystalline:Produced from a single silicon crystal, these panels offer high efficiency but less flexibility than thin-film.
- Polycrystalline:Made from multiple silicon crystals, these panels are more cost-effective but possess restricted pliability.
- Amorphous Silicon:This thin-film technology provides good low-light performance and inherent flexibility for portable electronics.
Today's leader: Thin-Film. Tomorrow's challenger: Cadmium Telluride.
Application:
The market's margin profile is significantly influenced by the specialized requirements and value propositions of different flexible solar panel applications.
- Building-Integrated Photovoltaics:This application embeds flexible panels into building envelopes like roofs and facades, enabling on-site power generation. It is a high-growth area, driven by EU mandates for nearly zero-energy buildings.
- Portable Chargers:These lightweight devices use flexible panels for off-grid power to mobile phones and small electronics. They command premium pricing for convenience and are in high demand for outdoor and remote activities.
- Wearable Electronics:Incorporating ultra-thin, pliable solar cells into smart fabrics and devices powers sensors directly from ambient light.
- Outdoor Lighting:Flexible panels power standalone streetlights, garden lights, and signage, reducing grid reliance in remote areas.
- Consumer Electronics:Integration into laptops, drones, and other gadgets provides extended battery life and supplementary power.
Building-Integrated Photovoltaics is expanding most quickly. Portable Chargers show a steep expansion trajectory.
End User:
Customer type segmentation highlights distinct demand patterns and procurement priorities within the flexible solar panel market.
- Recreational Vehicle Operators:This segment demands lightweight, durable, and portable power solutions for off-grid living and travel. Germany's RV sector shows particular interest in these flexible panels.
- Marine Equipment Suppliers:For yachts, sailboats, and other vessels, flexible panels provide essential auxiliary power without adding significant weight or requiring rigid mounting. Demand concentrates in regions with active marine tourism.
- Satellite Manufacturers:These entities require ultra-lightweight, radiation-resistant flexible solar arrays for powering spacecraft and orbital platforms.
- Emergency Services:Rapidly deployable, lightweight solar blankets and chargers are critical for disaster relief and maintaining communications in remote areas.
- Aviation:Flexible solar cells are explored for powering auxiliary systems in drones, stratospheric platforms, and potentially electric aircraft.
Recreational Vehicle Operators are gaining share fastest. Emergency Services show significant potential.
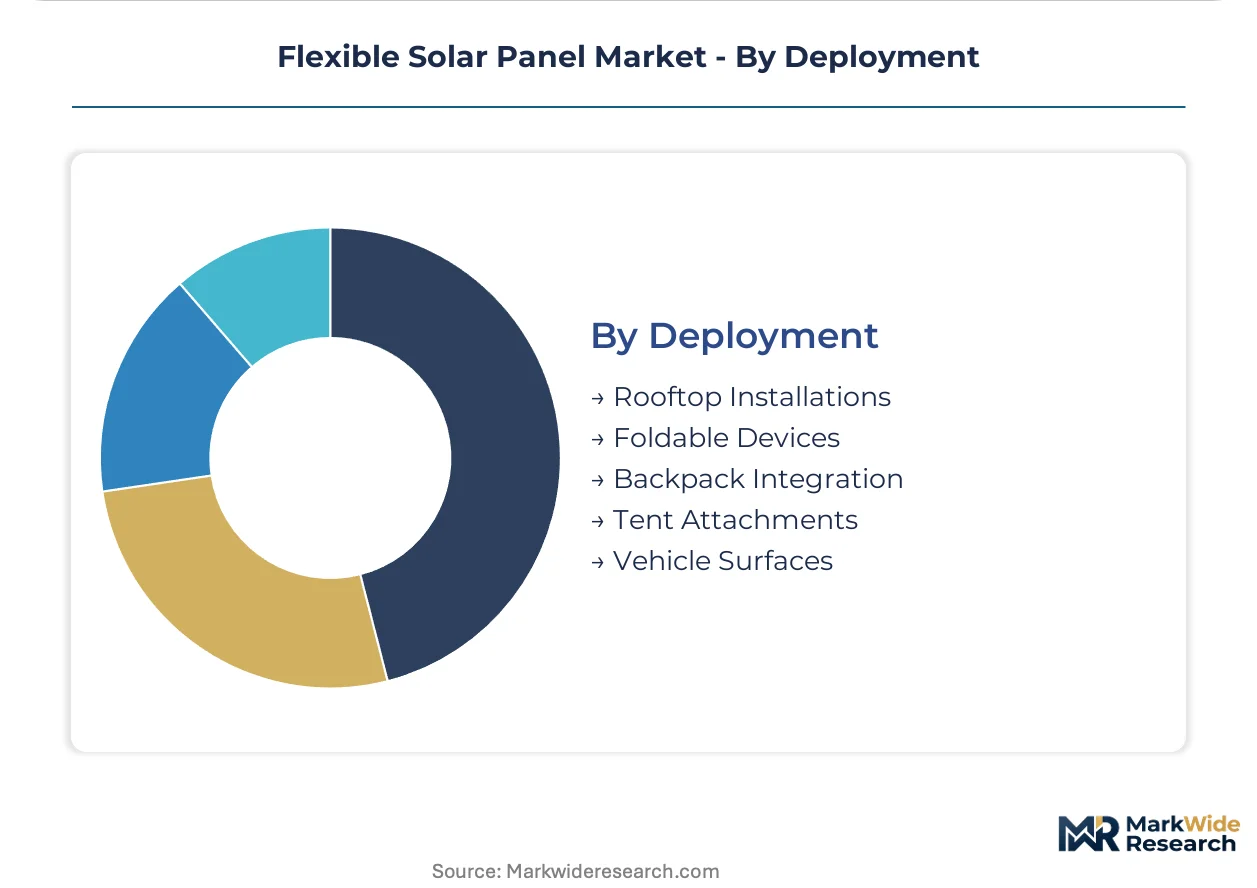
Deployment:
Volume dynamics for flexible solar panel deployment are shaped by the specific installation environments and integration requirements.
- Rooftop Installations:This involves integrating flexible panels onto curved or irregular roof surfaces, particularly in building-integrated photovoltaics. It offers aesthetic advantages where traditional rigid panels are unsuitable.
- Vehicle Surfaces:Incorporating flexible photovoltaic cells into the body panels of electric vehicles and commercial trucks extends range and powers auxiliary systems. This represents a significant automotive integration opportunity.
- Foldable Devices:These portable solutions allow users to deploy flexible panels on demand for temporary power generation in outdoor settings.
- Backpack Integration:Flexible panels are sewn or mounted onto backpacks to charge personal electronics during hiking or remote travel.
- Tent Attachments:Lightweight, conformable panels can be easily attached to tents, providing power for lighting and small devices in camping scenarios.
Rooftop Installations lead in established volume. Vehicle Surfaces show accelerating adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's strong demand for flexible panels in recreational vehicles contrasts with the United States' focus on military and off-grid applications. The European Union's Green Deal framework stimulates building-integrated photovoltaics across member states. Meanwhile, Asian markets like China and Japan are advancing thin-film material science and domestic manufacturing capabilities.
Germany
Germany's recreational vehicle and marine sectors drive significant demand for lightweight, portable power solutions. The EU Green Deal framework encourages building-integrated photovoltaics, offering aesthetic advantages for new constructions. Automotive and marine clusters in Bavaria and Mecklenburg-Vorpommern concentrate innovation for flexible panel integration.
United States
The United States market prioritizes flexible panels for military applications and off-grid power solutions. Incentives within the US Inflation Reduction Act (IRA) reshape supply chain calculations for domestic production. California's robust clean energy policies and advanced research institutions foster innovation in flexible solar technologies.
China
China's rapid urbanization and ambitious clean energy goals create substantial demand for building-integrated photovoltaics. The nation's dual carbon goals promote renewable energy integration into infrastructure projects. Manufacturing hubs in the Yangtze River Delta and Guangdong province scale up flexible thin-film panel production.
Japan
Japan's focus on high-tech applications and advanced materials science drives demand for next-generation flexible solar cells. The Ministry of Economy, Trade and Industry (METI) supports research into perovskite thin-film technologies. Research institutions in Tokyo and Kyoto lead advancements in ultra-thin and transparent solar applications.
India
India's expanding rural electrification initiatives and portable electronics market generate demand for flexible solar chargers. The Production Linked Incentive (PLI) scheme promotes domestic manufacturing of solar components. Renewable energy zones in Gujarat and Rajasthan are exploring flexible panel applications for remote power.
Flexible Solar Panel Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, defining the flexible solar panel market structure. The market exhibits a tiered structure, with established players focusing on high-efficiency niche applications and emerging manufacturers targeting scalable, cost-effective solutions. Strategic archetypes include technology innovators driving perovskite advancements, application-specific integrators for BIPV, and volume-focused producers of amorphous silicon panels. Companies pursue strategic partnerships to expand market reach and invest in capacity expansion to meet growing demand across diverse end-user segments.
Specialists in thin-film technologies and specialized applications anchor the market's competitive dynamics. SunPower Corporation, known for its established brand in high-efficiency cells, occupies a position among premium providers for specialized flexible applications. PowerFilm Solar exemplifies a producer focused on lightweight, durable solutions for military and portable power markets, leveraging its US-based operations for secure supply chains. MiaSolé, another US-based company, sits within the archetype of CIGS thin-film technology specialists, targeting unique architectural integrations and high-value building-integrated photovoltaics projects.
| Leading Market Players |
|---|
| SunPower Corporation |
| Flisom AG |
| PowerFilm Solar |
| MiaSolé |
| Global Solar |
| Alta Devices |
| Solbian |
| Ascent Solar Technologies |
| Hanergy Thin Film Power Group |
| Others |
Cost & Logistics Intelligence
Specialized BIPV installation expertise in Europe creates labor-cost differentials, influencing premium pricing for integrated flexible solar solutions.
Pricing Analysis
Capacity additions in China are reshaping price floors for amorphous silicon panels. The dominant pricing model is project-based for BIPV, with portable chargers using premium-mid-economy differentiation. Brand premium and after-sales service are key differentiation drivers. Pricing pressure stems from increased competition in thin-film manufacturing, making consumer electronics integrators most price-sensitive compared to BIPV developers.
Supply Chain Analysis
Single-source vulnerability sits with specialized material suppliers for indium and tellurium. Geographic supply concentration for these critical raw materials is primarily in China and Latin America. Key dependencies include CIGS and CdTe thin-film precursors. Commodity price volatility presents a structural supply chain risk. Distribution runs through a hybrid model combining direct sales for BIPV and retail channels for portable products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flexible solar panel market is evolving into a late-cycle quality story. Demand is shifting toward premium, aesthetically integrated solutions for building-integrated photovoltaics.
For Market Incumbents:
Deepen R&D into perovskite thin-film technology to counter performance differentials against traditional silicon. Consolidate market share in specialized applications like aerospace by acquiring smaller innovators. The threat of lower-cost, scalable thin-film manufacturing from Asian players necessitates continuous material science investment. Strengthen channel control for high-value BIPV projects.
For New Entrants and Emerging Players:
E-commerce platforms offer a direct route to penetrate the portable chargers segment. Target underpenetrated outdoor recreation markets in North America with lightweight, foldable devices. Focus on bundling hardware with cloud-based performance monitoring software for recurring revenue. A direct-to-consumer model can build brand loyalty among tech-savvy users.
For Investors and Strategic Acquirers:
Clean energy infrastructure funds are the most active acquirers in this space. The long-term viability hinges on advancements in material science and recycling infrastructure over the next decade. Target vertically integrated specialists with strong intellectual property in CIGS or perovskite technologies. The signal to watch is the commercialization scale of next-generation perovskite cells.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Perovskite R&D | Accelerates performance gains and cost reduction for next-generation flexible solar applications. |
| Develop BIPV Installer Training Programs | Addresses the installation skill gap and reduces project bottlenecks for architectural applications. |
| Expand Recycling Infrastructure for Thin-Films | Mitigates long-term environmental and regulatory challenges for composite panel manufacturers. |
| Strategic Partnerships for Automotive Integration | Leverages flexible panel technology to extend electric vehicle range and power auxiliary systems. |
| Offer Bundled Hardware-Software Solutions | Creates recurring service revenue and enhances customer engagement through performance monitoring. |
Research Approach
Direct dialogue with material scientists, BIPV architects, RV manufacturers, and renewable energy policy advisors informed the primary research. This was validated against extensive secondary data from IEC standards, EPA regulations, and the US Inflation Reduction Act filings. Bottom-up data collection from segment-specific sources was triangulated with top-down market sizing for comprehensive insights.
A bottom-up approach aggregated segment-level data, validated by top-down market sizing across the analysis window. The model segmented the market by product type, application, end user, and deployment method. Compound Annual Growth Rates were derived from historical trends and projected technological advancements. Key inputs included thin-film efficiency improvements and building mandate compliance rates.
Material cost volatility, regulatory shifts, and technological breakthroughs are the dominant revision risks. Forecasts reflect assumptions regarding market dynamics and competitive landscape evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Kiosk Market
Solar Power Systems
Floating Solar Panels Market
Solar Power Systems
United States Solar Microinverter Market
Solar Power Systems
Solar Sunlight Control System Market
Solar Power Systems
Hairy Solar Panels Market
Solar Power Systems
Solar Laminator Market
Solar Power Systems
Solar PV Mounting Systems Market
Solar Power Systems
Solar Panels Frame Market
Solar Power Systems
Solar Panel Cleaning System Market
Solar Power Systems
Global Concentrating Solar Power Market
Solar Power Systems
Solar Encapsulation Market
Solar Power Systems
Solar Thermal Collector Market
Solar Power Systems
Global Photovoltaic Glass Market
Solar Power Systems
Solar Flower Market
Solar Power Systems
Solar Grid-Tied Systems Market
Solar Power Systems
Thailand Solar Energy Market