
 Solar Flower Market | 2026-2036
Solar Flower Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Flower Market Intelligence
The EU Green Deal is pivoting solar flower demand toward building-integrated photovoltaics across European residential zones. SmartFlower leverages dual-axis tracking technology to sustain yield advantages in suburban deployments. Kubo anchors greenhouse-sector applications through specialized agrivoltaic configurations. Canadian Solar competes on module cost efficiency while extending distribution networks into Mediterranean markets.
Solar flowers are photovoltaic systems with petal-shaped panels that open at dawn and track the sun's arc, typically achieving conversion efficiencies between 18% and 22% through automated mechanical orientation. Their primary purpose is maximizing energy yield per unit area in space-constrained residential and commercial settings. Adjustable solar flowers command premium positioning due to precision tracking mechanics, while fixed variants dominate volume through simpler installation protocols. Rooftop deployment captures the largest addressable base, though community-based models are gaining structural traction where shared metering regulations permit collective generation schemes.
EMA guidelines on medical-grade facility renewables, REACH compliance for polymer components, and EU AI Act provisions on automated tracking algorithms collectively shape product certification pathways and market access conditions. Germany's KBA building codes and France's ANSM energy-efficiency mandates for public infrastructure further tighten performance benchmarks. Stakeholders must monitor how evolving F-Gas Regulation amendments affect thermal management system specifications in high-efficiency designs.
Market Dynamics
The EU Green Deal's renewable energy directives are compressing payback periods for distributed photovoltaic systems, redirecting capital from conventional rooftop arrays toward tracking-enabled solar flower architectures in suburban residential zones.
Growth Catalysts
- Feed-in tariff structures:Germany, Spain, and Italy maintain favorable distributed generation tariffs that reward dual-axis tracking yield premiums over static installations.
- Agrivoltaic integration:Specialized greenhouse configurations anchor commercial demand in Mediterranean agricultural corridors where land-use efficiency commands priority.
- Building-integrated photovoltaic mandates:EU member states are embedding renewable generation requirements into residential construction codes, favoring aesthetic-integrated systems over conventional panels.
Market Restraints
- Polymer supply concentration:REACH-compliant polymer components for petal housings face concentrated sourcing from specialized European compounders, creating input bottlenecks.
- Mechanical complexity premium:Precision dual-axis tracking mechanics carry 40-60% capital cost premiums versus fixed-tilt alternatives, constraining mass-market penetration.
- Substitution pressure:Conventional high-efficiency bifacial panels with optimized tilt angles capture overlapping use cases at lower installed cost per watt-peak.
Strategic Opportunities
- Community generation schemes:Shared metering regulations in France and Belgium permit collective solar flower deployments across multi-unit residential developments.
- AI-driven predictive maintenance:Automated tracking algorithms are converging with IoT sensor networks to enable remote diagnostics and service interval optimization.
- Public infrastructure mandates:France's ANSM energy-efficiency requirements for medical-grade facilities create certified demand for reliable distributed generation.
Industry Challenges
- CE marking complexity:Mechanical tracking systems must satisfy machinery directives alongside photovoltaic module certification, extending approval timelines.
- Dual-axis calibration expertise:Installation crews require specialized training in astronomical alignment and seasonal recalibration protocols that standard solar installers lack.
- F-Gas thermal management:Evolving EU F-Gas Regulation amendments restrict refrigerant choices for high-efficiency inverter cooling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Flower Market |
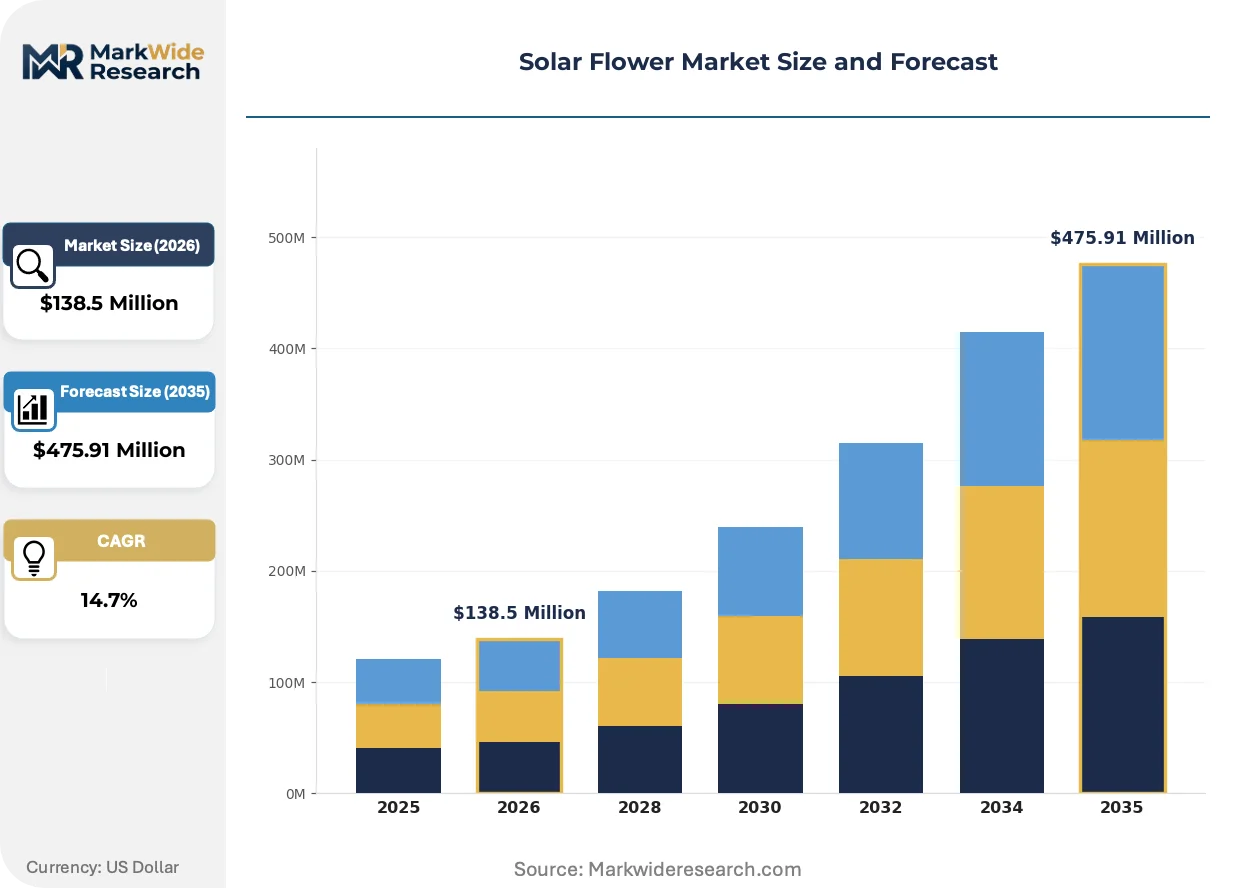
| Market Size in 2026 | $138.5 Million |
| Market Size in 2035 | $475.91 Million |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Solar Flowers, Adjustable Solar Flowers, Hybrid Solar Flowers, Portable Solar Flowers End User: Residential, Commercial, Agricultural, Industrial Deployment: Rooftop, Ground-mounted, Community-based, Off-grid Technology: Photovoltaic, Concentrated Solar Power, Thin Film, Bifacial |
| Companies Covered | Kubo, RBI, SmartFlower, Nexus Corporation, Luiten, Venlo, Palram, Canadian Solar, Atlas Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Flower Market Strategic Shifts & Innovations
Automated mechanical tracking is converging with building-integrated design languages, compressing the aesthetic-performance tradeoff that historically favored static panels in residential applications.
Perovskite-enhanced silicon architectures are converging with solar flower mechanical platforms, enabling lighter petal structures that reduce motor load and extend actuator service intervals. German and Austrian residential developers are specifying these hybrid cells for premium suburban installations. The structural consequence is a compression in the weight-yield ratio that previously constrained dual-axis scaling.
EU AI Act provisions on automated decision-making systems are reshaping certification pathways for tracking algorithms that adjust panel orientation without human intervention. Manufacturers must document algorithmic transparency and fail-safe protocols to maintain CE marking validity. Mediterranean markets with high solar irradiance show the fastest compliance adaptation due to concentrated vendor presence.
Homeowner associations and municipal planning boards are mandating aesthetic integration standards that favor sculptural photovoltaic forms over conventional rectangular arrays. Suburban districts in Bavaria and Lombardy are embedding these preferences into binding design guidelines. Channel partners are responding by bundling landscape architecture consultation with system sales.
Solar Flower Market Segmentation
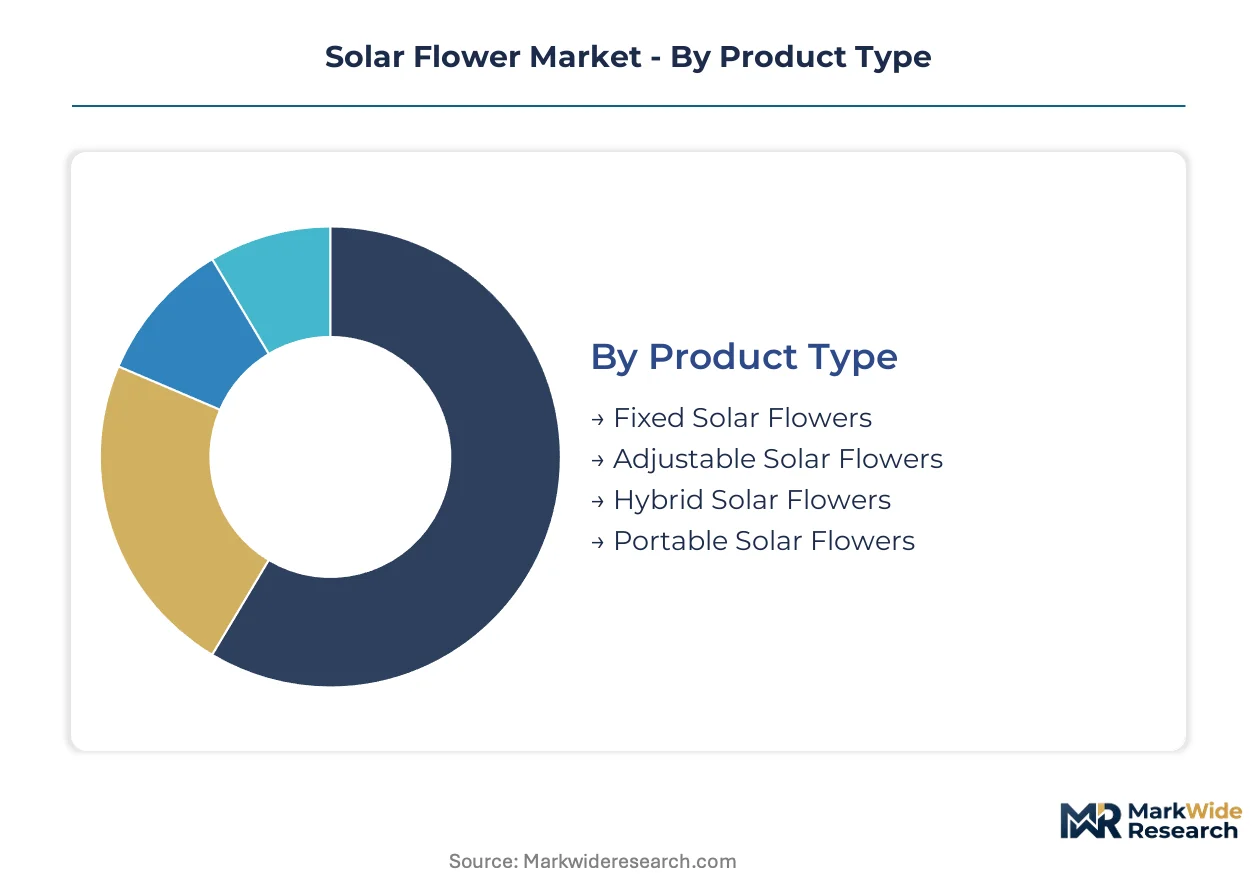
Solar flower architectures diverge sharply in certification burden, mechanical complexity, and addressable use case. Understanding these segment boundaries clarifies which product configurations align with specific regulatory pathways and customer procurement criteria.
Product Type:
CE marking requirements intensify with mechanical sophistication — fixed variants face streamlined photovoltaic module certification while adjustable and hybrid systems trigger additional machinery directive compliance.
- Fixed Solar Flowers:Static petal arrays eliminate dual-axis tracking mechanisms, reducing capital cost and maintenance exposure. Demand concentrates in German suburban residential zones where simplified installation protocols and lower upfront investment align with feed-in tariff payback calculations.
- Adjustable Solar Flowers:Precision dual-axis tracking mechanics achieve yield premiums through automated sun-tracking algorithms. Commercial deployments in Mediterranean agricultural corridors favor these systems where land-use efficiency and energy density justify 40-60% capital cost premiums over fixed alternatives.
- Hybrid Solar Flowers:Combines photovoltaic generation with thermal capture or storage integration. Specialized applications in medical-grade facilities requiring ANSM-compliant reliable distributed generation.
- Portable Solar Flowers:Compact, transportable units designed for temporary or mobile power needs. Emergency response and remote construction applications in off-grid scenarios.
Leading the category by volume: Fixed Solar Flowers. Growing fastest: Adjustable Solar Flowers.
End User:
Procurement authority and budget scale vary dramatically across customer types, shaping sales cycle length and specification complexity.
- Residential:Eco-conscious homeowners in Bavaria and Lombardy drive suburban rooftop demand, with municipal design guidelines increasingly mandating aesthetic-integrated systems over conventional panels.
- Commercial:Greenhouse operators and agricultural processors in Spain and Italy anchor specialized agrivoltaic configurations where dual-use land productivity commands procurement priority.
- Agricultural:Mediterranean corridor greenhouse-sector applications prioritize land-use efficiency through Kubo-style specialized configurations.
- Industrial:Manufacturing facilities with continuous baseload requirements and ESG compliance mandates.
Dominant by procurement volume: Residential. Steepest expansion trajectory: Agricultural.
Deployment:
Physical mounting configuration determines grid interconnection complexity, permitting requirements, and shared ownership eligibility.
- Rooftop:Space-constrained residential and commercial buildings in dense European urban centers. Building-integrated photovoltaic mandates in EU member states favor aesthetic-integrated rooftop architectures.
- Ground-mounted:Larger-scale installations on dedicated land parcels with optimized solar access. Agricultural and industrial end users in Spain and Italy.
- Community-based:Shared metering regulations in France and Belgium enable collective multi-unit residential deployments, bypassing individual rooftop constraints.
- Off-grid:Remote locations lacking grid infrastructure, requiring integrated storage and standalone power capability.
Highest installation base: Rooftop. Gaining structural traction: Community-based.
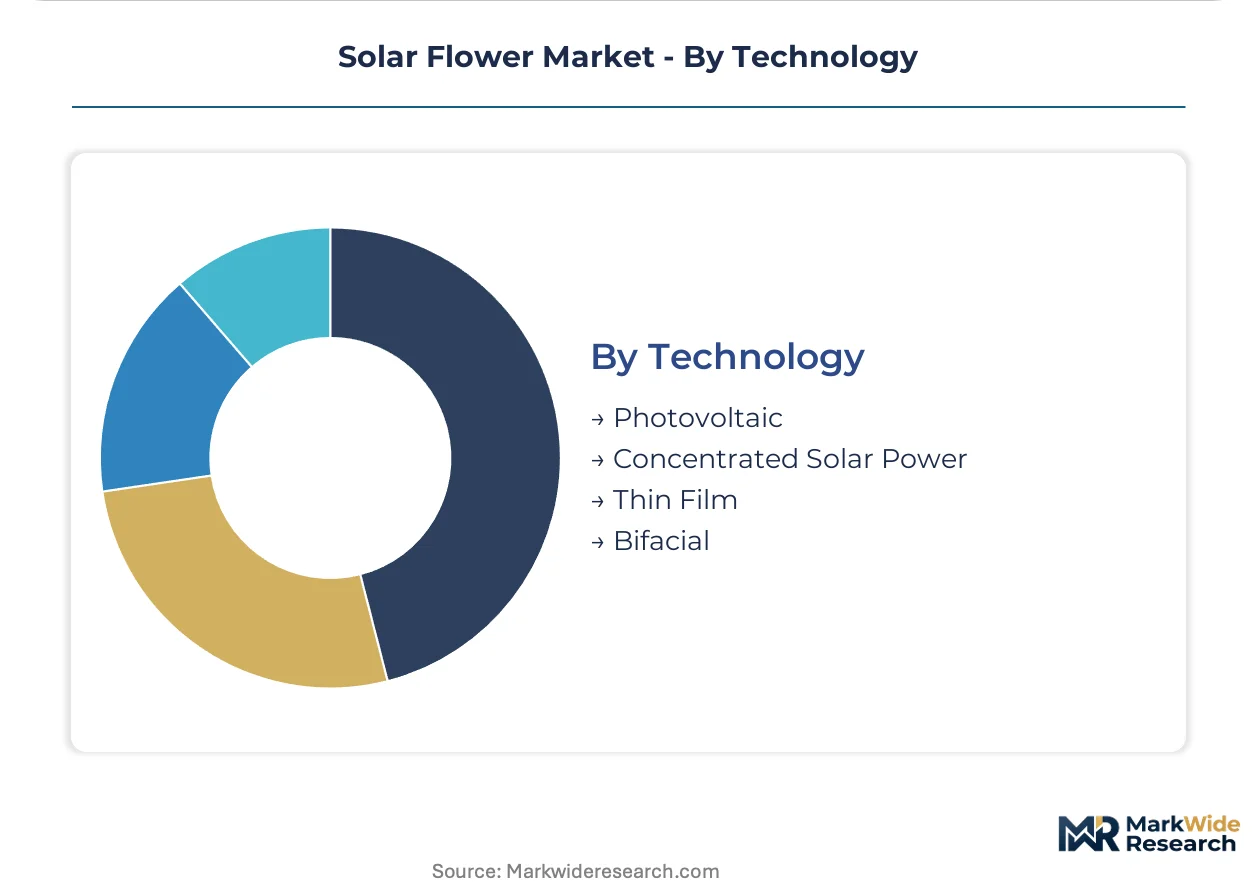
Technology:
Cell architecture selection trades conversion efficiency, weight-yield ratio, and supply chain maturity against specific application requirements.
- Photovoltaic:Crystalline silicon cells delivering 18-22% conversion efficiency through automated mechanical orientation. German and Austrian premium residential developers specify perovskite-enhanced variants for reduced petal weight.
- Concentrated Solar Power:Lens or mirror systems focusing sunlight onto small high-efficiency receivers. Specialized utility-scale and research applications with high direct normal irradiance requirements.
- Thin Film:Lightweight flexible substrates enabling unconventional form factors and reduced structural loading.
- Bifacial:Dual-sided cell architectures capturing reflected and diffuse light. Ground-mounted deployments with high albedo surfaces.
Technology maturity leader: Photovoltaic. Fastest technology transition: Bifacial integration with tracking platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European manufacturing concentrates precision mechanical components in German and Austrian industrial clusters while Mediterranean markets absorb the bulk of installed capacity. Spain and Italy drive ground-mounted deployment in agricultural corridors. Distributed generation policy variations across member states create divergent go-to-market pathways for tracking-enabled systems.
Germany
Residential rooftop demand concentrates in Bavarian and Baden-Württemberg suburban districts where municipal design guidelines mandate aesthetic-integrated photovoltaic forms. KBA building codes tighten structural performance benchmarks for mechanical tracking systems. Stuttgart-based engineering clusters supply precision actuator components to domestic and export markets.
Spain
Greenhouse operators in Almería and Murcia anchor specialized agrivoltaic configurations where land-use efficiency commands procurement priority. National renewable energy plans embed distributed generation targets that favor dual-axis tracking yield premiums. Valencia serves as the primary distribution hub for Mediterranean agricultural corridor deployments.
Italy
Feed-in tariff structures in Lombardy and Veneto reward high-yield tracking systems over static installations in residential zones. ANSM energy-efficiency mandates for medical-grade facilities create certified demand for reliable distributed generation. Milan industrial districts manufacture polymer petal housings under REACH compliance protocols.
France
Shared metering regulations enable collective solar flower deployments across multi-unit residential developments in Île-de-France and Auvergne-Rhône-Alpes. ANSM certification requirements for public infrastructure tighten performance benchmarks. Lyon-based automation specialists supply astronomical alignment calibration services to installation crews.
Belgium
Community generation schemes in Flanders and Wallonia bypass individual rooftop constraints through collective ownership structures. CNIL data governance provisions affect IoT sensor networks in automated tracking systems. Brussels serves as the regulatory compliance coordination center for Benelux market access.
Solar Flower Market Key Industry Players
The competitive structure tilts toward specialized mechanical engineering firms with photovoltaic integration capabilities rather than pure-play solar module manufacturers. Market concentration remains moderate with distinct tiering between premium tracking specialists and cost-optimized fixed-array providers. Two strategic archetypes dominate: precision automation engineers leveraging dual-axis expertise and agricultural greenhouse specialists repurposing structural systems. Dominant competitive moves include technology licensing partnerships for tracking algorithms and geographic expansion through certified installer network development.
Among European precision automation specialists, SmartFlower and Kubo occupy distinct positioning archetypes. SmartFlower represents the dual-axis tracking premium tier with mechanical orientation systems designed for suburban residential aesthetics. Kubo anchors the agricultural application vector through greenhouse-sector structural expertise. Canadian Solar sits within the cost-efficiency tier, leveraging module manufacturing scale to extend distribution reach into Mediterranean price-sensitive segments. These three exemplify how mechanical sophistication, sector specialization, and manufacturing scale create non-overlapping competitive territory.
| Leading Market Players |
|---|
| Kubo |
| RBI |
| SmartFlower |
| Nexus Corporation |
| Luiten |
| Venlo |
| Palram |
| Canadian Solar |
| Atlas Manufacturing |
| Others |
Cost & Logistics Intelligence
Perovskite-enhanced silicon cell adoption is simultaneously reducing petal weight thresholds and concentrating premium component sourcing among German and Austrian engineering clusters, compressing cost economics for dual-axis systems while tightening supply control among precision automation specialists.
Pricing Analysis
Margin tightening in adjustable solar flower tiers reflects REACH-compliant polymer premiums and specialized actuator costs. Three-tier pricing structure across premium tracking, standard fixed, and economy fixed-array levels separates dual-axis yield advantages from installation simplicity. Price differentiation traces to CE marking complexity and astronomical calibration service bundling. Residential buyers in Germany exhibit highest price sensitivity, while Mediterranean greenhouse operators absorb premiums for land-use efficiency.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Valencia, and Milan anchor hub-and-spoke patterns for precision mechanical components. Supply concentrates in Germany for actuators, Italy for polymer housings, and Austria for tracking algorithms. Raw material dependencies include REACH-certified polymer compounds, rare-earth magnet assemblies, and perovskite precursor chemicals. Single-source vulnerability concentrates in specialized European compounders for petal housing materials. Distribution runs through certified installer networks with astronomical alignment training requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar flower market is consolidating around mechanical engineering capabilities, with CE marking complexity and dual-axis calibration expertise forcing out pure-play photovoltaic assemblers lacking precision automation heritage.
For Market Incumbents: Cement position through backward integration into polymer compounding capabilities and captive supply of REACH-certified housing materials. Invest in AI-driven predictive maintenance platforms to offset substitution pressure from bifacial panel alternatives. Control certified installer networks in Bavaria and Lombardy to lock out module-cost competitors. For New Entrants and Emerging Players: Launch via community generation scheme partnerships in France and Belgium where shared metering regulations bypass individual rooftop constraints. Target agricultural greenhouse configurations in Spain's Almería corridor where Kubo-style specialization leaves price-sensitive volume unattended. Pursue white-label manufacturing for cost-optimized fixed-array variants. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to agricultural greenhouse engineering firms seeking photovoltaic integration capabilities. Five-to-ten-year viability favors precision automation specialists with dual-axis algorithm portfolios over fixed-array assemblers. Watch F-Gas Regulation amendment timing as inflection signal for thermal management system redesign cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Partnership | SmartFlower-style tracking algorithms extend reach to agricultural greenhouse specialists lacking precision automation heritage. |
| Certified Installer Network Expansion | Astronomical alignment training programs in Lyon and Stuttgart tighten channel control against module-cost competitors. |
| Perovskite Cell Integration | Hybrid silicon-perovskite architectures reduce petal weight and extend actuator service intervals in premium residential tiers. |
| Agrivoltaic Configuration Specialization | Kubo-style greenhouse-sector expertise captures Mediterranean land-use efficiency premiums unavailable to rooftop-focused competitors. |
| AI-Driven Predictive Maintenance Platform | EU AI Act-compliant algorithmic transparency documentation maintains CE marking validity for automated tracking systems. |
Research Approach
Multi-period observation of feed-in tariff adjustments, CE marking timeline extensions, and polymer supply bottlenecks anchored the trend analysis, supplemented by interviews with precision automation engineering directors, agricultural greenhouse operators, certified solar installation crews, REACH compliance officers, and municipal planning board officials. Secondary validation drew from EU Green Deal directive filings, ECHA REACH registration databases, KBA building code amendments, and ANSM energy-efficiency mandate documentation. Bottom-up project pipeline tracking triangulated against top-down regulatory impact modeling.
Segment-weighting across product type, end user, deployment configuration, and technology architecture informed the analytical framework throughout the forecast period. CAGRs derived from installation volume trajectories, yield premium capture rates, and capital cost evolution curves. Industry-specific inputs included dual-axis tracking adoption curves in Mediterranean agricultural corridors and perovskite cell penetration timelines in German premium residential developments.
Regulatory amendment timing, polymer supply concentration disruptions, and bifacial panel substitution acceleration are the dominant revision risks for projection validity. Forecasts reflect documented assumptions regarding CE marking pathway stability and feed-in tariff structure continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Box Solar Cookers Market
Solar Power Systems
Solar EVA Market
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Skylights Market
Solar Power Systems
Global Solar Panel Materials Market
Solar Power Systems
Floating Solar Panels Market
Solar Power Systems
Portable Solar Charger Market
Solar Power Systems
Solar Panel Lights Market
Solar Power Systems
Solar Module Market
Solar Power Systems
Floating Solar System Market
Solar Power Systems
Chile Solar Photovoltaic (PV) Market
Solar Power Systems
Distributed Solar Power Generation System Market
Solar Power Systems
Solar Photovoltaics Wafer Market
Solar Power Systems
Solar Updraft Tower Market
Solar Power Systems
Solar Microgrid Market
Solar Power Systems
Thin Film Solar PV Market
Solar Power Systems
Japan Solar Energy Market