
 Solar Laminator Market | 2026-2036
Solar Laminator Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Laminator Market Insights
Preventive maintenance contracts and software-defined thermal profiling is consolidating vendor relationships around uptime guarantees rather than equipment transactions. Ecoprogetti leverages Italian engineering heritage to dominate European BIPV laminator niches. Shenzhen Jingsheng anchors Asia-Pacific supply through aggressive manufacturing scale and captive component sourcing. NPC Incorporated differentiates via precision control systems for thin-film applications.
A solar laminator thermally bonds encapsulant films, back sheets, and cover glass to photovoltaic cells under vacuum and controlled pressure, typically operating at 140-160°C with ±2°C uniformity across the platen. Flat laminators command the largest installed base due to crystalline silicon module standardization, while hybrid laminators represent the fastest-growing product category as manufacturers seek flexible formats for heterojunction and TOPCon cell architectures. Ethylene vinyl acetate remains the dominant encapsulant material, though thermoplastic polyurethane adoption accelerates in bifacial and floating solar segments demanding extended moisture resistance.
The EU Green Deal and F-Gas Regulation constrain fluorinated polymer use in encapsulants, pushing reformulation toward polyolefin alternatives. China's MIIT enforces GB standards for module reliability testing that directly specify laminator thermal cycle performance. India's BIS certification mandates IEC 61215 compliance, which requires validated lamination protocols for module qualification. Stakeholders must monitor how evolving national content requirements reshape equipment localization strategies and aftermarket service economics.
Market Dynamics
Utility-scale solar farm developers are consolidating procurement around uptime-guaranteed service contracts rather than discrete equipment purchases, compressing vendor margins while locking in long-term aftermarket revenue streams for laminator manufacturers.
Growth Catalysts
- EU Green Deal module durability mandates:Tightened reliability requirements under the EU Green Deal are forcing module manufacturers to upgrade lamination equipment, directly expanding replacement demand for precision thermal control systems.
- Heterojunction cell architecture proliferation:Advanced cell technologies requiring lower-temperature lamination cycles are pulling hybrid laminator adoption across tier-one module assembly lines.
- China's integrated PV manufacturing ecosystem:Government-backed capacity expansions and captive component supply chains concentrate laminator demand in domestic production clusters.
Market Restraints
- Ethylene vinyl acetate price volatility:Petrochemical feedstock fluctuations for encapsulant materials compress module assembler margins and delay laminator capital expenditure cycles.
- Fluorinated polymer regulatory phase-out:The EU F-Gas Regulation constrains traditional encapsulant formulations, forcing costly reformulation R&D before equipment qualification.
- High-precision thermal control capex thresholds:±2°C uniformity specifications for next-generation cells require platen heating system investments that exclude mid-scale entrants.
Strategic Opportunities
- Floating solar moisture resistance requirements:Bifacial and floating installations are accelerating thermoplastic polyurethane encapsulant adoption, opening specialized laminator configurations for extended durability protocols.
- India BIS certification compliance services:IEC 61215 validation requirements create aftermarket revenue streams for protocol consulting and equipment recalibration.
- Building-integrated photovoltaics thermal profiling:Architectural module formats demand non-standard lamination cycles, fragmenting demand toward flexible-format hybrid systems.
Industry Challenges
- Vacuum system engineering talent scarcity:Specialized mechatronics expertise for large-format vacuum chamber design concentrates among legacy European and Japanese equipment houses.
- GB standard thermal cycle validation timelines:China's MIIT reliability testing protocols extend equipment qualification periods, delaying revenue recognition for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Laminator Market |
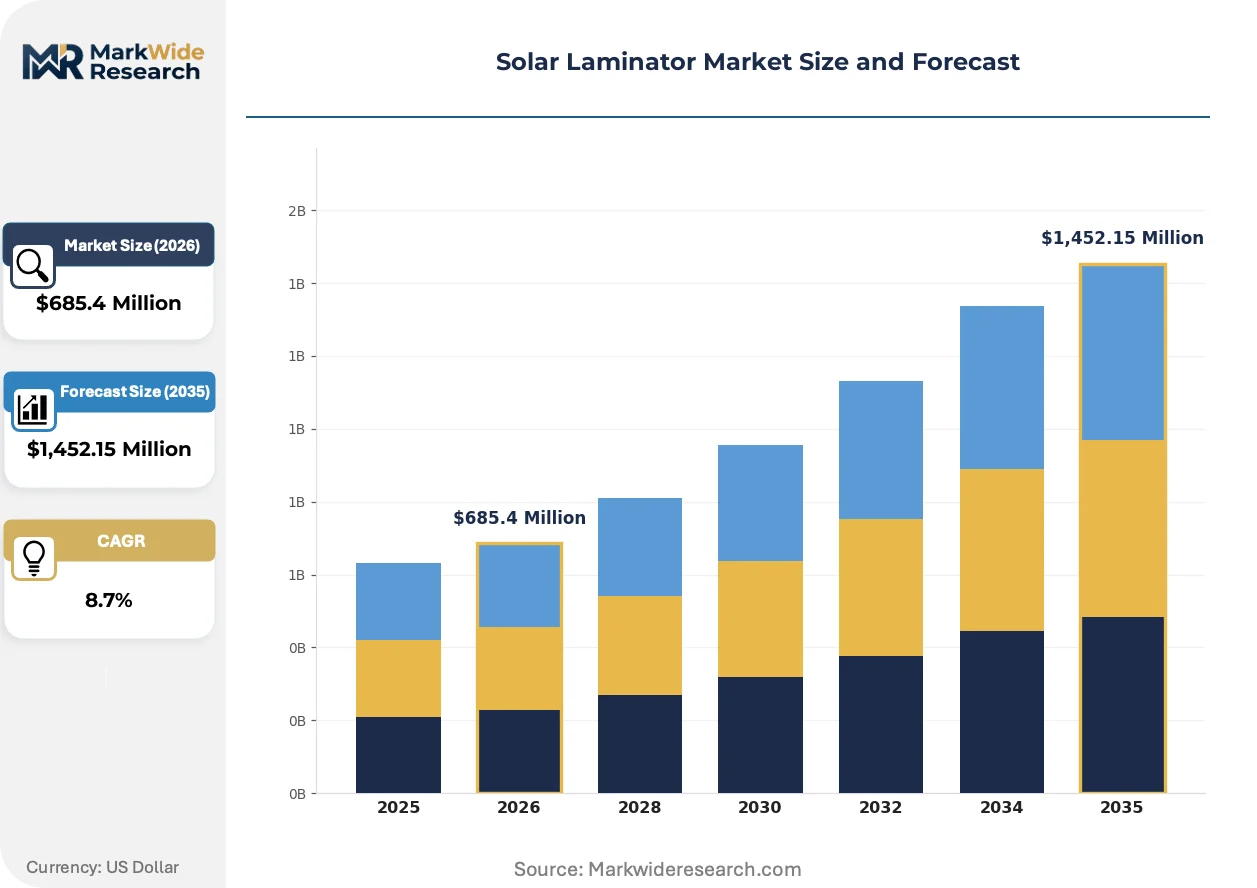
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Laminators, Roll Laminators, Hybrid Laminators, Laser Laminators Technology: Photovoltaic, Thin-Film, BIPV, Multi-Junction End User: Manufacturers, Installers, Research Institutions, OEMs Material: Ethylene Vinyl Acetate, Polycarbonate, Glass, TPU |
| Companies Covered | MC Machinery Systems, EXPO Solar, Ecoprogetti, Shenzhen Jingsheng, Hengshui Runyang Machinery Equipment, Bürkle, STR Automations, Landgent, NPC Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Laminator Market Trends and Innovations
Thermoplastic encapsulant materials and software-defined thermal profiling are fragmenting traditional equipment categories while compressing the vendor-customer relationship toward continuous service engagement rather than transactional sale.
Non-ethylene vinyl acetate encapsulant chemistries are decentralizing module manufacturing location decisions by reducing temperature sensitivity and enabling distributed assembly near end-use sites. Floating solar developers in Southeast Asia and agricultural PV integrators in Southern Europe are adopting these materials fastest. This decentralization is compressing logistics costs while complicating centralized laminator vendor service coverage models.
The EU F-Gas Regulation is accelerating polyolefin encapsulant reformulation across European module supply chains. Industrial consequence includes invalidated legacy lamination protocols and forced equipment recalibration investments. Bifacial module lines in Germany and the Netherlands are responding with parallel validation tracks for fluorine-free alternatives.
Preventive maintenance contract structures are displacing traditional equipment sale-and-install models among utility-scale developers. Long-term thermal performance guarantees now anchor vendor selection criteria. This shift concentrates most visibly in Chinese state-owned solar farm operators and European independent power producers managing multi-gigawatt module fleets.
Solar Laminator Market Segmentation
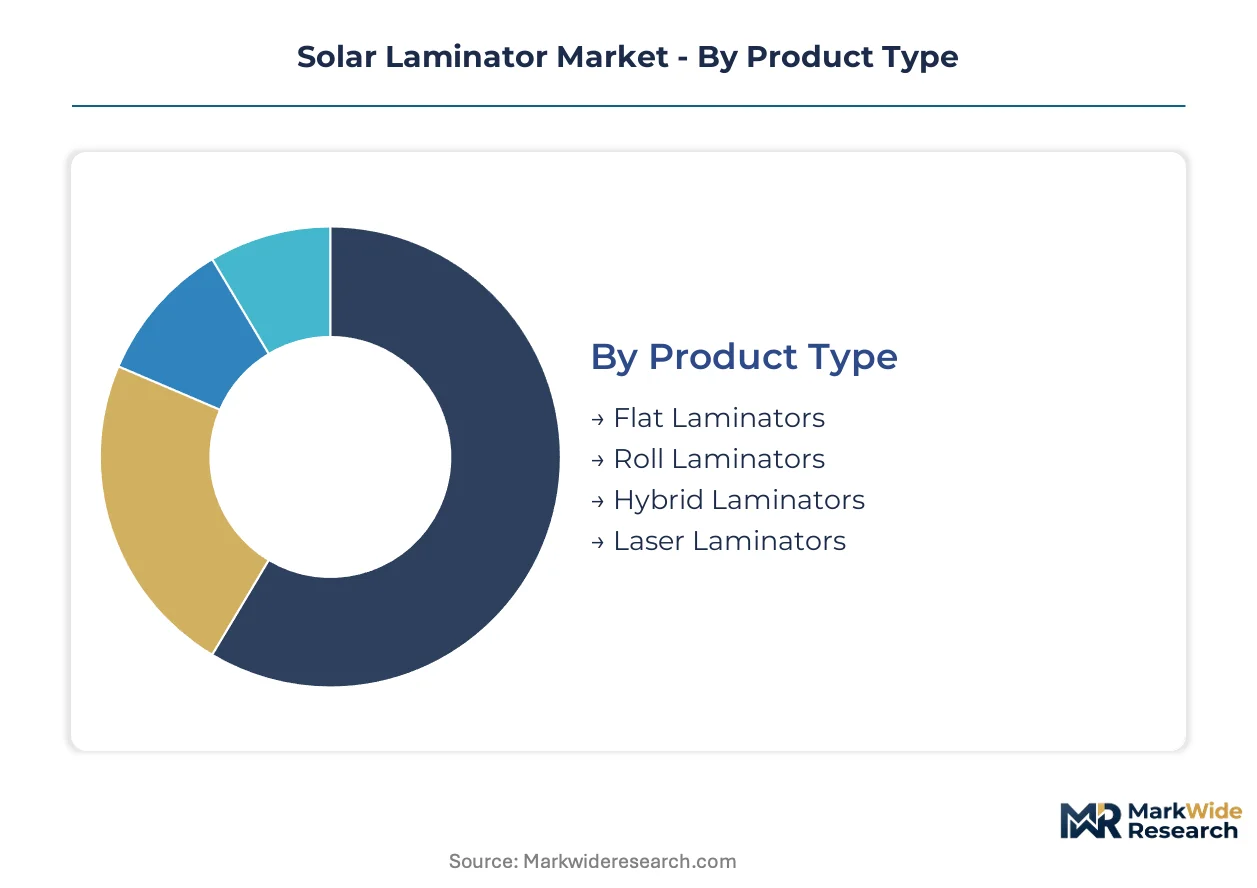
Solar laminator segmentation reveals how equipment specifications diverge across cell architectures and encapsulant chemistries. Procurement patterns cluster around thermal uniformity requirements and format flexibility rather than throughput alone.
Product Type:
Flat laminators dominate installed base volumes while hybrid systems command premium positioning for advanced cell formats.
- Flat Laminators:Standard platen-based systems bond crystalline silicon modules at 140-160°C with ±2°C uniformity across the heating surface. Chinese module assembly clusters in Jiangsu and Anhui provinces absorb the majority of new flat laminator shipments as domestic capacity expands.
- Hybrid Laminators:Configurable pressure and temperature zones accommodate heterojunction and TOPCon cells requiring lower-temperature lamination cycles. German and Dutch bifacial module lines are retrofitting hybrid systems fastest to qualify fluorine-free encapsulant protocols under EU F-Gas Regulation constraints.
- Roll Laminators:Continuous-feed systems process flexible thin-film substrates for building-integrated applications.
- Laser Laminators:Emerging thermal bonding technology eliminates mechanical pressure for fragile perovskite tandem architectures.
Today's leader: Flat Laminators. Tomorrow's challenger: Hybrid Laminators.
Technology:
Application-specific thermal profiles separate commodity module production from architectural and research-grade systems.
- Photovoltaic:Conventional crystalline silicon lamination commands the largest equipment footprint, with utility-scale developers in China and India standardizing on 2.5m x 1.5m platen formats. MIIT GB reliability testing mandates directly specify thermal cycle performance for this segment.
- BIPV:Building-integrated formats require non-standard glass-glass lamination with aesthetic tolerances for visible edges. Italian and Spanish architectural module specialists are driving demand for customized thermal profiling in this category.
- Thin-Film:Cadmium telluride and CIGS processing requires precise temperature ramp control to prevent delamination.
- Multi-Junction:Space-grade and concentrated photovoltaic applications demand vacuum integrity below 1 mbar for III-V semiconductor bonding.
Photovoltaic systems anchor current procurement volumes. BIPV configurations are climbing the fastest as European Green Deal building mandates tighten.
End User:
Customer type determines contract structure, with manufacturers favoring capital purchases and installers migrating toward service-based engagements.
- Manufacturers:Tier-one module producers in China, Vietnam, and Thailand purchase equipment directly with captive maintenance capabilities. These buyers specify platen uniformity tolerances and vacuum pump redundancy in procurement tenders.
- Installers:Distributed solar integrators in Germany and Australia are adopting preventive maintenance contracts with uptime guarantees rather than equipment ownership. This shift compresses upfront vendor margins while locking in 10-year service revenue streams.
- Research Institutions:National laboratories and university programs require programmable thermal profiles for next-cell architecture validation.
- OEMs:Equipment-integrated module producers source laminators as subsystems for turnkey production line exports.
Manufacturers retain the dominant buyer position. Installers represent the steepest expansion trajectory as asset-light service models penetrate distributed solar markets.
Material:
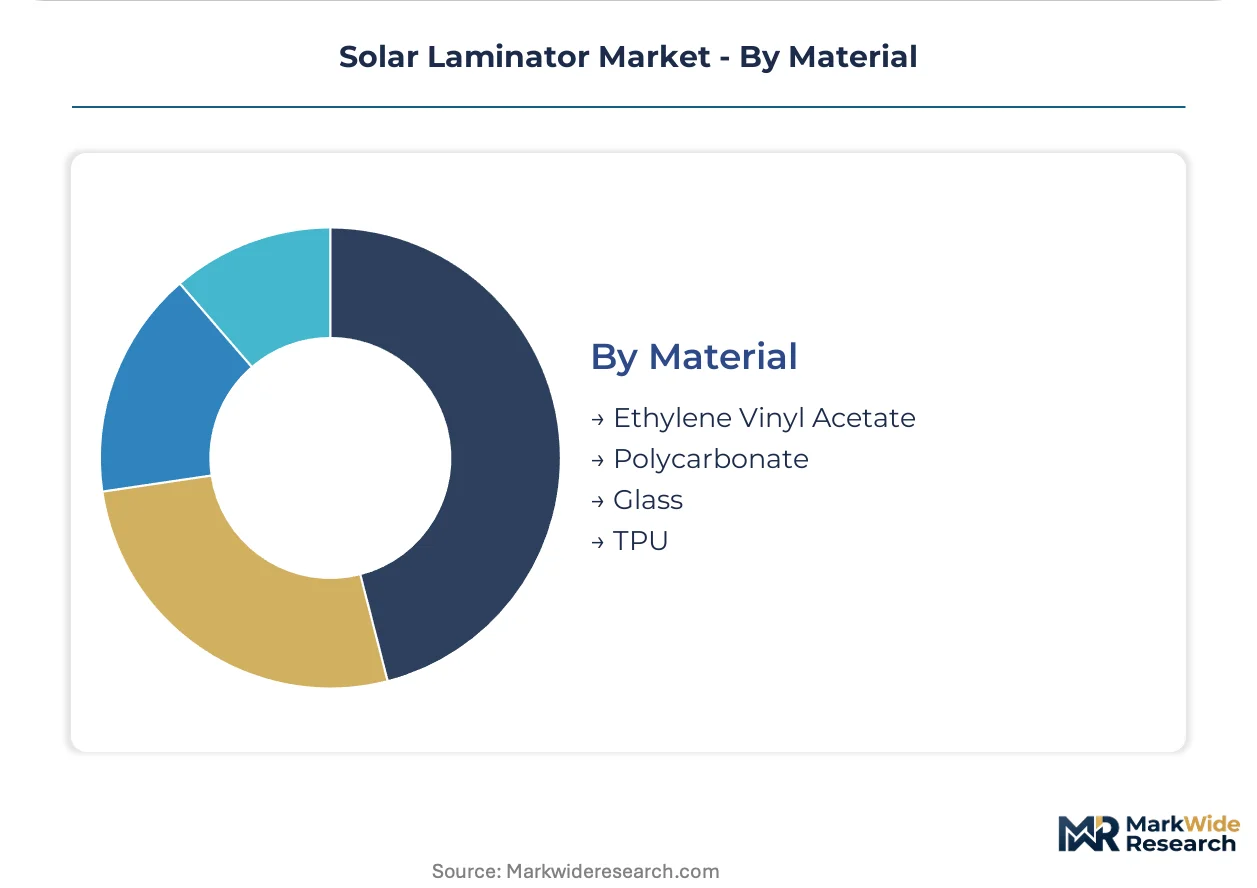
Encapsulant chemistry dictates lamination temperature windows and equipment calibration requirements.
- Ethylene Vinyl Acetate:The incumbent encapsulant requires 150°C lamination temperatures with cross-linking initiator activation. Petrochemical feedstock volatility for EVA resins is compressing module assembler margins and delaying laminator capital cycles in Southeast Asian production hubs.
- TPU:Thermoplastic polyurethane enables lower-temperature processing at 120-130°C with superior moisture resistance for floating solar installations. Developers in Vietnam and the Netherlands are validating TPU protocols for aquatic and agricultural PV applications.
- Polycarbonate:Structural encapsulant alternatives for lightweight modules in rooftop weight-constrained environments.
- Glass:Direct glass-glass lamination for bifacial and frameless architectural modules eliminates backsheet materials entirely.
Ethylene Vinyl Acetate holds current formulation dominance. TPU is gaining share fastest as moisture resistance specifications tighten for non-terrestrial installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates laminator procurement through state-directed capacity expansions while Germany drives equipment upgrading cycles through regulatory durability mandates. India and Vietnam are emerging as volume assembly hubs with distinct certification requirements. The Netherlands and Japan represent specialized demand pockets for advanced cell architectures.
China
MIIT GB reliability standards mandate thermal cycle performance validation that extends equipment qualification timelines. Jiangsu and Anhui province clusters absorb the majority of flat laminator shipments as domestic module capacity scales. State-owned solar farm operators are consolidating procurement around preventive maintenance contracts with decade-long uptime guarantees.
Germany
Bifacial module lines in Saxony and Bavaria are retrofitting hybrid systems fastest to qualify fluorine-free encapsulants under EU F-Gas Regulation constraints. The EU Green Deal tightens module durability requirements that force lamination equipment upgrades across tier-one assemblers. EPCs managing multi-gigawatt fleets now anchor vendor selection on long-term thermal performance guarantees rather than capital cost.
India
BIS certification mandates IEC 61215 compliance that requires validated lamination protocols for module qualification. Gujarat and Tamil Nadu production hubs are standardizing on 2.5m x 1.5m platen formats for utility-scale export contracts. Domestic content requirements under the PLI scheme are reshaping equipment localization strategies for multinational laminator suppliers.
Vietnam
Floating solar developers in the Mekong Delta are validating thermoplastic polyurethane encapsulant protocols for aquatic installations demanding extended moisture resistance. Module assemblers here face ethylene vinyl acetate price volatility that compresses margins and delays capital expenditure cycles. Northern industrial zones around Hai Phong are absorbing second-hand laminator transfers from Chinese capacity upgrades.
Netherlands
Agricultural PV integrators in Gelderland and North Brabant are adopting lower-temperature encapsulant materials that enable distributed assembly near end-use sites. EU F-Gas Regulation compliance is invalidating legacy lamination protocols and forcing equipment recalibration investments. Architectural module specialists here drive demand for customized thermal profiling in building-integrated formats.
Solar Laminator Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with European engineering houses commanding premium positioning in architectural and thin-film niches while Chinese fabricators capture volume through integrated supply chains. The vendor base stratifies across three archetypes: precision thermal control specialists, scale-driven mass producers, and regional system integrators. M&A activity concentrates on captive component sourcing capabilities, while technology licensing agreements proliferate for heterojunction-compatible lamination cycles.
Among Italy-based precision specialists, Ecoprogetti exemplifies the European engineering heritage archetype in building-integrated photovoltaic laminator niches. Shenzhen Jingsheng and NPC Incorporated occupy positions at opposite ends of the specialization spectrum—one representing scale-driven Asia-Pacific supply anchoring through aggressive manufacturing footprint, the other exemplifying precision control system differentiation for thin-film and advanced cell architectures. These three collectively illustrate how geographic concentration, thermal uniformity capabilities, and format flexibility define competitive positioning in this equipment category.
| Leading Market Players |
|---|
| MC Machinery Systems |
| EXPO Solar |
| Ecoprogetti |
| Shenzhen Jingsheng |
| Hengshui Runyang Machinery Equipment |
| Bürkle |
| STR Automations |
| Landgent |
| NPC Incorporated |
| Others |
Pricing and Supply Chain Analysis
Ethylene vinyl acetate resin costs cascade from petrochemical feedstock volatility through module assembler margins into laminator procurement cycles, with Chinese state-owned solar farm operators and European independent power producers anchoring opposite ends of the pricing spectrum through divergent contract structures.
Pricing Analysis
Capacity additions in Jiangsu and Anhui provinces are reshaping price floors for flat laminators as domestic Chinese fabricators compete on scale. Three-tier pricing structure across premium, standard, and economy levels separates European precision engineering houses with ±2°C uniformity guarantees from mass-market Asian suppliers. Pricing pressure stems from EVA price volatility compressing module assembler capital budgets. Utility-scale developers in China exhibit lowest price sensitivity due to state-backed financing, while distributed solar integrators in Germany and Australia prioritize uptime-guaranteed service contracts over capital cost.
Supply Chain Analysis
Single-source vulnerability sits with vacuum pump and precision heating element suppliers concentrated in Germany and Japan. Platen manufacturing draws from Chinese steel processing, Italian engineering design houses, and Japanese control system specialists. Tariff exposure runs through encapsulant resin imports subject to EU F-Gas Regulation constraints. Distribution runs through direct OEM relationships for tier-one module producers and regional system integrators for mid-scale retrofit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through preventive maintenance contract structures that transform equipment transactions into decade-long service revenue streams, particularly as thermal performance guarantees displace capital cost in vendor selection criteria.
For Market Incumbents: Lock in long-term thermal performance guarantees with Chinese state-owned solar farm operators and European independent power producers managing multi-gigawatt fleets. Deepen upstream control over vacuum pump and heating element supply chains to defend against precision engineering talent scarcity. Invest in software-defined thermal profiling capabilities to anchor continuous service engagement models.
For New Entrants and Emerging Players: Distributed solar integrators in Germany and Australia represent the most penetrable buyer archetype as asset-light service models displace equipment ownership. Agricultural PV integrators in the Netherlands and floating solar developers in Vietnam offer white-space expansion for lower-temperature encapsulant protocols. Pursue protocol consulting and equipment recalibration services around India BIS certification compliance as the primary go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where captive component sourcing capabilities determine competitive positioning in precision thermal control segments. Target European engineering houses with heterojunction-compatible lamination cycle expertise and established relationships with architectural module specialists. Watch for inflection where GB standard thermal cycle validation timelines accelerate revenue recognition for qualified equipment introductions.
| Strategic Initiative | Industry Significance |
|---|---|
| Preventive Maintenance Contract Expansion | Transforms transactional equipment sales into decade-long recurring revenue with Chinese state-owned operators. |
| Backward Integration into Vacuum System Components | Secures supply of precision heating elements and vacuum pumps concentrated among German and Japanese suppliers. |
| Software-Defined Thermal Profiling Development | Enables real-time lamination cycle optimization for heterojunction and TOPCon cell architectures. |
| EU F-Gas Regulation Compliance Services | Captures equipment recalibration demand as fluorine-free encapsulant protocols invalidate legacy processes. |
| India BIS Certification Consulting | Opens aftermarket revenue streams through IEC 61215 validation requirements for module qualification. |
Research Methodology
Multiple input streams — primary interviews with module production engineers, EPC procurement directors, and aftermarket service heads; secondary validation through MIIT GB standard filings, EU F-Gas Regulation compliance databases, and customs trade data for laminator equipment flows — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations spanned tier-one module producers in China, Vietnam, and Thailand; utility-scale developers in Germany and India; and precision equipment specialists in Italy and Japan. Secondary sources included SEC filings from publicly traded module manufacturers, IEA renewable energy deployment statistics, and national certification body protocol documentation.
Data-stream reconciliation across the projection horizon applied analytical frameworks segmented by laminator product type, encapsulant material chemistry, end-user contract structure, and regional regulatory cluster. CAGRs were derived from equipment shipment trajectories, capacity expansion announcements, and replacement cycle modeling. Industry-specific forecast inputs incorporated heterojunction cell architecture adoption curves and thermoplastic polyurethane encapsulant validation timelines for floating solar applications.
Underlying measurement precision varies by segment; flat laminator volumes in Chinese production clusters carry tighter precision than emerging hybrid system adoption in European bifacial module lines. Forecasts reflect assumptions around MIIT GB reliability testing protocol stability, EU Green Deal durability mandate enforcement intensity, and petrochemical feedstock price normalization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Residential Solar Energy Market
Solar Power Systems
Solar Microinverter and Power Optimizer Market
Solar Power Systems
Bifacial Solar Panels Market
Solar Power Systems
US Solar Tracker Market
Solar Power Systems
Slovakia Renewable Energy Market
Solar Power Systems
Biohybrid Solar Cell Market
Solar Power Systems
Solar Roof Tiles Market
Solar Power Systems
Perovskite Solar Module Market
Solar Power Systems
Thin Film Solar PV Market
Solar Power Systems
GCC Solar Microinverter Market
Solar Power Systems
Europe Concentrated Solar Power Market
Solar Power Systems
Solar Power Market
Solar Power Systems
High-Efficiency Solar Modules Market
Solar Power Systems
Asia-Pacific Rooftop Solar Market
Solar Power Systems
Solar Kiosk Market
Solar Power Systems
Ecuador Solar Energy Market