
 Solar PV Mounting Systems Market | 2026-2036
Solar PV Mounting Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Solar PV Mounting Systems Market Analysis
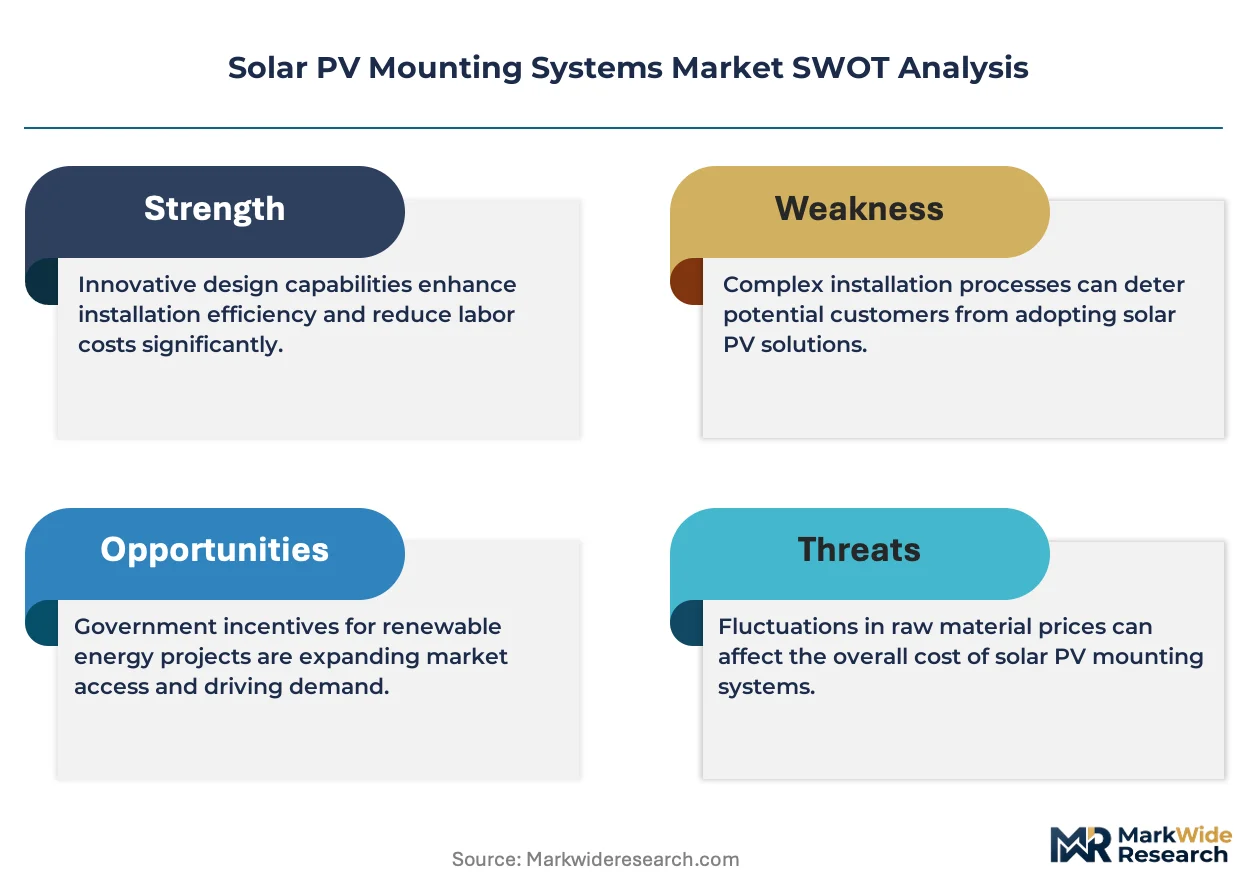
The EU Green Deal is shifting the cost-of-entry calculus for mounting system suppliers seeking European project pipelines. Nextracker Inc. leverages its horizontal single-axis tracker portfolio to dominate utility-scale bids across North American deserts. Array Technologies Inc. sustains manufacturing scale through domestic steel sourcing that qualifies for IRA domestic content adders. GameChange Solar anchors its position with factory-direct structural systems that compress balance-of-system timelines for independent power producers.
Solar PV mounting systems are structural assemblies that secure photovoltaic panels to rooftops, terrain, or floating platforms at specified tilt angles, typically fabricated from extruded aluminum alloys, galvanized steel, or fiber-reinforced composites and engineered to withstand wind loads and seismic forces while enabling thermal expansion. Their primary purpose is to optimize irradiance capture, ensure mechanical integrity across decades of environmental exposure, and reduce installation labor through modular pre-assembly. Ground-mount systems occupy the largest revenue pool given their steel intensity and prevalence in utility-scale procurement, while floating installations represent the fastest-growing niche as reservoir and coastal projects multiply in Japan and Southeast Asia. Aluminum roof-mount portfolios differentiate through lightweight corrosion resistance that expands addressable building stock in aging commercial real estate.
The IRA's domestic content requirements and the EU Green Deal's carbon border adjustments are reshaping supplier geography and material certification demands across the Atlantic basin. China's MIIT enforces GB standards for structural steel and aluminum extrusions that govern export qualification for mounting system OEMs serving Belt and Road solar installations. India's BIS certification for steel products and the PLI scheme for solar module manufacturing are cascading into mounting system localization mandates. Stakeholders must monitor evolving domestic content thresholds and carbon intensity benchmarks to preserve project eligibility and margin structures.
Market Dynamics
Utility-scale solar procurement is compressing balance-of-system timelines, forcing mounting system suppliers to pre-assemble modules and integrate steel fabrication with tracker electronics before site delivery.
Growth Catalysts
- IRA Domestic Content Adders:The Inflation Reduction Act's bonus credits for US-manufactured steel and aluminum are redirecting procurement toward domestic extrusion and galvanization facilities.
- Utility-Scale Procurement Volume:Independent power producers in Texas, California, and Arizona are bundling tracker systems into multi-gigawatt supply agreements that favor factory-direct structural solutions.
- Floating PV Expansion:Reservoir and coastal installations across Japan and Southeast Asia are creating specialized demand for corrosion-resistant mooring assemblies and polymer-composite float structures.
Market Restraints
- Steel Price Volatility:Hot-rolled coil fluctuations tied to scrap metal markets and energy-intensive electric arc furnace operations compress margin visibility for ground-mount fabricators.
- Aluminum Supply Concentration:Primary smelting capacity clusters in China's Yunnan and Xinjiang provinces, exposing extrusion-dependent roof-mount suppliers to export quota disruptions.
- Seismic Load Certification:California's Title 24 and Japan's Building Standard Law impose divergent structural testing protocols that fragment R&D resource allocation.
Strategic Opportunities
- Agrivoltaics Integration:Dual-use solar installations over agricultural land in France and Italy are creating demand for elevated fixed-tilt structures that accommodate mechanized farming equipment.
- EU Carbon Border Adjustment:The CBAM's phased implementation on steel and aluminum imports is incentivizing European mounting system OEMs to source from low-carbon Nordic and Spanish mills.
- Drone-Enabled Installation:Aerial lifting systems for panel placement are reducing labor hours on remote terrain projects in Australia's outback and Chile's Atacama.
Industry Challenges
- Geotechnical Engineering Talent:Site-specific foundation design for tracker systems requires scarce expertise in soil mechanics and wind load modeling across desert and alpine environments.
- Multi-Jurisdiction Certification:Mounting systems must simultaneously satisfy IEC 62817 for tracker mechanics, local building codes, and utility interconnection standards, extending product validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar PV Mounting Systems Market |
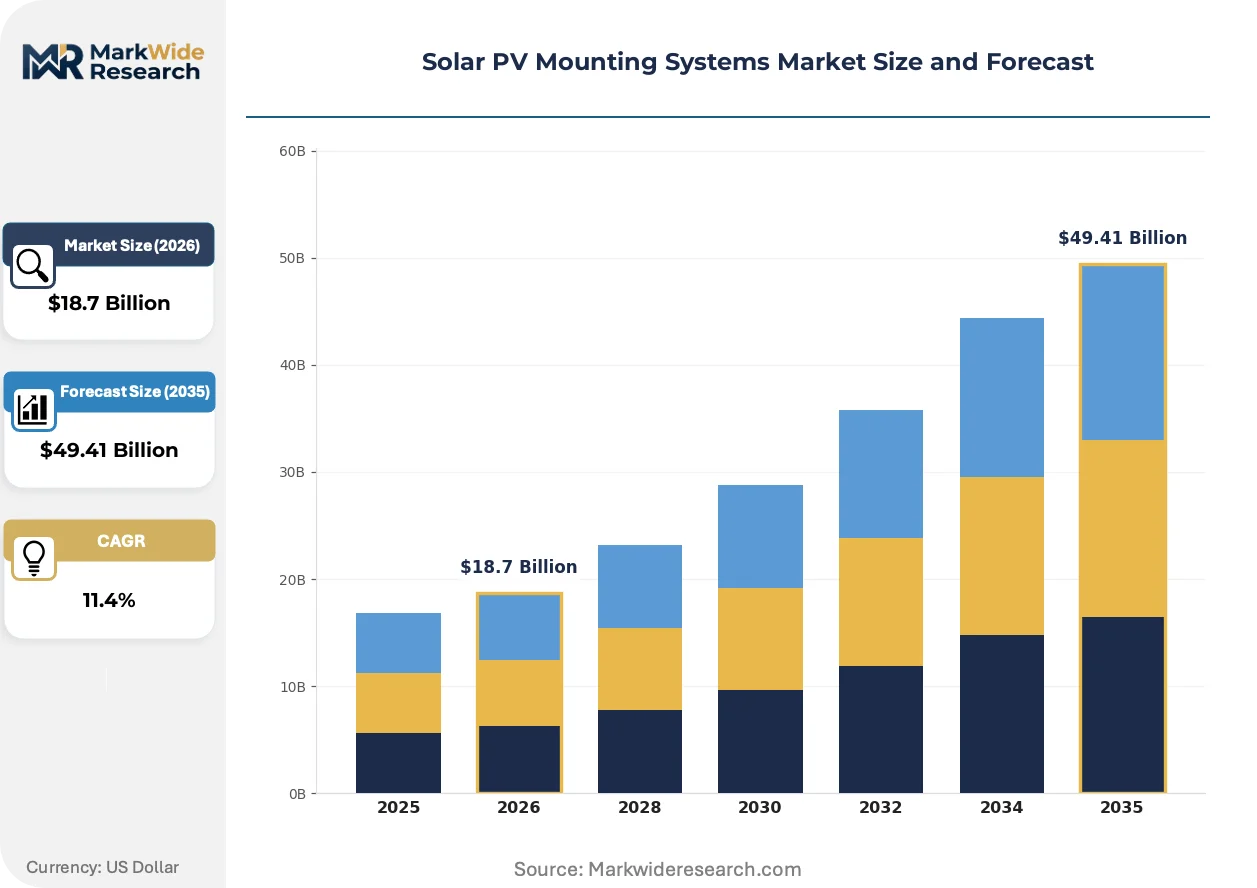
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Tilt, Adjustable Tilt, Ground Mount, Roof Mount Material: Aluminum, Steel, Plastic, Composite Application: Residential, Commercial, Utility Scale, Industrial Installation Type: On-grid, Off-grid, Hybrid, Floating |
| Companies Covered | Nextracker Inc., Array Technologies Inc., GameChange Solar, Arctech Solar Holding Co., Ltd., Soltec Power Holdings, PVHardware, Unirac Inc., Schletter Inc., IronRidge Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar PV Mounting Systems Market Emerging Trajectories
Tracker control systems are converging with power electronics and weather forecasting, transforming mounting structures from passive hardware into active grid assets that anticipate cloud transients and optimize tilt algorithms.
Artificial intelligence-driven predictive maintenance is consolidating tracker reliability protocols. Machine learning models trained on motor current signatures and anemometer data now forecast bearing degradation before mechanical failure. Large solar asset operators in Nevada and Rajasthan are deploying these systems to compress unplanned downtime. The technology is consolidating aftermarket service contracts into performance-guaranteed subscription models.
The EU Green Deal's carbon border adjustment mechanism is tightening documentation requirements for embodied emissions in steel and aluminum structural members. Mounting system suppliers must now secure Environmental Product Declarations from European mills or face tariff penalties. German and Spanish project developers are responding by qualifying domestic extruders ahead of the 2026 full implementation phase.
Engineering-procurement-construction firms are unbundling installation labor from hardware supply, creating direct procurement relationships between independent power producers and mounting system OEMs. This disintermediation compresses margin capture for traditional EPC middlemen. The shift is most visible in Texas and Arizona, where vertically integrated developers now specify tracker systems through factory-direct contracts rather than general construction packages.
Solar PV Mounting Systems Market Segmentation
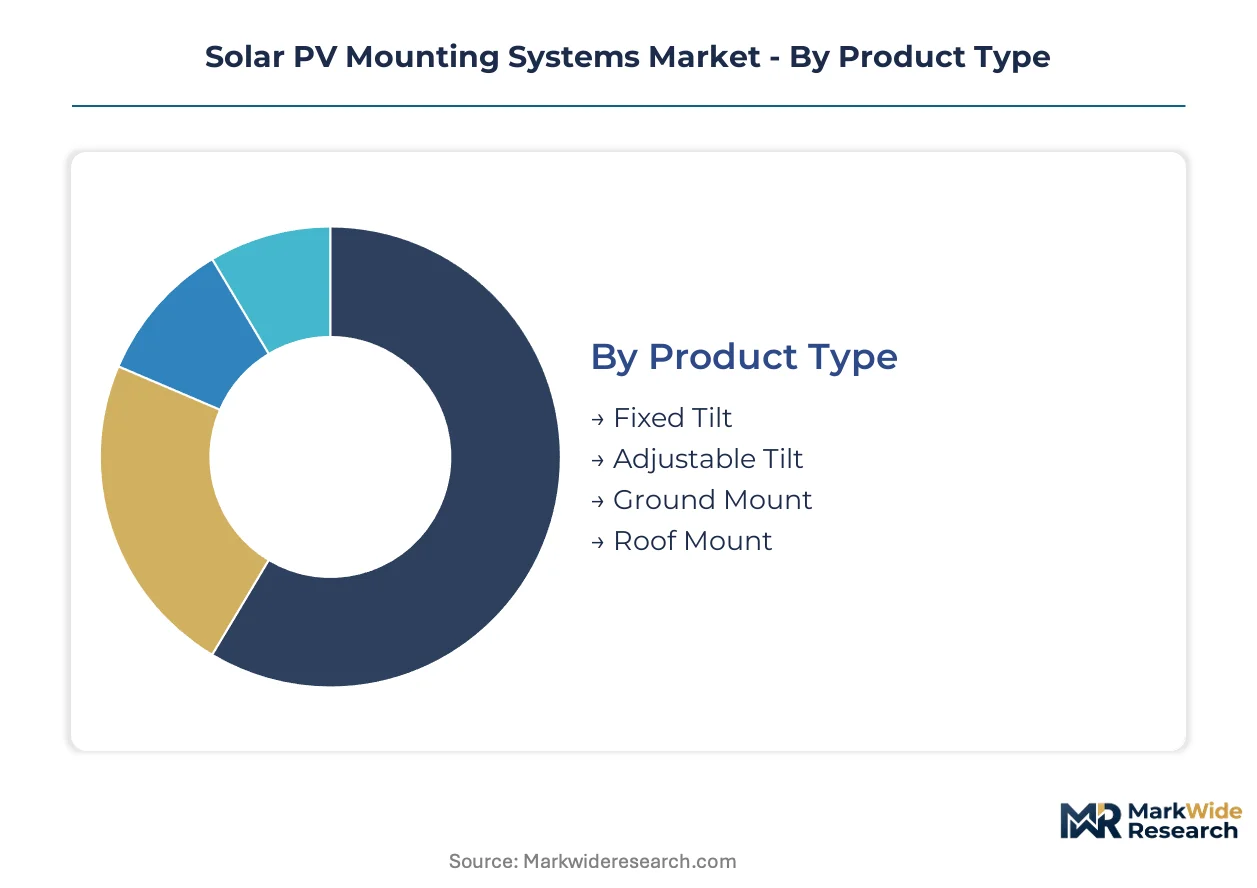
Mounting system procurement splits along steel intensity, structural geometry, and grid connectivity. Each dimension dictates foundation engineering, material certification requirements, and installation labor economics. Suppliers must align factory capacity with the specific load-bearing and regulatory demands of each segment cluster.
Product Type:
Supply concentration in steel fabrication favors high-volume fixed-tilt and ground-mount platforms, while precision-engineered adjustable systems command premium positioning in constrained sites.
- Fixed Tilt:Rigid steel or aluminum structures set at permanent angles optimized for latitude-specific irradiance. Demand clusters in utility-scale deserts of the United States, China, and India where standardized foundations minimize civil engineering overhead. IRA domestic content adders reinforce procurement from US-based galvanization facilities.
- Ground Mount:Steel-intensive pier-and-beam assemblies engineered for uneven terrain and high wind zones. Procurement volumes concentrate with independent power producers in Texas and Arizona bundling multi-gigawatt tracker contracts. Factory-direct structural systems compress balance-of-system timelines.
- Adjustable Tilt:Seasonally reconfigurable hinge mechanisms for residential and commercial rooftops. German and Italian project developers specify these for agrivoltaic dual-use installations.
- Roof Mount:Lightweight aluminum rail-and-clamp systems for commercial building stock. Corrosion resistance expands addressable inventory in aging European real estate.
Today's leader: Ground Mount. Tomorrow's challenger: Adjustable Tilt.
Material:
Cost tier differentiation separates commodity steel from certified low-carbon aluminum and specialized polymer composites.
- Steel:Hot-rolled coil and galvanized structural sections dominate ground-mount tonnage. Procurement from domestic US mills qualifies for IRA bonus credits, while EU project developers pivot to Nordic and Spanish low-carbon sources ahead of CBAM implementation.
- Aluminum:Extruded 6000-series alloys deliver corrosion-resistant lightweighting for roof-mount portfolios. Supply concentration in China's Yunnan and Xinjiang provinces exposes extrusion-dependent suppliers to export quota volatility.
- Plastic:UV-stabilized polymer components for floating PV mooring assemblies. Japanese reservoir installations drive specialized demand.
- Composite:Fiber-reinforced materials for coastal and high-salinity environments. Southeast Asian floating projects specify these for saltwater resistance.
Steel commands volume. Aluminum captures margin.
Application:
Customer type fragmentation requires distinct certification protocols and installation labor models across building-integrated and utility-scale deployment.
- Utility Scale:Multi-megawatt procurement with factory-preassembled tracker modules. Texas and California independent power producers specify integrated steel-and-electronics packages.
- Commercial:Roof-mount portfolios for distributed generation on warehouses and retail facilities. Aging building stock in France and Italy demands lightweight aluminum solutions.
- Residential:Standardized rail systems for rooftop retrofits. Permitting complexity varies by US state and European municipality.
- Industrial:Heavy-load ground-mount structures for manufacturing facility carports and canopies. Load-bearing requirements exceed commercial specifications.
Utility Scale anchors revenue. Commercial expands fastest.
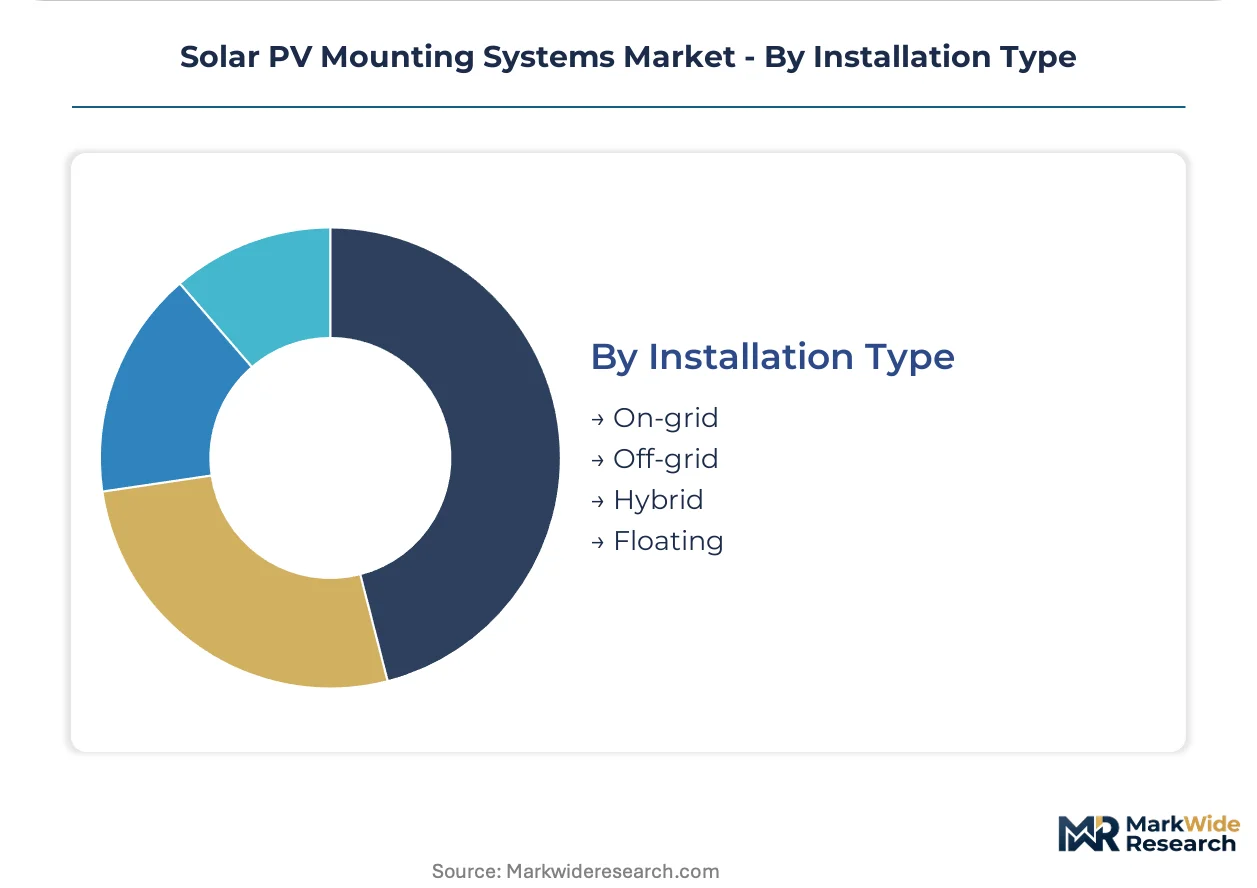
Installation Type:
Grid connectivity and siting constraints reshape foundation engineering and material selection across terrestrial and aquatic deployment.
- On-grid:Standardized utility-interconnected systems dominating procurement volumes. FERC interconnection queues in the United States dictate project pacing.
- Floating:Polymer-composite float structures and corrosion-resistant mooring for reservoirs and coastal waters. Japan and Southeast Asia lead deployment with specialized engineering requirements.
- Off-grid:Standalone battery-coupled systems for remote industrial and rural electrification. Australia's outback and Chile's Atacama specify helicopter-delivered preassembled units.
- Hybrid:Dual-mode systems switching between grid-tied and islanded operation. Microgrid developers in California and Texas specify these for resilience premiums.
On-grid dominates scale. Floating gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent for solar mounting systems clusters around steel fabrication corridors and tracker electronics development hubs. This workforce concentration shapes where procurement decisions concentrate and where domestic content compliance expertise resides.
United States
Utility-scale independent power producers in Texas and Arizona are bundling multi-gigawatt tracker supply agreements that compress balance-of-system timelines. The IRA's domestic content adders redirect procurement toward US-based galvanization and extrusion facilities. Nextracker anchors manufacturing scale through factory-direct structural systems serving desert solar farms.
China
Primary aluminum smelting capacity in Yunnan and Xinjiang provinces feeds extrusion-dependent roof-mount suppliers serving Belt and Road solar installations. MIIT enforces GB standards for structural steel and aluminum extrusions governing export qualification. Zhejiang and Jiangsu provinces host concentrated OEM fabrication clusters for ground-mount steel assemblies.
Germany
Commercial building stock in aging European real estate demands lightweight aluminum roof-mount solutions with corrosion resistance. The EU Green Deal's carbon border adjustment mechanism tightens documentation requirements for embodied emissions in structural members. Bavarian and North Rhine-Westphalian project developers qualify domestic extruders ahead of CBAM's full implementation.
India
Utility-scale solar farms in Rajasthan and Gujarat drive procurement of steel-intensive ground-mount systems. BIS certification for steel products and the PLI scheme for solar module manufacturing cascade into mounting system localization mandates. Tamil Nadu and Karnataka host emerging fabrication clusters serving domestic content requirements.
Japan
Reservoir and coastal floating PV installations create specialized demand for corrosion-resistant mooring assemblies and polymer-composite float structures. METI guidelines shape project economics for dual-use agricultural solar. Kyushu and Chubu regions concentrate engineering expertise for seismic load certification under the Building Standard Law.
Solar PV Mounting Systems Market Vendor Landscape
The competitive structure tilts toward vertically integrated tracker specialists with captive steel sourcing and factory-direct installation support. Three tiers stratify the vendor base: multinational scale players with domestic content compliance infrastructure, regional fabricators serving protected procurement markets, and niche specialists in floating or agrivoltaic structural systems. Dominant competitive moves include backward integration into galvanization and extrusion capacity, plus geographic expansion through local content partnerships in India and Brazil.
Among US-based tracker specialists, Nextracker Inc. and Array Technologies Inc. exemplify the scale-driven archetype with integrated steel-and-electronics portfolios. Arctech Solar Holding Co., Ltd. represents the China-based export-oriented fabricator segment serving Belt and Road installations. These three anchors illustrate how competitive positioning diverges between domestic content compliance in North America and cost-optimized export manufacturing from Chinese extrusion clusters.
| Leading Market Players |
|---|
| Nextracker Inc. |
| Array Technologies Inc. |
| GameChange Solar |
| Arctech Solar Holding Co., Ltd. |
| Soltec Power Holdings |
| PVHardware |
| Unirac Inc. |
| Schletter Inc. |
| IronRidge Inc. |
| Others |
Supply Flow & Price Mechanics
Hot-rolled coil steel traverses from Chinese and Indian mills through galvanization facilities in Texas and Arizona before crystallizing into three-tier pricing structures across premium tracker systems, standard fixed-tilt assemblies, and economy ground-mount portfolios for independent power producers.
Pricing Analysis
Bundled factory-direct contracts with pre-assembled steel-and-electronics packages command premium positioning against unbundled hardware-only supply. Price differentiation separates IRA-compliant domestic content tiers from import-dependent alternatives, with certification grade and volume scale as secondary drivers. Cost compression in standard fixed-tilt segments is intensifying because EPC disintermediation strips margin capture from traditional middlemen. Utility-scale independent power producers exhibit lowest price sensitivity given multi-gigawatt procurement scale, while commercial roof-mount buyers in aging European real estate demand lightweight aluminum solutions at economy pricing.
Supply Chain Analysis
Direct-to-IPP channels handle hyperscale buyer demand across Texas, California, and Arizona, bypassing traditional EPC intermediaries. Geographic supply concentration clusters in China for primary aluminum smelting, the United States for galvanized steel fabrication, and Germany for precision extrusion. Raw material dependencies draw from hot-rolled coil, 6000-series aluminum billets, and UV-stabilized polymer resins. Single-source vulnerability in China's Yunnan and Xinjiang smelting regions exposes roof-mount suppliers to export quota disruptions. Distribution runs through factory-direct contracts for utility-scale procurement and regional fabricator networks for commercial installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Solar PV Mounting Systems Market functions as a geographic-arbitrage play where IRA domestic content bonuses in the United States create margin premiums unavailable to import-dependent competitors serving European projects facing CBAM carbon border adjustments.
For Market Incumbents: Deploy captive steel sourcing as a defensive lever against hot-rolled coil volatility and emerging tracker electronics specialists. Backward integration into galvanization capacity in Texas and Arizona preserves IRA bonus credit eligibility. Certification investment in seismic load testing under California Title 24 and Japan's Building Standard Law defends positioning against regional fabricators with fragmented compliance infrastructure. For New Entrants and Emerging Players: Capture floating PV mooring assembly demand in Japan and Southeast Asia where polymer-composite engineering requirements create specialist barriers. Agrivoltaic dual-use installations in France and Italy represent the most penetrable segment given elevated fixed-tilt structural complexity. Factory-direct channel partnerships with independent power producers bypass EPC margin extraction. For Investors and Strategic Acquirers: Consolidation pressure builds where domestic content compliance infrastructure exceeds the capital reach of regional fabricators in India and Brazil. Long-term viability centers on vertically integrated tracker specialists with captive steel sourcing and factory-direct installation support. Acquisition target archetypes include niche floating PV structural engineers and agrivoltaic hinge mechanism specialists. The signal to watch is CBAM implementation pace affecting European mill qualification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Galvanization | Captures IRA domestic content adders for steel-intensive ground-mount systems in Texas and Arizona. |
| Floating PV Mooring System Development | Addresses corrosion-resistant demand from Japanese reservoir and Southeast Asian coastal installations. |
| Agrivoltaic Structural Platform Launch | Targets elevated fixed-tilt specifications for mechanized farming compatibility in France and Italy. |
| Low-Carbon Aluminum Sourcing Partnership | Qualifies Nordic and Spanish extruders ahead of EU CBAM full implementation on structural members. |
| Predictive Maintenance Service Subscription | Consolidates tracker reliability protocols into performance-guaranteed contracts with Nevada and Rajasthan operators. |
Methodological Framework
Direct dialogue with tracker system procurement officers at independent power producers, EPC contract managers, galvanization facility operators, and aluminum extrusion technical directors grounds qualitative findings. Secondary validation draws from FERC interconnection filings, EIA solar deployment databases, IRA domestic content guidance documents, and EU CBAM implementation notices. Bottom-up and top-down triangulation cross-checks project-level procurement data against national installation aggregates.
Bottom-up modeling builds from individual project announcements and supply contract disclosures, while top-down analysis calibrates against national renewable energy targets and steel consumption benchmarks. Segmentation dimensions span product type, material composition, application scale, and installation connectivity across the projection horizon. CAGRs derive from regression analysis of historical procurement volumes against policy incentive trajectories. Forecast inputs incorporate tracker adoption rates in desert solar zones and floating PV penetration in reservoir-rich geographies.
Steel price volatility, aluminum export quota disruptions, and seismic certification timeline extensions are the dominant revision risks to modeled projections. Forecasts reflect documented assumptions regarding IRA bonus credit continuity and EU CBAM phase-in schedules. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Spain Solar Energy Market
Solar Power Systems
Europe Solar Photovoltaic (PV) Market
Solar Power Systems
Solar PV Backsheet Market
Solar Power Systems
Rooftop Solar Photovoltaic (PV) Installation Market
Solar Power Systems
Sweden Solar Energy Market
Solar Power Systems
Europe Solar Concentrator Market
Solar Power Systems
India Rooftop Solar Market
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Roofing Market
Solar Power Systems
Solar Concentrator Market
Solar Power Systems
Greece Solar Energy Market
Solar Power Systems
Solar Cell Busbar Market
Solar Power Systems
Rooftop Solar Panels Market
Solar Power Systems
Marine Solar Panel Market
Solar Power Systems
Biohybrid Solar Cell Market
Solar Power Systems
Dual Axis Solar Tracker Market
Solar Power Systems
Solar Panel Lights Market