
 Solid State Battery Market | 2026-2036
Solid State Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Solid State Battery Market Analysis
Cell manufacturing margin pools are migrating from liquid-electrolyte assembly toward solid-electrolyte deposition and dry electrode processing, which is reconfiguring how battery makers allocate capital and technical talent. Toyota leverages its three-decade solid-state patent portfolio to sustain development leadership in sulfide-based electrolytes. QuantumScape anchors its position through proprietary ceramic separator technology aimed at lithium-metal anodes. Samsung SDI competes by operating integrated pilot lines in South Korea that bridge materials science with automotive qualification protocols.
A solid-state battery replaces flammable liquid electrolytes with ion-conducting solids such as sulfides, oxides, or polymers, enabling energy densities above 400 Wh/kg and eliminating thermal runaway risks that constrain conventional lithium-ion designs. Thin-film solid-state cells dominate medical device and wearable applications where form factor and safety premiums justify higher unit costs. Bulk solid-state technology leads electric vehicle development timelines because automotive OEMs prioritize cell-level energy density and manufacturing scalability over miniaturization. Composite electrolyte approaches occupy an emerging middle ground, attracting R&D investment from suppliers seeking to bridge performance gaps between sulfide ionic conductivity and oxide air stability.
FDA device-safety standards shape medical-grade solid-state battery requirements in the United States, while the EU Battery Regulation mandates carbon-footprint disclosure and recycled-content thresholds that affect cell design choices entering European markets. Japan's METI coordinates national solid-state consortia that align domestic chemical suppliers, automotive OEMs, and university laboratories around shared manufacturing roadmaps. Stakeholders must monitor which electrolyte chemistry achieves automotive qualification first, as this determination will lock in supply chain partnerships and patent licensing structures for the following decade.
Market Dynamics
Automotive OEM procurement of solid-state cells is compressing development timelines, forcing battery suppliers to accelerate pilot-line qualification ahead of mature manufacturing economics.
Growth Catalysts
- EU Battery Regulation:Carbon-footprint disclosure mandates and recycled-content thresholds are pushing European automotive OEMs toward solid-state designs that simplify supply chain compliance.
- Electric vehicle range extension:Cell-level energy density above 400 Wh/kg addresses consumer range anxiety without increasing pack weight, driving procurement commitments from premium EV platforms.
- Sulfide electrolyte R&D:Japan's METI-funded consortia are coordinating domestic chemical suppliers and university laboratories around shared manufacturing roadmaps that de-risk scale-up.
Market Restraints
- Manufacturing capex intensity:Dry electrode processing and solid-electrolyte deposition require entirely new capital equipment, constraining supplier balance sheets before revenue recognition.
- Technical limitation in air stability:Sulfide-based electrolytes degrade upon moisture exposure, necessitating hermetic manufacturing environments that inflate unit costs.
- Substitution threat from silicon-anode liquid cells:Near-term energy density improvements in conventional lithium-ion designs delay solid-state conversion decisions at price-sensitive OEMs.
Strategic Opportunities
- Medical device miniaturization:Thin-film solid-state cells command premium pricing in FDA-regulated implantable devices where form factor and thermal safety outweigh cost sensitivity.
- South Korea pilot-line qualification:Integrated production facilities bridging materials science with automotive testing protocols offer first-mover advantage in cell certification.
- Composite electrolyte convergence:Hybrid approaches combining sulfide ionic conductivity with oxide air stability attract development investment from suppliers seeking intermediate performance tiers.
Industry Challenges
- Solid-state manufacturing talent scarcity:The intersection of ceramic processing, thin-film deposition, and electrochemistry lacks trained engineers, elongating hiring cycles for pilot-line operations.
- Automotive qualification timeline compression:OEMs demand 10-year cell validation data that does not yet exist, forcing suppliers to accelerate aging studies without compromising statistical rigor.
- IP licensing complexity in sulfide chemistries:Dense patent thickets around lithium-metal anode interfaces create negotiation friction between materials suppliers and cell manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid State Battery Market |
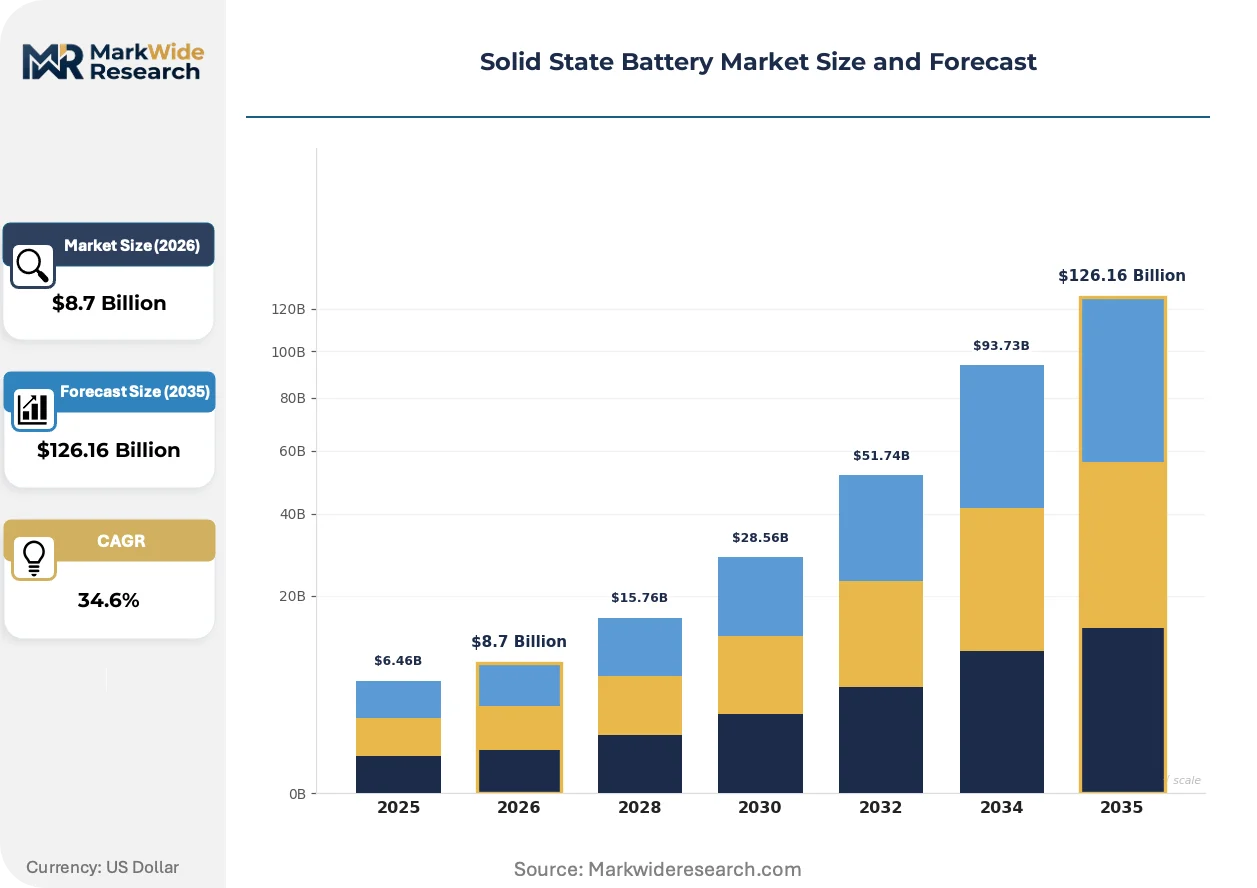
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $126.16 Billion |
| CAGR (2026 – 2036) | 34.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium Metal, Lithium Ion, Sodium Ion, Other End User: Consumer Electronics, Automotive OEMs, Aerospace, Medical Devices Technology: Thin Film, Bulk, Composite, Other Application: Electric Vehicles, Grid Storage, Portable Devices, Wearable Technology |
| Companies Covered | CATL, LG Energy Solution, QuantumScape, Gotion High-Tech, BYD, Solid Power, Samsung SDI, SES AI Corporation, Toyota, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid State Battery Market Emerging Trajectories
Cell architecture is pivoting from liquid-electrolyte wet processing toward solid-state dry manufacturing, reconfiguring equipment supplier relationships and factory floor layouts across the battery industry.
Sulfide electrolyte deposition is migrating from batch ceramic sintering toward continuous roll-to-roll manufacturing. Automotive cell suppliers in South Korea and Japan are piloting this transition to match liquid-electrolyte throughput rates. The shift is compressing equipment supplier lead times and forcing incumbent toolmakers to develop solid-state-specific deposition chambers.
Japan's METI coordinates national solid-state consortia that align domestic chemical suppliers, automotive OEMs, and university laboratories around shared manufacturing roadmaps. This industrial policy reduces duplicative R&D and accelerates standardization of sulfide electrolyte handling protocols. Korean suppliers are responding by establishing equivalent government-backed coordination mechanisms to maintain competitive parity.
Fleet procurement managers now require cell-level thermal runaway test data before platform integration commitments, displacing reliance on pack-level safety engineering alone. This specification shift elevates solid-state suppliers in vendor selection processes. The pattern is most visible in premium European electric vehicle programs where insurance underwriters influence battery specification decisions.
Solid State Battery Market Segmentation
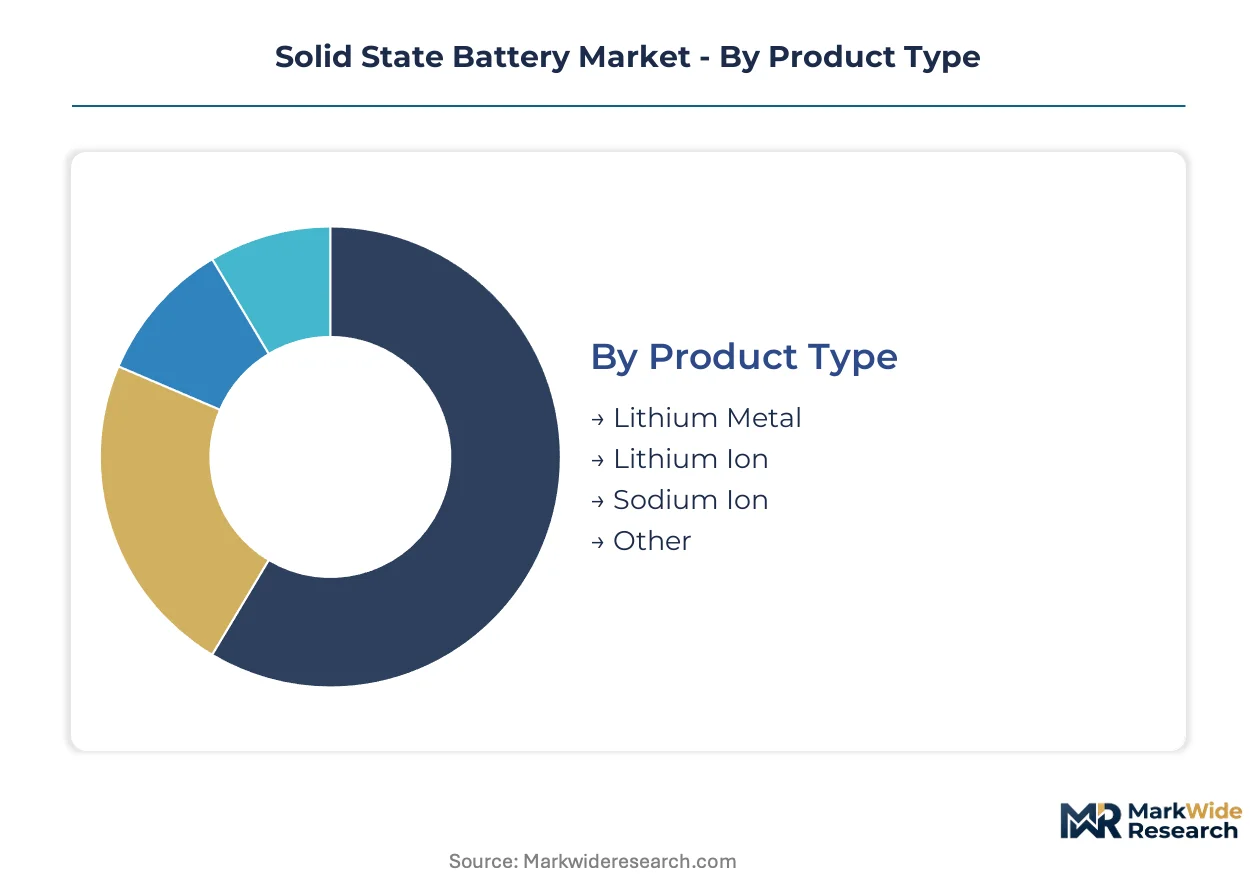
Solid-state battery segmentation reveals divergent technical requirements across mobility, medical, and energy storage applications. Each product architecture demands distinct electrolyte chemistries, manufacturing scales, and qualification timelines that reshape supplier competitive positioning.
Product Type:
After-sales service intensity varies sharply by chemistry, with lithium-metal systems requiring specialized diagnostic protocols and sodium-ion variants demanding minimal field intervention.
- Lithium Metal:Employs pure metallic lithium anodes paired with ceramic or sulfide electrolytes to achieve energy densities exceeding 400 Wh/kg. Automotive OEMs in South Korea and Japan are prioritizing procurement of lithium-metal cells for premium electric vehicle platforms where range extension justifies elevated unit costs and complex manufacturing.
- Lithium Ion:Retains graphite or silicon-composite anodes while replacing liquid electrolytes with solid conductors, offering intermediate performance with reduced manufacturing risk. Consumer electronics manufacturers in Taiwan and China favor this architecture for smartphone and laptop applications where supply chain continuity outweighs maximum energy density targets.
- Sodium Ion:Substitutes abundant sodium for lithium in solid-electrolyte configurations, targeting cost-sensitive grid storage deployments where energy density requirements remain modest. India's PLI scheme is incentivizing domestic sodium-ion development for stationary applications.
- Other:Encompasses magnesium-ion, potassium-ion, and aluminum-ion experimental chemistries under active evaluation at university laboratories in Germany and the United States.
Lithium Ion holds the largest share; momentum sits with Lithium Metal.
End User:
Cost tier stratification separates medical device buyers seeking premium safety certification from automotive OEMs optimizing for manufacturing scale.
- Automotive OEMs:Command the highest volume procurement commitments, driving sulfide electrolyte scale-up investments and dry electrode processing equipment orders. Toyota, Hyundai, and BMW have established dedicated solid-state engineering teams with direct supplier integration.
- Consumer Electronics:Prioritizes thin-film form factors for smartphone and tablet applications where space constraints and thermal safety influence vendor selection. Japanese and South Korean electronics conglomerates are qualifying solid-state suppliers for next-generation flagship devices.
- Medical Devices:Demands hermetic packaging and FDA-compliant manufacturing traceability for implantable cardiac monitors and neurostimulators. Swiss and German device manufacturers specify solid-state cells for applications where battery replacement requires surgical intervention.
- Aerospace:Requires radiation-hardened solid-state designs for satellite power systems and electric aircraft propulsion, with qualification timelines extending beyond commercial automotive schedules.
Automotive OEMs dominate procurement volume; Medical Devices command the steepest expansion trajectory.
Technology:
Volume concentration in bulk manufacturing is displacing thin-film dominance as automotive qualification timelines accelerate.
- Bulk:Stacked or wound cell architectures using pressed ceramic or sulfide electrolyte layers, designed for kilowatt-hour-scale applications. South Korean pilot lines at Samsung SDI and LG Energy Solution are advancing bulk solid-state production toward automotive qualification protocols.
- Thin Film:Vacuum-deposited electrolyte and electrode layers on micrometer-scale substrates, enabling millimeter-thin form factors. Medical device manufacturers in Switzerland and the United States specify thin-film cells for implantable applications where volume constraints are absolute.
- Composite:Hybrid electrolyte structures combining sulfide ionic conductivity with oxide air stability, attracting R&D investment from suppliers seeking intermediate performance tiers. Japanese METI-funded consortia are coordinating composite electrolyte roadmaps across domestic chemical suppliers.
- Other:Includes glass-ceramic, polymer-ceramic, and gel-quasi-solid architectures under evaluation for specialized temperature or mechanical stress environments.
Bulk technology leads manufacturing investment; Composite approaches are gaining share fastest.
Application:
Customer type differentiation separates fleet procurement managers demanding decade-long warranty data from consumer electronics buyers prioritizing annual product refresh cycles.
- Electric Vehicles:Requires cell-level energy density above 400 Wh/kg and thermal runaway elimination to address consumer range anxiety and insurance underwriting requirements. European premium OEMs are mandating solid-state cell specifications for next-generation platforms.
- Portable Devices:Encompasses smartphones, laptops, and tablets where solid-state safety profiles enable thinner device profiles and reduced thermal management hardware. Taiwanese and Chinese contract manufacturers are evaluating solid-state options for flagship product lines.
- Grid Storage:Prioritizes cycle life and capital cost over energy density, with sodium-ion solid-state architectures targeting utility-scale deployments. India's national storage mission is soliciting solid-state proposals for renewable integration projects.
- Wearable Technology:Demands extreme form factor flexibility and biocompatibility for fitness trackers, hearing aids, and augmented reality headsets. FDA and EU MDR compliance requirements shape supplier qualification for medical-adjacent wearable applications.
Electric Vehicles anchor capital deployment; Wearable Technology represents the fastest-climbing application tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Solid-state battery consumption patterns diverge sharply by geography. Japan and South Korea prioritize automotive qualification timelines. Europe emphasizes regulatory compliance for carbon footprint disclosure. The United States concentrates on medical device miniaturization and defense applications.
Japan
Automotive OEM procurement drives sulfide electrolyte development at unprecedented velocity. METI coordinates national consortia aligning chemical suppliers, university laboratories, and Toyota around shared manufacturing roadmaps. Nagoya and Kyoto host the densest clusters of pilot-line facilities bridging materials science with automotive testing protocols.
South Korea
Samsung SDI and LG Energy Solution operate integrated production facilities targeting premium electric vehicle platforms. The national government mirrors Japan's coordination mechanisms to maintain competitive parity in automotive qualification. Gyeonggi Province concentration of dry electrode processing equipment suppliers accelerates scale-up timelines for sulfide deposition chambers.
Germany
European premium OEMs mandate solid-state specifications for next-generation platforms, driven by EU Battery Regulation carbon-footprint thresholds. BMW maintains dedicated solid-state engineering teams with direct supplier integration. Stuttgart and Munich anchor the automotive qualification ecosystem, with insurance underwriters increasingly influencing cell-level thermal runaway specifications.
United States
FDA device-safety standards shape medical-grade requirements for implantable cardiac monitors and neurostimulators, commanding premium pricing independent of automotive scale economics. QuantumScape anchors development in ceramic separator technology for lithium-metal anodes. California and Massachusetts concentrate thin-film deposition expertise for wearable and defense applications.
China
CATL and BYD leverage existing liquid-electrolyte manufacturing scale to fund parallel solid-state development tracks. MIIT standards for next-generation battery safety accelerate domestic qualification timelines. Shenzhen and Ningbo host the largest concentrations of composite electrolyte R&D seeking intermediate performance tiers between sulfide conductivity and oxide stability.
Solid State Battery Market Vendor Landscape
Capability concentration sits with specialized solid-state developers possessing proprietary ceramic or sulfide electrolyte formulations; scale advantage sits with incumbent lithium-ion manufacturers leveraging existing capital equipment and automotive customer relationships. The market structure organizes into three strategic archetypes: automotive-integrated chemical conglomerates, venture-backed technology developers, and contract cell manufacturers seeking portfolio diversification. Dominant competitive moves include strategic partnerships for pilot-line qualification and technology licensing agreements to navigate dense patent thickets around lithium-metal anode interfaces.
Within the automotive-integrated tier, Toyota represents three-decade patent accumulation in sulfide-based electrolytes, while Samsung SDI exemplifies the Korean model of government-coordinated scale-up. QuantumScape occupies a position as the venture-backed anchor for ceramic separator development targeting lithium-metal architectures. These three companies collectively illustrate the geographic and technological divergence shaping competitive positioning through the qualification window.
| Leading Market Players |
|---|
| CATL |
| LG Energy Solution |
| QuantumScape |
| Gotion High-Tech |
| BYD |
| Solid Power |
| Samsung SDI |
| SES AI Corporation |
| Toyota |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Rotterdam maritime corridor carries sulfide electrolyte precursors and dry electrode processing equipment at freight rates that directly compress margins for European automotive OEMs while amplifying price differentiation between hermetic manufacturing tiers and standard assembly lines. South Korean and Japanese suppliers leverage shorter Pacific routes to North American ports, capturing logistics cost advantages that translate into bidding leverage for premium electric vehicle contracts.
Pricing Analysis
Long-term offtake agreements dominate procurement between automotive OEMs and cell manufacturers, with spot markets limited to small-batch medical device and aerospace applications where qualification timelines extend beyond contract horizons. Price differentiation separates FDA-validated thin-film cells for implantable devices from bulk automotive cells certified to OEM thermal runaway protocols. Cost compression in sulfide electrolyte deposition is intensifying because dry processing equipment suppliers in Gyeonggi Province are expanding chamber manufacturing capacity. Consumer electronics manufacturers in Taiwan exhibit the highest price sensitivity, while Swiss medical device OEMs accept premiums for hermetic packaging traceability.
Supply Chain Analysis
Samsung SDI and LG Energy Solution anchor contract manufacturing concentration for automotive-grade bulk cells, with pilot-line capacity expansion concentrated in Gyeonggi Province. Raw material dependencies draw from lithium carbonate processing in Australia, sulfur refining in Japan, and ceramic separator substrates from German specialty chemical suppliers. Single-source vulnerability concentrates in sulfide electrolyte precursor synthesis, where moisture-sensitive handling protocols limit qualified chemical suppliers to METI-coordinated Japanese consortia. Distribution runs through Tier 1 automotive battery integrators with direct OEM engineering integration, bypassing traditional electronics distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state battery incumbents face substitution defense against silicon-anode liquid lithium-ion cells achieving near-term energy density improvements that delay conversion decisions at price-sensitive OEMs. The analysis window demands strategic positioning before electrolyte chemistry qualification locks in decade-long supply relationships.
For Market Incumbents: Insulate patent positions around lithium-metal anode interfaces through accelerated licensing negotiations with sulfide electrolyte suppliers, while expanding captive production of dry electrode processing equipment in South Korea to reduce chamber procurement lead times. Toyota's three-decade sulfide portfolio and QuantumScape's ceramic separator IP represent defensive moats against emerging composite electrolyte challengers.
For New Entrants and Emerging Players: Mid-market grid storage deployments in India represent the most penetrable entry point, where sodium-ion solid-state architectures align with PLI scheme incentives and modest energy density requirements reduce technical barriers. FDA-regulated wearable devices in the United States offer secondary white-space through thin-film form factors where biocompatibility certification creates incumbent blind spots. Go-to-market execution should prioritize direct engineering relationships with national storage mission procurement officers over automotive qualification timelines.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with dormant solid-state electrolyte R&D divisions lacking automotive customer access. Long-term viability centers on which electrolyte chemistry achieves first automotive qualification, locking in royalty structures and supply chain partnerships across the projection horizon. Monitor METI consortium patent filing velocity and South Korean pilot-line yield data as inflection indicators. Quarterly review of automotive OEM platform announcement timing and insurance underwriter thermal runaway specification adoption is advised to detect inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Sulfide Electrolyte Scale-Up Partnership | Aligns Toyota's patent portfolio with Samsung SDI's pilot-line capacity for automotive qualification acceleration. |
| Dry Electrolyte Deposition Equipment Order | Compresses equipment supplier lead times for LG Energy Solution's Gyeonggi Province expansion. |
| FDA 510(k) Submission for Thin-Film Cells | Opens premium pricing tiers for implantable cardiac monitor applications in Swiss and German device markets. |
| Composite Electrolyte R&D Consortium | Bridges METI-funded sulfide conductivity with oxide air stability for intermediate performance tier capture. |
| Long-Term Supply Agreement with Premium OEM | Secures decade-long offtake commitment from BMW's dedicated solid-state engineering team. |
Methodological Framework
A standing panel of automotive platform engineers, solid-state materials scientists, cell manufacturing operations directors, and hospital procurement managers provided ongoing calibration across primary interview cycles. Secondary validation drew from SEC battery supplier filings, METI consortium disclosure documents, FDA 510(k) device databases, and IHS Markit electric vehicle production data. Bottom-up cell cost modeling and top-down automotive procurement commitment tracking enabled triangulation of volume and value estimates.
Scenario bracketing anchored projections across conservative, baseline, and accelerated automotive qualification timelines without assuming specific calendar-year milestones. Segmentation dimensions spanned electrolyte chemistry, cell architecture, end-use application, and regional regulatory cluster. CAGRs were derived from electrolyte deposition equipment order backlogs and OEM platform announcement timing. Forecast inputs incorporated sulfide handling protocol standardization progress and thin-film medical device certification pipeline status.
Practitioners should monitor silicon-anode liquid cell energy density improvements, automotive OEM platform delay announcements, and sulfide electrolyte air stability breakthroughs for early signals of forecast revision. Forecasts reflect assumptions around pilot-line yield progression and regulatory qualification timeline compression. Quarterly review of METI consortium patent velocity and South Korean equipment supplier capacity expansion is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium-Ion Battery Separator Market
Lithium-ion Battery
Marine Lithium-Ion Battery Market
Lithium-ion Battery
United States Battery Cell Market
Lithium-ion Battery
Automotive Lithium-Ion Battery Cell Market
Lithium-ion Battery
Lithium-Ion Batteries Electric Bike Market
Lithium-ion Battery
Southeast Asia Lithium-Ion Battery Market
Lithium-ion Battery
Lithium-Ion Stationary Battery Storage Market
Lithium-ion Battery
Europe Electric Vehicle Battery Anode Market
Lithium-ion Battery
Lithium Battery in Myanmar Market
Lithium-ion Battery
Europe Solid State Battery Market
Lithium-ion Battery
India Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lithium Polymer Battery Market
Lithium-ion Battery
China SLI Battery Market
Lithium-ion Battery
United Kingdom Electric Vehicle Battery Anode Market
Lithium-ion Battery
Laminated Lithium Ion Secondary Battery Market
Lithium-ion Battery
Pouch Lithium-Ion Batteries Market