
 Solar Encapsulation Market | 2026-2036
Solar Encapsulation Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Encapsulation Market Intelligence
The direct-to-manufacturer supply channel from bulk polymer producers is narrowing as module makers seek more integrated suppliers. DuPont de Nemours, Inc. leverages its extensive material science portfolio to offer differentiated products. Hangzhou First Applied Material Co., Ltd. dominates the market with immense production scale and cost leadership. Meanwhile, STR Holdings, Inc. specializes in customized encapsulant solutions for niche applications.
Solar encapsulation involves laminating photovoltaic cells between layers of protective polymer material. These materials provide critical electrical insulation, structural support, and high optical transparency to maximize light transmission to the cell. Ethylene Vinyl Acetate (EVA) remains the dominant product type due to its proven track record and low cost. However, Polyolefin Elastomers (POE) are gaining share in high-performance modules, particularly for bifacial technology used in Utility Scale Projects.
Material selection is governed by international standards like IEC 61215 for module design qualification and IEC 61730 for safety. Regulations such as the EU's RoHS directive and China's GB standards restrict hazardous substances, influencing polymer formulations. The central challenge for material suppliers and module manufacturers is improving long-term durability and resistance to potential-induced degradation without significantly increasing overall system costs.
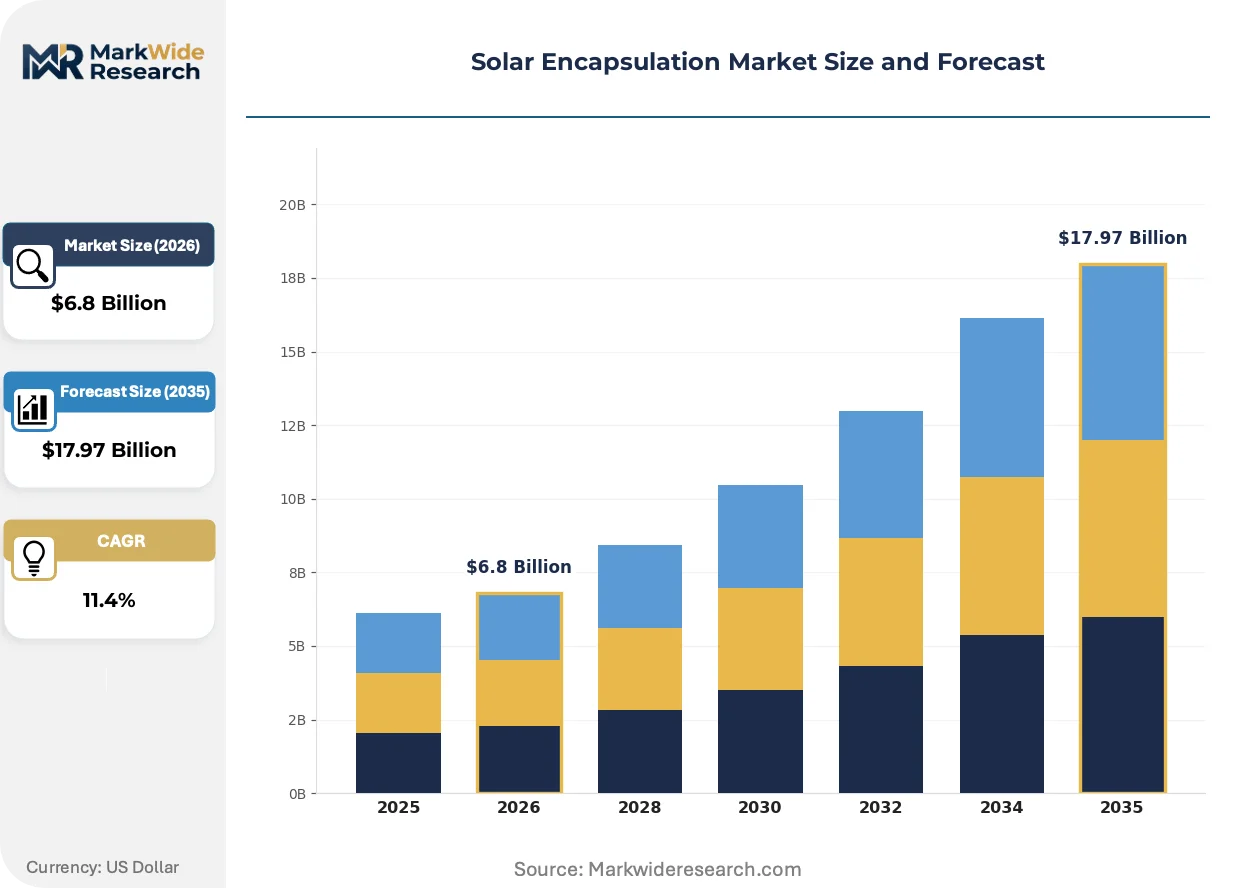
Market Dynamics
The market's central dynamic is the tension between policy-driven demand for solar energy in North America and Europe and the extreme concentration of polymer and encapsulant production capacity in China, which dictates global cost structures and material availability.
Growth Catalysts
- National Energy Policies:Government-led initiatives, such as the EU Green Deal and national renewable energy targets in countries like India and the United States, are accelerating the deployment of Utility Scale Projects, the largest end-use segment for encapsulants.
- Bifacial Module Adoption:The technical shift towards bifacial solar modules, which capture light on both sides, necessitates the use of higher-performance, highly transparent encapsulants like Polyolefin Elastomers (POE) to maximize energy yield.
- Emerging Market Electrification:Efforts to expand electricity access in parts of Southeast Asia and Africa are creating new, distributed demand for solar panels, opening smaller but consistent volume opportunities for encapsulant suppliers.
Market Restraints
- Raw Material Concentration:Heavy reliance on China for essential raw materials, including EVA and POE resins, exposes the global supply chain to significant geopolitical risks and price volatility, impacting module manufacturer margins.
- Technical Performance Trade-offs:There is a persistent trade-off between enhancing long-term durability, particularly resistance to potential-induced degradation (PID), and the higher material cost of advanced encapsulants like POE compared to incumbent EVA.
- Substitution from Film Backsheets:The evolution of integrated backsheet and encapsulant products presents a substitution threat, potentially reducing the total addressable market for standalone encapsulant films in certain module designs.
Strategic Opportunities
- Hybrid Encapsulant Films:Developing co-extruded films that combine the low cost and adhesion of EVA with the durability and PID resistance of POE offers a path to capture demand from performance-oriented and cost-sensitive module producers.
- Building-Integrated Photovoltaics (BIPV):The expansion of BIPV applications in commercial and residential construction creates an opportunity for specialized, aesthetically versatile encapsulants that meet both building codes and energy generation requirements. *Circular Economy Formulations: Formulating encapsulants for easier delamination and recycling at the end of a module's life presents a significant opportunity, aligning with sustainability mandates like the EU's Corporate Sustainability Reporting Directive (CSRD).
Industry Challenges
- Certification Timelines:The lengthy and costly qualification process to meet international standards like IEC 61215 and IEC 61730 for new material formulations acts as a barrier to rapid innovation and market entry for novel polymers.
- Manufacturing Scalability:Scaling production for newer materials like POE to match the immense global capacity and cost-efficiency of established EVA manufacturing lines requires significant capital investment and process optimization.
- Long-Term Degradation Pathways:Ensuring material stability against ultraviolet radiation, moisture, and thermal cycling over a 25-to-30-year module lifespan remains a core operational challenge for material scientists and quality assurance teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Encapsulation Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethylene Vinyl Acetate, Polyolefin Elastomers, Thermoplastic Polyurethane, Silicone, Laminates Technology: Bifacial, Monofacial, Tandem, Perovskite, Thin Film, Concentrator Application: Residential Installations, Commercial Systems, Utility Scale Projects, Off-grid Solutions, Agrivoltaics End User: Independent Power Producers, EPC Contractors, Renewable Energy Cooperatives, Energy Storage Providers |
| Companies Covered | STR Holdings, Inc., Mitsui Chemicals, Inc., DuPont de Nemours, Inc., Hangzhou First Applied Material Co., Ltd., Advanced Polymer Technology Corp., First Solar, Inc., SKC Co., Ltd., TPI Polene Power Public Co. Ltd., 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Encapsulation Market Strategic Shifts & Innovations
Material science is advancing to address the solar industry's core challenge: extending module operational lifetimes and enhancing energy yield without adding prohibitive cost. Innovations focus on creating more resilient material systems that can withstand decades of environmental stress in increasingly powerful solar arrays.
Co-extruded multi-layer films that strategically combine different polymers represent a major product evolution. High-performance module manufacturers are increasingly adopting these composite films for advanced n-type and bifacial solar cells. This approach is virtualizing the need for separate front and back encapsulant layers, simplifying the lamination process and optimizing material properties for each side of the cell.
Regulatory frameworks focused on material safety are influencing polymer chemistry. Directives such as the EU's RoHS and China's GB standards restrict the use of certain hazardous substances in electronics, including solar modules. This pressure forces the reformulation of additives and cross-linking agents used in encapsulants. EVA formulations are particularly affected, which in turn accelerates research into inherently more stable and cleaner polyolefin-based alternatives.
A notable shift in buying behavior is emerging from large-scale asset owners. Instead of leaving material selection solely to module manufacturers, utility developers are beginning to specify encapsulant types in their procurement contracts to mitigate long-term degradation risks. This pattern disrupts the traditional supply channel by creating a direct technical dialogue between polymer suppliers and end-users. This is most visible in bankability-focused Utility Scale Projects in North America and Europe.
Solar Encapsulation Market Segmentation
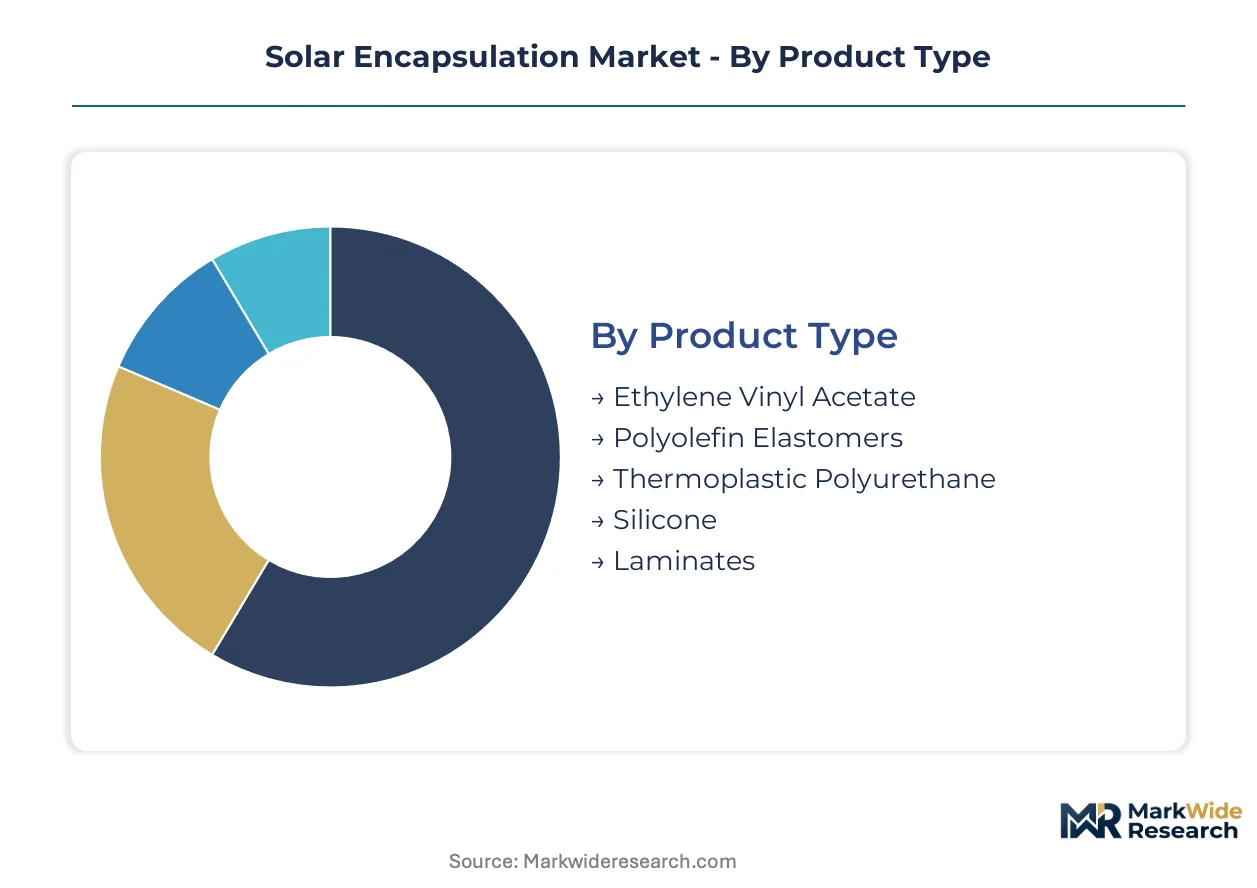
Understanding the segmentation within the solar encapsulation market is crucial for material suppliers and module manufacturers. Each segment presents distinct technical requirements, cost considerations, and market dynamics that influence product development and strategic investments. Analyzing these categories helps identify key growth areas and specific material demands.
Product Type:
The intensity of after-sales service and long-term warranty claims often correlates with the chosen encapsulant material, making product type a critical differentiation point for module longevity.
- Ethylene Vinyl Acetate:This polymer remains the industry standard due to its established performance, cost-effectiveness, and ease of processing. Demand for EVA is prevalent in conventional monofacial modules, particularly for price-sensitive projects in emerging markets.
- Polyolefin Elastomers:POE offers superior resistance to potential-induced degradation (PID) and moisture ingress, along with higher optical transparency. Utility Scale Projects increasingly specify POE for high-performance bifacial modules to maximize energy yield and long-term reliability.
- Thermoplastic Polyurethane:TPU encapsulants provide excellent abrasion resistance and flexibility, making them suitable for specialized applications requiring enhanced mechanical durability.
- Silicone:Silicone-based encapsulants are valued for their high temperature stability and UV resistance, often used in niche applications or extreme operating environments.
- Laminates:This category includes multi-layer or co-extruded films combining different polymer properties for optimized performance characteristics.
By volume, Ethylene Vinyl Acetate leads. By growth pace, Polyolefin Elastomers are ahead.
Technology:
The specific solar module technology dictates the required performance characteristics of the encapsulant, influencing material selection and overall module design.
- Bifacial:These modules capture sunlight from both front and rear surfaces, necessitating highly transparent and PID-resistant encapsulants for both sides. Bifacial technology is gaining traction in Utility Scale Projects to boost energy output.
- Monofacial:Traditional solar modules capture light from a single side, primarily relying on EVA for front-side encapsulation and a backsheet for the rear. This remains the dominant technology for many residential and commercial installations.
- Tandem:Tandem cell architectures, often combining perovskite with silicon, demand encapsulants with specific optical properties and chemical compatibility for optimal performance.
- Perovskite:Encapsulants for perovskite solar cells must provide exceptional moisture barrier properties and chemical stability to protect the sensitive active layer.
- Thin Film:Thin-film technologies, such as CIGS and CdTe, require specialized encapsulants that are compatible with their flexible substrates and sensitive cell materials.
- Concentrator:Concentrator photovoltaic (CPV) systems utilize lenses to focus sunlight, requiring encapsulants that can withstand higher temperatures and intense UV exposure.
Bifacial technology is expanding most quickly, while Monofacial technology commands the largest installed base.
Application:
The application segment influences both the volume and performance requirements for solar encapsulants, with large-scale projects driving significant demand.
- Residential Installations:These projects typically involve smaller arrays on rooftops, prioritizing cost-effective and durable encapsulants suitable for long-term household energy generation.
- Commercial Systems:Larger than residential but smaller than utility scale, commercial installations on business premises require reliable encapsulants that meet local building codes and performance expectations.
- Utility Scale Projects:These vast solar farms demand massive volumes of encapsulants, where long-term durability, PID resistance, and cost efficiency are paramount. Utility Scale Projects are the largest end-use segment for encapsulants.
- Off-grid Solutions:Remote power systems and portable solar products require encapsulants that offer robust protection against harsh environmental conditions and mechanical stress.
- Agrivoltaics:Combining solar energy generation with agriculture, agrivoltaic systems need encapsulants that are durable and potentially allow for specific light transmission for crop growth.
Utility Scale Projects drive the highest volume demand, while Off-grid Solutions provide specialized, distributed opportunities.
End User:
The type of end user determines procurement patterns, technical specifications, and the overall value chain for solar encapsulation materials.
- Independent Power Producers:These entities develop, own, and operate power generation facilities, making them significant buyers who prioritize long-term module reliability and bankability.
- EPC Contractors:Engineering, Procurement, and Construction contractors are responsible for the design, supply, and installation of solar projects. They influence material selection based on project specifications and cost targets.
- Renewable Energy Cooperatives:These community-owned organizations focus on local energy generation, often seeking cost-effective and environmentally friendly encapsulant solutions.
- Energy Storage Providers:Companies integrating solar with battery storage systems require encapsulants that support high-efficiency modules to optimize overall system performance.
Independent Power Producers represent a major purchasing force, while EPC Contractors mediate material choices for diverse projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extensive national grid infrastructure underwrites global solar energy deployment, influencing encapsulant demand across major markets. Policy frameworks and technological shifts drive material selection for photovoltaic modules. This analysis highlights key growth pockets and regulatory influences.
China
China's vast utility-scale solar projects and dominance in bifacial module production drive immense encapsulant demand. The country's dual carbon goals and GB standards influence polymer formulations. Manufacturing hubs in the Yangtze River Delta concentrate production for global export.
United States
The United States sees strong demand from utility-scale solar farms and a growing residential sector, driven by energy independence. The Inflation Reduction Act (IRA) incentivizes domestic solar manufacturing and deployment. Large-scale solar development in Southwestern states, including California, drives substantial encapsulant consumption.
Germany
Germany's ambitious decarbonization targets and robust rooftop solar market fuel consistent demand for high-performance encapsulants. The EU Green Deal and national EEG policies accelerate renewable energy deployment. Research and manufacturing centers in Bavaria and North Rhine-Westphalia focus on advanced module designs.
India
India's aggressive national renewable energy targets and rural electrification efforts drive significant demand for solar modules. The Production Linked Incentive (PLI) scheme supports domestic solar manufacturing, influencing local material sourcing. Major solar parks in Rajasthan and Gujarat represent large-scale encapsulant consumption.
Japan
Japan's focus on commercial and industrial solar, alongside disaster resilience, creates demand for durable encapsulant solutions. The Ministry of Economy, Trade and Industry (METI) guides solar deployment and material quality standards. Advanced material research and module integration efforts are concentrated in the Kanto region.
Solar Encapsulation Market Key Industry Players
On the supply side, the industry is characterized by a mix of large-scale material producers and specialized solution providers. Production capacity for core polymer resins and finished encapsulants is heavily concentrated in specific Asian geographies, influencing global supply dynamics. Large chemical conglomerates leverage extensive material science capabilities for product differentiation. Smaller, focused companies often target niche applications or specific performance requirements within the solar segment. Competitive moves include strategic partnerships to integrate material development with module manufacturing, alongside continuous innovation in polymer chemistry.
At the scale-driven end, Hangzhou First Applied Material Co., Ltd. exemplifies immense production scale and cost leadership, anchoring a significant portion of the global encapsulant supply. DuPont de Nemours, Inc. represents a major chemical corporation, leveraging its broad material science portfolio to offer differentiated encapsulant products for advanced module designs. Meanwhile, STR Holdings, Inc. occupies a position as a specialist provider, focusing on customized encapsulant solutions tailored for niche applications and specific performance requirements within the solar industry.
| Leading Market Players |
|---|
| STR Holdings, Inc. |
| Mitsui Chemicals, Inc. |
| DuPont de Nemours, Inc. |
| Hangzhou First Applied Material Co., Ltd. |
| Advanced Polymer Technology Corp. |
| First Solar, Inc. |
| SKC Co., Ltd. |
| TPI Polene Power Public Co. Ltd. |
| 3M Company |
| Others |
Cost & Logistics Intelligence
Trans-Pacific shipping lanes' volatile freight costs directly impact the pricing of solar encapsulants, where China's production concentration dictates global material availability. This influences downstream price differentiation for module manufacturers globally.
Pricing Analysis
Volume-based contract pricing structures dominate the solar encapsulant market, with significant discounts offered for large-scale procurement. Price differentiation stems from encapsulant performance grade, international certification levels, and the sheer volume of material purchased. Pricing softness reflects intense competition among suppliers and volatility in raw material costs, particularly for EVA resins. Conventional monofacial module producers in emerging markets exhibit high price sensitivity, while Utility Scale Projects prioritizing long-term reliability for bifacial modules are less price-sensitive.
Supply Chain Analysis
Raw material concentration in China for both EVA and POE resins exposes the solar encapsulant supply chain to significant geopolitical risks and price volatility. Key production hubs for encapsulants are heavily concentrated in China, influencing global material availability and cost structures. Module manufacturers worldwide depend on these Chinese suppliers for essential polymer materials and finished films. Distribution runs primarily through direct-to-manufacturer channels, though module makers increasingly seek integrated suppliers offering differentiated products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar encapsulation market represents a high-growth disruption, driven by the accelerating global transition to renewable energy and the technical shift towards bifacial module adoption. This market demands continuous innovation to meet evolving performance and sustainability requirements.
For Market Incumbents: Pre-empt market share erosion by heavily investing in advanced material science, particularly for hybrid POE/EVA encapsulants that address both cost and performance needs. Expand production capacity in diverse regions outside China to mitigate raw material supply chain concentration risks. Strategic partnerships with key module manufacturers are crucial to co-develop next-generation solutions and secure long-term contracts. Focus on maintaining rigorous international certification standards to differentiate product reliability.
For New Entrants and Emerging Players: Build out specialized product portfolios targeting niche applications like Building-Integrated Photovoltaics (BIPV) and agrivoltaics, where customized solutions command higher value. The market for circular economy formulations presents a significant white-space opportunity, aligning with EU CSRD mandates. Target performance-oriented segments in North America and Europe by offering highly differentiated encapsulants for n-type and bifacial modules. A go-to-market angle focused on superior technical support and rapid certification can accelerate adoption.
For Investors and Strategic Acquirers: Specialized material science firms with proprietary polymer formulations represent attractive acquisition targets for long-term growth in the solar encapsulation market. The industry is poised for strong expansion over the next decade, driven by global renewable energy mandates. Focus investment on companies developing advanced POE and hybrid encapsulants that address durability and PID resistance challenges. The signal to watch is increased adoption of multi-layer co-extruded films by top-tier module manufacturers, indicating a shift towards higher-value material systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for POE | Increases supply resilience outside China and meets growing demand from Utility Scale Projects. |
| Joint Venture with Module Manufacturers | Accelerates co-development of application-specific encapsulants, optimizing performance for bifacial technology. |
| Green Manufacturing Transition | Aligns with EU CSRD and global sustainability mandates, attracting environmentally conscious buyers. |
| Technology Licensing for Hybrid Encapsulants | Captures royalty streams and broadens market access for patented performance-enhancing formulations. |
| Certification Investment for Novel Polymers | Reduces market entry barriers and assures long-term reliability for new material science innovations under IEC 61215. |
Research Approach
Operator-level perspectives from polymer scientists, module manufacturing engineers, EPC procurement managers, and utility project developers anchored the qualitative base for this analysis. This primary research was triangulated with extensive secondary data, including IEC standards documents, EU RoHS directives, China GB standards, and company 10-K filings. A robust bottom-up and top-down approach validated market sizing and growth projections, ensuring comprehensive coverage.
Scenario-bracketing across optimistic, probable, and conservative market conditions informed the quantitative forecast over the projection horizon. The analytical framework modeled market dynamics across product type, technology, application, end user, and geographic region. Compound Annual Growth Rates were derived from a blend of historical growth trends and anticipated shifts in policy and technology. Key forecast inputs included global solar installation forecasts and raw material pricing trends.
Stress conditions across geopolitical stability, raw material supply, and regulatory policy were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding these variables, and unforeseen geopolitical events or abrupt shifts in national energy policies could revise projections. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Smart Solar Solutions Market
Solar Power Systems
PV Solar Data Logger Market
Solar Power Systems
North America Concentrated Solar Power (CSP) Market
Solar Power Systems
Asia-Pacific Solar Concentrator Market
Solar Power Systems
Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Ribbon Market
Solar Power Systems
Global EV Solar Modules Market
Solar Power Systems
Indonesia Renewable Energy Market
Solar Power Systems
Solar Mirror Market
Solar Power Systems
Dual Axis Solar Tracker Market
Solar Power Systems
Off-Grid Solar Generator Market
Solar Power Systems
Solar Photovoltaics Wafer Market
Solar Power Systems
Solar PV Mounting Systems Market
Solar Power Systems
Solar Microgrid Market
Solar Power Systems
United Kingdom Solar Power Market
Solar Power Systems
Building Applied Photovoltaics (BAPV) Market