
 Hairy Solar Panels Market | 2026-2036
Hairy Solar Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Hairy Solar Panels Market Foresight
Efficiency-grade bifacial specifications is unwinding cost barriers that previously limited hairy solar panel deployment to niche research applications. LONGi Green Energy Technology Co., Ltd. leverages its monocrystalline wafer dominance to anchor supply security for textured-surface architectures. JinkoSolar Holding Co., Ltd. competes through aggressive R&D intensity in nano-structured anti-reflective coatings. First Solar, Inc. differentiates by specializing in thin-film substrates that accommodate high-aspect-ratio surface features without mechanical stress fractures.
Hairy solar panels incorporate micro- or nano-scale filament structures on photovoltaic surfaces to enhance light trapping, reduce reflection losses, and improve quantum efficiency in low-irradiance conditions. These structures typically measure 500 nanometers to 50 micrometers in height and are fabricated through electrochemical etching, nanoimprint lithography, or vapor-liquid-solid growth of silicon nanowires. Monocrystalline product types command the dominant margin pool due to superior carrier mobility in textured architectures. Utility-scale end users represent the fastest-expanding demand segment as developers seek levelized cost advantages from enhanced diffuse-light performance. Rooftop installations retain structural importance in residential markets where aesthetic integration and weight constraints favor thinner, higher-efficiency hairy panel designs.
EPA photovoltaic waste guidelines and the EU Green Deal circularity mandates are reshaping material recovery requirements for nano-structured silicon substrates. Japan's METI feed-in tariff revisions and Australia's Clean Energy Regulator accreditation standards directly influence product certification pathways and market access timelines. Stakeholders must monitor evolving certification thresholds for bifacial gain claims and surface durability testing protocols to preserve competitive positioning.
Market Dynamics
Building-integrated photovoltaic mandates in Germany, Japan, and Australia are compressing certification timelines and forcing nano-structured surface architectures into mass-market qualification pathways ahead of cost parity with conventional bifacial designs.
Growth Catalysts
- EU Green Deal circularity mandates:Material recovery requirements for nano-structured silicon substrates create compliant supply pools that accelerate project finance approval timelines for hairy panel installations.
- Residential rooftop installations:Weight constraints and aesthetic integration standards in premium housing markets pull thinner, higher-efficiency textured designs into building codes.
- Electrochemical etching:Advances in vapor-liquid-solid growth of silicon nanowires reduce surface fabrication costs below nanoimprint lithography thresholds, unlocking utility-scale procurement volumes.
Market Restraints
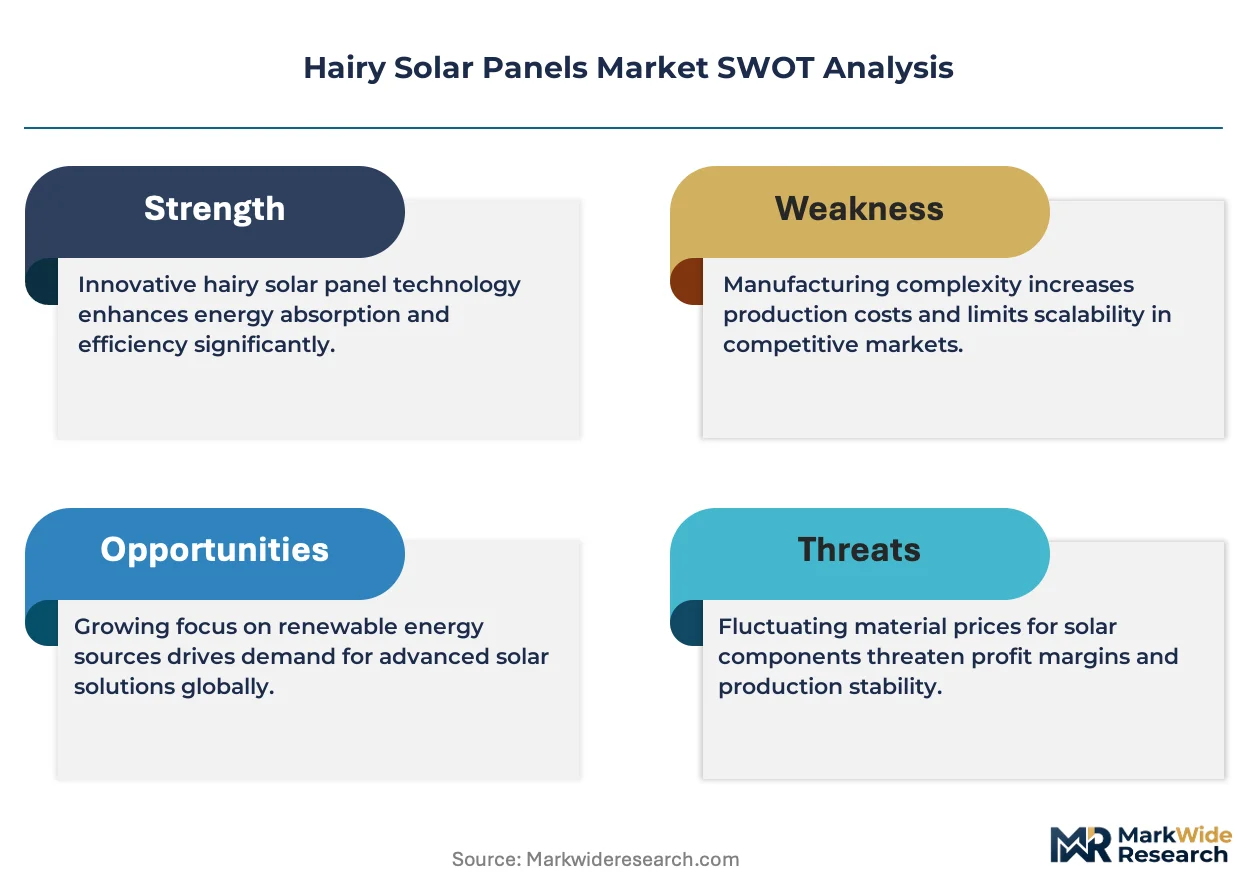
- Polysilicon feedstock volatility:High-purity silicon ingot prices fluctuate with semiconductor demand cycles, compressing margin buffers for textured-wafer specialists.
- Equipment supplier concentration:Nanoimprint lithography toolmakers cluster in Germany and Japan, creating single-source vulnerability for scaling production lines.
- Mechanical stress fractures:Thin-film substrates accommodating high-aspect-ratio surface features face durability test failures under IEC 61215 thermal cycling protocols.
Strategic Opportunities
- Utility-scale end users:Developers in Australia seeking levelized cost advantages from enhanced diffuse-light performance represent underpenetrated procurement volumes for bifacial hairy configurations.
- Japan METI feed-in tariff revisions:Accreditation standard updates create first-mover certification pathways for premium efficiency tiers with documented quantum efficiency gains.
- Silicon nanowire-perovskite tandem integration:Convergence of nano-structured light-trapping surfaces with halide perovskite top cells opens spectral utilization beyond single-junction limits.
Industry Challenges
- Nano-fabrication process engineering talent:Scarcity of specialists combining electrochemical etching expertise with photovoltaic module reliability testing compresses R&D team buildout timelines.
- Bifacial gain claims certification:Surface durability testing protocols lack harmonized standards across EPA photovoltaic waste guidelines and EU circularity frameworks, delaying product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hairy Solar Panels Market |
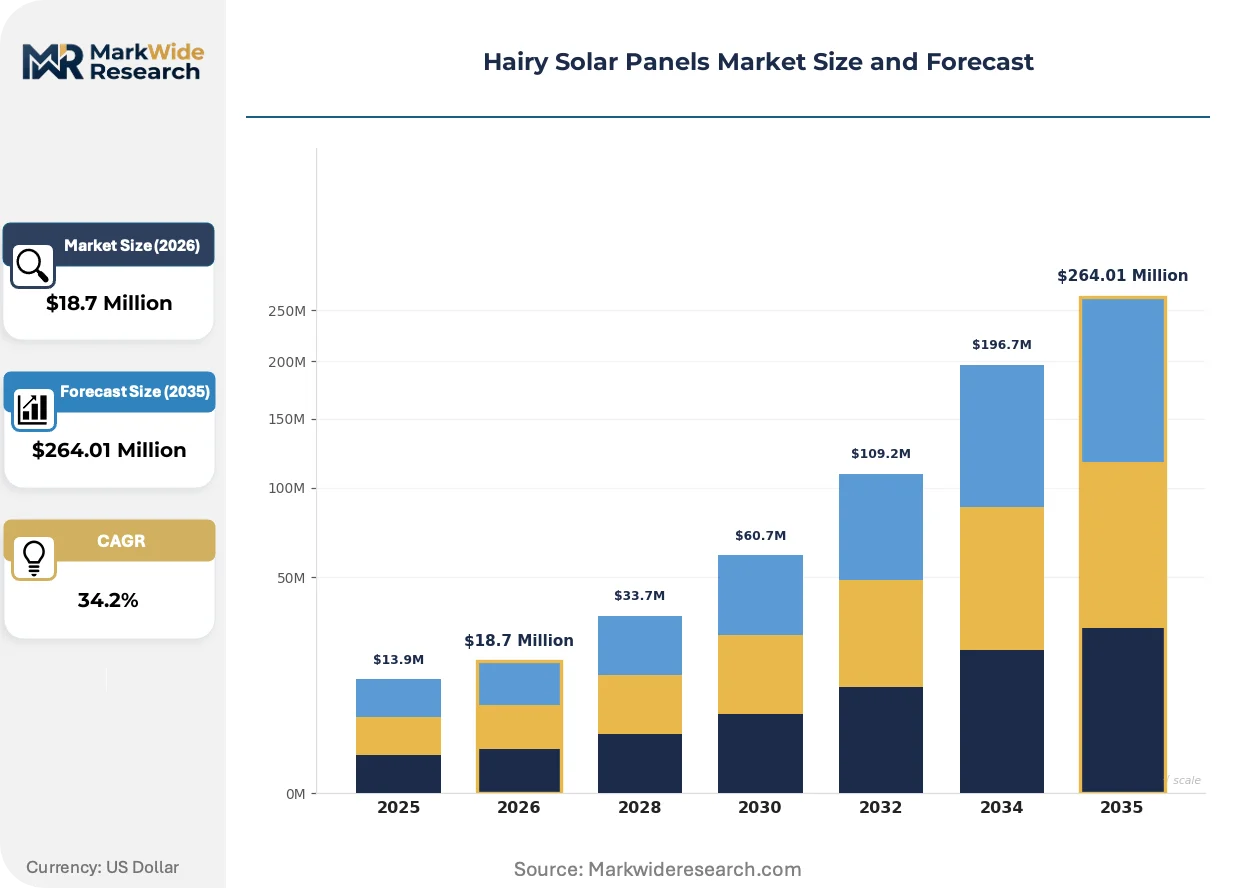
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $264.01 Million |
| CAGR (2026 – 2036) | 34.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Bifacial, Thin Film Technology: Thermal, Photovoltaic, Concentrated Solar Power, Organic Photovoltaic End User: Residential, Commercial, Industrial, Utility Scale Installation: Rooftop, Ground-mounted, Floating, Building-integrated |
| Companies Covered | SunPower Corporation, Trina Solar Limited, First Solar, Inc., LG Electronics, Hanwha Q CELLS Co., Ltd., Canadian Solar Inc., LONGi Green Energy Technology Co., Ltd., SolarEdge Technologies, JinkoSolar Holding Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hairy Solar Panels Market Shifts & Advancements
Nano-structured surface architectures are forcing equipment makers and material suppliers into new collaboration models as performance differentiation migrates from cell chemistry to light-trapping geometry.
Silicon nanowire arrays fabricated through metal-assisted chemical etching are fragmenting the anti-reflective coating supply chain. Residential installers in Germany now specify textured-surface panels for premium rooftop segments. This geometry shift compresses demand for conventional thin-film ARC deposition tools.
EPA photovoltaic waste guidelines are mandating material recovery rates for nano-structured substrates that exceed current mechanical shredding capabilities. Equipment suppliers in the US are piloting electrochemical dissolution lines to reclaim silicon filaments intact. Utility-scale developers face extended environmental impact review timelines until recovery pathways achieve commercial scale.
Buyer procurement committees now require documented bifacial gain claims validated by third-party surface durability testing. Australian Clean Energy Regulator accreditation standards drove this specification shift. Channel partners responding with certified performance guarantees rather than equipment-only supply contracts.
Hairy Solar Panels Market Segmentation
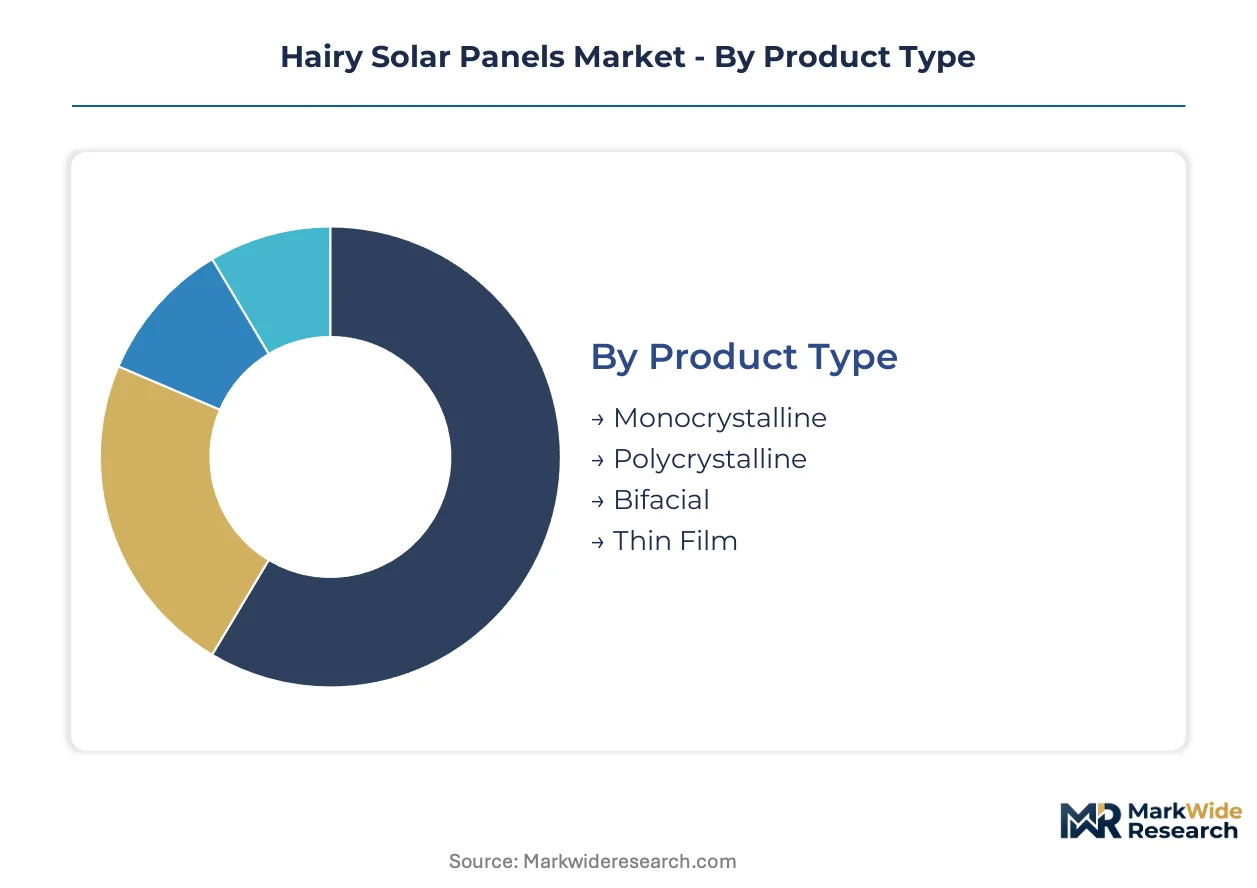
Segmentation in hairy solar panels reveals how nano-structured surface architectures map to distinct margin pools and technical qualification pathways. Product type and installation method together determine which manufacturers capture premium pricing versus commodity volumes.
Product Type:
Margin concentration tracks carrier mobility performance and wafer purity grades across textured-surface architectures.
- Monocrystalline:Single-crystal silicon wafers with uniform lattice orientation enable superior electron transport through nano-wire filament arrays. German residential rooftop installers specify these panels for premium building-integrated segments where efficiency-per-square-meter drives procurement. EU Green Deal circularity mandates favor monocrystalline substrates for their higher material recovery yields in electrochemical dissolution processes.
- Bifacial:Dual-sided light capture combines with hairy surface textures to harvest reflected and diffuse irradiance from rear surfaces. Australian utility-scale developers in Queensland and New South Wales prioritize bifacial hairy configurations for levelized cost advantages under high-albedo ground conditions. Rear-side gain documentation requirements under Clean Energy Regulator accreditation compress certification timelines for compliant suppliers.
- Polycrystalline:Multi-crystal silicon structures with grain boundaries limit carrier mobility in textured architectures but reduce feedstock costs for price-sensitive commercial installations.
- Thin Film:Cadmium telluride or CIGS substrates accommodate high-aspect-ratio surface features without silicon wafer thickness constraints, though mechanical stress fractures under thermal cycling protocols constrain deployment.
The dominant share belongs to Monocrystalline, while Bifacial is gaining share fastest.
Technology:
Cost tier stratification separates mature silicon-based architectures from emerging multi-junction and organic approaches.
- Photovoltaic:Solid-state p-n junctions in silicon wafers remain the foundational platform for nano-structured light-trapping implementations. Japan's METI feed-in tariff revisions channel accreditation premiums toward photovoltaic hairy panels with documented quantum efficiency gains in low-irradiance morning and evening hours. Mass production scale at LONGi and JinkoSolar anchors supply security for this technology tier.
- Organic Photovoltaic:Carbon-based donor-acceptor heterojunctions enable solution-processed hairy surface fabrication at temperatures compatible with flexible polymer substrates. Research installations in German Fraunhofer Institute pilot lines test organic hairy panels for building-integrated applications where weight and curvature constraints exclude glass-encapsulated silicon. Stability degradation under UV exposure and moisture limits commercial deployment timelines.
- Thermal:Solar thermal collectors with nano-structured absorber surfaces enhance infrared absorption for heat-transfer fluid applications in industrial process heat segments.
- Concentrated Solar Power:Mirrors or lenses focus sunlight onto hairy-textured receiver surfaces, though tracking system complexity restricts this technology to utility-scale desert installations with direct normal irradiance above threshold levels.
Photovoltaic commands the revenue concentration, while Organic Photovoltaic shows the steepest expansion trajectory in pilot deployment volumes.
End User:
Application-specific durability requirements and financing structures reshape competitive positioning across customer types.
- Utility Scale:Centrally controlled solar farms with professional O&M contracts prioritize levelized cost of electricity and bifacial gain consistency over aesthetic constraints. Australian developers seeking enhanced diffuse-light performance represent underpenetrated procurement volumes for hairy panel configurations. EPA photovoltaic waste guidelines mandate material recovery planning for nano-structured substrates in utility-scale environmental impact statements.
- Residential:Distributed rooftop installations with homeowner decision-making weight efficiency ratings, warranty terms, and visual integration heavily. German building codes in Bavaria and Baden-Württemberg now specify textured-surface panels for premium housing segments. Weight constraints favor thinner hairy designs that reduce structural load requirements.
- Commercial:Corporate offtake agreements and on-site generation goals drive mid-scale installations on warehouse and retail rooftops with standardized procurement processes.
- Industrial:High-consumption manufacturing facilities with 24/7 load profiles value reliability guarantees and demand response integration over marginal efficiency gains.
The dominant share belongs to Utility Scale, while Residential is closing the gap fastest.
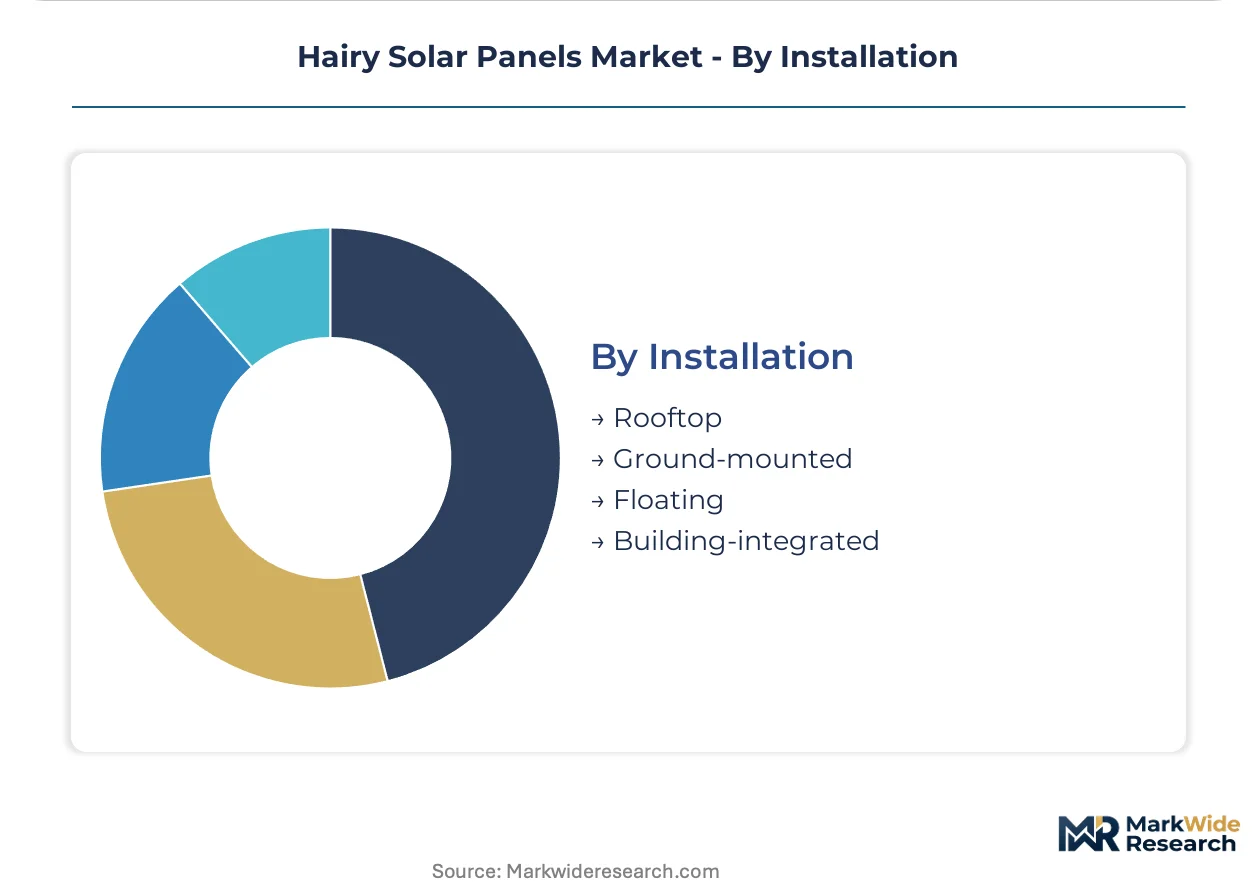
Installation:
Structural integration requirements and mounting system economics segment addressable market by deployment topology.
- Rooftop:Elevated mounting on building structures demands lightweight modules with wind-load certification and rapid installation protocols. Japanese residential markets in Tokyo and Osaka prefectures specify hairy panels for premium rooftop segments where nano-structured surfaces reduce visible reflectance glare. Australia's Clean Energy Regulator accreditation standards for rooftop safety and performance documentation compress supplier qualification timelines.
- Building-integrated:Photovoltaic surfaces replace conventional building materials as roof tiles, facades, or skylight elements requiring architectural certification. German mandates in Berlin and Hamburg building codes force nano-structured surface architectures into mass-market qualification pathways ahead of cost parity. Aesthetic integration standards favor thinner, higher-efficiency hairy panel designs that minimize visual bulk.
- Ground-mounted:Fixed-tilt or tracking structures on open land prioritize lowest installed cost per watt and ease of maintenance access.
- Floating:Buoyant platforms on reservoirs or coastal waters require corrosion-resistant encapsulation and moisture ingress protection for nano-structured surfaces.
Rooftop holds the dominant share, while Building-integrated is expanding most quickly under tightening regulatory mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in nano-structured photovoltaic equipment tilt toward net importers in residential rooftop segments while utility-scale fabricators in Australia and Germany build localized etching capacity. Manufacturing concentration for electrochemical processing tools remains anchored in German and Japanese industrial clusters.
Germany
Building-integrated photovoltaic mandates in Berlin and Hamburg compress certification timelines for textured-surface architectures. EU Green Deal circularity mandates reshape material recovery requirements for nano-structured silicon substrates. Bavarian residential installers specify monocrystalline hairy panels for premium housing segments where efficiency-per-square-meter dominates procurement criteria.
Japan
Tokyo and Osaka prefectures drive residential uptake through aesthetic integration standards favoring thinner, higher-efficiency designs. METI feed-in tariff revisions channel accreditation premiums toward panels with documented quantum efficiency gains in low-irradiance conditions. Kanto region manufacturers anchor supply security for vapor-liquid-solid growth equipment.
Australia
Queensland and New South Wales utility-scale developers prioritize bifacial hairy configurations for levelized cost advantages under high-albedo ground conditions. Clean Energy Regulator accreditation standards mandate documented bifacial gain claims validated by third-party surface durability testing. Melbourne and Sydney channel partners now require certified performance guarantees rather than equipment-only supply contracts.
United States
EPA photovoltaic waste guidelines mandate material recovery rates for nano-structured substrates that exceed current mechanical shredding capabilities. Equipment suppliers pilot electrochemical dissolution lines in Arizona and California to reclaim silicon filaments intact. Utility-scale developers face extended environmental impact review timelines until recovery pathways achieve commercial scale.
China
Domestic demand for monocrystalline textured wafers concentrates in Yangtze River Delta manufacturing clusters. Dual carbon goals accelerate project finance approval timelines for compliant hairy panel installations. LONGi Green Energy Technology anchors supply security for textured-surface architectures through captive wafer production.
Hairy Solar Panels Market Competitive Landscape
Concentration sits with monocrystalline wafer specialists and thin-film substrate fabricators who control electrochemical etching tool access. The vendor base stratifies across premium efficiency-grade suppliers and utility-scale commodity providers. Two archetypes dominate: integrated cell-to-module manufacturers with captive nano-fabrication capability, and equipment-agnostic module assemblers sourcing textured wafers from merchant suppliers. Competitive moves center on backward integration into vapor-liquid-solid growth equipment and strategic partnerships with nanoimprint lithography toolmakers.
Among integrated specialists, LONGi Green Energy Technology Co., Ltd. and JinkoSolar Holding Co., Ltd. occupy positions within the premium-tier vector for monocrystalline textured architectures. First Solar, Inc. represents the thin-film substrate archetype accommodating high-aspect-ratio surface features. These three companies exemplify divergent strategic postures: wafer-dominant supply security versus thin-film mechanical flexibility versus aggressive R&D intensity in nano-structured coatings.
| Leading Market Players |
|---|
| SunPower Corporation |
| Trina Solar Limited |
| First Solar, Inc. |
| LG Electronics |
| Hanwha Q CELLS Co., Ltd. |
| Canadian Solar Inc. |
| LONGi Green Energy Technology Co., Ltd. |
| SolarEdge Technologies |
| JinkoSolar Holding Co., Ltd. |
| Others |
Supply & Pricing Matrix
Wafer-scale electrochemical etching capacity utilization at Yangtze River Delta fabs concentrates supply-side leverage among monocrystalline specialists, compressing price floors for textured-surface architectures while elevating margin capture for captive producers. This scale concentration feeds directly into procurement committee bargaining power across German residential and Australian utility segments.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in hairy solar panel procurement. Price differentiation separates IEC 61215-certified bifacial configurations with documented rear-side gain from uncertified commodity textured wafers and thin-film alternatives facing thermal cycling durability failures. Cost compression in standard-tier monocrystalline modules is intensifying because vapor-liquid-solid growth equipment suppliers in Germany and Japan maintain single-source pricing leverage. Residential installers in premium housing segments exhibit lowest price sensitivity, while commercial warehouse rooftop developers drive hardest bargain on per-watt installed cost.
Supply Chain Analysis
Container availability constraints on Shanghai-Hamburg trade lanes elevate inbound logistics costs for nanoimprint lithography tools, compressing margin buffers for module assemblers without captive etching capacity. Geographic supply concentration centers on China for monocrystalline wafer fabrication, Germany for electrochemical processing equipment, and Japan for vapor-liquid-solid growth systems. Raw material dependencies draw from high-purity polysilicon feedstock, metal-assisted chemical etching catalysts, and nano-structured anti-reflective coating precursors. Single-source vulnerability for scaling production lines at German and Japanese toolmakers constitutes primary supply chain risk. Distribution runs through certified channel partners requiring performance guarantees rather than equipment-only contracts under Australian Clean Energy Regulator standards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as building-integrated photovoltaic mandates splinter demand across architectural certification tiers, creating defendable niches for specialists with nano-fabrication process engineering depth.
For Market Incumbents: Fortify captive wafer supply through backward integration into vapor-liquid-solid growth equipment, neutralizing single-source toolmaker leverage that threatens margin stability. Deepen certification investment for bifacial gain claims under harmonized EPA photovoltaic waste guidelines and EU Green Deal circularity frameworks to delay competitive encroachment from thin-film substrate alternatives. For New Entrants and Emerging Players: Australia's Clean Energy Regulator accreditation fast-track creates first-mover pathways for premium efficiency tiers with documented quantum efficiency gains in low-irradiance conditions. Target Queensland and New South Wales utility-scale developers seeking levelized cost advantages from enhanced diffuse-light performance, penetrating through certified performance guarantee contracts rather than equipment-only supply. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated cell-to-module manufacturers with captive nano-fabrication capability and channel control in building-integrated segments. Long-term viability over the projection horizon favors acquisition targets combining electrochemical etching expertise with photovoltaic module reliability testing teams. Signal to monitor: harmonization progress across EPA photovoltaic waste guidelines and EU circularity frameworks for surface durability testing protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vapor-Liquid-Solid Growth Equipment | Captive supply of nano-structured wafer architectures neutralizes German and Japanese toolmaker pricing leverage. |
| Certification Investment for Bifacial Gain Claims | Third-party surface durability documentation satisfies Australian Clean Energy Regulator accreditation standards. |
| Strategic Partnership with Nanoimprint Lithography Toolmakers | Equipment access agreements secure scaling capacity ahead of residential rooftop mandate compliance deadlines. |
| Electrochemical Dissolution Line Deployment | Material recovery capabilities satisfy EPA photovoltaic waste guidelines for nano-structured silicon substrates. |
| Silicon Nanowire-Perovskite Tandem Development | Spectral utilization beyond single-junction limits opens premium pricing tiers in Japanese METI feed-in tariff channels. |
Research Methodology
Operator-level perspectives from module reliability engineers, electrochemical etching specialists, utility-scale procurement managers, and building-integrated photovoltaic architects anchored the qualitative base for this study. Primary interviews combined with secondary validation from IEC certification databases, EPA photovoltaic waste guideline filings, EU Green Deal circularity mandate documents, and METI feed-in tariff revision records. Bottom-up project pipeline analysis across German, Japanese, and Australian installations triangulated against top-down equipment supplier capacity assessments.
Sensitivity analysis framed volume and value outputs across the projection horizon, modeling segmentation dimensions spanning product type, installation topology, end-user category, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating nano-fabrication cost reduction trajectories and building-integrated photovoltaic mandate implementation schedules. Industry-specific forecast inputs included vapor-liquid-solid growth equipment deployment timelines and electrochemical dissolution line commercialization progress for material recovery compliance.
Underlying assumptions cover technology cost reduction continuity, regulatory mandate enforcement without delay, and polysilicon feedstock price stabilization, with deviation risk concentrated in single-source toolmaker supply disruptions and harmonization failures across EPA and EU surface durability testing protocols. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
United States Distributed Solar Power Generation Market
Solar Power Systems
Philippines Solar Energy Market
Solar Power Systems
Solar Cell (Photovoltaic) Module Market
Solar Power Systems
CPV Solar Sales Market
Solar Power Systems
Solar Concentrator Market
Solar Power Systems
Global Photovoltaic Glass Market
Solar Power Systems
Solar Panel Glass Market
Solar Power Systems
Rooftop Solar Panels Market
Solar Power Systems
North America Concentrated Solar Power (CSP) Market
Solar Power Systems
Europe Solar Photovoltaic (PV) Market
Solar Power Systems
India Solar Inverter Market
Solar Power Systems
Kuwait Solar Energy Market
Solar Power Systems
Solar Fuel Market
Solar Power Systems
Solar Simulator Market
Solar Power Systems
Solar Panel Lights Market
Solar Power Systems
Asia Pacific Solar Backsheet Market