
 China Hybrid Electric Vehicle Battery Market | 2026-2036
China Hybrid Electric Vehicle Battery Market Size, Share, and Industry Trends Forecast 2026-2036
China Hybrid Electric Vehicle Battery Market Insights
Direct supply contracts between cell makers and domestic OEMs is reconfiguring how hybrid battery volumes flow into vehicle assembly. Contemporary Amperex Technology Co. Limited leverages its Ningdao production base to anchor cathode supply security for hybrid programs. BYD Company controls the full stack from cell to vehicle, sustaining cost advantages that competitors struggle to match. Gotion High-Tech specializes in LFP formulations for cost-sensitive hybrid platforms, positioning itself as a secondary source for volume brands.
A hybrid electric vehicle battery combines electrochemical cells with power electronics to store and discharge energy across partial electric-only propulsion cycles, typically operating at voltages between 100 and 300 volts depending on hybrid architecture. The battery enables torque assist, regenerative braking recovery, and engine-off coasting to reduce fuel consumption in conventional drivetrains. Lithium-ion chemistry dominates installed capacity due to superior energy density and cycle life versus nickel-metal hydride alternatives, though solid-state prototypes promise thermal safety improvements. Passenger car applications generate the largest revenue pool, while commercial vehicle segments attract margin premiums from durability requirements and fleet uptime guarantees.
MIIT sets mandatory energy density thresholds and recycling accountability under China's new energy vehicle regulatory framework, while GB standards define safety testing protocols for cell-level thermal runaway containment. SAMR enforces market access rules that favor domestic suppliers with certified production lines, tightening qualification timelines for foreign cell makers. Stakeholders must monitor how Beijing adjusts subsidy taper schedules and dual carbon enforcement mechanisms to anticipate procurement volume shifts.
Market Dynamics
Direct supply contracts between cell makers and domestic OEMs is reconfiguring how hybrid battery volumes flow into vehicle assembly, compressing qualification timelines and locking in cathode supply security for multi-year programs.
Growth Catalysts
- Fleet electrification mandates:Urban logistics operators under MEE dual carbon enforcement are expanding hybrid powertrain procurement to meet emissions targets without full infrastructure dependency.
- LFP chemistry maturation:Cost-sensitive hybrid platforms are adopting lithium iron phosphate formulations that trade energy density for thermal stability and cycle longevity in stop-start duty cycles.
- Yangtze River Delta clustering:Shanghai-centered manufacturing concentration enables just-in-time cell delivery to assembly plants, reducing working capital requirements for volume brands.
Market Restraints
- Cathode metal volatility:Lithium and nickel price swings transmit directly into cell cost structures, eroding margin visibility for multi-year OEM contracts.
- Foreign supplier exclusion:SAMR certification timelines favor domestic production lines, structurally limiting qualified capacity from non-Chinese cell makers.
- Nickel-metal hydride legacy:Mature NiMH systems in Toyota hybrid architectures constrain lithium-ion penetration in certain cost-optimized vehicle segments.
Strategic Opportunities
- Commercial vehicle uptime guarantees:Durability-focused fleet contracts for urban delivery vans command margin premiums unavailable in passenger car volume plays.
- Solid-state prototyping:Thermal safety improvements from ceramic electrolyte research promise to unlock higher voltage architectures for next-generation hybrid systems.
- GB standards harmonization:Unified cell-level thermal runaway testing protocols under MIIT frameworks reduce redundant certification costs for multi-platform suppliers.
Industry Challenges
- Power electronics integration:Synchronizing battery management systems with engine control units requires embedded software expertise scarce in traditional cell engineering teams.
- Recycling accountability compliance:MIIT mandatory energy density thresholds bundle end-of-life recovery obligations that demand new reverse logistics infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Hybrid Electric Vehicle Battery Market |
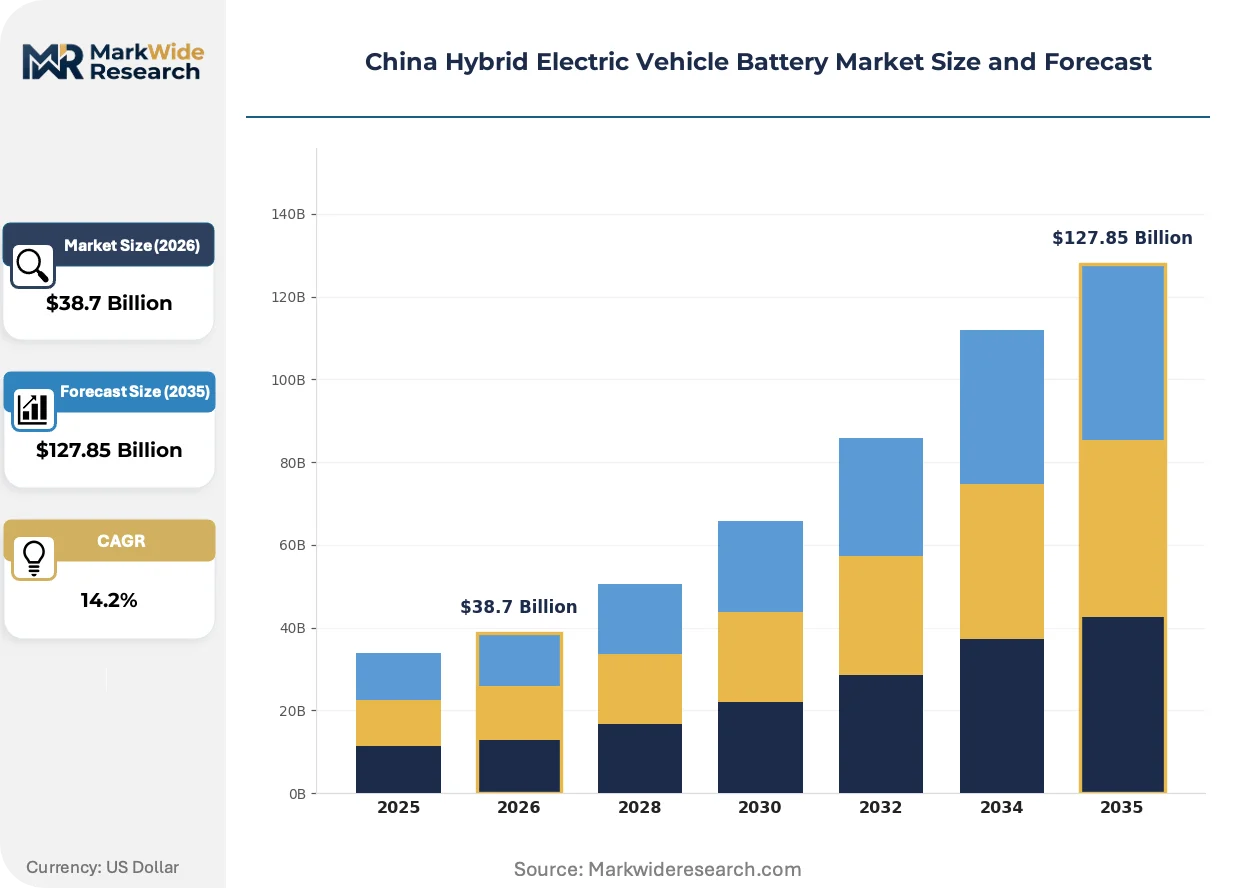
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-ion, Nickel-metal Hydride, Lead-acid, Solid-state Application: Passenger Cars, Commercial Vehicles, Two-wheelers, Buses Manufacturing Stage: Cell Production, Module Assembly, Pack Integration, End-of-life Processing End User: OEMs, Aftermarket Providers, Fleet Operators, Government Agencies |
| Companies Covered | Contemporary Amperex Technology Co. Limited, BYD Company, LG Energy Solution Ltd, Panasonic Holdings Corporation, Toshiba Corporation, China Aviation Battery Co. Ltd., EVE Energy Co. Ltd., SVOLT Energy Technology Co. Ltd., Gotion High-Tech, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Hybrid Electric Vehicle Battery Market Trends and Innovations
Cell-to-pack architectures and silicon-anode prototyping are compressing system cost curves while regulatory pressure on thermal safety accelerates chemistry diversification beyond conventional lithium-ion.
Silicon-doped graphite anodes are hybridizing conventional lithium-ion energy density limits by replacing carbon matrices with silicon composites that accommodate tenfold lithium ion storage. Passenger car platforms from domestic OEMs are piloting these materials in 2024 model year hybrid programs. The technology is hybridizing cost-performance tradeoffs that previously forced a binary choice between energy density and cycle stability.
MIIT energy density mandates are tightening qualification thresholds for new energy vehicle subsidy eligibility, forcing cell makers to prioritize high-nickel cathode chemistries. Domestic suppliers with captive precursor refining are securing preferential SAMR market access. Commercial vehicle segments face compressed compliance timelines as dual carbon enforcement mechanisms phase in stricter fleet-average emissions accounting.
Fleet procurement departments are consolidating supplier rosters around vertically integrated cell makers capable of warranty-backed uptime commitments. Direct OEM-cell maker partnerships are displacing tiered distributor networks that previously managed inventory risk. This concentration is most visible in Yangtze River Delta logistics hubs where municipal clean-air deadlines accelerate contract finalization.
China Hybrid Electric Vehicle Battery Market Segmentation
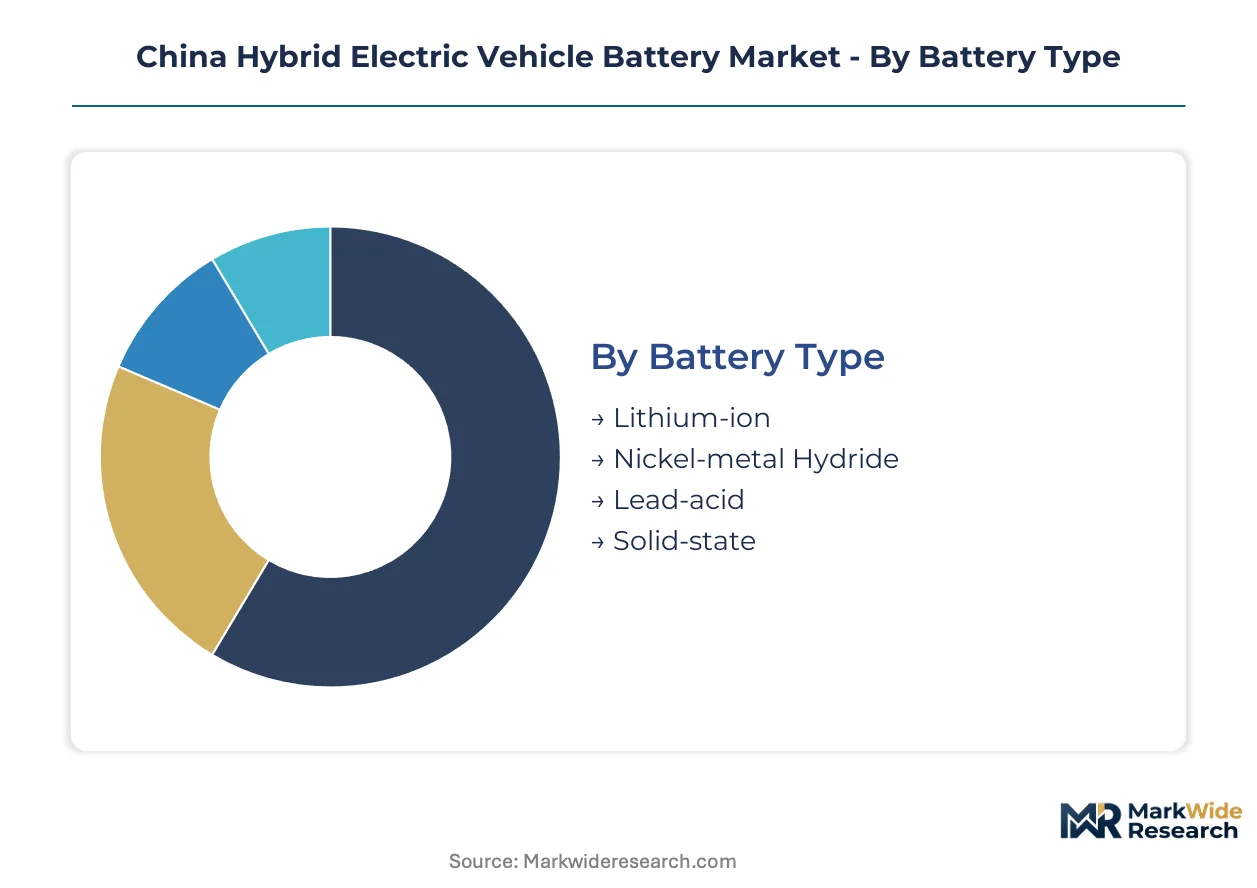
China's hybrid battery market fragments across chemistry choices, vehicle architectures, and supply chain positions that determine margin capture and regulatory compliance pathways. Segment boundaries shift as MIIT energy density mandates and dual carbon enforcement reshape procurement priorities across the Yangtze River Delta manufacturing cluster.
Battery Type:
Use-case spectrum spans from cost-optimized urban logistics to premium thermal safety requirements in high-voltage architectures.
- Lithium-ion:Dominant chemistry utilizing nickel-manganese-cobalt and lithium iron phosphate cathodes, delivering 150-250 Wh/kg energy density for passenger car torque assist and regenerative braking. Yangtze River Delta OEMs concentrate procurement here due to mature supply chains and SAMR-certified domestic cell capacity.
- Nickel-metal Hydride:Mature electrochemical system with proven cycle stability in stop-start duty cycles, retaining cost advantages in price-sensitive hybrid platforms where energy density requirements remain modest. Toyota hybrid architectures in China continue sourcing NiMH for select volume models.
- Lead-acid:Auxiliary power applications in mild-hybrid systems and legacy vehicle electrification retrofits.
- Solid-state:Prototype ceramic electrolyte designs targeting thermal runaway elimination for next-generation high-voltage hybrid architectures.
The dominant share belongs to Lithium-ion, while Solid-state is closing the gap fastest on safety-driven R&D investment.
Application:
Volume concentration maps directly to fleet electrification mandates and municipal clean-air deadlines across Chinese urban centers.
- Passenger Cars:Largest revenue pool spanning compact hybrids to full-hybrid sedans, with dual carbon goals from MEE accelerating OEM powertrain diversification. Shanghai and Shenzhen municipal procurement incentives favor hybrid passenger platforms lacking full charging infrastructure.
- Commercial Vehicles:Urban delivery vans and light trucks command margin premiums through durability-focused uptime guarantees, with fleet operators consolidating supplier rosters around vertically integrated cell makers capable of warranty-backed service commitments.
- Two-wheelers:Cost-optimized LFP configurations for electric-assisted bicycles and delivery scooters.
- Buses:Municipal transit electrification programs with standardized pack specifications for route predictability.
Passenger Cars anchor current volume, though Commercial Vehicles exhibit the steepest expansion trajectory on fleet procurement consolidation.
Manufacturing Stage:
Margin capture shifts downstream as direct OEM-cell maker partnerships displace tiered distributor networks.
- Cell Production:Electrochemical manufacturing of cathodes, anodes, and electrolyte assembly, representing the highest capital intensity and IP concentration. Ningdao and Ningbo production bases anchor cathode supply security for hybrid programs serving domestic OEMs.
- Module Assembly:Intermediate cell grouping with basic battery management integration, positioned between commodity cell supply and differentiated pack design.
- Pack Integration:Final system assembly incorporating thermal management, power electronics, and vehicle-specific form factors.
- End-of-life Processing:MIIT-mandated recycling accountability driving new reverse logistics infrastructure for material recovery.
Cell Production commands structural margin advantages, while Pack Integration is gaining share fastest on power electronics integration requirements.
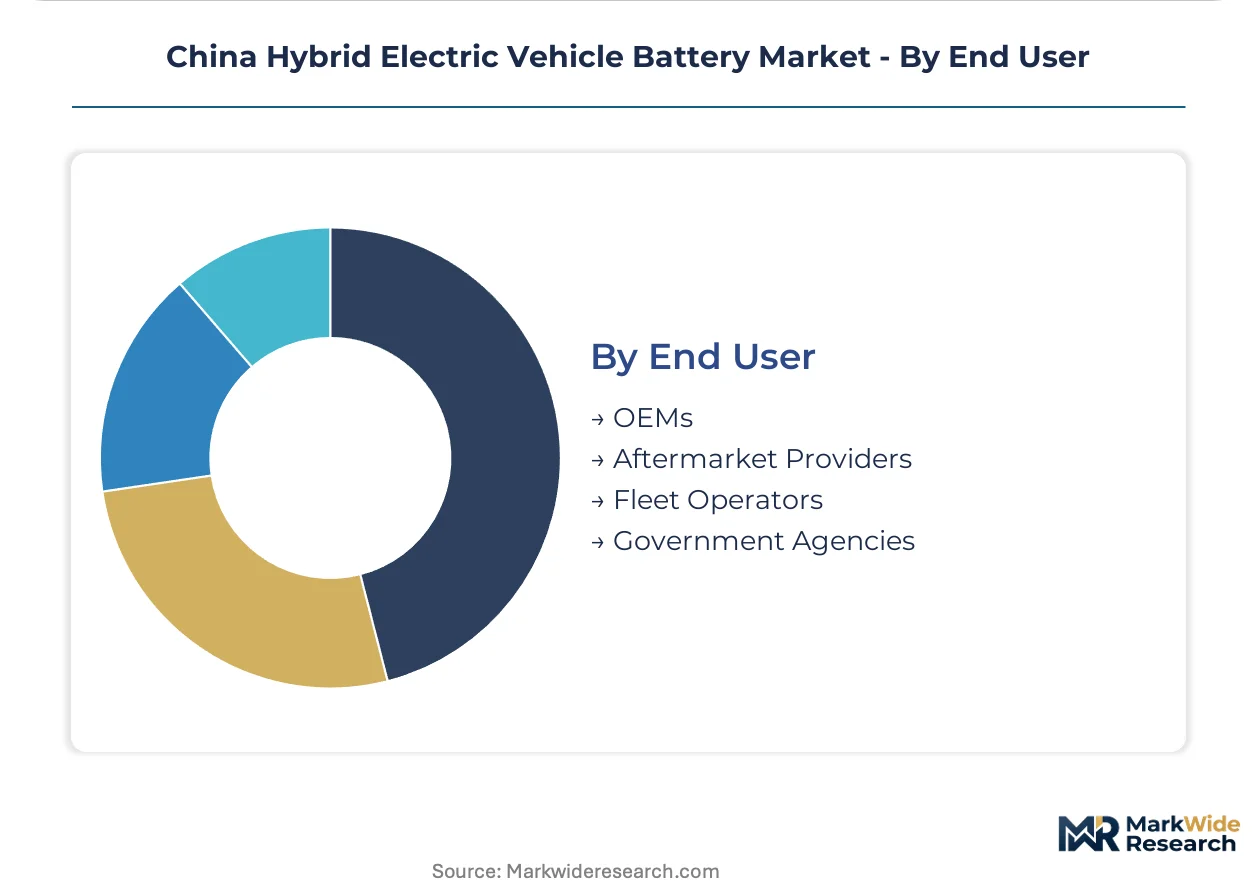
End User:
Procurement authority concentrates around entities with multi-year volume commitments and regulatory compliance obligations.
- OEMs:Direct supply contracts compressing qualification timelines and locking in cathode supply security for multi-year hybrid programs, with BYD and domestic volume brands controlling the full stack from cell to vehicle.
- Fleet Operators:Urban logistics entities under MEE dual carbon enforcement expanding hybrid powertrain procurement to meet emissions targets without full infrastructure dependency.
- Aftermarket Providers:Replacement pack sourcing for out-of-warranty hybrid vehicles and legacy fleet retrofits.
- Government Agencies:Municipal transit authorities and procurement departments setting clean-air deadlines that accelerate contract finalization.
OEMs retain the dominant procurement position, while Fleet Operators are expanding their share fastest on electrification mandate compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT energy density mandates and dual carbon enforcement from MEE are redistributing hybrid battery procurement across China's manufacturing belt. Municipal clean-air deadlines in tier-one cities accelerate contract finalization with cell makers possessing SAMR-certified production lines.
Yangtze River Delta
Shanghai-centered demand concentrates around urban logistics fleet operators meeting MEE emissions targets without full charging infrastructure. GB standards for cell-level thermal runaway containment shape procurement qualification timelines. Ningbo and Ningdao production bases anchor cathode supply security for domestic OEM hybrid programs serving this cluster.
Pearl River Delta
Shenzhen municipal incentives favor hybrid passenger platforms lacking residential charging penetration. SAMR market access rules tighten qualification windows for foreign cell makers relative to domestic suppliers. Guangzhou assembly plants source LFP configurations from vertically integrated cell makers capable of warranty-backed uptime commitments.
Beijing-Tianjin-Hebei
Capital region fleet electrification mandates drive commercial vehicle hybrid powertrain procurement for urban delivery compliance. MIIT recycling accountability obligations bundle end-of-life recovery requirements into OEM contracts. Tianjin port logistics hubs consolidate supplier rosters around cell makers with captive precursor refining capabilities.
Sichuan-Chongqing
Western China manufacturing expansion attracts secondary sourcing arrangements from volume brands seeking cost-sensitive LFP supply. Dual carbon enforcement mechanisms phase in stricter fleet-average emissions accounting for municipal transit operators. Chengdu assembly plants pilot silicon-anode prototyping for 2024 model year hybrid programs.
Shandong Peninsula
Qingdao and Yantai industrial zones host module assembly operations positioned between commodity cell supply and differentiated pack integration. Provincial clean-air deadlines accelerate contract finalization with suppliers possessing GB-certified thermal management systems. Jinan-based fleet operators expand hybrid procurement to meet MEE dual carbon targets without infrastructure dependency.
China Hybrid Electric Vehicle Battery Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated domestic specialists and foreign cell makers with SAMR-certified production lines. Tiered competitive positioning separates full-stack controllers from component-focused suppliers. Three archetypes dominate: captive OEM-affiliated producers, independent merchant cell makers, and foreign technology licensors. Capacity expansion and direct OEM supply contract lock-ins represent the dominant competitive moves compressing qualification timelines.
Among domestic full-stack specialists, BYD Company exemplifies the captive OEM-affiliated archetype through in-house production spanning cell to vehicle assembly. Contemporary Amperex Technology Co. Limited anchors the independent merchant tier with Ningdao-based cathode supply security for multi-year hybrid programs. LG Energy Solution Ltd represents foreign technology licensors navigating SAMR certification timelines that structurally favor domestic production lines.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co. Limited |
| BYD Company |
| LG Energy Solution Ltd |
| Panasonic Holdings Corporation |
| Toshiba Corporation |
| China Aviation Battery Co. Ltd. |
| EVE Energy Co. Ltd. |
| SVOLT Energy Technology Co. Ltd. |
| Gotion High-Tech |
| Others |
Pricing and Supply Chain Analysis
Overcapacity signals from Yangtze River Delta cathode plants are forcing cell makers into extended payment concessions while compressing spot-market premiums for LFP formulations. MIIT energy density mandates intensify price competition as domestic OEMs leverage qualified supplier abundance to renegotiate multi-year contract terms.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with fleet operators commanding steeper concessions than passenger car OEMs due to aggregate pack commitments. Pricing stratifies across premium high-nickel cathode grades, standard LFP configurations, and economy-tier NiMH replacements for legacy platforms. Cost compression in standard-tier LFP cells is intensifying because Gotion High-Tech and secondary suppliers are absorbing margin erosion to secure SAMR-certified volume slots. Fleet operators exhibit highest price sensitivity, while premium hybrid architectures for luxury OEMs show lowest elasticity due to thermal safety certification requirements.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are proliferating as supplier-financing instruments, with Ningbo-based cathode refiners offering supply-chain finance facilities to lock in OEM allocation. Geographic supply concentration centers on China, South Korea, and Japan, with domestic Chinese capacity controlling over 80% of qualified hybrid cell output. Raw material dependencies rest on Australian spodumene concentrate, Indonesian nickel matte, and domestic Chinese graphite anode supply. Single-source vulnerability around high-purity lithium hydroxide from Qinghai brine operations poses structural risk. Distribution runs through direct OEM-cell maker partnerships that displace tiered distributor networks across Yangtze River Delta assembly corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's hybrid battery market is entering a cyclical recovery phase as MIIT subsidy taper schedules and dual carbon enforcement create replacement demand waves. Cathode metal price stabilization and LFP chemistry maturation are restoring margin visibility for qualified suppliers.
For Market Incumbents: Harden cathode supply security through backward integration into Qinghai lithium brine or Indonesian nickel processing assets. Lock multi-year offtake agreements with Yangtze River Delta fleet operators before municipal clean-air deadlines compress qualification windows. Solid-state prototyping R&D represents the critical defensive lever against emerging ceramic electrolyte specialists threatening next-generation thermal safety positioning.
For New Entrants and Emerging Players: Western China manufacturing corridors around Chengdu and Chongqing offer underpenetrated white-space for cost-sensitive LFP supply to secondary domestic OEMs. Commercial vehicle uptime guarantee contracts for urban delivery fleets provide the most penetrable segment due to incumbent capacity constraints on durability-focused cell testing. A go-to-market angle anchored in silicon-anode prototyping partnerships with Sichuan-based OEM pilot programs accelerates SAMR certification timelines.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated cell makers with captive precursor refining and direct OEM supply contracts spanning the analysis window. Long-term viability favors suppliers with backward integration into lithium and nickel feedstocks rather than merchant cathode purchasers exposed to commodity volatility. The signal to watch is MIIT adjustments to energy density thresholds that would force accelerated chemistry transitions and stranded capacity risks for LFP-heavy portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Precursor Backward Integration | Captive refining of lithium hydroxide and nickel sulfate insulates margin from SAMR-qualified supply constraints. |
| Solid-State Ceramic Electrolyte R&D Partnership | Thermal runaway elimination unlocks higher voltage architectures for next-generation hybrid systems under GB standards. |
| Fleet Operator Direct Supply Contract | Warranty-backed uptime commitments for urban logistics command premium pricing unavailable in passenger car volume plays. |
| Silicon-Anode Pilot Production Scale-Up | Tenfold lithium ion storage density from silicon-doped graphite hybridizes cost-performance tradeoffs for 2024 model year programs. |
| MIIT-Certified Recycling Infrastructure Buildout | Mandatory end-of-life recovery obligations under dual carbon enforcement create new revenue streams from reverse logistics. |
Research Methodology
The analysis maps lithium-ion, nickel-metal hydride, and solid-state battery sub-sectors, each validated through OEM platform engineers, fleet procurement directors, and cathode refining specialists. Primary interviews with SAMR certification officers, MIIT policy researchers, and Yangtze River Delta logistics operators combined with secondary validation from customs trade data, MIIT new energy vehicle registration databases, and GB standards documentation. Bottom-up cell production capacity estimates triangulated against top-down vehicle production forecasts across the projection horizon.
Assumption sets held MIIT energy density thresholds and dual carbon enforcement mechanisms fixed while varying cathode metal price trajectories and fleet electrification mandate compliance rates. Segmentation dimensions modeled include battery chemistry type, vehicle application class, manufacturing stage depth, and end-user procurement authority. CAGRs derived from weighted average of historical volume trends and forward-looking OEM platform announcements. Industry-specific forecast inputs incorporated silicon-anode pilot timelines and solid-state prototype commercialization pathways.
Practitioners should monitor MIIT subsidy taper adjustments, lithium carbonate spot price movements, and SAMR certification backlog durations for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Asia-Pacific LFP Battery Pack Market
EV Batteries
Europe Electric Vehicle Solid State Battery Market
EV Batteries
Spain Rechargeable Battery Market
EV Batteries
Asia Pacific Electric Vehicle Battery Manufacturing Market
EV Batteries
Italy Electric Vehicle Battery Electrolyte Market
EV Batteries
United States Electric Vehicle Battery Materials Market
EV Batteries
Asia-Pacific Electric Vehicle Solid State Battery Market
EV Batteries
Europe Electric Vehicle Battery Manufacturing Market
EV Batteries
Cobalt Powder for EV Battery Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Europe Electric Bus Battery Pack Market
EV Batteries
EV Battery Water Cold Plates Market
EV Batteries
Italy Electric Vehicle Battery Manufacturing Market
EV Batteries
Middle-East and Africa Electric Vehicle Battery Anode Market
EV Batteries
Europe Electric Vehicle Battery Electrolyte Market
EV Batteries
South America Electric Vehicle Battery Manufacturing Market