
 Thin-Film Photovoltaic Market | 2026-2036
Thin-Film Photovoltaic Market Size, Share, and Industry Trends Forecast 2026-2036
Thin-Film Photovoltaic Market Intelligence
A performance divergence between high-efficiency tandem cells and commodity amorphous silicon films is repositioning the market's value proposition. First Solar leverages its scale in Cadmium Telluride production for utility-grade projects. Oxford Photovoltaics specializes in developing next-generation perovskite-on-silicon tandem cells for premium applications. Meanwhile, Kaneka Corporation competes with a portfolio that includes flexible amorphous silicon technologies for niche uses.
Thin-film photovoltaics are second-generation solar cells made by depositing one or more thin layers of photovoltaic material onto a substrate. These devices, often just a few micrometers thick, convert sunlight into electricity and are suited for applications requiring flexibility or low weight. Among product types, perovskite cells represent the fastest-growing segment due to rapid efficiency gains. Building-integrated power applications command significant investment, particularly for commercial facilities seeking aesthetic and functional energy solutions.
Regulations like Europe's RoHS directive restrict hazardous substances in electronic components, influencing material choices for manufacturers. In the United States, EPA rules governing manufacturing emissions and waste disposal add compliance costs for domestic producers. The ability to scale production of next-generation materials like perovskites while navigating evolving environmental health and safety standards will determine future market leadership.
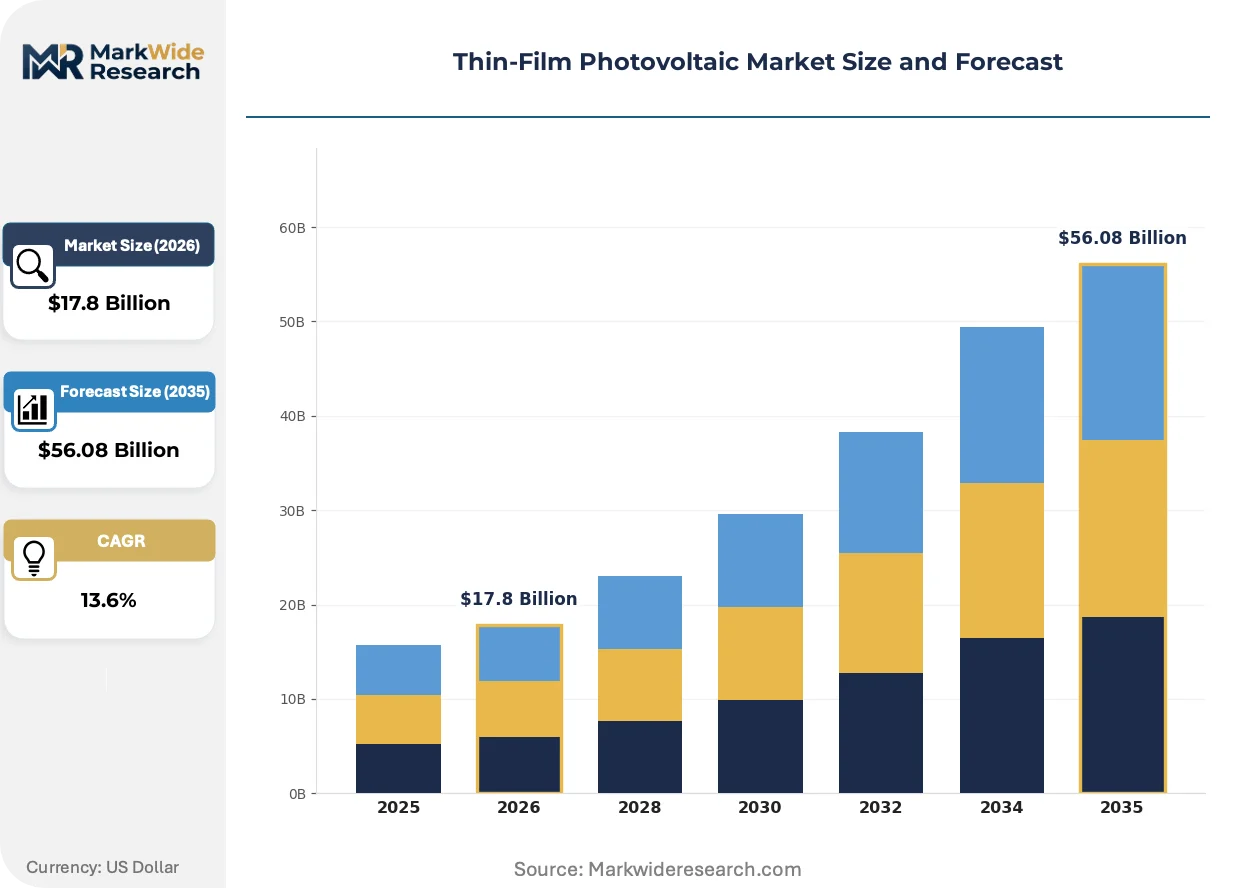
Market Dynamics
The advancement of novel photovoltaic materials is the central force creating a performance-based stratification in the market. This divergence separates high-efficiency tandem cells, designed for premium applications, from established commodity films used in large-scale utility projects.
Growth Catalysts
- Perovskite Efficiency:Rapid improvements in the power conversion efficiency of perovskite solar cells are unlocking new performance tiers, attracting significant research and development investment for next-generation devices.
- National Climate Policies:China's dual carbon goals are driving massive public and private investment in utility-scale solar farms, creating sustained demand for cost-effective thin-film modules like Cadmium Telluride.
- Building-Integrated Photovoltaics:The architectural sector's demand for aesthetic energy solutions is fueling adoption in commercial building facades and roofing, where thin-film's flexibility and appearance offer distinct advantages.
Market Restraints
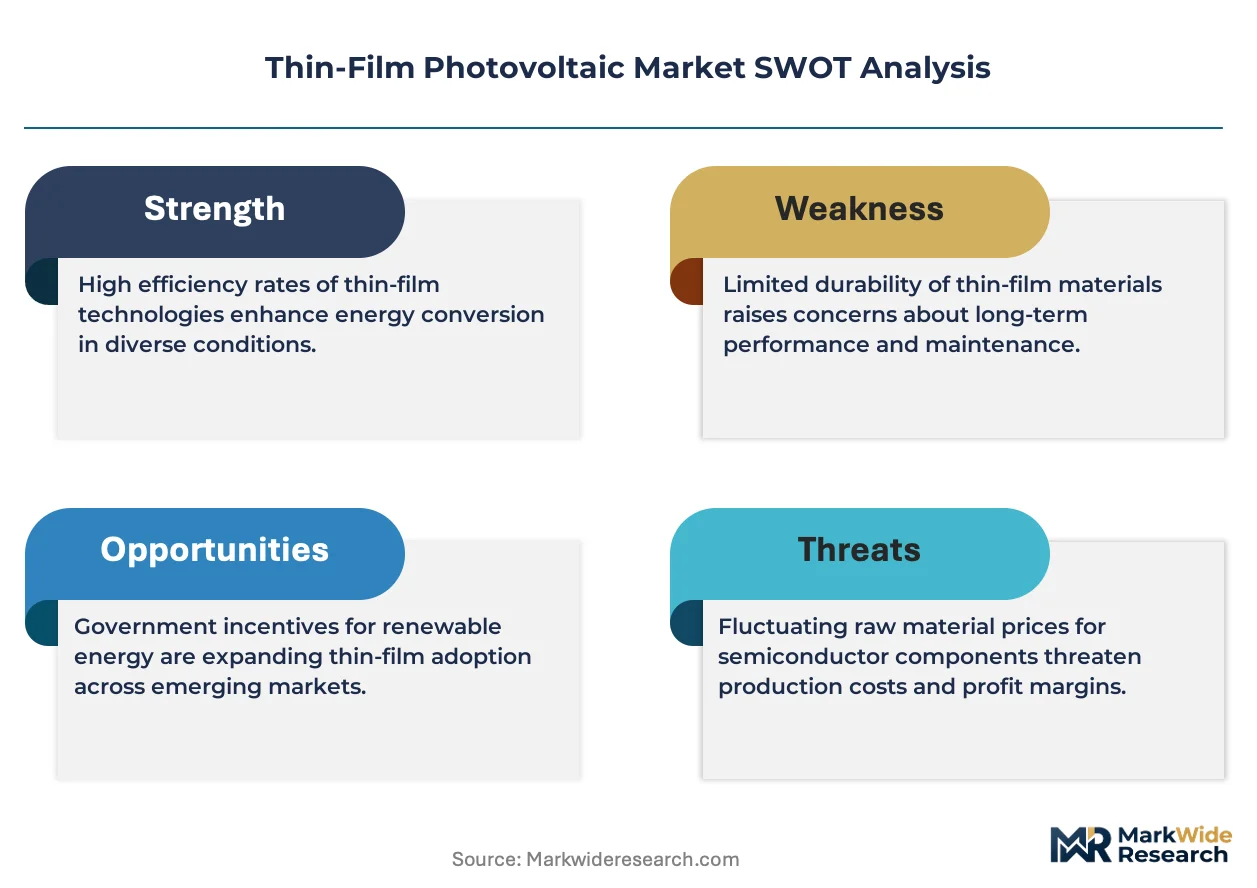
- Regulatory Material Restrictions:Europe's RoHS directive limits the use of hazardous substances like cadmium, compelling manufacturers targeting the EU market to invest in alternative materials or complex compliance and recycling programs.
- Material Degradation:The long-term operational stability and susceptibility to moisture-induced degradation of emerging materials, particularly perovskites, remain significant technical barriers to widespread commercial deployment.
- Input Supply Concentration:The global supply of tellurium, a critical raw material for CdTe cells, is concentrated in a few countries, creating price volatility and supply chain risks for producers.
Strategic Opportunities
- Flexible Electronics Integration:The inherent flexibility of amorphous silicon and organic photovoltaics creates opportunities in emerging applications such as portable power for military use, electronic textiles, and Internet of Things sensors.
- Tandem Cell Architectures:Combining perovskite layers with conventional silicon cells to create perovskite-on-silicon tandem devices offers a pathway to efficiencies surpassing what either technology can achieve alone, opening a premium market segment.
- Agrivoltaics Development:The semi-transparent nature of certain thin-film products presents an opportunity for dual-use land applications in agrivoltaics, where panels provide shade for crops while generating electricity.
Industry Challenges
- Manufacturing Scalability:Scaling production of next-generation materials like perovskites from laboratory to gigawatt-factory scale requires substantial capital investment and overcoming novel manufacturing process challenges.
- EHS Compliance for New Materials:Navigating evolving environmental, health, and safety standards for novel photovoltaic compounds adds complexity and cost, potentially delaying the market entry of new technologies.
- Standardization Gaps:A lack of universally accepted testing protocols and bankability standards for tandem and flexible solar cells can create friction for project financing and slow customer adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thin-Film Photovoltaic Market |
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $56.08 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cadmium Telluride, Copper Indium Gallium Selenide, Amorphous Silicon, Perovskite Technology: Flexible Modules, Rigid Modules, Tandem Cells, Organic Photovoltaics Application: Building-Integrated Power, Portable Electronics, Transportation, Off-Grid Power End User: Residential Consumers, Commercial Facilities, Agricultural Enterprises, Government Organizations |
| Companies Covered | First Solar, Kaneka Corporation, Ascent Solar Technologies, Oxford Photovoltaics, Hanwha Qcells, Sharp Corporation, MiaSole, Avancis GmbH, Solar Frontier, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thin-Film Photovoltaic Market Strategic Shifts & Innovations
Material science breakthroughs are reshaping competitive positioning, creating a distinct split between high-volume, cost-focused technologies and high-performance, specialized solutions. This dynamic influences investment, application focus, and regional manufacturing strategies across the value chain.
Tandem Cells Consolidate R&D Focus
Perovskite-on-silicon tandem cells function by layering a perovskite thin film over a traditional silicon wafer to capture different wavelengths of light. Developers of high-performance solar solutions are adopting this architecture to push efficiency boundaries beyond the limits of single-junction cells. This technology is consolidating research efforts around hybrid designs, establishing a new premium segment for applications where maximum power density is critical.
The Inflation Reduction Act Reshores Production
The United States' Inflation Reduction Act (IRA) offers substantial tax credits for domestic manufacturing of solar components, including thin-film modules. This policy directly incentivizes companies to build or expand production capacity within the US to serve local demand. Cadmium Telluride module producers are most directly impacted, gaining a powerful tool to improve cost-competitiveness against crystalline silicon panels imported from Asia.
Aesthetic Value Drives BIPV Procurement
A notable behavioral shift is occurring in the commercial construction sector, where architects are increasingly specifying solar products based on aesthetic qualities. This change elevates building-integrated photovoltaics from a simple energy component to a core architectural design element, shifting procurement influence. This trend is particularly prominent in European city centers, where design-forward, energy-generating building facades are gaining traction.
Thin-Film Photovoltaic Market Segmentation
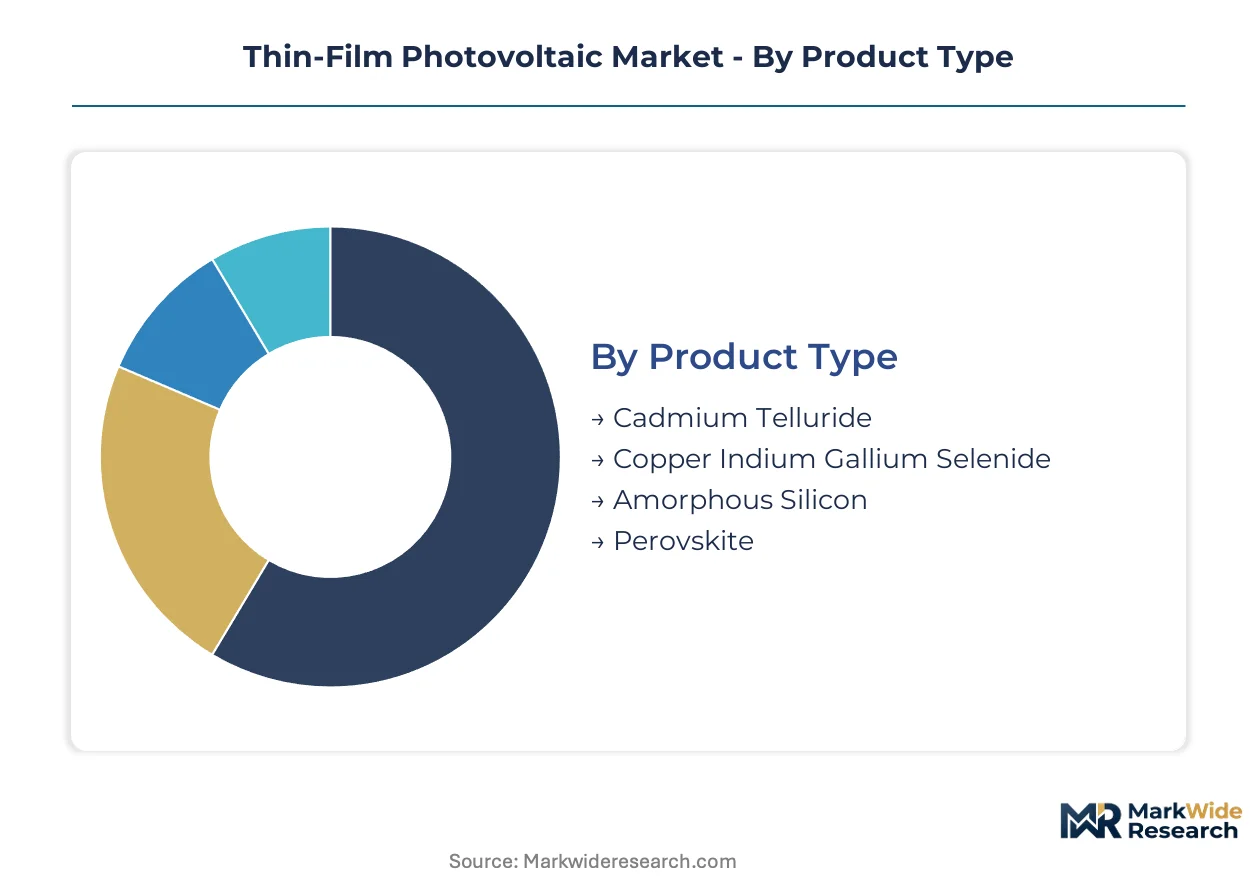
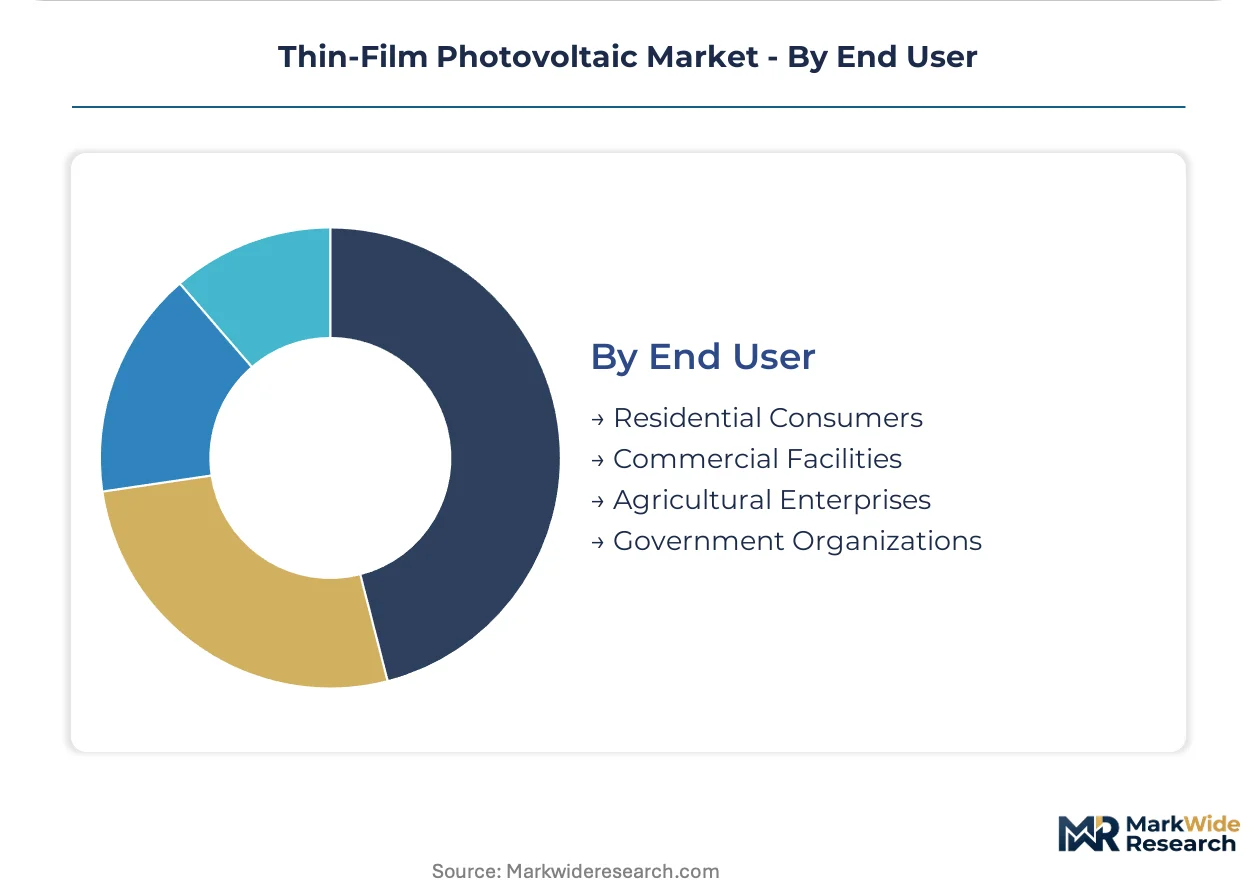
The Thin-Film Photovoltaic Market exhibits diverse segmentation across product types, technologies, applications, and end users. This stratification reflects the varying performance characteristics, integration requirements, and economic drivers influencing market adoption. Understanding these segments is crucial for identifying areas of concentrated demand and emerging growth trajectories within the industry.
Product Type:
The upgrade cycle for existing solar installations often dictates the choice of thin-film product type, balancing efficiency gains with installation costs.
- Perovskite:Perovskite cells utilize hybrid organic-inorganic lead or tin halide-based materials as the active light-harvesting layer. Demand is concentrating in research and development for next-generation devices, driven by rapid efficiency gains.
- Cadmium Telluride:Cadmium Telluride (CdTe) modules are polycrystalline thin films formed by depositing a cadmium and tellurium compound onto a substrate. Utility-grade projects in China and the United States drive demand, supported by cost-effectiveness and large-scale deployment capabilities.
- Copper Indium Gallium Selenide:CIGS technology employs a thin-film mixture of copper, indium, gallium, and selenium, offering good efficiency on flexible substrates.
- Amorphous Silicon:Amorphous silicon films are non-crystalline silicon layers, valued for their flexibility and performance in low-light conditions.
Cadmium Telluride sits at the top of the volume ranking, with Perovskite climbing the fastest.
Technology:
Different thin-film technologies cater to distinct application requirements, from robust utility-scale installations to specialized flexible devices.
- Tandem Cells:Tandem cells integrate multiple photovoltaic layers, such as perovskite over silicon, to absorb a broader spectrum of sunlight. Premium applications requiring maximum power density drive demand, particularly in space-constrained or high-value installations.
- Flexible Modules:Flexible modules are thin-film devices deposited on bendable substrates like plastic or metal foil, allowing for non-planar integration. Emerging applications in electronic textiles and portable power for military use are fueling demand due to their adaptable form factor.
- Rigid Modules:Rigid modules, typically glass-backed, are common in traditional solar installations requiring durability and structural integrity.
- Organic Photovoltaics:Organic photovoltaics (OPV) utilize carbon-based materials, offering lightweight and semi-transparent options for niche aesthetic applications.
Tandem cell architectures are pushing efficiency boundaries, while flexible modules offer versatility for novel product integration.
Application:
The volume of thin-film deployment varies significantly across different applications, reflecting diverse energy needs and integration challenges.
- Building-Integrated Power:BIPV integrates thin-film solar cells directly into building elements like facades, roofs, and windows, serving both aesthetic and energy functions. Commercial facilities in Europe are driving significant investment, seeking aesthetic energy solutions and reduced operational costs.
- Off-Grid Power:Off-grid power applications use thin-film modules to provide electricity in remote locations without access to conventional grid infrastructure. Rural communities and remote industrial sites globally are concentrating demand, valuing the low weight and ease of deployment.
- Portable Electronics:Portable electronics utilize compact thin-film cells for on-the-go charging of devices, where flexibility and light weight are critical.
- Transportation:Transportation applications integrate thin-film photovoltaics into vehicles for auxiliary power or range extension, particularly in specialized electric vehicles.
Building-Integrated Power applications command substantial investment, while Off-Grid Power addresses critical energy access gaps.
End User:
The margin profiles for thin-film products can differ significantly across end-user segments, influenced by project scale and customization requirements.
- Commercial Facilities:Commercial facilities include office buildings, retail centers, and industrial complexes integrating thin-film solutions for self-consumption and green branding. Demand is strong in urban areas seeking to meet sustainability targets and reduce energy bills through aesthetically pleasing BIPV solutions.
- Agricultural Enterprises:Agricultural enterprises deploy thin-film photovoltaics in agrivoltaics systems, allowing for simultaneous crop cultivation and energy generation. European farms are driving demand for semi-transparent panels, optimizing land use and providing shade for specific crops.
- Residential Consumers:Residential consumers adopt thin-film for rooftop solar, especially for lightweight or architecturally integrated solutions on homes.
- Government Organizations:Government organizations utilize thin-film for public infrastructure projects, military applications, and remote monitoring stations, prioritizing reliability and specific form factors.
Commercial Facilities represent a significant revenue stream, with Agricultural Enterprises showing expanding potential for dual-use land applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled engineering talent and a robust research ecosystem anchor the thin-film photovoltaic market's regional dynamics. These concentrations foster innovation in material science and drive large-scale deployment initiatives. Policy support further amplifies regional growth trajectories across key geographies.
China
China's vast manufacturing capacity and ambitious dual carbon goals create immense demand for cost-effective thin-film modules. The nation's MEE regulations influence material choices for domestic producers. Large-scale solar farms in provinces like Inner Mongolia and Xinjiang exemplify this utility-grade deployment.
United States
The United States sees substantial demand for utility-grade projects and advanced solar technologies. The Inflation Reduction Act (IRA) provides significant tax credits, incentivizing domestic manufacturing of thin-film components. The Arizona-based manufacturing hub for Cadmium Telluride production demonstrates this localized industrial focus.
Germany
Germany's architectural sector drives demand for aesthetic building-integrated photovoltaics. Europe's RoHS directive mandates stringent material restrictions, influencing manufacturing processes for thin-film cells. Research institutions in regions like Bavaria are at the forefront of perovskite cell development.
Japan
Japan's focus on technological innovation and space-constrained applications supports demand for high-efficiency thin-film solutions. METI policies encourage advancements in next-generation solar technologies. Research clusters in the Kanto region actively develop flexible amorphous silicon and CIGS technologies.
India
India's rapidly expanding energy requirements and solar capacity targets fuel demand for diverse photovoltaic solutions. The PLI scheme offers incentives for local solar manufacturing, including thin-film technologies. States like Rajasthan and Gujarat are witnessing large-scale solar park developments, incorporating various module types.
Thin-Film Photovoltaic Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the thin-film photovoltaic market, creating a stratified competitive environment. The market structure exhibits a tiered consolidation, with large-scale manufacturers dominating utility segments and specialized firms focusing on premium applications. Archetypes include integrated manufacturers, R&D-focused innovators, and niche technology providers. Dominant competitive moves involve capacity expansion for commodity products and strategic partnerships for next-generation material development.
Integrated manufacturers like First Solar, a US-based corporation, anchor the utility-grade segment with their large-scale Cadmium Telluride production capabilities. These players leverage economies of scale to serve vast energy projects efficiently. Conversely, Oxford Photovoltaics, a UK-based company, represents the R&D-focused innovators, specializing in perovskite-on-silicon tandem cells for premium applications requiring maximum power density. Kaneka Corporation, a Japan-based entity, sits within the niche technology provider archetype, offering flexible amorphous silicon solutions for specialized uses such as portable power or BIPV.
| Leading Market Players |
|---|
| First Solar |
| Kaneka Corporation |
| Ascent Solar Technologies |
| Oxford Photovoltaics |
| Hanwha Qcells |
| Sharp Corporation |
| MiaSole |
| Avancis GmbH |
| Solar Frontier |
| Others |
Cost & Logistics Intelligence
Manufacturing compliance costs for novel materials, influenced by regulations like Europe's RoHS directive, directly impact the final pricing of thin-film modules across different application tiers. This regulatory burden shapes the value proposition for next-generation photovoltaics.
Pricing Analysis
The bundled service offering in building-integrated photovoltaics often commands premium pricing, while commodity amorphous silicon films are transactionally priced. Price differentiation stems from efficiency gains in tandem cells and customization levels for aesthetic BIPV solutions. Pricing softness reflects intense competition from crystalline silicon panels in utility-grade projects. Commercial facilities and agricultural enterprises show lower price sensitivity for integrated solutions, unlike residential consumers focused on cost per watt.
Supply Chain Analysis
Tellurium supply for Cadmium Telluride production draws from a concentration of mining operations in a few countries, primarily China and the United States. Key raw materials include cadmium, tellurium, and specialized substrates. Single-source vulnerability for rare earth elements presents a structural supply chain risk. Distribution runs through large-scale project developers for utility applications and specialized distributors for BIPV and niche flexible electronics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thin-film photovoltaic market acts as a regulatory compounder, with policies like the US Inflation Reduction Act (IRA) significantly accelerating domestic manufacturing and demand for localized solar components. This policy environment shapes strategic investment decisions across the value chain.
For Market Incumbents: Cement market share by investing in gigawatt-scale production capacity for Cadmium Telluride modules in regions like the United States, leveraging IRA tax credits. Pursue strategic partnerships for advanced material research to counter the efficiency threat from perovskite-on-silicon tandem cells. Enhance vertical integration into substrate manufacturing to secure critical raw material supply chains. Focus on cost optimization to maintain competitiveness against low-cost imports.
For New Entrants and Emerging Players: Capture niche opportunities by specializing in flexible amorphous silicon for portable power or organic photovoltaics for aesthetic BIPV applications. The building-integrated power segment, particularly in European city centers, offers the most penetrable market due to demand for design-forward solutions. Develop robust go-to-market strategies focused on architectural firms and specialized integrators. Prioritize rapid prototyping and certification for novel perovskite chemistries.
For Investors and Strategic Acquirers: Consolidation pressure builds where manufacturing scale and R&D intensity diverge, favoring integrated producers or specialized innovators. Long-term viability hinges on companies demonstrating scalable production pathways for next-generation materials like perovskites. Target acquisition archetypes include R&D-heavy startups with patented intellectual property in tandem cell architectures or specialized manufacturers with established BIPV integration expertise. Watch for breakthroughs in perovskite stability as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | First Solar's expansion in the US leverages IRA incentives, ensuring cost-competitive Cadmium Telluride supply. |
| Perovskite R&D Investment | Oxford Photovoltaics drives efficiency gains in tandem cells, pushing performance boundaries for premium applications. |
| Flexible Module Development | Kaneka Corporation targets niche markets like portable power, expanding thin-film's application versatility. |
| BIPV Solution Integration | Commercial facilities in Europe seek aesthetic energy solutions, driving demand for integrated thin-film products. |
| EHS Compliance Upgrade | Manufacturers navigate Europe's RoHS directive, influencing material choices and market access for electronic components. |
Research Approach
Multiple input streams — primary interviews with industry stakeholders, secondary validation from regulatory filings, and market intelligence reports — were reconciled to construct a comprehensive market view. This involved engaging R&D directors, procurement managers at commercial facilities, BIPV architects, and government energy officials. Secondary sources included EIA data, IEA reports, and corporate financial statements, triangulated with bottom-up and top-down analyses.
Historical market performance was cross-referenced with expert panel input to project future growth trajectories across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and regional demand patterns. Compound Annual Growth Rates were derived from a multi-factor regression model incorporating economic indicators and policy shifts. Forecast inputs included raw material price volatility and manufacturing capacity build-out plans.
Underlying measurement precision varies by segment; Cadmium Telluride and Amorphous Silicon carry tighter precision than emerging perovskite technologies. Forecasts reflect assumptions regarding regulatory stability and material science advancements. Material degradation rates for novel compounds or unexpected shifts in raw material supply chains warrant pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Bifacial Solar Panels Market
Solar Power Systems
APAC Solar Micro Inverters Market
Solar Power Systems
Solar-Powered EV Charging Stations Market
Solar Power Systems
US Solar Market
Solar Power Systems
Solar Thermal Power Market
Solar Power Systems
Asia-Pacific Solar Blanket Market
Solar Power Systems
Global Solar Water Heaters Market
Solar Power Systems
Asia-Pacific Distributed Solar Power Generation Market
Solar Power Systems
On-Grid Solar Inverter Market
Solar Power Systems
Solar Collector Panels Market
Solar Power Systems
Solar Shingles Market
Solar Power Systems
Germany Solar Energy Market
Solar Power Systems
Solar Tracker for Power Generation Market
Solar Power Systems
Spray-On Solar Cells Market
Solar Power Systems
South America Solar PV Inverters Market
Solar Power Systems
Solar Concentrator Market