
 Solar Panel Cleaning System Market | 2026-2036
Solar Panel Cleaning System Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Panel Cleaning System Market Intelligence
The capital intensity divergence between fully automated robotic solutions and manual cleaning equipment is reorganizing the competitive landscape. Ecoppia specializes in high-capital, water-free robotic systems for utility-scale desert installations, offering a fully autonomous solution. In contrast, Kärcher leverages its extensive distribution and brand strength in conventional cleaning equipment to serve smaller commercial and residential clients. SunBrush mobil positions its vehicle-mounted systems for both large agricultural and commercial applications, bridging the gap between manual and fully robotic methods.
A solar panel cleaning system is a device designed to remove soiling agents like dust, pollen, and bird droppings from photovoltaic surfaces to maximize energy output. These systems utilize methods ranging from high-pressure water jets to robotic arms equipped with soft brushes or air blowers, often operating autonomously based on sensor inputs. Robotic Systems and waterless cleaning technologies are experiencing high adoption in the utility-scale application. This segment's demand is driven by the direct financial impact of soiling losses on large-scale power generation projects.
Operational standards are shaped by a mix of national and international frameworks. In the United States, OSHA guidelines govern worker safety for manual cleaning, while water usage regulations within the EU Green Deal framework influence technology selection in Europe. ISO 14001 certification often guides procurement for large clean energy companies, emphasizing environmental management. The critical decision for asset owners remains balancing the upfront capital cost of automated systems against long-term operational expense and performance gains.
Market Dynamics
The fundamental tension between high-capital, autonomous robotic systems and low-capital, labor-intensive manual methods defines market dynamics. This divergence forces asset owners to make critical trade-offs between upfront investment and long-term operational expenditure, shaping technology adoption across different market segments.
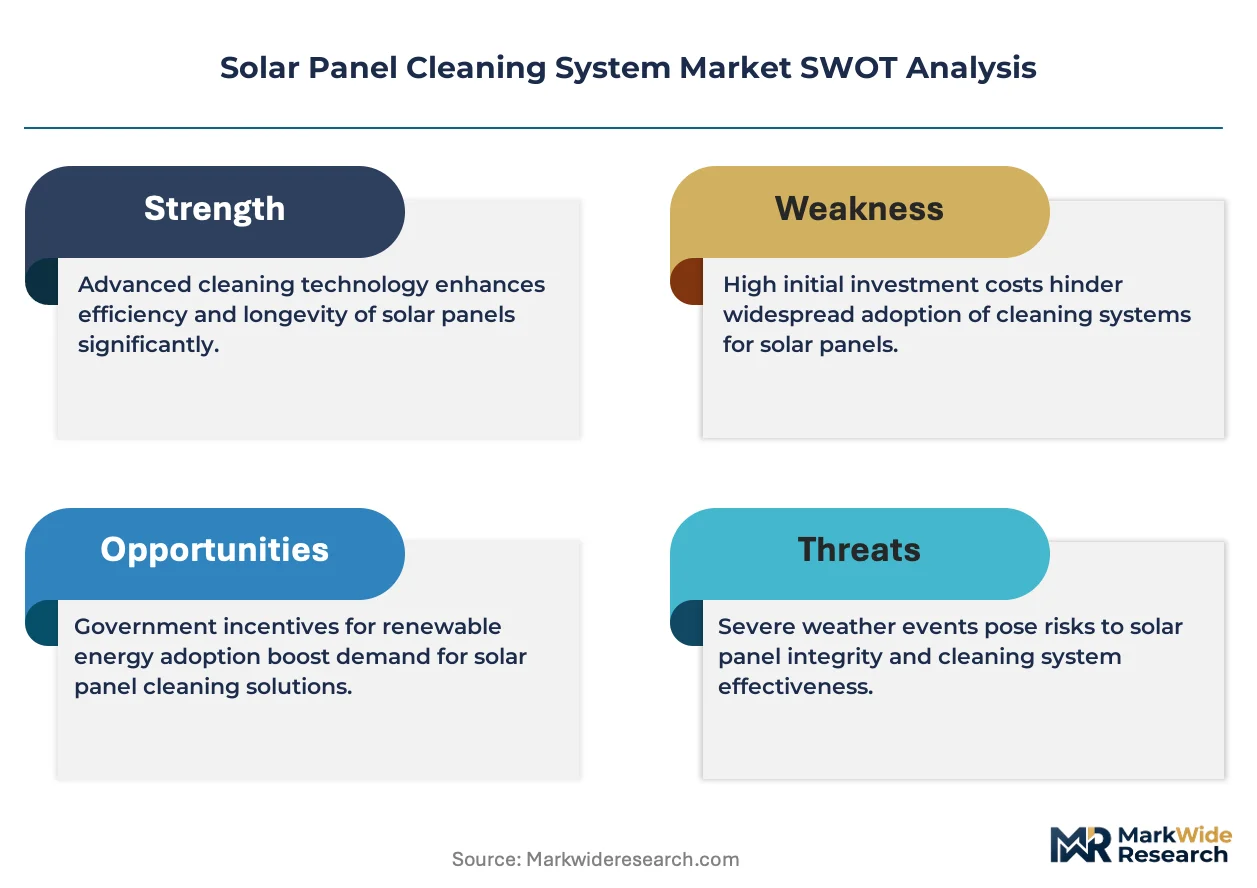
Growth Catalysts
- Utility-Scale Deployments:The construction of massive solar farms in arid regions like Saudi Arabia and Australia necessitates automated, water-efficient cleaning solutions to maintain energy yield and ensure project bankability.
- Water Scarcity Regulations:Frameworks such as the EU Green Deal encourage the adoption of waterless cleaning technologies by placing implicit costs and restrictions on water consumption for industrial activities, including solar plant maintenance.
- Predictive Maintenance Integration:The development of IoT sensors and AI software that predict soiling losses allows operators to schedule cleaning proactively, maximizing the return on investment for advanced cleaning systems.
Market Restraints
- High Capital Cost:The significant upfront investment required for fully automated robotic cleaning systems remains a primary barrier for small to medium-sized commercial solar installations and developers with constrained budgets.
- Technical Standardization Gaps:A lack of industry-wide standards for mounting interfaces and communication protocols complicates the integration of robotic systems across diverse solar panel and racking hardware, increasing deployment costs.
- Operational Complexity:Advanced robotic systems require specialized technicians for maintenance and repair, creating operational challenges in remote locations where skilled labor is scarce.
Strategic Opportunities
- Retrofit Market:Upgrading existing, aging solar farms with modern autonomous cleaning systems to boost their declining power output and extend their profitable lifespan presents a major service and equipment opportunity.
- Emerging Solar Geographies:Markets across North Africa and Southeast Asia with ambitious solar energy targets but nascent cleaning infrastructure offer significant greenfield potential for both manual and automated system providers.
- Integrated Diagnostic Services:Combining cleaning operations with drone-based thermography or electroluminescence (EL) testing allows service providers to offer a bundled package of cleaning and fault detection.
Industry Challenges
- Skilled Labor Shortage:The industry faces a deficit of technicians with the mechatronics, robotics, and software expertise needed to install, operate, and service sophisticated automated cleaning systems effectively.
- System Durability in Extreme Climates:Ensuring the long-term reliability and performance of robotic components, such as motors and brushes, in harsh environments with extreme temperatures, high winds, and abrasive sand is a persistent engineering challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Panel Cleaning System Market |
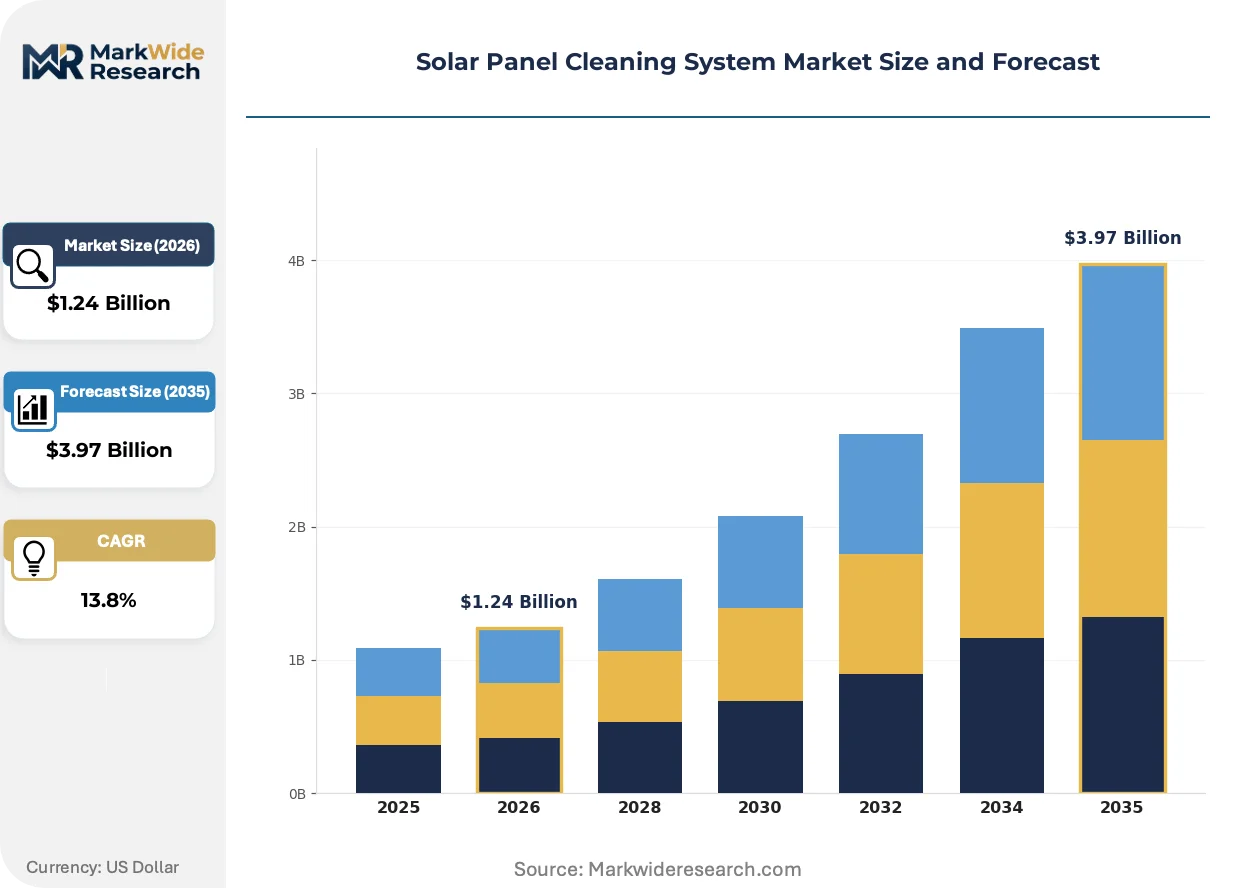
| Market Size in 2026 | $1.24 Billion |
| Market Size in 2035 | $3.97 Billion |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Cleaners, Manual Cleaners, Robotic Systems, Hybrid Solutions Technology: Ultrasonic Cleaning, Brush-based Cleaning, Waterless Cleaning, Chemical Cleaning Application: Residential, Commercial, Utility-scale, Agricultural End User: Homeowners, Facility Managers, Clean Energy Companies, Maintenance Contractors |
| Companies Covered | SunBrush mobil, Aegeus Technologies, Ecoppia, Boson Robotics, Nomadd Desert Solar Solutions, Kärcher, Serbot AG, Clean Solar Solutions, SolarCleano, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Panel Cleaning System Market Strategic Shifts & Innovations
The market is pivoting from reactive, schedule-based cleaning to proactive, data-driven maintenance strategies. This shift treats soiling not as a simple nuisance but as a manageable variable in the overall financial performance optimization of a solar asset.
Advanced analytics platforms that integrate soiling sensors, satellite weather data, and energy output models are gaining traction. Utility-scale solar asset managers are the primary adopters, using these tools to justify cleaning cycles based on a clear cost-benefit analysis. This data-centric methodology is decomposing the rigid, calendar-based cleaning schedule into a flexible, condition-based operational workflow that optimizes resource use.
Worker safety mandates, including OSHA guidelines in the United States, elevate the risk and cost associated with manual cleaning on large-scale or rooftop solar arrays. These regulations increase insurance premiums and operational overhead for methods requiring human labor at height or in hazardous conditions. Consequently, commercial and utility segments are accelerating investment into robotic solutions to minimize human exposure and ensure regulatory compliance.
A preference for performance-based service contracts is altering equipment procurement models. Instead of purchasing cleaning systems outright, many large asset owners now favor "Cleaning-as-a-Service" (CaaS) agreements that tie payments to verified energy gains or plant availability. This trend is most visible in new utility-scale projects in the Middle East, where providers guarantee a certain level of plant cleanliness for a fixed operational fee.
Solar Panel Cleaning System Market Segmentation
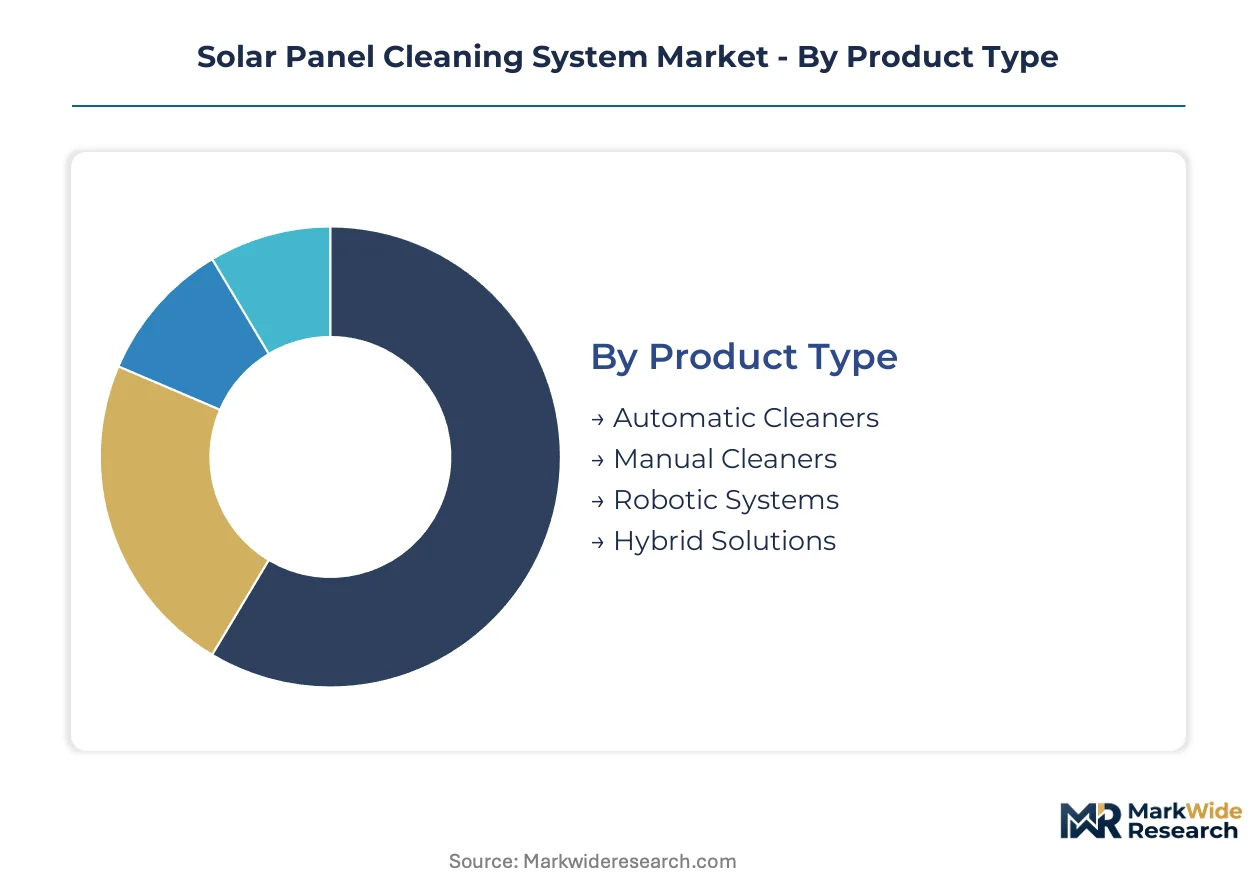
Segmentation within the solar panel cleaning system market illuminates the diverse operational requirements and investment priorities across different solar asset owners. Understanding these distinct segments helps manufacturers tailor solutions and service providers optimize their offerings for specific client needs.
Product Type:
Regulatory frameworks, such as OSHA guidelines for worker safety, significantly differentiate the market for solar panel cleaning systems based on their operational approach.
- Automatic Cleaners:These systems operate autonomously or semi-autonomously, often on a scheduled basis, using various mechanisms like brushes or water jets. Demand concentrates in large commercial and utility-scale projects in regions like Saudi Arabia, driven by the need to reduce labor costs and improve efficiency.
- Robotic Systems:Highly sophisticated, self-propelled devices that navigate solar arrays, often employing sensors for obstacle avoidance and precise cleaning. Utility-scale solar farms in Australia are rapidly adopting these systems to minimize human intervention and optimize cleaning cycles in harsh conditions.
- Manual Cleaners:These systems involve human operators using handheld tools, brushes, or pressure washers, typically for smaller installations.
- Hybrid Solutions:These systems combine elements of automated and manual cleaning, offering flexibility for varied site conditions and operational requirements.
Established volume favors Manual Cleaners; emerging adoption favors Robotic Systems.
Technology:
The choice of cleaning technology often hinges on the specific environmental challenges and resource availability at a solar installation site.
- Waterless Cleaning:These methods utilize brushes, air blowers, or electrostatic charges to remove dust and debris without liquid, crucial for arid regions. Demand is concentrating in desert environments such as the UAE, where water scarcity regulations and operational costs strongly favor these solutions.
- Brush-based Cleaning:This common technology employs rotating or reciprocating brushes, often combined with water, to physically dislodge soiling from panel surfaces. Commercial and agricultural installations in Europe frequently deploy brush-based systems due to their effectiveness and adaptability across various panel types.
- Ultrasonic Cleaning:This technology uses high-frequency sound waves in a liquid medium to dislodge microscopic particles from solar panel surfaces.
- Chemical Cleaning:This method involves applying specialized cleaning agents to break down stubborn grime, typically used for severe soiling or specific types of contaminants.
Brush-based Cleaning maintains a significant market presence, while Waterless Cleaning exhibits the steepest expansion trajectory.
Application:
The scale of solar energy deployment directly influences the preferred cleaning system application, dictating investment levels and operational models.
- Utility-scale:Encompasses massive solar farms spanning acres, where cleaning efficiency and automation are critical for maintaining gigawatt-level power output. Projects in Saudi Arabia prioritize these solutions to maximize energy yield and ensure financial viability over decades.
- Commercial:Refers to installations on businesses, industrial facilities, and large institutional buildings, requiring robust and often semi-automated cleaning solutions. European commercial sites frequently adopt these systems to comply with energy efficiency mandates and reduce operational expenditure.
- Residential:Pertains to rooftop solar arrays on individual homes, typically serviced by manual methods or simpler automated solutions.
- Agricultural:Involves solar panels integrated into farming operations, such as agrivoltaics, where cleaning must be adaptable to agricultural schedules and environments.
Residential applications represent a foundational volume, with Utility-scale applications gaining share fastest.
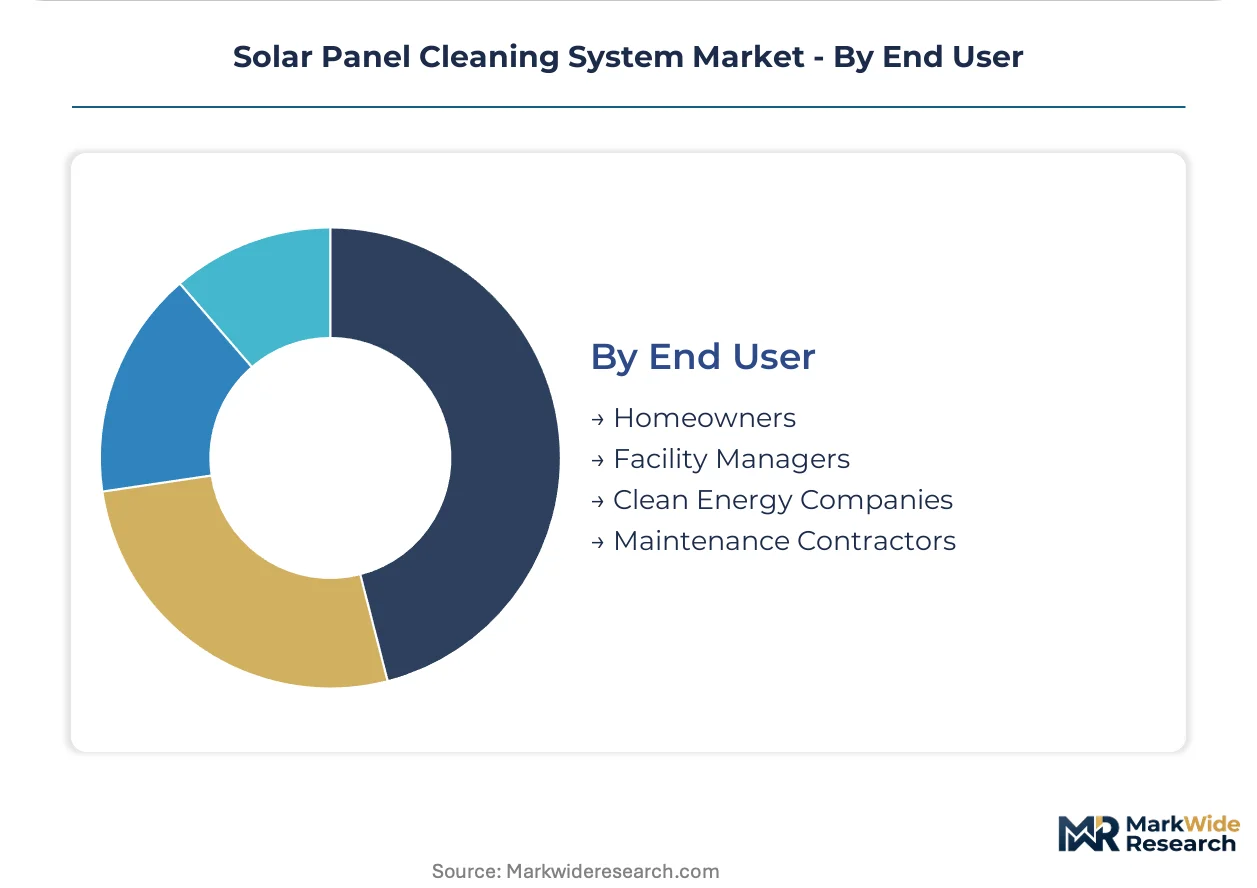
End User:
Different end-user segments prioritize distinct operational efficiencies and cost structures when selecting solar panel cleaning solutions.
- Clean Energy Companies:These entities own and operate large solar farms, demanding highly efficient, often robotic, cleaning solutions to optimize energy production and asset performance. Leading clean energy companies in the United States invest in advanced systems to ensure consistent power generation and meet grid demands.
- Maintenance Contractors:Third-party service providers specializing in the upkeep of solar installations for various clients, requiring versatile and scalable cleaning equipment. Contractors in India utilize a mix of manual and semi-automated tools to serve a diverse portfolio of commercial and utility-scale projects.
- Homeowners:Individual consumers with residential solar panels, often opting for DIY cleaning methods or occasional professional services.
- Facility Managers:Professionals responsible for the upkeep of commercial or industrial properties, who procure cleaning services or equipment for their on-site solar arrays.
Homeowners form a broad base for basic cleaning needs, while Clean Energy Companies are expanding quickly in their adoption of specialized systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing-power asymmetry is evident, with high-capital automated solutions commanding premium pricing in arid regions like Saudi Arabia. More cost-sensitive markets such as India prioritize scalable, hybrid cleaning approaches. This divergence shapes technology adoption and investment across different geographies.
Saudi Arabia
Utility-scale solar farms in Saudi Arabia drive significant demand for advanced robotic cleaning systems to maintain peak energy output. The country's national energy policies strongly support large-scale renewable projects. Developers in the Eastern Province and NEOM city invest heavily in autonomous solutions for long-term operational viability.
Australia
Australian solar asset owners prioritize robotic systems to minimize human intervention and optimize cleaning cycles across vast, remote installations. Australia's clean energy targets drive investment in technologies ensuring consistent power generation. Large solar parks in Queensland and New South Wales increasingly deploy autonomous cleaners.
United States
United States utility-scale and commercial projects demand cleaning solutions addressing worker safety and maximizing energy output. OSHA guidelines influence technology selection, accelerating investment in robotic systems. California's extensive solar installations and the arid Southwest regions are key adoption hubs for advanced automated and waterless cleaning.
Germany
German commercial and agricultural solar installations require robust cleaning solutions that comply with energy efficiency mandates. The EU Green Deal framework encourages water-efficient technologies and sustainable operational practices. Sites across Bavaria and North Rhine-Westphalia frequently deploy brush-based and hybrid systems due to their effectiveness.
India
India's rapidly expanding solar sector generates demand for versatile and scalable cleaning equipment. The country's national renewable energy targets emphasize consistent power generation from solar assets. Maintenance contractors in states like Rajasthan and Gujarat utilize a mix of manual and semi-automated tools for their growing utility-scale client base.
Solar Panel Cleaning System Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the solar panel cleaning system market. The market exhibits a tiered structure, with highly specialized robotic system providers at the premium end and a broader base of conventional cleaning equipment manufacturers. Strategic archetypes include high-capital automated solution providers, versatile hybrid system developers, and labor-intensive manual cleaning equipment suppliers. Companies engage in strategic partnerships to integrate diagnostic services and expand their geographic reach into emerging solar geographies.
Specialists in high-capital, water-free robotic systems, such as Ecoppia, exemplify the premium segment targeting utility-scale desert installations. These providers focus on fully autonomous solutions for critical infrastructure projects. Kärcher, in contrast, represents a conventional cleaning equipment manufacturer leveraging extensive distribution and brand strength to serve smaller commercial and residential clients with established product lines. SunBrush mobil positions its vehicle-mounted systems for both large agricultural and commercial applications, effectively bridging the gap between manual and fully robotic methods with adaptable solutions.
| Leading Market Players |
|---|
| SunBrush mobil |
| Aegeus Technologies |
| Ecoppia |
| Boson Robotics |
| Nomadd Desert Solar Solutions |
| Kärcher |
| Serbot AG |
| Clean Solar Solutions |
| SolarCleano |
| Others |
Cost & Logistics Intelligence
OSHA guidelines and ISO 14001 certification gate both supply qualification and price differentiation in the solar panel cleaning market. These frameworks influence technology selection and operational costs, directly impacting pricing strategies.
Pricing Analysis
Configured-to-order robotic systems command a premium over standard manual cleaning equipment. The dominant pricing model is project-based for large utility-scale deployments, frequently shifting towards Cleaning-as-a-Service (CaaS) agreements that tie payments to verified energy gains. Price differentiation stems from customization level for harsh environments and integrated diagnostic services. Pricing softness affects manual solutions due to labor cost competition, with residential clients exhibiting high price sensitivity compared to utility-scale asset owners who prioritize performance.
Supply Chain Analysis
Strategic-stockpile preferences are emerging for specialized robotic components, balancing just-in-time delivery for standard parts. Geographic supply concentration for advanced mechatronics and sensor components leans towards Germany, China, and the United States. The industry relies on specialized motors, durable brushes, and advanced sensor components, creating single-source vulnerability for custom robotic parts. Distribution runs through direct sales channels for utility-scale projects and regional distributor networks for commercial applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a significant service-attach opportunity, with Cleaning-as-a-Service (CaaS) agreements expanding faster than outright hardware purchases. Asset owners increasingly seek outcome-based contracts for optimized energy yield.
For Market Incumbents: Fortify core market positions by acquiring niche waterless cleaning technology providers to address arid region demand. Deepen channel partnerships in emerging solar geographies like North Africa to counter new entrant archetype competition. Invest in R&D for system durability in extreme climates and pursue ISO 14001 certification to reinforce environmental management standards. This defends against technical standardization gaps and margin pressure. For New Entrants and Emerging Players: Anchor in the retrofit market by offering upgrade solutions for aging solar farms, boosting their power output. Target emerging solar geographies in Southeast Asia with bundled cleaning and integrated diagnostic services. The most penetrable segment is commercial solar in Europe, leveraging a go-to-market angle of outcome-based service contracts tied to verified energy gains. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial cleaning equipment manufacturers seeking to divest non-core solar assets. This market offers long-term viability as solar asset performance relies heavily on effective cleaning. Focus on specialized robotic system developers with strong intellectual property in waterless technologies. The signal to watch is a sustained increase in Cleaning-as-a-Service (CaaS) adoption rates among utility-scale operators.| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Waterless Technology Development | Addresses water scarcity regulations and operational challenges in arid environments like Saudi Arabia. |
| Integrated Diagnostic Service Offering | Combines cleaning with drone-based thermography for comprehensive solar asset management. |
| Geographic Expansion into Emerging Markets | Captures greenfield potential in North Africa with ambitious solar energy targets. |
| Cleaning-as-a-Service (CaaS) Model Adoption | Aligns with asset owner preference for performance-based contracts and predictable operational expenses. |
| Robotic System Durability R&D | Ensures long-term reliability of components in harsh climates, critical for utility-scale deployments. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews, validated by extensive secondary research. Stakeholders included utility planning officers, solar farm managers, maintenance contractors, and robotic engineers. Secondary data sources comprised industry association reports, government energy statistics, patent databases, and company financial filings. This facilitated bottom-up and top-down triangulation for robust market sizing.
Over the projection horizon, the analytical framework modeled market dynamics across product type, technology, application, end user, and regional regulatory frameworks. Compound Annual Growth Rates (CAGRs) were derived from historical trends and projected adoption rates. Industry-specific inputs included utility-scale solar installation rates and regional water scarcity indices. This provided a comprehensive outlook across the analysis window.
Material uncertainties — significant policy shifts or raw material price volatility — sit outside the modeled envelope, yet forecasts reflect current market assumptions. Geopolitical events impacting global supply chains also pose a risk. Revision becomes warranted when these conditions cross critical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Parabolic Solar Cookers Market
Solar Power Systems
Amorphous Silicon PV Market
Solar Power Systems
GCC Solar Water Heater Market
Solar Power Systems
Spain Rooftop Solar Market
Solar Power Systems
Global Photovoltaic Market
Solar Power Systems
Solar Bug Zapper Market
Solar Power Systems
Solar Power Manager Market
Solar Power Systems
Solar Ribbon Market
Solar Power Systems
Solar-Powered EV Charging Stations Market
Solar Power Systems
Global Solar Panel Tracking Mount Market
Solar Power Systems
Solar Collector Panels Market
Solar Power Systems
South America Solar Photovoltaic Market
Solar Power Systems
Spain Solar Energy Market
Solar Power Systems
Solar Module Market
Solar Power Systems
Global Airport Solar Power Market
Solar Power Systems
Solar Backsheet Market