
 Solar Panels Frame Market | 2026-2036
Solar Panels Frame Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Panels Frame Market Insights
Utility-scale developers is redrawing procurement priorities in the Solar Panels Frame Market as module formats exceed 2.3 meters and tracker compatibility becomes non-negotiable. JinkoSolar anchors its frame supply through captive aluminum extrusion partnerships in Southeast Asia. Hanwha Q CELLS differentiates via integrated frame-glass-module testing protocols that reduce field failure rates. Clenergy specializes in tracker-adaptive frame geometries that accommodate larger torque tubes.
A solar panel frame is a structural perimeter enclosure, typically extruded from 6063-T5 aluminum alloy or galvanized steel, that mechanically supports photovoltaic laminates, enables mounting interface compatibility, and protects edge seals from environmental degradation. Aluminum frames dominate current production due to their strength-to-weight ratio and anodization compatibility, though steel variants gain traction in high-wind and coastal corrosion zones. Ground Mounted applications lead volume demand through utility-scale deployment, while BIPV frames command premium positioning as building codes integrate photovoltaic facades into structural envelopes. Roof Mounted segments sustain steady replacement demand across residential retrofit markets where rail compatibility constraints limit supplier switching.
The EU Green Deal and REACH frameworks regulate aluminum smelting emissions and chemical surface treatments, pushing European frame buyers toward low-carbon billet sourcing. India's BIS certification mandates dimensional tolerances and load ratings for imported frames, creating compliance barriers for non-certified Asian suppliers. China's GB standards and dual carbon goals enforce energy consumption caps on aluminum extrusion plants, constraining domestic frame capacity expansion. Stakeholders must monitor evolving embodied carbon accounting rules that increasingly determine eligibility for subsidized solar procurement programs.
Market Dynamics
Module format inflation beyond 2.3 meters is compressing frame design cycles and forcing aluminum extruders to retool press lines for wider profiles. Tracker compatibility requirements now gate qualification for utility-scale procurement, reshaping supplier selection criteria.
Growth Catalysts
- EU Green Deal embodied carbon rules:Low-carbon aluminum billet sourcing is becoming mandatory for subsidized solar projects across Germany, Spain, and Italy.
- India PLI scheme:Domestic manufacturing incentives are attracting integrated frame and mounting system investments from Southeast Asian suppliers.
- Tracker-adaptive geometries:Clenergy and specialized fabricators are developing torque tube-compatible frames that reduce installation labor by 15-20%.
Market Restraints
- LME aluminum volatility:Frame margins compress when raw material costs spike without pass-through mechanisms in fixed-price EPC contracts.
- China extrusion capacity constraints:Dual carbon goals enforce energy consumption caps on aluminum plants, limiting domestic frame supply expansion.
- Steel substitution limits:Coastal corrosion zones restrict galvanized steel frames despite 30% lower material costs versus aluminum.
Strategic Opportunities
- BIPV facade integration:Building codes in France and Germany are mandating photovoltaic envelopes, creating premium frame specifications for structural glazing systems.
- Recycled aluminum certification:EPD-verified low-carbon frames command price premiums in Nordic utility procurement.
- Rail standardization convergence:Cross-manufacturer mounting interface compatibility is opening aftermarket replacement demand in residential retrofit channels.
Industry Challenges
- Anodization chemistry compliance:REACH restrictions on hexavalent chromium surface treatments force process retooling with 18-24 month qualification timelines.
- Dimensional tolerance enforcement:India's BIS certification creates testing bottlenecks for non-certified Asian suppliers seeking market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Panels Frame Market |
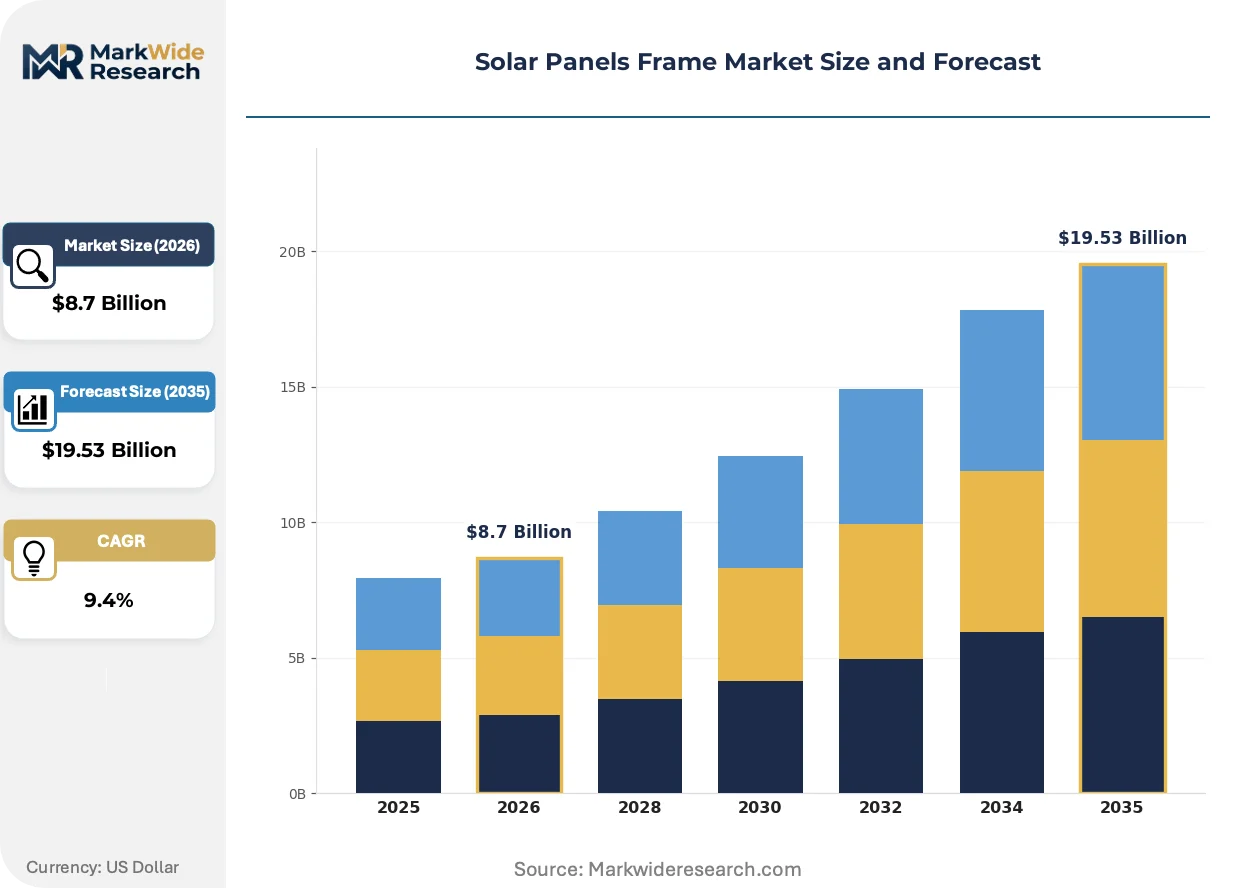
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum, Steel, Plastic, Wood End User: Residential, Commercial, Industrial, Utility Application: Ground Mounted, Roof Mounted, Floating, BIPV Installation Type: DIY, Professional, Hybrid, Modular |
| Companies Covered | APEX Aluminum, Vishakha Renewables, Aluenco, Sapa Group, Schletter Group, Clenergy, Xiamen Grace Solar, JinkoSolar, Hanwha Q CELLS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Panels Frame Market Trends and Innovations
Frame engineering is splitting along performance-versus-cost fault lines as module weights climb past 35 kilograms. Manufacturers are pursuing divergent strategies: premium anodized aluminum for coastal utility projects, cost-optimized steel-aluminum hybrids for inland installations.
High-strength 6005A-T6 aluminum alloy is displacing standard 6063-T5 in tracker applications where torsional loads exceed 2.5 kilonewton-meters. Utility-scale developers in Texas and Rajasthan are specifying the upgraded alloy for 600W+ module formats. The material specification is bifurcating procurement pools into performance-tier and standard-tier supplier categories with limited crossover.
REACH Annex XVII restrictions on chromium trioxide anodizing are forcing European frame producers to adopt trivalent chromium or thin-film ceramic coatings. The chemical transition adds 8-12% to surface treatment costs but preserves access to Green Deal-linked tenders. German and Dutch EPCs are now requiring coating chemistry disclosure in technical submittals.
Long-term frame supply agreements are replacing spot purchasing among top-ten utility-scale developers. Procurement teams are locking aluminum billet pricing through 2027-2028 to hedge LME volatility. This contracting evolution concentrates volume with extruders offering metallurgical traceability and carbon accounting documentation, squeezing undifferentiated Asian suppliers out of premium project tiers.
Solar Panels Frame Market Segmentation
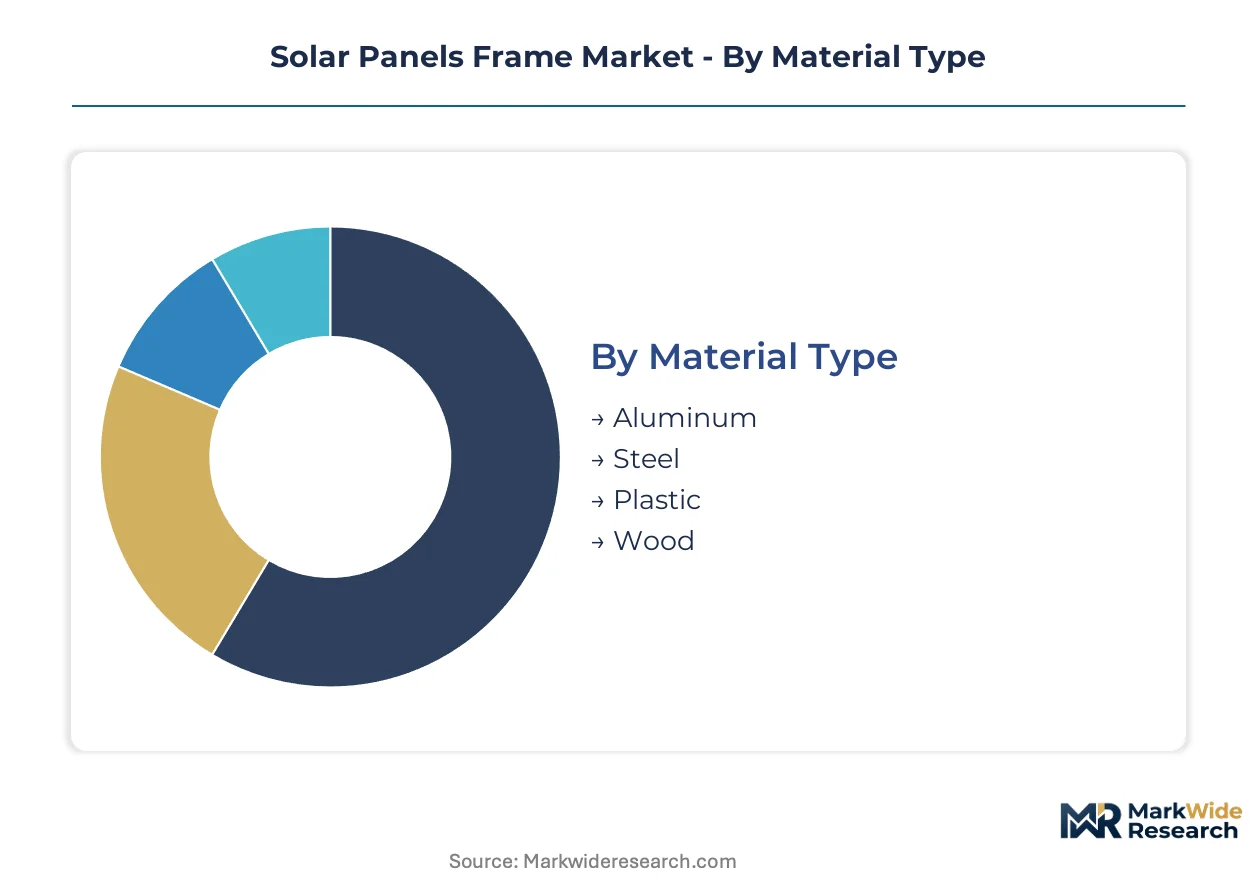
Module format inflation and tracker compatibility requirements are fragmenting procurement pools across material grades and installation specifications. Channel economics now favor suppliers who can certify across multiple segment boundaries rather than optimize within single categories.
Material Type:
Channel mix splits sharply: aluminum flows through EPC direct contracts and tier-one module OEM supply agreements, while steel and alternative materials concentrate in secondary distributor networks serving price-sensitive retrofit segments.
- Aluminum:Extruded 6063-T5 and 6005A-T6 alloys deliver the strength-to-weight ratio required for 600W+ module formats. Utility-scale developers in Texas and Rajasthan specify upgraded alloys where torsional loads exceed 2.5 kilonewton-meters. REACH Annex XVII restrictions on hexavalent chromium anodizing are forcing European producers toward trivalent or ceramic coatings.
- Steel:Galvanized steel variants compete on material cost advantages but face corrosion limitations in coastal zones. India's BIS certification mandates dimensional tolerances that filter out uncertified Asian suppliers.
- Plastic:Polymer composite frames serve niche BIPV facade applications where thermal expansion coefficients must match glazing systems.
- Wood:Timber frames occupy premium architectural segments in Nordic markets where EPD-verified low-carbon credentials command procurement preference.
By volume, aluminum leads. By growth pace, steel is gaining share fastest in inland utility installations.
End User:
Margin structures diverge across customer sophistication tiers, with utility procurement teams demanding metallurgical traceability while residential channels prioritize rail compatibility over material certification.
- Residential:Retrofit demand concentrates in rail-standardized replacement channels where cross-manufacturer mounting interface compatibility limits supplier switching.
- Commercial:Rooftop installations drive steady replacement cycles as building owners integrate photovoltaic systems into facility energy management.
- Industrial:C&I off-takers specify tracker-adaptive geometries for ground-mounted arrays where torque tube compatibility reduces installation labor.
- Utility:Long-term frame supply agreements now extend through 2027-2028 to hedge LME aluminum volatility, concentrating volume with extruders offering carbon accounting documentation.
Utility procurement commands the largest contract values. Residential retrofit channels are expanding most quickly as rail standardization opens aftermarket access.
Application:
Ground-mounted deployment dominates tonnage throughput, while BIPV specifications command premium positioning through structural glazing integration mandates.
- Ground Mounted:Tracker compatibility requirements now gate qualification for utility-scale procurement, reshaping supplier selection criteria toward torque tube-compatible frame geometries.
- Roof Mounted:Rail compatibility constraints in residential retrofit markets sustain steady replacement demand with limited supplier mobility.
- Floating:Aquatic photovoltaic installations in Southeast Asia specify corrosion-resistant surface treatments beyond standard anodization protocols.
- BIPV:Building codes in France and Germany mandate photovoltaic envelopes, creating premium frame specifications for structural glazing systems with thermal expansion matching.
Ground-mounted applications absorb the highest frame tonnage. BIPV facade integration is climbing the fastest as European building codes tighten.
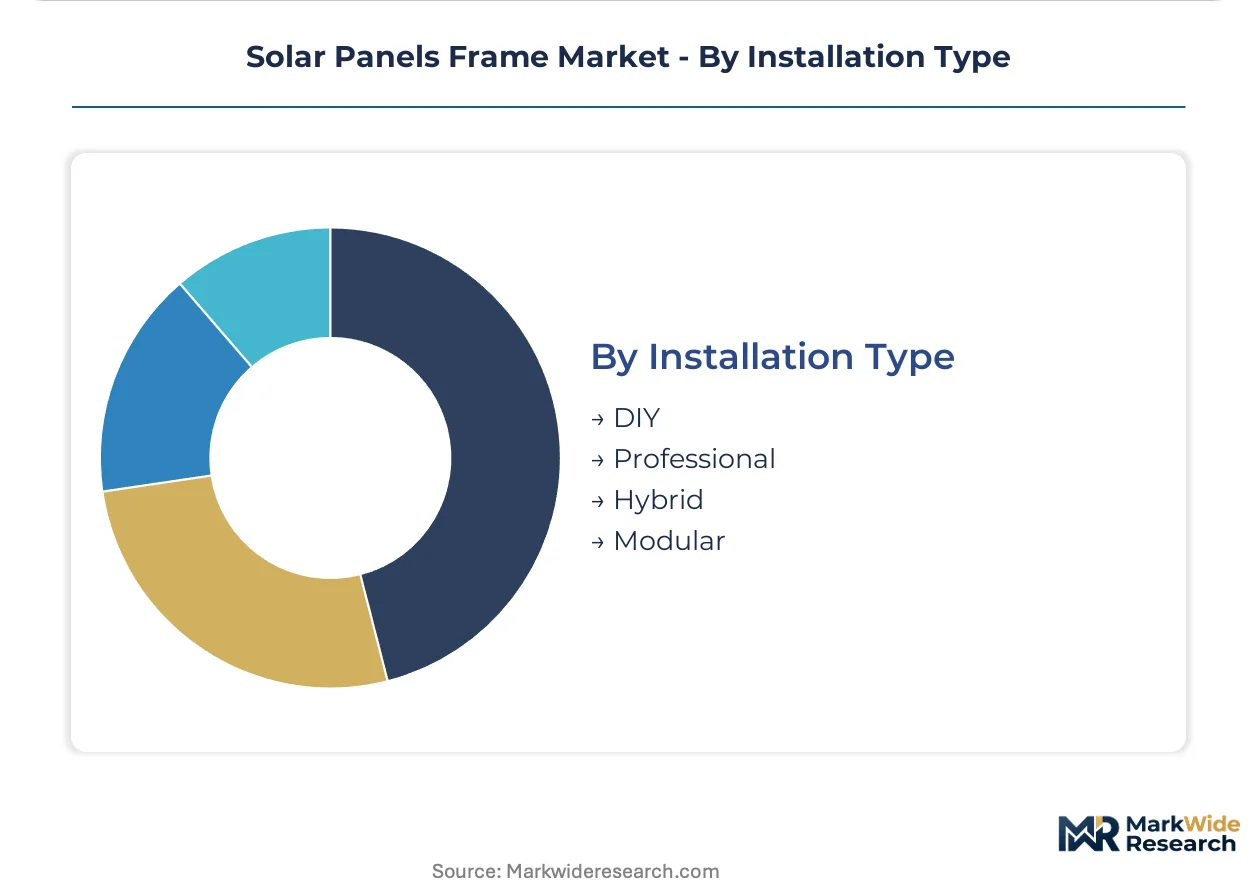
Installation Type:
Professional installation channels capture value through labor efficiency guarantees, while DIY and modular formats expand through e-commerce distribution targeting residential self-installation.
- DIY:Pre-assembled frame kits with integrated mounting hardware serve residential self-installation through e-commerce channels.
- Professional:EPC-contracted installation demands dimensional precision and load certification documentation for utility-scale project acceptance.
- Hybrid:Split procurement models separate frame supply from installation labor in commercial segments seeking cost transparency.
- Modular:Prefabricated frame-and-rail assemblies reduce field labor by 15-20% in tracker applications where torque tube alignment is critical.
Professional installation handles the greatest project value. Modular formats are gaining share fastest as labor costs rise in utility-scale deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's aluminum billet handling capacity underwrites European frame supply security, while India's Mundra port anchors Southeast Asian raw material inflows for domestic extrusion expansion.
China
Dual carbon goals enforce energy consumption caps on aluminum extrusion plants in Shandong and Henan provinces. GB standards mandate energy efficiency benchmarks that constrain frame capacity expansion. The Yangtze River Delta cluster hosts integrated module-frame manufacturing complexes serving Southeast Asian export markets.
India
Utility-scale solar parks in Rajasthan and Gujarat drive frame procurement volumes exceeding 2-gigawatt annual deployment. The PLI scheme for solar manufacturing attracts Southeast Asian frame and mounting system investments with domestic content requirements. Mundra and Hazira ports handle aluminum billet imports for Gujarat-based extrusion facilities serving the Delhi-Mumbai Industrial Corridor.
Germany
Ground-mounted tracker installations in Bavaria and North Rhine-Westphalia specify low-carbon aluminum frames for Green Deal-linked tenders. REACH Annex XVII restrictions on hexavalent chromium anodizing force coating chemistry transitions at extrusion plants. The Rhine-Ruhr industrial zone concentrates EPC procurement teams negotiating long-term billet supply agreements through 2028.
United States
Texas and California utility-scale developers specify 6005A-T6 alloy frames for 600W+ module formats in high-wind zones. The Inflation Reduction Act domestic content bonuses incentivize North American aluminum sourcing for subsidized projects. The Permian Basin solar buildout anchors frame demand from Gulf Coast billet suppliers.
Spain
Ground-mounted solar parks in Extremadura and Andalusia drive tracker-compatible frame procurement for merchant power offtake. EU Green Deal embodied carbon rules mandate low-carbon billet certification for subsidized project eligibility. The Port of Algeciras handles aluminum imports for southern Iberian extrusion facilities.
Solar Panels Frame Market Competitive Landscape
Listed leaders compete with private specialists across capital access and contract flexibility. The vendor base splits between integrated module OEMs with captive frame supply and independent extruders serving project-specific procurement. Three archetypes dominate: aluminum specialists with metallurgical traceability systems, steel fabricators competing on material cost, and integrated solar manufacturers controlling upstream extrusion capacity. M&A activity concentrates on Southeast Asian extrusion assets, while long-term supply agreements now extend through 2027-2028 to hedge raw material volatility.
Among Chinese-integrated solar manufacturers, JinkoSolar and Hanwha Q CELLS anchor the captive supply archetype, each controlling upstream aluminum extrusion partnerships that secure frame availability for module production. Clenergy occupies a specialist position in tracker-adaptive frame geometries, representing the independent fabricator tier that serves EPCs seeking installation labor reduction. These three entities exemplify the competitive divergence between integrated module supply chains and project-specific component procurement.
| Leading Market Players |
|---|
| APEX Aluminum |
| Vishakha Renewables |
| Aluenco |
| Sapa Group |
| Schletter Group |
| Clenergy |
| Xiamen Grace Solar |
| JinkoSolar |
| Hanwha Q CELLS |
| Others |
Pricing and Supply Chain Analysis
Aluminum extrusion capacity utilization in Shandong and Henan provinces shapes both supply concentration and price floors for frame procurement. EPCs purchasing 6005A-T6 alloy for 600W+ module formats face tiered volume commitments that compress margins for undifferentiated suppliers.
Pricing Analysis
Volume-discount tiering structures separate certified low-carbon billet frames from standard-grade alternatives in utility procurement pools. Price differentiation rests on metallurgical traceability and REACH-compliant coating chemistry, with German and Dutch EPCs paying premiums for EPD-verified documentation. Cost compression in standard-grade aluminum intensifies as Chinese dual carbon goals constrain domestic extrusion expansion. Residential retrofit channels exhibit highest price sensitivity, while utility-scale developers prioritize carbon accounting over unit economics.
Supply Chain Analysis
China and India anchor aluminum billet processing and frame extrusion for global solar deployment. Raw material flows draw from Yangtze River Delta integrated complexes and Mundra port import channels serving Gujarat-based facilities. Single-source vulnerability concentrates in Shandong energy-capped plants where GB standards limit expansion flexibility. Distribution runs through EPC direct contracts for utility volumes and secondary distributor networks for residential retrofit segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
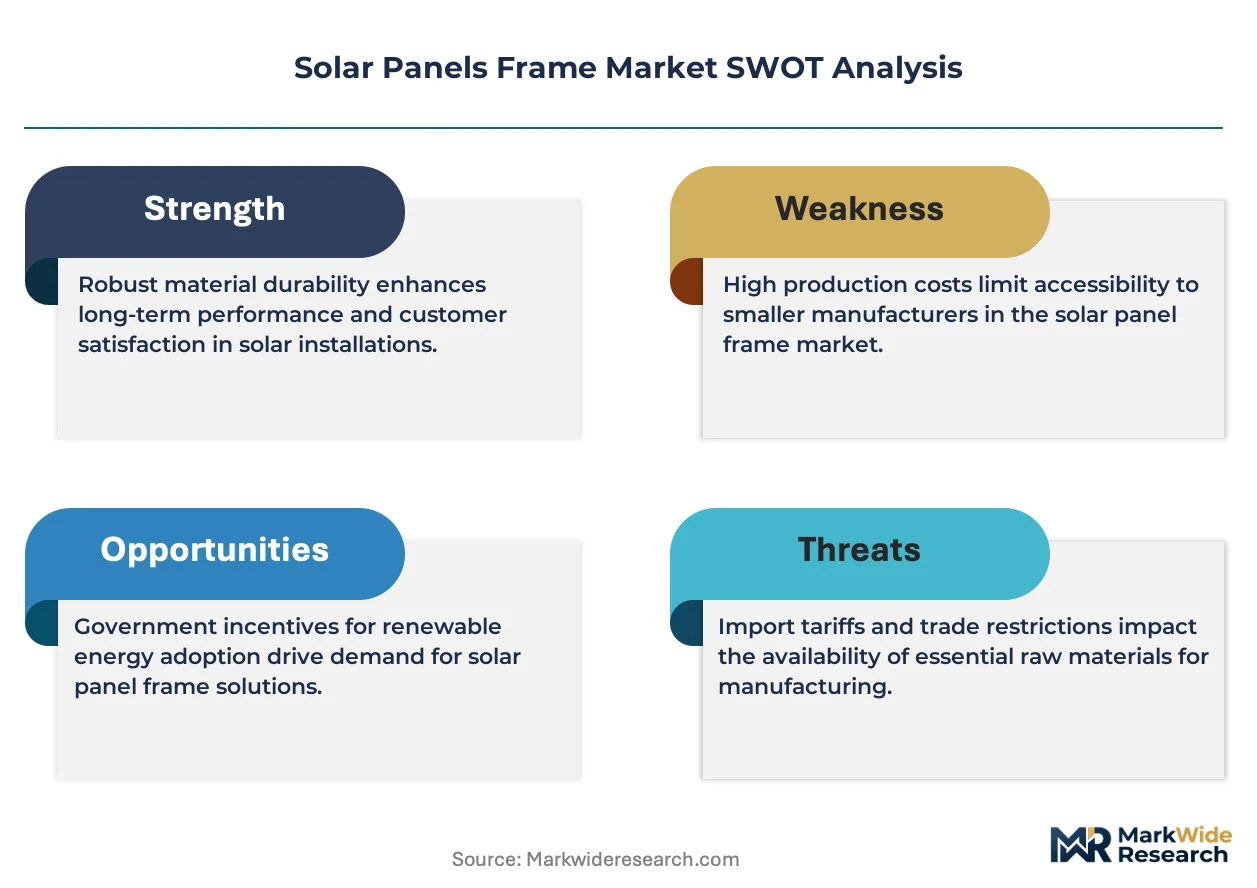
Module format fragmentation above 2.3 meters creates niche opportunities for tracker-adaptive geometries and BIPV structural glazing systems. The divergence between performance-tier and standard-tier procurement pools rewards specialists who certify across multiple segment boundaries.
For Market Incumbents: Compound metallurgical traceability investments to defend against Southeast Asian entrants capturing PLI-linked Indian demand. Lock long-term billet supply agreements through captive partnerships in Vietnam and Thailand. Prioritize REACH-compliant coating chemistry transitions ahead of Annex XVII enforcement timelines. For New Entrants and Emerging Players: After-sales rail compatibility certification services represent underserved white space where incumbent extruders lack installation-channel presence. Target residential retrofit segments in Nordic markets where EPD-verified timber frames command procurement preference. Lead with modular frame-and-rail assemblies that reduce field labor for tracker deployments. For Investors and Strategic Acquirers: Independent tracker-geometry specialists with torque tube-compatible IP portfolios offer acquisition exposure to utility-scale procurement growth. Frame supply viability over the coming decade hinges on low-carbon billet sourcing credentials and anodization chemistry compliance. Monitor India's BIS certification enforcement as a demand inflection signal for domestic extrusion capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Aluminum Billet Supply Agreement | Locks pricing through 2027-2028 to hedge LME volatility for utility-scale EPCs. |
| REACH-Compliant Coating Chemistry Transition | Preserves Green Deal tender eligibility for European frame producers. |
| Tracker-Adaptive Frame Geometry Development | Reduces installation labor by 15-20% for Clenergy and specialized fabricators. |
| Recycled Aluminum Certification Program | Commands price premiums in Nordic utility procurement through EPD verification. |
| Backward Integration into Southeast Asian Extrusion | Secures frame supply for JinkoSolar and Hanwha Q CELLS module production. |
Research Methodology
The analysis maps aluminum alloy grades, installation applications, and end-user segments, each validated through procurement officers at utility-scale developers, EPC project managers, aluminum extrusion plant directors, and residential installation contractors. Primary interview insights combined with secondary validation from customs trade data, SEC 10-K filings, BIS certification registries, and EU Green Deal tender documentation. Bottom-up volume estimates and top-down market sizing triangulate across stakeholder inputs.
Consistency checks validated volume and value outputs against IEA solar deployment projections and regional aluminum consumption patterns. Segmentation dimensions modeled include material type, application format, end-user sophistication tier, and installation channel across the projection horizon. CAGRs derived from weighted average growth rates across segment-level demand drivers, incorporating module format inflation trajectories and tracker penetration assumptions.
Forecasts assume regulatory continuity in EU Green Deal implementation and India's PLI scheme administration; material policy shifts would require re-modeling. Specific risks include LME aluminum price spikes, REACH Annex XVII enforcement acceleration, and BIS certification timeline extensions. Recalibration cycles align with material shifts in module format standards and embodied carbon accounting rules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Box Solar Cookers Market
Solar Power Systems
Trinidad and Tobago Solar Energy Market
Solar Power Systems
Solar PV Tracker Market
Solar Power Systems
Greece Solar Energy Market
Solar Power Systems
United Kingdom Solar Power Market
Solar Power Systems
Off-Grid Solar Power Market
Solar Power Systems
Full-Cell Solar Module Market
Solar Power Systems
Malaysia Solar Energy Market
Solar Power Systems
Bangladesh Solar Energy Market
Solar Power Systems
North America Rooftop Solar Market
Solar Power Systems
Parabolic Solar Cookers Market
Solar Power Systems
Czech Republic Solar Energy Market
Solar Power Systems
Plastic Solar Cell Market
Solar Power Systems
Solar EVA Market
Solar Power Systems
Solar Kiosk Market
Solar Power Systems
Global Micro Solar Inverter Market