
 Off-Grid Solar Lighting Market | 2026-2036
Off-Grid Solar Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Off-Grid Solar Lighting Market Outlook
The skilled photovoltaic technician labor pool across East Africa is collapsing, creating installation backlogs that constrain deployment velocity even where hardware financing exists. SEPCO leverages its integrated manufacturing footprint in Florida to sustain direct-to-municipality contracting for large-scale solar street projects. Azuri Technologies Ltd anchors pay-as-you-go rural distribution through mobile-money platforms that bypass traditional banking infrastructure. Sunna Design SA competes on French-engineered battery management systems that extend operational lifespans in equatorial humidity.
Off-grid solar lighting denotes autonomous luminaire systems that harvest photovoltaic energy, store charge in electrochemical cells typically rated between 10 Ah and 200 Ah, and illuminate spaces through solid-state LED emitters without grid interconnection, serving unelectrified households, remote infrastructure, and mobile security operations. Solar lantern and solar flood light categories dominate current shipment volumes, while solar string lights command disproportionate margin pools in recreational and hospitality channels. Residential end users absorb the majority of unit demand, though military procurement of tactical solar field kits represents the fastest-growing contract segment as defense agencies prioritize energy-independent forward operating bases.
FDA oversight of lithium battery transport safety intersects with EPA hazardous material disposal rules to shape product design and end-of-life obligations for US-distributed equipment, while Kenya's Rural Electrification Authority and India's Ministry of New and Renewable Energy direct subsidy flows that determine viable price points in their respective national markets. Stakeholders must monitor how evolving national storage safety codes and shifting import tariff schedules on photovoltaic modules reshape cost structures and competitive entry barriers across target geographies.
Market Dynamics
Lithium iron phosphate battery chemistry is displacing lead-acid storage across product portfolios, compressing supply chains toward integrated cell manufacturers and eliminating secondary battery distributors from procurement channels.
Growth Catalysts
- Kenya's Rural Electrification Authority subsidies:Direct capital injection reduces household acquisition costs for solar home systems, accelerating penetration in unelectrified counties.
- Mobile-money pay-as-you-go platforms:Digital credit infrastructure bypasses traditional banking exclusion, unlocking addressable demand among unbanked rural populations.
- LED emitter efficiency gains:Solid-state luminaire technology reduces wattage requirements, shrinking photovoltaic panel sizing and lowering system costs for entry-tier products.
Market Restraints
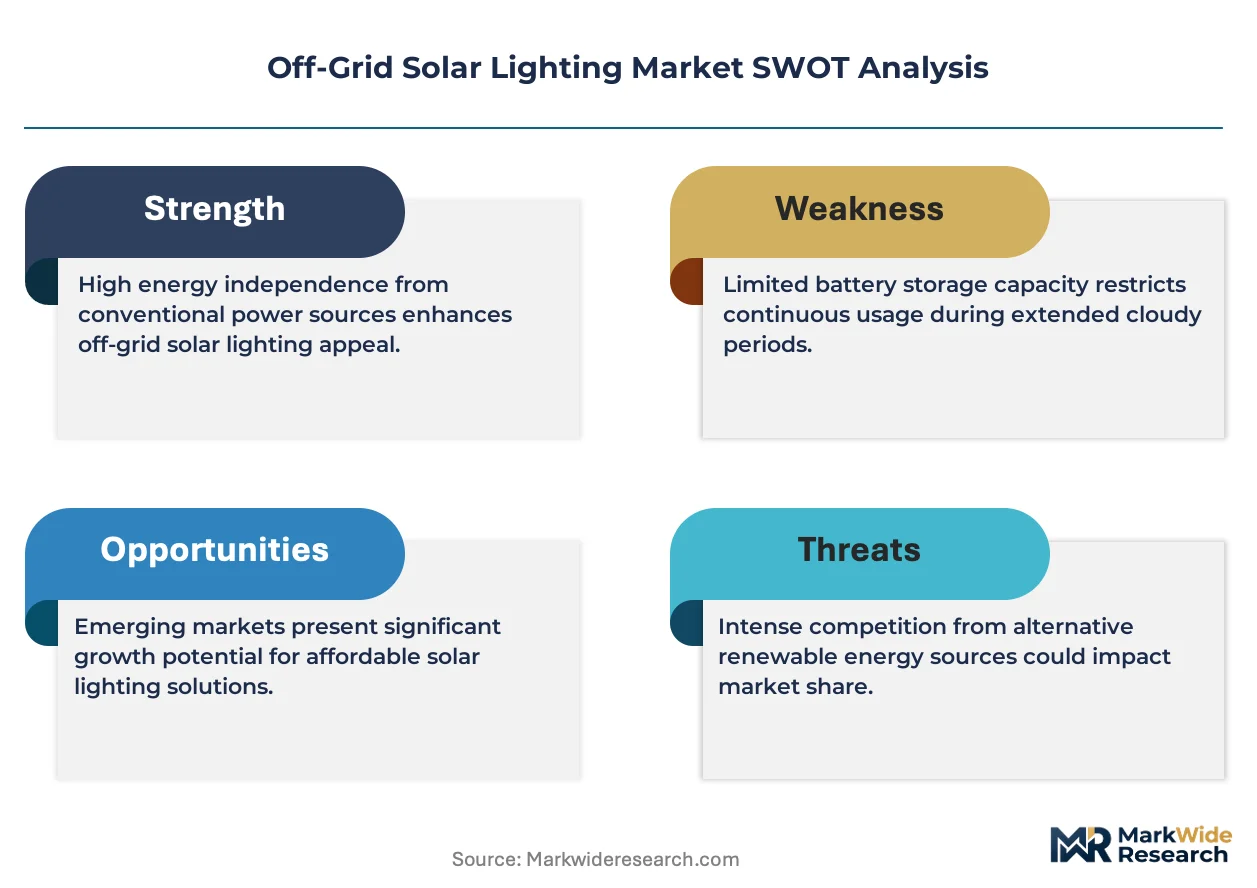
- Lithium carbonate price volatility:Raw material input swings compress gross margins for battery pack assemblers unable to pass through costs to subsidy-capped end markets.
- Photovoltaic module import tariffs:Trade policy friction elevates landed costs for non-integrated manufacturers dependent on overseas cell sourcing.
- Skilled technician scarcity:Installation labor shortages in East Africa create deployment backlogs that throttle sales velocity regardless of hardware availability.
Strategic Opportunities
- Defense energy independence mandates:Military procurement of tactical solar field kits creates premium contract segments with accelerated payment cycles.
- India's Ministry of New and Renewable Energy subsidy expansion:Central government capital allocation targets distributed solar deployment in underserved states.
- IoT-enabled remote monitoring convergence:Cellular connectivity integration enables predictive maintenance services and usage-based financing models.
Industry Challenges
- EPA hazardous material disposal compliance:End-of-life battery collection obligations impose reverse logistics infrastructure costs on distributors without established recycling partnerships.
- BIS certification timelines:Indian safety standard approval delays product launches by 8-14 months, freezing working capital in pre-market inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Off-Grid Solar Lighting Market |
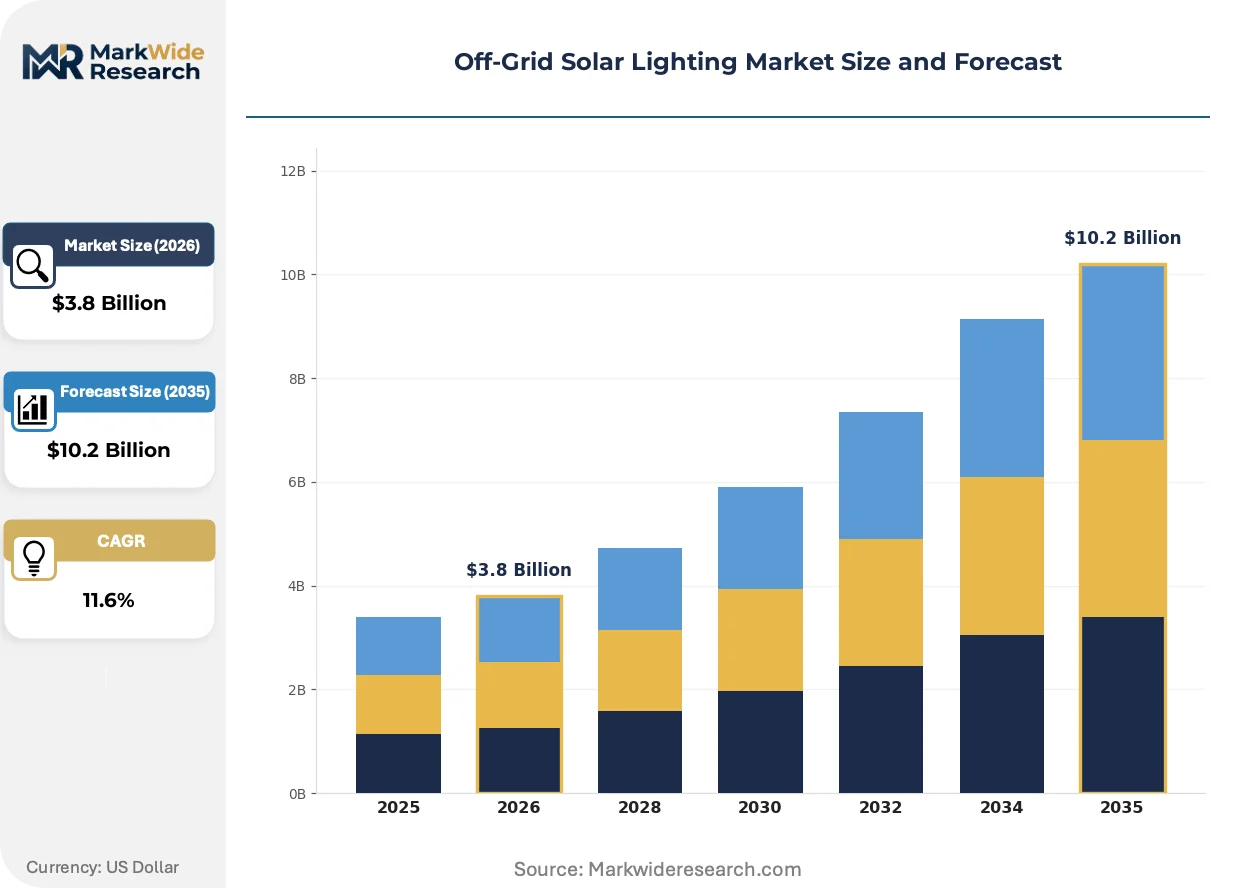
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
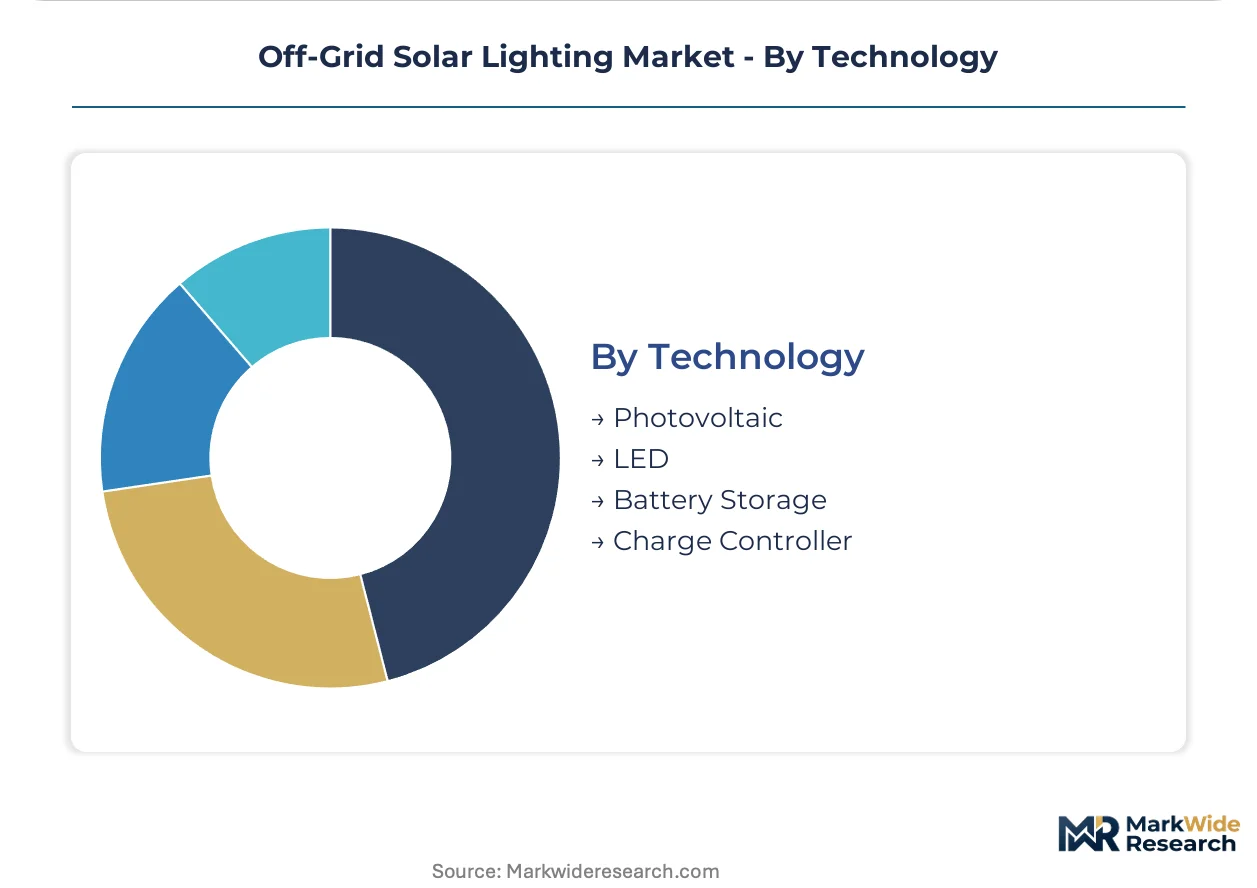
| Segmentation | Product Type: Solar Lanterns, Solar String Lights, Solar Flood Lights, Solar Garden Lights Application: Home Lighting, Outdoor Recreation, Emergency Lighting, Street Lighting End User: Residential, Commercial, Military, Non-Profit Organizations Technology: Photovoltaic, LED, Battery Storage, Charge Controller |
| Companies Covered | SEPCO, Azuri Technologies Ltd, Solar Lighting International, Inc., SolarAid, Fonroche Lighting, Best Solar Street Lights USA, Sunna Design SA, Solar Street Lights USA, SolarOne Solutions, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Off-Grid Solar Lighting Market Strategic Shifts
Product architecture is converging around solid-state electronics and intelligent charge management, while distribution models fragment across direct-to-municipality contracting and mobile-enabled rural financing.
Solid-state LED emitters paired with lithium iron phosphate cells are displacing legacy lead-acid and compact fluorescent combinations in household solar lanterns. Rural electrification programs in Nigeria and Tanzania specify lithium-based systems for new procurements, citing cycle life advantages in high-temperature operating environments. This chemistry migration is compressing the addressable market for lead-acid battery recyclers and forcing incumbent assemblers to retool production lines.
REACH substance restrictions and RoHS compliance mandates in Europe are reshaping component sourcing for manufacturers targeting export markets. Suppliers must certify solder alloys and PCB substrates against hazardous substance thresholds, adding documentation overhead to procurement processes. French-engineered battery management systems are capturing specification preference in humid equatorial climates where thermal runaway risks elevate warranty exposure.
Pay-as-you-go financing unbundles traditional retail distribution by embedding credit decisions in mobile network operator platforms. East African households purchase solar home systems through micro-installment plans deducted from M-Pesa balances, displacing cash-based corner store transactions. This channel shift concentrates customer relationship value with platform operators rather than hardware vendors, altering brand loyalty dynamics in Kenya and Ethiopia.
Off-Grid Solar Lighting Market Segmentation
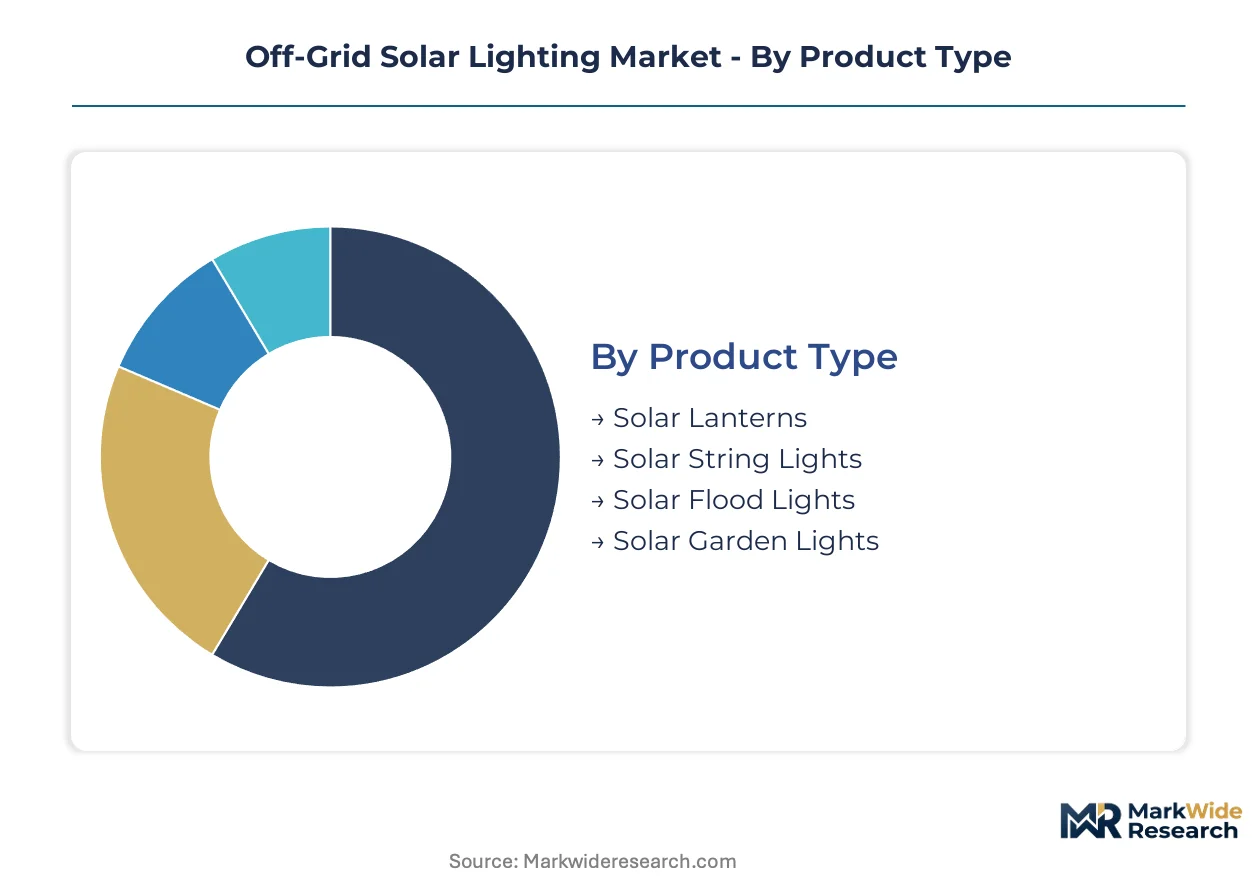
Off-grid solar lighting markets fragment across product architectures, deployment contexts, and financing mechanisms. Each segmentation dimension reveals distinct procurement patterns, margin structures, and regulatory exposure profiles that shape vendor strategy.
Product Type:
Domestic manufacturing concentrates solar lanterns and flood lights for regional African markets, while solar string lights and garden fixtures flow predominantly through export channels to European and North American retail.
- Solar Lanterns:Compact photovoltaic units integrate 10-50 Ah lithium iron phosphate cells with solid-state LED emitters rated for 300-1000 lumens. Demand clusters in rural Kenyan and Nigerian households purchasing through pay-as-you-go platforms, where acquisition cost sensitivity drives specification toward entry-tier lumen output.
- Solar Flood Lights:High-output luminaires deploy 100-200 Ah storage and 50-200 watt-equivalent LED arrays for perimeter security and commercial yard illumination. Municipal procurement in Indian states and Ethiopian urban centers sustains volume, with India's Ministry of New and Renewable Energy subsidy eligibility determining viable price points.
- Solar String Lights:Decorative low-voltage arrays target recreational and hospitality channels with premium margin profiles.
- Solar Garden Lights:Stake-mounted pathway luminaires serve residential landscaping segments in developed markets with established retail distribution.
Solar lanterns command the established base. The steepest expansion runs through solar flood lights.
Application:
Cost tier stratification separates subsidized rural electrification programs from self-funded commercial and recreational deployments.
- Home Lighting:Distributed solar home systems replace kerosene and candle illumination in unelectrified households, with Kenya's Rural Electrification Authority directing capital toward verified product registries.
- Street Lighting:Autonomous pole-mounted systems with 150-300 Ah storage serve municipalities lacking grid extension budgets, with SEPCO contracting directly with Florida and Ethiopian city administrations.
- Outdoor Recreation:Portable and decorative systems target camping, marine, and hospitality use cases with minimal regulatory friction.
- Emergency Lighting:Backup-optimized designs with rapid-charge capability address disaster preparedness and humanitarian stockpiling requirements.
Home lighting absorbs unit volume concentration. Street lighting delivers the fastest contract value expansion.
End User:
Customer type determines financing mechanism, with residential segments dependent on micro-credit infrastructure and military procurement operating on accelerated federal payment cycles.
- Residential:Unelectrified households across sub-Saharan Africa and rural India constitute the core addressable market, with mobile-money platforms enabling credit access for unbanked populations.
- Military:Defense agencies prioritize tactical solar field kits for forward operating base energy independence, with procurement specifications emphasizing ruggedized enclosures and electromagnetic compatibility.
- Commercial:Agricultural operations, remote mining camps, and cellular tower operators purchase higher-capacity systems with direct capital expenditure.
- Non-Profit Organizations:Humanitarian and development agencies deploy subsidized systems through grant-funded programs in conflict and disaster zones.
Residential end users anchor volume. Military procurement climbs the fastest.
Technology:
Supply concentration in integrated cell manufacturing is compressing procurement channels and eliminating secondary battery distributors from value chains.
- Battery Storage:Lithium iron phosphate chemistry displaces lead-acid alternatives across product tiers, with cycle life advantages in high-temperature equatorial environments driving specification preference in Kenyan and Tanzanian rural electrification tenders.
- LED:Solid-state emitter efficiency gains reduce photovoltaic panel sizing requirements, lowering system costs for entry-tier products while extending operational lifespan.
- Photovoltaic:Module sourcing faces tariff exposure for non-integrated manufacturers dependent on overseas cell production.
- Charge Controller:Intelligent power management electronics optimize depth-of-discharge profiles and enable IoT-enabled remote monitoring convergence.
Battery storage commands technology investment focus. LED efficiency gains drive the steepest cost reduction trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kenya deploys off-grid solar lighting predominantly through rural household pay-as-you-go platforms, while India channels capital toward municipal street infrastructure and military buyers in the United States prioritize tactical field kits for forward operating bases.
Kenya
Rural electrification drives household adoption of solar lanterns and home systems through mobile-money financing. The Rural Electrification Authority directs subsidy capital toward verified product registries, reducing acquisition costs for unelectrified counties. Nairobi anchors distribution coordination for East African supply chains.
India
The Ministry of New and Renewable Energy expands central subsidy allocation for distributed solar deployment in underserved states. BIS certification requirements delay product launches by 8-14 months, freezing working capital in pre-market inventory. Maharashtra and Gujarat concentrate manufacturing and state-level procurement administration.
United States
Defense agencies prioritize energy-independent forward operating bases, creating premium contract segments for tactical solar field kits. FDA oversight of lithium battery transport safety intersects with EPA hazardous material disposal rules to shape product design obligations. Florida sustains direct-to-municipality contracting for large-scale solar street projects.
Nigeria
Rural electrification programs specify lithium-based systems for new procurements, citing cycle life advantages in high-temperature operating environments. The country's national renewable energy agency channels subsidy capital into distributed solar deployment. Lagos and Abuja coordinate import logistics and federal tender administration.
France
REACH substance restrictions and RoHS compliance mandates reshape component sourcing for manufacturers targeting export markets. French-engineered battery management systems capture specification preference in humid equatorial climates. Paris-based engineering clusters concentrate design and certification expertise for African market entry.
Off-Grid Solar Lighting Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with manufacturing concentration in Florida and French engineering clusters creating geographic differentiation in procurement channels. The vendor base organizes around three strategic archetypes: integrated manufacturers with captive cell production, pay-as-you-go platform operators leveraging mobile-money infrastructure, and specialized battery management system designers. Competitive moves concentrate on backward integration into lithium cell manufacturing and strategic partnerships with mobile network operators for rural distribution access.
Within the integrated manufacturing tier, SEPCO exemplifies direct-to-municipality contracting capability, while Sunna Design SA occupies a position representing French-engineered thermal management specialization for equatorial deployment. Azuri Technologies Ltd anchors the pay-as-you-go platform archetype, embedding credit decisions in mobile network operator infrastructure to bypass traditional banking exclusion in East African markets.
| Leading Market Players |
|---|
| SEPCO |
| Azuri Technologies Ltd |
| Solar Lighting International, Inc. |
| SolarAid |
| Fonroche Lighting |
| Best Solar Street Lights USA |
| Sunna Design SA |
| Solar Street Lights USA |
| SolarOne Solutions, Inc. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts with integrated lithium cell manufacturers lock in supply access and price visibility for battery pack assemblers serving Kenya's Rural Electrification Authority subsidy programs, compressing procurement channels while insulating against lithium carbonate spot market volatility.
Pricing Analysis
Project-based contracting dominates municipal solar street lighting procurement, with India's Ministry of New and Renewable Energy subsidy eligibility and BIS certification tier serving as primary price differentiation drivers. Cost compression in entry-tier solar lanterns is intensifying because mobile-money platform operators extract financing margin from hardware vendors. Rural households purchasing through pay-as-you-go plans exhibit highest price sensitivity, while defense agencies procuring tactical field kits demonstrate lowest sensitivity due to energy independence mandates.
Supply Chain Analysis
Inventory lead times for lithium iron phosphate cells stretch 12-16 weeks for non-integrated assemblers dependent on Chinese and South Korean cell production. Battery pack manufacturing draws from photovoltaic module inputs facing tariff exposure in the United States and India, plus LED emitter components subject to REACH substance restrictions in European export markets. Single-source vulnerability concentrates in integrated cell manufacturers eliminating secondary battery distributors. Distribution runs through direct-to-municipality contracting for large-scale projects and mobile-enabled rural financing for household systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Off-grid solar lighting sits in early-cycle expansion as rural electrification programs in sub-Saharan Africa and India accelerate household penetration before grid extension reaches unelectrified counties.
For Market Incumbents: Consolidate backward integration into lithium iron phosphate cell manufacturing to escape margin compression from raw material volatility and capture specification preference in Kenyan and Tanzanian rural electrification tenders. Deepen channel control through exclusive mobile-money platform partnerships that lock out competing hardware vendors from M-Pesa and similar infrastructure.
For New Entrants and Emerging Players: Predictive maintenance service layers represent an under-served gap where incumbents lack IoT-enabled remote monitoring capabilities. Target military procurement segments in the United States and European defense agencies with ruggedized tactical solar field kits engineered for electromagnetic compatibility. Pursue direct contracting relationships with national renewable energy agencies rather than competing through retail distribution.
For Investors and Strategic Acquirers: Capital is best deployed toward pay-as-you-go platform operators with embedded mobile-money credit infrastructure and established customer relationships in East African markets. The five-to-ten year viability window favors asset-light distribution models over capital-intensive manufacturing. Watch for BIS certification approval acceleration in India as an inflection indicator for working capital release and product launch velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Manufacturing | Captive lithium iron phosphate supply secures margin control against raw material volatility in Kenyan subsidy markets. |
| Mobile-Money Platform Partnership | Exclusive M-Pesa integration locks in customer access for rural household solar home system distribution. |
| Defense Agency Certification | Ruggedized tactical kit approval opens premium contract segments with accelerated federal payment cycles. |
| IoT-Enabled Remote Monitoring | Cellular connectivity integration enables predictive maintenance services and usage-based financing models. |
| BIS Certification Pre-Investment | Early compliance commitment reduces Indian market entry delays and frozen working capital exposure. |
Study Parameters
Initial hypotheses were tested against primary input from rural electrification program directors, battery pack manufacturing executives, mobile-money platform operators, and municipal procurement officers, then refined through secondary validation against Kenya's Rural Electrification Authority tender databases, India's Ministry of New and Renewable Energy subsidy registries, EPA hazardous material disposal filings, and customs trade records for photovoltaic module imports. Bottom-up unit shipment estimates and top-down addressable market sizing were triangulated to converge on volume and value outputs.
Variance decomposition across product type, application context, end-user category, and technology platform shaped the analytical framework throughout the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers and policy subsidy trajectories. Forecast inputs incorporated lithium carbonate price indices, LED emitter efficiency curves, and mobile-money penetration rates by national market.
Forecasts assume regulatory continuity in Kenya's Rural Electrification Authority subsidy regimes and India's BIS certification timelines; material policy shifts would require re-modeling. Lithium supply constraints, photovoltaic module tariff escalations, or mobile-money platform consolidation represent specific risk factors that could revise trajectory. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Spray-On Solar Cells Market
Solar Power Systems
Asia-Pacific Rooftop Solar Market
Solar Power Systems
Solar Panel Cleaning Equipment Market
Solar Power Systems
Solar Metal Roof Market
Solar Power Systems
Asia-Pacific Solar Tracker Market
Solar Power Systems
Solar Simulator Market
Solar Power Systems
Solar PV Inverter Market
Solar Power Systems
Floating Solar Panels Market
Solar Power Systems
Mexico Rooftop Solar Market
Solar Power Systems
Canada Distributed Solar Power Generation Market
Solar Power Systems
Solar Microinverter and Power Optimizer Market
Solar Power Systems
US Solar Power Meters Market
Solar Power Systems
Solar Concentrator Market
Solar Power Systems
Solar PV Carport Market
Solar Power Systems
Asia Pacific Solar Inverter Market
Solar Power Systems
Saudi Arabia Solar Energy Market