
 Thailand Solar Energy Market | 2026-2036
Thailand Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Solar Energy Market Analytics
Multi-source procurement of photovoltaic modules is rebalancing toward domestic and regional suppliers as developers mitigate tariff exposure and logistics risk. BCPG Public Company Limited leverages its utility-scale project pipeline across Thailand's renewable energy zones. Canadian Solar Inc. anchors module supply agreements with Thai independent power producers seeking bankable equipment warranties. Energy Absolute Public Company Limited specializes in integrated solar-plus-storage developments that combine generation assets with lithium-ion battery systems.
Thailand solar energy encompasses photovoltaic power generation, thermal collection, and grid-connected storage systems utilizing crystalline silicon cells with conversion efficiencies typically ranging from 20% to 22% in commercial modules. The technology serves industrial load centers, municipal utilities, and distributed commercial consumers seeking to reduce dependence on natural gas-fired generation. Photovoltaic panels dominate installed capacity across utility and commercial segments, while bifacial modules capture growing share in ground-mounted installations where albedo reflection boosts yield. Floating solar arrays represent an emerging installation type, capitalizing on Thailand's reservoir infrastructure to circumvent land-use constraints around Bangkok and the Central Plains.
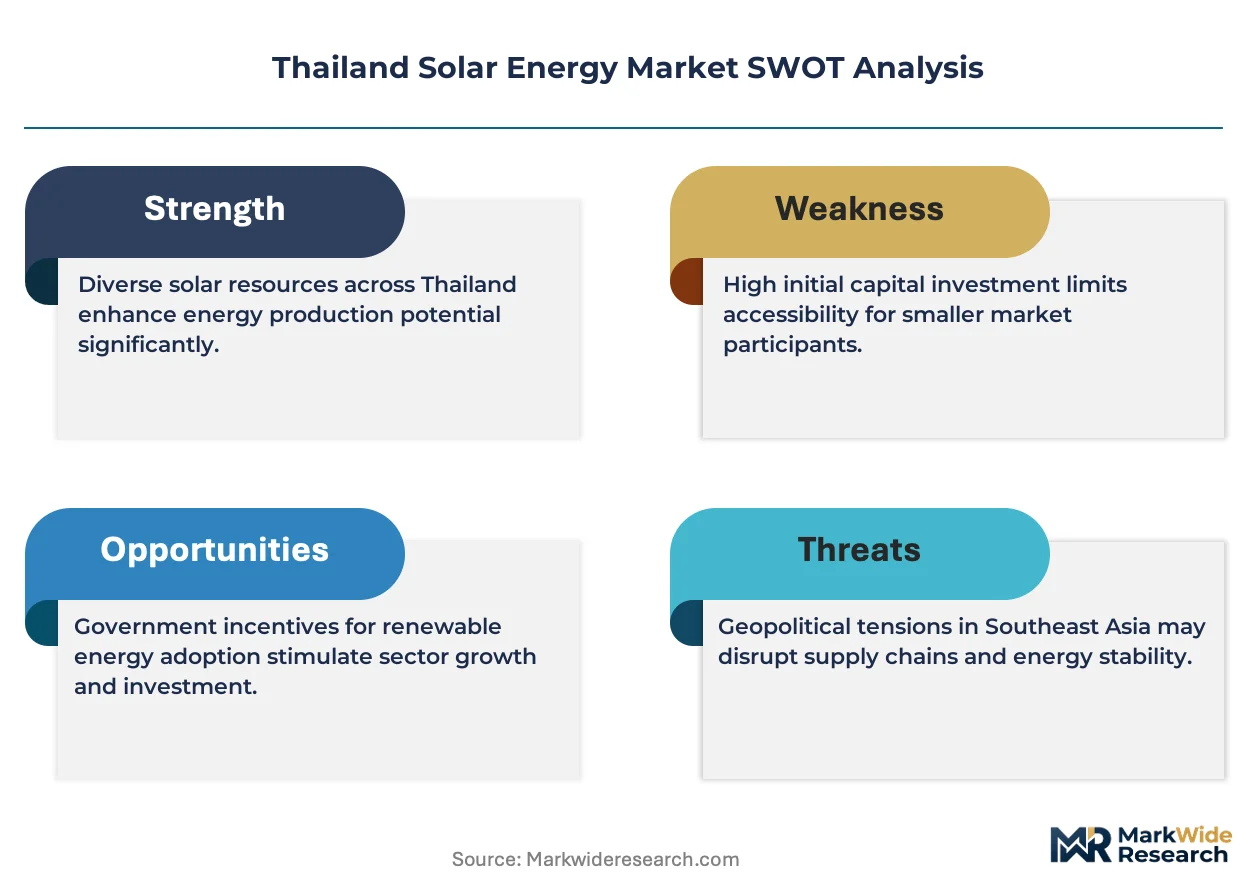
The Energy Regulatory Commission governs power purchase agreement terms and feed-in tariff structures that determine project bankability for Thai solar developers. The Ministry of Energy's renewable energy targets and the Department of Alternative Energy Development and Efficiency's permitting frameworks shape deployment timelines and technology qualification requirements. Grid code standards administered by the Electricity Generating Authority of Thailand dictate inverter performance and interconnection protocols for utility-scale facilities. Stakeholders must monitor regulatory revisions to net metering rules and storage mandate proposals that could alter residential and commercial segment economics.
Market Dynamics
Feed-in tariff revisions by the Energy Regulatory Commission are redirecting developer capital from distributed rooftop systems toward utility-scale ground-mounted installations, compressing project timelines and reshaping equipment procurement patterns across Thailand's renewable energy zones.
Growth Catalysts
- Industrial Load Growth:Automotive suppliers and electronics manufacturers in the Eastern Economic Corridor are executing renewable power purchase agreements to offset natural gas price volatility and secure carbon-neutral supply chain credentials.
- Alternative Energy Development and Efficiency Incentives:The Ministry of Energy's permitting frameworks prioritize utility-scale solar zones with streamlined environmental clearances and grid interconnection protocols.
- Bifacial Module Technology:Ground-mounted installations incorporating dual-sided photovoltaic panels are capturing albedo reflection gains, improving capacity factors on Thailand's high-reflectivity agricultural and reservoir-adjacent terrain.
Market Restraints
- Polysilicon Supply Concentration:Thai developers remain exposed to upstream polysilicon price volatility originating from concentrated Chinese metallurgical-grade silicon refining capacity.
- Grid Interconnection Queues:Electricity Generating Authority of Thailand transmission upgrade timelines create permitting bottlenecks for utility-scale projects exceeding 100 megawatts in the Central Plains region.
- Land-Use Competition:Agricultural protection zones around Bangkok and the Chao Phraya Delta restrict available terrain for ground-mounted arrays, elevating site acquisition costs relative to regional benchmarks.
Strategic Opportunities
- Floating Solar Deployment:Reservoir infrastructure at Sirindhorn and Ubol Ratana dams offers 2,000+ megawatts of untapped surface area circumventing land-use constraints in densely populated provinces.
- Solar-Plus-Storage Integration:Lithium-ion battery cost declines are enabling hybrid projects that capture peak pricing spreads and provide frequency regulation services to the national grid.
- Net Metering Expansion:Proposed Energy Regulatory Commission revisions to residential feed-in tariffs could unlock distributed generation growth in Bangkok metropolitan condominium and commercial building segments.
Industry Challenges
- Skilled Installation Labor Scarcity:Certified electrical technicians familiar with IEC 62446 commissioning standards remain concentrated in Bangkok, constraining deployment velocity in secondary provinces.
- Equipment Warranty Enforcement:Module performance guarantees spanning 25 years create long-tail liability exposure for Thai independent power producers sourcing from multi-tier supplier bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Solar Energy Market |
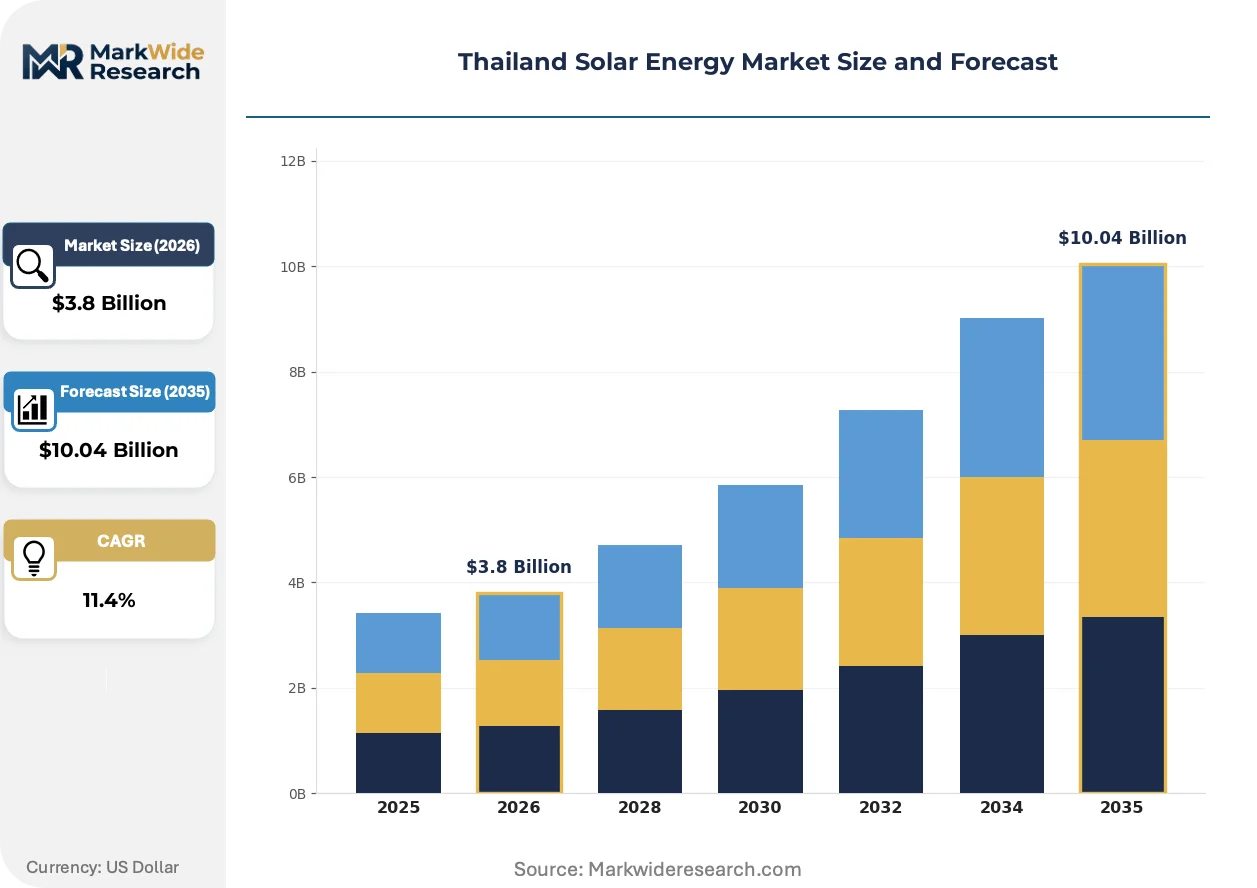
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Panels, Solar Inverters, Storage Systems, Charge Controllers Technology: C-Si, Thin Film, Bifacial, Concentrated Solar Power End User: Residential, Commercial, Industrial, Utilities Installation Type: Ground-mounted, Rooftop, Floating, Hybrid |
| Companies Covered | BCPG Public Company Limited, Canadian Solar Inc., Energy Absolute Public Company Limited, Sungrow Power Supply Co. Ltd., Delta Electronics (Thailand) PLC, SPCG Public Company Limited, B.Grimm Power PLC, Hitachi Energy Thailand, Thai Solar Energy PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Solar Energy Market Evolving Landscape
Technology convergence and procurement model evolution are compressing project development cycles while elevating performance expectations for Thai solar assets. Three developments merit particular attention.
Bifacial photovoltaic modules with heterojunction cell architecture are electrifying utility-scale project economics in Thailand's high-albedo agricultural regions. Independent power producers including those serving Eastern Economic Corridor industrial estates are specifying bifacial panels for new ground-mounted installations. The technology is electrifying yield projections by 8-12% relative to monofacial equivalents, compressing levelized cost thresholds and enabling merchant power sales without full feed-in tariff dependency.
Energy Regulatory Commission amendments to power purchase agreement structures are mandating stricter grid code compliance for inverter reactive power capabilities. The revised interconnection standards require utility-scale facilities to provide voltage ride-through and frequency response services previously reserved for conventional thermal generators. Large-scale solar farms in the Northeast and Central Plains are retrofitting inverter fleets or specifying advanced power electronics to maintain offtake contract eligibility.
Industrial offtakers are consolidating procurement through multi-year renewable energy supply contracts with independent power producers, bypassing traditional utility intermediaries. Automotive and electronics manufacturers with Scope 2 emissions targets are executing direct bilateral agreements for solar-generated electrons with physical delivery guarantees. This pattern is most visible among Japanese and Korean multinational suppliers operating manufacturing facilities in Rayong and Chonburi provinces.
Thailand Solar Energy Market Segmentation
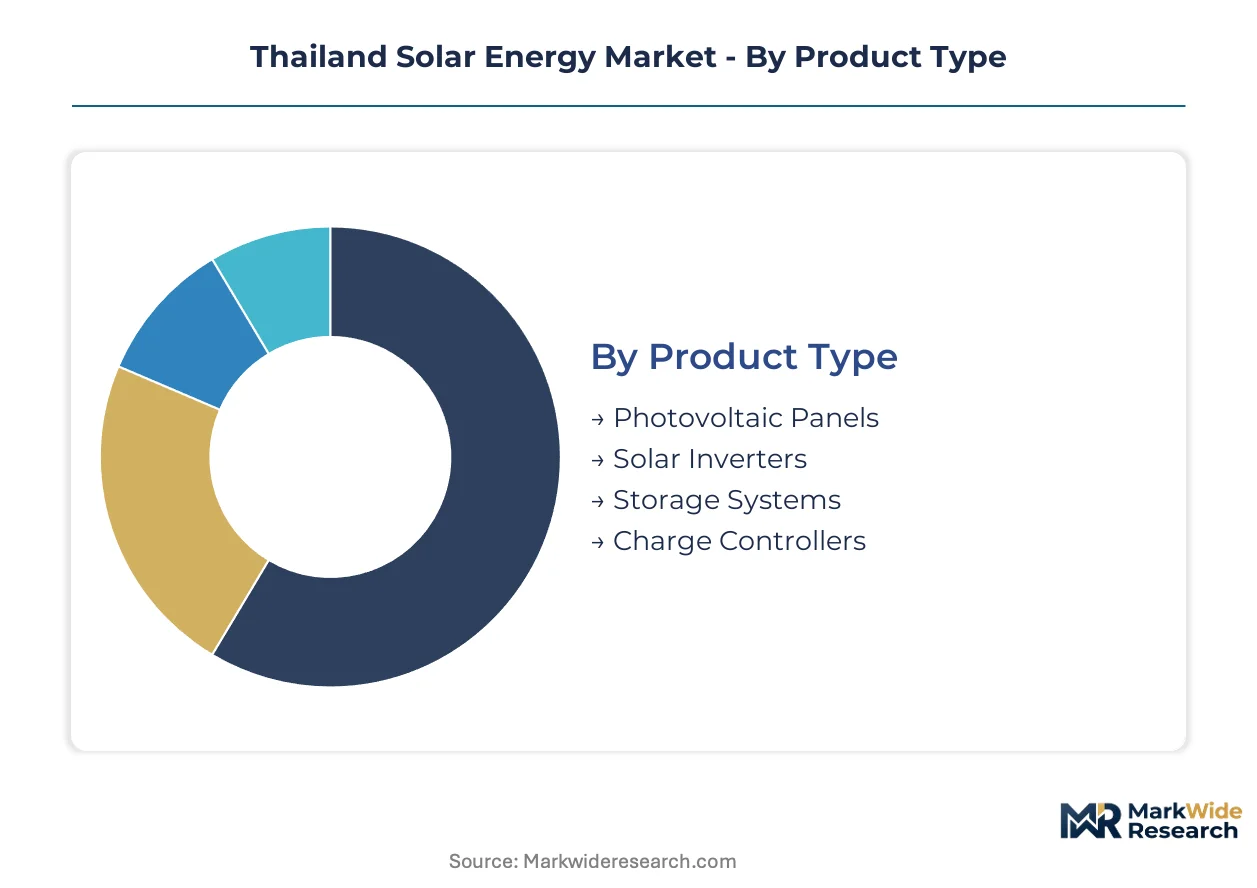
Thailand's solar market stratifies across technology generations, installation topologies, and customer scale. Each segmentation axis carries distinct procurement patterns, regulatory exposure, and margin profiles that shape developer strategy and equipment vendor positioning.
Product Type:
Module specifications and balance-of-system components define project bankability and long-term performance guarantees.
- Photovoltaic Panels:Crystalline silicon modules with 20-22% commercial efficiency dominate procurement volumes across Eastern Economic Corridor industrial estates. Thai independent power producers specify tier-1 manufacturer warranties to secure project financing from domestic banking syndicates.
- Solar Inverters:String and central inverter architectures convert DC generation to grid-compliant AC output. Utility-scale facilities exceeding 100 megawatts deploy central inverters with reactive power capabilities mandated by Electricity Generating Authority of Thailand grid codes.
- Storage Systems:Lithium-ion battery integration enables peak shifting and frequency regulation services.
- Charge Controllers:DC-DC conversion electronics manage battery charging cycles in off-grid and hybrid configurations.
Photovoltaic panels lead on scale; storage systems lead on momentum.
Technology:
Cell architecture and module construction determine yield profiles and land-use intensity across Thailand's high-insolation zones.
- C-Si:Monocrystalline and polycrystalline silicon cells anchor installed capacity with proven degradation rates and established recycling pathways.
- Thin Film:Cadmium telluride and amorphous silicon technologies offer temperature coefficient advantages in Thailand's tropical climate.
- Bifacial:Dual-sided photovoltaic panels capture direct and reflected irradiance, improving capacity factors on high-albedo agricultural terrain and reservoir-adjacent sites around Sirindhorn Dam.
- Concentrated Solar Power:Parabolic trough and tower systems with thermal storage enable dispatchable renewable generation.
C-Si dominates current deployment; bifacial modules are climbing the fastest.
End User:
Customer scale determines contract structures, financing mechanisms, and regulatory engagement intensity.
- Residential:Distributed rooftop systems under net metering frameworks serve Bangkok metropolitan condominium owners and provincial households.
- Commercial:Office buildings and retail facilities execute behind-the-meter installations to offset retail electricity tariffs.
- Industrial:Automotive suppliers and electronics manufacturers in Rayong and Chonburi provinces execute renewable power purchase agreements to secure carbon-neutral supply chain credentials.
- Utilities:State-owned and independent power producers develop utility-scale facilities under feed-in tariff and auction mechanisms administered by the Energy Regulatory Commission.
Utilities anchor capacity additions; industrial offtakers drive contract innovation.
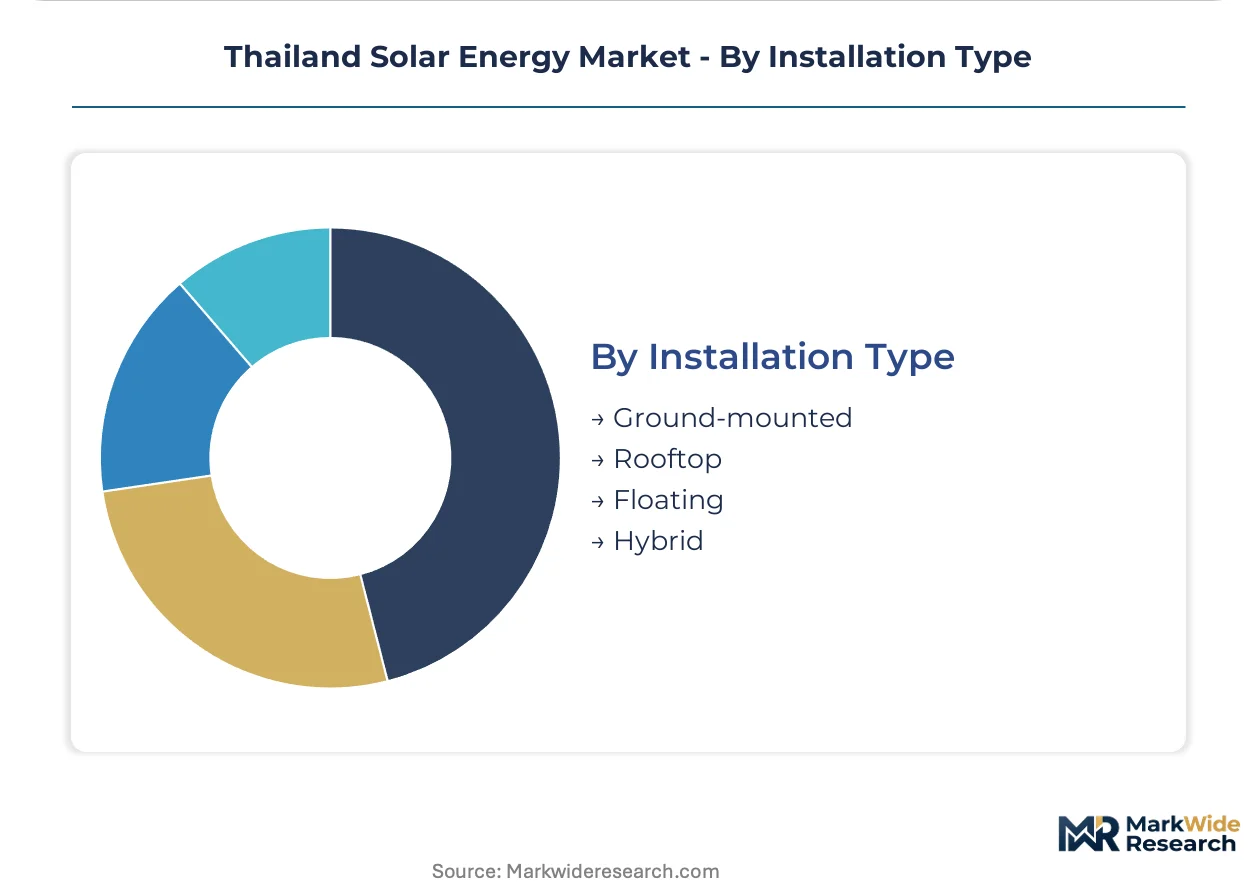
Installation Type:
Mounting topology dictates site acquisition constraints, environmental permitting pathways, and engineering procurement construction cost structures.
- Ground-mounted:Fixed-tilt and tracking arrays on agricultural and brownfield terrain constitute the majority of utility-scale capacity.
- Rooftop:Distributed commercial and industrial installations on manufacturing facilities reduce grid dependency and operational energy expenditures.
- Floating:Reservoir-mounted arrays at Ubol Ratana and other dam infrastructure circumvent land-use restrictions in densely populated Central Plains provinces.
- Hybrid:Co-located solar-plus-storage configurations capture peak pricing spreads and provide ancillary services to the national grid.
Ground-mounted arrays dominate capacity; floating solar shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost-of-compliance gaps across Southeast Asian feed-in tariff regimes are redirecting developer capital toward Thailand's streamlined permitting frameworks and established grid interconnection protocols administered by the Energy Regulatory Commission.
Eastern Economic Corridor
Automotive suppliers and electronics manufacturers in Rayong and Chonburi provinces are executing renewable power purchase agreements to offset natural gas price volatility. The Ministry of Energy's permitting frameworks prioritize utility-scale solar zones with streamlined environmental clearances. Industrial estates in Map Ta Phut and Laem Chabang anchor procurement concentration for behind-the-meter installations.
Central Plains
Agricultural protection zones around Bangkok restrict available terrain for ground-mounted arrays, elevating site acquisition costs relative to regional benchmarks. The Electricity Generating Authority of Thailand's transmission upgrade timelines create permitting bottlenecks for utility-scale projects exceeding 100 megawatts. Floating solar deployment at reservoir infrastructure circumvents land-use constraints in densely populated provinces.
Northeast Region
High-insolation zones with high-reflectivity agricultural terrain attract bifacial module installations capturing albedo reflection gains. Grid code standards mandate inverter reactive power capabilities for utility-scale facilities. Khon Kaen and Udon Thani provinces host independent power producers developing merchant power sales without full feed-in tariff dependency.
Northern Region
Reservoir infrastructure at Sirikit Dam offers untapped surface area for floating solar arrays. The Department of Alternative Energy Development and Efficiency's technology qualification requirements shape deployment timelines for hybrid solar-plus-storage configurations. Chiang Mai and Lampang provinces concentrate distributed commercial installations on manufacturing facilities.
Thailand Solar Energy Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue integrated solar-plus-storage configurations and floating solar specialization. The vendor base stratifies across utility-scale independent power producers, module supply specialists, and balance-of-system equipment fabricators. Three archetypes dominate: domestic independent power producers with project development pipelines, international module manufacturers with bankable equipment warranties, and power electronics specialists with grid code compliance capabilities. Competitive moves concentrate on strategic partnerships for reservoir-adjacent site access and technology licensing for bifacial module deployment.
Within the domestic independent power producer tier, BCPG Public Company Limited and Energy Absolute Public Company Limited exemplify developers with integrated project pipelines across Thailand's renewable energy zones. Among international module suppliers, Canadian Solar Inc. anchors equipment supply relationships with Thai independent power producers. These three entities represent distinct competitive positioning: domestic development expertise, integrated generation-storage capabilities, and bankable manufacturing scale.
| Leading Market Players |
|---|
| BCPG Public Company Limited |
| Canadian Solar Inc. |
| Energy Absolute Public Company Limited |
| Sungrow Power Supply Co. Ltd. |
| Delta Electronics (Thailand) PLC |
| SPCG Public Company Limited |
| B.Grimm Power PLC |
| Hitachi Energy Thailand |
| Thai Solar Energy PLC |
| Others |
Value Network & Pricing Analysis
Thailand's renewable energy certificate mandates gate qualified module supply and premium-tier pricing access for developers seeking offtake eligibility under Energy Regulatory Commission frameworks. These sustainability requirements compress procurement pools toward tier-1 manufacturers with verified carbon footprints, elevating contract premiums for bankable equipment warranties that satisfy domestic banking syndicate standards.
Pricing Analysis
Input-cost pass-through from polysilicon and lithium-ion battery raw materials shapes project-level pricing dynamics across Thai solar developments. Contract-based long-term offtake structures dominate utility-scale procurement, with price differentiation resting on module efficiency tier and inverter grid-code certification grade. Cost compression in standard-tier equipment is intensifying because Chinese polysilicon spot volatility feeds directly into engineering-procurement-construction bids. Industrial offtakers in the Eastern Economic Corridor exhibit lowest price sensitivity due to carbon-neutral supply chain mandates, while residential net-metering participants face highest sensitivity to upfront capital requirements.
Supply Chain Analysis
Single-source vulnerability sits with Chinese polysilicon refining capacity, which feeds crystalline silicon wafer production across Thai module assembly facilities. Geographic supply concentration centers on China, Vietnam, and Malaysia for photovoltaic cell fabrication, with balance-of-system components drawing from Taiwanese and South Korean power electronics manufacturers. Raw material dependencies rest on metallurgical-grade silicon, silver metallization paste, and aluminum framing extrusions. Tariff exposure on Chinese-origin cells creates procurement hedging behavior among Thai independent power producers. Distribution runs through Bangkok-based engineering-procurement-construction contractors with provincial deployment capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's solar market functions as a stable compounder, with industrial decarbonization mandates from Japanese and Korean automotive multinationals driving steady capacity absorption across the Eastern Economic Corridor.
For Market Incumbents: Deepen backward integration into lithium-ion battery assembly to capture solar-plus-storage margin pools that emerging pure-play developers cannot access. Secure long-term site leases at reservoir-adjacent locations before floating solar zoning restrictions tighten under Department of Alternative Energy Development and Efficiency permitting revisions. Prioritize IEC 62446-certified installation labor training programs to defend deployment velocity against skilled technician scarcity in secondary provinces. For New Entrants and Emerging Players: Bifacial module technology with heterojunction cell architecture offers a technology-first wedge into utility-scale ground-mounted segments where albedo reflection gains justify premium procurement. Target the Northeast Region's high-insolation agricultural zones for merchant power developments that bypass feed-in tariff dependency. Pursue direct bilateral power purchase agreements with Rayong-based electronics manufacturers seeking Scope 2 emissions reductions without utility intermediary markups. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale independent power producers with 50-150 megawatt pipelines because fragmented land ownership and permitting expertise create acquisition synergies across Thailand's renewable energy zones. Platform consolidation of reservoir-adjacent site access rights offers defensive moats against land-use competition in the Central Plains. Monitor Energy Regulatory Commission storage mandate proposals as the inflection signal for hybrid project valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Utility-scale ground-mounted arrays in Khon Kaen province capture Northeast Region insolation advantages. |
| Power Purchase Agreement | Direct bilateral contracts with Map Ta Phut industrial estates secure long-term offtake visibility. |
| Technology Licensing | Heterojunction bifacial module partnerships elevate yield projections on high-albedo agricultural terrain. |
| Vertical Integration into Storage | In-house lithium-ion battery assembly captures peak pricing spreads and frequency regulation revenues. |
| Green Certification Program | Renewable energy certificate eligibility unlocks premium pricing from carbon-neutral supply chain buyers. |
Research Methodology
Coverage spans Thailand's Eastern Economic Corridor, Central Plains, Northeast Region, and Northern Region, with primary inputs from each zone combined with secondary validation. The research team conducted structured interviews with utility planning officers at the Electricity Generating Authority of Thailand, independent power producer project developers, engineering-procurement-construction contractors, and grid interconnection specialists. Secondary sources include Energy Regulatory Commission feed-in tariff filings, Ministry of Energy permitting databases, Department of Alternative Energy Development and Efficiency technology qualification records, and customs data on photovoltaic module imports. Bottom-up project pipeline aggregation triangulates against top-down national capacity targets.
Rate-of-change decomposition separates volume growth from unit value movements across the analysis window. The analytical framework models segmentation dimensions including technology type, installation topology, end-user scale, and regional grid interconnection capacity. CAGRs derive from capacity addition schedules, equipment cost trajectories, and regulatory revision timelines. Forecast inputs incorporate polysilicon price volatility assumptions and inverter grid-code compliance upgrade requirements mandated by Electricity Generating Authority of Thailand standards.
The model holds under stable feed-in tariff regimes and continuing industrial decarbonization commitments from multinational manufacturers; deviation in Energy Regulatory Commission auction mechanisms or Chinese export restriction triggers would shift deployment trajectories. Forecasts reflect documented assumptions about module efficiency improvements and battery cost decline curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Germany Solar Energy Market
Solar Power Systems
Solar Backsheet Market
Solar Power Systems
Hairy Solar Panels Market
Solar Power Systems
Global Micro Solar Inverter Market
Solar Power Systems
Solar Bug Zapper Market
Solar Power Systems
South America Solar Photovoltaic Market
Solar Power Systems
Spain Rooftop Solar Market
Solar Power Systems
Industrial Solar Water Heaters Market
Solar Power Systems
Germany Distributed Solar Power Generation Market
Solar Power Systems
Malaysia Solar Energy Market
Solar Power Systems
Solar Shed Light Market
Solar Power Systems
Asia-Pacific Rooftop Solar Market
Solar Power Systems
Australia Rooftop Solar Market
Solar Power Systems
Smart Solar Power Market
Solar Power Systems
Solar Power Manager Market
Solar Power Systems
Polycrystalline Solar Panel Market