
 Solar Kiosk Market | 2026-2036
Solar Kiosk Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Kiosk Market Analytics
The EU Green Deal's off-grid energy access targets is shifting procurement criteria toward modular solar retail infrastructure across emerging economies. JA Solar Holdings leverages its vertically integrated cell-to-module production to sustain cost leadership in high-efficiency panels for kiosk deployments. Solarkiosk Solutions anchors its position through purpose-built designs for rural African markets, while Hanwha Q CELLS competes on PERC cell efficiency ratings that extend daily operating windows for commercial kiosk operators.
A solar kiosk constitutes a self-contained, photovoltaic-powered retail or service unit integrating PV modules, battery storage, power electronics, and point-of-service hardware into a weatherized enclosure, typically rated between 1 kW and 30 kW depending on load profile. These systems convert incident solar irradiance into stored DC electricity, then invert it to AC for appliance loads including mobile device charging, refrigeration, lighting, and digital payment terminals, serving populations beyond centralized grid reach. Standalone kiosks dominate current installations due to lower capital barriers and simplified permitting, while integrated kiosks capture expanding margin pools as operators bundle cold chain, banking, and telecommunications services into single footprints. Off-grid installations represent the fastest-growing installation type, driven by rural electrification gaps and mini-grid deferral economics across Sub-Saharan Africa and South Asia.
FCC equipment authorization requirements govern wireless communication modules in US-deployed kiosks, while India's CEA technical standards for distributed solar systems shape product certification pathways for manufacturers serving South Asian markets. The EU AI Act's emerging provisions for automated retail transactions will influence software architecture decisions for kiosk payment and inventory systems in European development finance-backed projects. Stakeholders must monitor how national rural electrification agencies calibrate subsidy mechanisms against commercial tariff sustainability to determine viable deployment geographies.
Market Dynamics
Falling lithium-ion battery costs and pay-as-you-go financing penetration are compressing capital barriers for rural solar kiosk deployment, shifting procurement from donor-funded pilots to commercially scalable infrastructure.
Growth Catalysts
- Rural electrification mandates:Kenya's off-grid energy programs and India's Ministry of New and Renewable Energy directives are channeling public capital into distributed solar retail infrastructure.
- Mobile money integration:Digital payment rails across sub-Saharan Africa enable automated revenue collection without physical cash handling, reducing operating cost structures for kiosk operators.
- Cold chain extension:Agricultural cooperatives in South Asia are bundling refrigeration services with mobile charging, expanding per-kiosk revenue streams beyond basic power provision.
Market Restraints
- Import tariff volatility:India's DGFT duty structures on lithium-ion cells create input cost uncertainty for integrated battery storage systems.
- Component supply concentration:PV module sourcing clusters in Southeast Asia expose procurement timelines to regional logistics bottlenecks.
- Technical degradation curves:Battery replacement cycles in high-temperature operating environments compress asset lifespans below financing tenors.
Strategic Opportunities
- Underserved Sahel corridor:Mali and Burkina Faso present deployment gaps where mini-grid economics remain unfavorable and standalone kiosk density is minimal.
- Telecommunications convergence:Kiosk operators integrating last-mile data connectivity with power services capture margin pools from mobile network infrastructure gaps.
- EU Green Deal financing:Development finance institutions are prioritizing modular off-grid retail infrastructure in their emerging market energy access portfolios.
Industry Challenges
- Certification timeline compression:India's CEA technical standards for distributed solar systems require extended product testing cycles that delay commercial rollout schedules.
- Skilled technician scarcity:Field maintenance capacity for power electronics and battery management systems remains concentrated in urban centers, complicating rural service coverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Kiosk Market |
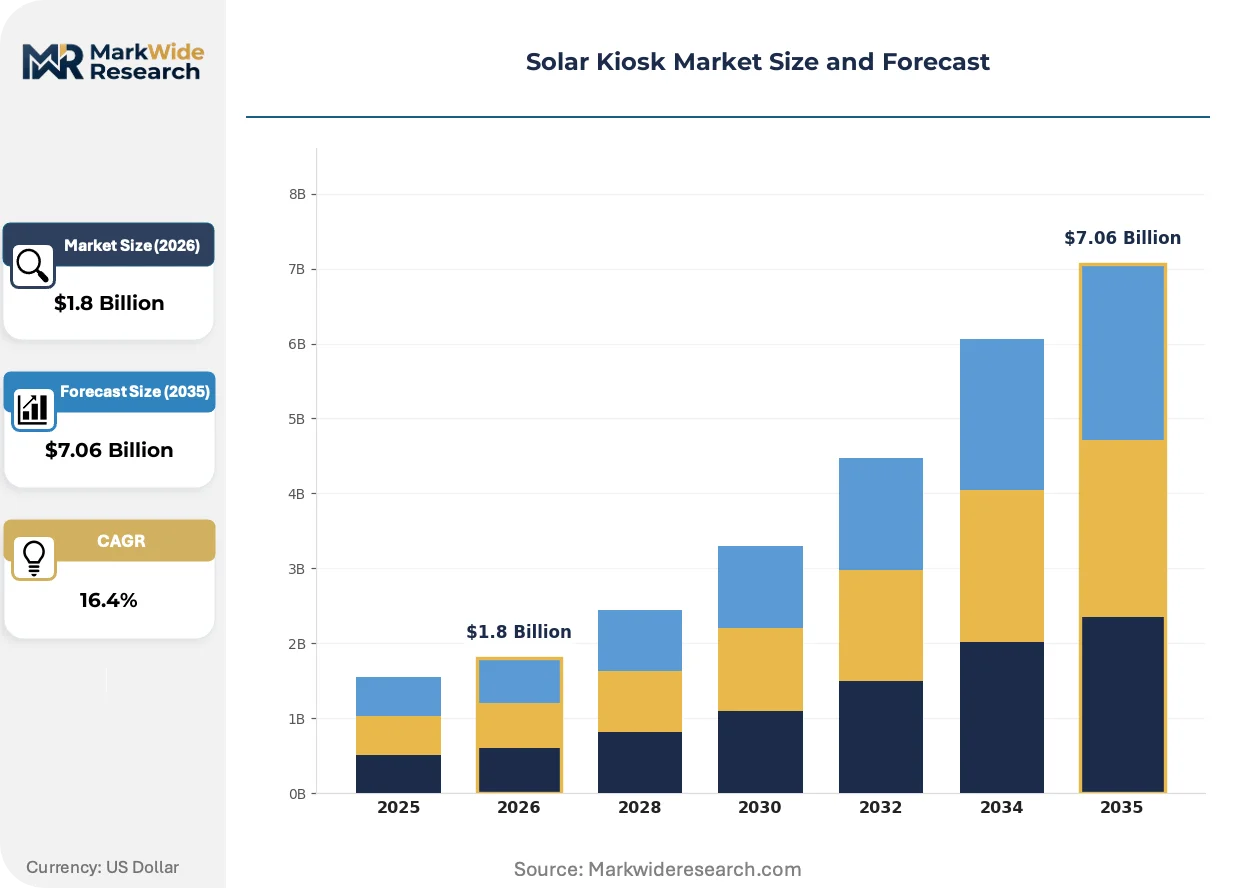
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Kiosks, Integrated Kiosks, Mobile Kiosks, Fixed Kiosks End User: Retail Outlets, Educational Institutions, Rural Communities, Business Enterprises Installation Type: Permanent Installations, Temporary Installations, Mobile Installations, Off-Grid Installations Power Rating: Low Power (1-5 kW), Moderate Power (6-15 kW), High Power (16-30 kW), Ultra High Power (31+ kW) |
| Companies Covered | JA Solar Holdings, GCL-Poly Energy Holdings, Solarkiosk Solutions, LS Power, Trina Solar, NextEra Energy, Hanwha Q CELLS, Recurrent Energy, LONGi Green Energy Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Kiosk Market Evolving Landscape
System architecture is pivoting from hardware-centric supply toward software-defined service platforms that bundle energy access with digital financial and agricultural services.
Containerized kiosk designs with pre-integrated battery storage and inverter systems are rewriting deployment economics for remote site installation. Agricultural cooperatives in Kenya's Rift Valley are adopting these units for cold chain hubs, compressing commissioning timelines from weeks to days and reducing skilled labor requirements on-site.
REACH chemical safety registrations and emerging EU AI Act provisions for automated retail transactions are reshaping procurement specifications for European development finance-backed projects. Equipment vendors must now document supply chain substance compliance and algorithmic transparency for payment systems, adding certification layers that favor established manufacturers with dedicated regulatory affairs functions.
Pay-as-you-go financing structures are displacing upfront capital purchase models across East African markets. Rural households in Tanzania and Uganda now access kiosk services through mobile money micro-payments, shifting revenue risk from end-users to platform operators and equipment financiers who underwrite hardware deployment costs.
Solar Kiosk Market Segmentation
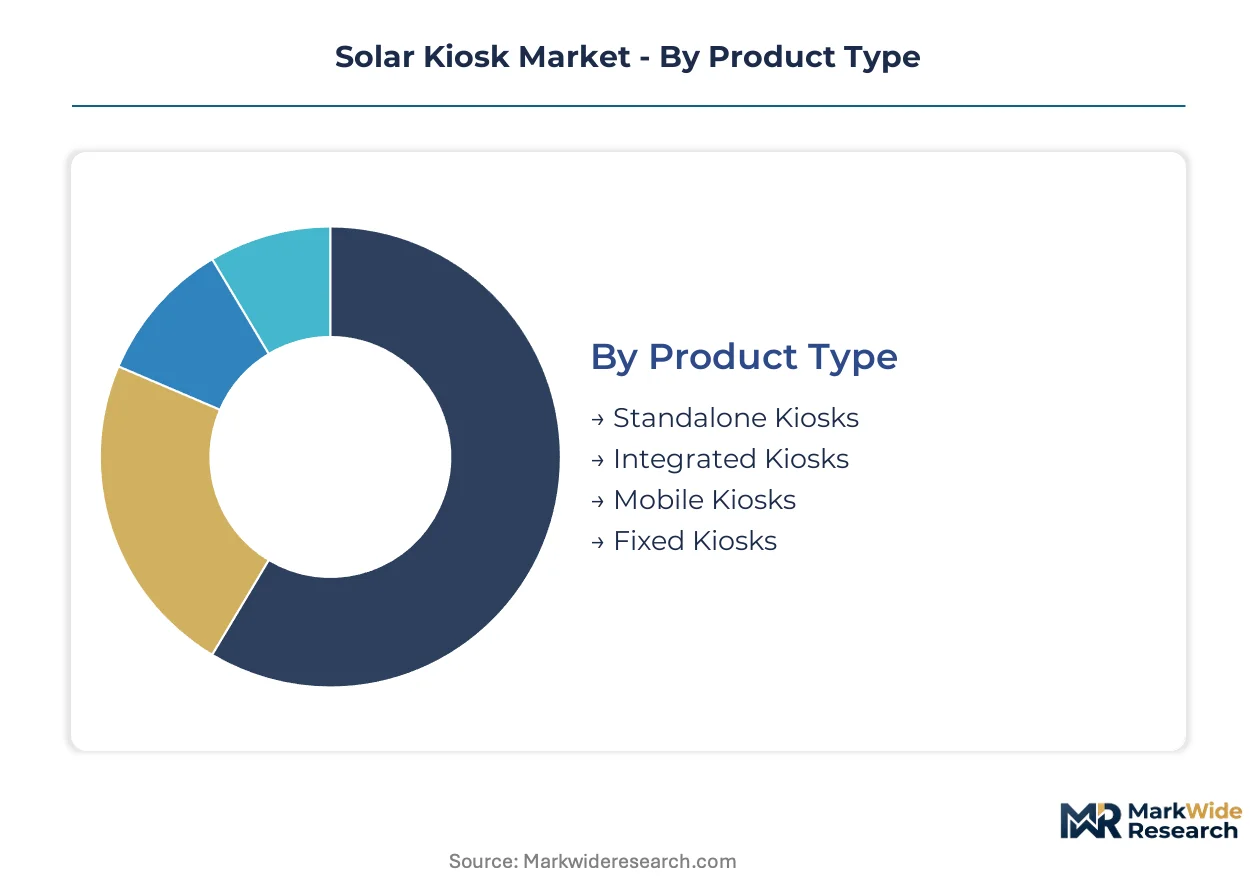
Solar kiosk procurement patterns diverge sharply across deployment contexts, with product architecture and installation permanence driving fundamentally different supply chain and financing requirements. Understanding these segment boundaries clarifies where margin pools concentrate versus where scale economics dominate.
Product Type:
Upgrade cycles vary dramatically across kiosk architectures, with integrated systems demanding coordinated component refreshes while standalone units permit modular battery or inverter swaps without full enclosure replacement.
- Standalone Kiosks:Self-contained PV-battery units in weatherized enclosures serve single-service applications like mobile charging or lighting. Rural electrification programs across Kenya and Tanzania favor these for pay-as-you-go scaling due to lower capital barriers and simplified permitting pathways.
- Integrated Kiosks:Multi-service platforms bundle cold storage, digital payments, and telecommunications into unified footprints. Agricultural cooperatives in South Asia drive demand here as operators capture revenue from refrigeration services alongside basic power provision.
- Mobile Kiosks:Trailer-mounted or portable units deploy for temporary events, disaster response, or seasonal agricultural cycles.
- Fixed Kiosks:Permanent foundation-mounted structures anchor commercial zones with extended asset depreciation schedules.
Volume placements concentrate in standalone configurations; the faster expansion belongs to integrated kiosks bundling multiple revenue streams.
End User:
Customer procurement sophistication spans from informal cash transactions to structured concession financing, with each end-use segment imposing distinct technical specifications and service level requirements.
- Retail Outlets:Small merchants and shopkeepers power inventory lighting, mobile charging stations, and basic refrigeration. These deployments cluster in peri-urban Kenya where grid reliability gaps create commercial demand for backup power.
- Rural Communities:Village-level shared infrastructure serves households beyond centralized grid reach. Sub-Saharan Africa's off-grid population drives this segment through development finance-backed mini-grid deferral economics.
- Educational Institutions:Schools and training centers require extended daily operating windows for digital learning equipment.
- Business Enterprises:Corporate remote operations and telecommunications infrastructure use higher-capacity systems.
Deployment scale favors rural community installations; margin capture runs highest through retail outlet commercialization.
Installation Type:
Site permanence decisions lock in financing structures and regulatory pathways, with temporary permits processing faster but limiting debt tenors and subsidy eligibility.
- Off-Grid Installations:Fully autonomous systems without grid interconnection dominate sub-Saharan Africa and South Asian markets. Mini-grid deferral economics in Mali and Burkina Faso accelerate these deployments where centralized infrastructure remains uneconomic.
- Permanent Installations:Fixed foundation systems with 15-20 year depreciation schedules anchor commercial and institutional sites.
- Temporary Installations:Event-duration or construction-phase deployments with rapid commissioning and decommissioning requirements.
- Mobile Installations:Relocatable units following seasonal agricultural patterns or population movements.
Project pipelines fill fastest with off-grid configurations; permanent installations carry the longest revenue visibility.
Power Rating:
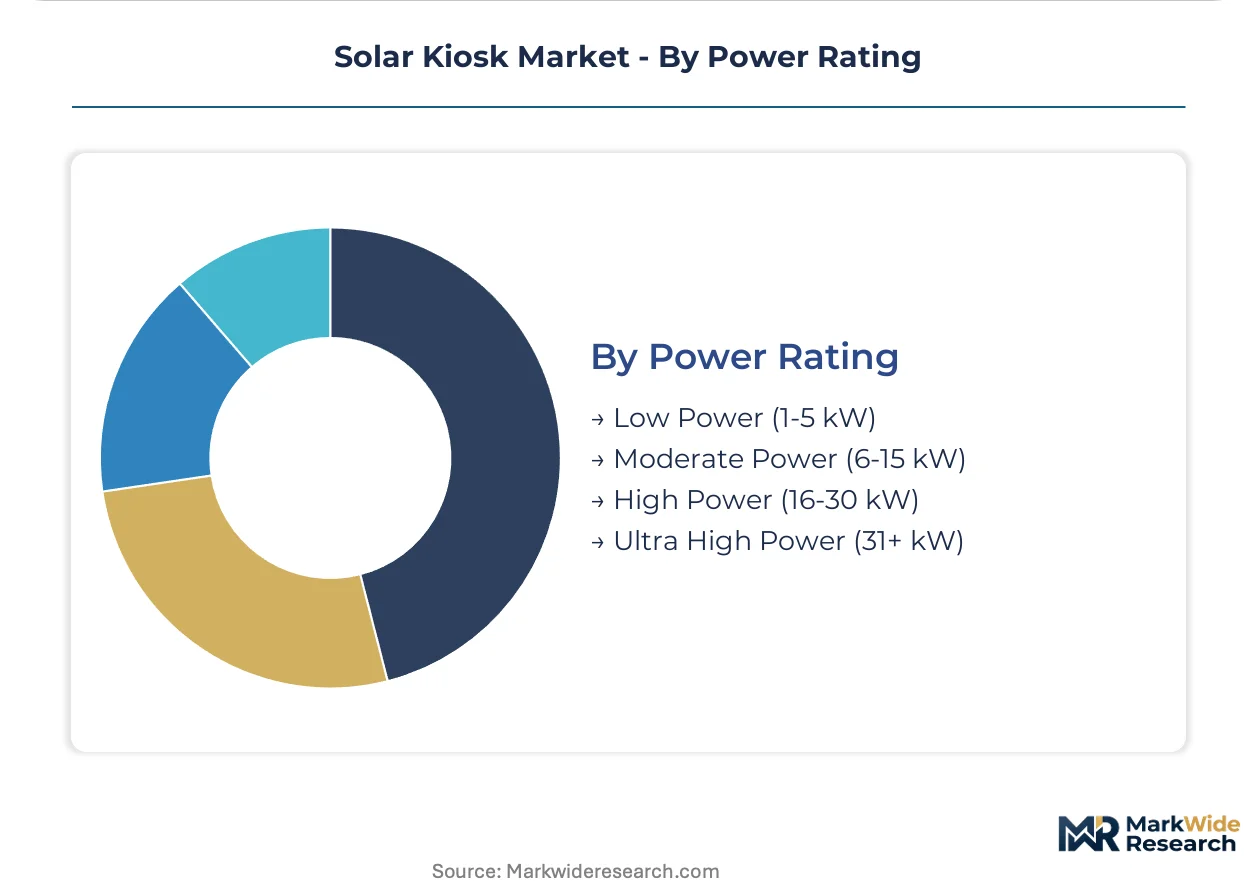
Capacity tiers segment procurement by load profile complexity, with higher ratings demanding more sophisticated power electronics and thermal management that concentrate supply among specialized vendors.
- Low Power (1-5 kW):Basic mobile charging and LED lighting systems serve individual retail operators. India's Ministry of New and Renewable Energy subsidy programs channel significant volume through this tier for rural electrification.
- Moderate Power (6-15 kW):Cold chain and multi-appliance configurations support agricultural cooperatives and small commercial hubs. Kenya's Rift Valley dairy collectives represent concentrated demand as refrigeration preserves harvest value.
- High Power (16-30 kW):Telecommunications backup and institutional loads require advanced inverter and battery management systems.
- Ultra High Power (31+ kW):Industrial remote operations and mini-grid anchor nodes serve specialized extraction and processing applications.
Unit shipments peak in low-power systems; value expansion tracks toward moderate-power cold chain integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration in China and Southeast Asia supplies photovoltaic modules worldwide, while deployment demand clusters across sub-Saharan Africa and South Asia where electrification gaps persist. This production-consumption divide shapes financing flows and regulatory compliance requirements across distinct national pathways.
Kenya
Rural electrification programs channel public capital into distributed solar retail infrastructure across off-grid counties. The Rural Electrification and Renewable Energy Corporation directs subsidy mechanisms toward standalone kiosk deployments in arid and semi-arid lands. Nairobi anchors procurement coordination for pay-as-you-go platform operators scaling commercial viability in Rift Valley agricultural zones.
India
The Ministry of New and Renewable Energy mandates accelerate integrated kiosk procurement for cold chain and digital payment services in un-electrified villages. Central Electricity Authority technical standards for distributed solar systems shape product certification pathways for manufacturers serving South Asian markets. Gujarat and Maharashtra concentrate manufacturing clusters for lithium-ion battery assembly feeding kiosk system integrators.
Germany
EU Green Deal financing prioritizes modular off-grid retail infrastructure in emerging market energy access portfolios. REACH chemical safety registrations and emerging EU AI Act provisions for automated retail transactions reshape procurement specifications for development finance-backed projects. Berlin-based development finance institutions coordinate subsidy calibration against commercial tariff sustainability in partner countries.
United States
FCC equipment authorization requirements govern wireless communication modules in domestically deployed kiosks. The Inflation Reduction Act's domestic content provisions influence procurement patterns for battery storage components in federal rural electrification programs. California and Texas host system integrators specializing in containerized pre-integrated designs for disaster response and remote commercial applications.
Brazil
ANVISA regulatory frameworks for medical cold chain applications extend to solar-powered pharmaceutical storage kiosks in Amazonian regions. National rural electrification programs in the Northeast prioritize standalone units for mobile charging and agricultural cooperative services. São Paulo anchors financing coordination for pay-as-you-go models adapting East African commercial structures to Latin American market conditions.
Solar Kiosk Market Competitive Landscape
The competitive structure tilts toward photovoltaic module manufacturers with captive cell production and purpose-built system integrators serving rural African markets. Tiered specialization separates high-volume panel suppliers from kiosk-specific designers optimizing enclosures for tropical operating conditions. Dominant competitive moves include backward integration into lithium-ion battery supply and strategic partnerships with mobile money platform operators.
Among module manufacturers with upstream control over cell production, JA Solar Holdings and LONGi Green Energy Technology exemplify scale-driven archetypes optimizing cost structures for high-efficiency deployments. Solarkiosk Solutions occupies a position within the purpose-built system integrator tier, representing specialization in weatherized enclosure design for sub-Saharan operating environments. Hanwha Q CELLS sits within the premium-efficiency segment, anchoring competitive positioning through PERC cell performance ratings that extend daily operating windows.
| Leading Market Players |
|---|
| JA Solar Holdings |
| GCL-Poly Energy Holdings |
| Solarkiosk Solutions |
| LS Power |
| Trina Solar |
| NextEra Energy |
| Hanwha Q CELLS |
| Recurrent Energy |
| LONGi Green Energy Technology |
| Others |
Value Network & Pricing Analysis
India's CEA technical standards for distributed solar systems are forcing kiosk manufacturers to absorb extended certification testing cycles, compressing margins on low-power standalone units while shifting procurement preference toward integrated system providers with dedicated regulatory affairs capacity.
Pricing Analysis
Outcome-based pricing tied to daily operating uptime anchors commercial kiosk deployments across Kenya's Rift Valley agricultural zones. Three-tier pricing structure across premium, standard, and economy levels separates PERC cell efficiency ratings from basic polycrystalline configurations, with cold chain integration commanding substantial service premiums. Cost compression in low-power mobile charging tiers is intensifying because India's Ministry of New and Renewable Energy subsidy programs cap reimbursable hardware costs. Rural community cooperatives exhibit highest price sensitivity, while telecommunications infrastructure operators prioritize reliability over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Chinese polysilicon ingot production feeding wafer manufacturing clusters in Southeast Asia. Lithium-ion cell assembly draws from China, South Korea, and Japan, while weatherized enclosure fabrication rests on steel processing concentrated in India and Vietnam. Tariff exposure on battery components through India's DGFT duty structures creates input cost volatility for integrated storage systems. Distribution runs through Nairobi-based platform operators coordinating pay-as-you-go hardware deployment across East African markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar kiosk market has become a vertical-integration race, with captive lithium-ion battery production emerging as the decisive cost lever separating scalable platform operators from hardware-assemblers dependent on spot-market cell procurement.
For Market Incumbents: Hedge against margin erosion in low-power standalone tiers by deepening in-house production of battery management systems and power electronics. Solarkiosk Solutions and JA Solar Holdings must defend against emerging containerized system integrators by securing exclusive supply agreements with pay-as-you-go platform operators in Kenya and Tanzania. Certification investment in India's CEA compliance pathways locks out smaller competitors lacking dedicated testing budgets.
For New Entrants and Emerging Players: The price-point gap between premium PERC-based integrated kiosks and economy-tier standalone units creates entry space for mid-efficiency system architects targeting Mali and Burkina Faso's underserved Sahel corridor. Agricultural cooperatives in South Asia's moderate-power cold chain segment represent the most penetrable white-space, with containerized pre-integrated designs enabling rapid commissioning without established service networks. Partner with mobile money infrastructure providers to embed automated revenue collection from launch.
For Investors and Strategic Acquirers: The window for entry favors purpose-built system integrators with captive enclosure manufacturing and established rural African distribution partnerships. Long-term viability hinges on backward integration into lithium-ion cell supply or strategic offtake agreements with South Korean and Japanese battery producers. Watch for inflection when India's DGFT duty structures stabilize, signaling predictable input cost environments for hardware financiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Supply | Captive lithium-ion cell production insulates kiosk operators from India's DGFT tariff volatility. |
| Containerized System Deployment | Pre-integrated designs compress commissioning timelines from weeks to days in Kenya's Rift Valley. |
| Mobile Money Platform Partnership | Automated revenue collection through M-Pesa integration reduces operating cost structures in Tanzania. |
| CEA Certification Investment | Extended testing cycle capacity locks out competitors from India's Ministry of New and Renewable Energy subsidy channels. |
| Cold Chain Service Bundling | Refrigeration revenue streams expand per-kiosk economics beyond basic power provision in South Asian agricultural zones. |
Research Methodology
Independent corroboration across kiosk platform operators, photovoltaic module procurement leads, and rural electrification agency planners underwrites the qualitative findings in this study. Primary interviews with pay-as-you-go financiers, cold chain cooperative managers, and battery system integrators were cross-checked against secondary validation from India's CEA technical standards documentation, Kenya's Rural Electrification and Renewable Corporation program disclosures, and EU Green Deal development finance portfolio reports. Bottom-up unit deployment estimates and top-down subsidy allocation analysis were reconciled through iterative triangulation.
Historical reference periods spanning pre-pandemic deployment baselines through current procurement cycles anchored the forecast window across the analysis window. The modeling framework segmented volume and value outputs by product architecture, installation permanence, power rating tier, and end-use sophistication. CAGRs were derived from installed base growth trajectories and revenue-per-kiosk expansion patterns. Forecast inputs incorporated lithium-ion battery cost decline curves and mobile money penetration rates across sub-Saharan markets.
Inputs from platform operator transaction data and government subsidy disbursement records were available through the study window; gaps in real-time field performance degradation metrics introduce uncertainty bands around asset lifespan assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Spain Rooftop Solar Market
Solar Power Systems
Japan Solar Energy Market
Solar Power Systems
Indonesia Renewable Energy Market
Solar Power Systems
Non-Concentrating Solar Collector Market
Solar Power Systems
South America Solar PV Inverters Market
Solar Power Systems
On-Site Photovoltaic Solar Power for Data Centers Market
Solar Power Systems
Photovoltaic Coating Market
Solar Power Systems
Bacteria Powered Solar Cell Market
Solar Power Systems
Thin-Film Photovoltaic Market
Solar Power Systems
Off-Grid Solar Energy Market
Solar Power Systems
United Kingdom Solar Power Market
Solar Power Systems
Organic Solar Cells Market
Solar Power Systems
Solar Bench Market
Solar Power Systems
Argentina Solar Energy Market
Solar Power Systems
Global Crystalline Solar Cells Market
Solar Power Systems
Global Solar Panel Materials Market