
 Global Lead Recycling Battery Market | 2026-2036
Global Lead Recycling Battery Market Size, Share, and Industry Trends Forecast 2026-2036
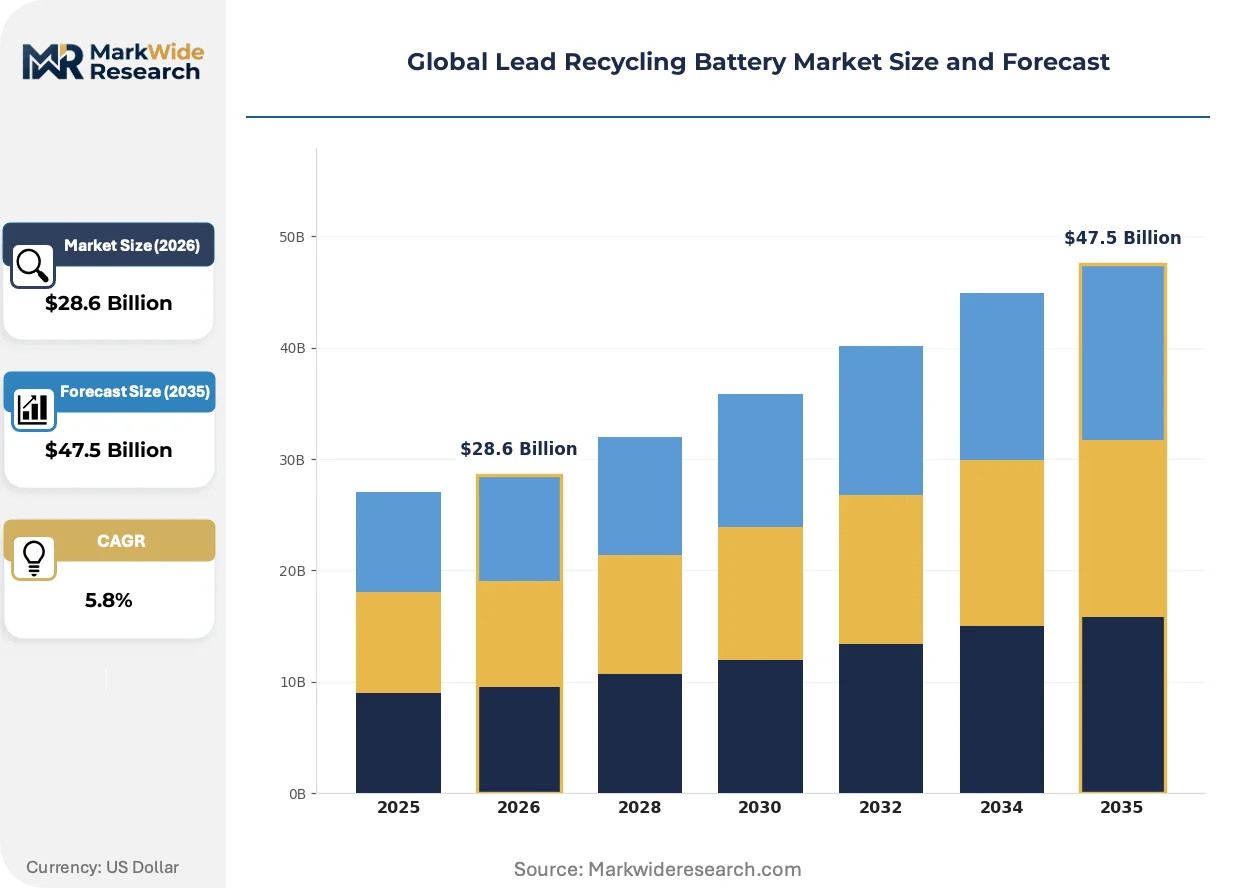
Global Lead Recycling Battery Market Outlook
Multi-source feedstock aggregation from fragmented collection networks is realigning how smelters secure spent battery volumes. Ecobat Technologies leverages its reverse logistics infrastructure across North America and Europe to capture urban mine flows. Gravita India Ltd anchors its cost position through backward integration into used battery collection across South Asian markets. Aqua Metals, Inc. differentiates via proprietary hydrometallurgical technology that eliminates high-temperature smelting emissions.
Lead recycling battery recovery strips spent lead-acid units through pyrometallurgical or hydrometallurgical routes to yield refined lead bullion with purity exceeding 99.97% for remelting into new battery plates. The process serves closed-loop manufacturing in automotive and industrial energy storage sectors where virgin lead mining faces ESG displacement. Automotive applications dominate volume throughput due to the standardized reverse logistics of starter-lighting-ignition battery returns. Hydrometallurgical processing methods attract capital fastest as environmental compliance costs reshape marginal economics across OECD smelters.
EPA hazardous waste rules under RCRA subtitle C govern US spent battery handling and smelter air permits, while China's MEE enforces dual carbon emissions caps on secondary lead capacity expansion. REACH and the EU Battery Regulation mandate recycled content thresholds and supply chain due diligence for batteries placed on European markets. Stakeholders must monitor regulatory divergence between jurisdictions where carbon border adjustments could redirect trade flows in secondary lead feedstock.
Market Dynamics
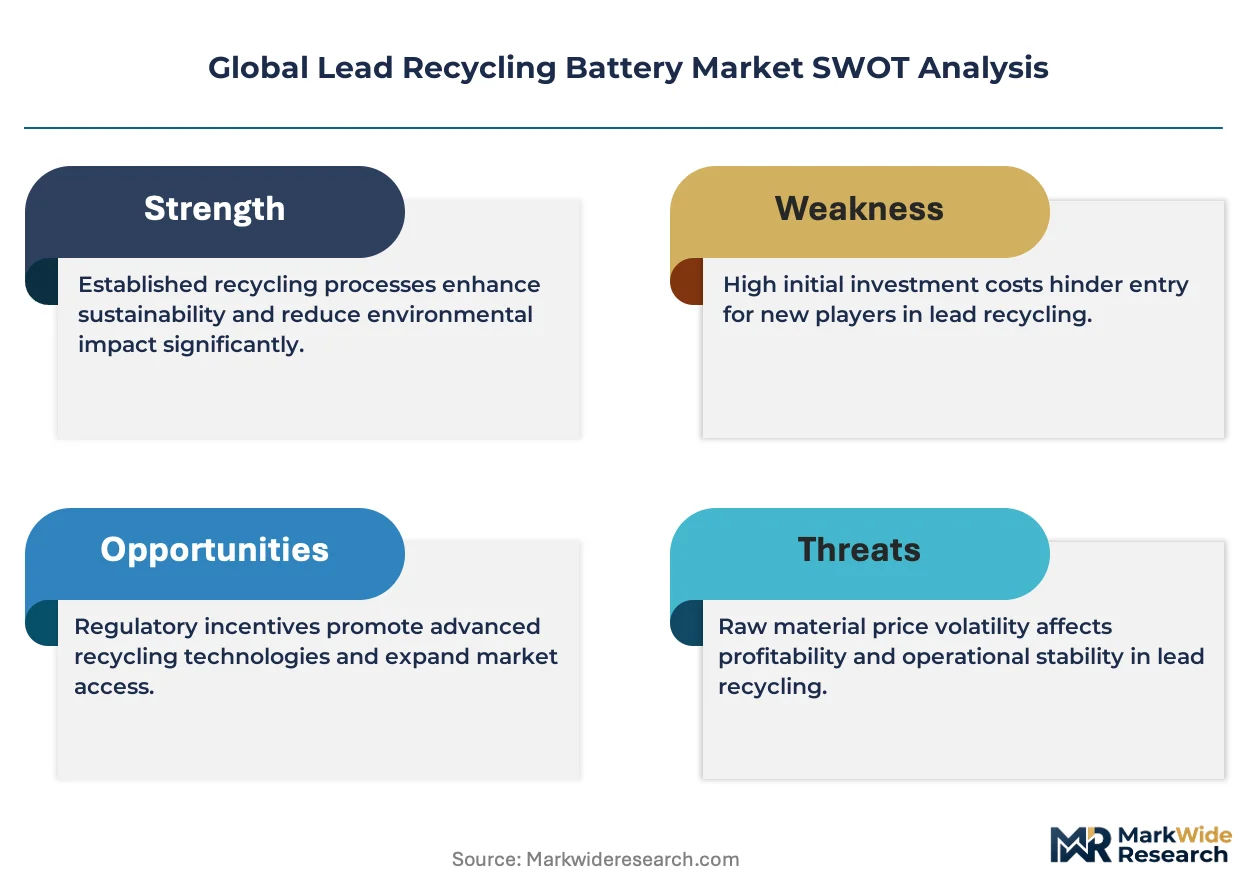
Environmental compliance costs are compressing pyrometallurgical margins while hydrometallurgical processing captures capital flows across OECD smelters. China's MEE dual carbon caps and EPA RCRA enforcement are accelerating technology substitution in secondary lead refining.
Growth Catalysts
- Automotive aftermarket standardization:Starter-lighting-ignition battery returns generate predictable feedstock volumes through established reverse logistics networks in Germany, China, and the United States.
- EU Battery Regulation mandates:Recycled content thresholds and supply chain due diligence requirements for batteries placed on European markets pull secondary lead into new production cycles.
- Hydrometallurgical process maturation:Electrochemical lead recovery eliminates smelter emissions while yielding battery-grade purity above 99.97%, attracting ESG-focused capital allocation.
Market Restraints
- Feedstock price volatility:Scrap battery collection costs fluctuate with lead LME pricing, squeezing smelter margins when primary metal prices spike.
- Concentrated refining geography:Secondary lead capacity clusters in Guangdong and Jiangsu provinces, creating supply disruption risk from localized environmental enforcement actions.
- Lithium-ion substitution pressure:Stationary energy storage and light electric vehicle applications are shifting toward lithium chemistries, eroding future lead-acid demand pools.
Strategic Opportunities
- India's informal sector formalization:Used battery collection networks in South Asian markets offer backward integration potential for organized recyclers seeking feedstock security.
- Carbon border adjustment preparation:EU CBAM implementation creates first-mover advantage for smelters with verified low-carbon process documentation and emissions tracking systems.
- Industrial battery service contracts:Forklift and telecom backup power users are adopting battery leasing models that guarantee closed-loop return flows to designated recyclers.
Industry Challenges
- Hydrometallurgical engineering scarcity:Electrochemical process design and solvent extraction expertise remains concentrated among specialized technology licensors, constraining rapid capacity scaling.
- Cross-border waste shipment compliance:Basel Convention amendments on hazardous waste transboundary movement are complicating spent battery trade flows between OECD and non-OECD jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lead Recycling Battery Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Acid Batteries, Lithium-Ion Batteries, Nickel-Cadmium Batteries, Gel Batteries Application: Automotive, UPS Systems, Renewable Energy Storage, Marine End User: Residential, Industrial, Commercial, Government Processing Method: Pyrometallurgical, Hydrometallurgical, Biotechnological, Reuse |
| Companies Covered | Ecobat Technologies, Exide Industries Limited, East Penn Manufacturing Company, Aqua Metals, Inc., Gravita India Ltd, Call2Recycle, Inc., Battery Solutions LLC, Umicore, Glencore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lead Recycling Battery Market Strategic Shifts
Processing technology substitution and regulatory documentation requirements are restructuring competitive advantage in secondary lead refining. Smelters must now demonstrate emissions performance and carbon intensity alongside traditional metallurgical yield metrics.
Aqua Metals' electrochemical lead recovery technology is expanding into commercial-scale operations through modular unit deployment. Industrial battery manufacturers in North America are piloting this solvent-based approach to bypass smelting emissions permitting constraints. The technology is expanding into markets where EPA Title V air permits face renewal uncertainty and local opposition to high-temperature processing.
China's MEE dual carbon enforcement mechanism now ties secondary lead capacity expansion permits to verified emissions intensity benchmarks. Smelters in Jiangsu province must demonstrate carbon capture readiness or renewable energy sourcing to secure operating licenses. Guangdong-based refiners are responding by retrofitting facilities with waste-heat recovery systems and procuring grid-connected solar generation.
Automotive original equipment manufacturers are consolidating battery procurement around suppliers with certified closed-loop recycling documentation. Tier-1 battery assemblers in Germany now require smelter partners to provide batch-level mass balance verification through blockchain-tracked feedstock chains. This certification-driven preference shift is most visible in European electric vehicle supply chains where OEM sustainability reporting obligations cascade through component suppliers.
Global Lead Recycling Battery Market Segmentation
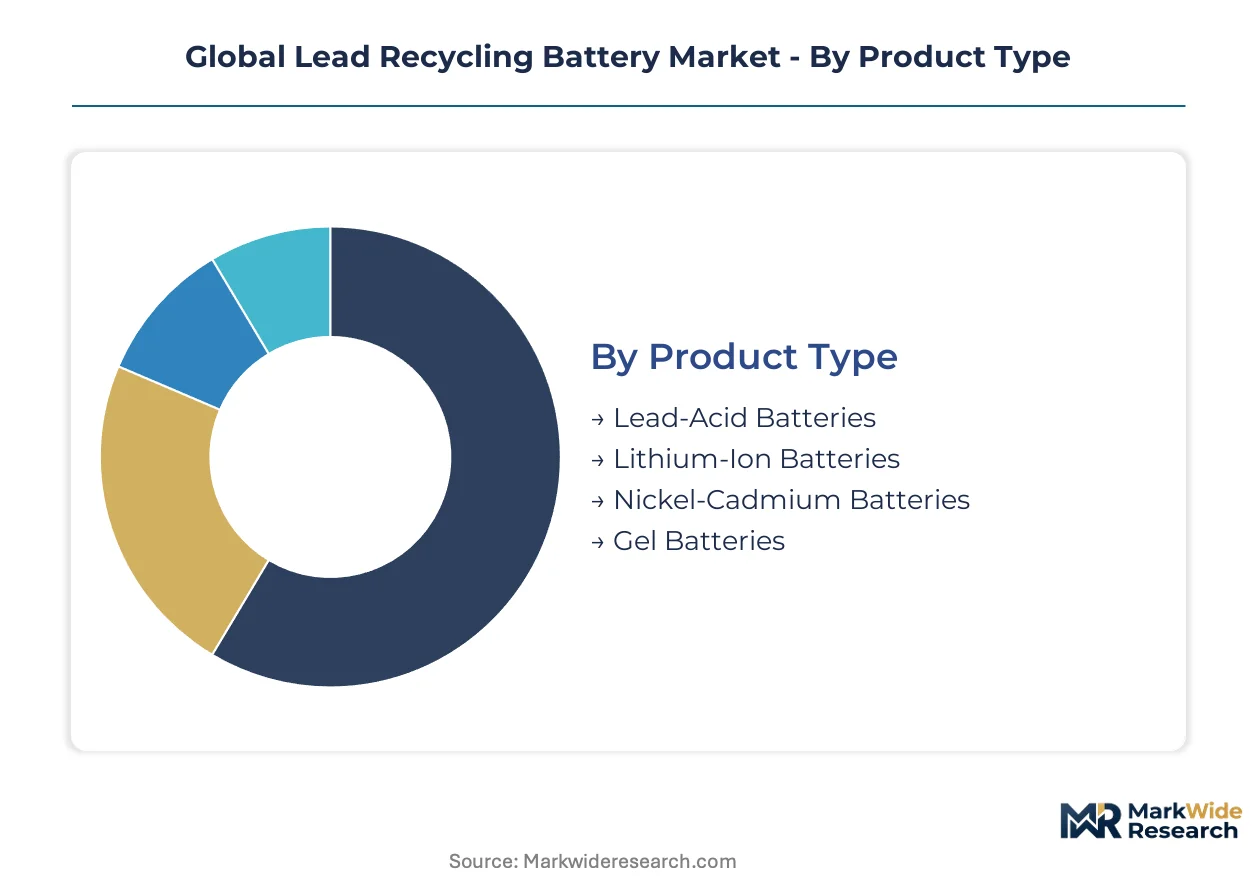
Lead recycling battery processing exhibits divergent capital requirements across product chemistries and recovery methods. Smelters must align infrastructure investments with feedstock availability and regulatory compliance thresholds in target markets.
Product Type:
Capital intensity peaks with lithium-ion battery recycling due to complex cathode separation and electrolyte handling infrastructure. Lead-acid recovery benefits from mature, depreciated pyrometallurgical assets.
- Lead-Acid Batteries:Flooded and sealed valve-regulated designs dominate feedstock volumes with standardized polypropylene casing and sulfuric acid electrolyte composition. Demand concentrates in Germany, China, and the United States where automotive aftermarket returns generate predictable collection flows through established reverse logistics networks.
- Lithium-Ion Batteries:NMC and LFP cathode chemistries require cryogenic shredding or inert atmosphere disassembly to prevent thermal runaway during preprocessing. Demand is climbing fastest in Guangdong province where battery manufacturers are integrating recycling capacity to secure cobalt and nickel feedstock against supply chain disruption.
- Nickel-Cadmium Batteries:Aviation and rail applications generate concentrated waste streams with cadmium toxicity driving specialized hydrometallurgical recovery investments.
- Gel Batteries:Deep-cycle designs from telecom backup and mobility applications yield silica-thickened electrolyte requiring modified smelter feed preparation protocols.
Lead-acid batteries absorb the bulk of installed capacity; lithium-ion batteries are expanding most quickly.
Application:
Volume distribution tracks battery replacement cycles and reverse logistics maturity across end-use sectors.
- Automotive:Starter-lighting-ignition batteries generate standardized 3-5 year replacement intervals with established dealer and retail collection channels in Germany and the United States. OEM sustainability mandates in the European Union are pulling certified recycled lead into new battery production.
- UPS Systems:Data center and critical facility backup batteries operate on 5-8 year replacement cycles with concentrated enterprise-scale waste generation. Demand is climbing fastest in Jiangsu province where cloud infrastructure expansion is creating predictable industrial feedstock volumes.
- Renewable Energy Storage:Off-grid solar and wind installations utilize deep-cycle lead-acid designs with decentralized waste generation complicating collection economics.
- Marine:Trolling motor and house battery applications generate seasonal replacement demand with corrosion-resistant casing specifications affecting smelter yield calculations.
Automotive applications command the largest processing volumes; UPS systems are gaining share fastest.
End User:
Customer scale determines collection efficiency and contract structuring for recyclers securing feedstock commitments.
- Industrial:Manufacturing facilities and logistics operators generate bulk battery waste through forklift fleet rotations and facility backup systems. Demand concentrates in Guangdong province where industrial park consolidation enables centralized collection contracts with guaranteed volume commitments.
- Commercial:Retail chains and office complexes produce fragmented but growing waste streams through facility maintenance cycles. Demand is climbing fastest in the United States where property management firms are adopting battery leasing models with embedded recycling provisions.
- Residential:Consumer automotive and small-scale solar applications generate dispersed collection challenges with high per-unit logistics costs.
- Government:Military and municipal fleet operations create regulated procurement pathways favoring certified recyclers with documented chain-of-custody systems.
Industrial end users anchor contract-based feedstock security; commercial segments are scaling fastest through service model innovation.
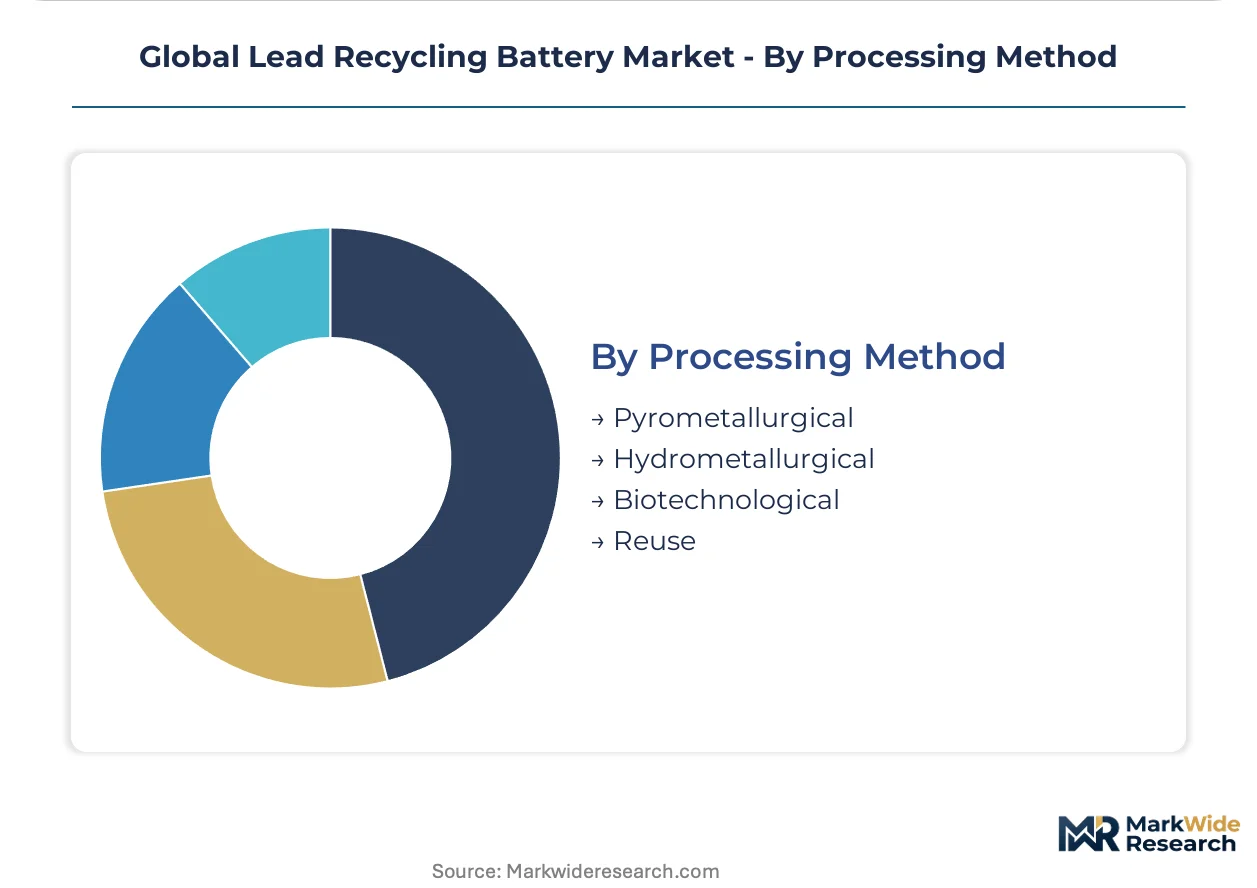
Processing Method:
Technology selection determines emissions compliance positioning and access to capital markets with ESG screening criteria.
- Pyrometallurgical:High-temperature smelting in blast or rotary furnaces remains the dominant installed base with established lead bullion recovery rates exceeding 95%. Demand concentrates in Jiangsu province where existing facilities are retrofitting emissions control systems to meet MEE dual carbon enforcement thresholds.
- Hydrometallurgical:Electrochemical and solvent extraction processes eliminate smelter emissions while enabling selective metal recovery. Demand is climbing fastest in the United States where EPA Title V permit renewal uncertainty is driving technology substitution toward electrochemical approaches.
- Biotechnological:Bioleaching using Acidithiobacillus ferrooxidans operates at ambient temperatures with reduced energy inputs but extended residence times constraining throughput economics.
- Reuse:Direct refurbishment of cells meeting residual capacity thresholds bypasses material recovery entirely, capturing value in secondary markets for stationary storage applications.
Pyrometallurgical capacity holds the majority of operational assets; hydrometallurgical methods are attracting capital fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban mining corridors in Guangdong province supply the densest feedstock flows for lead-acid battery recovery. Secondary lead capacity clusters near manufacturing demand centers where reverse logistics networks intersect with smelter infrastructure.
China
Automotive aftermarket returns and industrial UPS replacements generate steady feedstock volumes across Jiangsu province. MEE dual carbon enforcement ties capacity expansion permits to verified emissions intensity benchmarks. Guangdong-based refiners retrofit facilities with waste-heat recovery systems to secure operating licenses.
United States
Starter-lighting-ignition battery returns through dealer networks create predictable collection economics. EPA RCRA subtitle C governs spent battery handling while Title V permit renewal uncertainty accelerates technology substitution. Texas and Ohio host concentrated secondary lead capacity serving regional battery manufacturers.
Germany
OEM sustainability mandates pull certified recycled lead into new battery production for European electric vehicle supply chains. REACH and the EU Battery Regulation mandate recycled content thresholds and supply chain due diligence. Industrial clusters in North Rhine-Westphalia anchor closed-loop recycling partnerships with tier-1 battery assemblers.
India
Informal sector collection networks in South Asian markets offer backward integration potential for organized recyclers. BIS standards and state-level pollution control board enforcement gradually formalize used battery handling. Gujarat and Maharashtra concentrate emerging secondary lead capacity near manufacturing demand.
Global Lead Recycling Battery Market Competitive Environment
Technology licensing dominates the current landscape as hydrometallurgical process providers scale modular deployment. The vendor base separates into three tiers: integrated metals conglomerates with captive smelting assets, specialized secondary lead refiners with collection network control, and electrochemical technology licensors with IP-based differentiation. Strategic archetypes include feedstock-secured operators, emissions-compliant technology providers, and regional collection aggregators. Competitive moves concentrate on backward integration into used battery collection and technology substitution partnerships with battery manufacturers.
Among technology-focused developers, Aqua Metals, Inc. exemplifies the electrochemical recovery archetype through its proprietary solvent-based approach. Gravita India Ltd occupies a position within the feedstock-secured tier through its collection network integration across South Asian markets. Ecobat Technologies anchors the logistics-integrated archetype with reverse logistics infrastructure spanning North America and Europe.
| Leading Market Players |
|---|
| Ecobat Technologies |
| Exide Industries Limited |
| East Penn Manufacturing Company |
| Aqua Metals, Inc. |
| Gravita India Ltd |
| Call2Recycle, Inc. |
| Battery Solutions LLC |
| Umicore |
| Glencore |
| Others |
Value Chain & Pricing Dynamics
EU Battery Regulation recycled content mandates gate qualified supply access and premium-tier pricing for certified secondary lead. Smelters without verified mass balance documentation face exclusion from European OEM procurement while certified operators command contract premiums.
Pricing Analysis
Warranty and service bundling separates contract structures in lead recycling battery markets. Premium tier pricing incorporates guaranteed closed-loop return logistics and batch-level carbon intensity documentation. Standard tiers trade on spot lead LME pricing with unbundled collection responsibility. Price differentiation hinges on certification grade and volume scale. Pricing pressure stems from lithium-ion substitution eroding long-term lead-acid demand commitments. Industrial end users exhibit lowest price sensitivity due to embedded sustainability reporting obligations.
Supply Chain Analysis
Warehouse-distribution layers concentrate in Jiangsu and Guangdong provinces where regional distribution centers feed manufacturing corridors. Secondary lead supply draws from China, Germany, and the United States as dominant refining geographies. Raw material dependencies center on spent battery collection networks, sulfuric acid neutralization reagents, and grid electricity for electrochemical processing. Single-source vulnerability concentrates in Guangdong's environmental enforcement jurisdiction. Distribution runs through reverse logistics partnerships with automotive dealer networks and industrial battery service contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Feedstock security constraints prop pricing power for smelters with locked collection contracts. Qualified capacity expansion permits under China's MEE dual carbon caps create structural supply bottlenecks.
For Market Incumbents: To counter hydrometallurgical technology substitution, Ecobat Technologies and Gravita India Ltd should deepen backward integration into informal collection networks across South Asian markets. Incumbents must retrofit existing pyrometallurgical assets with waste-heat recovery systems to secure MEE operating license renewals in Jiangsu province. Certification investment in blockchain-tracked mass balance systems defends tier-1 battery assembler relationships. For New Entrants and Emerging Players: Capture India's informal sector formalization opportunity through state-level pollution control board partnerships in Gujarat and Maharashtra. The most penetrable segment lies in commercial battery leasing models with embedded recycling provisions across United States property management firms. Go-to-market positioning should emphasize modular electrochemical unit deployment for EPA Title V permit-constrained smelters. For Investors and Strategic Acquirers: MEE dual carbon enforcement action announcements are the leading indicator that secondary lead capacity constraints are tightening. Long-term viability favors technology licensors with proprietary solvent extraction IP over commodity-exposed pyrometallurgical operators. Acquisition targets should display verified low-carbon process documentation and renewable energy sourcing agreements. Watch for EU CBAM implementation timeline clarity as the signal for premium pricing tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrometallurgical Technology Licensing | Electrochemical recovery eliminates EPA Title V permitting constraints for North American smelters. |
| Backward Integration into Collection Networks | Urban mine access in South Asian markets secures feedstock against LME price volatility. |
| Carbon Intensity Certification Programs | Blockchain-tracked mass balance documentation satisfies EU Battery Regulation due diligence mandates. |
| Waste-Heat Recovery System Retrofits | Jiangsu province smelters achieve MEE dual carbon benchmarks to secure operating licenses. |
| Industrial Battery Service Contract Expansion | Forklift and telecom backup leasing models guarantee closed-loop return flows to designated recyclers. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with smelter operations directors, battery manufacturer procurement leads, environmental compliance officers, and reverse logistics coordinators combined with secondary validation. Secondary sources encompassed EPA RCRA enforcement databases, China MEE emissions disclosure filings, EU Battery Regulation implementation guidance, and spent battery trade flow customs records. Bottom-up capacity utilization estimates triangulated against top-down demand modeling from automotive production and industrial battery replacement cycle data.
Data-stream reconciliation across feedstock availability, regulatory capacity constraints, and technology substitution rates shaped the analytical framework. Segmentation dimensions modeled included processing method, battery chemistry, end-use application, and geographic regulatory cluster. CAGRs were derived from installed capacity expansion trajectories weighted against lithium-ion substitution elasticity estimates. Forecast inputs incorporated MEE dual carbon enforcement intensity scenarios and EU CBAM implementation progression assumptions across the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium-ion technology cost curves and carbon border adjustment scope expansion. Outputs reflect documented assumptions around regulatory enforcement consistency and feedstock collection network formalization rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Recycling
Lead Acid Battery Recycling Market
Battery Recycling
Global Lead-Acid Battery Scrap Market
Battery Recycling
Lithium Recycling Market
Battery Recycling
Asia-Pacific Battery Recycling Market
Battery Recycling
Battery Recycling Market
Battery Recycling
Lithium Iron Phosphate Battery Recycling Market
Battery Recycling
India Battery Recycling Market
Battery Recycling
Nickel-Cadmium Battery Recycling Market
Battery Recycling
Lithium Ion Battery Recycling Market
Battery Recycling
Lithium-Ion Battery Recycling Solution Market
Battery Recycling
Europe Solar Panel Recycling Market
Battery Recycling
Lithium-Ion Battery Recycling Process Market
Battery Recycling
Solar Components Recycling Market
Battery Recycling
Automotive Oil Recycling Market
Battery Recycling
Global Primary Battery Recycling Market
Battery Recycling
Battery Scrap Market