
 Flexible Electronics Market | 2026-2036
Flexible Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Electronics Market Intelligence
Modular sensor-to-substrate bundling is decoupling from traditional rigid PCB procurement patterns, letting buyers mix polymer substrates with application-specific circuitry rather than accepting one-size-fits-all assemblies. Samsung Electronics leverages captive OLED expertise to dominate flexible display supply for automotive tier-1s. LG Display anchors its position through vertical control over roll-to-roll manufacturing equipment. E Ink Holdings specializes in low-power electrophoretic films, occupying a defensible niche in e-reader and logistics-tag applications.
Flexible electronics comprise electronic circuits and devices fabricated on bendable substrates—typically polyimide, PET, or ultra-thin glass—enabling curvature radii below 10 mm without functional degradation, with primary purpose being integration into non-planar product surfaces from skin-wearable patches to curved automotive instrument panels. Displays command the largest value share among product types, though battery segments are widening fastest as solid-state thin-film chemistries mature for wearable power. Consumer electronics absorbs the greatest application volume, yet healthcare devices carry superior margin pools due to regulatory certification barriers and patient-specific customization requirements.
FDA device classification rules and EPA substrate chemical restrictions jointly determine which polymer-metal combinations gain commercial traction in the United States, while REACH compliance in Europe filters out halogenated conductor inks from cross-border supply. ISO 10993 biocompatibility standards govern healthcare-device market access, creating a certification moat around implantable and skin-contact flexible systems. Stakeholders must track how RoHS exemptions for lead-free solders on flexible substrates evolve, as this technical detail will reshape material substitution roadmaps and foundry equipment investments.
Market Dynamics
Roll-to-roll manufacturing scale-up is compressing unit economics for flexible substrates while REACH chemical restrictions force substrate reformulation across European supply chains, creating simultaneous cost pressure and compliance investment requirements.
Growth Catalysts
- Remote patient monitoring expansion:Conformable biosensors gain traction in post-acute care settings as healthcare systems prioritize ambulatory monitoring over facility-based observation. FDA 510(k) clearance pathways for Class II medical devices accelerate commercialization timelines for skin-wearable patches.
- EU Green Deal substrate mandates:Hazardous material substitution requirements push manufacturers toward halogen-free polyimide and recyclable PET alternatives, opening procurement windows for compliant suppliers.
- Solid-state thin-film battery maturation:Energy density improvements in lithium-polymer and zinc-air chemistries enable self-powered flexible systems without external charging infrastructure.
Market Restraints
- Indium tin oxide supply concentration:Over 70% of transparent conductor supply originates from Chinese rare-earth processing facilities, exposing display and touch-sensor manufacturers to geopolitical disruption risk and price volatility.
- High-purity polyimide precursor costs:Pyromellitic dianhydride and 4,4'-oxydianiline feedstock prices fluctuate with petroleum derivatives, compressing margins for substrate converters unable to pass through input cost swings.
- Dimensional stability limitations:Thermal expansion mismatch between polymer substrates and deposited metal traces causes yield loss in multilayer flexible circuits above 85°C operating environments.
Strategic Opportunities
- Automotive interior surface integration:Curved instrument panels and haptic control surfaces in electric vehicles create specification pull for conformable display and capacitive sensor assemblies from tier-1 cockpit module suppliers.
- India PLI scheme electronics manufacturing:Production-linked incentive allocations for semiconductor packaging and display assembly attract flexible substrate laminators and roll-to-roll equipment providers to Gujarat and Tamil Nadu corridors.
- AI-enabled predictive maintenance labels:Convergence of printed sensor arrays with edge-computing microcontrollers enables self-diagnosing logistics tags that monitor shock, temperature, and humidity throughout cold-chain distribution.
Industry Challenges
- ISO 10993 biocompatibility certification timelines:Cytotoxicity and sensitization testing for skin-contact devices requires 12-18 month validation cycles, delaying revenue recognition for healthcare-focused product launches.
- Hybrid manufacturing skill scarcity:Roll-to-roll processing expertise rarely overlaps with precision lithography or semiconductor packaging experience, forcing workforce development investments or external hiring premiums.
- Legacy PCB procurement system integration:Enterprise resource planning platforms at automotive and industrial OEMs lack flexible electronics bill-of-material structures, requiring custom middleware development for supplier onboarding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Electronics Market |
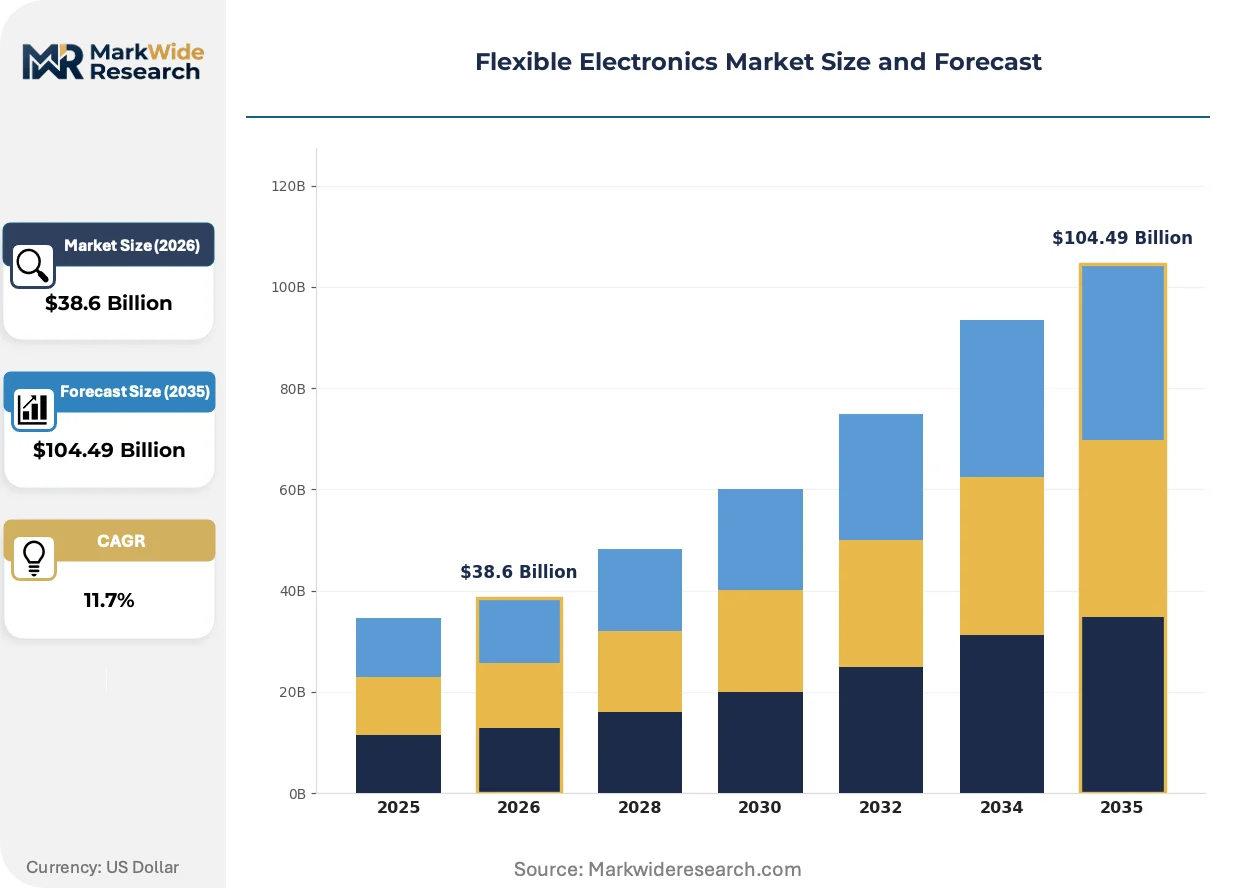
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $104.49 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Displays, Sensors, Batteries, Circuitry Application: Consumer Electronics, Healthcare Devices, Automotive Displays, Wearable Technology Material: Polymer, Metal Foil, Glass, Organic Material End User: Manufacturers, Retailers, OEMs, Research Institutions |
| Companies Covered | AU Optronics, E Ink Holdings, Samsung Electronics, PragmatIC Semiconductor, Innolux Corporation, LG Display, Royole Corporation, Heliatek, BOE Technology Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Electronics Market Strategic Shifts & Innovations
Micro-LED transfer printing and laser lift-off techniques are collapsing the boundary between rigid semiconductor performance and substrate flexibility, while regulatory chemical restrictions accelerate materials science investment.
Printed silver nanowire networks are decentralizing transparent conductor supply away from sputtered indium tin oxide. Automotive tier-1s and foldable smartphone assemblers now specify spray-coated or gravure-printed alternatives for curved touch surfaces. This conductor technology is decentralizing procurement power from vacuum deposition equipment owners toward roll-to-roll printing houses.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing reformulation of substrate coatings and barrier films. European converters must qualify fluorine-free alternatives for moisture and oxygen ingress protection by 2026 deadlines. Medical device laminators face the steepest requalification burden as ISO 10993 biocompatibility must be re-established for each substrate-coating combination.
Modular sensor-to-substrate bundling is fragmenting traditional rigid PCB procurement patterns. Buyers now specify polymer substrate, printed circuitry, and functional layer separately rather than accepting pre-integrated assemblies. This specification behavior is most pronounced in South Korean display supply chains, where Seoul-based foundries mix captive OLED expertise with external sensor module sourcing for automotive cockpit programs.
Flexible Electronics Market Segmentation
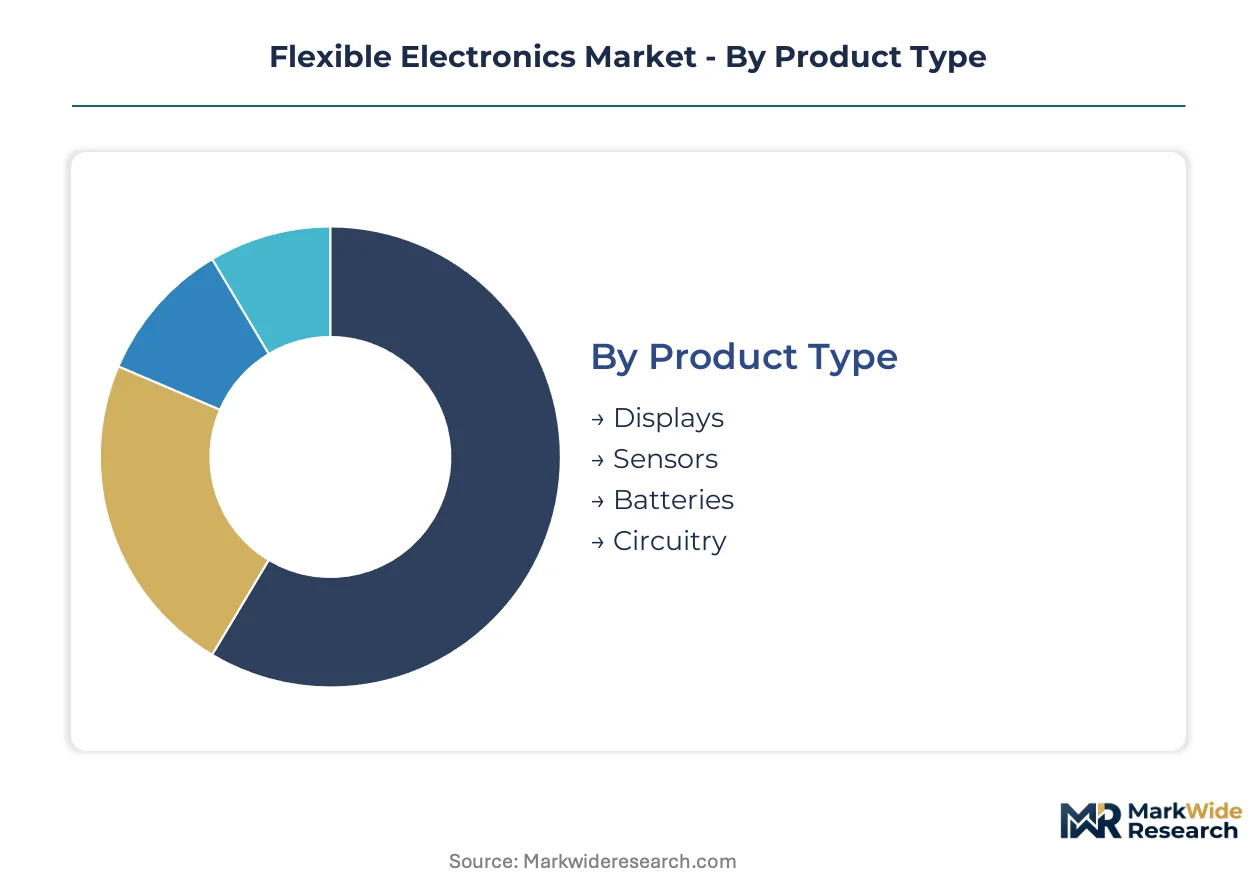
Segmentation in flexible electronics reveals how substrate bendability, power integration, and surface conformity requirements fragment procurement patterns across end-use verticals. Buyers now disaggregate sensor modules from substrate laminates rather than accepting pre-bonded assemblies.
Product Type:
Customization intensity varies sharply across this category, with some segments demanding patient-specific form factors while others prioritize mass-manufactured uniformity.
- Displays:OLED and electrophoretic films fabricated on polyimide or ultra-thin glass substrates enable curvature radii below 5 mm for automotive instrument panels and foldable smartphones. Samsung Electronics and LG Display concentrate supply in South Korea's Seoul-Gumi corridor, where captive OLED expertise meets roll-to-roll manufacturing scale.
- Sensors:Printed biosensor arrays integrate conformable electrodes with hydrogel interfaces for continuous glucose monitoring and cardiac rhythm detection. FDA 510(k) clearance pathways accelerate commercialization for Class II medical devices in post-acute care settings.
- Batteries:Solid-state thin-film lithium-polymer and zinc-air chemistries enable self-powered skin-wearable patches without external charging infrastructure.
- Circuitry:Multilayer flexible printed circuit boards with copper traces on PET substrates bridge rigid semiconductor components with bendable product surfaces.
Leading the category by volume: Displays. Growing fastest: Batteries.
Application:
Margin structure diverges across this category, with regulatory certification barriers creating premium pricing pockets in regulated healthcare verticals versus commoditized consumer segments.
- Consumer Electronics:Foldable smartphones, e-readers, and curved television panels absorb the greatest production volume. E Ink Holdings dominates low-power electrophoretic films for logistics tags and electronic shelf labels.
- Healthcare Devices:Conformable biosensors for remote patient monitoring carry superior margin pools due to ISO 10993 biocompatibility certification requirements and patient-specific customization demands.
- Automotive Displays:Curved instrument panels and haptic control surfaces in electric vehicles create specification pull for conformable display assemblies from tier-1 cockpit module suppliers.
- Wearable Technology:Skin-wearable patches for fitness tracking and wellness monitoring balance aesthetic conformity with sweat-resistant encapsulation.
Highest margin capture: Healthcare Devices. Steepest volume expansion: Consumer Electronics.
Material:
REACH chemical restrictions and thermal performance requirements fragment substrate selection across operating environment specifications.
- Polymer:Polyimide and PET films dominate flexible substrate supply, though pyromellitic dianhydride feedstock price volatility compresses converter margins. EU Green Deal mandates push substitution toward halogen-free alternatives.
- Metal Foil:Ultra-thin copper and stainless-steel foils provide electromagnetic shielding and thermal dissipation for high-frequency flexible circuits.
- Glass:Flexible glass substrates below 100 micrometers thickness combine optical clarity with barrier properties for OLED encapsulation.
- Organic Material:Biodegradable cellulose and silk fibroin substrates emerge for transient implantable electronics requiring dissolution after therapeutic function completion.
Widest adoption: Polymer. Most rapid material innovation: Organic Material.
End User:
Procurement sophistication varies from vertically integrated captive production to outsourced module assembly across this category.
- Manufacturers:Display foundries and materials suppliers cluster around Seoul and Gumi in South Korea, leveraging proximity for just-in-time substrate delivery.
- Retailers:Electronics distributors and logistics operators specify printed sensor labels for cold-chain monitoring and inventory tracking.
- OEMs:Automotive tier-1s and smartphone assemblers demand modular sensor-to-substrate bundling rather than pre-integrated rigid PCB assemblies.
- Research Institutions:University laboratories and corporate R&D centers prototype novel substrate-coating combinations ahead of regulatory qualification.
Primary volume driver: Manufacturers. Fastest procurement pattern evolution: OEMs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian display foundries while consumption fragments across healthcare systems and automotive assembly plants in North America and Europe. South Korea and China host substrate laminators and roll-to-roll equipment clusters. Regulatory chemical restrictions in the EU and FDA clearance pathways in the US reshape import demand patterns.
South Korea
Seoul-based foundries mix captive OLED expertise with external sensor sourcing for automotive cockpit programs. MFDS biocompatibility guidelines accelerate Class II medical device registrations for skin-wearable patches. Display manufacturers cluster in Gumi and the Seoul Capital Area, leveraging proximity for just-in-time polyimide substrate delivery.
United States
FDA 510(k) clearance pathways compress commercialization timelines for conformable biosensors in post-acute care settings. EPA substrate chemical restrictions filter polymer-metal combinations entering domestic supply chains. Boston and San Diego research corridors prototype novel substrate-coating combinations ahead of regulatory qualification.
Germany
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances force substrate reformulation by 2026 deadlines. KBA automotive standards create specification pull for curved instrument panels in electric vehicle cockpits. Bavaria and Baden-Württemberg host tier-1 cockpit module suppliers sourcing conformable display assemblies.
China
MIIT industrial standards accelerate domestic substitution of indium tin oxide with printed silver nanowire networks. Dual carbon goals push display manufacturers toward halogen-free substrate alternatives. Yangtze River Delta and Pearl River Delta clusters concentrate roll-to-roll printing capacity for curved touch surfaces.
Japan
METI technology roadmaps prioritize solid-state thin-film battery maturation for self-powered wearable systems. PMDA medical device regulations align with ISO 10993 biocompatibility standards for implantable electronics. Kanto and Kansai regions maintain precision lithography expertise for multilayer flexible circuit fabrication.
Flexible Electronics Market Key Industry Players
The competitive structure tilts toward vertically integrated display conglomerates with captive substrate expertise. Foundry-scale manufacturers dominate high-volume segments while specialist laminators capture premium healthcare niches. Two archetypes prevail: integrated electronics conglomerates controlling roll-to-roll manufacturing equipment, and materials-focused specialists occupying defensible technology niches. Capacity expansion and strategic partnerships represent the dominant competitive moves, with foundries locking in automotive tier-1 supply agreements.
Within the integrated conglomerate tier, Samsung Electronics and LG Display anchor supply concentration in South Korea's Seoul-Gumi corridor, exemplifying the captive OLED-to-substrate model. E Ink Holdings occupies a specialist position in low-power electrophoretic films, representing the niche-technology archetype that resists commoditization through application-specific performance advantages.
| Leading Market Players |
|---|
| AU Optronics |
| E Ink Holdings |
| Samsung Electronics |
| PragmatIC Semiconductor |
| Innolux Corporation |
| LG Display |
| Royole Corporation |
| Heliatek |
| BOE Technology Group |
| Others |
Cost & Logistics Intelligence
Roll-to-roll lithography specialists concentrated in South Korea's Seoul-Gumi corridor command wage premiums that compress margin spreads between premium medical-grade substrates and standard consumer electronics laminates. Labor-cost differentials between captive OLED foundries and independent substrate converters widen pricing-tier spreads as REACH compliance investments compound fixed-cost burdens.
Pricing Analysis
Cost-down pressure on standard-grade PET substrates accelerates because automotive tier-1s demand ISO-certified medical-grade pricing parity for curved instrument panels. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared biocompatible laminates from industrial-grade alternatives, with certification grade and volume scale as primary differentiation drivers. Price differentiation traces to pyromellitic dianhydride feedstock volatility and REACH reformulation costs. Healthcare device OEMs exhibit lowest price sensitivity due to patient-specific customization requirements, while logistics tag assemblers in consumer electronics face acute margin compression.
Supply Chain Analysis
Returns and refurbishment flows for defective multilayer flexible circuits remain underdeveloped, creating working-capital inefficiencies for substrate converters managing yield loss from thermal expansion mismatch. Supply concentrates in South Korea, China, and Japan, with indium tin oxide sourcing tethered to Chinese rare-earth processing and silver nanowire inks drawing from Japanese chemical specialists. Single-source vulnerability in transparent conductor supply exposes display manufacturers to geopolitical disruption. Distribution runs through just-in-time substrate delivery clusters around Seoul and Gumi, with automotive tier-1s demanding modular sensor-to-substrate bundling rather than pre-integrated assemblies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flexible electronics is transitioning from rigid PCB substitution toward native conformable architectures, with printed silver nanowire networks displacing sputtered indium tin oxide as the dominant transparent conductor technology.
For Market Incumbents: Lock in automotive tier-1 supply agreements for curved cockpit displays before solid-state thin-film battery integration raises technical barriers. Deepen backward integration into roll-to-roll manufacturing equipment to defend against independent substrate converters capturing modular bundling margins. Prioritize REACH-compliant halogen-free polyimide qualification to preempt regulatory exclusion from EU medical device supply chains. For New Entrants and Emerging Players: Capture India's PLI scheme electronics manufacturing corridors in Gujarat and Tamil Nadu before substrate laminator capacity saturates. Target AI-enabled predictive maintenance labels for cold-chain logistics as the most penetrable application, leveraging printed sensor arrays with edge-computing microcontrollers. Pursue hospital system partnerships for remote patient monitoring patches as the primary go-to-market angle, bypassing direct competition with Samsung and LG Display in consumer displays. For Investors and Strategic Acquirers: Re-rating potential sits with specialist materials suppliers possessing ISO 10993 biocompatibility certification moats, given FDA 510(k) clearance pathway acceleration for Class II medical devices. Long-term viability favors laminators with captive roll-to-roll expertise rather than pure-play equipment lessors exposed to automotive cyclicality. Monitor MFDS biocompatibility guideline harmonization with FDA standards as the inflection signal for South Korean healthcare device export expansion.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Substrate Reformulation | European medical device laminators must requalify fluorine-free barrier films before 2026 deadlines. |
| Automotive Tier-1 Supply Agreement | Curved instrument panel specifications from Bavaria-based cockpit module suppliers anchor volume commitments. |
| Solid-State Thin-Film Battery Integration | Self-powered skin-wearable patches eliminate external charging infrastructure for remote patient monitoring. |
| Printed Silver Nanowire Network Scale-Up | Gravure-printed transparent conductors decentralize procurement from Chinese indium tin oxide sputtering. |
| India PLI Scheme Manufacturing Footprint | Production-linked incentives in Gujarat attract substrate laminators serving display assembly corridors. |
Research Approach
Multi-period observation of roll-to-roll manufacturing capacity additions, REACH chemical restriction implementation timelines, and FDA 510(k) clearance volumes anchored the trend analysis, supplemented by interviews with biomedical engineers at hospital purchasing committees, GPO contracts managers, substrate converter plant managers, and automotive tier-1 procurement leads. Secondary validation drew from FDA filings, ECHA REACH Annex XVII updates, SEC 10-K disclosures from display manufacturers, and customs data for polyimide precursor trade flows. Bottom-up substrate production estimates triangulated against top-down healthcare device shipment projections.
Segment-weighting across product type, application, material substrate, and end-user procurement sophistication shaped the analytical framework, with value allocations calibrated to margin structures in regulated healthcare versus commoditized consumer segments. CAGRs derived from multilayer flexible circuit yield improvement curves, solid-state battery energy density roadmaps, and automotive display content-per-vehicle trajectories. Forecast inputs incorporated MFDS biocompatibility guideline harmonization schedules and EU Green Deal hazardous material substitution mandates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to indium tin oxide supply disruption, pyromellitic dianhydride feedstock volatility, and ISO 10993 requalification timelines for reformulated substrate coatings. Practitioners should monitor printed silver nanowire network adoption rates in foldable smartphone assemblies and automotive tier-1 haptic surface specifications for early signals of transparent conductor technology transition.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Global 3D TSV and 2.5D Market
Emerging and Next Generation Technologies
Mexico Cleanroom Technology Market
Emerging and Next Generation Technologies
Nanopatterning Market
Emerging and Next Generation Technologies
Haptic Technology Market
Emerging and Next Generation Technologies
Global Electronic Design Automation (EDA) Market
Emerging and Next Generation Technologies
Chipless RFID Market
Emerging and Next Generation Technologies
Flexible PV Cell Market
Emerging and Next Generation Technologies
Transparent Solar Cells Market
Emerging and Next Generation Technologies
Hyperscale Computing Market
Emerging and Next Generation Technologies
Triboelectric Nano-Generator Market
Emerging and Next Generation Technologies
Global Broad Ion Beam Technology Market
Emerging and Next Generation Technologies
Global Hybrid Intelligence Market
Emerging and Next Generation Technologies
Asia Pacific Quantum Computing Market
Emerging and Next Generation Technologies
Molecular Electronics Market
Emerging and Next Generation Technologies
Stretchable Electronics Market
Emerging and Next Generation Technologies
Global High-Performance Computing (HPC) Market