
 Haptic Technology Market | 2026-2036
Haptic Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Haptic Technology Market Analysis
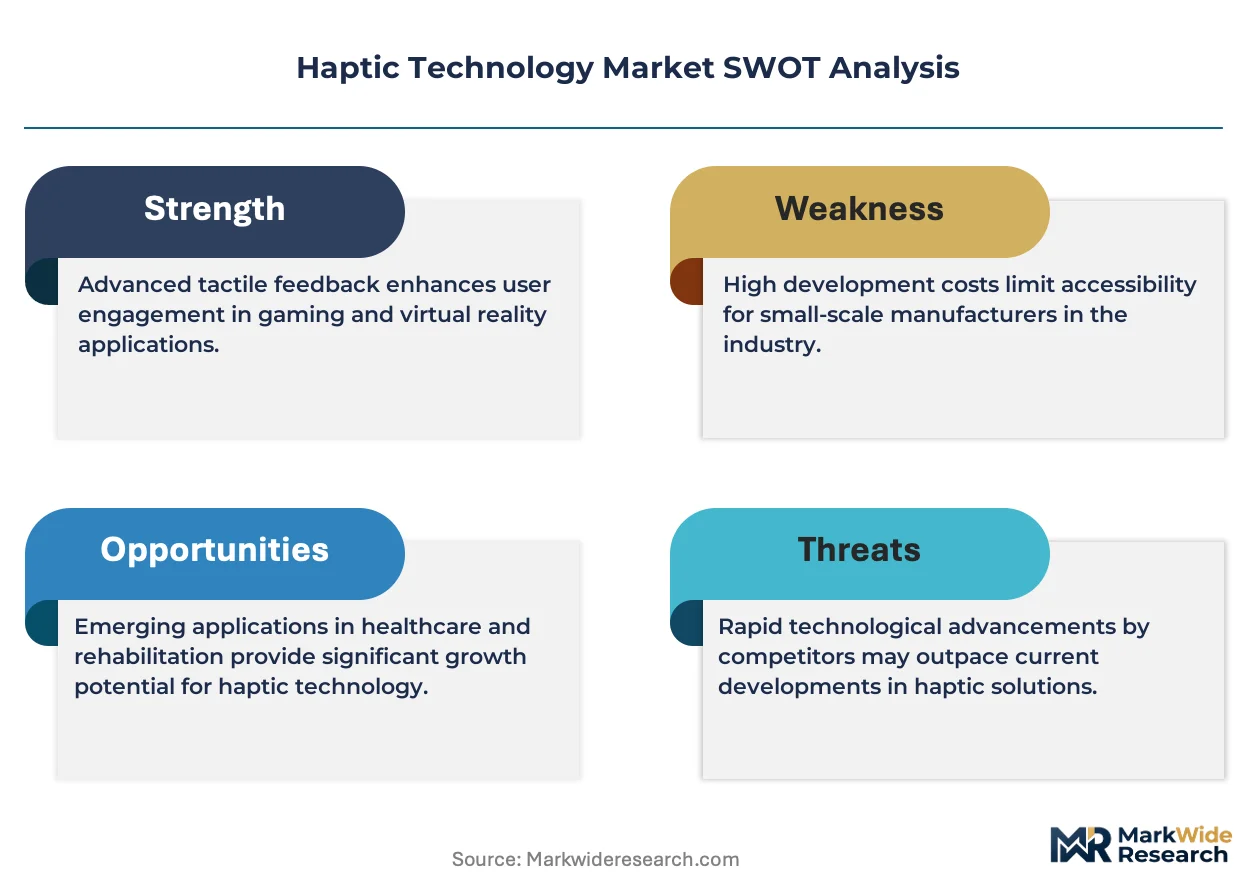
The haptic feedback stack is fragmenting across piezoelectric, eccentric rotating mass, and linear resonant actuator architectures as OEMs demand application-specific performance profiles. Synaptics Incorporated leverages its touch controller heritage to anchor premium mobile haptic modules. Texas Instruments Incorporated sustains R&D intensity in precision driver ICs for automotive and industrial feedback loops. Ultraleap Holdings Ltd. differentiates through ultrasonic mid-air haptics, competing for spatial computing deployments where contactless interaction is mandatory.
Haptic technology encompasses mechanical systems that generate tactile sensations through vibration, force, or motion feedback, typically operating at frequencies between 50 Hz and 300 Hz with displacement resolutions below 0.1 mm for precision applications. Its primary commercial purpose is to close the sensory loop in human-machine interfaces, enabling operators to perceive texture, pressure, or spatial boundaries without visual confirmation. Actuators and feedback devices command the dominant value share as automotive interfaces and medical training systems demand higher fidelity and faster response times than legacy eccentric motor solutions can deliver. Wearable devices represent the fastest-expanding product type category, driven by AR glasses and fitness bands that embed localized vibration patterns for navigation alerts and biometric notifications.
The Federal Communications Commission in the United States governs electromagnetic emissions from wireless haptic controllers, while the EU's Radio Equipment Directive and CE marking framework enforce interoperability and safety standards for devices sold across member states. Japan's Ministry of Economy, Trade and Industry coordinates domestic haptic innovation through JIS standards for industrial robotics and automotive applications, shaping procurement criteria for exporters. Stakeholders must monitor how the EU AI Act's risk classification system applies to autonomous systems incorporating haptic feedback loops, as compliance costs will reshape vendor selection criteria for European automotive and healthcare buyers.
Market Dynamics
The haptic technology market is fragmenting across actuator architectures as automotive and consumer electronics OEMs demand application-specific performance profiles rather than one-size-fits-all vibration modules. This specialization is forcing component suppliers to align R&D roadmaps with discrete torque, frequency, and displacement requirements.
Growth Catalysts
- EU AI Act compliance mandates:European automotive and healthcare buyers now require certified human-machine interfaces, creating procurement pull for haptic feedback systems that meet risk classification standards for autonomous operation.
- Linear resonant actuators (LRAs):These precision vibration motors deliver faster response times and richer texture libraries than eccentric rotating mass alternatives, accelerating replacement cycles in premium mobile devices.
- South Korea's consumer electronics cluster:Samsung and LG integration of advanced tactile feedback into flagship smartphones and wearables concentrates component demand in Gyeonggi Province fabrication facilities.
Market Restraints
- Piezoelectric ceramic supply concentration:High-purity lead zirconate titanate feedstock depends on Chinese and Japanese specialty chemical suppliers, exposing actuator manufacturers to input cost volatility and export control risks.
- CE marking friction:The EU's Radio Equipment Directive imposes extended interoperability testing timelines for wireless haptic controllers, delaying product launches by 6-12 months for non-European vendors.
- Ultrasonic mid-air substitution:Contactless haptic alternatives from Ultraleap Holdings threaten to displace physical actuator demand in spatial computing applications where hygiene and wear elimination matter.
Strategic Opportunities
- India's medical simulation market:Surgical training centers in Bengaluru and Hyderabad remain underpenetrated by high-fidelity haptic interfaces, offering first-mover positioning for force-feedback device vendors.
- Automotive haptic steering:Germany's KBA type-approval process for driver assistance systems is accelerating certification pathways for force-feedback interfaces in lane-keeping and parking assist applications.
- Piezoelectric-LRA convergence:Hybrid actuator architectures combining piezo precision with LRA bandwidth are opening white space in industrial robotics where both spatial resolution and sustained vibration are required.
Industry Challenges
- Mechatronics talent scarcity:The intersection of mechanical vibration engineering and embedded firmware development lacks trained practitioners, extending product development cycles for complex multi-axis feedback systems.
- ISO 26262 functional safety certification:Automotive haptic interfaces require ASIL-rated hardware and software validation, demanding 18-24 month compliance timelines that strain startup capitalization.
- Legacy CAN bus integration:Industrial and automotive haptic modules must interface with decades-old controller area network protocols, forcing expensive backward compatibility engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Haptic Technology Market |
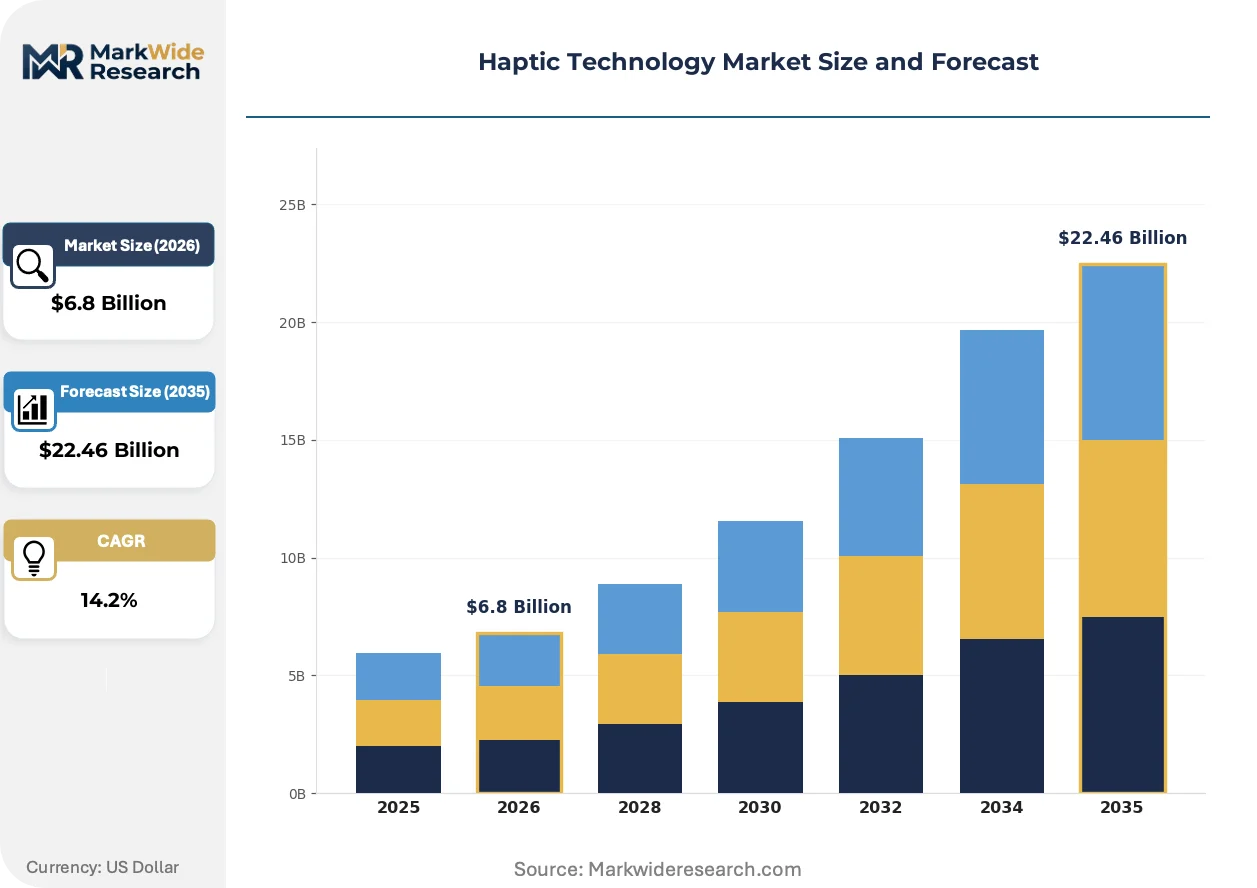
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Microcontrollers, Actuators, Feedback Devices, Sensors Product Type: Wearable Devices, Gaming Controllers, Mobile Devices, Automotive Interfaces Application: Virtual Reality, Teleoperation, Robotics, Medical Training End User: Gaming Industry, Healthcare Providers, Automotive Manufacturers, Entertainment Sector |
| Companies Covered | Immersion Corporation, 3D Systems Corporation, Synaptics Incorporated, Texas Instruments Incorporated, Johnson Electric Holdings Limited, Microchip Technology Inc., Ultraleap Holdings Ltd., Cirrus Logic Inc., hap2U, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Haptic Technology Market Emerging Trajectories
Actuator architecture specialization is reshaping competitive positioning as end-users reject generic vibration modules. Vendors now compete on frequency bandwidth, displacement resolution, and thermal envelope rather than unit cost alone.
Piezoelectric actuators generate sub-millimeter precision displacement through ceramic deformation under electric field, enabling texture rendering in medical simulation and automotive interfaces. Automotive Tier 1 suppliers in Germany and Japan are adopting these modules for steering wheel feedback at accelerating procurement volumes. This technology is hybridizing with legacy eccentric motor supply chains, compressing the addressable market for commodity vibration components while expanding premium actuator margins.
The EU AI Act's risk classification framework now governs autonomous systems incorporating haptic feedback loops, mandating documented safety validation for high-risk applications. Industrial consequence includes mandatory third-party conformity assessment for surgical robots and driver assistance interfaces sold in member states. Medical device and automotive OEMs are responding by front-loading compliance expenditure into 2024-2025 product development cycles, prioritizing European market entry over faster regulatory jurisdictions.
Certification-driven procurement preferences are displacing specification-sheet buying in safety-critical haptic applications. European healthcare systems and German automotive OEMs now require CE marking plus functional safety documentation before vendor qualification, replacing traditional price-performance evaluation. This shift is most visible in surgical robotics and advanced driver assistance systems, where procurement committees exclude non-compliant suppliers regardless of technical superiority or cost position.
Haptic Technology Market Segmentation
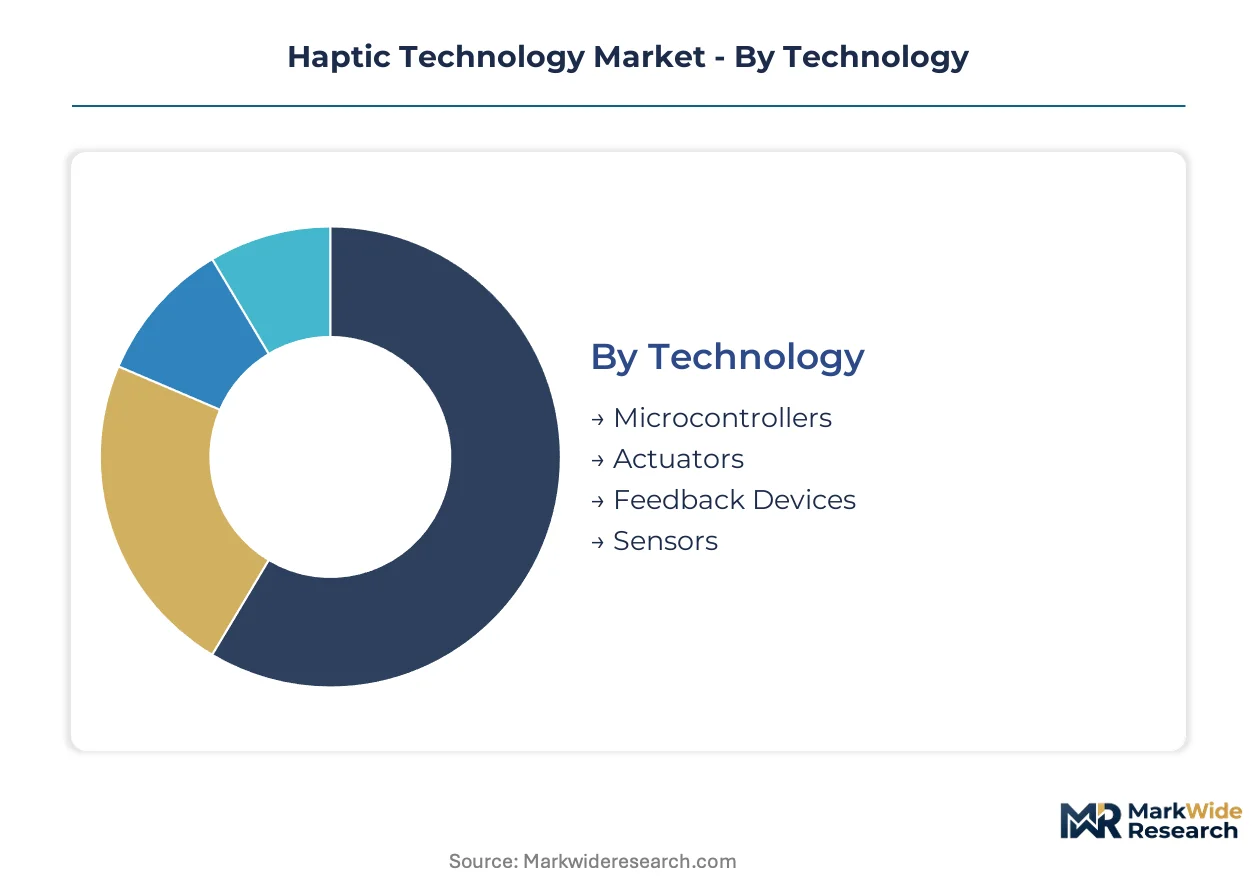
Haptic technology segments diverge sharply in replacement cadence. Automotive interfaces and medical training systems operate on multi-year validation cycles, while mobile and gaming peripherals refresh annually. Understanding these velocity differentials shapes inventory positioning and R&D allocation across supplier portfolios.
Technology:
Actuators and driver ICs exhibit the widest cycle-time dispersion, with consumer-grade eccentric motors turning in 12-18 months versus automotive-qualified piezo stacks enduring 5-7 year design locks.
- Microcontrollers:Embedded processors orchestrate timing sequences and waveform libraries, executing closed-loop control algorithms at sub-millisecond latency. Demand clusters in Germany's automotive Tier 1 suppliers, where KBA type-approval requirements for driver assistance systems mandate ASIL-rated hardware validation that extends procurement timelines.
- Actuators:Electromechanical transducers convert electrical signals into mechanical displacement through piezoelectric ceramics, voice coils, or eccentric rotating masses. South Korea's Gyeonggi Province fabrication facilities concentrate LRA production for Samsung and LG flagship device programs, with force-feedback modules for automotive steering now commanding premium qualification cycles.
- Feedback Devices:Integrated modules combining actuators with haptic rendering software deliver texture libraries and pressure profiles to end-users. Gaming peripheral manufacturers in Shenzhen and Dongguan drive volume procurement for controller rumble packs.
- Sensors:Force, pressure, and capacitive arrays capture operator input for closed-loop haptic response. Industrial robotics integrators in Japan specify high-resolution strain gauges for teleoperation precision.
Actuators anchor the volume base while microcontrollers gain share at the steepest rate as software-defined haptic experiences displace hardware-only solutions.
Product Type:
Cost stratification separates disposable consumer peripherals from capital-intensive automotive and medical installations, with certification burden driving tiered pricing architecture.
- Wearable Devices:Compact haptic modules embedded in AR glasses, fitness bands, and smartwatches deliver navigation alerts and biometric notifications through localized vibration patterns. Component suppliers target Bengaluru and Hyderabad medical simulation centers with force-feedback gloves for surgical training applications.
- Gaming Controllers:Handheld peripherals deploy eccentric motors and LRAs for immersive rumble effects. Console manufacturers refresh controller SKUs annually, compressing supplier margin cycles.
- Mobile Devices:Smartphones integrate linear resonant actuators beneath display surfaces for precise tap simulation and texture rendering. Samsung and LG procurement committees in South Korea specify frequency bandwidth and displacement resolution thresholds that exclude commodity vibration vendors.
- Automotive Interfaces:Steering wheels, center consoles, and seat systems incorporate force-feedback for lane-keeping alerts and parking assistance. Germany's KBA and Japan's METI coordinate divergent certification pathways that fragment supplier qualification investments.
Mobile devices generate the highest unit volumes while wearable devices expand most quickly as AR glasses and fitness bands proliferate.
Application:
Customer maturity varies dramatically, with medical and industrial buyers demanding documented safety validation while entertainment applications prioritize rapid feature iteration.
- Virtual Reality:Head-mounted displays and handheld controllers combine spatial tracking with haptic feedback for immersive simulation. Enterprise training deployments in Germany and Japan specify ISO 26262 and JIS-compliant hardware that extends sales cycles.
- Teleoperation:Remote manipulation systems transmit force feedback across network links, enabling hazardous environment operation. Industrial robotics OEMs in Japan integrate multi-axis haptic arms for nuclear and subsea applications.
- Robotics:Collaborative and surgical robots embed force-sensitive actuators for safe human interaction. The EU AI Act's risk classification framework mandates third-party conformity assessment for surgical systems sold in member states.
- Medical Training:Simulators replicate tissue resistance and instrument feedback for surgical education. India's Bengaluru and Hyderabad training centers remain underpenetrated by high-fidelity interfaces, offering first-mover positioning.
Robotics commands the highest average selling prices while medical training climbs the fastest as simulation-based credentialing expands.
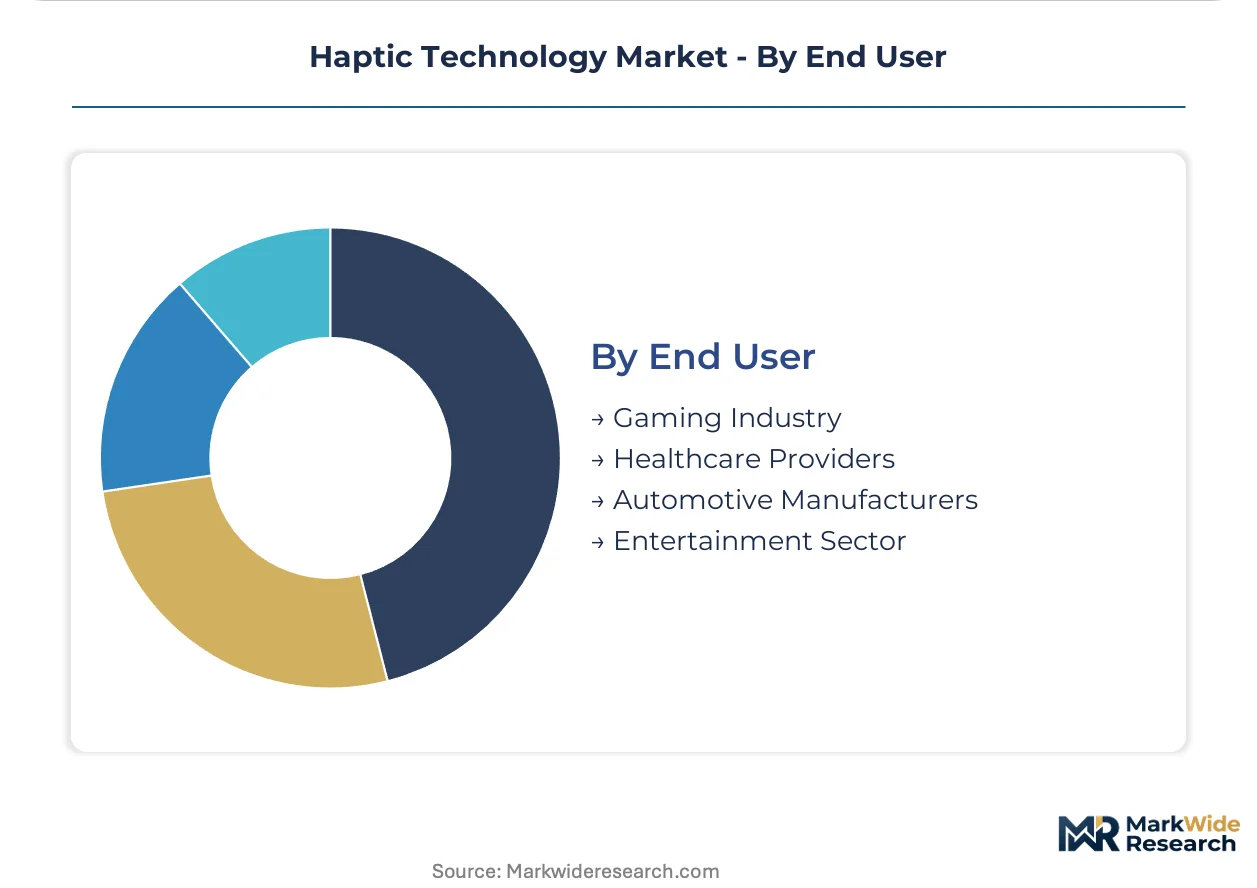
End User:
Procurement authority concentration differs across sectors, with automotive and healthcare buyers consolidating vendor selection through committee structures while gaming and entertainment segments fragment across publisher and studio purchasing decisions.
- Gaming Industry:Console manufacturers and peripheral publishers drive high-volume, low-margin actuator procurement. Annual SKU refreshes compress supplier development timelines.
- Healthcare Providers:Hospital systems and surgical training centers specify haptic interfaces for robotic surgery and simulation. European procurement committees now require CE marking plus functional safety documentation before vendor qualification.
- Automotive Manufacturers:OEMs and Tier 1 suppliers integrate force-feedback for advanced driver assistance systems. Germany's KBA type-approval process accelerates certification for lane-keeping and parking assist applications.
- Entertainment Sector:Theme parks, location-based VR venues, and cinema exhibitors deploy immersive haptic seating and environmental effects. Capital expenditure cycles follow entertainment real estate development patterns.
Automotive manufacturers anchor the revenue base while healthcare providers gain share at the steepest rate as surgical robotics and simulation credentialing expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and consumer electronics manufacturers concentrate procurement authority in Germany, Japan, and South Korea, while medical simulation demand is fragmenting across India's emerging training infrastructure. Regulatory divergence between the EU AI Act, Japan's METI standards, and the FCC's electromagnetic framework is forcing suppliers to maintain parallel certification tracks.
United States
The FCC governs electromagnetic emissions from wireless haptic controllers, creating compliance overhead for gaming peripheral and industrial teleoperation vendors. FDA scrutiny of surgical robotics incorporating force-feedback interfaces extends validation timelines for medical device submissions. California's Bay Area hosts spatial computing developers piloting ultrasonic mid-air haptic systems for enterprise AR deployments.
Germany
KBA type-approval requirements for driver assistance systems accelerate certification pathways for force-feedback steering interfaces in lane-keeping applications. The EU AI Act's risk classification framework mandates third-party conformity assessment for autonomous systems sold across member states. Bavarian automotive Tier 1 suppliers in Munich and Ingolstadt anchor European procurement volumes for piezoelectric actuator modules.
Japan
METI coordinates domestic haptic innovation through JIS standards for industrial robotics and automotive applications, shaping export procurement criteria for foreign vendors. PMDA oversight of surgical robots incorporating tactile feedback loops imposes documentation requirements comparable to EU MDR. Nagoya's Chubu region concentrates precision actuator manufacturing for Toyota and Honda advanced driver assistance programs.
South Korea
Samsung and LG procurement committees specify frequency bandwidth and displacement resolution thresholds that exclude commodity vibration vendors from flagship smartphone programs. MFDS certification requirements for surgical training simulators create parallel validation tracks for medical haptic interfaces. Gyeonggi Province fabrication facilities concentrate LRA production capacity serving Seoul Capital Area consumer electronics clusters.
India
Surgical training centers in Bengaluru and Hyderabad remain underpenetrated by high-fidelity haptic interfaces, offering first-mover positioning for force-feedback device vendors. BIS standards for electronic components are converging with international IEC frameworks, reducing import friction for certified actuators. CDSCO's medical device rules are tightening documentation requirements for surgical simulators, extending sales cycles for foreign suppliers.
Haptic Technology Market Vendor Landscape
Channel-controlling players compete with product-specialist players across actuator architectures and application verticals. The vendor base separates into three tiers: diversified semiconductor houses with touch controller heritage, precision actuator specialists serving automotive qualification requirements, and ultrasonic mid-air technology developers targeting spatial computing deployments. Consolidation pressure is intensifying as automotive OEMs reduce qualified supplier lists to manage ISO 26262 validation costs. Dominant competitive moves include strategic partnerships for piezoelectric ceramic feedstock security and geographic expansion into India's medical simulation infrastructure.
Within the touch controller heritage tier, Synaptics Incorporated and Cirrus Logic Inc. occupy positions shaped by mobile device integration requirements. Texas Instruments Incorporated exemplifies the precision driver IC archetype serving automotive and industrial feedback loops. Ultraleap Holdings Ltd. anchors the contactless haptics segment where spatial computing applications demand mid-air tactile rendering without physical actuator contact.
| Leading Market Players |
|---|
| Immersion Corporation |
| 3D Systems Corporation |
| Synaptics Incorporated |
| Texas Instruments Incorporated |
| Johnson Electric Holdings Limited |
| Microchip Technology Inc. |
| Ultraleap Holdings Ltd. |
| Cirrus Logic Inc. |
| hap2U |
| Others |
Supply Flow & Price Mechanics
Incheon-to-Rotterdam container freight corridors transmit cost volatility from piezoelectric ceramic feedstock hubs into European automotive actuator pricing, compressing margins for non-integrated suppliers while amplifying differentiation premiums for vendors with captive lead zirconate titanate sourcing.
Pricing Analysis
Cost-plus contracts with London Metal Exchange-linked indexation dominate piezoelectric ceramic procurement, insulating Japanese suppliers from spot volatility while exposing German Tier 1s to margin compression. Pricing stratifies across automotive ASIL-certified, medical CE-marked, and consumer-grade tiers, with certification burden accounting for the widest spreads. Cost compression in mobile LRA modules intensifies as Samsung and LG procurement committees consolidate qualified vendor lists. Gaming peripheral manufacturers exhibit highest price sensitivity, while surgical robotics buyers prioritize functional safety documentation over unit economics.
Supply Chain Analysis
Foxconn and Jabil Electronics concentrate contract manufacturing capacity for haptic driver ICs and LRA modules, with Pegatron holding secondary share in gaming peripheral assembly. Feedstock draws from Chinese and Japanese specialty chemical suppliers for lead zirconate titanate, South Korean foundries for precision voice coils, and Taiwanese packaging houses for ASIC integration. Single-source vulnerability concentrates in high-purity piezoelectric ceramics, where export control exposure threatens actuator cost stability. Distribution runs through automotive Tier 1 direct procurement, consumer electronics ODM channels, and medical device specialist distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Haptic technology markets reward service-attach strategies, with firmware licensing and texture library subscriptions expanding faster than hardware shipments as OEMs prioritize software-defined tactile experiences over commodity actuator procurement.
For Market Incumbents:Entrench ASIL-D certification leadership by accelerating KBA type-approval pathways for automotive steering interfaces, locking out non-compliant challengers. Deepen backward integration into lead zirconate titanate feedstock through offtake agreements with Japanese specialty chemical suppliers, neutralizing Chinese export control exposure. Ultrasonic mid-air substitution from Ultraleap Holdings threatens physical actuator demand in spatial computing deployments.
For New Entrants and Emerging Players:Establish a beachhead in India's surgical training infrastructure, where Bengaluru and Hyderabad simulation centers remain underpenetrated by force-feedback glove vendors. Target hybrid piezoelectric-LRA architectures for industrial robotics white space, where neither pure-play technology satisfies combined precision and bandwidth requirements. Partner with Gyeonggi Province fabrication facilities for LRA supply security before Samsung and LG procurement committees finalize qualified vendor lists.
For Investors and Strategic Acquirers:Carve-out targets emerge from diversified semiconductor houses with undermonetized haptic IP portfolios, where touch controller heritage can be extracted and focused on premium actuator markets. Long-term viability hinges on software-defined haptic rendering capabilities displacing hardware-only solutions. Watch for EU AI Act third-party conformity assessment bottlenecks as inflection signals for surgical robotics and automotive ADAS vendor consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Piezoelectric Ceramic Feedstock Security | Long-term offtake agreements with Japanese specialty chemical suppliers neutralize Chinese export control exposure for automotive actuator manufacturers. |
| EU AI Act Compliance Pre-Investment | Front-loaded third-party conformity assessment expenditure accelerates market entry for surgical robotics and ADAS interface vendors ahead of enforcement deadlines. |
| Hybrid Actuator Architecture Development | Convergence of piezoelectric precision with LRA bandwidth opens industrial robotics applications requiring simultaneous spatial resolution and sustained vibration. |
| India Medical Simulation Partnership | Force-feedback glove deployment in Bengaluru and Hyderabad training centers captures first-mover positioning in underpenetrated surgical education infrastructure. |
| Ultrasonic Mid-Air Haptics Licensing | Spatial computing platform integration licenses from Ultraleap Holdings enable contactless tactile rendering for enterprise AR deployments without physical actuator manufacturing. |
Methodological Framework
Cross-validation between primary interviews with automotive Tier 1 procurement directors, surgical robotics biomedical engineers, and consumer electronics ODM program managers anchors the qualitative findings, with secondary triangulation against SEC 10-K filings, KBA type-approval databases, and EU AI Act implementation guidance. Bottom-up actuator shipment modeling and top-down haptic module value estimation converge through iterative reconciliation across the analysis window.
Calibration against historical automotive qualification timelines and mobile device refresh cycles shapes the projection framework, with segmentation across actuator architecture, product type, application, and end-user verticals. CAGRs derive from weighted average of technology adoption curves and replacement cadence differentials, incorporating EU regulatory enforcement assumptions and South Korean consumer electronics procurement patterns as sensitivity inputs.
Sensitivities concentrate around EU AI Act third-party assessment capacity constraints, Chinese export control expansion for piezoelectric ceramics, and ultrasonic mid-air haptics substitution velocity in spatial computing. Quarterly review of KBA type-approval queue lengths, MFDS medical device certification timelines, and Gyeonggi Province LRA fab utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Global High-Performance Computing (HPC) Market
Emerging and Next Generation Technologies
Metamaterial Medium Market
Emerging and Next Generation Technologies
Third-Generation Solar Cells Market
Emerging and Next Generation Technologies
Printed Electronics Market
Emerging and Next Generation Technologies
Global Plasma Pulse Technology Market
Emerging and Next Generation Technologies
Piezoelectric Nanogenerator Market
Emerging and Next Generation Technologies
Edge Computing Market
Emerging and Next Generation Technologies
Asia Pacific Wigig Market
Emerging and Next Generation Technologies
Programmable Semiconductor Technologies Market
Emerging and Next Generation Technologies
Global Digital Twin Technology Market
Emerging and Next Generation Technologies
Swarm Intelligence Market
Emerging and Next Generation Technologies
North America Wigig Market
Emerging and Next Generation Technologies
Triboelectric Nano-Generator Market
Emerging and Next Generation Technologies
Nanodiamond Market
Emerging and Next Generation Technologies
North America Quantum Computing Market
Emerging and Next Generation Technologies
Ultra-Fine Ath Market