
 Global 3D TSV and 2.5D Market | 2026-2036
Global 3D TSV and 2.5D Market Size, Share, and Industry Trends Forecast 2026-2036
Global 3D TSV and 2.5D Market Analysis
Hyperscale data center operators are unwinding traditional monolithic chip procurement as memory bandwidth bottlenecks force a shift toward chiplet-based architectures. Taiwan Semiconductor Manufacturing Company Limited leverages CoWoS capacity expansion to anchor advanced interposer supply for NVIDIA and AMD accelerators. Samsung Electronics Co. Ltd sustains hybrid bonding R&D across its Pyeongtaek complex to compete in HBM stacking. Intel Corporation differentiates through Foveros direct bonding while navigating foundry model transitions.
3D TSV and 2.5D refer to vertical and quasi-vertical integration technologies that connect stacked silicon dies through microscopic copper-filled vias or silicon interposers, enabling inter-die bandwidth exceeding 2 TB/s with sub-100-micron interconnect pitches. Through Silicon Via technology leads in high-bandwidth memory applications where pitch scaling below 40 micrometers defines yield economics, while 2.5D Interposer platforms capture margin pools in multi-die AI processors where reticle-size substrates command premium pricing. Fine Pitch bonding methods are displacing conventional wire bonding in networking equipment where signal integrity requirements exceed 56 Gbps per lane.
EPA cleanroom emission standards and OSHA semiconductor chemical exposure limits shape fabrication facility siting decisions across the United States, while REACH substance restrictions and the EU Chips Act investment thresholds govern European interposer qualification pathways. China's MIIT GB standards and dual carbon goals constrain new TSV etching capacity additions. Stakeholders must monitor how export control classifications on advanced packaging equipment reshape supplier eligibility for Chinese foundry projects.
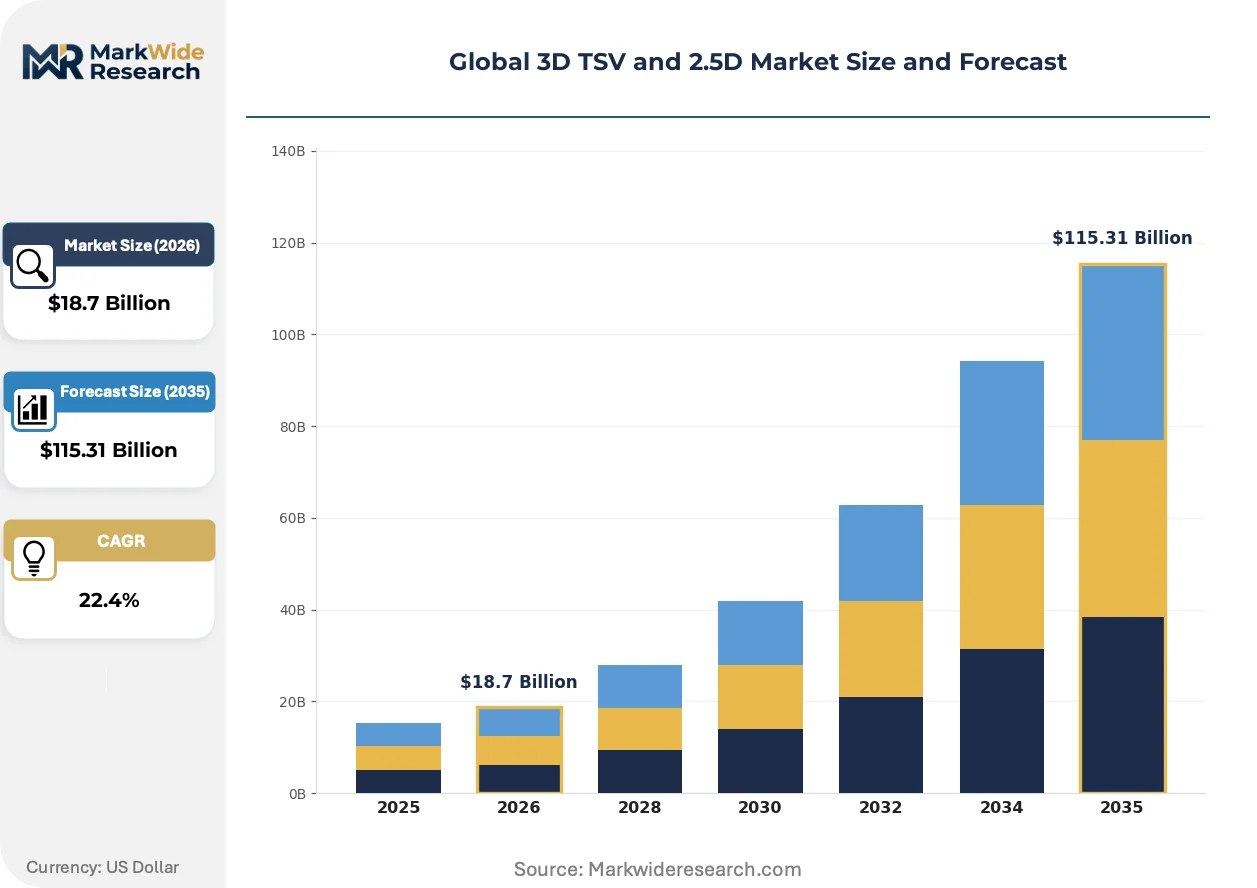
Market Dynamics
Chiplet disaggregation is compressing monolithic die economics while pulling foundry investment toward interposer and hybrid bonding capacity. Memory bandwidth walls in AI training clusters now dictate packaging technology roadmaps more than transistor scaling.
Growth Catalysts
- HBM3E stacking requirements:High-bandwidth memory generations above 24GB layers demand TSV pitch scaling below 30 micrometers, locking in copper via etching capacity expansion.
- EU Chips Act capital access:European interposer fabrication projects qualify for streamlined investment screening under the regulation's advanced packaging carve-out.
- China MIIT dual carbon enforcement:Domestic foundry qualification pathways now prioritize low-emission TSV etching chemistries, redirecting subsidy flows toward greenfield interposer lines.
Market Restraints
- Fluorinated gas supply concentration:C4F8 and SF6 etching precursors face export licensing bottlenecks from Japanese and South Korean chemical suppliers.
- Hybrid bonding yield cliffs:Sub-10 micrometer pitch direct bonding exhibits defect rates above commercial thresholds at wafer scales above 300mm.
- OSHA cleanroom exposure limits:United States fabrication siting decisions face NIOSH permissible exposure limit compliance costs for copper nanoparticle handling.
Strategic Opportunities
- India PLI scheme packaging incentives:Domestic semiconductor assembly and test capacity expansion includes TSV-enabled module qualification for import substitution.
- Automotive sensor fusion modules:LiDAR and camera processor chiplets in autonomous driving platforms create new interposer volume outside data center concentration.
- Photonics-electronics convergence:Silicon photonic transceivers for 800G networking leverage 2.5D interposer platforms for laser diode integration.
Industry Challenges
- Process integration engineering scarcity:Hybrid bonding and TSV metrology expertise concentrates among senior engineers at Taiwan and South Korean foundries.
- Multi-die thermal management certification:JEDEC HBM3 thermal interface specifications require extended validation cycles for new interposer materials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 3D TSV and 2.5D Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D TSV, 2.5D Interposer, Hybrid Bonding, Embedded Die Technology: Through Silicon Via, Microbumps, Fine Pitch, Wafer Level Packaging Application: Consumer Electronics, Aerospace Systems, Data Storage Solutions, Networking Equipment End User: Semiconductor Foundries, OSAT Providers, Electronic OEMs, Contract Manufacturers |
| Companies Covered | ASE Technology Holding Co. Ltd, Broadcom Ltd, Taiwan Semiconductor Manufacturing Company Limited, JCET Group Co. Ltd, United Microelectronics Corp., Samsung Electronics Co. Ltd, Amkor Technology, Powertech Technology Inc., Intel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 3D TSV and 2.5D Market Emerging Trajectories
Packaging technology roadmaps are diverging from monolithic scaling economics toward heterogeneous integration architectures. Three concurrent developments are reshaping competitive positioning.
Hybrid bonding is fragmenting the high-bandwidth memory stack market into pitch-specific tiers. AI accelerator designers at hyperscale operators now specify direct bonding for HBM4 prototypes while maintaining TSV microbumping for current generation products. This technical schism is fragmenting equipment supplier relationships and creating captive bonding development programs at major foundries.
REACH substance restrictions on per- and polyfluoroalkyl substances are forcing European interposer manufacturers to qualify fluorine-free plasma etching chemistries. ECHA authorization timelines now extend TSV process qualification cycles by 8-14 months for new material introductions. German and French packaging research consortia are accelerating alternative precursor development through national innovation funding.
Cloud service provider procurement is consolidating advanced packaging sourcing under direct foundry contracts rather than through traditional OSAT intermediaries. Microsoft, Amazon Web Services, and Google Cloud now negotiate CoWoS capacity allocations directly with Taiwan Semiconductor Manufacturing Company. This disintermediation is compressing margin pools for legacy packaging houses and transferring pricing power to foundry operators.
Global 3D TSV and 2.5D Market Segmentation
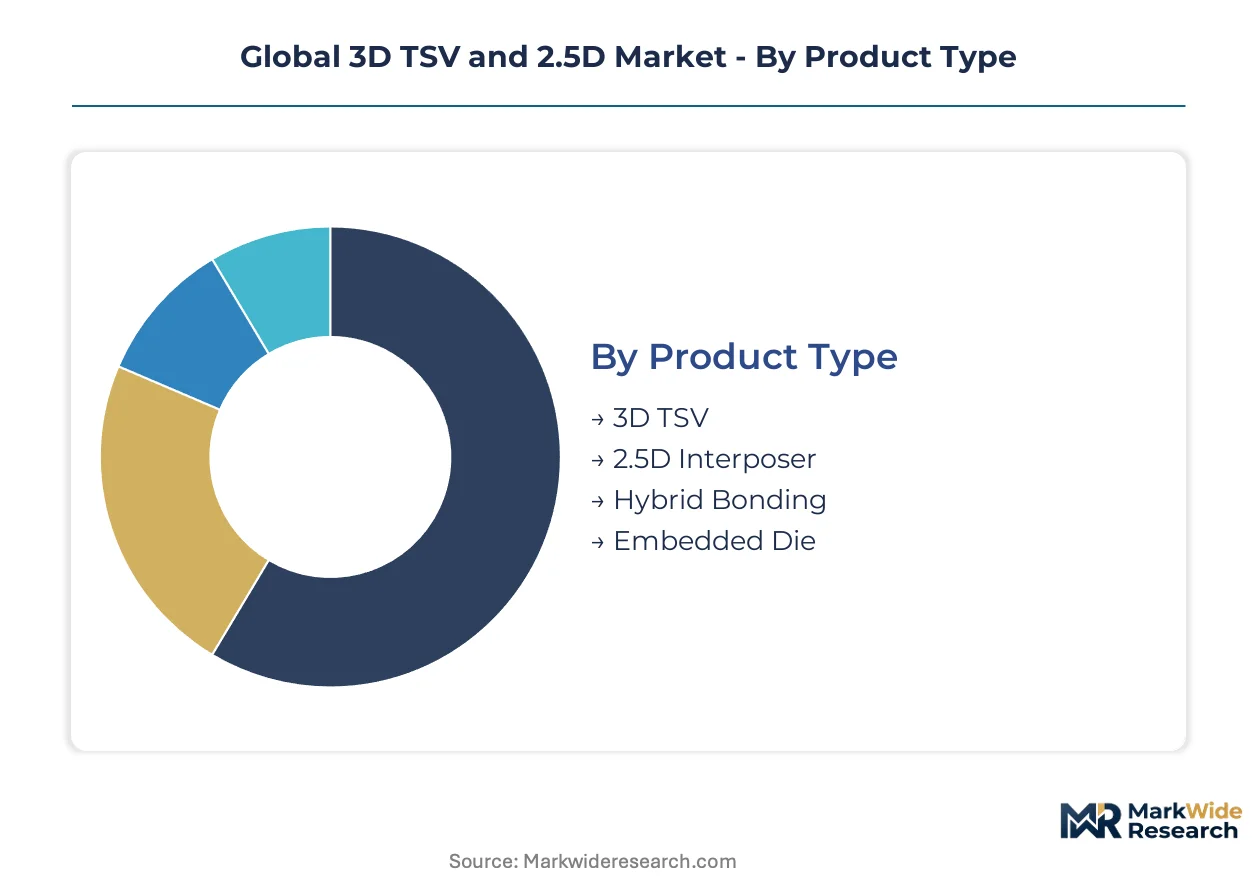
Packaging technology selection directly determines bandwidth ceilings and thermal budgets for AI accelerators and high-performance memory stacks. Foundries and OSAT providers allocate capital across these segments based on customer roadmaps for chiplet disaggregation and HBM stacking.
Product Type:
Premium pricing concentrates in technologies enabling sub-40-micron interconnect pitches, where yield economics separate profitable lines from commodity packaging.
- 3D TSV:Vertical copper-filled vias penetrate stacked silicon dies to deliver inter-layer bandwidth exceeding 2 TB/s. HBM3E production at Samsung and SK Hynix fabs in South Korea locks in TSV etching capacity for memory-first applications.
- 2.5D Interposer:Silicon substrates route signals between dies mounted side-by-side, bypassing reticle-size limits of monolithic chips. Taiwan Semiconductor Manufacturing Company anchors CoWoS supply for NVIDIA and AMD AI accelerators, commanding margin premiums on reticle-stitching expertise.
- Hybrid Bonding:Direct oxide-to-oxide bonding eliminates microbumps for sub-10-micron pitches. Intel Foveros and Samsung X-Cube programs target HBM4 prototypes.
- Embedded Die:Active components integrate into laminate substrates for automotive radar modules. European packaging houses qualify fluorine-free etching chemistries under ECHA timelines.
The dominant share belongs to 3D TSV, while hybrid bonding is closing the gap fastest as pitch scaling demands accelerate.
Technology:
Process maturity and equipment depreciation curves create cost tier separation between established via formation and emerging direct-bonding methods.
- Through Silicon Via:Deep reactive ion etching forms high-aspect-ratio vias filled with copper. Japanese chemical suppliers concentrate C4F8 and SF6 precursor production, creating export licensing bottlenecks for Chinese foundry projects.
- Microbumps:Solder-based interconnects bridge stacked dies at 40-100 micron pitches. Current HBM2E and HBM3 production relies on this established infrastructure.
- Fine Pitch:Thermocompression bonding achieves sub-20-micron bump pitches for networking equipment exceeding 56 Gbps per lane. Signal integrity requirements in 800G optical transceivers pull demand toward finer geometries.
- Wafer Level Packaging:Fan-out and fan-in redistribution layers package dies at wafer scale. Cost advantages in mobile application processors sustain volume outside data center concentration.
Through silicon via commands installed capacity leadership, though fine pitch is expanding most quickly in networking applications.
Application:
End-use thermal constraints and bandwidth requirements dictate interposer material selection and bonding method qualification cycles.
- Consumer Electronics:Mobile processors and wearables drive fan-out wafer-level packaging volumes. Cost sensitivity limits interposer adoption to premium tier smartphones.
- Aerospace Systems:Radiation-hardened chiplets for satellite payloads require extended JEDEC qualification cycles. Defense procurement in the United States and Europe sustains captive packaging lines.
- Data Storage Solutions:SSD controllers and CXL memory expanders leverage 2.5D integration for NAND interface aggregation. Hyperscale data center buildouts in Taiwan and the United States anchor demand.
- Networking Equipment:Switch ASICs and 800G optical engines demand sub-100-micron interconnect pitches. Signal integrity specifications exceed conventional wire bonding capabilities.
Networking equipment holds the steepest expansion trajectory, while consumer electronics maintains volume leadership through mobile processor shipments.
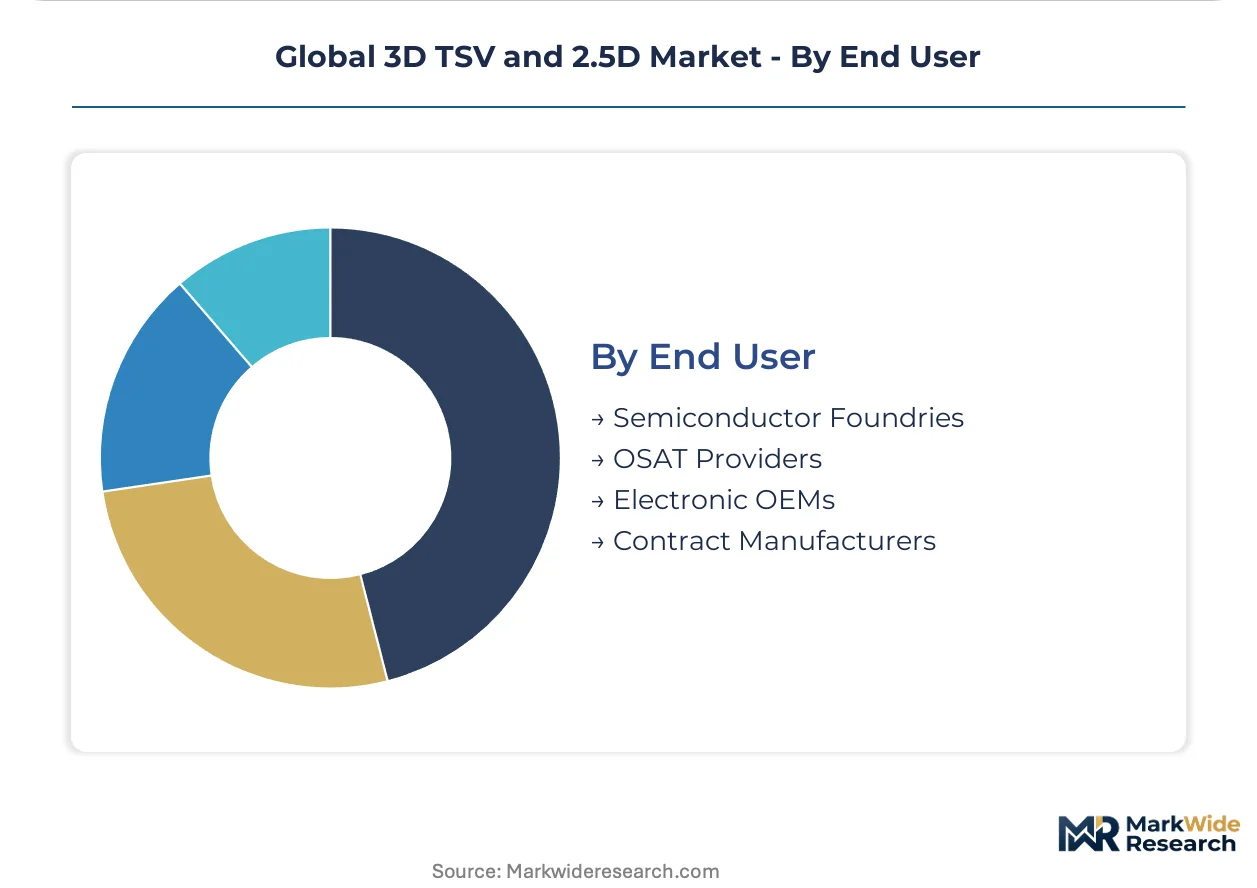
End User:
Customer type determines pricing power and capacity allocation priority in supply-constrained advanced packaging environments.
- Semiconductor Foundries:Taiwan Semiconductor Manufacturing Company, Samsung, and Intel internalize CoWoS and Foveros capacity. Direct contracts with Microsoft, Amazon Web Services, and Google Cloud disintermediate traditional OSAT relationships.
- OSAT Providers:ASE Technology and Amkor Technology compete for mid-range interposer and TSV module assembly. Margin compression from foundry verticalization forces specialization in automotive and industrial niches.
- Electronic OEMs:Apple and Tesla negotiate captive packaging capacity for proprietary chiplet architectures. In-house packaging engineering teams bypass standard OSAT qualification pathways.
- Contract Manufacturers:Foxconn and Jabil integrate TSV-enabled modules into system-level assembly. India PLI scheme incentives target this tier for domestic semiconductor ecosystem buildout.
Semiconductor foundries capture the dominant value share, though electronic OEMs are gaining procurement leverage through direct capacity investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
TSV-enabled production capacity clusters in Taiwan, South Korea, and the United States, with foundry investments concentrating in specific metropolitan corridors where regulatory frameworks and subsidy programs intersect.
United States
Hyperscale data center operators in Phoenix and Austin drive CoWoS capacity allocation for AI accelerators. EPA cleanroom emission standards and OSHA semiconductor chemical exposure limits shape fabrication facility siting decisions across Arizona and Texas. Intel's Foveros development in Oregon and New Mexico anchors domestic advanced packaging engineering.
Taiwan
TSMC's CoWoS expansion in Hsinchu and Taichung supplies NVIDIA and AMD interposer demand for training clusters. The National Development Council's semiconductor innovation subsidies prioritize TSV etching chemistry localization. Southern Taiwan Science Park hosts the densest concentration of hybrid bonding R&D lines outside South Korea.
South Korea
Samsung Electronics and SK Hynix in Pyeongtaek and Icheon lock in HBM3E TSV capacity for memory-first applications. METI-aligned export controls on fluorinated etching precursors create supply licensing bottlenecks for Chinese foundry projects. Seoul Capital Area fabs concentrate sub-30-micron pitch copper via expertise.
China
Domestic foundry qualification pathways under MIIT GB standards prioritize low-emission TSV etching for interposer lines. Dual carbon goals constrain new capacity additions in Yangtze River Delta clusters. Shanghai and Beijing packaging research consortia redirect subsidy flows toward greenfield interposer fabrication.
Germany
European interposer projects in Dresden and Munich qualify for EU Chips Act streamlined investment screening. ECHA REACH substance restrictions on per- and polyfluoroalkyl substances extend TSV process qualification cycles by 8-14 months. Fraunhofer packaging research consortia accelerate fluorine-free plasma etching precursor development.
Global 3D TSV and 2.5D Market Vendor Landscape
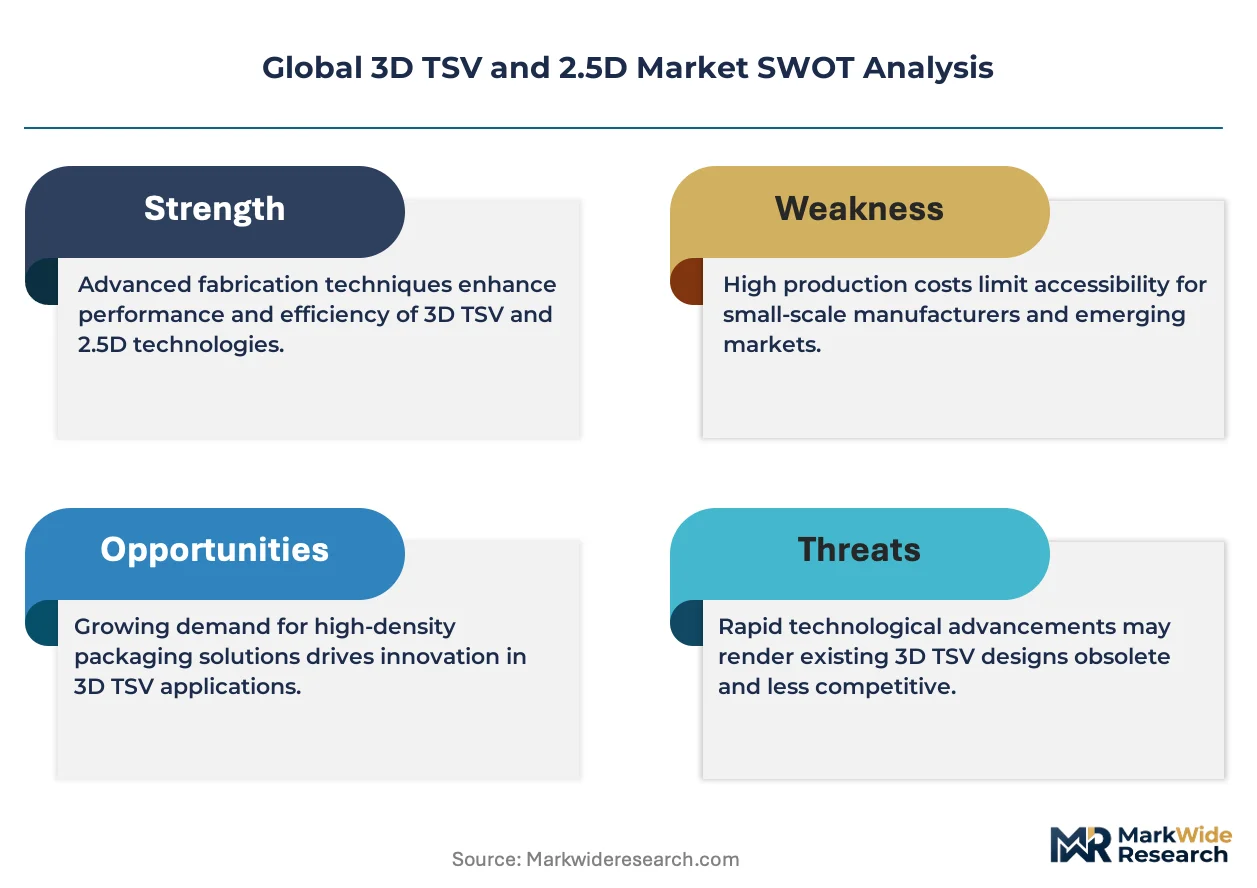
Concentration sits with integrated foundries that internalize CoWoS and Foveros capacity. The vendor structure tiers across three archetypes: pure-play foundries with captive packaging, memory-integrated conglomerates with HBM stacking expertise, and OSAT providers competing for mid-range module assembly. Foundry verticalization and direct cloud-provider procurement compress traditional packaging house margins. Capacity expansion and strategic partnerships dominate competitive moves.
Among Taiwan-based fabricators, Taiwan Semiconductor Manufacturing Company Limited and ASE Technology Holding Co. Ltd occupy positions at opposite ends of the integration spectrum. Samsung Electronics Co. Ltd represents the memory-integrated archetype with captive HBM stacking. Intel Corporation sits within the IDM-foundry hybrid tier navigating model transitions. JCET Group Co. Ltd exemplifies Chinese OSAT capacity targeting domestic substitution incentives.
| Leading Market Players |
|---|
| ASE Technology Holding Co. Ltd |
| Broadcom Ltd |
| Taiwan Semiconductor Manufacturing Company Limited |
| JCET Group Co. Ltd |
| United Microelectronics Corp. |
| Samsung Electronics Co. Ltd |
| Amkor Technology |
| Powertech Technology Inc. |
| Intel Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts lock in CoWoS interposer supply for hyperscale operators while anchoring price visibility across multi-year AI accelerator procurement cycles. These arrangements concentrate pricing power with Taiwan-based foundries as HBM3E stacking demand outstrips etching capacity additions in South Korea and the United States.
Pricing Analysis
Volume-discount tiering structures separate reticle-stitching expertise premiums from commodity microbumping rates. Three-tier pricing stratifies across CoWoS-enabled AI accelerators, standard HBM2E memory stacks, and fan-out mobile processors. Cost compression in mid-range interposer assembly intensifies because OSAT providers compete for automotive radar module qualification. Electronic OEMs with captive packaging engineering teams exhibit lowest price sensitivity, while contract manufacturers in India PLI scheme zones face acute margin pressure.
Supply Chain Analysis
Strategic stockpile preferences dominate fluorinated gas procurement as Japanese and South Korean chemical suppliers concentrate C4F8 and SF6 precursor production. Taiwan, South Korea, and the United States anchor TSV-enabled fabrication capacity. The supply chain draws from copper nanoparticle handling systems, deep reactive ion etching equipment, and silicon interposer substrates. Single-source vulnerability concentrates in hybrid bonding metrology tools. Distribution runs through direct foundry contracts with hyperscale operators rather than traditional OSAT intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Process integration engineering services and thermal interface validation contracts expand faster than hardware margins as heterogeneous integration complexity outpaces in-house foundry staffing. Recurring revenue from qualification-cycle acceleration and JEDEC compliance consulting now exceeds equipment depreciation schedules.
For Market Incumbents: Compound hybrid bonding yield expertise through captive R&D lines in Southern Taiwan Science Park before sub-10-micron pitch requirements commercialize. Lock in fluorine-free plasma etching precursor supply under ECHA REACH timelines to preempt European interposer qualification delays. Threat substitution from direct oxide bonding at Intel Foveros and Samsung X-Cube programs demands backward integration into copper via etching chemistry localization. For New Entrants and Emerging Players: Lead with automotive sensor fusion module packaging as LiDAR and camera processor chiplets escape data center demand concentration. India PLI scheme incentives for domestic semiconductor assembly and test capacity offer the most penetrable geographic entry point. Qualify TSV-enabled modules under BIS standards for import substitution contracts with contract manufacturers. For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors foundries with captive interposer supply over OSAT-dependent models. Long-term viability hinges on positioning before HBM4 prototype direct bonding transitions to volume production. Acquisition targets should display process integration engineering depth and existing JEDEC thermal specification validation records. Watch hybrid bonding defect rate trajectories at 300mm wafer scales as the inflection indicator for technology transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| CoWoS Capacity Expansion | TSMC's foundry additions in Hsinchu and Taichung anchor NVIDIA and AMD accelerator supply. |
| Fluorine-Free Etching Chemistry Development | Fraunhofer consortia in Dresden accelerate REACH-compliant precursor alternatives for European interposer lines. |
| Hybrid Bonding R&D Investment | Samsung's Pyeongtaek complex targets HBM4 sub-10-micron pitch direct bonding prototypes. |
| Direct Cloud Provider Procurement | Microsoft, Amazon Web Services, and Google Cloud negotiate capacity allocations outside OSAT channels. |
| Automotive Packaging Qualification | European packaging houses target LiDAR and camera processor chiplet modules for autonomous platforms. |
Methodological Framework
A spread of perspectives from foundry process integration engineers, OSAT procurement directors, hyperscale data center hardware architects, fluorinated gas chemical suppliers, and JEDEC standards committee members converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through SEC filings from TSMC, Samsung, Intel, and ASE Technology, SEMI equipment shipment databases, and EPA cleanroom emission compliance records. Bottom-up capacity buildout estimates triangulated against top-down AI accelerator demand projections from hyperscaler capex disclosures.
Segmentation dimensions modeled include packaging technology type, interconnect pitch tier, application thermal budget, end-user procurement archetype, and regional regulatory cluster across the analysis window. CAGRs derived from equipment depreciation curves, foundry capacity expansion announcements, and memory bandwidth scaling requirements in training clusters. Forecast inputs incorporated HBM layer stacking roadmaps and EU Chips Act investment screening timelines.
The analysis sits within stated boundaries; outcomes outside sustained AI training cluster buildouts or relaxed export control classifications would require recalibration. Forecasts reflect assumptions on hybrid bonding yield improvement trajectories and fluorinated gas supply licensing continuity. Revision becomes warranted when sub-10-micron pitch defect rates cross commercial thresholds or ECHA authorization timelines extend beyond process qualification windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Global Broad Ion Beam Technology Market
Emerging and Next Generation Technologies
Next Gen TV (ATSC TV) Market
Emerging and Next Generation Technologies
Transparent Solar Cells Market
Emerging and Next Generation Technologies
Edge Computing Market
Emerging and Next Generation Technologies
Transparent Electronics Market
Emerging and Next Generation Technologies
Global Plasma Pulse Technology Market
Emerging and Next Generation Technologies
Metal Additive Manufacturing Systems Market
Emerging and Next Generation Technologies
Nanopatterning Market
Emerging and Next Generation Technologies
Next Generation Processors Market
Emerging and Next Generation Technologies
Metamaterial Medium Market
Emerging and Next Generation Technologies
In-Mold Electronics (IME) Market
Emerging and Next Generation Technologies
Global Terahertz Components and Systems Market
Emerging and Next Generation Technologies
Internet of Nano Things Market
Emerging and Next Generation Technologies
Multi-Touch Technology Market
Emerging and Next Generation Technologies
1550nm LiDAR Pulsed Fiber Laser Market
Emerging and Next Generation Technologies
Triboelectric Nano-Generator Market