
 Global Laser Material Market | 2026-2036
Global Laser Material Market Size, Share, and Industry Trends Forecast 2026-2036
Global Laser Material Market Foresight
Project finance for specialty ceramic production lines is tilting competitive advantage toward capital-intensive operators. Morgan Advanced Materials leverages its vertical integration in alumina substrates to sustain pricing power across fiber laser supply chains. CeramTec GmbH anchors European supply through its dominance in medical-grade ceramic formulations for surgical laser systems. BASF SE differentiates via polymer matrix innovations that extend thermal tolerance in high-power diode applications.
Laser materials comprise engineered substrates, gain media, optical components, and thermal management elements formulated to specific refractive indices, thermal conductivity thresholds, and damage resistance parameters, serving as the functional backbone of coherent light generation and beam delivery systems. Fiber laser technology leads installed capacity due to superior wall-plug efficiency and maintenance intervals, while ceramics and semiconductors capture expanding margin pools as power scaling demands intensify thermal load management. Polymers compete aggressively in cost-sensitive marking and engraving applications where lower fluence requirements reduce material specification thresholds.
FDA 21 CFR Part 820 quality system regulations and EU MDR material biocompatibility standards constrain market access for medical laser component suppliers, while China's GB standards and NMPA registration pathways impose parallel conformity burdens on imported gain media. REACH substance restrictions and RoHS hazardous material limits further narrow permissible dopant chemistries in European-manufactured laser crystals. Stakeholders must monitor divergence between FDA laser product classification rules and emerging EU AI Act risk frameworks for autonomous beam steering systems.
Market Dynamics
Power scaling in industrial fiber lasers is compressing thermal management tolerances, forcing material suppliers to reformulate ceramic substrates and dopant chemistries under tighter regulatory surveillance across multiple jurisdictions.
Growth Catalysts
- EU MDR traceability mandates:Medical device manufacturers in Germany and France now require batch-level documentation for laser crystals, pulling premium-grade sapphire and YAG substrates into surgical equipment supply chains.
- Semiconductor packaging miniaturization:Taiwan and South Korea's advanced packaging fabs are procuring UV-grade fused silica for wafer dicing applications at volumes that strain incumbent suppliers.
- China's dual carbon goals:MIIT efficiency standards for industrial equipment are accelerating replacement of CO2 lasers with fiber systems, expanding demand for ytterbium-doped gain media and aluminum nitride heat spreaders.
Market Restraints
- Rare earth element concentration:Neodymium and ytterbium processing capacity clusters in China's Inner Mongolia and Jiangxi provinces, exposing non-Chinese laser OEMs to supply interruption risks during export license reviews.
- REACH dopant restrictions:ECHA substance of very high concern listings for certain heavy metal stabilizers are forcing reformulation of Nd:YAG crystal growth melts, extending qualification timelines by 12-18 months for European suppliers.
- Technical ceiling on power density:Thermal lensing effects in conventional bulk crystal architectures impose hard limits on kilowatt-class continuous wave outputs, constraining penetration into thick-section metal cutting applications.
Strategic Opportunities
- India's PLI scheme for electronics:Subsidized capital expenditure for semiconductor and display manufacturing is creating first-mover openings for laser material distributors to establish local blending and finishing operations.
- Autonomous beam steering convergence:Integration of MEMS mirrors with AI-driven path planning in EU industrial installations is hybridizing optical component specifications, opening margin pools for adaptive coating technologies.
- Japan's METI hydrogen roadmap:Fuel cell stack manufacturing requires precision laser welding of bipolar plates, generating pull-through demand for corrosion-resistant ceramic nozzles and protective windows.
Industry Challenges
- Crystal growth technician scarcity:Czochralski and Bridgman furnace operation expertise concentrates in aging workforces across Russia and Ukraine, complicating capacity expansion plans for YAG and vanadate producers.
- Multi-jurisdiction certification stacking:Simultaneous FDA 510(k), EU MDR, and NMPA registration for a single medical laser crystal formulation requires parallel toxicology and biocompatibility studies, compressing R&D productivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Laser Material Market |
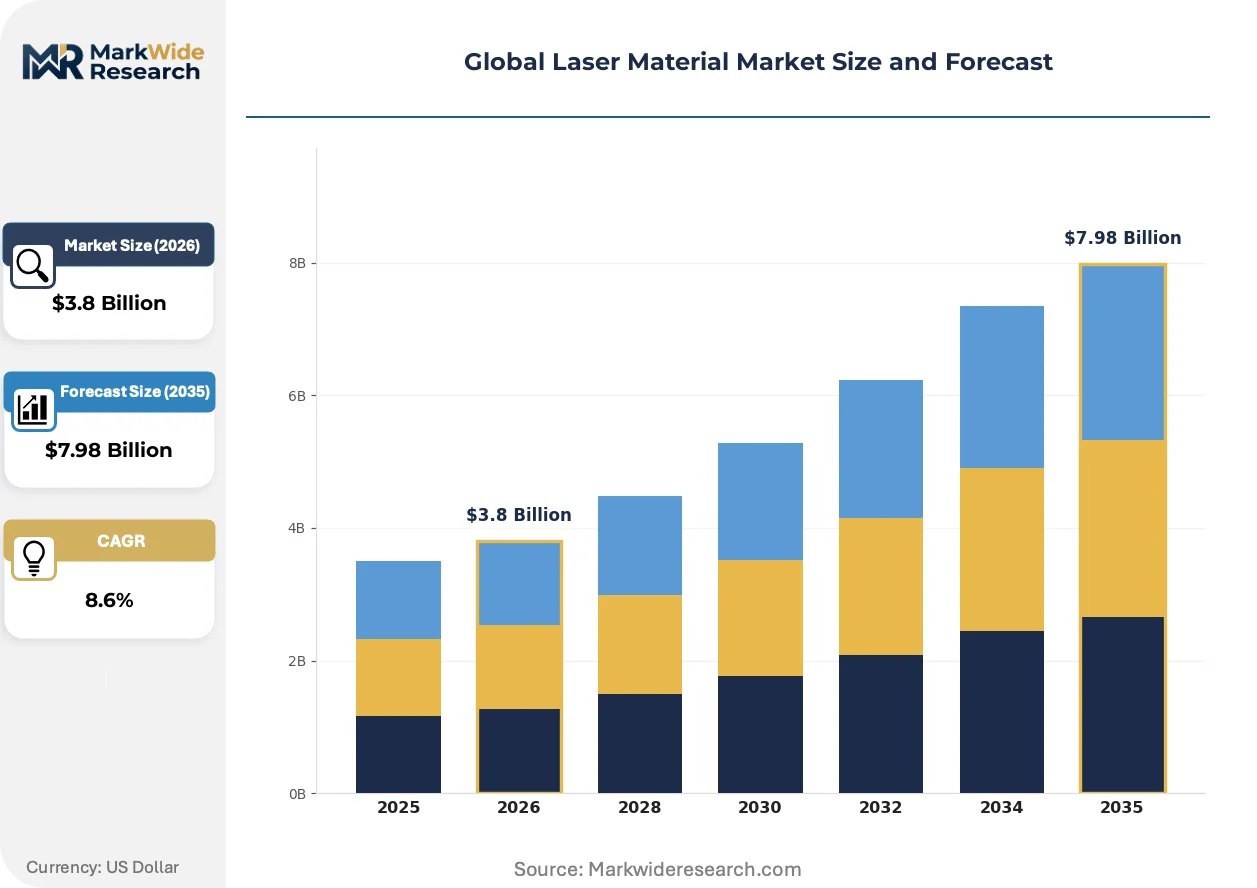
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Metals, Ceramics, Polymers, Composites, Glass, Semiconductors Laser Technology: CO2 Laser, Fiber Laser, Nd:YAG Laser, Diode Laser, Excimer Laser, Direct Diode Laser Application: Cutting, Welding, Marking, Engraving, Drilling, Micromachining End User Industry: Electronics Manufacturers, Aerospace Firms, Defense Contractors, Medical Device Makers, Consumer Electronics Firms, Fabrication Workshops |
| Companies Covered | Morgan Advanced Materials, Dow Chemical Company, BASF SE, CeramTec GmbH, Mitsubishi Chemical Holdings Corporation, Evonik, Corning Incorporated, GrafTech International, AGC Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Laser Material Market Shifts & Advancements
Material science advances are redefining performance boundaries across thermal, optical, and mechanical axes, while regulatory convergence and procurement rationalization reshape how specifications propagate through value chains.
Ceramic matrix composites for laser thermal management is hybridizing traditional alumina and aluminum nitride monoliths with silicon carbide reinforcement phases. Japanese automotive battery manufacturers are qualifying these materials for gigawatt-class welding stations. The structural consequence is compression of pure-play ceramic substrate margins as hybrid formulations capture high-heat-flux applications.
REACH substance restrictions are tightening permissible dopant chemistries in laser crystals manufactured for European medical device OEMs. ECHA's 2024 candidate list expansion forced immediate reformulation of chromium co-doping protocols in alexandrite growth processes. German surgical laser system builders now require suppliers to certify full material substance inventories down to 0.1% weight thresholds.
Direct long-term contracting between laser OEMs and rare earth processors is displacing spot-market purchasing for ytterbium and neodymium feedstocks. IPG Photonics and Trumpf have established offtake agreements with Australian and Canadian mining ventures. This pattern is most visible in North American defense and aerospace laser programs where supply assurance outweighs price optimization.
Global Laser Material Market Segmentation
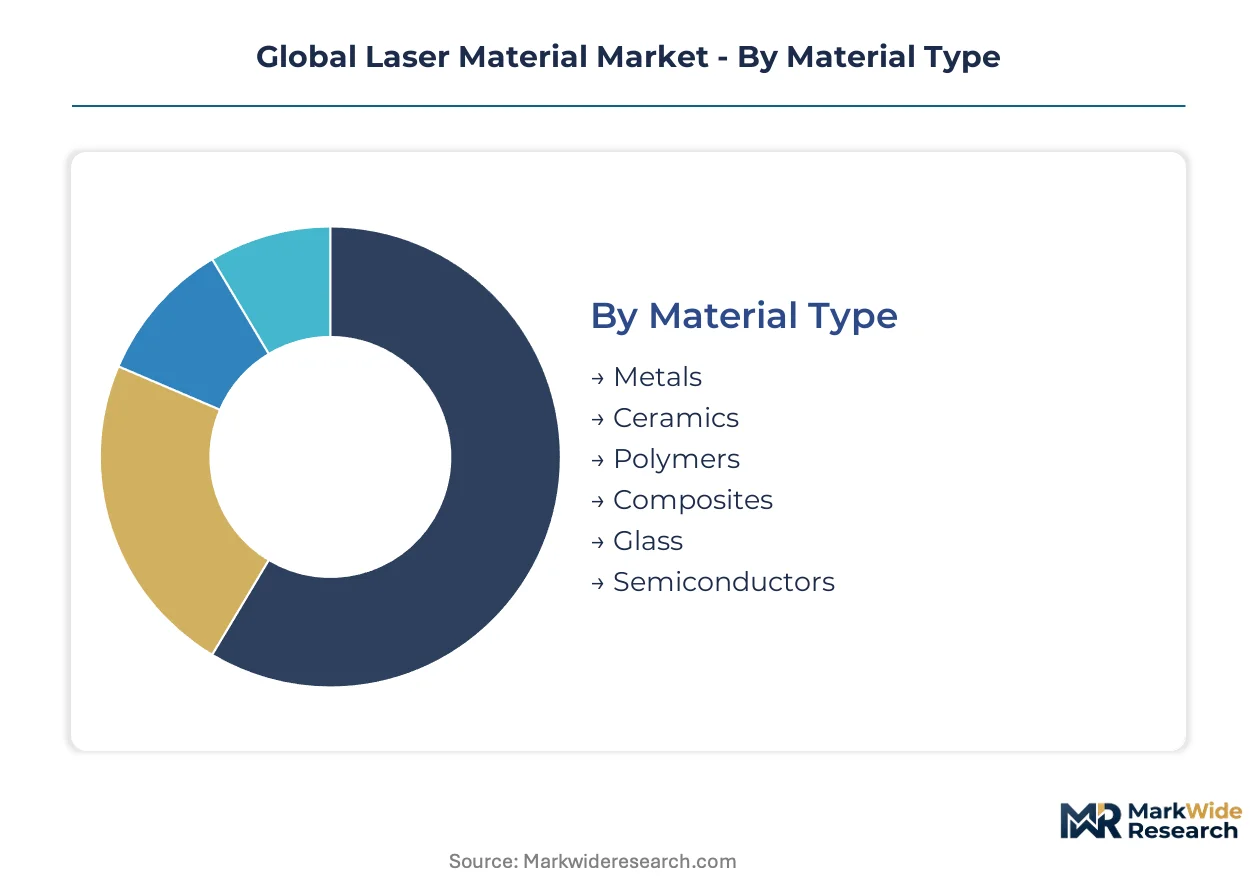
Material specifications in laser systems cascade through thermal, optical, and mechanical performance requirements. Procurement patterns diverge sharply between industrial power scaling and precision micromachining applications.
Material Type:
Use-case spectrum spans from high-thermal-flux industrial welding stations to cost-sensitive marking equipment where specification thresholds compress material selection.
- Ceramics:Aluminum oxide and aluminum nitride substrates manage heat flux in fiber laser resonators and pump modules. Demand concentrates in Germany's Stuttgart industrial cluster where TRUMPF and IPG Photonics qualify thermal management components for multi-kilowatt systems. REACH substance restrictions on dopant chemistries extend European supplier qualification timelines.
- Glass:Fused silica and borosilicate formulations deliver UV transmission and thermal shock resistance for excimer and CO2 laser optics. Taiwan's advanced packaging fabs are procuring UV-grade fused silica for wafer dicing at volumes that strain incumbent suppliers.
- Metals:Copper and aluminum heat sinks and electrode materials in solid-state laser pump chambers.
- Polymers:Polyimide and fluoropolymer coatings for flexible circuit marking and lower-power beam delivery.
- Composites:Ceramic matrix composites with silicon carbide reinforcement for next-generation thermal management in gigawatt-class welding stations.
- Semiconductors:Gallium arsenide and indium phosphide substrates for diode laser fabrication.
Established volume favors ceramics; emerging adoption favors composites.
Laser Technology:
Technology maturity determines whether material suppliers compete on specification refinement or cost minimization.
- Fiber Laser:Ytterbium-doped silica gain media and aluminum nitride heat spreaders dominate industrial metal cutting and welding. China's MIIT efficiency standards are accelerating CO2 laser replacement, expanding demand for ytterbium feedstocks. Australian and Canadian mining ventures are securing direct offtake agreements with major OEMs.
- CO2 Laser:Zinc selenide and gallium arsenide optics for legacy cutting systems in fabrication workshops. Demand concentrates in cost-sensitive emerging markets where replacement cycles lag industrialized economies.
- Nd:YAG Laser:Neodymium-doped yttrium aluminum garnet crystals for medical and precision industrial applications. ECHA substance of very high concern listings are forcing reformulation of chromium co-doping protocols.
- Diode Laser:Semiconductor epitaxial structures for direct energy applications and pump sources.
- Excimer Laser:Noble gas halide mixtures and UV-grade optical materials for semiconductor lithography and eye surgery.
- Direct Diode Laser:High-brightness semiconductor arrays for materials processing without fiber delivery.
Power scaling applications favor fiber architectures; precision medical systems sustain crystal-based platforms.
Application:
Process requirements stratify material specifications across thermal load, beam quality, and positioning precision.
- Cutting:High-power fiber laser systems with ceramic thermal management for thick-section metal processing. Thermal lensing effects in conventional bulk crystals impose technical ceilings on continuous wave outputs.
- Micromachining:Ultrafast laser systems with engineered nonlinear optical materials for electronics manufacturers in East Asia. Precision requirements pull premium-grade sapphire and YAG substrates into supply chains.
- Welding:Fiber and diode laser systems for automotive and battery manufacturing.
- Marking:Lower-power CO2 and fiber systems where polymer and coated metal specifications suffice.
- Engraving:Pulsed laser systems for decorative and functional surface modification.
- Drilling:Percussion and trepanning laser systems for aerospace component fabrication.
Throughput-driven cutting commands premium ceramics; precision micromachining drives specification innovation.
End User Industry:
Regulatory exposure and volume concentration reshape how material specifications propagate through procurement channels.
- Electronics Manufacturers:UV-grade fused silica and precision ceramics for semiconductor packaging and display fabrication. Taiwan and South Korea fabs are qualifying new suppliers for wafer dicing applications.
- Medical Device Makers:Biocompatible laser crystals and surgical system optics constrained by FDA 21 CFR Part 820 and EU MDR batch-level traceability mandates. German and French manufacturers now require full material substance inventories down to 0.1% weight thresholds.
- Aerospace Firms:High-reliability optical components for manufacturing and sensing applications.
- Defense Contractors:Supply-assured rare earth gain media for directed energy and rangefinding systems.
- Consumer Electronics Firms:Cost-optimized marking and welding materials for assembly automation.
- Fabrication Workshops:Standard-grade consumables for job-shop metal processing.
Regulatory stringency in medical devices favors certified suppliers; electronics volume drives procurement rationalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in rare earth feedstocks and finished optical components define regional competitive positioning. China maintains net exporter status in ytterbium-doped gain media while Germany and the United States run structural deficits in medical-grade ceramic substrates.
China
MIIT efficiency mandates are accelerating fiber laser deployment across metal fabrication workshops. NMPA medical device traceability rules now require batch-level documentation for imported gain media. Jiangxi and Inner Mongolia provinces host concentrated rare earth processing capacity that supplies domestic OEMs and selective export contracts.
Germany
Stuttgart and Munich industrial clusters drive procurement of aluminum nitride heat spreaders for multi-kilowatt fiber systems. EU MDR batch-level documentation requirements pull premium-grade sapphire into surgical laser supply chains. Baden-Württemberg's precision manufacturing base sustains demand for qualified ceramic substrates with full substance inventories.
United States
FDA 21 CFR Part 820 quality system regulations constrain market access for medical laser component suppliers. Defense and aerospace programs prioritize supply assurance over price optimization in rare earth procurement. IPG Photonics maintains direct offtake agreements with Australian and Canadian mining ventures to secure ytterbium feedstocks.
Japan
METI's hydrogen roadmap generates demand for corrosion-resistant ceramic nozzles in fuel cell stack manufacturing. Automotive battery producers are qualifying ceramic matrix composites for gigawatt-class welding stations. Kanto and Kansai industrial corridors concentrate precision optics fabrication for semiconductor lithography applications.
South Korea
Advanced packaging fabs in Gyeonggi Province are procuring UV-grade fused silica for wafer dicing at volumes straining incumbent suppliers. MFDS medical device regulations parallel EU MDR traceability standards for imported laser crystals. Seoul Capital Area electronics manufacturers are expanding laser material procurement for precision micromachining.
Global Laser Material Market Competitive Landscape
On the supply side, the industry is consolidating around capital-intensive operators with captive rare earth processing or vertical ceramic fabrication capabilities. Three strategic archetypes dominate: integrated materials-science conglomerates with polymer and ceramic portfolios, specialized ceramic substrate manufacturers with medical-grade certifications, and rare earth processors with direct OEM offtake relationships. Competitive moves concentrate on backward integration into feedstock supply and geographic expansion into subsidized manufacturing jurisdictions.
Among European ceramic specialists, CeramTec GmbH exemplifies the medical-grade certification archetype, while Morgan Advanced Materials occupies a position bridging industrial and medical applications through alumina substrate expertise. BASF SE represents the diversified materials-science conglomerate model with polymer matrix innovations for thermal management. These three entities anchor the competitive structure through differentiated control points across substrate formulations, regulatory qualifications, and polymer-ceramic hybrid portfolios.
| Leading Market Players |
|---|
| Morgan Advanced Materials |
| Dow Chemical Company |
| BASF SE |
| CeramTec GmbH |
| Mitsubishi Chemical Holdings Corporation |
| Evonik |
| Corning Incorporated |
| GrafTech International |
| AGC Inc. |
| Others |
Supply & Pricing Matrix
Rare earth export license reviews in China's Inner Mongolia and Jiangxi provinces expose non-Chinese laser OEMs to supply interruption risks that compress pricing spreads between premium-certified and standard-grade thermal management materials while forcing buyers toward long-term offtake contracts.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure that stratifies across premium, standard, and economy tiers. Price differentiation rests on certification grade—FDA 21 CFR Part 820 and EU MDR tiers command substantial premiums—and volume scale, with multi-year agreements securing ytterbium feedstock allocations. Cost compression in standard-grade ceramics is intensifying because Chinese MIIT efficiency standards are accelerating CO2-to-fiber laser conversions, stretching incumbent capacity. Defense contractors exhibit the least price sensitivity, prioritizing supply assurance through direct Australian and Canadian mining offtakes.
Supply Chain Analysis
Export-control regimes limiting flows of ytterbium-doped gain media and aluminum nitride substrates concentrate supply in China, Germany, and the United States. Raw material dependencies draw from neodymium and ytterbium rare earth oxides, UV-grade fused silica, and medical-grade sapphire substrates. Single-source vulnerability in Czochralski crystal growth expertise—concentrated in aging workforces across Russia and Ukraine—threatens YAG and vanadate expansion timelines. Distribution runs through qualified ceramic substrate distributors with medical-grade certifications and direct OEM procurement teams for defense programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward laser OEMs and defense contractors as direct offtake agreements with rare earth processors displace spot-market purchasing, consolidating procurement leverage among capital-intensive operators with multi-year contract capacity.
For Market Incumbents: Build regulatory certification moats by securing parallel FDA 510(k), EU MDR, and NMPA registrations for medical laser crystal formulations before REACH dopant restrictions extend qualification timelines. Add ceramic matrix composite capacity in Japan's Kanto corridor to capture METI hydrogen roadmap demand for fuel cell welding applications. Backward integration into Australian ytterbium mining ventures defends against Chinese export license volatility. For New Entrants and Emerging Players: India's PLI-subsidized electronics manufacturing zones represent the most penetrable entry point for laser material blending and finishing operations, with semiconductor packaging fabs in Gyeonggi Province offering secondary white-space for UV-grade fused silica distribution. Target autonomous beam steering integration in EU industrial installations through adaptive coating technologies for MEMS mirror hybridization. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized ceramic substrate manufacturers with captive medical-grade certifications and direct rare earth offtake relationships. Long-term viability over a five-to-ten-year window rests on regulatory qualification depth rather than commodity scale. Watch for divergence between FDA laser product classification rules and EU AI Act risk frameworks as the inflection signal for autonomous beam steering material specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Mining | Direct Australian and Canadian ytterbium offtakes secure supply assurance for defense contractors ahead of Chinese export volatility. |
| Medical-Grade Certification Investment | Parallel FDA, EU MDR, and NMPA registrations compress competitor entry timelines for surgical laser crystal supply chains. |
| Ceramic Matrix Composite Capacity Expansion | Japanese automotive battery manufacturers are qualifying hybrid alumina-silicon carbide substrates for gigawatt-class welding stations. |
| Long-Term Supply Agreement Structuring | Multi-year ytterbium feedstock contracts with IPG Photonics and Trumpf displace spot-market purchasing in North American defense programs. |
| Geographic Expansion into Subsidized Jurisdictions | India's PLI scheme for electronics creates first-mover openings for local laser material blending and finishing operations. |
Research Methodology
Cross-validation between primary interviews with fiber laser OEM procurement directors, ceramic substrate plant managers, rare earth processing executives, and medical device regulatory affairs leads anchors the qualitative findings against secondary validation from SEC 10-K filings, ECHA substance restriction updates, NMPA registration databases, and customs/trade flow records. Bottom-up demand modeling across material type, laser technology, and end-use industry segments triangulates with top-down market sizing from producer capacity disclosures.
Calibration against historical capacity utilization rates and qualification timeline data from German and Chinese ceramic substrate producers shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include material grade tier, laser technology architecture, application thermal load requirement, and regional regulatory cluster. CAGRs derive from installed base replacement cycles, power scaling adoption curves, and medical device traceability mandate implementation pacing.
Practitioners should monitor REACH substance of very high concern listing expansions, Chinese rare earth export license review frequency, and EU AI Act risk framework finalization for early signals of forecast revision triggers. Material shifts in ytterbium processing capacity geography or medical-grade certification requirement harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Air Bearing Spindle Market
Industrial Equipment
Equipment Cases Market
Industrial Equipment
Grading and Batching Systems Market
Industrial Equipment
Precision Dispensing Accessories Market
Industrial Equipment
Global Ultrasonic Cleaning Market
Industrial Equipment
Snowrator Market
Industrial Equipment
Floor Scales Market
Industrial Equipment
Laser Marking Equipment Market
Industrial Equipment
Industrial Polishing Machine Market
Industrial Equipment
Fiber Laser Market
Industrial Equipment
Global Dosing Systems Market
Industrial Equipment
Seal Inspection Equipment Market
Industrial Equipment
PCB Punching Machine Market
Industrial Equipment
Fusion Splicer Market
Industrial Equipment
Battery Power Tools Market
Industrial Equipment
Industrial I/O Modules Market