
 Nanopatterning Market | 2026-2036
Nanopatterning Market Size, Share, and Industry Trends Forecast 2026-2036
Nanopatterning Market Outlook
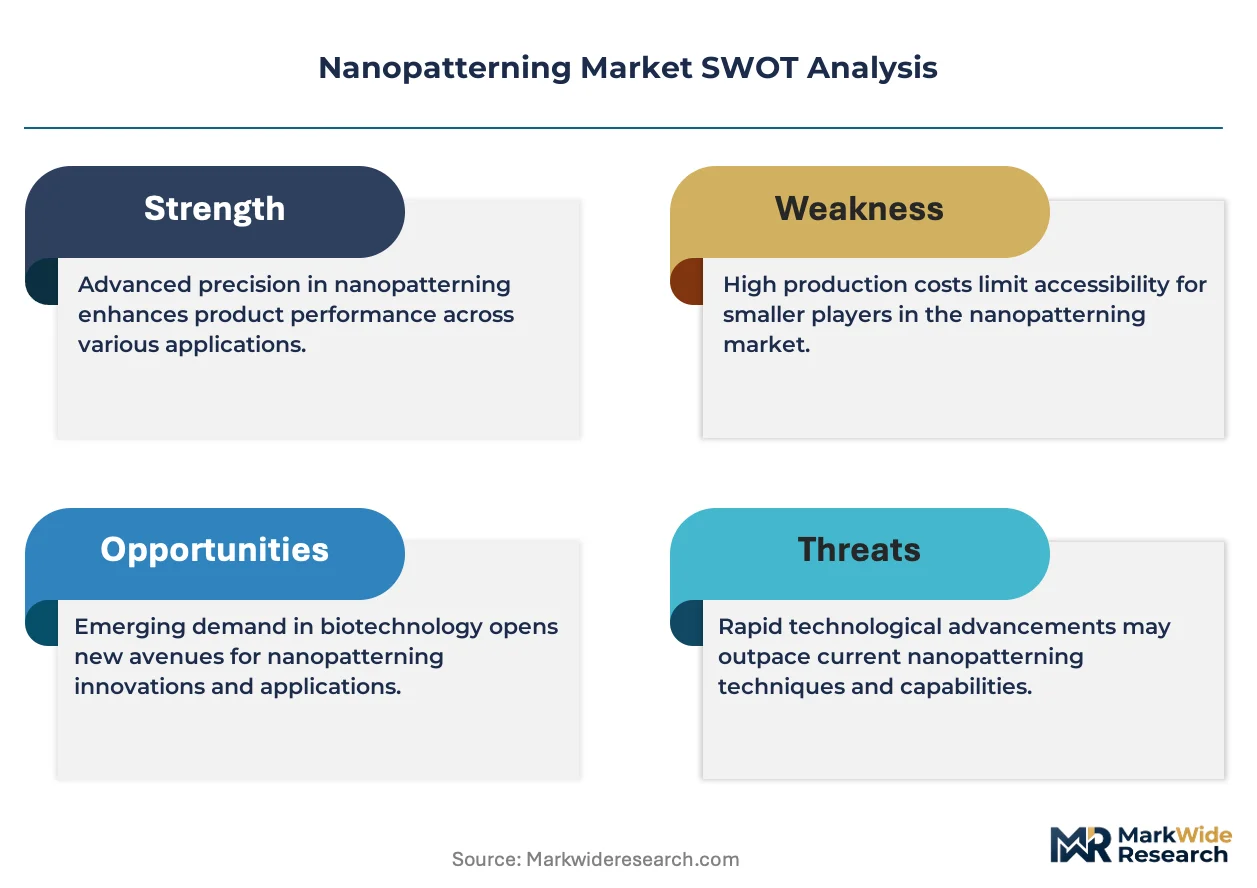
Modular tool configurations are recalibrating procurement decisions across the Nanopatterning Market. EV Group leverages its dominance in wafer bonding and nanoimprint systems to anchor European research fabs. Canon Inc. competes through integrated lithography-metrology bundles that extend its footprint in Asian semiconductor foundries. SUSS MicroTec SE specializes in mask aligner and bonding equipment, occupying a distinct niche in compound semiconductor processing.
Nanopatterning encompasses the fabrication of structures with feature sizes below 100 nanometers through directed energy or mechanical stamping processes, typically achieving resolutions of 10-50 nm using ultraviolet light, electron beams, or thermoplastic embossing. The technique enables precise surface engineering for photonic bandgap materials, sub-wavelength optical elements, and high-density interconnect architectures. Photolithography and electron beam lithography command the largest installed base, though nanoimprint lithography is capturing margin pools in display and memory applications where throughput economics favor stamp-based replication. Electron beam systems sustain premium positioning in photomask writing and prototyping, while femtosecond laser approaches are gaining traction in glass and sapphire direct structuring for sensors and optical devices.
The US EPA regulates perfluorinated compound emissions from lithography processes, pushing equipment makers toward closed-loop chemical recovery designs. The EU REACH framework restricts certain photoresist polymers and etchant chemistries, compelling material suppliers to reformulate coatings and semiconductor-grade resists. Japan's METI coordinates national nanomanufacturing roadmaps that align EV Group and Canon Inc. R&D priorities with domestic semiconductor reshoring targets. Stakeholders must monitor evolving chemical substance restrictions and foundry localization policies to calibrate capacity investments and regional service footprints.
Market Dynamics
Semiconductor foundries in Taiwan and South Korea are consolidating nanoimprint lithography procurement around multi-tool cluster contracts, compressing vendor margins while locking in decade-long service agreements.
Growth Catalysts
- Sub-7nm Node Migration:Advanced logic and memory fabs require high-resolution patterning for gate-all-around transistors and 3D NAND stacks, pulling nanoimprint systems into high-volume manufacturing lines.
- EU REACH Chemical Reformulation:Restrictions on perfluorinated photoresist components are accelerating closed-loop solvent recovery adoption, creating upgrade cycles for existing installed base equipment.
- Photonics Packaging Demand:Silicon photonics for data centers and telecom requires sub-wavelength grating couplers, driving electron beam direct-write orders from compound semiconductor foundries.
Market Restraints
- High-Purity Gas Supply Concentration:Specialty fluorinated gases for deep-UV lithography originate from a concentrated supplier base in Japan and Germany, exposing fabs to price volatility and allocation risk.
- Electron Beam Throughput Ceiling:Serial writing architectures impose fundamental speed limitations versus parallel optical systems, restricting e-beam to mask-making and prototyping despite superior resolution.
- EPA Emissions Compliance Burden:US fabs face escalating monitoring and abatement costs for lithography process exhaust, diverting capital from capacity expansion.
Strategic Opportunities
- India Semiconductor Mission:Domestic fab incentives and design-linked subsidy schemes are attracting lithography equipment vendors to establish service hubs in Gujarat and Karnataka.
- Femtosecond Laser Glass Structuring:Direct laser writing in sapphire and fused silica for AR/VR waveguides and automotive lidar represents an emerging application vector outside traditional semiconductor processing.
- AI-Assisted Process Control:Machine learning overlay correction and predictive maintenance modules are unifying metrology and lithography workflows, opening software and service revenue streams.
Industry Challenges
- Specialized Technician Scarcity:Vacuum systems, electron optics, and resist chemistry expertise rarely coexist in single candidates, extending hiring timelines for field service and applications engineering roles.
- Multi-Generational Tool Integration:Legacy 193nm immersion systems must interoperate with EUV and nanoimprint modules in hybrid production flows, complicating fab automation and wafer tracking.
- IP Licensing Fragmentation:Nanoimprint template replication patents span university, corporate, and national lab portfolios, creating negotiation complexity for equipment makers entering new regional markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanopatterning Market |
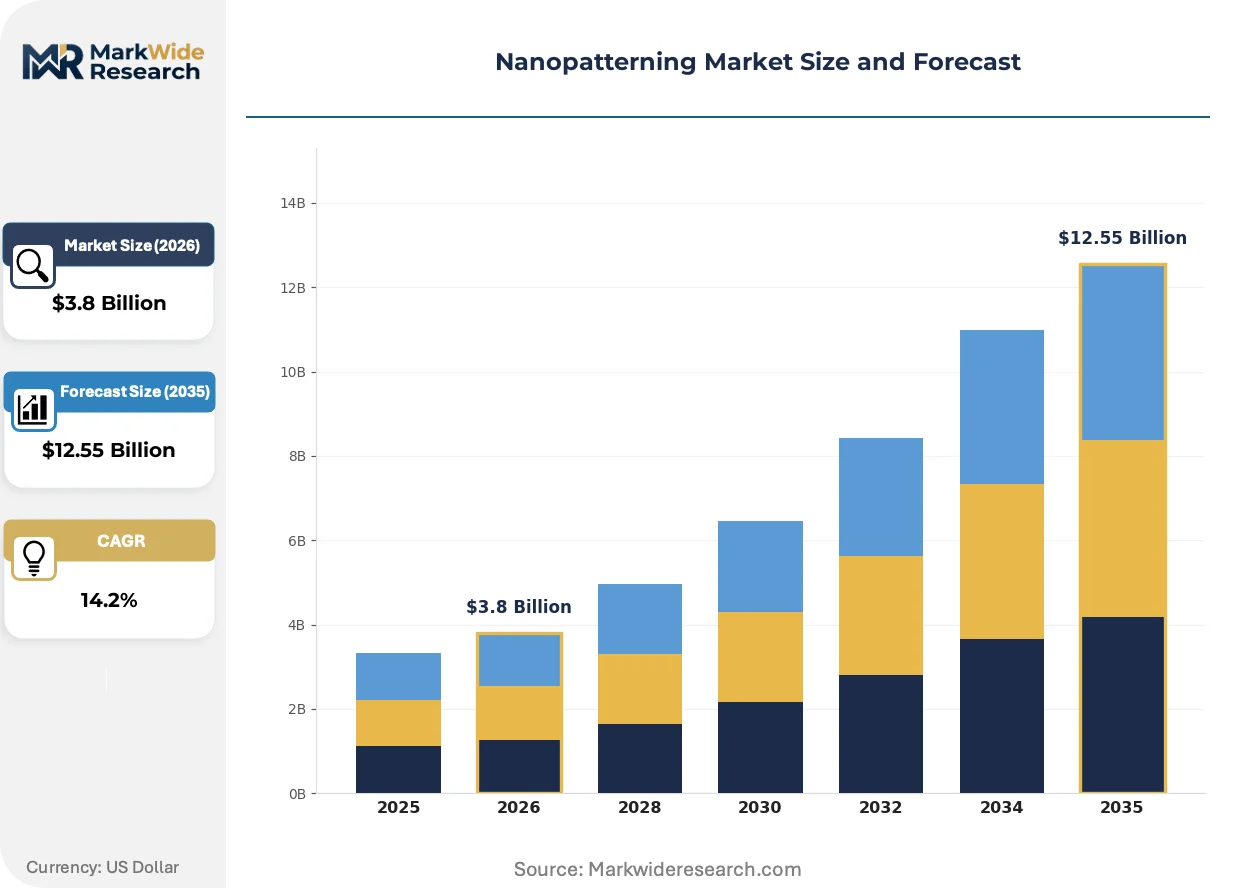
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Photolithography, Electron Beam Lithography, Nanoimprint Lithography, Femtosecond Laser End User: Electronics, Healthcare, Automotive, Defense Application: Sensors, Circuit Boards, Coatings, Optical Devices Material: Polymers, Metals, Semiconductors, Glass |
| Companies Covered | EV Group, Canon Inc., Nanoscribe GmbH, AMO GmbH, Micro Resist Technology GmbH, Toppan Printing Co., Ltd., Raith GmbH, Obducat AB, SUSS MicroTec SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanopatterning Market Strategic Shifts
Patterning workflows are converging toward unified metrology-lithography platforms that compress cycle times and reduce yield excursion detection latency. Equipment vendors and foundry customers are co-developing closed-loop control architectures.
Hybrid nanoimprint-optical systems are unifying mechanical stamping with in-situ overlay measurement, enabling real-time template-wafer alignment correction. Display panel manufacturers in South Korea are adopting these configurations for micro-LED color conversion layers. The technology is unifying what were previously separate imprint and inspection process steps, reducing capital footprint per thousand wafers.
Japan's METI has coordinated national roadmaps that align domestic equipment makers with semiconductor reshoring targets, channeling R&D subsidies toward 450mm wafer handling and extreme-UV resist development. Japanese fabs are accelerating qualification of domestically sourced materials to reduce import dependency. The policy most directly affects memory and logic producers in Kyushu and Hiroshima, which are restructuring supply contracts to prioritize local chemical and substrate vendors.
Equipment-as-a-service contracts are displacing traditional capital purchase models for mid-size research fabs and compound semiconductor foundries. Vendors retain ownership and bundle consumables, maintenance, and upgrades into per-wafer pricing. This shift is most visible among European photonics clusters and US university nanofabrication facilities facing constrained endowment capital.
Nanopatterning Market Segmentation
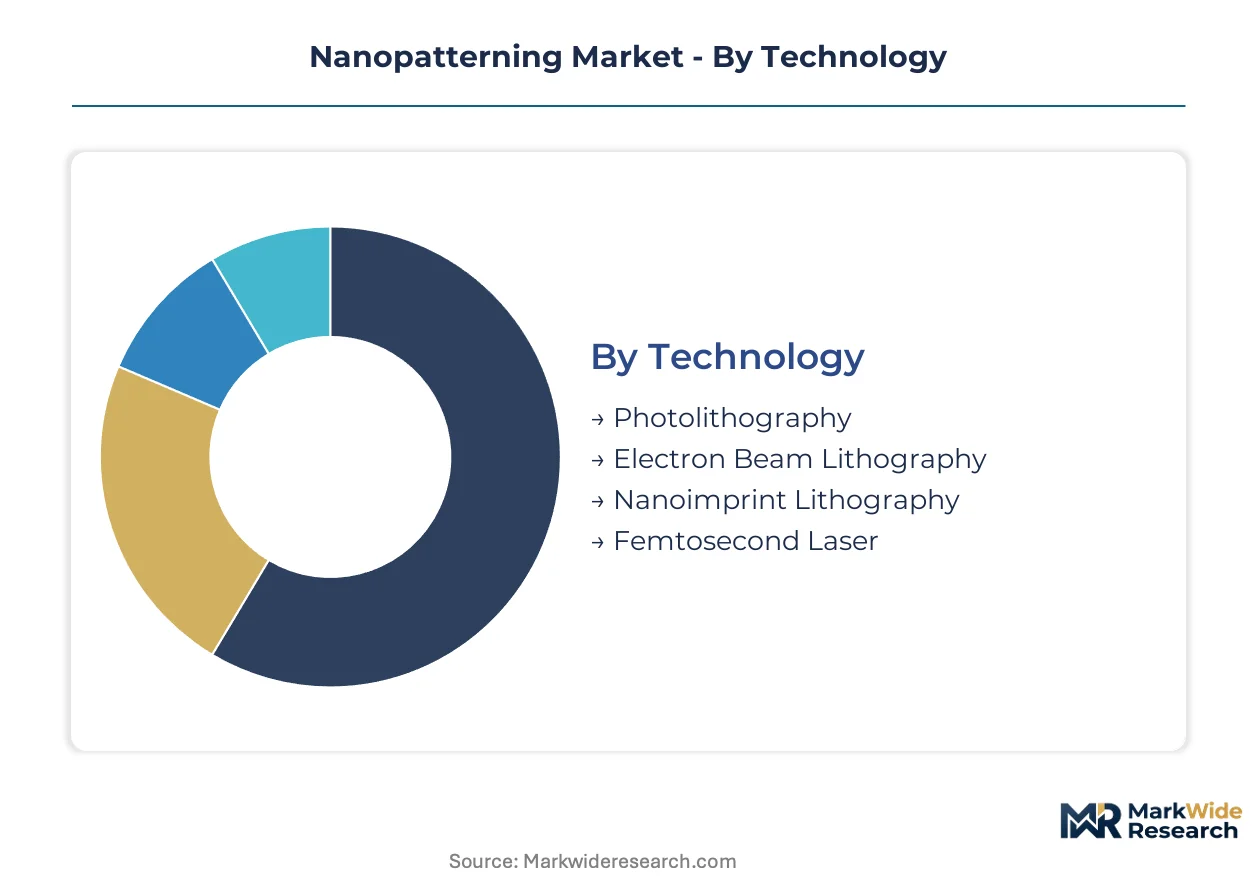
Nanopatterning equipment selection hinges on resolution requirements, throughput economics, and regulatory compliance burdens that vary sharply across technology generations. Segmentation reveals where capital concentrates and which process flows face the steepest certification barriers.
Technology:
EPA emissions rules and EU REACH substance restrictions apply unevenly across patterning modalities, with chemical-intensive optical systems facing heavier compliance loads than dry mechanical processes.
- Photolithography:Deep-UV and immersion systems dominate high-volume logic and memory fabrication, utilizing chemically amplified resists now targeted by perfluorinated compound regulations. Taiwan Semiconductor Manufacturing and Samsung Electronics anchor demand for multi-patterning-capable 193nm systems as they scale below 5nm effective resolution.
- Electron Beam Lithography:Maskless direct-write systems achieve sub-10nm resolution through serial electron exposure, sustaining premium positioning in photomask production and research prototyping despite throughput limitations. Japanese photomask shops and European research consortia absorb the majority of new system placements.
- Nanoimprint Lithography:Thermoplastic embossing avoids vacuum UV chemistry entirely, appealing to display manufacturers facing REACH photoresist restrictions. South Korean panel producers drive adoption for micro-LED pixel definition layers.
- Femtosecond Laser:Ultrafast pulse ablation enables direct glass and sapphire structuring without photomasks or cleanroom processing, gaining traction in AR waveguide and automotive lidar sensor fabrication.
Leading the category by volume: Photolithography. Expanding most quickly: Nanoimprint Lithography.
End User:
Customer procurement sophistication spans captive semiconductor fabs with decade-long equipment roadmaps to fragmented research facilities purchasing through equipment-as-a-service contracts.
- Electronics:Integrated device manufacturers and foundries command the largest capital allocation, with sub-7nm logic and 3D NAND flash driving multi-billion-dollar lithography clusters. Taiwan, South Korea, and Japan concentrate the highest fab density.
- Healthcare:Diagnostic biosensors and implantable device manufacturers utilize soft lithography and imprint methods for microfluidic channel definition, with FDA device center oversight shaping material biocompatibility requirements.
- Automotive:Lidar emitter arrays and interior touch surfaces employ laser direct structuring and roll-to-roll nanoimprint, with German and Japanese tier-one suppliers qualifying processes for AEC-Q100 reliability standards.
- Defense:Secure foundries and national laboratories prioritize electron beam systems for radiation-hardened ASIC prototyping, with ITAR export controls constraining vendor selection and service access.
Electronics captures the dominant revenue share. Healthcare demonstrates the steepest expansion trajectory among mid-size capital purchasers.
Application:
Patterning precision requirements scale with feature density, separating commodity interconnect layers from sub-wavelength optical structures demanding sub-50nm overlay accuracy.
- Sensors:MEMS microphones, pressure transducers, and gas sensors combine bulk silicon etching with surface nanopatterning for sensitivity enhancement. Automotive and consumer electronics fabs in Japan and Germany drive qualified process adoption.
- Circuit Boards:High-density interconnect substrates for advanced packaging require laser-drilled microvias and lithographically defined redistribution layers, with substrate manufacturers in Taiwan and South Korea expanding captive patterning capacity.
- Optical Devices:AR/VR waveguides, telecom filters, and laser resonators demand sub-wavelength grating structures with strict period uniformity, pulling specialized imprint and interference lithography systems into photonics foundries.
- Coatings:Anti-reflective and self-cleaning surfaces utilize moth-eye nanostructures replicated through roll-to-roll embossing, with solar panel and display cover glass manufacturers qualifying high-throughput processes.
Sensors anchor the installed equipment base. Optical Devices are climbing the fastest as silicon photonics packaging scales.
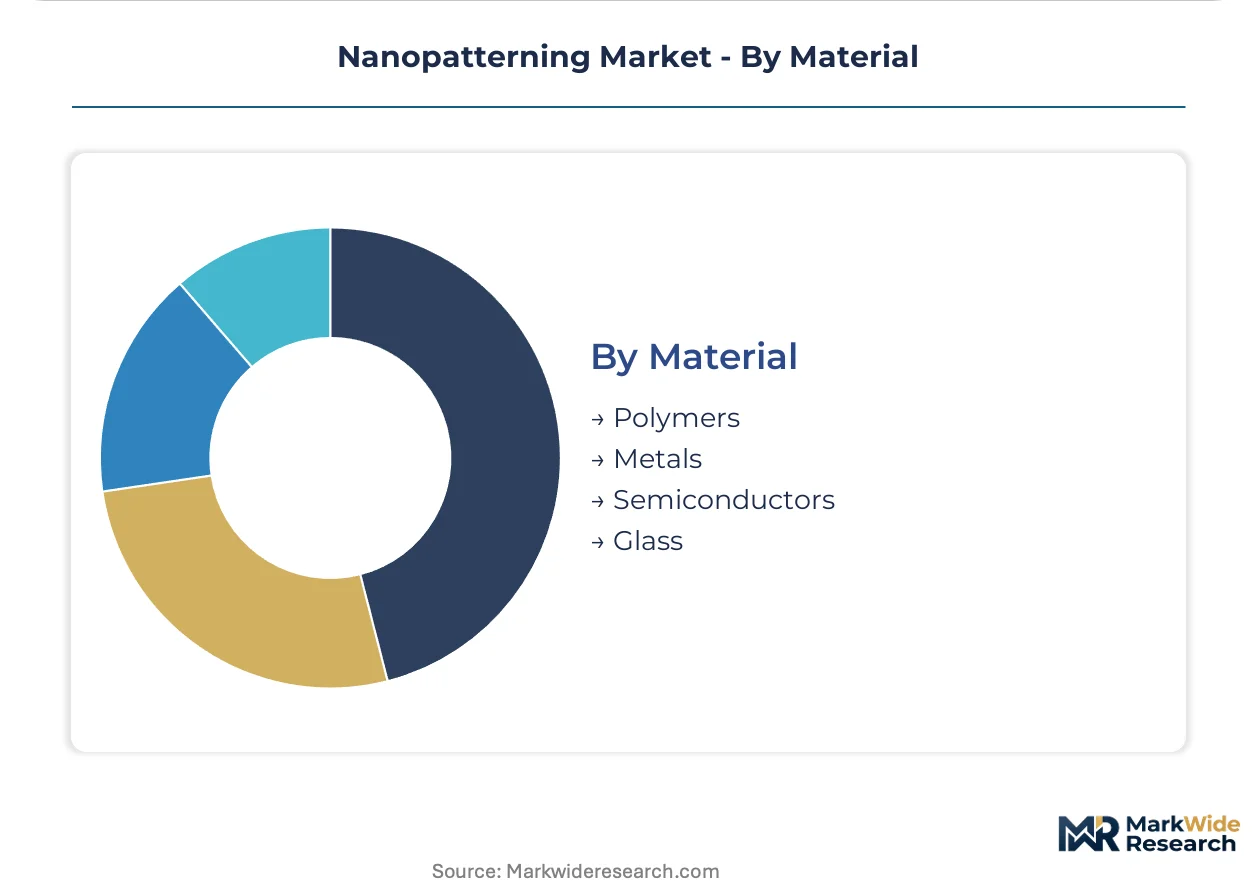
Material:
Substrate hardness and thermal stability dictate compatible patterning modalities, with brittle materials requiring non-contact optical approaches and ductile layers accommodating mechanical embossing.
- Semiconductors:Silicon wafers and compound semiconductor substrates receive the majority of capital equipment deployment, with epitaxial layer patterning for power electronics and RF devices expanding beyond traditional CMOS logic.
- Polymers:Flexible substrates for wearable electronics and disposable diagnostics enable low-cost roll-to-roll nanoimprint, with thermoplastic polyurethane and cyclic olefin copolymers dominating medical and consumer applications.
- Metals:Plasmonic structures and transparent conductive meshes utilize subtractive patterning or template-directed electrodeposition, with silver nanowire touch sensors and electromagnetic shielding films driving precision requirements.
- Glass:Fused silica and sapphire substrates for photonics and harsh-environment sensors require femtosecond laser or ion beam patterning, with German and Japanese specialty glass manufacturers qualifying direct-write processes.
Semiconductors lead by cumulative equipment investment. Glass substrates are gaining share fastest in non-traditional semiconductor applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment production concentrates in Germany and Japan while consumption tilts toward East Asian fabrication clusters. Taiwan and South Korea absorb the majority of nanoimprint lithography system shipments. The United States maintains captive demand through defense-secure foundries and national laboratory procurement.
United States
Defense-secure foundries and national laboratories sustain electron beam lithography demand for radiation-hardened ASIC prototyping. EPA emissions regulations push equipment buyers toward closed-loop chemical recovery architectures. Greater Boston and Silicon Valley host the densest concentrations of university nanofabrication facilities adopting equipment-as-a-service contracts.
Germany
Automotive lidar and industrial sensor manufacturers drive femtosecond laser system adoption for glass direct structuring. EU REACH substance restrictions compel photoresist reformulation across Bavarian and Saxon research consortia. The Eindhoven-Aachen-Dresden corridor anchors European photonics packaging demand for nanoimprint equipment.
Japan
Domestic memory and logic producers in Kyushu and Hiroshima accelerate qualification of locally sourced materials under METI-coordinated reshoring roadmaps. Photomask shops sustain premium electron beam system placements despite throughput limitations. Canon Inc. and domestic suppliers channel R&D subsidies toward 450mm wafer handling development.
South Korea
Display panel manufacturers adopt hybrid nanoimprint-optical systems for micro-LED color conversion layers at scale. Multi-tool cluster contracts compress vendor margins while locking in decade-long service agreements. Seoul Capital Area and Busan-Ulsan fabs consolidate procurement around integrated lithography-metrology bundles.
Taiwan
Foundry leaders anchor global demand for multi-patterning-capable 193nm immersion systems as they scale below 5nm effective resolution. Sub-7nm node migration pulls nanoimprint systems into high-volume manufacturing lines for gate-all-around transistors. Hsinchu Science Park and Tainan Technology Industrial Park concentrate the highest fab density.
Nanopatterning Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across equipment categories, creating tiered competitive dynamics. The vendor base spans multinational optical systems houses, European research equipment specialists, and Japanese precision machinery groups. Three archetypes dominate: integrated lithography-metrology bundlers, nanoimprint and wafer bonding specialists, and electron beam direct-write purists. Capacity expansion in East Asian service hubs and strategic patent licensing for template replication represent the dominant competitive moves.
Within the European specialist tier, EV Group and SUSS MicroTec SE exemplify focused equipment architects concentrating on wafer bonding, mask alignment, and nanoimprint modalities. Canon Inc. occupies a position among diversified optical conglomerates leveraging integrated system portfolios. These three anchors represent distinct strategic postures: European precision tooling for research and compound semiconductor applications versus Japanese integrated platforms for high-volume foundry deployment.
| Leading Market Players |
|---|
| EV Group |
| Canon Inc. |
| Nanoscribe GmbH |
| AMO GmbH |
| Micro Resist Technology GmbH |
| Toppan Printing Co., Ltd. |
| Raith GmbH |
| Obducat AB |
| SUSS MicroTec SE |
| Others |
Value Chain & Pricing Dynamics
Specialty fluorinated gas price indices cascade through nanopatterning equipment supply chains, compressing margins for deep-UV lithography system vendors while amplifying pricing power for dry mechanical patterning alternatives exempt from perfluorinated compound regulations.
Pricing Analysis
Cost-down pressure on standard-grade photolithography systems accelerates because multi-tool cluster contracts in Taiwan and South Korea consolidate procurement leverage around integrated lithography-metrology bundles. Three-tier pricing structure across premium electron-beam direct-write, standard immersion optical, and economy nanoimprint configurations differentiates primarily on resolution specification and after-sales service bundling. Foundry buyers exhibit highest price sensitivity for high-volume production equipment, while defense-secure foundries and national laboratories tolerate premium positioning for ITAR-compliant electron beam systems.
Supply Chain Analysis
ISO 14644 cleanroom certification and SEMI S2 safety qualification gate equipment component sourcing, extending lead times for vacuum pumps and electron optics assemblies. Manufacturing concentrates in Germany, Japan, and the United States for precision motion stages and ion beam columns. Deep-UV laser light sources and specialty fluorinated gases draw from concentrated Japanese and German supplier bases. Single-source vulnerability for 193nm excimer laser tubes exposes equipment makers to allocation risk. Distribution runs through direct sales forces for captive semiconductor fabs and regional service partners for research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized technician scarcity across vacuum systems, electron optics, and resist chemistry domains props pricing for field service contracts and applications engineering support, constraining capacity expansion regardless of equipment order backlogs.
For Market Incumbents: Lock in decade-long service agreements with East Asian foundry clusters before emerging femtosecond laser direct-write vendors qualify for micro-LED and AR waveguide applications. Deepen backward integration into template replication intellectual property to deflect patent licensing fragmentation risks. Prioritize closed-loop chemical recovery system upgrades for the US installed base facing escalating EPA emissions monitoring burdens. For New Entrants and Emerging Players: Femtosecond laser glass structuring capabilities offer a technology-first wedge into automotive lidar and AR/VR waveguide fabrication outside traditional semiconductor cleanroom infrastructure. Target European photonics clusters in the Eindhoven-Aachen-Dresden corridor adopting equipment-as-a-service contracts to bypass capital purchase barriers. Lead with per-wafer pricing models bundling maintenance and consumables to match constrained endowment capital at university nanofabrication facilities. For Investors and Strategic Acquirers: The window for entry favors equipment-as-a-service platform operators with captive installed bases in compound semiconductor and photonics applications. Long-term viability hinges on software and service revenue streams from AI-assisted process control modules unifying metrology and lithography workflows. Watch for inflection in India Semiconductor Mission fab construction timelines as a signal for lithography equipment vendor service hub expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Template Replication Patent Licensing | Secures freedom-to-operate for nanoimprint equipment makers entering South Korean display panel markets. |
| Closed-Loop Chemical Recovery System Deployment | Enables US fab compliance with EPA perfluorinated compound emissions regulations without capacity interruption. |
| Equipment-as-a-Service Contract Expansion | Matches European photonics cluster budget constraints while capturing recurring revenue from consumables bundling. |
| Femtosecond Laser Direct-Write Qualification | Opens non-semiconductor revenue streams in AR waveguide and automotive lidar sensor fabrication. |
| AI-Assisted Process Control Module Integration | Unifies metrology and lithography workflows for Taiwan foundry customers compressing yield excursion detection latency. |
Study Parameters
Document review covered SEC equipment vendor filings, SEMI industry association capacity databases, and EPA emissions compliance records, complemented by interviews with lithography tool engineering directors, foundry procurement leads, photoresist formulation chemists, and vacuum system field service managers. Secondary validation drew from patent assignment databases, customs trade data for fluorinated gas imports, and national nanomanufacturing roadmap publications. Bottom-up equipment shipment tallies and top-down fab capex allocation estimates were cross-referenced for triangulation.
Historical shipment patterns were cross-referenced against panel input from equipment vendor sales executives and foundry planning officers. Segmentation dimensions modeled include patterning modality, end-user industry, application precision requirement, and substrate material hardness. CAGRs were derived from installed base expansion rates and replacement cycle timing across the projection horizon. Forecast inputs incorporated EU REACH substance restriction timelines and Japan METI reshoring subsidy qualification criteria.
Several conditions sit outside the modeled scope, including unannounced merger activity among specialty gas suppliers and abrupt shifts in US export control classifications for electron beam systems. Forecasts reflect documented assumptions regarding node migration timelines and foundry localization policy durability. A model refresh is warranted upon material change in EPA emissions rule enforcement intensity or India domestic fab incentive disbursement schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Edge Computing Market
Emerging and Next Generation Technologies
Swarm Computing Market
Emerging and Next Generation Technologies
Global Metamaterials Technologies Market
Emerging and Next Generation Technologies
Deep Tech Market
Emerging and Next Generation Technologies
Next Gen TV (ATSC TV) Market
Emerging and Next Generation Technologies
Mexico Cleanroom Technology Market
Emerging and Next Generation Technologies
Global Flexible and Printed Electronics Market
Emerging and Next Generation Technologies
Terahertz Radiation Devices Market
Emerging and Next Generation Technologies
Flexible PV Cell Market
Emerging and Next Generation Technologies
Global Metamaterial Market
Emerging and Next Generation Technologies
Ultra-Fine Ath Market
Emerging and Next Generation Technologies
3D Xpoint Technology Market
Emerging and Next Generation Technologies
Next-Generation Transistors Market
Emerging and Next Generation Technologies
Global Hybrid Intelligence Market
Emerging and Next Generation Technologies
Flexible Electronics Market
Emerging and Next Generation Technologies
Medical Terahertz Technology Market