
 Global Flexible Electronics and Circuit Market | 2026-2036
Global Flexible Electronics and Circuit Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flexible Electronics and Circuit Market Analysis
ISO 13485 qualification for medical-grade flexible substrates is bifurcating the supplier landscape into certified and non-certified tiers. Samsung Electronics Co Ltd leverages its captive OLED fab network to sustain vertical control over flexible display output. DuPont de Nemours Inc. anchors the polyimide substrate segment through proprietary Kapton formulations, while PragmatIC Semiconductor differentiates by specializing in ultra-low-cost flexible integrated circuits for disposable applications.
Flexible electronics and circuits comprise electrically functional systems fabricated on bendable polymer substrates, typically polyimide or polyethylene naphthalate, using thin-film transistor processes that enable curvature radii below 5 millimeters without performance degradation. These systems serve as interconnect and active component platforms for applications requiring mechanical compliance, weight reduction, or conformal mounting on non-planar surfaces. Displays technology leads in value contribution due to smartphone foldable panel penetration, while printed electronics represents the fastest-expanding segment as roll-to-roll gravure and inkjet deposition methods mature. Sensors application commands premium pricing in healthcare wearables, whereas RFID technology occupies a volume-driven position in logistics and retail authentication.
FDA device classification rules for flexible biosensors, REACH substance restrictions on halogenated flame retardants, and EU Green Deal circularity mandates collectively determine which material sets gain commercial traction across consumer and medical verticals. The EPA's emerging framework on per- and polyfluoroalkyl substances threatens incumbent fluoropolymer barrier films, accelerating substitution toward silicone and parylene encapsulants. Stakeholders must monitor regulatory divergence between the US and European chemical safety regimes when qualifying next-generation substrate and encapsulation platforms.
Market Dynamics
Display foundry consolidation in South Korea is concentrating substrate procurement power among vertically integrated OLED manufacturers, forcing mid-tier flexible circuit suppliers to absorb margin compression or exit medical-grade qualification tiers entirely.
Growth Catalysts
- Foldable smartphone panel penetration:Samsung Display and BOE Technology are expanding polyimide substrate orders for hinge-compatible OLED stacks, pulling through copper-nanowire transparent conductor demand.
- REACH substance restrictions:ECHA's tightening halogenated flame retardant limits are accelerating silicone encapsulant adoption in EU-bound medical wearables, creating first-mover advantage for qualified material suppliers.
- Roll-to-roll gravure maturation:Printed electronics manufacturers in Germany and Japan are achieving micron-scale registration accuracy on polyethylene naphthalate webs, unlocking RFID antenna volume economics previously captive to etched-copper processes.
Market Restraints
- Fluoropolymer barrier film dependency:EPA's emerging PFAS framework threatens incumbent encapsulation materials, forcing costly reformulation cycles before silicone and parylene alternatives achieve equivalent moisture barrier performance.
- Polyimide precursor concentration:Kapton and UPIlex formulations remain concentrated among Japanese and US chemical suppliers, exposing downstream converters to feedstock allocation risk during display fab capacity ramps.
- Thermal management limitations:Flexible substrates' low glass-transition temperatures constrain power handling in 5G millimeter-wave antenna modules, capping addressable market share in high-frequency consumer electronics.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Modified incentive structures for component sourcing are attracting flexible circuit substrate packaging investments to Gujarat and Tamil Nadu clusters, creating alternative supply geography to East Asian concentration.
- Wearable biosensor convergence:Integration of glucose monitoring and cardiac rhythm detection on single flexible patches is opening reimbursement pathways under Germany's DiGA framework and Japan's Sakigake designation.
- EU Green Deal circularity mandates:Design-for-recycling requirements are favoring soluble conductive inks and biodegradable substrate alternatives, positioning gravure-printed silver-nanowire circuits ahead of subtractive etching processes.
Industry Challenges
- ISO 13485 certification timelines:Medical-grade substrate qualification requires eighteen-to-twenty-four-month validation cycles, locking working capital and creating entry barriers for new polyimide film entrants.
- Thin-film transistor process integration:Hybrid integration of organic and oxide semiconductors on identical flexible backplanes demands rare cross-functional expertise spanning materials science, device physics, and roll-to-roll manufacturing engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flexible Electronics and Circuit Market |
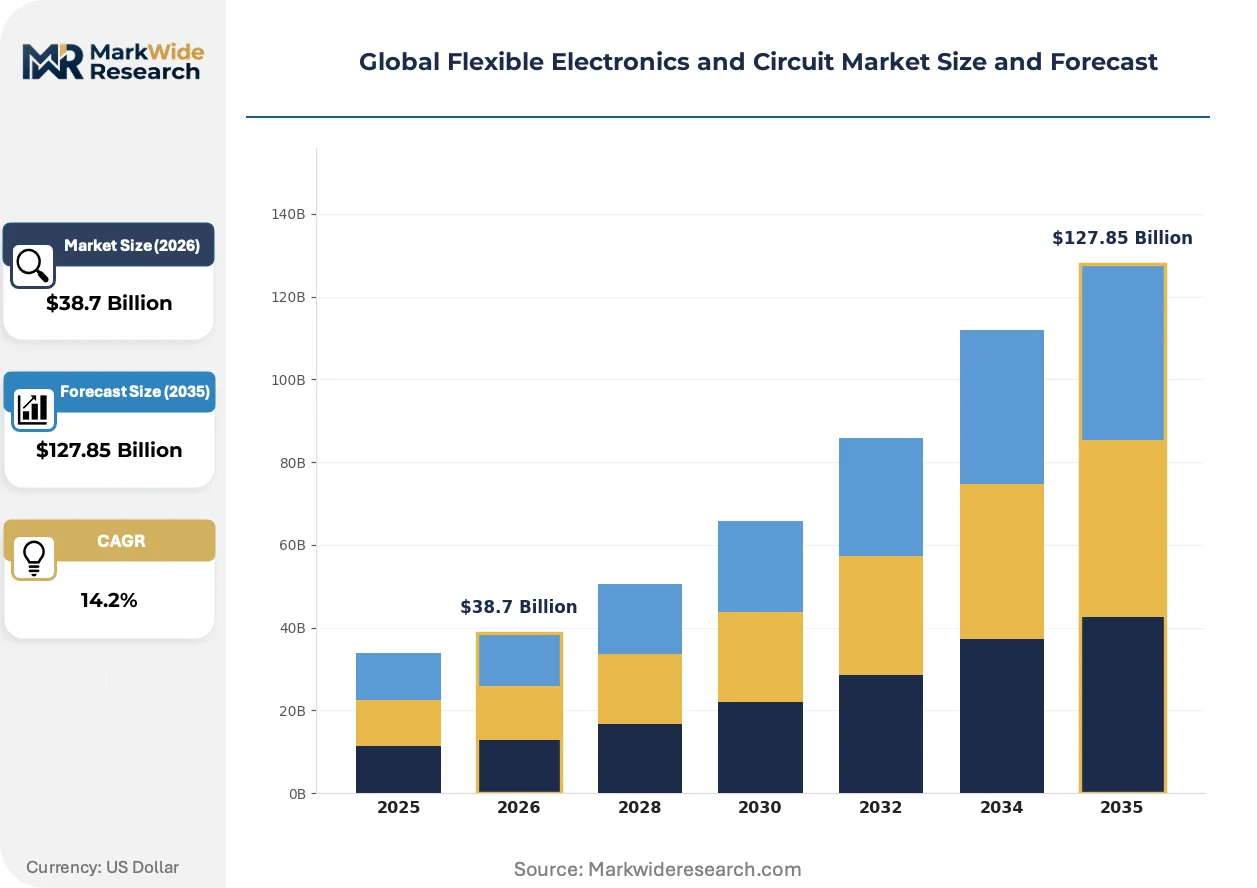
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Displays, Sensors, Batteries, Antennas Technology: OLED, Printed Electronics, RFID, Photovoltaics Application: Consumer Electronics, Automotive, Healthcare, Wearables End User: Manufacturers, OEMs, Retailers, Research Institutions |
| Companies Covered | Samsung Electronics Co Ltd, Panasonic Corporation, The 3M Company, LG Display Co Ltd, BOE Technology Group Co Ltd, AU Optronics Corporation, DuPont de Nemours Inc., PragmatIC Semiconductor, Konica Minolta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flexible Electronics and Circuit Market Emerging Trajectories
Micro-LED transfer processes and hybrid bonding techniques are compressing pixel pitch limits while straining legacy substrate thermal expansion specifications, forcing simultaneous innovation across materials, equipment, and inspection protocols.
Silver-nanowire transparent conductors are displacing indium tin oxide in flexible touch sensor stacks. Automotive interior designers at Hyundai and BMW are specifying curved dashboard interfaces exceeding five-hundred-millimeter bend radii. This conductor transition is displacing vacuum sputtering capital expenditure with slot-die coating equipment, reallocating competitive advantage toward chemical formulation specialists.
EU F-Gas Regulation phase-down schedules are restricting hydrofluorocarbon etching chemistries used in polyimide substrate surface activation. German and French converter operations are retrofitting plasma treatment lines to accommodate fluorine-free alternatives. Medical wearable manufacturers sourcing from EU-based substrate finishers face six-to-nine-month process requalification timelines.
Hospital procurement consortia are consolidating flexible biosensor vendor panels from twelve to three approved suppliers per therapeutic category. Medtronic and Philips are negotiating multi-year substrate supply agreements with volume-commitment clauses. This concentration is most visible in Dutch and Danish healthcare systems where centralized purchasing authorities enforce standardization.
Global Flexible Electronics and Circuit Market Segmentation
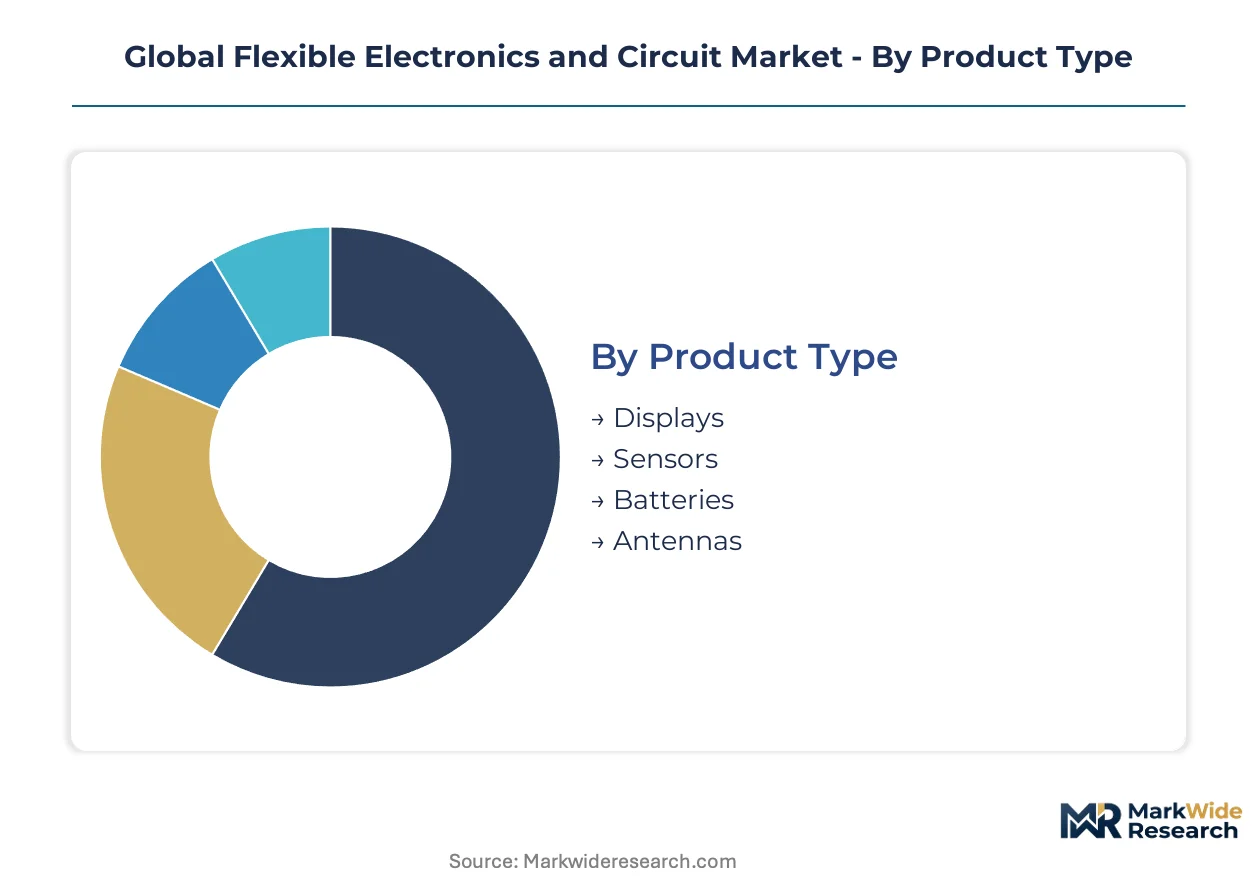
Segment boundaries in flexible electronics shift as roll-to-roll manufacturing matures and substrate materials diversify. Understanding where substitution pressure concentrates helps suppliers allocate qualification resources and anticipate margin compression.
Product Type:
Substitute threats vary sharply across product categories, with rigid alternatives and emerging form factors pressuring certain segments more than others.
- Displays:Foldable OLED stacks on polyimide substrates enable curvature radii below 2 millimeters. Samsung Display and BOE Technology are expanding hinge-compatible panel procurement, pulling through copper-nanowire transparent conductor demand from South Korean and Chinese component suppliers.
- Sensors:Flexible biosensor patches integrate glucose monitoring and cardiac rhythm detection on single substrates. REACH compliance requirements and FDA device classification rules are tightening material qualification timelines for EU and US-bound medical wearables.
- Batteries:Solid-state thin-film cells on polymer substrates target micro-power applications in disposable medical patches.
- Antennas:5G millimeter-wave modules face thermal management constraints from low glass-transition temperature substrates, capping power handling in high-frequency consumer devices.
Displays anchors the volume base while Sensors gains share at the steepest rate.
Technology:
Cost tier differentiation separates premium deposition methods from high-volume printing approaches, with capital intensity determining competitive entry barriers.
- OLED:Vacuum thermal evaporation and inkjet printing of organic emissive layers on flexible backplanes deliver pixel densities exceeding 500 ppi. South Korean display foundries concentrate substrate procurement power, forcing mid-tier suppliers to absorb margin compression or exit medical-grade qualification tiers.
- Printed Electronics:Roll-to-roll gravure and inkjet deposition on polyethylene naphthalate webs achieves micron-scale registration accuracy. German and Japanese manufacturers are unlocking RFID antenna volume economics previously captive to etched-copper processes.
- RFID:Silver-nanowire and conductive ink antennas enable item-level tracking at unit costs below etched-metal alternatives.
- Photovoltaics:Organic and perovskite thin-film cells on flexible substrates target building-integrated and portable power applications.
OLED commands premium pricing while Printed Electronics expands most quickly as gravure registration accuracy improves.
Application:
Customer type fragmentation splits demand between specification-driven automotive procurement and price-sensitive consumer electronics sourcing.
- Consumer Electronics:Smartphone foldable panels and wearable devices drive substrate orders for hinge-compatible form factors. Samsung Electronics leverages captive OLED fab networks to sustain upstream control over flexible display output.
- Automotive:Curved dashboard interfaces exceeding 500-millimeter bend radii are specified by Hyundai and BMW interior designers, displacing vacuum sputtering with slot-die coating equipment.
- Healthcare:Hospital procurement consortia in the Netherlands and Denmark are consolidating flexible biosensor vendor panels from twelve to three approved suppliers per therapeutic category.
- Wearables:Germany's DiGA framework and Japan's Sakigake designation are opening reimbursement pathways for integrated glucose and cardiac monitoring patches.
Consumer Electronics provides the volume foundation while Healthcare climbs the fastest on regulatory tailwinds.
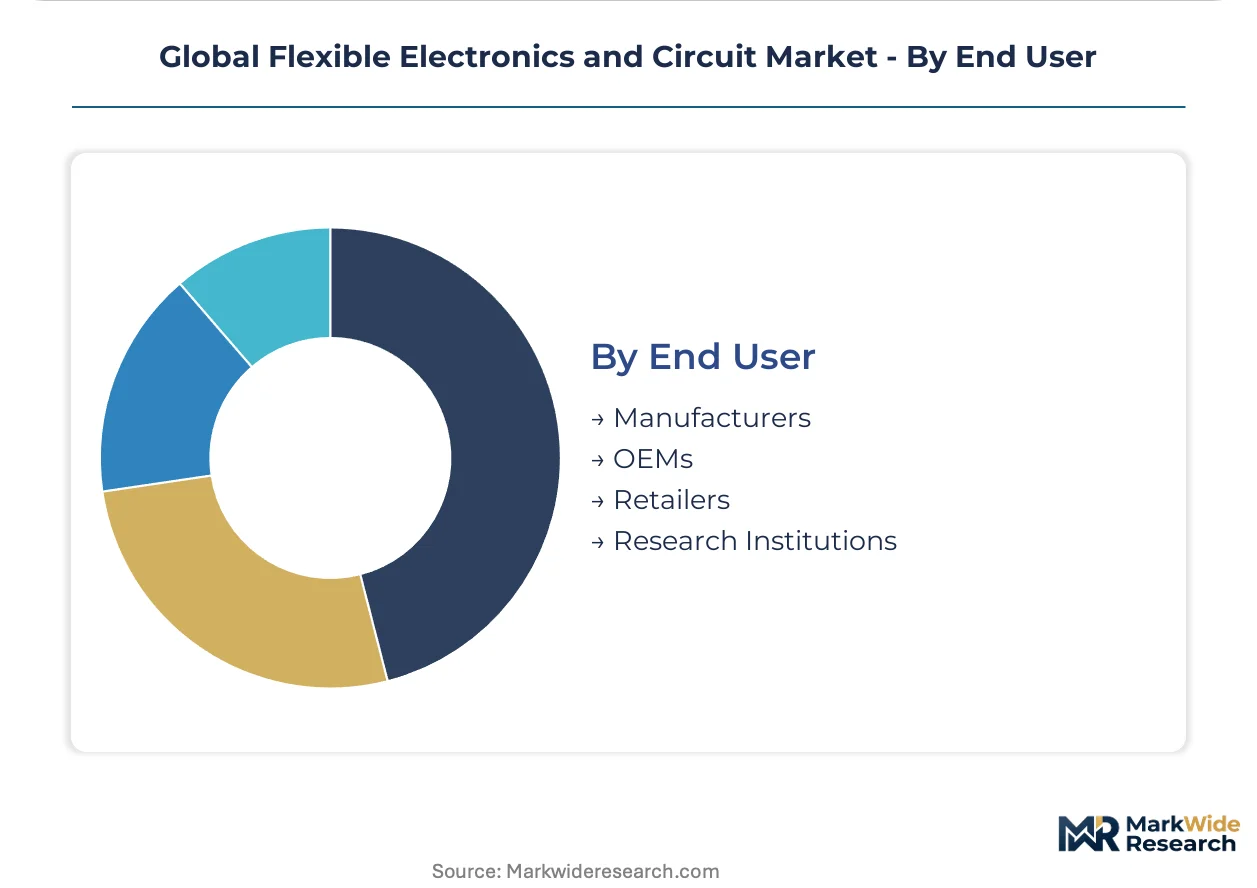
End User:
Supply concentration varies by procurement sophistication, with research institutions demanding customization that manufacturers reject.
- Manufacturers:Display foundries and flexible circuit converters purchase substrate materials in roll quantities. DuPont de Nemours anchors polyimide supply through proprietary Kapton formulations, while PragmatIC Semiconductor targets ultra-low-cost flexible integrated circuits for disposable applications.
- OEMs:Device assemblers specify complete flexible subassemblies including substrate, conductive traces, and encapsulation layers.
- Retailers:Logistics operators deploy RFID-enabled flexible tags for inventory authentication and supply chain visibility.
- Research Institutions:Universities and national laboratories qualify experimental substrate materials and novel deposition chemistries.
Manufacturers dominate procurement volume while Research Institutions drive the steepest technology transfer rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flexible substrate procurement concentrates among vertically integrated display foundries and medical device OEMs with exacting qualification requirements. South Korean and Chinese panel manufacturers anchor volume demand, while German and US healthcare technology firms drive premium-grade specifications.
South Korea
Samsung Display and LG Display dominate foldable OLED substrate procurement, pulling through polyimide film orders at scale. The Ministry of Trade, Industry and Energy enforces K-REACH chemical registration parallel to EU standards. Display manufacturing clusters in Gyeonggi Province and the Seoul Capital Area concentrate copper-nanowire transparent conductor integration for hinge-compatible smartphone panels.
China
BOE Technology expands flexible display capacity for domestic smartphone brands and export markets. The National Medical Products Administration issues device classification guidance for flexible biosensors entering clinical use. Manufacturing concentration in the Yangtze River Delta and Pearl River Delta supports roll-to-roll gravure printing infrastructure for RFID antenna volume production.
United States
Medtronic and Philips negotiate multi-year substrate supply agreements with volume-commitment clauses for cardiac monitoring patches. The FDA maintains device classification rules for flexible biosensors while the EPA advances PFAS framework restrictions on fluoropolymer barrier films. Medical technology procurement concentrates in Minnesota and Massachusetts healthcare manufacturing corridors.
Germany
Continental and BMW specify curved dashboard interfaces exceeding 500-millimeter bend radii for automotive interior applications. The ECHA enforces REACH substance restrictions on halogenated flame retardants, accelerating silicone encapsulant adoption. Printed electronics manufacturing clusters in Baden-Württemberg and Bavaria achieve micron-scale registration accuracy on polyethylene naphthalate webs.
Japan
Panasonic and Konica Minolta supply polyimide precursor formulations and flexible circuit manufacturing equipment. The Ministry of Economy, Trade and Industry coordinates JIS standards alignment with international medical device quality systems. Chemical manufacturing concentration in the Chubu region around Nagoya anchors Kapton and UPIlex feedstock supply to downstream converters.
Global Flexible Electronics and Circuit Market Vendor Landscape
Player mix skews toward vertically integrated display manufacturers and specialty chemical suppliers with captive material formulations. Market structure concentrates substrate procurement power among South Korean and Chinese OLED foundries, forcing mid-tier flexible circuit suppliers toward margin compression or medical-grade qualification tier exits. Strategic archetypes include captive display manufacturers controlling upstream substrate supply, polyimide film specialists with proprietary precursor formulations, and printed electronics roll-to-roll converters. Dominant competitive moves center on capacity expansion in foldable display substrates and strategic partnerships for medical-grade qualification pathways.
Among vertically integrated electronics conglomerates, Samsung Electronics Co Ltd exemplifies captive supply chain control through in-house OLED fab networks. DuPont de Nemours Inc. occupies a position as a polyimide substrate anchor with proprietary Kapton formulations. PragmatIC Semiconductor represents the ultra-low-cost flexible integrated circuit archetype targeting disposable application volumes.
| Leading Market Players |
|---|
| Samsung Electronics Co Ltd |
| Panasonic Corporation |
| The 3M Company |
| LG Display Co Ltd |
| BOE Technology Group Co Ltd |
| AU Optronics Corporation |
| DuPont de Nemours Inc. |
| PragmatIC Semiconductor |
| Konica Minolta |
| Others |
Supply Flow & Price Mechanics
Display fab capacity utilization above eighty percent in South Korea and China compresses polyimide substrate spot availability while elevating contract price floors for medical-grade tiers. This scale concentration forces mid-tier converters to absorb margin compression or exit qualification-intensive segments entirely.
Pricing Analysis
Cost-plus contracts with polyimide precursor indexation dominate procurement between Japanese chemical suppliers and downstream converters. Pricing stratifies across ISO 13485-certified medical tiers, REACH-compliant EU-bound shipments, and standard consumer electronics grades. Cost compression in consumer-grade substrates is intensifying because South Korean display foundries are consolidating vendor panels. Hospital procurement consortia in Germany and the Netherlands exhibit the lowest price sensitivity due to reimbursement-backed volume commitments, while RFID logistics buyers drive aggressive unit-cost negotiations.
Supply Chain Analysis
Strait of Malacca transit underwrites polyimide precursor feedstock flows from Japanese chemical plants to South Korean display clusters. Supply concentrates in Japan for Kapton and UPIlex formulations, South Korea for copper-nanowire transparent conductors, and China for roll-to-roll gravure equipment. Raw material dependencies include pyromellitic dianhydride monomers, silver-nanowire dispersions, and polyethylene naphthalate webs. Single-source vulnerability pervades medical-grade substrate qualification tiers where FDA and ECHA compliance locks converters to approved suppliers. Distribution runs through direct mill relationships for high-volume display foundries and specialized distributors for medical device OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flexible electronics incumbents face substitution defense imperatives as rigid PCB alternatives and micro-LED on glass threaten cost-sensitive consumer segments. The report frames strategic positioning around qualification moats and material chemistry differentiation.
For Market Incumbents: Shield medical-grade substrate margins by accelerating ISO 13485 certification timelines ahead of REACH substance restriction enforcement. Deepen backward integration into polyimide precursor formulations to reduce Japanese feedstock allocation risk. Consolidate vendor relationships with Dutch and Danish hospital procurement consortia before three-supplier panel limits harden. For New Entrants and Emerging Players: Differentiate on silicone encapsulant formulations for EU-bound medical wearables as ECHA halogenated flame retardant limits tighten. Target India's Gujarat and Tamil Nadu electronics clusters under modified PLI incentive structures for component sourcing. Penetrate via gravure-printed RFID antenna volumes where micron-scale registration accuracy now matches etched-copper economics. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors roll-to-roll manufacturing equipment specialists with cross-functional organic-oxide semiconductor integration capabilities. Long-term viability hinges on qualification pathway ownership as FDA device classification rules and EPA PFAS frameworks reshape material sets. Watch ECHA substance restriction expansion timelines as the inflection signal for silicone and parylene encapsulant substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Medical-Grade Certification Investment | ISO 13485 qualification creates eighteen-to-twenty-four-month moats against commodity substrate competitors. |
| Silicone Encapsulant Scale-Up | ECHA REACH restrictions on halogenated flame retardants favor qualified silicone suppliers in EU medical wearables. |
| India Manufacturing Footprint | PLI scheme modifications for component sourcing attract substrate packaging investments to Gujarat clusters. |
| Roll-to-Roll Gravure Partnership | Micron-scale registration accuracy on polyethylene naphthalate unlocks RFID antenna volume economics. |
| PFAS-Free Barrier Film Development | EPA framework threats to fluoropolymer films accelerate parylene alternative qualification cycles. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with display fab procurement directors, medical device OEM substrate engineers, roll-to-roll manufacturing equipment specialists, and ECHA regulatory affairs consultants. Secondary validation drew from FDA 510(k) device filings, ECHA substance restriction announcements, SEC 10-K disclosures from listed materials suppliers, and South Korean Ministry of Trade import-export statistics. Bottom-up substrate volume estimates triangulated against top-down display panel production forecasts.
Across the analysis window, projections incorporated segment-level modeling by product type, technology platform, application vertical, and end-user procurement sophistication. CAGRs derived from elasticity-adjusted demand curves for foldable OLED penetration, printed electronics volume scaling, and medical wearable reimbursement expansion. Industry-specific inputs included polyimide precursor capacity utilization rates, copper-nanowire transparent conductor yield improvements, and REACH compliance cost pass-through coefficients.
The analysis sits within stated boundaries; outcomes outside sustained display fab capacity expansion or accelerated PFAS regulatory timelines would require recalibration. Forecasts reflect documented assumptions about hinge-compatible smartphone panel adoption curves and hospital procurement consolidation velocity. Practitioners should keep alternative scenarios live as ECHA substance restriction scope and EPA fluoropolymer framework enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Asia-Pacific USB Retimer Market
Electronic Components
PTC Resettable Device Market
Electronic Components
Data Acquisition Hardware Market
Electronic Components
Acoustic Diaphragm Market
Electronic Components
Industrial Relays Market
Electronic Components
Battery Holders Market
Electronic Components
AC Adapter Market
Electronic Components
Microcontroller Socket Market
Electronic Components
Motherboard Battery Market
Electronic Components
Electronic Speed Controllers Market
Electronic Components
Global Ethernet Controller Market
Electronic Components
Graphics Add-In Board (AIB) Market
Electronic Components
Global Industrial Media Converters Market
Electronic Components
Gigabit Interface Converter Market
Electronic Components
Structural Electronics Market
Electronic Components
Pneumatic Components Market