
 Asia Pacific Quantum Computing Market | 2026-2036
Asia Pacific Quantum Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Quantum Computing Market Insights
Japan's METI quantum technology roadmap is pivoting national R&D priorities toward fault-tolerant quantum systems, redirecting both public funding and private sector alignment across the region. Alibaba Quantum Lab leverages captive cloud infrastructure to dominate quantum-as-a-service deployment in China. Fujitsu Quantum Computing anchors its position through deep specialization in superconducting qubit architectures for industrial simulation. Baidu Quantum Computing competes aggressively on quantum machine learning toolkits tailored to Asian language processing and financial modeling.
Quantum computing harnesses superposition, entanglement, and interference to manipulate qubits at temperatures near absolute zero, typically requiring dilution refrigerators operating below 15 millikelvin, enabling computation of problems intractable to classical silicon architectures. Quantum Hardware occupies the dominant value pool given cryogenic control electronics and custom fab requirements, while Quantum Software captures expanding margins as algorithm libraries mature across finance and defense verticals. Cloud-Based deployment leads adoption among research institutions seeking elastic access without capital-intensive cryogenic infrastructure.
China's MIIT sets domestic quantum technology standards that constrain foreign system access, while Japan's METI coordinates patent pools and supply chain security protocols. South Korea's MFDS and national quantum initiative shape healthcare and pharmaceutical simulation requirements. Stakeholders must monitor how divergent national certification regimes fragment interoperability standards and dictate alliance structures across the region.
Market Dynamics
Fault-tolerant quantum architectures are redirecting capital flows across the Asia Pacific region, compressing development timelines for error-corrected systems while straining cryogenic supply chains concentrated in Japan and South Korea.
Growth Catalysts
- MIIT domestic standards:China's Ministry of Industry and Information Technology mandates quantum-safe encryption protocols for state-owned financial institutions, mandating hardware procurement from certified domestic suppliers.
- Portfolio optimization demand:Singaporean and Hong Kong asset managers deploy variational quantum eigensolvers for risk-weighted return calculations across multi-asset portfolios.
- Superconducting qubit maturation:Dilution refrigerator reliability improvements below 15 millikelvin extend coherence windows, enabling deeper circuit execution for pharmaceutical molecular simulation.
Market Restraints
- Helium-3 supply concentration:Cryogenic cooling dependence on Russian and Qatari isotope exports creates input cost volatility for dilution refrigerator operators.
- Foreign system exclusion:China's MIIT certification regime structurally blocks non-domestic quantum hardware from government and defense procurement channels.
- Classical algorithm advancement:Tensor network methods and GPU-accelerated simulation narrow the quantum advantage window for optimization problems in logistics and finance.
Strategic Opportunities
- ASEAN underpenetration:Indonesia, Vietnam, and Thailand lack domestic quantum infrastructure, creating whitespace for cloud-based quantum-as-a-service expansion from Singapore and Australian hubs.
- METI fault-tolerance funding:Japan's 2024 R&D roadmap directs public-private capital toward error-corrected logical qubit demonstration, accelerating patent pool formation.
- Photonic-quantum convergence:Room-temperature photonic interconnects hybridized with superconducting processors reduce cryogenic footprint for edge deployment in manufacturing quality control.
Industry Challenges
- Cryogenic engineering talent scarcity:Microwave engineering and dilution refrigerator operation expertise concentrates in Tokyo, Beijing, and Sydney, constraining regional expansion.
- Interoperability certification delays:Divergent national quantum cryptography standards between China, Japan, and South Korea fragment cross-border financial network deployment.
- Legacy HPC integration friction:Financial institutions in Hong Kong and Singapore struggle to embed quantum processing units within existing risk management software stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Quantum Computing Market |
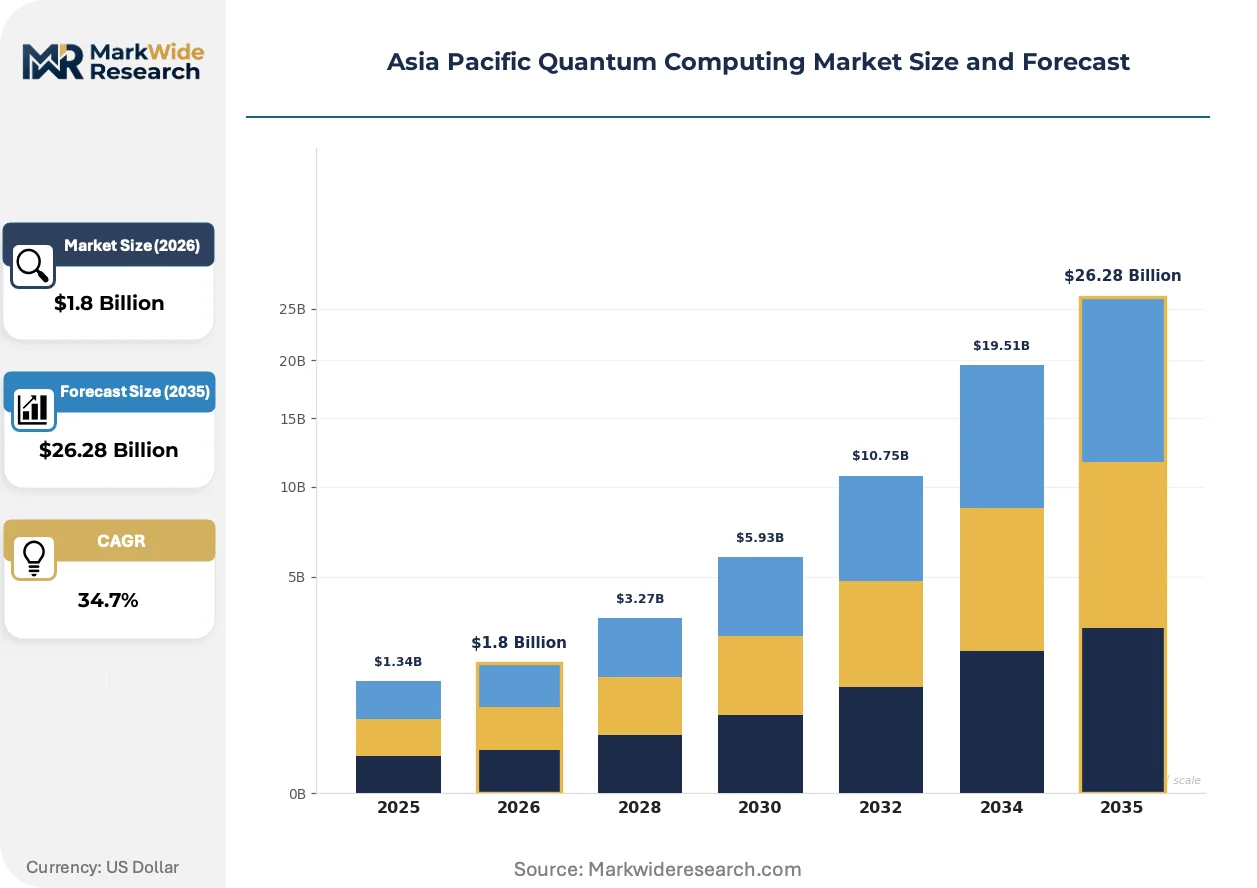
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $26.28 Billion |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quantum Hardware, Quantum Software, Quantum Networking, Quantum Sensors End User: Finance, Healthcare, Defense, Research Institutions Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing Solution: Quantum Simulation, Quantum Cryptography, Quantum Communication, Quantum Machine Learning |
| Companies Covered | Alibaba Quantum Lab, Fujitsu Quantum Computing, Baidu Quantum Computing, NEC Corporation, Toshiba Research Europe Ltd., JSR Corporation, IBM Corporation, Google Quantum AI, Rigetti Computing, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Quantum Computing Market Trends and Innovations
Quantum error correction is compressing the path to commercial utility, reshaping how hardware developers, cloud providers, and end-users align around fault-tolerant roadmaps rather than noisy intermediate-scale quantum benchmarks.
Logical qubit encoding via surface code architectures is rewriting the competitive calculus for quantum hardware vendors. Japanese superconducting specialists and Chinese trapped-ion developers now prioritize error correction overhead reduction over raw physical qubit counts. Financial services procurement teams in Singapore evaluate systems based on logical error rates rather than device specifications, compressing sales cycles for fault-tolerant platforms.
METI's quantum technology roadmap mandates supply chain security protocols for cryogenic control electronics, requiring domestic sourcing of FPGA-based pulse generators and microwave cabling. Japanese semiconductor foundries are retooling for superconducting circuit fabrication, displacing previous reliance on European and North American specialty suppliers. South Korea's national quantum initiative is drafting complementary standards, creating regulatory fragmentation for vendors seeking pan-Asia Pacific deployment.
Consumption patterns among Asia Pacific research institutions favor subscription-based quantum cloud access over capital-intensive on-premise dilution refrigerator installation. University consortia in Australia and Taiwan pool credits for time-shared access to Japanese and Chinese quantum processors, unbundling hardware ownership from experimental capability. This procurement model shift concentrates revenue with cloud platform operators while compressing margins for bare-metal hardware vendors.
Asia Pacific Quantum Computing Market Segmentation
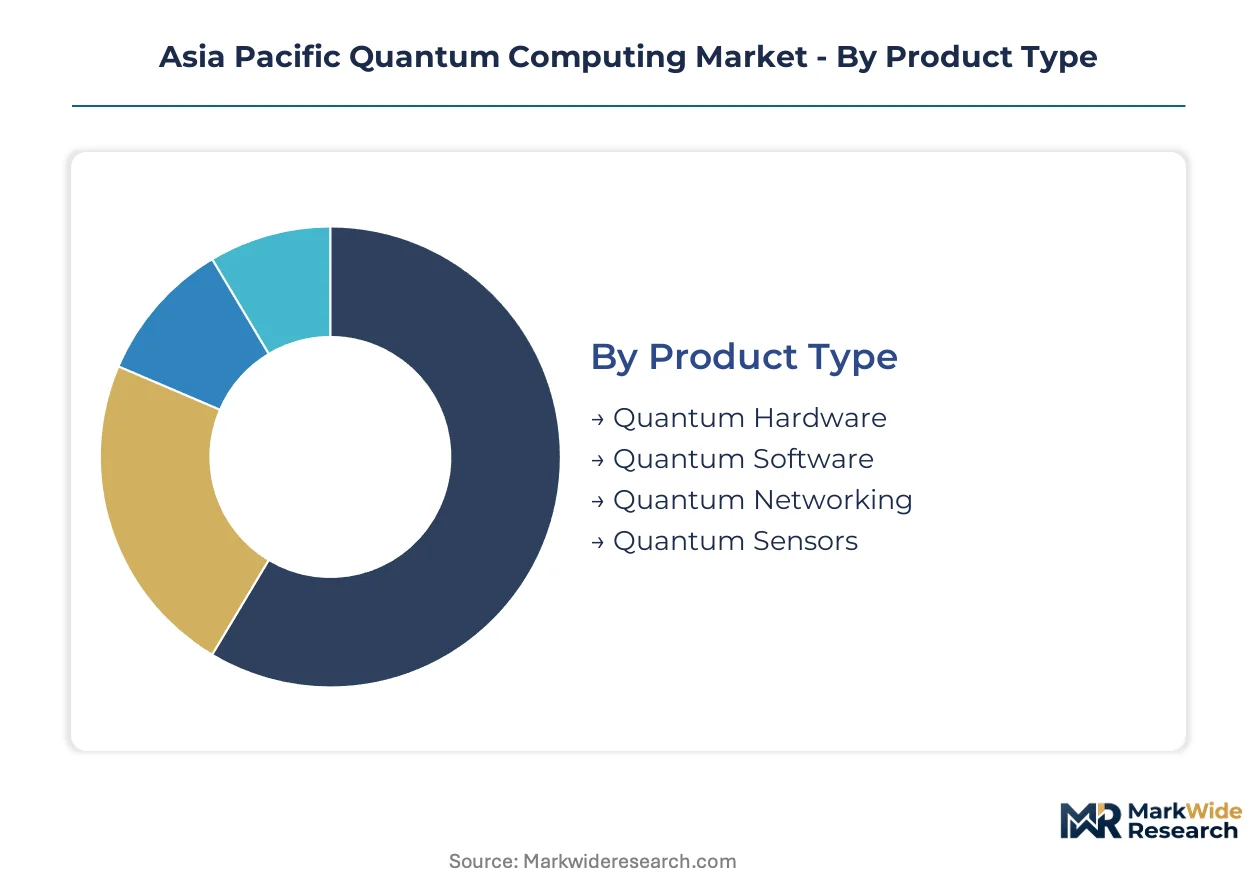
Quantum computing market segmentation reveals how value concentrates across the technology stack and where procurement patterns diverge between capital-intensive hardware ownership and elastic cloud consumption. Understanding these splits enables vendors to align R&D investment with actual deployment economics across Asia Pacific's heterogeneous national markets.
Product Type:
Quantum Hardware commands the dominant value pool due to cryogenic fabrication requirements and captive control electronics supply chains, while Quantum Software captures expanding margins as algorithm libraries mature.
- Quantum Hardware:Superconducting qubit processors, dilution refrigerators, and microwave control electronics form the capital core. Japanese and South Korean fabs specialize in niobium-based circuit fabrication for METI-certified systems. Beijing, Shanghai, and Hefei anchor China's domestic supply chain for cryogenic infrastructure.
- Quantum Software:Algorithm development kits, error correction compilers, and quantum-classical hybrid orchestration layers. Singaporean and Hong Kong financial institutions drive demand for portfolio optimization SDKs that interface with cloud hardware backends.
- Quantum Networking:Entanglement distribution hardware and quantum key distribution protocols for secure fiber and satellite links.
- Quantum Sensors:Atomic interferometers and nitrogen-vacancy magnetometers for precision navigation and geological surveying.
Mature deployment sits with Quantum Hardware. Newer deployment is concentrated in Quantum Software.
End User:
Financial services procurement teams in Singapore and Hong Kong evaluate systems based on logical error rates, compressing sales cycles for fault-tolerant platforms.
- Finance:Asset managers deploy variational quantum eigensolvers for risk-weighted return calculations. Singapore's Monetary Authority and Hong Kong's central bank shape quantum-safe encryption mandates for cross-border payment infrastructure.
- Healthcare:Pharmaceutical molecular simulation and drug-target interaction modeling. South Korea's MFDS drafts validation protocols for quantum-accelerated clinical trial design.
- Defense:Secure communications, battlefield optimization, and cryptographic resilience. China's MIIT certification regime blocks foreign hardware from defense procurement channels.
- Research Institutions:University consortia in Australia and Taiwan pool credits for time-shared cloud access to Japanese and Chinese processors.
Procurement sophistication peaks in Finance. Experimental adoption spreads fastest through Research Institutions.
Deployment:
Cloud-Based consumption dominates among institutions avoiding capital-intensive dilution refrigerator ownership, while Hybrid architectures address latency-sensitive financial workloads.
- Cloud-Based:Subscription access to remote quantum processors via API integration. Alibaba and Baidu leverage captive infrastructure to dominate quantum-as-a-service deployment in China.
- On-Premise:Dedicated dilution refrigerator installation for sovereign data requirements. Japanese government labs and defense facilities favor METI-certified domestic systems.
- Hybrid:Quantum processing units embedded within classical high-performance computing clusters. Hong Kong and Singapore banks struggle with legacy risk management stack integration.
- Edge Computing:Room-temperature photonic interconnects for manufacturing quality control in distributed facilities.
Elastic scaling concentrates in Cloud-Based. Sovereign control drives On-Premise retention.
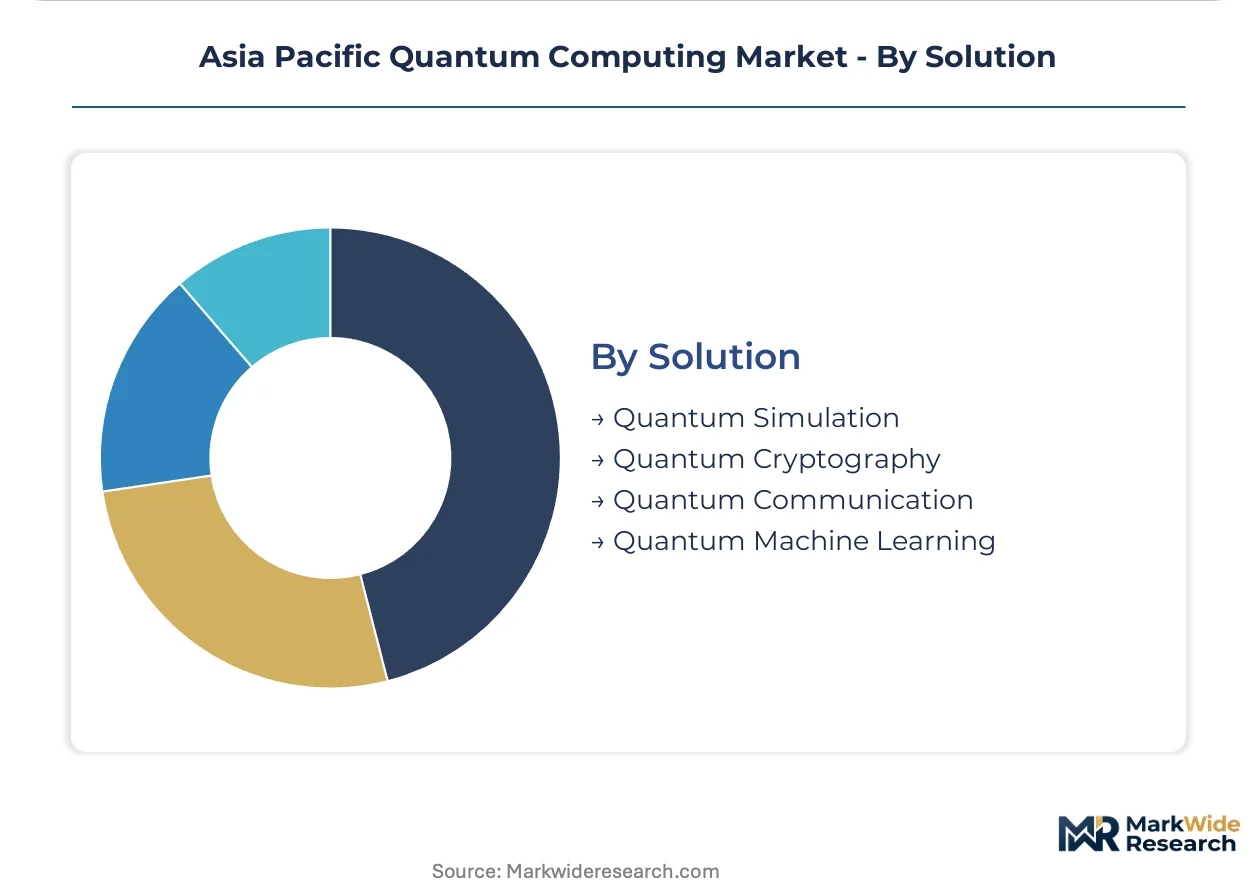
Solution:
Quantum Cryptography gains regulatory tailwinds from MIIT encryption mandates, while Quantum Machine Learning attracts venture funding for Asian language processing applications.
- Quantum Simulation:Molecular dynamics and materials science computation. Pharmaceutical demand concentrates in Shanghai and Osaka for superconducting-circuit-based simulators.
- Quantum Cryptography:Quantum key distribution and post-quantum cryptographic protocols. China's MIIT mandates quantum-safe standards for state-owned financial institutions.
- Quantum Communication:Satellite-based entanglement distribution and fiber-linked quantum networks.
- Quantum Machine Learning:Quantum neural networks and kernel methods for pattern recognition. Baidu competes aggressively on toolkits tailored to Asian language processing.
Regulatory compliance anchors Quantum Cryptography. Research novelty propels Quantum Machine Learning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beijing anchors Asia Pacific quantum computing deployment through its concentration of national laboratories and state-backed cloud infrastructure. The technology corridor linking Shanghai and Hefei extends this concentration with dedicated superconducting fabrication facilities and trapped-ion research centers. National regulators across the region are erecting divergent certification regimes that fragment cross-border procurement patterns.
China
MIIT domestic standards mandate quantum-safe encryption protocols for state-owned banks, requiring hardware procurement from certified domestic suppliers. The ministry's certification regime structurally excludes foreign quantum systems from government and defense channels. Beijing, Shanghai, and Hefei form the eastern technology corridor where Alibaba and Baidu operate captive cloud infrastructure for quantum-as-a-service deployment.
Japan
METI's quantum technology roadmap directs public-private R&D funding toward fault-tolerant systems with error-corrected logical qubits. The ministry coordinates patent pools and supply chain security protocols for cryogenic control electronics. Tokyo and Osaka anchor superconducting circuit fabrication, with Japanese foundries retooling to displace previous reliance on European specialty suppliers.
South Korea
MFDS drafts validation protocols for quantum-accelerated pharmaceutical simulation, shaping healthcare procurement requirements. The national quantum initiative complements Japanese standards, creating regulatory fragmentation for vendors seeking pan-regional deployment. Seoul and Daejeon concentrate cryogenic engineering talent and dilution refrigerator manufacturing capacity.
Singapore
The Monetary Authority shapes quantum-safe encryption mandates for cross-border payment infrastructure, accelerating financial services adoption. Asset managers deploy variational quantum eigensolvers for portfolio optimization across multi-asset strategies. The city-state functions as a quantum-as-a-service hub for ASEAN markets lacking domestic infrastructure.
Australia
University consortia pool subscription credits for time-shared access to Japanese and Chinese quantum processors, unbundling hardware ownership from experimental capability. Sydney concentrates microwave engineering expertise for cryogenic system operation. Research institutions favor elastic cloud access over capital-intensive on-premise dilution refrigerator installation.
Asia Pacific Quantum Computing Market Competitive Landscape
The competitive structure tilts toward captive cloud infrastructure operators with state-aligned R&D backing. Market concentration remains moderate, with domestic champions in China and Japan holding protected positions while international specialists compete for financial services contracts in Singapore and Hong Kong. Three archetypes dominate: state-aligned cloud platforms, superconducting hardware specialists, and quantum software toolkit providers. Strategic moves center on patent pool formation and supply chain security certification rather than direct price competition.
Within the state-aligned cloud tier, Alibaba Quantum Lab and Baidu Quantum Computing exemplify the model of leveraging captive infrastructure to dominate domestic quantum-as-a-service deployment. Fujitsu Quantum Computing anchors the superconducting hardware specialist position through its concentration on industrial simulation applications. These three companies illustrate how national technology policy shapes competitive positioning across the region's fragmented regulatory environment.
| Leading Market Players |
|---|
| Alibaba Quantum Lab |
| Fujitsu Quantum Computing |
| Baidu Quantum Computing |
| NEC Corporation |
| Toshiba Research Europe Ltd. |
| JSR Corporation |
| IBM Corporation |
| Google Quantum AI |
| Rigetti Computing |
| Others |
Pricing and Supply Chain Analysis
Captive vertical integration into cryogenic control electronics anchors both supply security and pricing power for Japanese and Chinese system vendors. METI domestic-content mandates and MIIT certification regimes force foreign competitors into premium-priced niche positions or cloud-service partnerships.
Pricing Analysis
Logical error rate performance anchors value-based pricing for fault-tolerant quantum systems. Three-tier pricing structure across premium fault-tolerant platforms, standard NISQ devices, and economy cloud-access tiers separates procurement budgets. Cost compression in cloud-access tiers is intensifying because Alibaba and Baidu leverage captive infrastructure for aggressive subscription pricing. Research institutions exhibit highest price sensitivity, while defense procurement teams prioritize certification compliance over unit cost.
Supply Chain Analysis
METI domestic-content mandates and MIIT local-sourcing rules are reshaping procurement patterns for dilution refrigerators and superconducting circuits. Supply concentrates in Japan, South Korea, and China for cryogenic infrastructure, with Beijing, Tokyo, and Seoul anchoring fabrication clusters. Helium-3 isotope feeds from Russian and Qatari sources, niobium substrates, and FPGA-based pulse generators constitute critical input dependencies. Single-source vulnerability in helium-3 supply creates structural risk for refrigerator operators. Distribution runs through state-certified system integrators and cloud platform operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fault-tolerant quantum architectures are displacing noisy intermediate-scale quantum benchmarks as the commercial viability threshold, compressing vendor roadmaps and procurement evaluation criteria across the region.
For Market Incumbents: Deepen patent pool formation around surface code error correction to lock in architectural standards. Expand captive niobium foundry capacity in Tokyo and Osaka to secure METI-certified supply chains against South Korean competition. Cloud platform operators face margin compression from classical algorithm advancement in financial optimization.
For New Entrants and Emerging Players: Begin with cloud-native quantum machine learning toolkits for ASEAN financial institutions lacking on-premise infrastructure. Indonesia and Vietnam present whitespace for API-integrated portfolio optimization services. Partner with Singaporean asset managers for regulatory co-development of quantum-safe encryption protocols.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by hyperscaler cloud platforms seeking captive quantum hardware capabilities. Five-to-ten-year viability hinges on logical qubit demonstration milestones rather than physical qubit scale. Watch for METI patent pool licensing terms as inflection signal for regional standard consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Patent Pool Formation | METI-coordinated intellectual property sharing accelerates fault-tolerant system development timelines. |
| Cryogenic Foundry Expansion | Japanese niobium circuit fabrication retooling displaces European specialty supplier dependence. |
| Cloud Platform Integration | Alibaba and Baidu captive infrastructure dominates quantum-as-a-service deployment in China. |
| ASEAN Hub Establishment | Singapore-based quantum-as-a-service expansion captures underpenetrated Indonesian and Vietnamese demand. |
| Supply Chain Security Certification | MIIT and METI divergent standards fragment interoperability and dictate alliance structures. |
Research Methodology
Independent corroboration across cryogenic engineering specialists, financial services procurement officers, and national laboratory program directors underwrites the qualitative findings. Primary fieldwork encompassed quantum hardware engineering leads, cloud platform product managers, defense research contract officers, and pharmaceutical R&D directors. Secondary validation drew from MIIT standard filings, METI roadmap publications, patent registry analysis, and hyperscaler capital expenditure disclosures. Bottom-up demand modeling and top-down technology adoption curves were triangulated against regional regulatory timelines.
Rate-of-change decomposition across hardware maturation curves, algorithm library expansion, and cloud consumption patterns shaped the analytical framework. Segmentation dimensions encompassed product type, end-use vertical, deployment model, and national regulatory cluster. CAGRs were derived from installed base projections and average revenue per user trajectories. Cryogenic engineering talent concentration and helium-3 supply elasticity served as industry-specific forecast inputs across the projection horizon.
MIIT certification regime expansion, METI funding allocation shifts, and classical algorithm breakthroughs in optimization are the dominant revision risks. Forecasts reflect documented assumptions regarding fault-tolerant system demonstration timelines and cloud platform pricing elasticity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Global Flexible and Printed Electronics Market
Emerging and Next Generation Technologies
Microfluidics Prototype Market
Emerging and Next Generation Technologies
NB-IoT Module Market
Emerging and Next Generation Technologies
Mexico Cleanroom Technology Market
Emerging and Next Generation Technologies
Global Broad Ion Beam Technology Market
Emerging and Next Generation Technologies
Switchable Smart Film Market
Emerging and Next Generation Technologies
Flexible PV Cell Market
Emerging and Next Generation Technologies
Internet of Nano Things Market
Emerging and Next Generation Technologies
Next-Generation Organic Solar Cell Market
Emerging and Next Generation Technologies
Global Terahertz Components and Systems Market
Emerging and Next Generation Technologies
Molecular Electronics Market
Emerging and Next Generation Technologies
Global 3D TSV and 2.5D Market
Emerging and Next Generation Technologies
Spintronics Market
Emerging and Next Generation Technologies
Printed Electronics Market
Emerging and Next Generation Technologies
Deep Tech Market
Emerging and Next Generation Technologies
Global High-Performance Computing (HPC) Market