
 Global Electronic Design Automation (EDA) Market | 2026-2036
Global Electronic Design Automation (EDA) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electronic Design Automation (EDA) Market Intelligence
China's significant investment in domestic semiconductor fabrication capacity is rewriting the competitive landscape for EDA tool providers. This shift creates new opportunities and challenges for established leaders. Synopsys leverages its comprehensive portfolio spanning from silicon to software. Cadence Design Systems differentiates through its focus on intelligent system design and computational software, while Siemens EDA sustains its position by integrating its tools with broader industrial software ecosystems.
Electronic Design Automation comprises a suite of software tools used to design, verify, and manufacture complex electronic systems, including integrated circuits and printed circuit boards. These tools automate critical design stages, such as register-transfer level (RTL) synthesis and physical verification, enabling the creation of multi-billion transistor chips. Within product types, the IC Physical Design & Verification segment commands the largest share due to its criticality in chip tape-outs. The automotive OEM and telecommunications application segments represent the fastest-growing areas, driven by demand for advanced driver-assistance systems and 5G infrastructure.
The market operates under stringent export control regimes, such as the Export Administration Regulations (EAR) managed by the U.S. Department of Commerce, which restrict access to advanced EDA technologies. Concurrently, national industrial policies like the EU Chips Act and China's "dual carbon goals" influence design priorities, pushing for energy-efficient chip architectures. Stakeholders must navigate this complex geopolitical and regulatory web to maintain access to critical design tools and end markets.
Market Dynamics
The imperative to manage escalating design complexity for next-generation semiconductors is the central force shaping the Electronic Design Automation market. This pressure stems from the technological shift toward advanced transistor architectures and the functional demands of AI and automotive systems.
Growth Catalysts
- System-on-Chip (SoC) Complexity:Demand from the automotive and telecommunications sectors for sophisticated SoCs, which integrate multiple functions onto a single chip for applications like ADAS and 5G, requires more advanced EDA synthesis and verification tools.
- Advanced Process Nodes:The industry's transition to gate-all-around (GAA) and other three-dimensional transistor architectures necessitates entirely new EDA toolchains capable of handling novel physical effects and layout rules, driving investment from foundries and fabless designers.
- National Semiconductor Initiatives:Government policies, including the EU Chips Act and investments by China in its domestic industry, are stimulating regional semiconductor design activity, creating localized demand for EDA software and IP licenses to support these strategic goals.
Market Restraints
- Export Control Regimes:Geopolitical tensions manifest as stringent export controls, such as the U.S. Department of Commerce's Export Administration Regulations (EAR), which restrict access to advanced EDA tools for entities in certain countries, fragmenting the market.
- Extreme Computational Costs:Verifying multi-billion transistor designs at advanced nodes requires massive computational resources, creating a significant cost barrier for smaller design houses and startups that lack access to large-scale data centers or cloud computing budgets.
- High R&D Investment Barrier:The immense capital required to develop and maintain a competitive EDA tool portfolio for leading-edge nodes creates a high barrier to entry, leading to market concentration and limiting competitive pressure from new entrants.
Strategic Opportunities
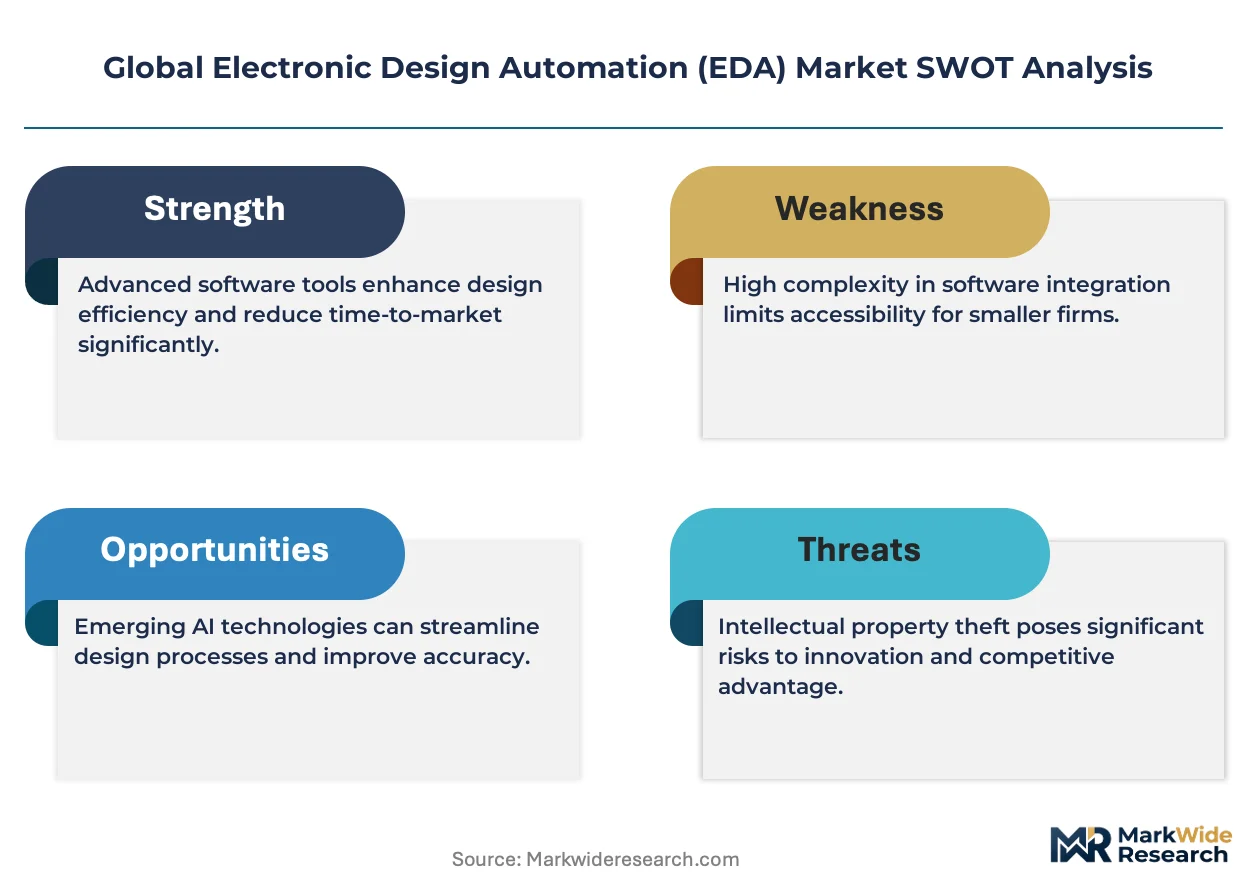
- AI-Specific Chip Architectures:The proliferation of artificial intelligence and machine learning workloads creates a significant opportunity for EDA tools tailored to designing specialized hardware accelerators, such as TPUs and NPUs, that are optimized for power and performance.
- Cloud-Based EDA Platforms:The delivery of EDA tools via cloud platforms offers a new business model that lowers the barrier to entry for startups and provides scalable, on-demand compute resources, opening an underpenetrated segment of the market.
- Digital Twin and System-Level Integration:Integrating EDA tools with broader system design and simulation platforms allows for the creation of digital twins of entire electronic systems, enabling pre-silicon validation and optimization that considers both hardware and software.
Industry Challenges
- Specialized Talent Shortage:The industry faces a critical shortage of engineers with the specialized skills required for physical design, verification, and methodology development for advanced process nodes below 7nm, constraining project timelines.
- IP Integration Complexity:Assembling complex SoCs from numerous third-party and internal Intellectual Property (IP) blocks creates significant challenges in ensuring compatibility, managing licensing terms, and verifying the integrated system's performance and security.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electronic Design Automation (EDA) Market |
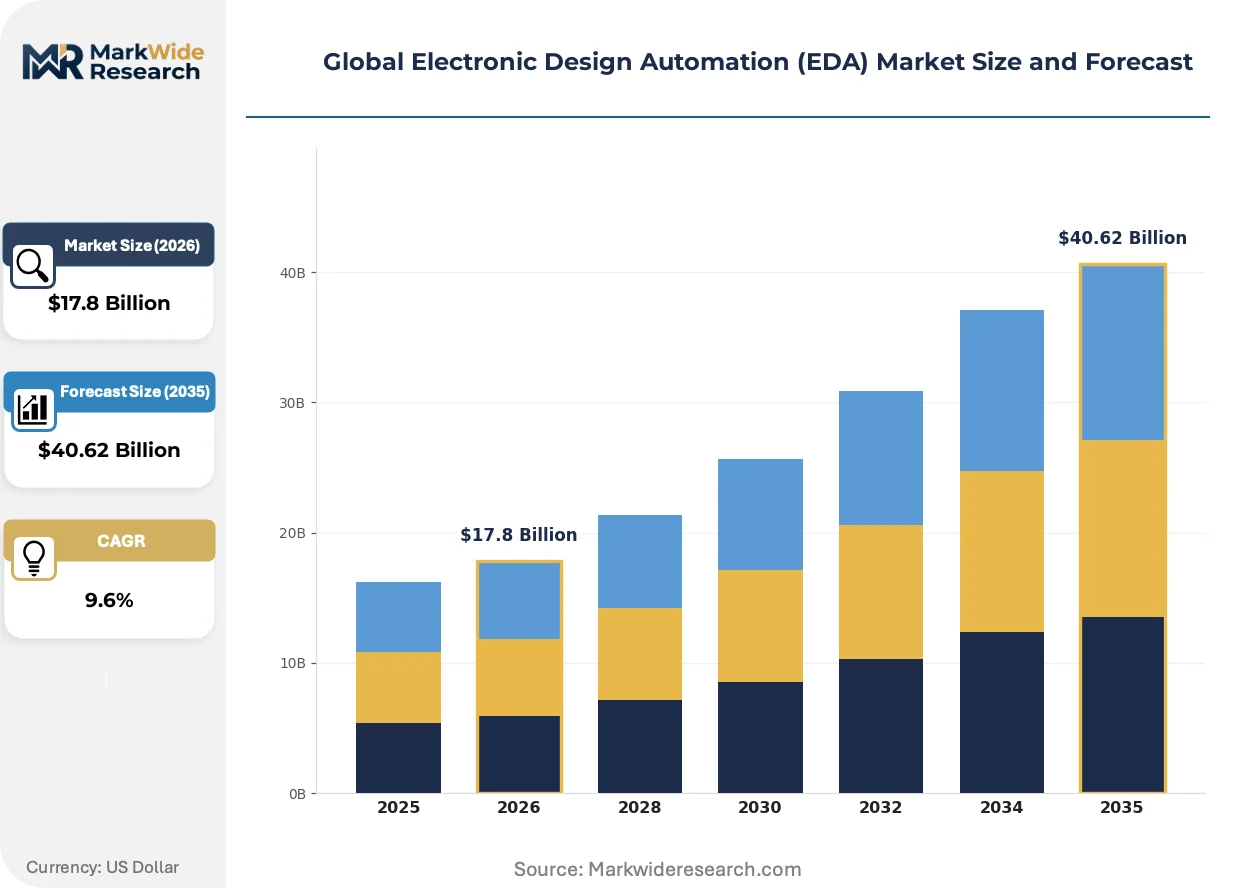
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $40.62 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IC Physical Design & Verification, Functional Verification, RTL Design & Verification, PCB Design, Others Technology: ASIC, FPGA, SoC, Analog/Mixed Signal, Custom IC Application: Consumer Electronics, Telecommunications, Aerospace & Defense, Semiconductor Manufacturing, Automotive OEMs End User: Chip Designers, Foundries, Electronic Manufacturing Services, IP Vendors, Fabless Companies |
| Companies Covered | Ansys, Altium, Synopsys, Silvaco, Zuken, Cadence Design Systems, Keysight Technologies, Aldec, Siemens EDA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electronic Design Automation (EDA) Market Strategic Shifts & Innovations
The EDA market is being redefined by the infusion of artificial intelligence into the design process itself. This trend addresses the unsustainable rise in design complexity and engineering hours required for each new generation of silicon, shifting focus toward automated optimization.
AI-powered automation is a transformative technology within EDA, using machine learning to optimize chip layout and verification. Leading fabless semiconductor companies and integrated device manufacturers are rapidly adopting these tools to accelerate design closure on complex projects. The entire chip design workflow is migrating from a reliance on human-driven heuristics and iterative manual adjustments to a model where AI explores the design space to find optimal power, performance, and area solutions.
China's "dual carbon goals" are influencing semiconductor design priorities well beyond its borders. This national policy directly incentivizes the development of low-power electronics, impacting the global supply chain for components used in consumer electronics and data centers. The telecommunications and industrial automation segments are most affected, responding by demanding EDA tools with superior power estimation and thermal analysis capabilities to meet new energy efficiency standards.
A fundamental shift in consumption patterns involves the move away from perpetual on-premise licenses toward cloud-based, pay-per-use access models. This change disrupts the traditional direct sales channel, elevating cloud providers like AWS and Azure to key distribution and infrastructure partners for EDA vendors. The trend is most prominent among semiconductor startups and small-to-medium design teams, particularly in innovation clusters like Santa Clara and Hsinchu, which prioritize operational flexibility.
Global Electronic Design Automation (EDA) Market Segmentation
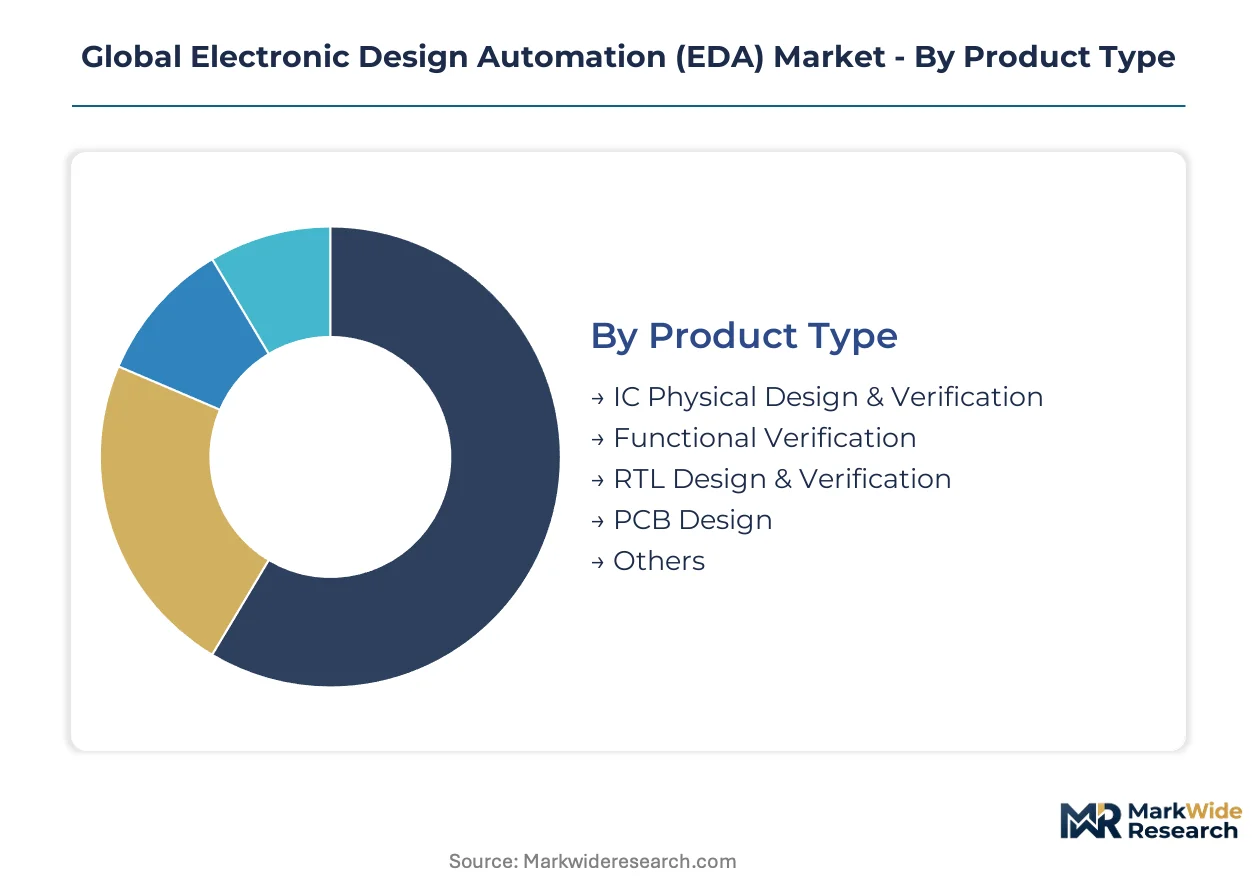
The Electronic Design Automation market is disaggregated into distinct categories, reflecting the diverse requirements of chip design, verification, and manufacturing across the semiconductor ecosystem. Understanding these segments clarifies the specific technological demands and application-driven growth vectors within the industry.
Product Type:
The functional scope of EDA tools delineates the market by the specific design tasks they address, from initial concept to final physical layout. This categorization highlights the specialized software suites essential for various stages of chip development.
- IC Physical Design & Verification:These tools manage the intricate layout, routing, and physical verification of integrated circuits, ensuring manufacturability and performance for multi-billion transistor designs. Demand concentrates in advanced semiconductor design clusters like Santa Clara, United States, and Hsinchu, Taiwan, for leading-edge process nodes.
- Functional Verification:This segment encompasses software for validating the logical correctness and behavior of a design against its specifications, critical for preventing costly re-spins. Demand originates from automotive OEMs for safety-critical ADAS systems and telecommunications for complex 5G infrastructure.
- RTL Design & Verification:Focuses on the register-transfer level, enabling engineers to describe digital circuits' behavior and structure using hardware description languages.
- PCB Design:Tools within this segment facilitate the creation, layout, and analysis of printed circuit boards, integrating various electronic components.
- Others:This category includes specialized EDA tools for areas such as intellectual property (IP) integration, design for testability, and power analysis.
IC Physical Design & Verification commands the established base. The steepest expansion runs through Functional Verification.
Technology:
The underlying chip architectures supported by EDA software define this segment, indicating the specific design methodologies and complexities involved for different semiconductor types.
- SoC:System-on-Chip solutions integrate multiple functional blocks onto a single silicon die, requiring sophisticated EDA for comprehensive design, verification, and integration. Demand from telecommunications for 5G base stations and automotive for advanced infotainment systems drives this segment.
- ASIC:Application-Specific Integrated Circuits are custom-designed for a particular application, offering optimized performance and power efficiency for high-volume production. Demand from data centers for specialized AI accelerators and consumer electronics for dedicated processors remains significant.
- FPGA:Field-Programmable Gate Arrays provide reconfigurable hardware platforms, primarily used for prototyping, lower-volume production, and applications requiring flexibility.
- Analog/Mixed Signal:This segment addresses the design and simulation of circuits that combine both analog and digital components, crucial for sensors and communication interfaces.
- Custom IC:Encompasses the design of highly specialized integrated circuits for niche applications where off-the-shelf solutions are insufficient.
SoC solutions are gaining traction. ASIC technology continues to underpin high-volume production.
Application:
The end-use industries driving demand for EDA capabilities classify this segment, highlighting the critical role of electronic design in various sectors.
- Automotive OEMs:This sector requires advanced EDA for designing complex electronic control units, advanced driver-assistance systems (ADAS), and electric vehicle powertrains. Demand from German automotive manufacturers and Japanese carmakers emphasizes safety and reliability.
- Telecommunications:Drives demand for EDA tools to develop chips for 5G infrastructure, network equipment, and communication devices, focusing on high-speed and low-latency performance. Demand from Chinese telecom giants and US network providers fuels innovation in this area.
- Consumer Electronics:Encompasses a broad range of devices, including smartphones, tablets, and smart home appliances, requiring EDA for compact, power-efficient, and feature-rich chip designs.
- Semiconductor Manufacturing:Utilizes EDA for process design kits (PDKs), mask data preparation, and yield optimization within fabrication facilities.
- Aerospace & Defense:Demands highly robust, secure, and reliable electronic designs for critical avionic systems, radar, and satellite communication.
Automotive OEMs and Telecommunications segments are experiencing robust expansion. Consumer Electronics maintains a substantial volume base.
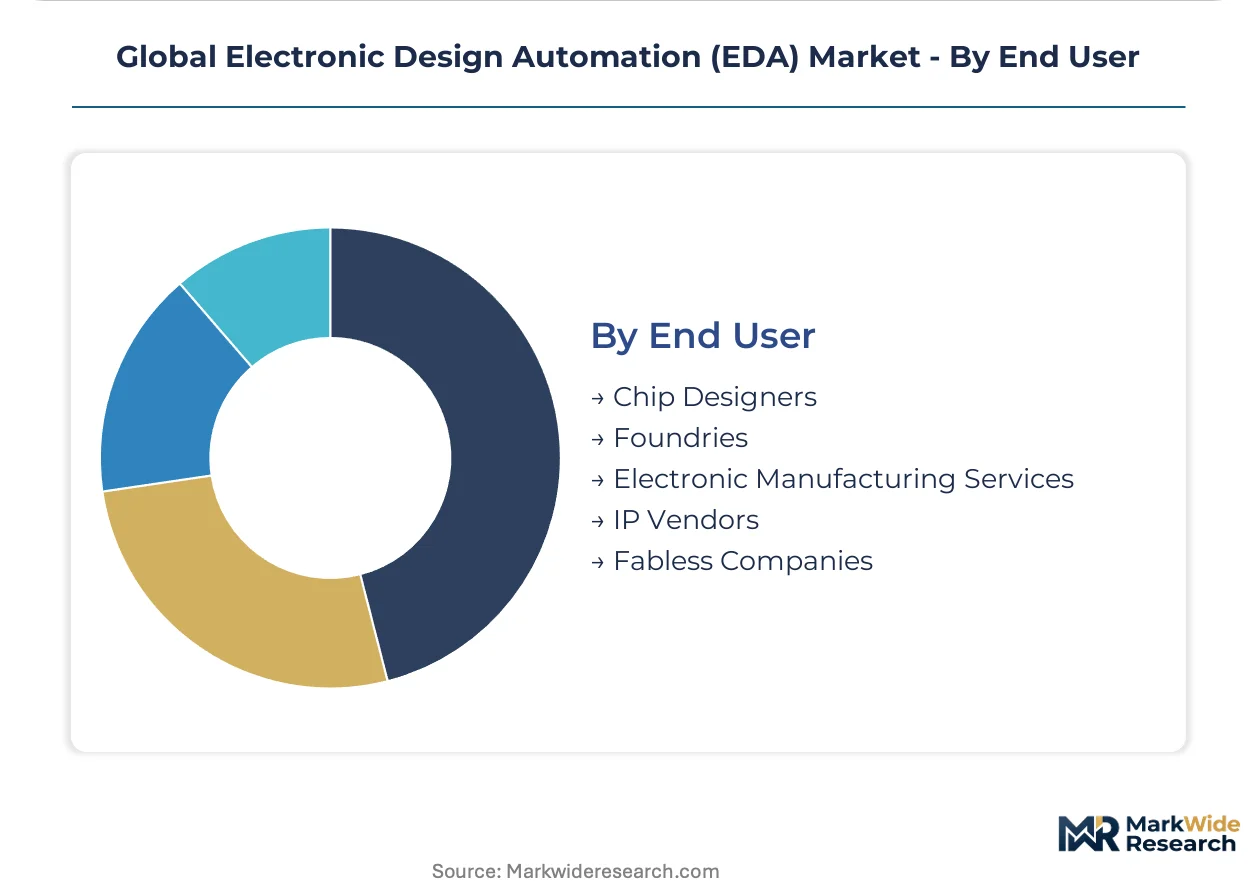
End User:
The direct beneficiaries and purchasers of EDA solutions categorize this segment, reflecting the diverse stakeholders involved in the semiconductor value chain.
- Fabless Companies:These entities specialize in chip design but outsource manufacturing, making them intensive users of EDA tools for design, verification, and physical implementation. Companies in Santa Clara, United States, and Hsinchu, Taiwan, are prominent examples.
- Chip Designers:This segment includes individual engineers and design teams within larger semiconductor firms or startups, utilizing EDA for specific circuit blocks or full system integration. Demand for specialized tools supports their intricate design processes.
- Foundries:Semiconductor fabrication plants use EDA software for developing process design kits, optimizing manufacturing flows, and ensuring design-to-manufacturing alignment.
- Electronic Manufacturing Services:These firms utilize EDA tools primarily for printed circuit board design, assembly planning, and ensuring manufacturability of electronic products.
- IP Vendors:Companies that develop and license intellectual property blocks rely on EDA for the creation, verification, and integration of their reusable design components.
Fabless Companies drive significant EDA consumption. Foundries integrate EDA tools for process optimization and manufacturing readiness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Electronic Design Automation market exhibits significant geographic concentration in semiconductor design and manufacturing hubs. Key regions drive demand for advanced EDA tools, reflecting their strategic investments in next-generation chip development. These clusters are essential for fostering innovation and technological leadership in complex electronic systems.
United States
Demand for advanced EDA tools in the United States stems from specialized AI accelerators and high-performance computing. The U.S. CHIPS and Science Act incentivizes domestic semiconductor research and production. Santa Clara in California remains a central hub, where fabless companies and design teams push the boundaries of SoC complexity.
China
China's extensive investment in domestic semiconductor fabrication capacity drives demand for comprehensive EDA solutions. National industrial policies, including its "dual carbon goals," prioritize energy-efficient chip designs. Shanghai and Beijing are significant design centers, fostering a growing ecosystem for integrated circuit development.
Germany
German automotive manufacturers require sophisticated EDA for advanced driver-assistance systems and electric vehicle powertrains. The EU Chips Act supports regional semiconductor design activity, stimulating localized demand for EDA software. Dresden, Germany, functions as a prominent semiconductor cluster, focusing on specialized chip development and manufacturing.
Taiwan
Taiwanese foundries and fabless companies drive substantial demand for IC Physical Design & Verification tools for leading-edge process nodes. The government actively supports the semiconductor industry through strategic investments and R&D incentives. Hsinchu, Taiwan, anchors global demand for advanced EDA, particularly for multi-billion transistor designs.
South Korea
South Korea's leadership in memory and logic semiconductors creates strong demand for functional verification and SoC design tools. Government initiatives promote advanced packaging technologies and AI chip development. The Seoul metropolitan area hosts major design centers, where chip designers focus on complex system integration.
Global Electronic Design Automation (EDA) Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying critical design blocks. The Electronic Design Automation market exhibits significant concentration among a few dominant software providers. These firms operate as comprehensive solution providers and specialized tool developers. Competitive moves center on strategic partnerships, continuous R&D investment in advanced nodes, and portfolio diversification to capture emerging AI and automotive segments.
Within the comprehensive solution provider archetype, Synopsys exemplifies leadership in offering end-to-end EDA toolchains spanning silicon to software. Cadence Design Systems also sits within this tier, differentiating through its focus on intelligent system design and computational software, critical for advanced system-level integration. Siemens EDA sustains its position by integrating its tools with broader industrial software ecosystems, extending its reach into diverse application segments. These entities collectively anchor the market for advanced design, verification, and manufacturing support, particularly for complex SoC and GAA architectures. Their offerings are essential for fabless companies and foundries navigating the challenges of advanced process nodes.
| Leading Market Players |
|---|
| Ansys |
| Altium |
| Synopsys |
| Silvaco |
| Zuken |
| Cadence Design Systems |
| Keysight Technologies |
| Aldec |
| Siemens EDA |
Cost & Logistics Intelligence
High utilization rates for advanced EDA toolchains, driven by complex SoC designs and GAA architectures, exert significant influence over both vendor investment strategies and pricing postures. This demand for specialized capabilities shapes the competitive landscape for software providers.
Pricing Analysis
Export Administration Regulations (EAR) dictate the pricing tier structure for advanced EDA tools, influencing accessibility for certain entities. The dominant pricing model combines perpetual software licenses with increasingly prevalent subscription-based access, especially for cloud platforms. Price differentiation stems from the level of customization required for specific design flows and the extensive after-sales support provided for complex tool integrations. Pricing pressure stems from the immense R&D investment needed for leading-edge nodes. Startups and smaller design houses exhibit the highest price sensitivity, seeking flexible, pay-per-use models.
Supply Chain Analysis
Access to highly specialized software engineering talent forms the critical upstream feedstock for the EDA market's intellectual property development. Geographic supply concentration for core EDA innovation resides in the United States, with significant contributions from design clusters in Taiwan and Germany. A key supply chain risk is the specialized talent shortage for advanced process nodes, constraining project timelines. Furthermore, geopolitical export controls, such as the U.S. Department of Commerce's EAR, introduce regulatory restrictions. Distribution runs through direct sales channels and increasingly via cloud platform partnerships with hyperscalers like AWS and Azure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The critical shortage of engineers with specialized skills for physical design and verification at advanced process nodes defines a capability-scarcity market. This talent gap necessitates strategic adjustments across the value chain to ensure continued innovation.
For Market Incumbents: Pre-empt emerging AI-driven design tools by investing heavily in machine learning integration for physical design and verification. This mitigates threats from specialized AI startups and enhances optimization capabilities for complex chip architectures. Diversify revenue streams through cloud platform partnerships, leveraging scalable compute resources for broader market reach.
For New Entrants and Emerging Players: Establish a beachhead in cloud-based EDA platforms, targeting startups and small-to-medium design teams that prioritize operational flexibility. Focus on specialized AI-specific chip architectures, such as TPUs and NPUs, where existing toolchains may be less optimized. A SaaS model with flexible, pay-per-use pricing offers a compelling go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across advanced process node tool development due to immense R&D costs. The EDA market presents long-term viability as an essential enabler for the entire semiconductor industry. Target niche AI/ML EDA specialists or cloud-native EDA startups for acquisition. The adoption rates of cloud-based EDA by fabless companies serve as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in AI/ML Integration | Enhances design automation and optimization for complex multi-billion transistor chips. |
| Develop Cloud-Native EDA Platforms | Lowers entry barriers for startups and offers scalable compute resources for verification. |
| Form Geopolitical Compliance Teams | Navigates stringent export control regimes like U.S. EAR for critical EDA technologies. |
| Acquire Niche IP Verification Firms | Strengthens functional verification capabilities for safety-critical automotive ADAS systems. |
| Expand Talent Development Programs | Addresses the specialized talent shortage in physical design and advanced process nodes. |
Research Approach
Initial hypotheses were tested against primary input from chip designers, R&D directors at EDA firms, foundry process engineers, and automotive OEM electronics leads, and refined through iterative feedback. This primary research was validated against secondary sources including industry association reports, patent databases, government semiconductor initiatives, and financial filings of public EDA companies. The analysis employed both bottom-up and top-down triangulation to ensure comprehensive data coverage.
The demand-supply balance for advanced EDA tools was modeled across the analysis window, considering technological shifts and application-specific requirements. Segmentation dimensions included product type, technology, application, end-user, and regional design cluster. Compound annual growth rates were derived from historical data and projected future trends. Key industry-specific forecast inputs included semiconductor capital expenditure trends and advanced node adoption rates.
Macroeconomic conditions sit as an overlay; deviation in global GDP growth or semiconductor capital expenditure would shift the trajectory of market expansion. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Cross-checking against external semiconductor industry benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
1550nm LiDAR Pulsed Fiber Laser Market
Emerging and Next Generation Technologies
Medical Terahertz Technology Market
Emerging and Next Generation Technologies
Nanoelectronics Market
Emerging and Next Generation Technologies
Global Metamaterial Market
Emerging and Next Generation Technologies
Programmable Semiconductor Technologies Market
Emerging and Next Generation Technologies
Molecular Electronics Market
Emerging and Next Generation Technologies
Global Metamaterials Technologies Market
Emerging and Next Generation Technologies
North America Quantum Computing Market
Emerging and Next Generation Technologies
MLDW Technology Market
Emerging and Next Generation Technologies
Global Next Generation Computing Market
Emerging and Next Generation Technologies
Third-Generation Solar Cells Market
Emerging and Next Generation Technologies
Flexible PV Cell Market
Emerging and Next Generation Technologies
North America Cleanroom Technology Market
Emerging and Next Generation Technologies
Deep Tech Market
Emerging and Next Generation Technologies
Hyperscale Computing Market
Emerging and Next Generation Technologies
Lab on Chips Market