
 Stretchable Electronics Market | 2026-2036
Stretchable Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Stretchable Electronics Market Outlook
Buyer concentration in the healthcare sector is expanding as hospital networks and remote patient monitoring platforms consolidate procurement around validated stretchable sensor suppliers. Samsung Electronics leverages its display manufacturing scale to anchor production of flexible OLED substrates for wearable applications. DuPont de Nemours sustains materials leadership through proprietary silicone-polymer composites that enable high-cycle strain tolerance.
Stretchable electronics comprise circuit architectures and functional components engineered to maintain electrical performance under mechanical deformation exceeding 20% strain, typically fabricated through thin-film metallization on elastomeric substrates or intrinsically conductive polymer networks. Their primary commercial purpose centers on conformal integration with soft biological tissues, textiles, and curved mechanical surfaces where rigid conventional electronics fail. Printing technology dominates volume manufacturing for disposable biosensors, while stretchable sensors capture premium margins in clinical-grade continuous monitoring applications. Hybrid technologies are gaining traction as manufacturers combine microfabricated silicon dies with elastomeric interconnects to bridge performance and compliance requirements.
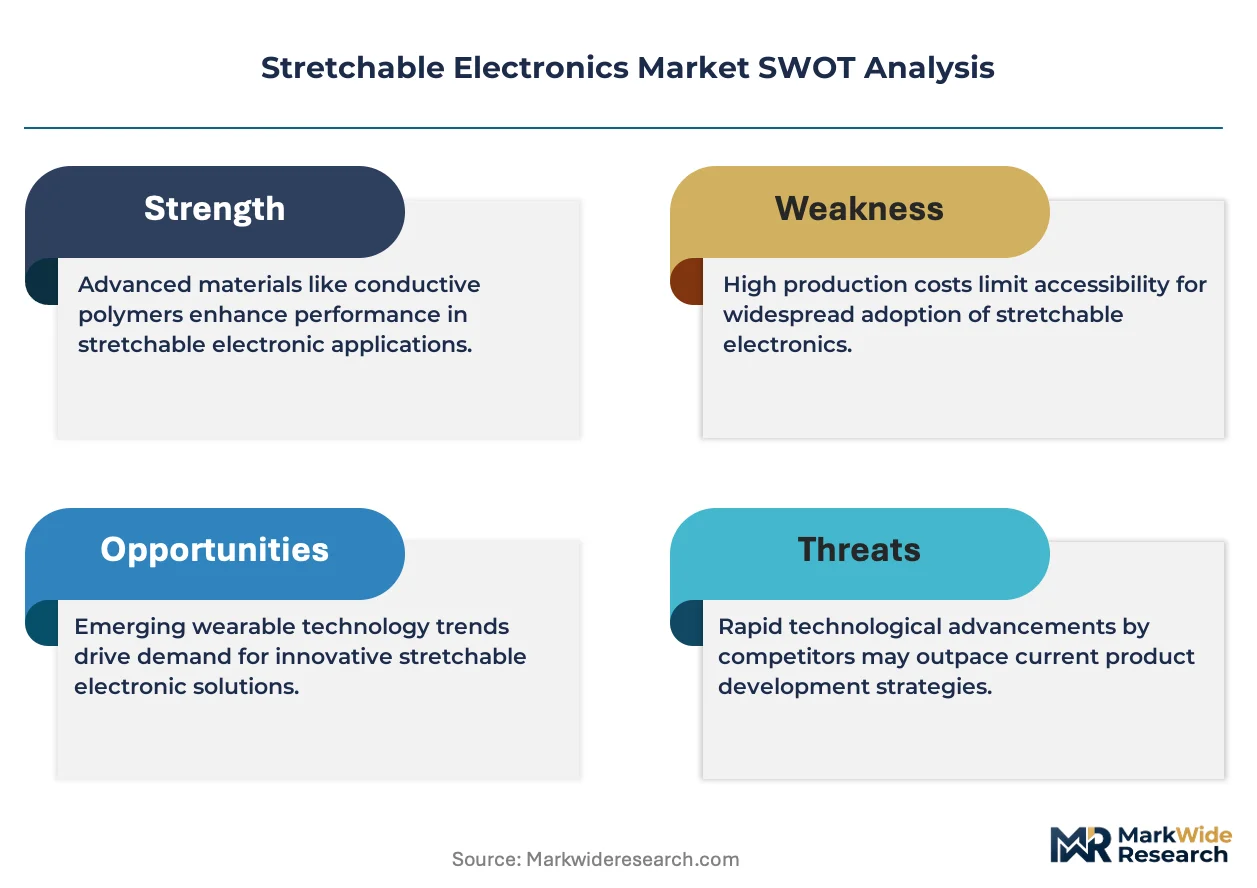
The FDA regulates skin-contact stretchable devices under biocompatibility and electrical safety frameworks, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for Class IIa and above wearable diagnostics. ISO 10993 standards govern cytotoxicity and sensitization testing protocols that determine market access timelines for new materials. Stakeholders must monitor evolving interoperability mandates from healthcare systems that increasingly require seamless data integration between stretchable wearables and electronic health record platforms.
Market Dynamics
Hospital procurement consolidation and the EU Medical Device Regulation's tightened biocompatibility standards are compressing supplier qualification timelines while favoring vertically integrated manufacturers with in-house materials science capabilities.
Growth Catalysts
- EU Medical Device Regulation:Class IIa and above wearable diagnostics now require stricter clinical evidence, accelerating demand for validated stretchable sensor suppliers with established ISO 10993 testing protocols.
- Printed electronics manufacturing:Germany's industrial clusters around printed electronics are scaling roll-to-roll production for disposable biosensors, reducing unit costs for high-volume healthcare applications.
- Remote patient monitoring platforms:Hospital network consolidation is centralizing procurement around stretchable patch suppliers capable of seamless electronic health record integration.
Market Restraints
- Silicone-polymer composite supply:Proprietary elastomeric substrates rely on concentrated specialty chemical production, creating input cost volatility for strain-tolerant materials.
- Thin-film metallization equipment:Sputtering and evaporation systems for elastomeric substrates require significant capital outlay, limiting new entrant participation.
- ISO 10993 certification timelines:Cytotoxicity and sensitization testing protocols extend market access timelines by 18-24 months for novel skin-contact materials.
Strategic Opportunities
- Hybrid microfabrication:Combining microfabricated silicon dies with elastomeric interconnects bridges performance-compliance gaps in clinical-grade continuous monitoring.
- Flexible OLED substrate expansion:Display manufacturing scale is creating spillover capacity for wearable applications requiring conformal optoelectronic integration.
- Interoperability mandates:Healthcare systems are requiring seamless data integration between stretchable wearables and electronic health record platforms, favoring suppliers with software capabilities.
Industry Challenges
- Multiphysics simulation talent:Coupled mechanical-electrical-thermal modeling for stretchable architectures requires scarce computational mechanics expertise.
- Legacy electronic health record integration:Stretchable sensor data formats often conflict with established healthcare IT infrastructure, requiring custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stretchable Electronics Market |
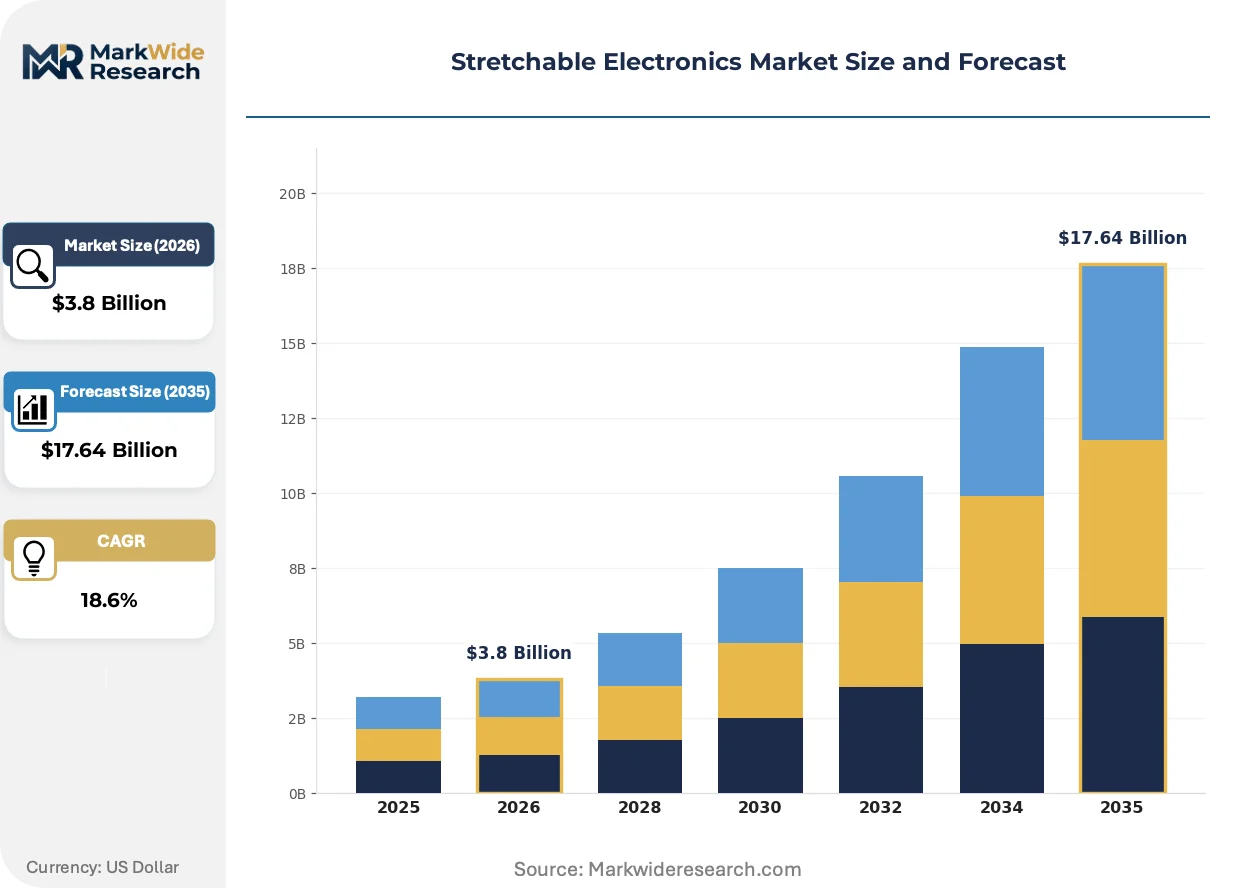
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conductive Polymers, Stretchable Sensors, Flexible Displays, Wearable Devices Technology: Printing Technology, Roll-to-Roll Processing, Microfabrication, Hybrid Technologies Application: Healthcare Monitoring, Smart Textiles, Consumer Electronics, Automotive Components End User: Aerospace, Military, Healthcare, Sports |
| Companies Covered | Panasonic Corporation, Applied Materials, Samsung Electronics, Universal Display Corporation, Flex, LG Display, 3M Company, Imprint Energy, DuPont de Nemours, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stretchable Electronics Market Strategic Shifts
Materials science breakthroughs and regulatory harmonization efforts are compressing development cycles while expanding the addressable application space beyond traditional healthcare boundaries.
Intrinsically conductive polymer networks are absorbing mechanical strain through molecular-level deformation rather than geometric engineering, enabling simpler manufacturing architectures. Wearable diagnostic manufacturers in Germany and South Korea are adopting these materials for next-generation cardiac monitoring patches. The technology is absorbing market share from metal-on-elastomer approaches in applications requiring washability and long-term skin contact.
The EU Medical Device Regulation's biocompatibility framework is forcing manufacturers to front-load clinical evidence generation before market entry. This regulatory shift has extended development timelines but reduced post-market recall risk for Class IIa stretchable diagnostics. German notified bodies are experiencing backlog pressures as suppliers rush to certify skin-contact electronics under the tightened standards.
Hospital procurement departments are consolidating vendor panels around full-stack stretchable sensor providers capable of hardware, firmware, and data analytics integration. This buying-pattern change is marginalizing component-only suppliers and favoring systems integrators with healthcare IT certification. The concentration is most visible in US hospital networks and German university medical centers with established remote patient monitoring programs.
Stretchable Electronics Market Segmentation
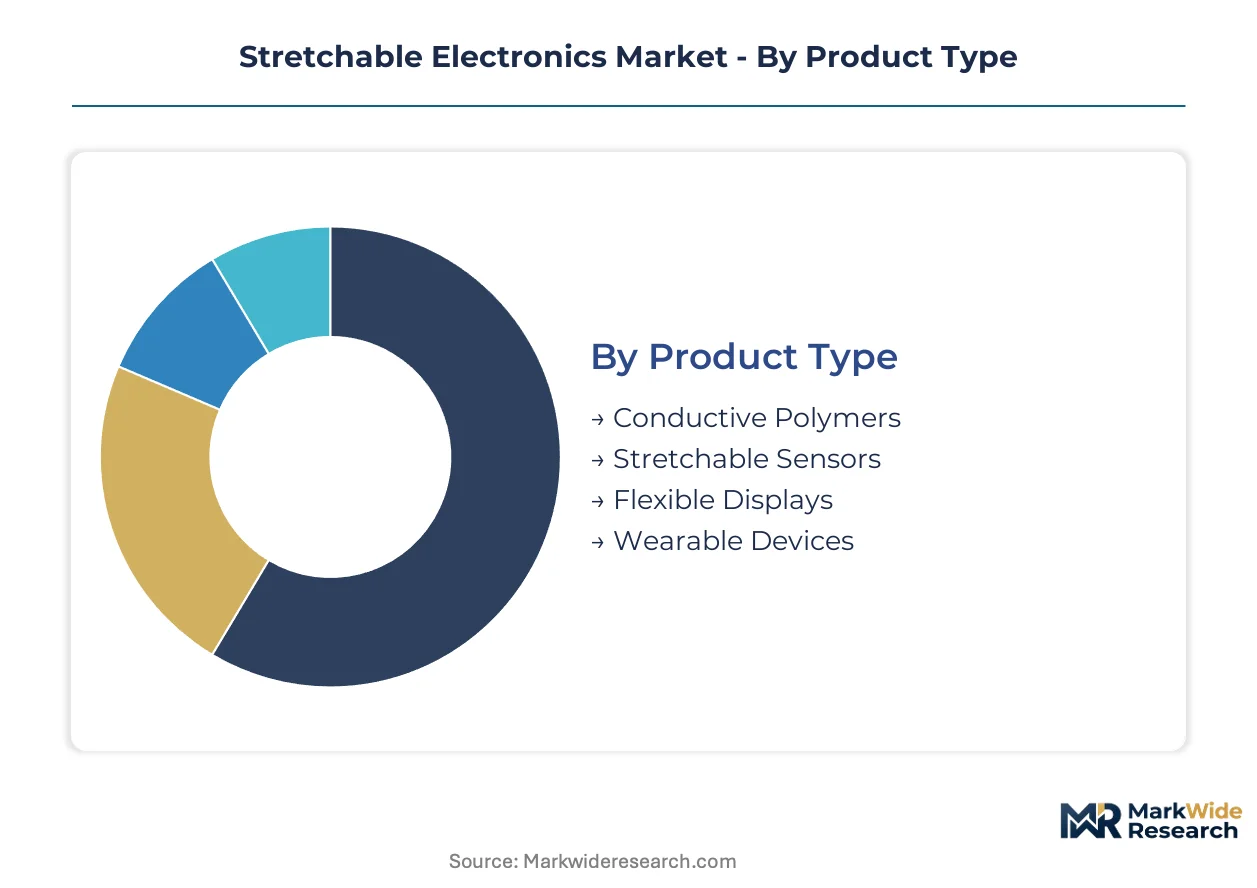
Stretchable electronics demand fragments across integration depths, from standalone wearable patches to embedded automotive interior systems. Procurement patterns diverge sharply between disposable healthcare consumables and capital-intensive industrial installations. Understanding segment boundaries clarifies where manufacturing scale advantages apply versus where customization premiums persist.
Product Type:
Standalone surface-mount products dominate high-volume healthcare deployments, while embedded substrate-integrated formats capture automotive and aerospace qualification premiums.
- Conductive Polymers:Intrinsically stretchable polymer networks deform at molecular scales without geometric patterning complexity. Demand concentrates in German cardiac monitoring patch manufacturers seeking washability and long-term skin contact compliance under EU MDR biocompatibility frameworks.
- Stretchable Sensors:Thin-film metallization on elastomeric substrates enables strain-tolerant strain gauges, temperature sensors, and electrophysiological electrodes. Hospital procurement consolidation in US networks and German university medical centers is centralizing vendor qualification around suppliers with ISO 10993 testing protocols and electronic health record interoperability.
- Flexible Displays:OLED substrates fabricated on polyimide or metal foil backplanes enable conformal optoelectronic integration. Samsung Electronics leverages display manufacturing scale for wearable spillover applications.
- Wearable Devices:Complete patch systems integrate sensing, processing, and wireless transmission for continuous physiological monitoring. Remote patient monitoring platforms require seamless data integration capabilities.
Volume placements concentrate in Stretchable Sensors; the faster expansion belongs to Conductive Polymers.
Technology:
Cost tier stratification separates high-throughput roll-to-roll methods from precision microfabrication, with hybrid approaches bridging mid-range performance requirements.
- Printing Technology:Screen, inkjet, and gravure deposition of conductive inks onto elastomeric substrates enables low-cost disposable biosensor manufacturing. Germany's printed electronics industrial clusters scale production for high-volume healthcare applications.
- Roll-to-Roll Processing:Continuous reel-to-reel fabrication achieves unit economics competitive with conventional rigid electronics for large-area applications. Demand concentrates in disposable diagnostic patch manufacturing where throughput determines procurement decisions.
- Microfabrication:Photolithographic patterning of thin-film metals and semiconductors on temporary carriers enables sub-micron feature resolution. Clinical-grade continuous monitoring applications require this precision for signal fidelity.
- Hybrid Technologies:Combining microfabricated silicon dies with elastomeric interconnects bridges performance-compliance gaps. US hospital networks favor these architectures for Class IIa diagnostic wearables requiring both computational power and mechanical compliance.
Roll-to-Roll Processing commands the highest shipment volumes; Hybrid Technologies are climbing the fastest as manufacturers balance silicon performance with elastomeric conformability.
Application:
Application maturity spans FDA-cleared clinical devices to emerging automotive interior concepts, with margin structure inversely correlated with regulatory pathway length.
- Healthcare Monitoring:Continuous cardiac, glucose, and hydration sensing via skin-conformal patches. EU MDR Class IIa requirements and FDA biocompatibility frameworks govern market access. German notified bodies face certification backlogs as suppliers rush to validate skin-contact electronics.
- Smart Textiles:Integration of stretchable interconnects and sensors into apparel for motion capture and environmental sensing. Sports performance tracking drives initial adoption before healthcare rehabilitation applications.
- Consumer Electronics:Fitness bands, smartwatches, and hearables incorporating stretchable components for ergonomic fit. Samsung Electronics anchors flexible OLED substrate supply for this segment.
- Automotive Components:Conformal interior sensing surfaces for occupant monitoring and human-machine interfaces. Longer qualification timelines and temperature cycling requirements delay volume ramp compared to healthcare.
Healthcare Monitoring captures the dominant revenue share; Smart Textiles are gaining share fastest as washability requirements drive conductive polymer substitution.
End User:
Customer type determines specification rigor, from military environmental tolerance requirements to sports cost sensitivity.
- Healthcare:Hospital networks, remote patient monitoring platforms, and home care services procuring validated stretchable sensor systems. Procurement consolidation favors full-stack suppliers with hardware, firmware, and analytics integration.
- Sports:Professional teams and consumer fitness brands seeking motion capture and biometric feedback. Price sensitivity limits adoption to premium performance tiers.
- Military:Soldier physiological monitoring and soft robotics applications requiring extreme environmental tolerance. Extended qualification cycles and security requirements restrict supplier base.
- Aerospace:Cabin crew and passenger monitoring systems, plus structural health monitoring of composite airframes. FAA certification pathways for skin-contact electronics remain under development.
Healthcare absorbs the greatest unit volume; Aerospace presents the steepest expansion trajectory as cabin monitoring mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consolidation concentrates stretchable sensor demand in Germany's industrial clusters and US hospital networks, while South Korean display manufacturers exploit manufacturing scale for wearable spillover applications.
United States
FDA biocompatibility frameworks and HIPAA interoperability mandates drive Class IIa wearable diagnostic procurement. Hospital network consolidation centralizes vendor qualification around suppliers with ISO 10993 testing protocols. Greater Boston's medtech corridor anchors remote patient monitoring platform development.
Germany
EU MDR tightened standards accelerate demand for validated stretchable sensor suppliers with established clinical evidence. German notified bodies face certification backlogs as suppliers rush to validate skin-contact electronics. Bavaria's printed electronics industrial clusters scale roll-to-roll production for disposable biosensors.
South Korea
Display manufacturing scale creates spillover capacity for flexible OLED substrates in wearable applications. MFDS regulates skin-contact devices under biocompatibility and electrical safety frameworks. Seoul Capital Area anchors Samsung Electronics' flexible substrate production for consumer electronics integration.
China
NMPA biocompatibility requirements and domestic healthcare digitization expand procurement for continuous monitoring patches. MIIT standards govern wearable device electrical safety and data transmission protocols. Yangtze River Delta industrial zones concentrate printed electronics manufacturing for high-volume biosensor exports.
Japan
PMDA clinical evidence requirements for Class IIa wearables extend market access timelines while reducing post-market recall risk. METI funding programs support next-generation cardiac monitoring patch development. Kanto region's precision manufacturing base enables thin-film metallization for clinical-grade sensors.
Stretchable Electronics Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue hybrid microfabrication architectures and conductive polymer networks. The market exhibits tiered concentration with materials specialists, display manufacturers, and contract fabricators occupying distinct competitive positions. Strategic archetypes include vertically integrated materials-science leaders, display-scale substrate producers, and healthcare-certified systems integrators. Dominant competitive moves encompass backward integration into specialty elastomer production and strategic partnerships for electronic health record interoperability certification.
Within the display-scale substrate tier, Samsung Electronics and LG Display exemplify manufacturing-scale leverage for flexible OLED wearable applications. DuPont de Nemours occupies a position among materials-science specialists with proprietary silicone-polymer composite capabilities. Panasonic Corporation represents the diversified electronics conglomerate archetype with cross-segment stretchable component integration.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Applied Materials |
| Samsung Electronics |
| Universal Display Corporation |
| Flex |
| LG Display |
| 3M Company |
| Imprint Energy |
| DuPont de Nemours |
| Others |
Value Chain & Pricing Dynamics
Backward integration into silicone-polymer composite production anchors both supply security and margin protection for stretchable electronics manufacturers facing volatile specialty chemical markets. DuPont de Nemours and materials-science leaders leverage captive substrate capabilities to buffer against elastomer input cost swings while commanding premium positioning in clinical-grade sensor tiers.
Pricing Analysis
Volume placements in disposable biosensors run on thin margins through roll-to-roll manufacturing scale, while clinical-grade continuous monitoring patches capture premium returns via ISO 10993 certification barriers. Three-tier pricing structure across premium, standard, and economy levels separates validated Class IIa diagnostic suppliers from uncertified component vendors and high-throughput disposable producers. Cost compression in standard-tier conductive polymers is intensifying because German printed electronics clusters are scaling capacity for cardiac monitoring patch exports. Hospital networks show least price sensitivity for seamless electronic health record integration, whereas sports fitness brands drive hardest bargain negotiations for motion capture textiles.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Samsung Electronics and LG Display for flexible OLED substrates, while specialized distributors serve mid-tier healthcare patch manufacturers requiring technical support. Manufacturing concentrates in Germany's printed electronics clusters, South Korea's display fabrication hubs, and Japan's precision metallization corridors. The supply chain draws from concentrated silicone-polymer composite production, thin-film metallization equipment, and intrinsically conductive polymer feedstocks. Single-source vulnerability in specialty elastomer substrates creates exposure when notified body certification backlogs delay alternative supplier qualification. Distribution runs through healthcare IT integrators for hospital network procurement and through electronics manufacturing service providers for consumer wearable brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stretchable electronics supply is tightening around qualified silicone-polymer substrate capacity, with ISO 10993 certification timelines propping pricing power for validated manufacturers against uncertified entrants.
For Market Incumbents: Deepen backward integration into proprietary elastomer production to secure input cost stability against specialty chemical volatility. Incumbent manufacturers must accelerate hospital system partnership lock-ins before emerging conductive polymer networks displace metal-on-elastomer architectures in washability-critical applications. Capacity expansion in Bavaria's printed electronics corridors reinforces supply position for EU MDR-compliant patch exports. For New Entrants and Emerging Players: Capture white-space in aerospace cabin monitoring systems where FAA certification pathways remain under development and incumbent presence is sparse. New entrants should target sports rehabilitation textiles in German university medical centers seeking conductive polymer alternatives to legacy strain gauges. A software-forward go-to-market angle emphasizing electronic health record interoperability bypasses hardware scale disadvantages against Samsung Electronics and DuPont de Nemours. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified healthcare IT conglomerates seeking full-stack wearable diagnostic capabilities. Long-term viability hinges on navigating regulatory harmonization between FDA biocompatibility frameworks and EU MDR clinical evidence requirements. Acquisition targets should display hybrid microfabrication expertise combining silicon performance with elastomeric compliance. The signal to watch is German notified body backlog clearance rates as a proxy for market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10993 Certification Investment | Accelerates EU MDR market access for Class IIa skin-contact diagnostics in German notified body queues. |
| Hospital System Partnership | Locks in procurement consolidation around full-stack suppliers with electronic health record interoperability. |
| Backward Integration into Elastomers | Captures margin from proprietary silicone-polymer composites and buffers input cost volatility. |
| Hybrid Microfabrication Scale-Up | Bridges silicon computational performance with elastomeric mechanical compliance for clinical monitoring. |
| Conductive Polymer Network Development | Enables washability and long-term skin contact compliance displacing metal-on-elastomer approaches. |
Study Parameters
Multi-period observation of EU MDR certification timelines, hospital procurement consolidation patterns, and printed electronics capacity expansion anchored the trend analysis, supplemented by interviews with biomedical engineers, hospital GPO contracts managers, elastomer substrate R&D directors, and regulatory affairs leads at notified bodies. Secondary validation drew from FDA 510(k) filings, EMDR database entries, German medical device trade association reports, and SEC filings of display manufacturers. Bottom-up patch shipment estimates triangulated against top-down healthcare IT spending projections.
Input-output matrices mapped conductive polymer feedstock costs, thin-film metallization equipment utilization, and certification backlog durations against stretchable sensor pricing tiers across the projection horizon. Segmentation dimensions included product type integration depth, technology fabrication precision, application regulatory pathway length, and end-user specification rigor. CAGRs derived from elasticity-adjusted adoption curves for continuous monitoring penetration in hospital networks and conductive polymer substitution rates in smart textiles.
The model holds under stable EU MDR enforcement intensity and continued hospital procurement consolidation; deviation in notified body capacity expansion or FDA biocompatibility framework revision would shift market access timelines and competitive positioning. Forecasts reflect assumptions about elastomer substrate supply elasticity and healthcare IT interoperability mandate adoption. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Global Broad Ion Beam Technology Market
Emerging and Next Generation Technologies
Swarm Computing Market
Emerging and Next Generation Technologies
In-Mold Electronics (IME) Market
Emerging and Next Generation Technologies
Flexible Hybrid Electronics (FHE) Market
Emerging and Next Generation Technologies
3D Xpoint Technology Market
Emerging and Next Generation Technologies
Next Generation Processors Market
Emerging and Next Generation Technologies
Molecular Electronics Market
Emerging and Next Generation Technologies
Haptic Technology Market
Emerging and Next Generation Technologies
Ultra-Fine Ath Market
Emerging and Next Generation Technologies
Mexico Cleanroom Technology Market
Emerging and Next Generation Technologies
Laser Technology Market
Emerging and Next Generation Technologies
Lab on Chips Market
Emerging and Next Generation Technologies
Roll to Roll Flexible Electronics Market
Emerging and Next Generation Technologies
Global Next Generation Computing Market
Emerging and Next Generation Technologies
Spintronics Market
Emerging and Next Generation Technologies
Global WI SUN Technology Market